
 United States Home Office Furniture Market | 2026-2036
United States Home Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
United States Home Office Furniture Market Intelligence
Buyer concentration among remote workers is broadening beyond traditional corporate procurement channels toward individual consumers furnishing dedicated residential workspaces. HNI Corporation leverages its vertical manufacturing footprint to serve this dispersed demand through direct-to-consumer channels. Steelcase Inc. competes by sustaining its R&D intensity in ergonomic seating systems originally developed for enterprise clients. Herman Miller anchors the premium ergonomic segment with brand strength built on decades of workplace design leadership.
United States home office furniture encompasses desks, chairs, storage systems, and accessories engineered for residential productivity environments, typically incorporating adjustable height mechanisms, cable management integration, and materials meeting California Air Resources Board Phase II formaldehyde limits. The primary commercial purpose centers on replicating enterprise-grade functionality within space-constrained domestic settings. The product type dimension shows desks and chairs capturing dominant volume as core workstation investments, while shelving units represent the fastest-growing category as users seek vertical storage solutions for compact home offices. The material segment reveals wood maintaining margin leadership through solid and veneered constructions, though metal frames accelerate in seating as manufacturers prioritize durability warranties.
The Consumer Product Safety Commission enforces stability and tip-over standards for storage furniture, while California's Proposition 65 labeling requirements shape material selection across national supply chains. The EPA's formaldehyde standards and OSHA's voluntary ergonomic guidelines collectively elevate product compliance costs while creating differentiation opportunities for certified manufacturers. Stakeholders must monitor evolving municipal building codes in high-growth states as accessory dwelling unit legalization creates secondary home office demand streams.
Market Dynamics
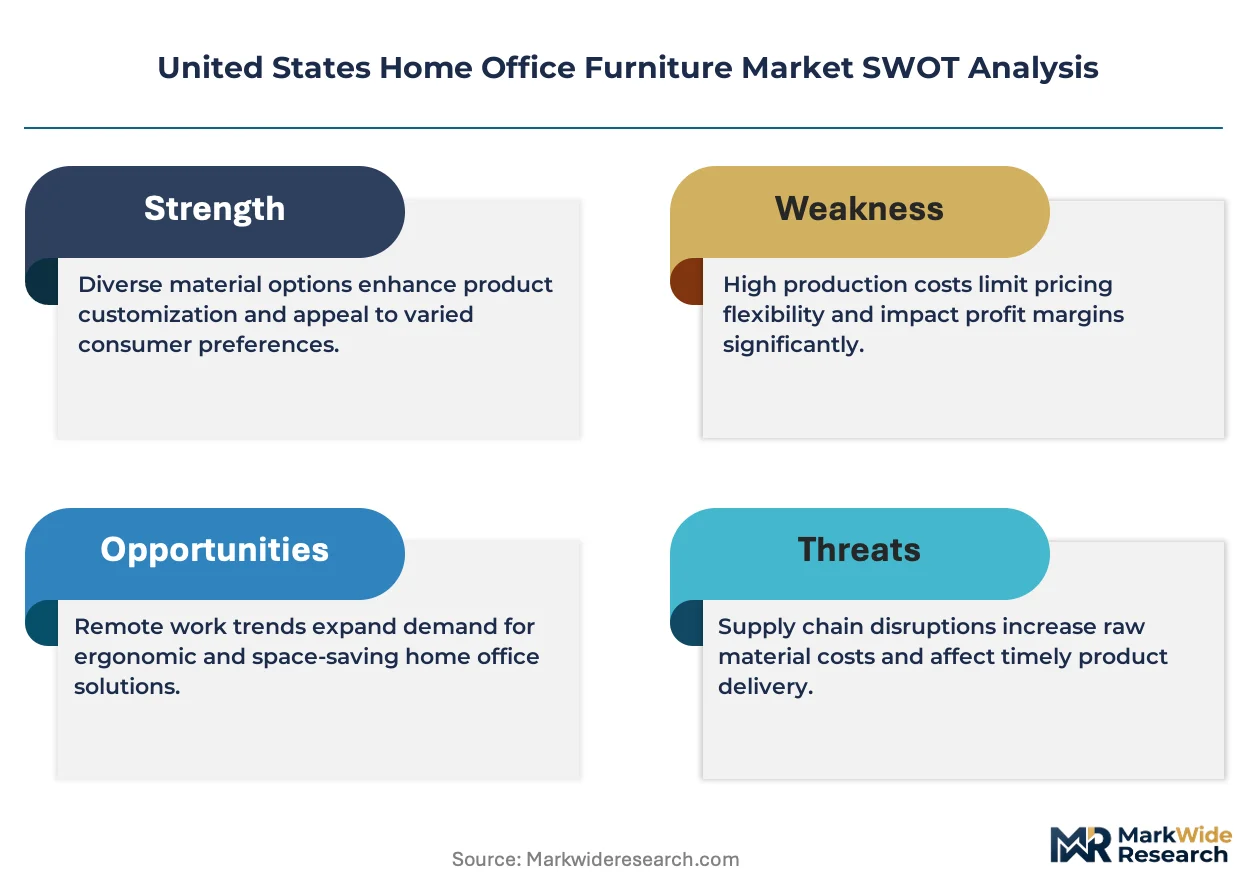
The structural force reshaping United States home office furniture is the permanent reconfiguration of residential space allocation as hybrid work stabilizes, forcing manufacturers to engineer for domestic electrical standards and spatial constraints rather than commercial building codes.
Growth Catalysts
- EPA Formaldehyde Standards:The Toxic Substances Control Act emission limits are accelerating manufacturer migration toward low-emission engineered wood products, creating compliance-based differentiation for certified suppliers.
- Remote Worker Demand:Individual consumers furnishing dedicated residential workspaces are displacing traditional corporate procurement volumes, broadening addressable market beyond enterprise channels.
- Sun Belt Migration:Residential construction and in-migration of remote professionals in Texas and Florida are concentrating demand in high-growth metropolitan corridors.
Market Restraints
- Lumber Price Volatility:Solid wood and veneer input costs fluctuate with North American softwood lumber markets, compressing margin predictability for domestic manufacturers.
- Asian Component Concentration:Metal frame mechanisms and adjustable height hardware rely heavily on concentrated overseas supply, exposing lead time risk.
- California Proposition 65:Warning label requirements for formaldehyde and other substances create national supply chain friction as manufacturers standardize to strictest state rules.
Strategic Opportunities
- Accessory Dwelling Unit Legalization:Municipal code changes across high-growth states are creating secondary home office demand streams in converted garage and backyard structures.
- OSHA Ergonomic Guidelines:Voluntary workplace standards are migrating into consumer purchasing criteria, opening certification-premium positioning for ergonomic seating specialists.
- Direct-to-Consumer Channels:E-commerce fulfillment infrastructure enables manufacturers to bypass traditional furniture retail, capturing margin from dispersed residential buyers.
Industry Challenges
- Product Safety Certification Timelines:Consumer Product Safety Commission stability testing for storage furniture extends new product introduction cycles, compressing seasonal windows.
- Ergonomic Engineering Talent:Shortage of industrial designers versed in both biomechanics and residential aesthetic requirements constrains R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Home Office Furniture Market |
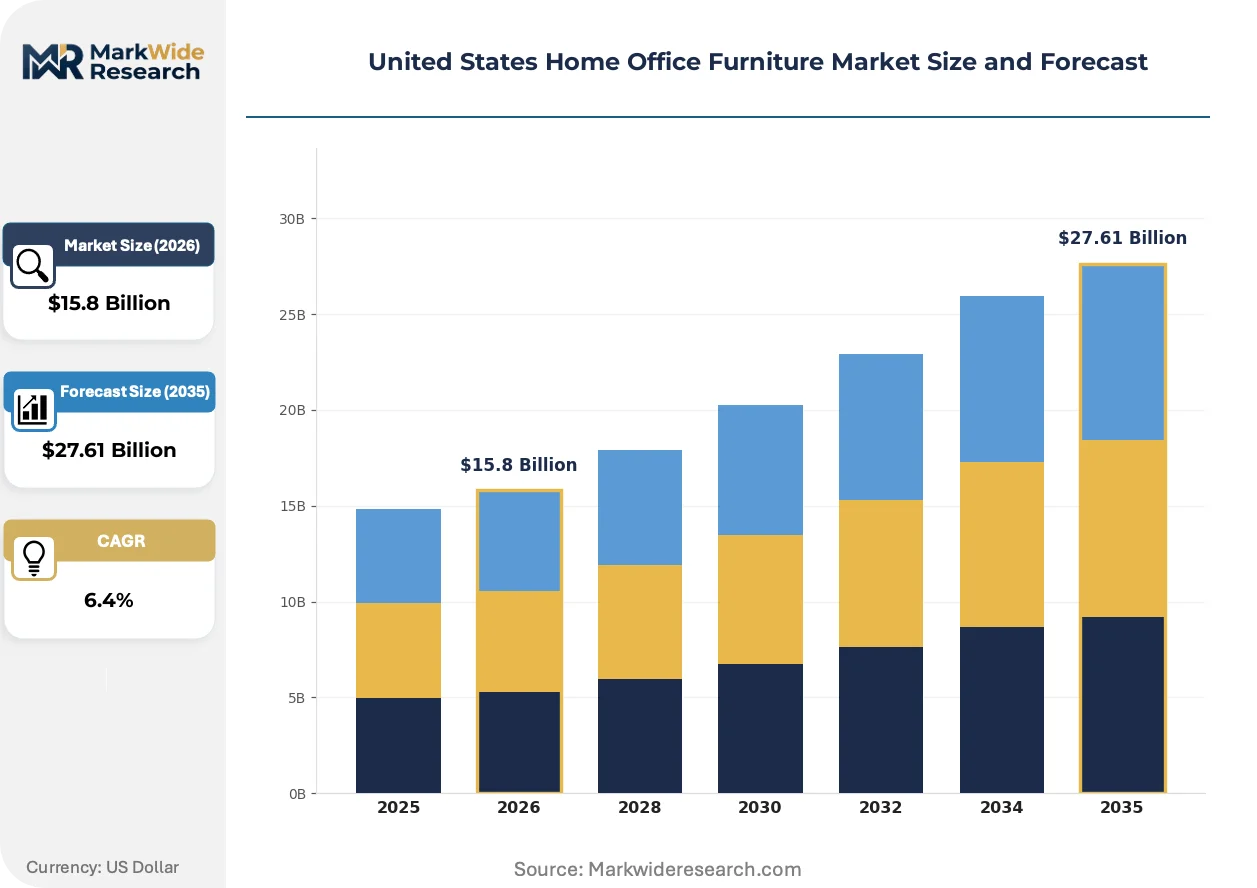
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $27.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Shelving Units, Storage Cabinets Material: Wood, Metal, Plastic, Glass Style: Modern, Traditional, Rustic, Contemporary End User: Freelancers, Small Businesses, Remote Workers, Students |
| Companies Covered | HNI Corporation, La-Z-Boy Incorporated, Steelcase Inc., Humanscale Corporation, Ashley Furniture Industries, Herman Miller, IKEA, Knoll, Haworth Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Home Office Furniture Market Strategic Shifts & Innovations
Active transformation in United States home office furniture centers on intelligent surface integration, emissions compliance as a design constraint, and the collapse of traditional channel boundaries between contract and residential supply.
Adjustable height desk mechanisms are expanding into mid-market residential price points as linear actuator costs decline and consumer familiarity with enterprise sit-stand workstations increases. Remote workers in Sun Belt states are adopting these systems fastest, compressing the premium-to-mass-market cycle that previously took decades in commercial furniture.
California Air Resources Board Phase II formaldehyde limits are reshaping material specifications nationwide as manufacturers standardize supply chains to single compliance tier. Engineered wood suppliers achieving CARB certification are capturing preferential placement in national retail programs, while uncertified producers face exclusion from major distribution channels.
Individual procurement of enterprise-grade ergonomic seating is fragmenting traditional contract furniture channels as buyers research specifications independently online. Steelcase and Herman Miller brand recognition from corporate environments is transferring to direct residential purchase, most visibly in metropolitan markets with high remote-worker density such as Austin and Miami.
United States Home Office Furniture Market Segmentation
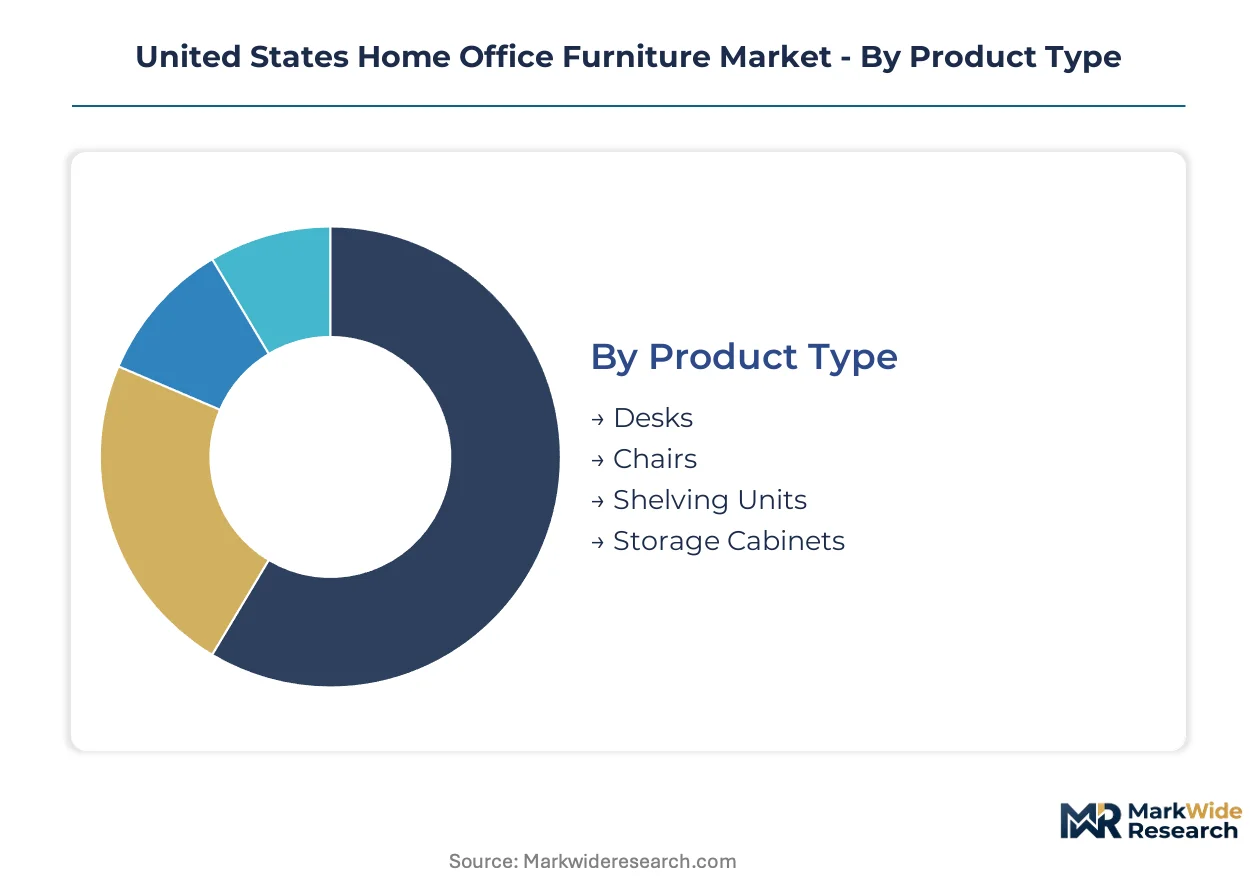
Segmentation in United States home office furniture reveals how capital deployment, regulatory exposure, and channel strategy diverge across product lines. Manufacturers allocate tooling budgets differently when serving remote workers versus traditional corporate buyers.
Product Type:
Capital intensity peaks in adjustable-height desk mechanisms and ergonomic seating platforms, where precision-engineered components demand dedicated production lines.
- Desks:Workstation surfaces incorporating cable management channels, height-adjustment hardware, and load-bearing frames rated for residential electrical integration. Demand concentrates in Texas and Florida metropolitan corridors where new residential construction accommodates dedicated office space.
- Chairs:Ergonomic seating systems with lumbar support mechanisms, mesh or upholstered surfaces, and caster bases meeting carpet and hard-floor specifications. Remote workers in Austin and Miami are driving specification migration from enterprise-grade features into mid-market price bands.
- Shelving Units:Vertical storage systems engineered for stability compliance under CPSC tip-over standards.
- Storage Cabinets:Enclosed compartment systems with locking mechanisms and formaldehyde-compliant engineered wood panels.
Desks absorb the bulk of installed capacity; shelving units are expanding most quickly.
Material:
Raw material selection determines compliance pathway and margin structure, with CARB Phase II certification creating tiered supplier qualification.
- Wood:Solid hardwood, veneered substrates, and engineered panels meeting EPA formaldehyde emission limits under TSCA. Sun Belt residential construction favors wood aesthetics, though lumber price volatility compresses margin predictability for domestic manufacturers.
- Metal:Steel and aluminum framing for seating bases, desk legs, and shelving supports. Adjustable-height desk mechanisms rely heavily on overseas component supply, exposing lead time risk.
- Plastic:Polymer components for chair shells, drawer glides, and cable management accessories.
- Glass:Tempered surface panels for executive-style desk inlays and contemporary shelving accents.
Wood commands the dominant production share; metal is climbing the fastest as durability warranties extend.
Style:
Aesthetic positioning shapes channel access and price realization, with direct-to-consumer platforms enabling style experimentation at lower inventory risk.
- Modern:Clean-lined forms with minimal ornamentation, neutral palettes, and integrated technology accommodation. Remote workers in technology sector employment favor this aesthetic for dedicated residential workspaces.
- Traditional:Ornamented hardwood constructions with classic proportioning and rich finishes. Small business owners in established suburban markets sustain demand for this segment.
- Rustic:Distressed wood surfaces, industrial metal accents, and farmhouse-influenced proportioning.
- Contemporary:Bold geometric forms, mixed material compositions, and statement-scale pieces.
Modern styling captures the largest addressable base; contemporary is gaining share fastest among urban remote workers.
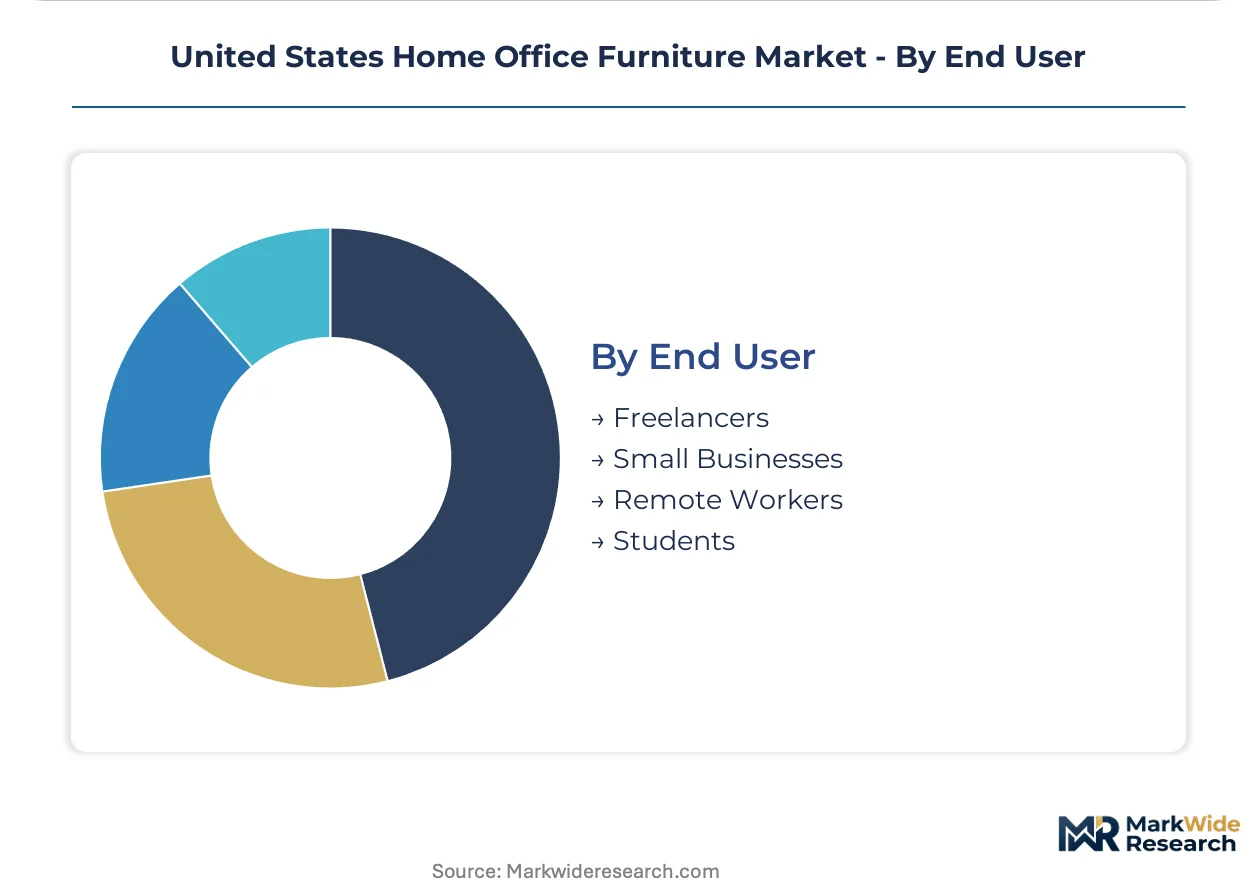
End User:
Procurement authority and specification knowledge vary sharply across user types, forcing manufacturers to engineer for independent research behavior versus institutional purchasing protocols.
- Remote Workers:Individual consumers furnishing dedicated residential offices with enterprise-grade functionality expectations. This segment concentrates in Sun Belt states where hybrid work arrangements have stabilized and residential construction supports home office allocation.
- Freelancers:Independent professionals with variable workspace requirements and price-sensitive procurement patterns.
- Small Businesses:Owner-operated entities purchasing for limited staff in home-based or micro-commercial settings.
- Students:Educational users seeking compact, budget-oriented solutions for dormitory or shared housing environments.
Remote workers represent the dominant volume endpoint; freelancers show the steepest expansion trajectory as independent employment grows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Remote worker demand concentrates in Sun Belt metropolitan corridors where hybrid work arrangements have stabilized and residential construction supports dedicated home office allocation. Texas and Florida anchor volume growth, though secondary markets across the Southeast and Mountain West are accelerating.
Texas
Austin and Dallas-Fort Worth metropolitan areas absorb the highest per-capita demand for adjustable-height desks and ergonomic seating as technology sector remote workers settle permanently. Municipal code liberalization for accessory dwelling units in Houston and San Antonio creates secondary demand for compact office solutions in converted garage structures. Dallas anchors distribution infrastructure serving the broader Southwest region.
Florida
Miami and Tampa Bay corridors attract finance and professional services remote workers from high-cost Northeast markets, driving specification migration toward premium ergonomic products. The state's building code adoption of enhanced residential electrical standards supports integrated cable management and powered desk installations. Orlando's logistics cluster enables rapid fulfillment to Southeast coastal markets.
California
Los Angeles and San Francisco Bay Area metros sustain demand for space-efficient solutions as high housing costs constrain dedicated office square footage. CARB Phase II formaldehyde standards originating here propagate nationwide through manufacturer supply chain standardization. San Diego's cross-border manufacturing relationships expose the market to Mexican component supply dynamics.
North Carolina
Charlotte and Raleigh-Durham technology corridors attract remote workers from Northeast and West Coast markets, concentrating demand for mid-market ergonomic seating. The state's furniture manufacturing heritage supports domestic production of wood-based storage systems meeting EPA TSCA emission limits. High Point's trade show infrastructure shapes national style trends.
Arizona
Phoenix and Tucson metropolitan areas absorb California outmigration, expanding addressable market for full home office suites in new suburban construction. Municipal water conservation requirements influence material selection toward lower-weight metal frame constructions. Scottsdale's affluent retiree segment sustains demand for executive-style traditional aesthetics.
United States Home Office Furniture Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer channels and ergonomic specialization. The vendor base stratifies across three maturity tiers: legacy contract furniture houses with residential extensions, pure-play direct-to-consumer platforms, and regional wood furniture manufacturers adapting emission-compliant engineered panel lines. Dominant competitive moves include backward integration into captive component supply and strategic partnerships with adjustable-height mechanism suppliers.
Within the legacy contract tier, Steelcase Inc., Herman Miller, and HNI Corporation exemplify manufacturers leveraging enterprise brand recognition for residential channel expansion. Steelcase and Herman Miller occupy positions translating corporate ergonomic expertise into direct consumer purchase, while HNI Corporation represents vertical manufacturing footprint deployment for dispersed demand fulfillment. These entities anchor the premium specification segment where OSHA ergonomic guideline familiarity drives purchasing decisions.
| Leading Market Players |
|---|
| HNI Corporation |
| La-Z-Boy Incorporated |
| Steelcase Inc. |
| Humanscale Corporation |
| Ashley Furniture Industries |
| Herman Miller |
| IKEA |
| Knoll |
| Haworth Inc. |
| Others |
Cost & Logistics Intelligence
Ergonomic engineering talent shortages in North Carolina's furniture manufacturing belt widen labor-cost differentials between premium ergonomic seating and standard desk products. CARB Phase II compliance investments and adjustable-height mechanism sourcing costs stratify pricing tiers across the United States home office furniture landscape.
Pricing Analysis
Volume concentrates in mid-market desks and chairs while margin accrues to certified ergonomic seating and low-emission engineered wood storage systems. Price differentiation separates CARB-certified product lines from standard offerings, with brand heritage from corporate environments commanding additional premium. Pricing pressure stems from lumber price volatility compressing domestic manufacturer margins, particularly for solid wood and veneered constructions. Remote workers in Sun Belt states show lowest price sensitivity for ergonomic seating, while students and freelancers drive economy-tier volume.
Supply Chain Analysis
Regional distribution centers in Dallas and Orlando anchor hub-and-spoke fulfillment patterns serving dispersed residential buyers across the South and Southwest. Manufacturing draws from China, Vietnam, and domestic facilities in North Carolina, with metal frame mechanisms and adjustable-height hardware heavily concentrated in Asian component supply. Raw material dependencies include North American softwood lumber, steel and aluminum framing, and CARB-certified engineered wood panels. Single-source vulnerability in linear actuator supply exposes lead time risk. Distribution runs through direct-to-consumer platforms bypassing traditional furniture retail, alongside big-box and specialty channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States home office furniture market sits in a technology-transition phase as intelligent surface integration and powered desk systems displace static workstation legacy formats. Adjustable-height mechanisms and cable management integration are becoming baseline expectations rather than premium differentiators.
For Market Incumbents: Extend enterprise ergonomic expertise into direct-to-consumer channels before emerging digital-native brands capture remote worker mindshare. Deepen backward integration into captive adjustable-height mechanism supply to reduce Asian component dependency. Invest in CARB Phase II certification ahead of potential EPA formaldehyde standard expansion. Control distribution through owned e-commerce infrastructure rather than ceding margin to third-party retail.
For New Entrants and Emerging Players: Enter via white-space targeting of accessory dwelling unit office solutions in Texas and Florida municipalities where garage conversion codes are liberalizing. The most penetrable segment is compact vertical storage systems for space-constrained California and Northeast urban markets. Pursue a sustainability-first go-to-market angle emphasizing low-emission materials and circular design credentials.
For Investors and Strategic Acquirers: The window for entry favors ergonomic seating specialists with OSHA guideline certification and established biomechanical R&D capabilities over commodity desk manufacturers. Long-term viability hinges on defensible intellectual property in adjustable-height mechanisms and durable brand recognition from corporate environments. Watch for inflection when municipal ADU legalization accelerates beyond current Sun Belt concentrations.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Launch | Bypasses furniture retail margin extraction and captures remote worker procurement data directly. |
| CARB Phase II Certification Investment | Secures placement in national retail programs as EPA formaldehyde standards tighten compliance thresholds. |
| Adjustable-Height Mechanism Supply Agreement | Reduces lead time risk from concentrated Asian component sources for desk manufacturers. |
| Ergonomic Seating R&D Expansion | Translates OSHA guideline familiarity into consumer-facing certification-premium positioning. |
| Accessory Dwelling Unit Product Line Development | Captures secondary demand from municipal code changes in high-growth Sun Belt metropolitan corridors. |
Research Approach
Multi-period observation of residential construction permits, remote worker migration patterns, and furniture retail channel mix anchored the trend analysis, supplemented by interviews with furniture manufacturing executives, ergonomic product designers, procurement managers at multi-channel retailers, and municipal planning officials across Texas, Florida, and California. Secondary validation drew from EPA formaldehyde emission databases, Consumer Product Safety Commission stability testing records, California Air Resources Board certification registries, and customs trade data on furniture component imports. Bottom-up demand modeling triangulated against top-down market sizing from construction activity and household formation data.
Segment-weighting across product type, material composition, and end-user archetype informed the analytical framework throughout the projection horizon. Modeled dimensions included desk versus chair versus storage unit demand splits, wood versus metal versus plastic material shares, and remote worker versus freelancer versus small business procurement patterns. CAGRs were derived from regression analysis against macro drivers including residential construction activity, hybrid work policy stabilization, and regulatory compliance cost trajectories. Forecast inputs incorporated lumber futures price volatility and adjustable-height mechanism cost decline curves.
Revisions become necessary when EPA formaldehyde standards expand beyond current TSCA limits, when major Asian component suppliers face trade restriction, or when municipal ADU legalization accelerates beyond modeled adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
Office Furniture Market
Office Furniture
Home Office Desk Market
Office Furniture
Indonesia Office Furniture Market
Office Furniture
US Office Furniture Market
Office Furniture
Rental Furniture Market
Office Furniture
South Korea Office Furniture Market
Office Furniture
Office Chairs Market
Office Furniture
Japan Office Furniture Market
Office Furniture
United States Furniture Market
Office Furniture
Luxury Office Furniture Market
Office Furniture
Russia Office Furniture Market
Office Furniture
China Office Furniture Market
Office Furniture
United Kingdom Office Furniture Market
Office Furniture
Asia-Pacific Office Furniture Market
Office Furniture
Canada Office Furniture Market
Office Furniture
Desk Chairs Market