
 United States Furniture Market | 2026-2036
United States Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
United States Furniture Market Analytics
Lease-to-own and rent-to-furnish programs is rewriting competitive access in the United States furniture sector, lowering capital barriers for younger consumers and apartment operators. Ashley Furniture leverages its captive manufacturing network across domestic plants to control cost position on upholstered goods. Steelcase anchors commercial workspace contracts through specification relationships with corporate procurement teams. Herman Miller differentiates via ergonomic research depth embedded in task seating design.
United States furniture comprises movable articles for seating, sleeping, storage, and work surfaces, typically constructed from engineered wood substrates, steel hardware, and polyurethane foam cushioning with textile or leather coverings, serving residential dwelling, corporate office, lodging, and institutional environments. Sofas and beds capture the largest revenue pools within product type segmentation, though hospitality-grade tables command premium pricing through durability certification requirements. The wood material segment retains volume leadership while upholstery materials generate higher per-unit margins through fabric upgrade paths. Distribution through online channels accelerates fastest, yet showrooms still dominate final purchase conversion for transactions above two thousand dollars.
The EPA oversees formaldehyde emissions under TSCA Title VI, while California's Air Resources Board enforces stricter composite wood standards that de facto shape national product design. The Consumer Product Safety Commission mandates flammability testing for upholstered furniture, influencing foam chemistry and fabric treatment choices across manufacturing. Stakeholders must monitor how evolving state-level chemical disclosure laws interact with federal preemption frameworks to determine compliance architecture and sourcing flexibility.
Market Dynamics
Lease-to-own financing structures are compressing traditional retail cycles across the United States furniture sector, forcing manufacturers to reconfigure production planning around rental fleet replenishment rather than discrete household purchases.
Growth Catalysts
- CARB Phase 2 compliance:California's formaldehyde emissions standards have normalized low-emission engineered wood substrates nationwide, opening procurement pathways for residential developers previously blocked by indoor air quality specifications.
- Texas metro corridor expansion:Dallas-Fort Worth and Austin population inflows sustain household formation rates that outpace national averages, concentrating demand for starter furniture packages.
- Water-based adhesive substitution:Chemistry advances in polyurethane dispersions eliminate solvent-based bonding in panel lamination, reducing compliance costs for domestic upholstery producers.
Market Restraints
- Lumber input volatility:Southern yellow pine and Appalachian hardwood price swings compress margin predictability for solid wood furniture producers dependent on spot market purchasing.
- Asian component concentration:Hardware, fasteners, and mechanism sourcing clusters in Zhejiang and Guangdong provinces expose finished goods assemblers to transpacific logistics disruption.
- Flammability testing bottlenecks:CPSC-mandated smolder resistance protocols for upholstered seating create 8-16 week certification delays that mismatch against fast-fashion inventory cycles.
Strategic Opportunities
- Modular furnishing packages:Multifamily residential developers in Sun Belt metros increasingly specify standardized unit fit-outs, creating volume contracts that amortize design costs across thousand-unit portfolios.
- Online channel conversion:Digital platforms now capture transactions below two thousand dollars where showroom economics previously excluded remote buyers, expanding addressable market depth.
- Ergonomic specification depth:Corporate procurement teams embed task seating research requirements into RFPs, rewarding manufacturers with captive biomechanics capabilities.
Industry Challenges
- Foam chemistry reformulation:CPSC flammability mandates require continuous adjustment of polyurethane formulations, forcing R&D cycles that strain mid-tier producers without captive laboratories.
- Last-mile delivery fragmentation:White-glass assembly and installation services resist standardization, creating customer experience variance that erodes brand equity for direct-to-consumer entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Furniture Market |
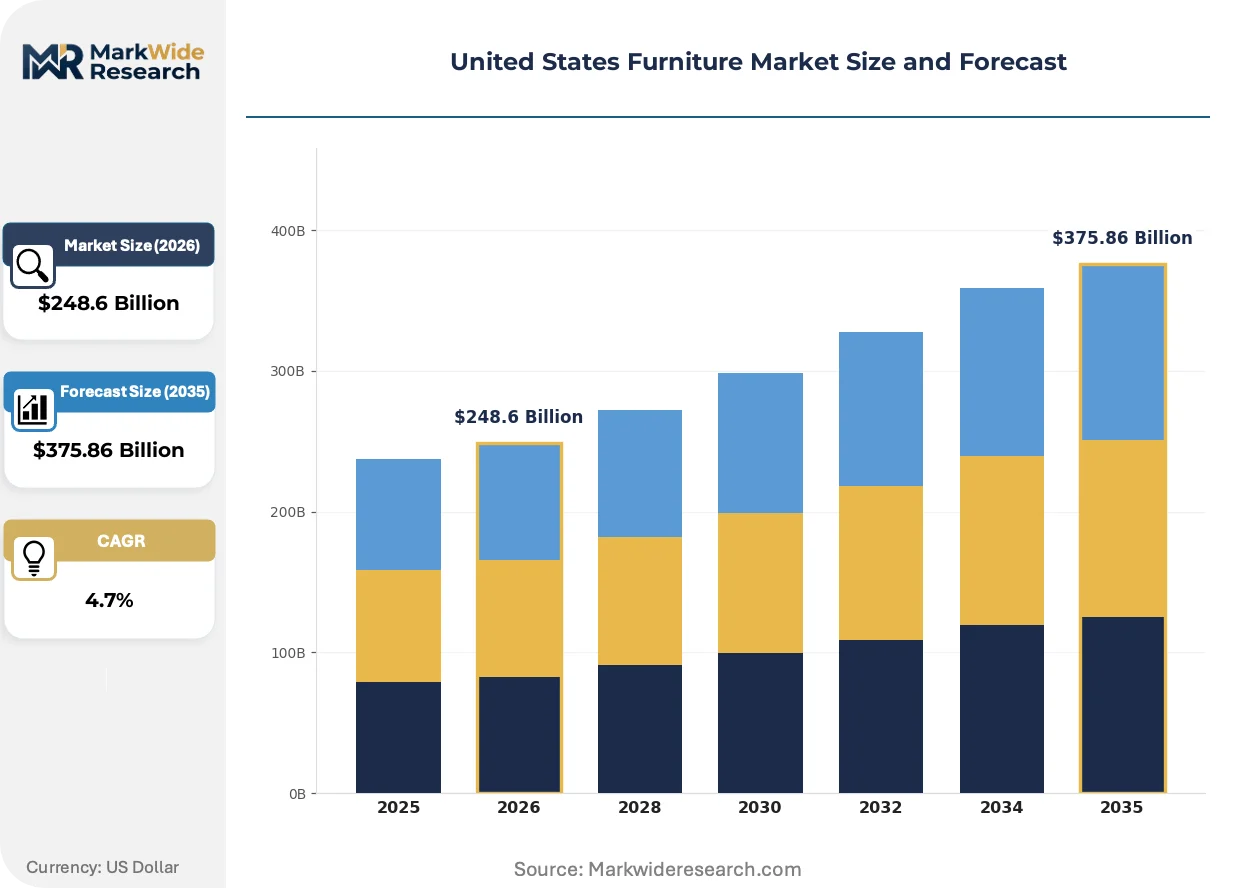
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $375.86 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Beds, Chairs, Tables Material: Wood, Metal, Upholstery, Plastic End User: Residential, Commercial, Hospitality, Educational Distribution Channel: Online, Showrooms, Wholesale, Direct Sales |
| Companies Covered | La-Z-Boy, Sauder Woodworking, Steelcase, Bernhardt, HNI Corporation, Ashley Furniture, Herman Miller, Kimball Hospitality, Haworth, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Furniture Market Evolving Landscape
Digital specification tools and predictive inventory systems are restructuring how furniture moves from factory floor to occupied dwelling, compressing traditional design-to-delivery timelines.
Generative design software is collapsing the traditional furniture prototyping phase. Residential and hospitality buyers now expect photorealistic renderings and dimensional accuracy before physical samples ship. This compression eliminates 6-10 week tooling cycles for upholstered goods, enabling micro-batch production runs that match seasonal color trends.
EPA enforcement under TSCA Title VI is tightening formaldehyde monitoring across composite wood supply chains. Domestic panel producers face expanded third-party certification requirements that raise compliance costs but simultaneously lock out informal importers. California's Air Resources Board maintains de facto national standard-setting authority through its stricter emission thresholds.
Corporate furniture procurement now bundles installation, reconfiguration, and end-of-life removal into single-source contracts. Facility managers in tech and financial services verticals prioritize vendor partners with circular logistics capabilities over pure product specifications. This service integration is most visible in Austin and Seattle office markets where lease flexibility demands frequent spatial reconfiguration.
United States Furniture Market Segmentation
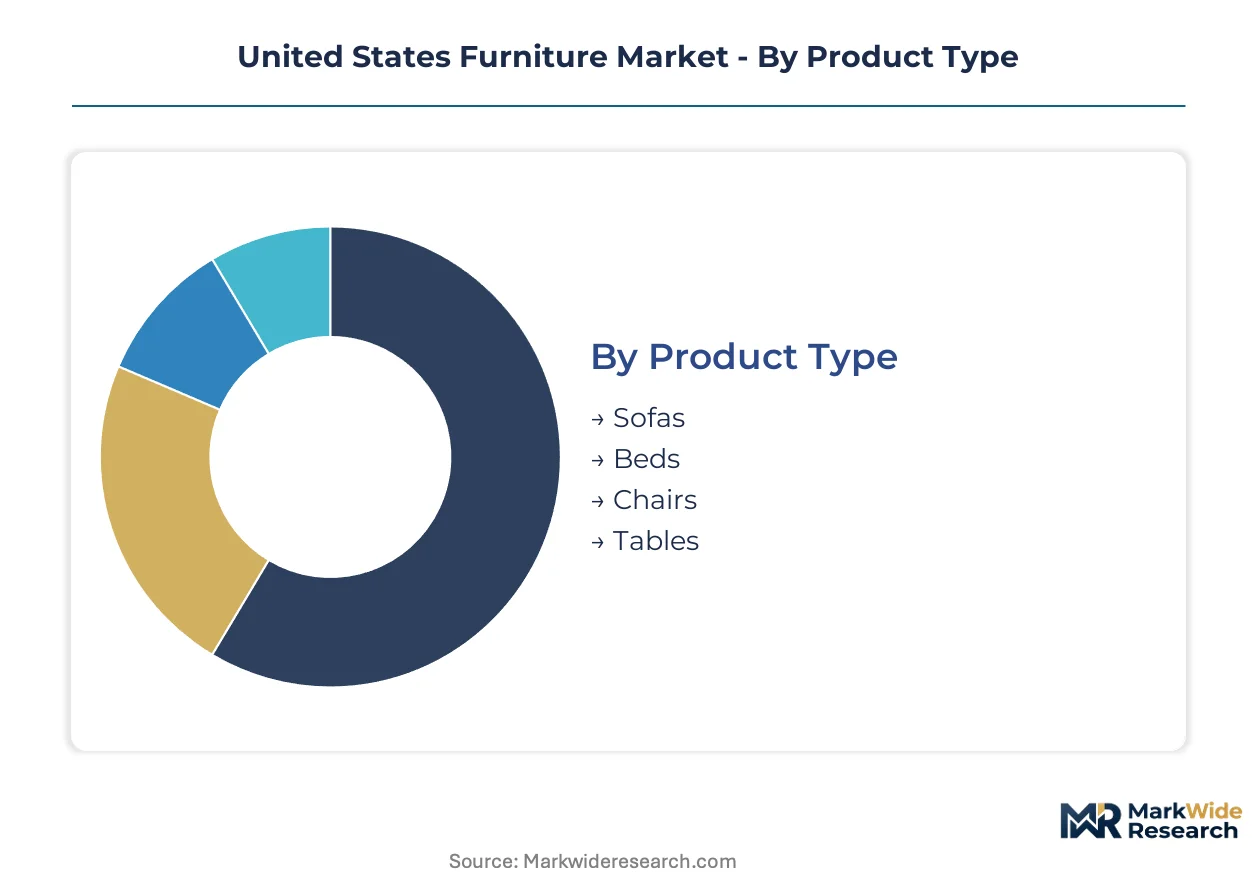
Furniture purchasing patterns diverge sharply across use cases and procurement channels, requiring manufacturers to maintain parallel production lines and inventory pools. Each segmentation dimension reveals distinct margin structures and specification requirements that shape competitive positioning.
Product Type:
Cost tier determines manufacturing complexity and upholstery labor intensity across the four core furniture categories.
- Sofas:Multi-cushion seating systems combine hardwood frames with sinuous spring suspension and high-resilience foam cores. Demand concentrates in Texas metro corridors where multifamily developers specify modular three-seat configurations for starter apartments. CARB Phase 2 compliance on engineered wood substrates has become a baseline procurement filter.
- Beds:Platform and panel bed designs integrate slat support systems with upholstered or wood headboards. Hospital-grade adjustable bases command premium specification in senior living developments across Florida and Arizona. Water-based adhesive substitution in panel lamination reduces compliance costs for domestic producers.
- Chairs:Task seating dominates commercial procurement with ergonomic research requirements embedded in corporate RFPs.
- Tables:Hospitality-grade surfaces require durability certification that extends production cycles but captures premium pricing.
Sofas hold installed capacity. Beds is rotating up the share rankings.
Material:
Application environment dictates substrate selection, with indoor air quality specifications increasingly filtering procurement decisions.
- Wood:Solid hardwood and engineered panel substrates retain volume leadership across residential furniture. Southern yellow pine price volatility compresses margin predictability for producers dependent on spot market purchasing. EPA TSCA Title VI enforcement tightens formaldehyde monitoring across composite wood supply chains.
- Upholstery:Fabric and leather coverings generate higher per-unit margins through upgrade paths and textile customization. Corporate procurement teams specify commercial-grade crypton or vinyl for high-traffic environments. CPSC flammability mandates require continuous foam chemistry reformulation.
- Metal:Steel hardware and aluminum framing anchor outdoor and commercial collections with powder-coat durability.
- Plastic:Polypropylene and polycarbonate components serve cost-sensitive outdoor and educational segments.
Wood holds installed capacity. Upholstery is rotating up the share rankings.
End User:
Customer type determines specification depth, with commercial and institutional buyers embedding service and circular logistics into contract terms.
- Residential:Single-family and multifamily dwelling units drive volume demand for starter furniture packages. Lease-to-own financing structures compress traditional retail cycles and force production planning around rental fleet replenishment. Dallas-Fort Worth and Austin population inflows sustain household formation rates above national averages.
- Commercial:Corporate office and workspace procurement bundles installation, reconfiguration, and end-of-life removal into single-source contracts. Facility managers in Austin and Seattle office markets prioritize vendors with circular logistics capabilities. Steelcase and Herman Miller anchor specification relationships through captive biomechanics research.
- Hospitality:Lodging and foodservice operations require durability certification and rapid replacement cycles.
- Educational:K-12 and university procurement emphasizes cost containment and institutional-grade construction standards.
Residential holds installed capacity. Commercial is rotating up the share rankings.
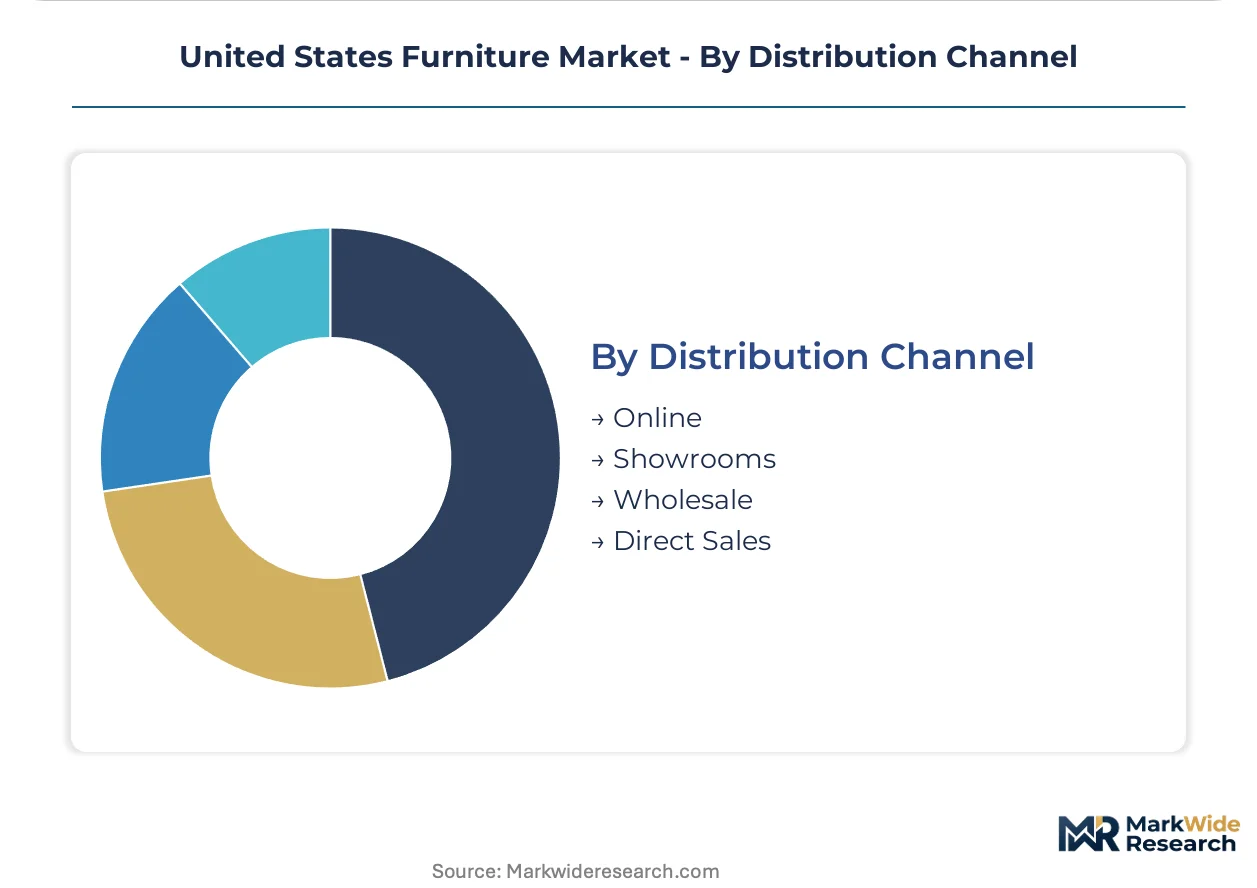
Distribution Channel:
Volume concentration and margin capture split across physical and digital touchpoints, with transaction size determining channel economics.
- Online:Digital platforms capture transactions below two thousand dollars where showroom economics previously excluded remote buyers. Last-mile delivery fragmentation for white-glove assembly resists standardization and creates customer experience variance. Ashley Furniture leverages captive manufacturing networks to control cost position on direct-to-consumer upholstered goods.
- Showrooms:Physical display spaces dominate final purchase conversion for transactions above two thousand dollars. Photorealistic rendering and dimensional accuracy expectations now precede physical sample shipments. Generative design software eliminates six-to-ten week tooling cycles for micro-batch production.
- Wholesale:Volume contracts with multifamily developers and hospitality operators amortize design costs across thousand-unit portfolios.
- Direct Sales:Corporate and institutional procurement teams engage manufacturers through specification relationships and RFP processes.
Showrooms hold installed capacity. Online is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA TSCA Title VI enforcement and California CARB Phase 2 standards have established de facto national emission benchmarks that shape manufacturing location decisions across domestic production networks.
California
CARB Phase 2 formaldehyde emissions standards exceed federal thresholds and drive specification requirements for low-emission engineered wood substrates. The California Air Resources Board maintains third-party certification protocols that raise compliance costs for panel producers. Los Angeles and San Francisco Bay Area housing markets concentrate demand for premium upholstered goods with indoor air quality credentials.
Texas
Dallas-Fort Worth and Austin metro corridors sustain household formation rates above national averages through sustained population inflows. Multifamily residential developers specify modular furnishing packages at scale across thousand-unit portfolios. Houston's port infrastructure anchors import distribution for Asian hardware and mechanism components.
North Carolina
Historical furniture manufacturing clusters in the Piedmont Triad retain upholstered goods production capacity and skilled labor pools. EPA regional enforcement offices coordinate TSCA Title VI compliance monitoring across composite wood supply chains. High Point maintains specification relationships with hospitality and commercial procurement teams.
Michigan
Grand Rapids anchors commercial furniture manufacturing with captive biomechanics research capabilities embedded in corporate procurement relationships. Steelcase and Herman Miller specification networks concentrate in this metro. State-level workforce development programs support advanced manufacturing transitions in panel lamination and water-based adhesive chemistry.
Pennsylvania
Appalachian hardwood sourcing corridors supply solid wood furniture producers with spot market exposure to southern yellow pine price volatility. Pittsburgh and Philadelphia distribution networks bridge mid-Atlantic residential demand with Midwest manufacturing capacity. CPSC flammability testing facilities in the Northeast create certification bottlenecks for upholstered seating producers.
United States Furniture Market Competitive Landscape
On the supply side, the industry is tiered between scale-driven manufacturers with captive production networks and specialized firms focused on specification relationships. The vendor base spans domestic upholstery producers, engineered wood panel fabricators, and commercial workspace specialists. Two strategic archetypes dominate: vertically integrated manufacturers controlling cost position through in-house production, and research-driven firms embedding ergonomic capabilities into corporate procurement. Competitive moves center on modular package standardization for multifamily developers and service integration bundling installation with product sales.
Among domestic manufacturers, Ashley Furniture, Steelcase, and Herman Miller exemplify contrasting competitive positions. Ashley Furniture occupies the scale-driven archetype with manufacturing network control over upholstered goods cost structures. Steelcase anchors commercial workspace contracts through specification depth with corporate procurement teams. Herman Miller represents the research-anchored tier with ergonomic capabilities embedded in task seating design requirements.
| Leading Market Players |
|---|
| La-Z-Boy |
| Sauder Woodworking |
| Steelcase |
| Bernhardt |
| HNI Corporation |
| Ashley Furniture |
| Herman Miller |
| Kimball Hospitality |
| Haworth |
| Others |
Value Network & Pricing Analysis
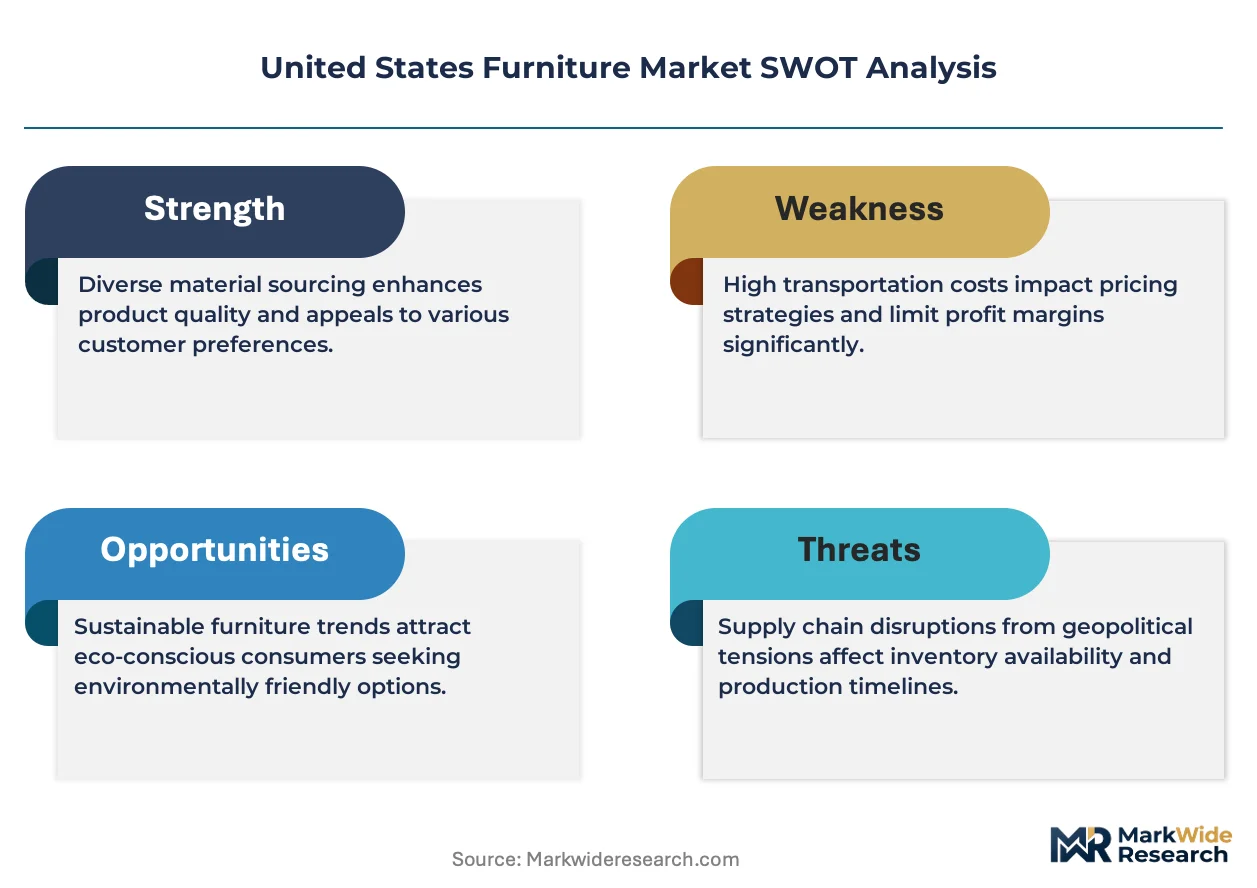
Zhejiang and Guangdong province hardware clusters feed directly into margin compression for domestic upholstered goods assemblers, concentrating pricing power upstream while finished goods compete on thin spreads in Texas multifamily procurement.
Pricing Analysis
Certification level (CARB Phase 2 versus baseline TSCA Title VI compliance) creates the primary spread between premium engineered wood substrates and commodity panel alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by indoor air quality credentials and upholstery fabric grade. Pricing pressure stems from lumber input volatility compressing margin predictability for solid wood producers. Multifamily developers in Dallas-Fort Worth exhibit highest price sensitivity, while corporate procurement teams in Austin and Seattle prioritize ergonomic specification depth over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates risk planning for mechanism and fastener sourcing. Hardware components draw from Zhejiang province, Guangdong province, and domestic Michigan metalworking clusters. Southern yellow pine and Appalachian hardwood spot markets anchor raw material dependencies. Single-source vulnerability concentrates in transpacific container logistics for Asian component replenishment. Distribution runs through Houston port infrastructure bridging import receipt with Texas metro corridor demand concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lease-to-own platform economics are restructuring furniture access as a service-layer business, with interoperability between rental fleet management software and developer procurement systems becoming the decisive ecosystem battleground.
For Market Incumbents: Entrench specification relationships with multifamily developers through modular package standardization that amortizes design costs across thousand-unit portfolios. Ashley Furniture's captive manufacturing network demonstrates how in-house production of upholstered goods defends cost position against direct-to-consumer entrants. Prioritize water-based adhesive chemistry R&D to maintain CARB Phase 2 compliance leadership as EPA TSCA Title VI enforcement tightens. For New Entrants and Emerging Players: Establish a beachhead in online channel conversion for transactions below two thousand dollars where showroom economics previously excluded remote buyers. White-space concentrates in last-mile delivery standardization for white-glove assembly services that resist scale. Target circular logistics capabilities for Austin and Seattle corporate office markets where facility managers bundle installation and reconfiguration into single-source contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed commercial furniture specialists holding specification relationships with tech and financial services verticals. Long-term viability hinges on service integration depth rather than pure product manufacturing scale. Watch generative design software adoption as the inflection signal separating micro-batch responsive producers from legacy tooling-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Package Standardization | Enables thousand-unit portfolio amortization for Sun Belt multifamily developers. |
| Water-Based Adhesive Transition | Reduces CARB Phase 2 compliance costs for domestic upholstery panel producers. |
| Direct-to-Consumer Platform Launch | Captures sub-two-thousand-dollar transactions previously excluded by showroom economics. |
| Circular Logistics Capability Buildout | Addresses Austin and Seattle corporate demand for bundled installation and reconfiguration. |
| Generative Design Software Integration | Eliminates six-to-ten week tooling cycles for seasonal micro-batch production runs. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Interview subjects included multifamily development procurement directors, corporate facility managers, upholstery plant operations heads, EPA regional enforcement officers, and composite wood panel technical directors. Secondary sources encompassed EPA TSCA Title VI compliance filings, California Air Resources Board certification records, customs import data for Asian hardware components, and SEC 10-K disclosures from publicly traded furniture manufacturers. Bottom-up production capacity estimates triangulated against top-down demand modeling across Texas metro corridor household formation data.
Forecast inputs considered product type segmentation across sofas, beds, chairs, and tables; material tiers spanning wood, upholstery, metal, and plastic; end-user categories from residential through commercial and hospitality; and distribution channel splits between online, showroom, wholesale, and direct sales. CAGRs derived from regression analysis against population inflow projections and multifamily construction permits. Industry-specific inputs included CARB Phase 2 adoption curves and water-based adhesive substitution rates across the analysis window.
Sensitivities concentrate around lumber spot price volatility, transpacific logistics disruption, and CPSC flammability testing timeline extensions. Forecasts embed assumptions regarding sustained Texas population inflows and EPA enforcement continuity. Macroeconomic contraction, regulatory preemption conflicts between state and federal chemical disclosure laws, or breakthroughs in foam chemistry reformulation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
South Korea Office Furniture Market
Office Furniture
India Office Furniture Market
Office Furniture
Europe Office Furniture Market
Office Furniture
Indonesia Office Furniture Market
Office Furniture
Ergonomic Office Furniture Market
Office Furniture
United States Home Office Furniture Market
Office Furniture
Office Chairs Market
Office Furniture
Brazil Office Furniture Market
Office Furniture
Home Office Spending Market
Office Furniture
Office Furniture Edgebands Market
Office Furniture
Office Furniture Market
Office Furniture
Home Office Desk Market
Office Furniture
Asia-Pacific Office Furniture Market
Office Furniture
Furniture and Home Furnishings Market
Office Furniture
Standing Desk Balance Boards Market
Office Furniture
Institutional Furniture Market