
 Luxury Office Furniture Market | 2026-2036
Luxury Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Office Furniture Market Insights
Italy is reconfiguring European supply dynamics through its concentration of design-forward manufacturing clusters in Milan and Brianza. Vitra leverages its Basel-adjacent production network to sustain premium positioning across Northern European corporate headquarters. Herman Miller anchors North American demand through its deep integration with technology sector campus expansions. Steelcase competes aggressively on configurable workstation systems for hybrid workplace rollouts.
Luxury office furniture comprises high-specification workplace furnishings engineered for executive, board-level, and premium collaborative environments, typically incorporating hardwood substrates, full-grain leather upholstery, precision-machined metal hardware, and ergonomic adjustments exceeding ANSI/BIFMA baseline standards. Its primary commercial purpose is to signal organizational stature while supporting extended-duration executive productivity through biomechanical optimization. Contemporary and modern style categories now command the dominant margin pools as financial and professional services firms prioritize aesthetic differentiation in talent recruitment. Wood and leather material segments retain premium price positioning, though metal-glass hybrid constructions are gaining share in technology sector installations where lighter visual mass aligns with open-plan architectures.
FDA oversight of antimicrobial surface claims and EPA certification requirements for low-emission finishes are tightening material specification protocols in US commercial interiors, while REACH and CE marking frameworks in Europe govern chemical content and structural safety thresholds for imported components. California's CARB Phase 2 formaldehyde standards and New York City's Local Law 97 carbon intensity rules are cascading into national procurement specifications through multinational corporate real estate standardization. Stakeholders must monitor how evolving building certification schemes such as WELL and LEED v5 integrate furniture-level health and circularity criteria into tenant improvement scoring.
Market Dynamics
The EU Green Deal's embodied carbon disclosure rules for building products are redirecting procurement specifications across corporate real estate portfolios, compressing supplier qualification timelines and elevating certified sustainable material premiums.
Growth Catalysts
- EU Green Deal carbon disclosure mandates:Procurement officers in Frankfurt and Munich office completions now require Environmental Product Declarations, accelerating specification of certified sustainable wood and recycled metal frames.
- Technology sector campus expansions:Northern California and Seattle headquarters are commissioning premium collaborative environments with lighter visual mass, driving demand for metal-glass hybrid constructions.
- Manhattan and London fit-out budget expansion:Law firms and private equity headquarters are increasing executive suite allocations, concentrating demand for hardwood substrates and full-grain leather upholstery.
Market Restraints
- European oak and walnut supply concentration:Brianza and Milan manufacturing clusters face extended lead times from certified forestry sources, constraining premium wood segment expansion.
- California CARB Phase 2 compliance costs:Formaldehyde emission testing and documentation requirements add 8-12% to landed costs for Asian-sourced substrates entering US distribution.
- Steel and aluminum price volatility:Precision-machined metal hardware components face input cost swings that compress margin buffers on fixed-price corporate contracts.
Strategic Opportunities
- WELL and LEED v5 furniture-level integration:Building certification schemes are incorporating health and circularity criteria into tenant improvement scoring, creating specification advantages for compliant manufacturers.
- Hybrid workplace workstation configurability:Financial services firms in Singapore and Sydney are unbundling traditional office suites into modular premium zones, opening demand for reconfigurable systems.
- Biomechanical optimization premiumization:Ergonomic adjustments exceeding ANSI/BIFMA baseline standards command 35-50% price multiples in extended-duration executive productivity applications.
Industry Challenges
- Antimicrobial surface claim substantiation:FDA oversight of efficacy documentation and EPA certification for low-emission finishes extends product development timelines by 6-9 months.
- REACH chemical content verification:European importers face complex supply chain auditing for SVHC compliance across multi-tier component sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Office Furniture Market |
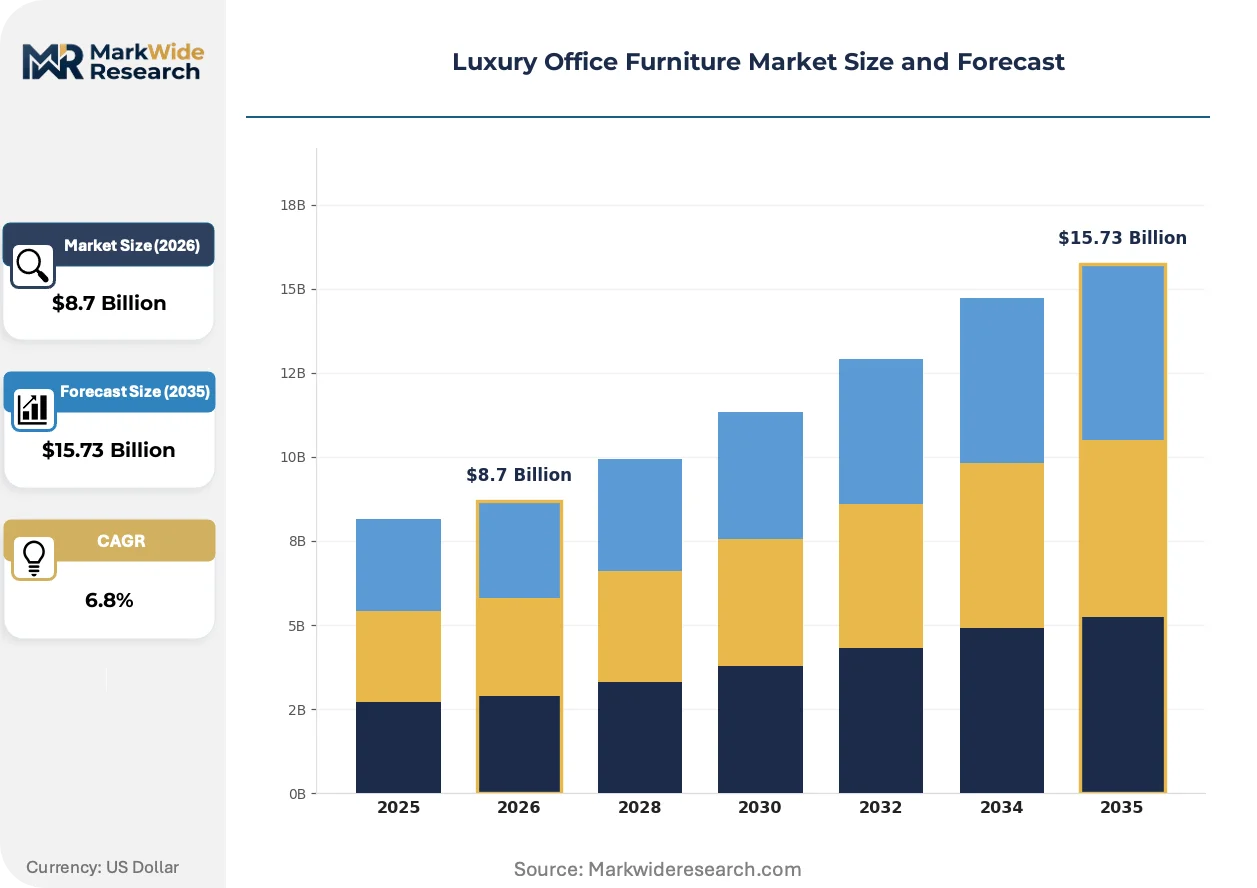
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Workstations, Filing Cabinets Material: Wood, Leather, Metal, Glass Style: Contemporary, Traditional, Modern, Minimalist End User: Corporations, Startups, Co-working Spaces, Freelancers |
| Companies Covered | Vitra, Teknion, Steelcase, Global Furniture Group, HNI Corporation, Herman Miller, Okamura, Bernhardt, Haworth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Office Furniture Market Trends and Innovations
Aesthetic differentiation has displaced pure functionality as the primary specification driver, with financial and professional services firms prioritizing design-forward environments in talent competition.
Biometric-adjustable seating is migrating from fixed-position executive chairs to dynamic workstations. Technology sector installations in Seattle and Austin are specifying pressure-mapping sensors and automated lumbar adaptation. This migration from passive ergonomics to active biomechanical support is compressing replacement cycles and elevating service contract attach rates.
REACH SVHC candidate list expansions are forcing reformulation of leather tanning agents and wood finishing compounds. Italian manufacturers in Brianza are accelerating water-based coating transitions ahead of 2025 sunset dates. The contemporary style category faces the most acute compliance pressure given its reliance on high-touch surface treatments.
Corporate real estate standardization is consolidating procurement authority. Multinational firms are deploying unified specification playbooks that cascade California and New York City carbon intensity rules into national vendor qualification requirements. This concentration is most visible in law firm and consulting office rollouts across London, Frankfurt, and Singapore.
Luxury Office Furniture Market Segmentation
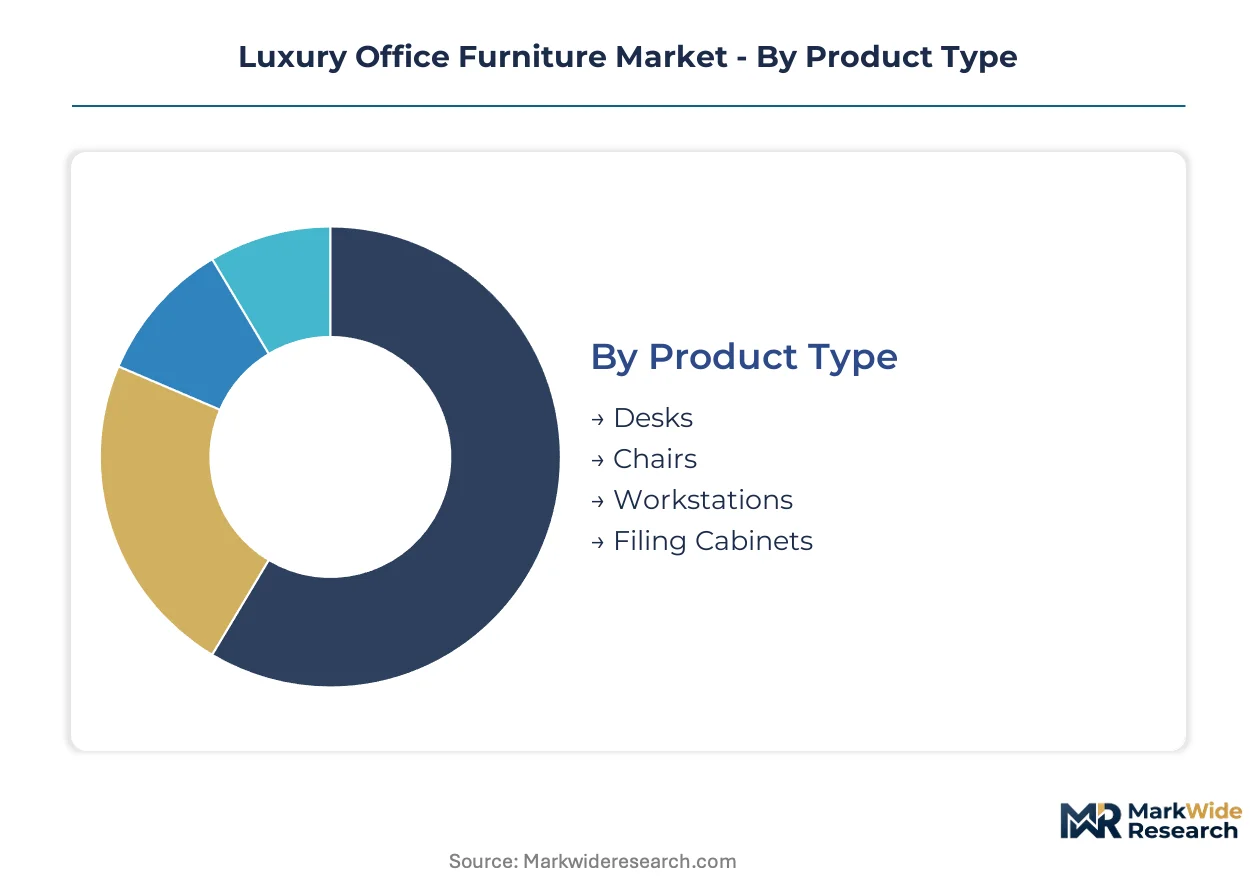
Segmentation in luxury office furniture reveals divergent service requirements across product categories. High-value executive seating demands intensive calibration support, while modular workstation systems prioritize rapid reconfiguration assistance. Understanding these patterns enables manufacturers to align warranty structures and field service networks with actual utilization profiles.
Product Type:
After-sales-service intensity varies dramatically across product categories, with precision-adjustable seating requiring ongoing ergonomic calibration versus fixed-surface desks needing minimal intervention.
- Chairs:Biomechanical seating with automated lumbar adaptation and pressure-mapping sensors demands scheduled technician visits for sensor calibration and pneumatic mechanism servicing. Law firms in Manhattan and London now specify 5-year comprehensive service contracts alongside executive chair purchases, treating maintenance as a bundled operational expense rather than discretionary add-on.
- Workstations:Configurable systems with modular power integration and height-adjustable surfaces require rapid-response reconfiguration teams. Technology sector campus expansions in Northern California commission quarterly layout adjustments, creating recurring service revenue streams that offset initial hardware margin compression.
- Desks:Hardwood executive desks with integrated cable management and precision-machined hardware concentrate demand in private equity headquarters.
- Filing Cabinets:Secure storage with biometric locking systems serves compliance-sensitive legal and financial services environments.
Chairs hold the largest share; momentum sits with workstations.
Material:
Cost tier stratification separates certified sustainable inputs commanding premium positioning from standardized substrates facing procurement commoditization pressures.
- Wood:European oak and walnut from certified forestry sources anchor executive suite specifications, with Environmental Product Declarations now mandatory for Frankfurt and Munich office completions. Brianza manufacturing clusters face extended lead times from FSC-certified suppliers, constraining volume scalability despite sustained price premiums.
- Leather:Full-grain upholstery from European tanneries faces REACH SVHC compliance pressure, accelerating water-based finishing transitions ahead of regulatory sunset dates. Italian manufacturers absorb 12-18% reformulation costs while maintaining positioning against synthetic alternatives.
- Metal:Recycled aluminum and precision-machined steel hardware gain share in technology sector installations seeking lighter visual mass.
- Glass:Tempered glass surfaces with low-iron clarity serve collaborative environments prioritizing open sightlines and natural light transmission.
Wood retains dominant positioning; metal is expanding most quickly.
Style:
Application context determines style selection, with financial services talent competition driving aesthetic differentiation in client-facing environments.
- Contemporary:Clean-lined forms with mixed material palettes dominate financial and professional services firm specifications, where recruitment objectives override pure functional procurement. This category faces acute REACH compliance pressure given reliance on high-touch surface treatments requiring intensive chemical content verification.
- Modern:Reduced ornamentation with emphasis on proportional harmony attracts technology sector buyers seeking visual coherence with open-plan architectures. Seattle and Austin headquarters specify this category for premium collaborative zones, unbundling traditional executive suite configurations.
- Traditional:Ornate detailing with heritage reference points persists in established law firm partnerships.
- Minimalist:Stripped-down forms with maximum material honesty serve boutique consultancy environments.
Contemporary commands the largest share; modern shows steepest expansion trajectory.
End User:
Customer type segmentation reveals procurement authority concentration, with multinational corporate real estate standardization cascading specifications across distributed portfolios.
- Corporations:Unified specification playbooks deployed by multinational firms now integrate California CARB Phase 2 and New York City Local Law 97 requirements into national vendor qualification. This concentration compresses supplier diversity while elevating compliance documentation burdens for qualified vendors.
- Co-working Spaces:Flexible lease structures demand rapid-deployment furniture systems with residual value recovery mechanisms. Singapore and Sydney operators prioritize reconfigurable premium zones over fixed installations, opening modular system demand previously captured by traditional office leases.
- Startups:Venture-backed firms in growth phases prioritize lease flexibility over capital-intensive ownership.
- Freelancers:Individual practitioners represent fragmented demand with high service cost-to-revenue ratios.
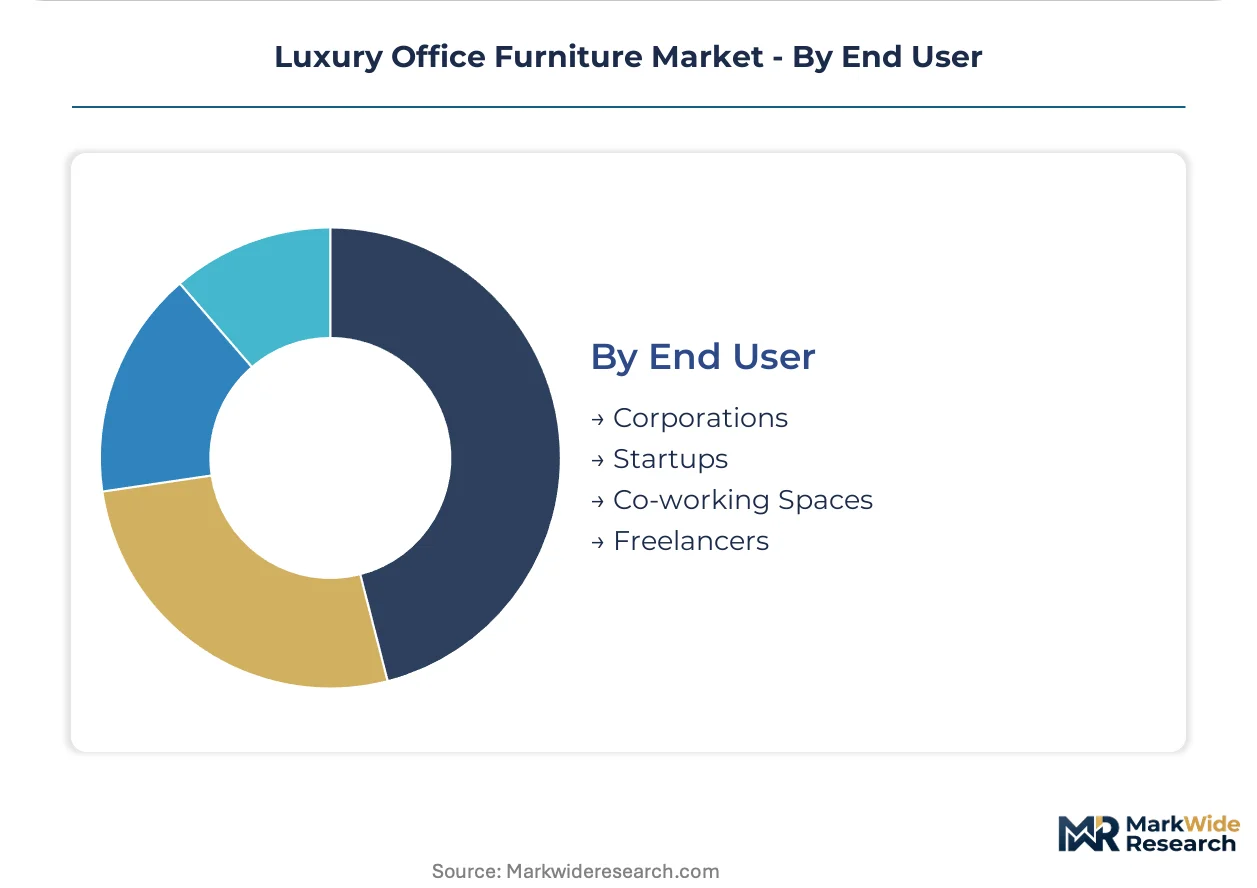
Corporations hold the largest share; co-working spaces are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal embodied carbon disclosure rules for building products are redirecting procurement specifications across corporate real estate portfolios, with Germany's ECHA REACH framework governing chemical content verification for SVHC compliance across multi-tier component sourcing.
Germany
Frankfurt and Munich office completions are setting new benchmarks for workplace quality, with Environmental Product Declarations now mandatory for certified sustainable wood and recycled metal frame specifications. ECHA REACH SVHC candidate list expansions are forcing Brianza-sourced leather tanning agent reformulations. The Hesse manufacturing corridor around Frankfurt is absorbing 12-18% water-based coating transition costs ahead of 2025 regulatory sunset dates.
United States
Manhattan law firms and private equity headquarters are expanding fit-out budgets for executive suites, concentrating demand for hardwood substrates and full-grain leather upholstery. FDA oversight of antimicrobial surface claims and EPA certification requirements for low-emission finishes are tightening material specification protocols. Northern California and Seattle technology sector campuses are commissioning premium collaborative environments with lighter visual mass, driving metal-glass hybrid construction specifications.
United Kingdom
London financial services firms are prioritizing aesthetic differentiation in talent recruitment, with contemporary and modern style categories commanding dominant margin pools. CE marking frameworks govern structural safety thresholds for imported components entering corporate real estate portfolios. The City of London and Canary Wharf clusters are unbundling traditional executive suite configurations into modular premium zones.
Italy
Milan and Brianza manufacturing clusters are reconfiguring European supply dynamics through design-forward concentration, though facing extended lead times from FSC-certified European oak and walnut sources. REACH compliance pressure is accelerating water-based finishing transitions in high-touch surface treatments. Lombardy's furniture production network is maintaining premium positioning against synthetic alternatives despite reformulation cost absorption.
Singapore
Financial services firms are unbundling traditional office suites into modular premium zones, opening demand for reconfigurable workstation systems previously captured by fixed installations. Co-working space operators prioritize rapid-deployment furniture systems with residual value recovery mechanisms. The central business district is absorbing hybrid workplace rollout specifications from multinational corporate real estate standardization playbooks.
Luxury Office Furniture Market Competitive Landscape
Capability concentration sits with design-forward European manufacturers; scale advantage sits with North American campus integration specialists. The vendor base stratifies across three tiers: heritage European houses with Milan and Brianza production networks, technology sector campus integrators with configurable workstation depth, and regional fabricators serving compliance-sensitive legal and financial services environments. Dominant competitive moves include strategic partnerships for embodied carbon certification acceleration and portfolio diversification into biometric-adjustable seating with automated lumbar adaptation.
Within the European heritage tier, Vitra leverages its Basel-adjacent production network to sustain premium positioning across Northern European corporate headquarters. Herman Miller anchors North American demand through deep integration with technology sector campus expansions in Northern California and Seattle. Steelcase competes aggressively on configurable workstation systems for hybrid workplace rollouts, representing the scale-driven archetype with rapid-response reconfiguration service networks.
| Leading Market Players |
|---|
| Vitra |
| Teknion |
| Steelcase |
| Global Furniture Group |
| HNI Corporation |
| Herman Miller |
| Okamura |
| Bernhardt |
| Haworth |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Asian substrate manufacturing is compressing margin buffers for mid-tier suppliers while elevating pricing power for European heritage manufacturers with certified sustainable material access. This utilization divergence is forcing procurement officers to accept extended lead times for FSC-certified European oak or absorb compliance premiums for California CARB Phase 2 documentation.
Pricing Analysis
Geographic price spreads between Brianza-sourced executive seating and Asian-manufactured alternatives have widened as EU Green Deal disclosure rules elevate certified material premiums. Three-tier pricing structure across heritage European, North American campus-integrated, and regional fabricator levels reflects brand positioning and certification depth. Cost compression in metal-glass hybrid constructions is intensifying because steel and aluminum input volatility erodes fixed-price contract margins. Co-working space operators exhibit highest price sensitivity due to residual value recovery requirements, while Manhattan law firms prioritize specification compliance over unit cost.
Supply Chain Analysis
Extended payment terms from multinational corporate real estate standardization programs are straining working capital for Brianza and Milan manufacturing clusters. Geographic supply concentration centers on Italy for design-forward hardwood and leather finishing, Germany for precision-machined metal hardware, and China for standardized substrate components. Raw material dependencies draw from FSC-certified European oak and walnut, full-grain leather from European tanneries, and recycled aluminum feedstock. Single-source vulnerability in certified forestry sources constrains volume scalability. Distribution runs through direct specification relationships with corporate procurement officers and architect-designer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from synthetic leather alternatives and metal-glass hybrid constructions as technology sector buyers prioritize lighter visual mass over traditional material prestige.
For Market Incumbents: Entrench specification relationships with Manhattan and London law firms through bundled 5-year comprehensive service contracts that treat maintenance as operational expense. Anchor positioning in WELL and LEED v5 compliant product portfolios as building certification schemes integrate furniture-level health criteria. Counter synthetic substitution threats by accelerating water-based coating transitions ahead of REACH sunset dates. For New Entrants and Emerging Players: Singapore and Sydney financial services firms represent underpenetrated demand for reconfigurable premium zones unbundling traditional executive suite configurations. Target co-working space operators with rapid-deployment systems featuring residual value recovery mechanisms. Pursue go-to-market positioning through architect-designer channels rather than direct corporate procurement contests. For Investors and Strategic Acquirers: Long-term, this sits as a certification-premium play because EU Green Deal embodied carbon disclosure rules and REACH SVHC compliance are consolidating procurement authority toward documented sustainable supply chains. Target acquisition archetypes include Italian manufacturers with captive FSC-certified forestry relationships and water-based coating capabilities. Monitor technology sector campus expansion velocity as inflection indicator for metal-glass hybrid construction demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Embodied Carbon Certification Acceleration | Environmental Product Declarations now mandatory for Frankfurt and Munich office completions. |
| Biometric-Adjustable Seating Portfolio Expansion | Pressure-mapping sensors and automated lumbar adaptation command 35-50% price multiples. |
| Water-Based Coating Transition Investment | Italian manufacturers absorb reformulation costs ahead of REACH 2025 regulatory sunset dates. |
| Reconfigurable Workstation Service Network Buildout | Technology sector campuses commission quarterly layout adjustments creating recurring revenue. |
| Corporate Real Estate Direct Specification Partnership | Unified playbooks cascade California CARB Phase 2 into national vendor qualification requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of corporate real estate procurement databases, architect specification registries, and building certification scheme documentation. Primary interviews engaged furniture manufacturing executives, corporate procurement officers, sustainability compliance leads, and architect-designer specification consultants. Secondary validation drew from EU ECHA REACH substance databases, US EPA low-emission finish certifications, and FSC supply chain audit records. Bottom-up demand modeling triangulated against top-down market sizing across product type, material, style, and end user dimensions.
Forecast inputs incorporate technology sector campus expansion pipelines, hybrid workplace rollout timelines, and regulatory compliance phase-in schedules across the projection horizon. Segmentation modeling captured product type intensity variations, material certification tier stratification, style category margin differentiation, and end user procurement authority concentration. CAGRs derived from demand elasticity analysis against price premium acceptance thresholds and replacement cycle compression patterns from biometric-adjustable seating migration.
Practitioners should monitor steel and aluminum price volatility, REACH SVHC candidate list expansion timing, and technology sector capex revision announcements for early signals. Forecasts reflect assumptions regarding sustained EU Green Deal enforcement trajectory and corporate real estate standardization consolidation. Macroeconomic contraction in financial services fit-out budgets, regulatory delay in embodied carbon disclosure implementation, or accelerated synthetic material substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
India Office Furniture Market
Office Furniture
Indonesia Office Furniture Market
Office Furniture
Australia Office Furniture Market
Office Furniture
Office Furniture Market
Office Furniture
France Office Furniture Market
Office Furniture
UAE Office Furniture Market
Office Furniture
United Kingdom Office Furniture Market
Office Furniture
China Office Furniture Market
Office Furniture
Japan Office Furniture Market
Office Furniture
Office Chairs Market
Office Furniture
Home Office Furniture Market
Office Furniture
South Korea Office Furniture Market
Office Furniture
United States Furniture Market
Office Furniture
Brazil Office Furniture Market
Office Furniture
Rental Furniture Market
Office Furniture
Office Furniture Edgebands Market