
 Back-Office Outsourcing in Financial Services Market | 2026-2036
Back-Office Outsourcing in Financial Services Market Size, Share, and Industry Trends Forecast 2026-2036
Back-Office Outsourcing in Financial Services Market Analysis
Modular service bundling is rebalancing procurement patterns across the back-office outsourcing landscape. Genpact leverages its domain expertise in insurance claims and mortgage servicing to anchor multi-year client relationships. Accenture competes through aggressive automation investments, embedding RPA and generative AI into core finance and accounting workflows. IBM differentiates by combining proprietary Watson capabilities with hybrid cloud infrastructure tailored to banking compliance requirements.
Back-office outsourcing in financial services encompasses the delegation of non-client-facing operational functions—transaction processing, data management, accounting reconciliation, and regulatory compliance support—to third-party providers operating under defined service-level agreements with measurable accuracy and turnaround parameters. The primary commercial purpose centers on cost arbitrage, operational scalability, and access to specialized talent pools without the fixed overhead of captive operations. Transaction processing and compliance support represent the most mature revenue pools, while AI Solutions within process automation command the fastest expansion trajectory as financial institutions pursue straight-through processing for KYC, AML, and document-intensive workflows. Cloud-Based Solutions within delivery models are attracting disproportionate capital allocation as providers rebuild legacy platforms for API-native, elastic infrastructure.
US financial institutions navigate overlapping oversight from the SEC, OCC, and state banking regulators, each imposing vendor management and data residency requirements that shape outsourcing contract architecture. European operations fall under GDPR data-protection mandates and DORA digital operational resilience standards, which restrict cross-border data flows and mandate business-continuity testing. Stakeholders must weigh regulatory fragmentation against automation ROI when selecting delivery models and geographic concentration levels.
Market Dynamics
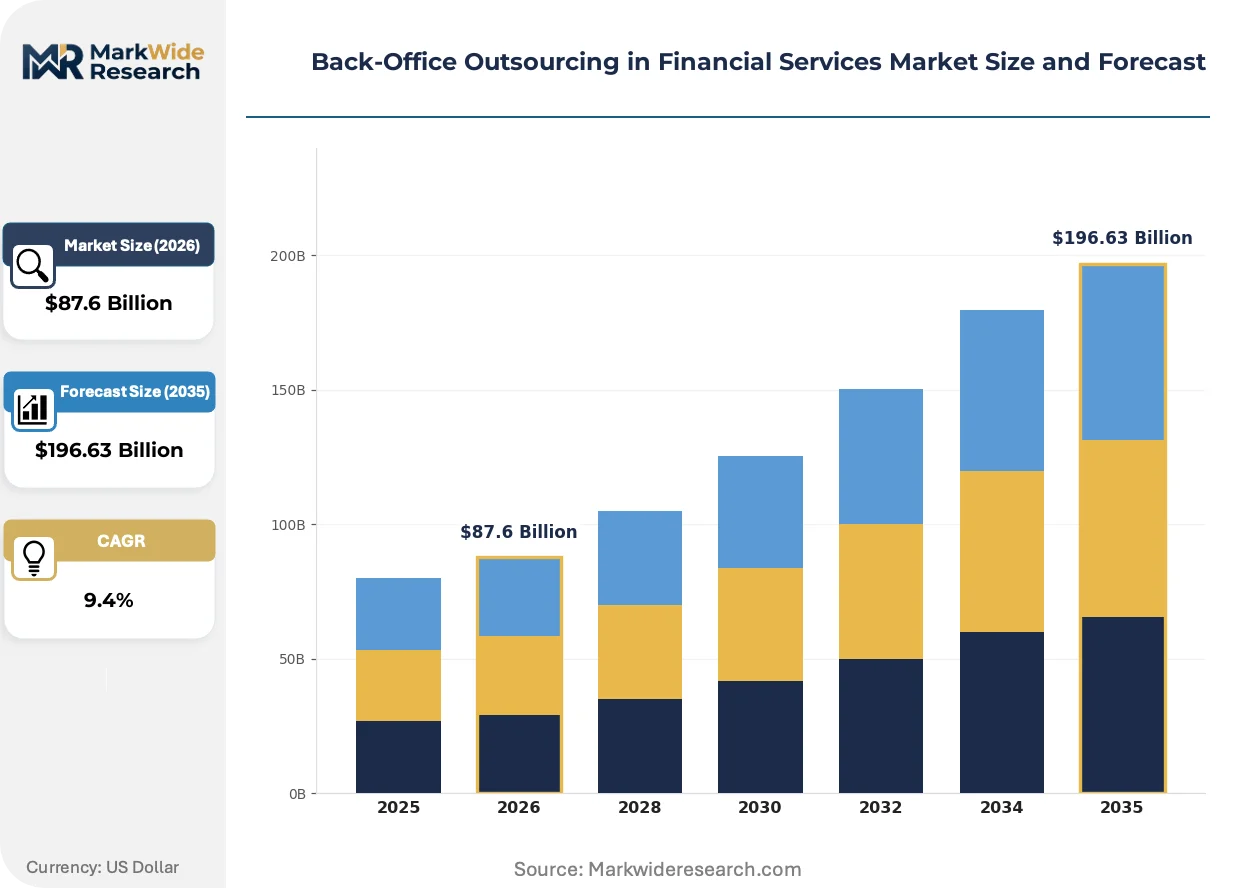
Cloud migration and AI integration are compressing service delivery economics while reconfiguring provider-client relationships around outcome metrics rather than headcount-based contracts.
Growth Catalysts
- India's delivery concentration:Bangalore and Hyderabad process substantial transaction volumes for North American and European financial institutions, creating talent pool depth and 24-hour operational coverage.
- DORA compliance mandates:Europe's Digital Operational Resilience Act requires business-continuity testing and incident reporting that drives demand for specialized third-party operational support.
- Straight-through processing:Automated KYC and AML workflows reduce manual intervention costs while accelerating customer onboarding velocity.
Market Restraints
- Cross-border data friction:GDPR restrictions on international data transfers limit geographic flexibility for European client portfolios.
- Legacy system entanglement:Core banking platforms built on COBOL architectures resist API-native integration without substantial middleware investment.
- Vendor concentration risk:Reliance on a narrow corridor of Indian delivery centers exposes operations to regional infrastructure or geopolitical disruptions.
Strategic Opportunities
- Underpenetrated insurance segments:Mid-tier carriers lag in claims automation, presenting white space for modular service bundling.
- Hybrid cloud orchestration:Converging private infrastructure with public elasticity enables tier-one banks to maintain sensitive data on-premise while bursting transactional workloads.
- RBI outsourcing guidelines:India's central bank framework for financial sector outsourcing creates regulatory clarity that accelerates contract velocity for domestic institutions.
Industry Challenges
- Domain-expertise scarcity:Professionals combining financial regulatory knowledge with AI implementation skills command premium compensation and attrition rates.
- Multi-jurisdiction compliance layering:Simultaneous adherence to SEC vendor management, OCC data residency, and state banking regulations fragments contract architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Back-Office Outsourcing in Financial Services Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transaction Processing, Data Management, Accounting Services, Compliance Support Client Type: Investment Firms, Insurance Companies, Banks, Hedge Funds Process Automation: RPA, AI Solutions, Workflow Automation, Document Processing Delivery Model: Onshore Services, Offshore Services, Hybrid Model, Cloud-Based Solutions |
| Companies Covered | Genpact, Capgemini, Deloitte, IBM, Accenture, KPMG, Infosys BPM, WNS, EY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Back-Office Outsourcing in Financial Services Market Emerging Trajectories
Workflow automation is compressing cycle times while regulatory technology investments are reshaping how compliance functions integrate with operational platforms.
Generative AI is unifying document-intensive processes across mortgage servicing and insurance claims. Tier-one banks deploy large language models to extract unstructured data from loan files and correspondence. This convergence is unifying previously siloed verification steps into continuous processing pipelines.
DORA's operational resilience testing requirements are mandating redundancy investments across European banking infrastructure. Providers must demonstrate failover capabilities and incident response protocols to retain contracts. Asset managers and payment processors face the steepest compliance ramps as they reconfigure vendor oversight frameworks.
Outcome-based contracting is displacing full-time-equivalent pricing in procurement negotiations. Buyers now specify accuracy rates and turnaround windows rather than staffing levels. This shift is most pronounced in North American mortgage servicing, where delinquency processing volume fluctuates with interest rate cycles.
Back-Office Outsourcing in Financial Services Market Segmentation
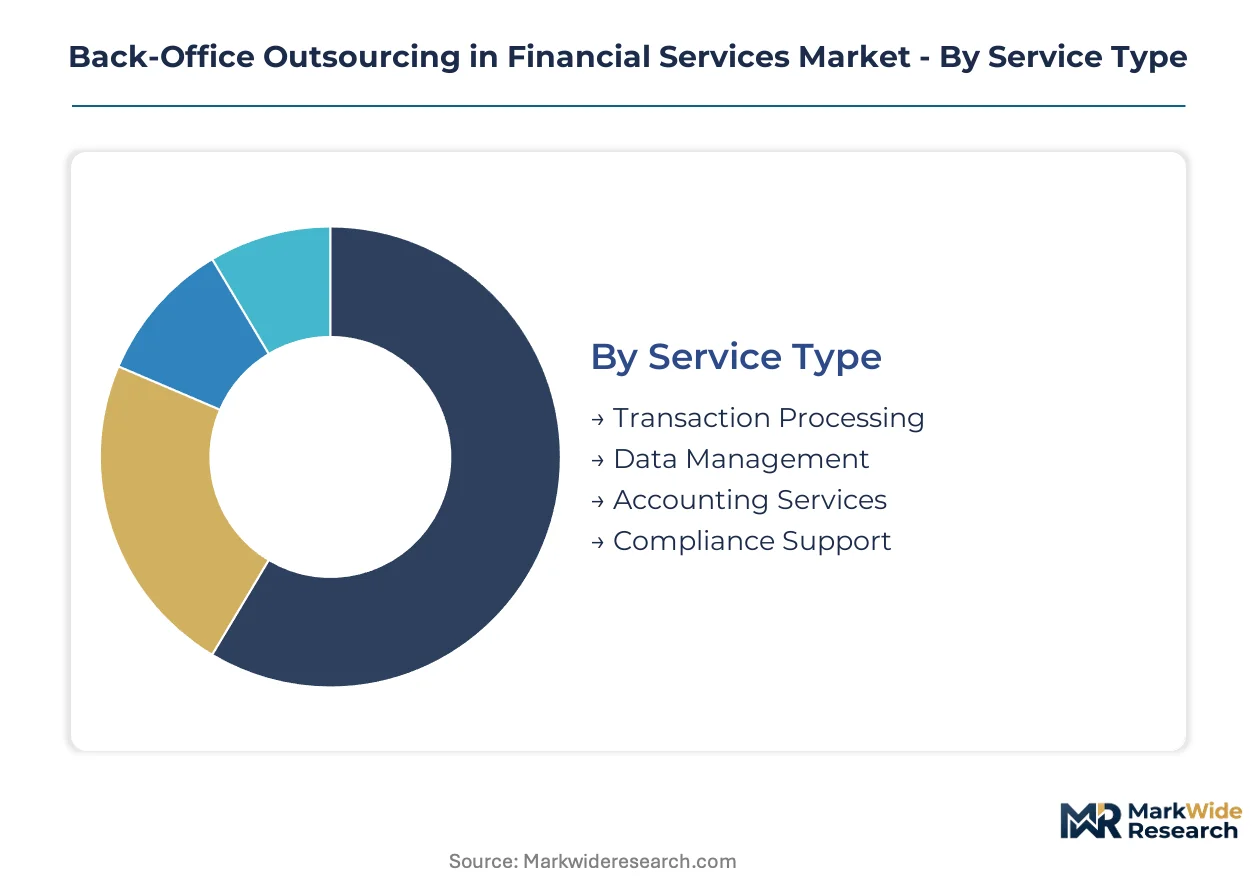
Segmentation in back-office outsourcing reveals how procurement patterns diverge between cost-driven transaction processing and premium compliance services. Financial institutions select service configurations based on regulatory exposure, automation maturity, and geographic delivery risk tolerance.
Service Type:
Volume concentrates in transaction processing while compliance support commands premium pricing.
- Transaction Processing:High-volume payment clearing, settlement reconciliation, and trade matching operations executed under strict SLA frameworks. Demand clusters at Indian delivery centers serving North American banks seeking 24-hour operational coverage and labor arbitrage.
- Compliance Support:Regulatory reporting, audit documentation, and risk data aggregation requiring specialized financial regulatory knowledge. European institutions under DORA mandates drive disproportionate investment in business-continuity testing and incident response capabilities.
- Data Management:Master data maintenance, reference data validation, and data quality assurance across fragmented banking systems.
- Accounting Services:General ledger reconciliation, financial statement preparation, and management reporting for mid-tier carriers.
Today's leader: Transaction Processing. Tomorrow's challenger: Compliance Support.
Client Type:
Procurement sophistication varies sharply between regulated banks and alternative asset managers.
- Banks:Universal and commercial banks with the most complex multi-jurisdiction vendor management requirements. US institutions navigate overlapping SEC, OCC, and state banking regulator oversight that shapes contract architecture and data residency clauses.
- Insurance Companies:Life and property-casualty carriers expanding outsourced claims processing and regulatory reporting functions. Mid-tier carriers present white space for modular service bundling as they lag in automation adoption.
- Investment Firms:Asset managers facing steep DORA compliance ramps as they reconfigure vendor oversight frameworks for operational resilience testing.
- Hedge Funds:Alternative investment managers with concentrated exposure to prime brokerage operational risk and counterparty documentation workflows.
Banks anchor current revenue pools. Insurance carriers offer the steepest expansion trajectory.
Process Automation:
Technology maturity separates RPA deployments from generative AI pilots.
- AI Solutions:Large language models extracting unstructured data from mortgage loan files and insurance correspondence. Tier-one banks deploy these capabilities to unify previously siloed verification steps into continuous processing pipelines.
- RPA:Rule-based bots handling repetitive data entry, validation, and system-to-system reconciliation tasks with measurable accuracy parameters.
- Workflow Automation:Straight-through processing for KYC and AML workflows reducing manual intervention costs while accelerating customer onboarding velocity.
- Document Processing:Intelligent capture and classification systems for paper-intensive legacy operations resistant to full digitization.
RPA dominates installed base. AI Solutions are gaining share fastest as providers embed generative capabilities into core finance workflows.
Delivery Model:
Geographic concentration risk competes with cost efficiency in model selection.
- Cloud-Based Solutions:API-native, elastic infrastructure rebuilt from legacy platforms to enable bursting transactional workloads. Tier-one banks maintain sensitive data on-premise while leveraging public cloud elasticity for variable volumes.
- Offshore Services:Bangalore and Hyderabad delivery centers processing substantial transaction volumes for North American and European financial institutions.
- Hybrid Model:Converging private infrastructure with public elasticity and retained onshore presence for client-facing compliance functions.
- Onshore Services:Domestic delivery for data residency requirements, regulatory examination support, and relationship-intensive advisory functions.
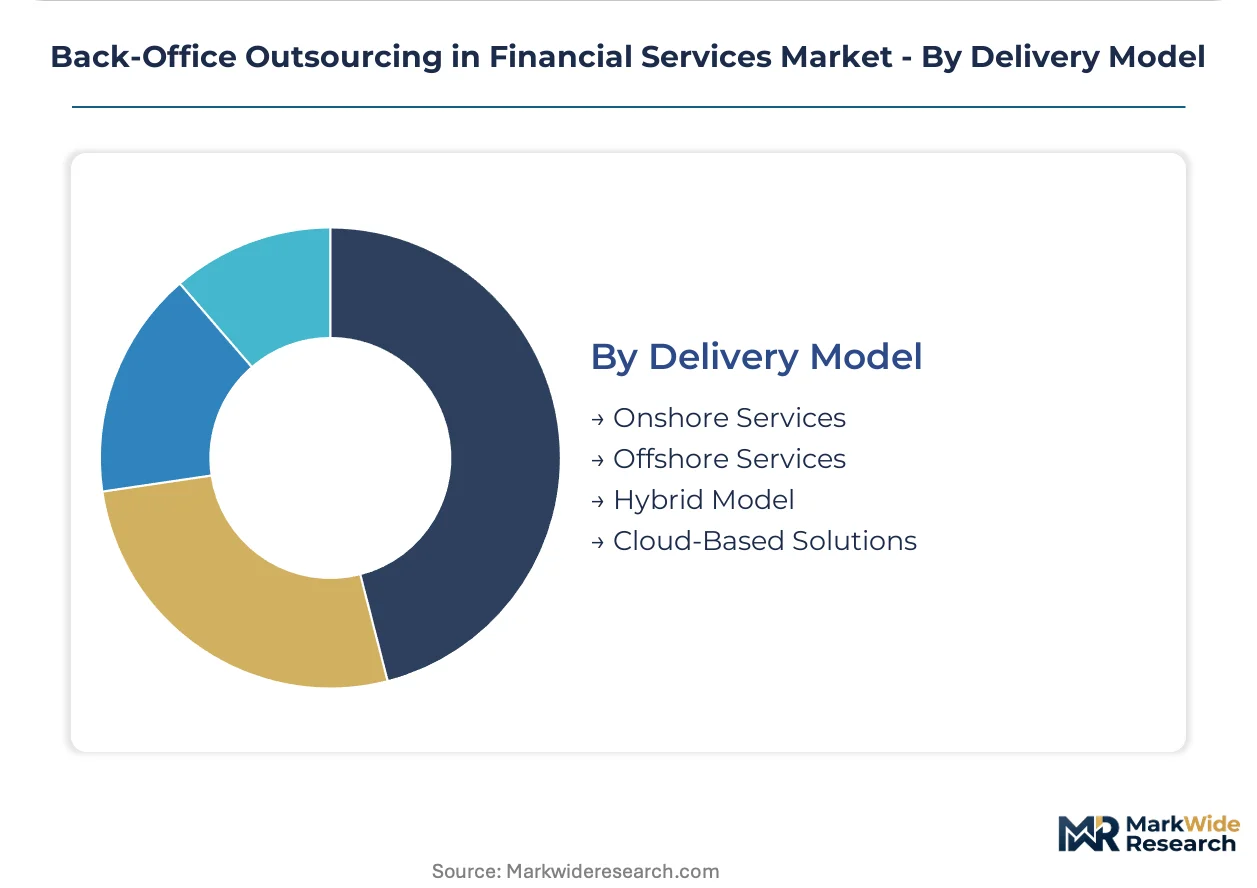
Offshore Services retain volume leadership. Cloud-Based Solutions are climbing the fastest as providers rebuild platforms for elastic infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Back-office outsourcing in financial services traces its modern scaling to India's liberalization of the services sector in the 1990s, when multinational banks established captive operations in Bangalore and Hyderabad. That foundation expanded into today's distributed delivery architecture spanning multiple regulatory jurisdictions.
United States
US banks drive demand for mortgage servicing automation and regulatory reporting under SEC and OCC oversight. The Dodd-Frank vendor management framework mandates rigorous due diligence on third-party relationships. New York and Charlotte host concentrated procurement decision-making for tier-one institutions outsourcing transaction processing.
United Kingdom
UK-based asset managers and insurers are expanding outsourced compliance functions ahead of full DORA implementation in 2025. The Financial Conduct Authority's operational resilience rules already require business-continuity testing for critical third parties. London's City cluster anchors vendor relationship management for European operations.
Germany
German universal banks are migrating core accounting reconciliation to cloud-native platforms under BaFin's outsourcing circular requirements. GDPR data residency restrictions limit cross-border data flows to approved jurisdictions. Frankfurt's banking quarter concentrates procurement authority for DAX-listed financial institutions.
India
India's delivery centers process the highest transaction volumes for North American and European clients, with Bangalore and Hyderabad employing specialized workforces in claims processing and KYC verification. RBI's 2023 outsourcing guidelines for banks and NBFCs clarified regulatory expectations and accelerated domestic contract velocity. Mumbai's financial district houses relationship management functions for global outsourcing contracts.
Singapore
Singapore's wealth management sector is driving demand for family office back-office outsourcing under MAS technology risk management guidelines. The Monetary Authority requires operational resilience for systemically important financial institutions. Raffles Place and Marina Bay concentrate decision-making for regional headquarters managing Asia-Pacific operations.
Back-Office Outsourcing in Financial Services Market Vendor Landscape
Premium-margin players sit above commodity-margin players across automation depth and domain specialization. The vendor base clusters into three tiers: global consultancies with integrated technology stacks, pure-play business process specialists with vertical expertise, and IT services firms with financial services practices. Consolidation pressures favor providers combining regulatory knowledge with generative AI capabilities. Dominant competitive moves include strategic partnerships for cloud infrastructure and selective acquisitions of niche compliance technology vendors.
Among the pure-play specialists, Genpact anchors the insurance claims and mortgage servicing vertical with multi-year client relationships. Accenture occupies a position at the automation-intensive end, embedding RPA and generative AI into core finance workflows. IBM sits within the hybrid cloud tier, combining proprietary Watson capabilities with infrastructure tailored to banking compliance requirements.
| Leading Market Players |
|---|
| Genpact |
| Capgemini |
| Deloitte |
| IBM |
| Accenture |
| KPMG |
| Infosys BPM |
| WNS |
| EY |
| Others |
Supply Flow & Price Mechanics
Cloud-native platform rebuilds are compressing unit economics while redistributing provider margins across automation-intensive and labor-dependent service tiers. This technological transition concentrates cost advantages with hyperscaler-aligned vendors in Bangalore and Hyderabad, widening pricing spreads between API-native offerings and legacy offshore delivery.
Pricing Analysis
Outcome-based contracting now dominates procurement negotiations across North American mortgage servicing and European insurance claims processing. Price differentiation separates premium automation tiers embedding generative AI from standard RPA-enabled delivery and economy-grade manual processing. Pricing pressure stems from buyer migration toward accuracy-guaranteed SLAs rather than headcount-based fees. Mid-tier insurance carriers exhibit highest price sensitivity, while tier-one banks under DORA mandates accept premium pricing for operational resilience certification.
Supply Chain Analysis
Reverse-logistics capabilities for contract termination and knowledge transfer are becoming competitive differentiators as financial institutions rebalance geographic exposure. Supply concentrates in India, the Philippines, and Poland, with Bangalore processing the highest transaction volumes for KYC and claims workflows. Talent pipelines draw from specialized finance and technology institutes, with attrition risk concentrated in AI implementation roles. Single-source vulnerability runs through the Bangalore-Hyderabad corridor, where infrastructure disruptions would cascade across multiple client portfolios. Distribution runs through direct enterprise sales teams anchored in New York, London, and Mumbai financial districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where labor cost differentials between Indian delivery centers and onshore compliance functions sustain margin structures that regulatory fragmentation alone cannot erode.
For Market Incumbents: Extend automation depth in mortgage servicing and insurance claims to defend against pure-play AI entrants. Vertical integration into proprietary large language model training for financial document extraction creates differentiation that commodity RPA vendors cannot replicate. Capacity addition in Poland and Mexico addresses client demands for geographic diversification beyond the Indian corridor. For New Entrants and Emerging Players: The premium-economy price gap in mid-tier insurance claims processing offers white-space entry where incumbent automation lags. Target this segment with modular service bundling that unifies compliance support with transaction processing under unified SLAs. A direct sales approach through industry-specific conferences and carrier association partnerships accelerates credibility building without incumbent-scale marketing spend. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap pure-play BPO specialists with concentrated insurance vertical exposure and limited AI capabilities. Long-term viability over a five-to-ten year window favors providers combining regulatory expertise with generative AI deployment. The signal to watch is DORA implementation velocity in European asset management, which will separate operational-resilience-certified vendors from compliance-lagged competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Platform Integration | Embedding large language models into mortgage servicing workflows unifies siloed verification steps for tier-one banks. |
| Geographic Delivery Diversification | Establishing Polish and Mexican centers reduces client exposure to single-corridor concentration risk in India. |
| DORA Compliance Certification | Operational resilience testing capabilities enable contract retention with European asset managers under ECB oversight. |
| Outcome-Based Contracting Transition | Accuracy-guaranteed SLAs align provider incentives with buyer cost reduction targets in mortgage delinquency processing. |
| Vertical Talent Pipeline Development | Partnerships with Indian Institutes of Technology and Management secure AI implementation expertise at scale. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork encompassed discussions with outsourcing procurement officers at tier-one banks, operations executives at insurance carriers, vendor relationship managers at asset management firms, and delivery center heads in Bangalore and Hyderabad. Secondary validation drew from SEC vendor management filings, RBI outsourcing circulars, EBA DORA implementation guidance, and hyperscaler cloud infrastructure disclosures. Bottom-up service line sizing and top-down macroeconomic benchmarking were reconciled through iterative triangulation.
Segment-weighting approaches distributed value estimates across transaction processing, compliance support, data management, and accounting services by client type and automation maturity. Deployment models were modeled across cloud-native, hybrid, offshore, and onshore delivery configurations. CAGRs were derived from trend extrapolation of automation adoption curves and regulatory compliance investment cycles. Forecast inputs incorporated RBI guideline implementation timelines and DORA operational resilience testing ramps.
Caveats apply where geopolitical disruptions to Indian infrastructure, accelerated generative AI substitution timelines, or divergent national implementations of DORA could materially shift the outlook. Practitioners should monitor European asset manager vendor requalification activity and Indian central bank outsourcing circular enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Currency Exchange Software Market
Financial Services
Europe E-Brokerages Market
Financial Services
United States Credit Agency Market
Financial Services
LAMEA Financial Services Software Market
Financial Services
Australia Gift Card and Incentive Card Market
Financial Services
Financial Services Software Market
Financial Services
North America Financial Advisory Services Market
Financial Services
Mobile Notary Public Market
Financial Services
Financial Auditing Professional Services Market
Financial Services
Islamic Finance Market
Financial Services
ATM Software Market
Financial Services
Global P2P Fundraising Tool Market
Financial Services
Peer-To-Peer (P2P) Market
Financial Services
Middle East Financial Consulting Software Market
Financial Services
United Kingdom E-Brokerage Market
Financial Services
Foreign Exchange Services Market