
 Soy Nut Market | 2026-2036
Soy Nut Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Nut Market Insights
Buyer concentration in the soy nut market is decoupling from traditional supermarket chains toward fragmented online retailers and specialty food stores. Archer Daniels Midland (ADM) leverages its crushing and processing infrastructure to anchor ingredient supply for downstream snack manufacturers. Cargill Incorporated competes through global origination networks that sustain cost-advantaged soybean procurement. Sincerely Nuts specializes in direct-to-consumer distribution, controlling niche channel access with curated product assortments.
Soy nuts are mature soybeans that undergo soaking, roasting, or frying to produce a crunchy texture with protein content typically exceeding 35% by weight, serving as functional ingredients in snack foods and as standalone retail products. The roasted soy nuts segment dominates volume due to established production economics and broad consumer familiarity, while soy nut butter captures expanding margin pools as a peanut butter alternative in allergen-sensitive households. Online retailers represent the fastest-growing distribution channel, though supermarkets still occupy the largest absolute revenue share through impulse-purchase placement and private-label expansion.
The FDA governs allergen labeling and health claim substantiation for soy-based foods in the United States, while the USDA oversees organic certification pathways that premium producers navigate for price differentiation. The EU Green Deal and EFSA nutrition profiling standards are tightening formulation requirements for plant-based snacks sold in European markets. Stakeholders must monitor evolving protein content thresholds and clean-label enforcement intensity as regulatory divergence between major markets intensifies compliance complexity.
Market Dynamics
Clean-label disclosure mandates and plant-protein certification requirements are compressing formulation timelines and forcing ingredient traceability investments across the soy nut supply chain.
Growth Catalysts
- EU Green Deal nutrition profiling:EFSA standards for plant-based snacks are accelerating reformulation toward higher-protein, lower-additive products that favor roasted soy nuts as clean-label ingredients.
- Allergen-sensitive households:Peanut-free school policies and daycare bans across the United States are redirecting lunchbox protein demand toward soy nut butter spreads.
- Specialty food store expansion:Curated retail formats in Germany, the United Kingdom, and Australia are devoting incremental shelf space to functional snack categories with transparent supply chains.
Market Restraints
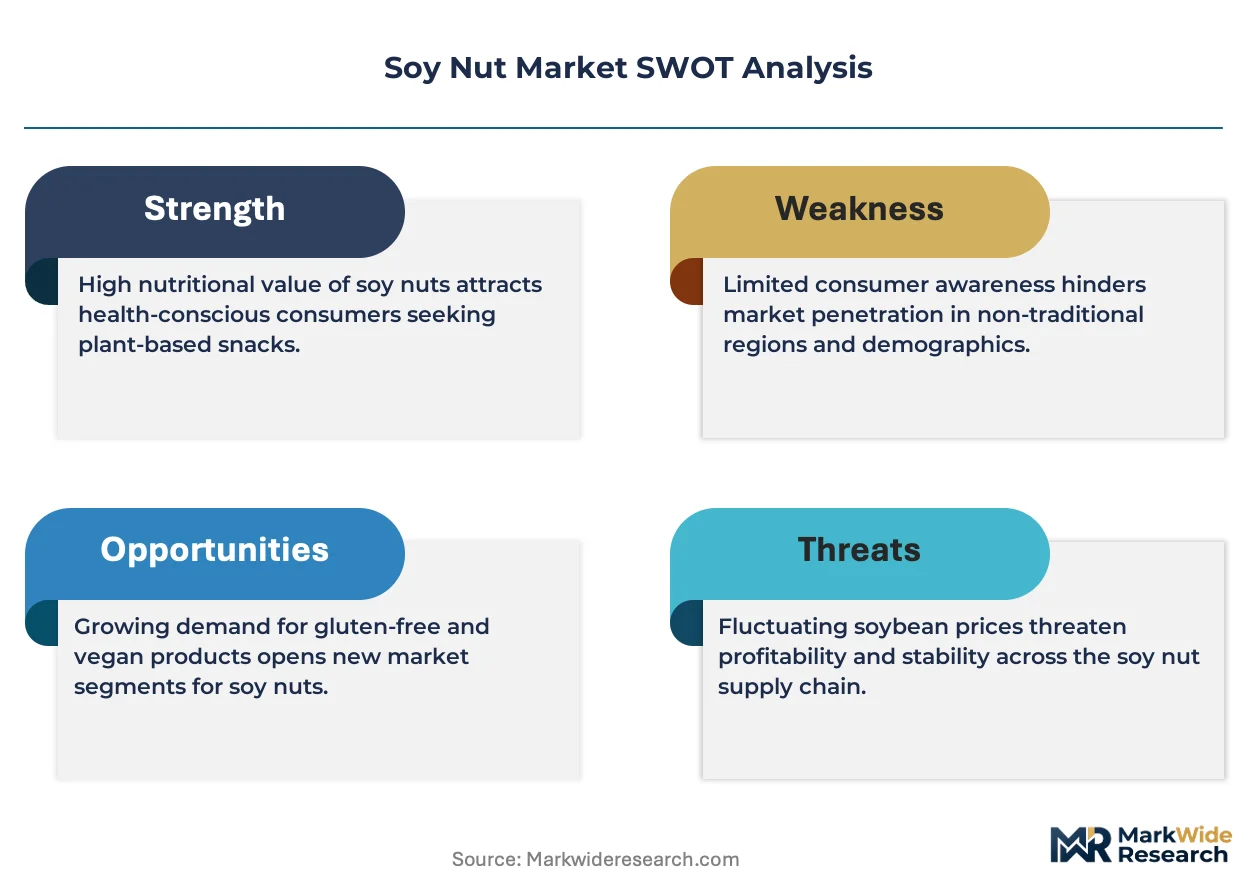
- Soybean price volatility:Weather-driven yield fluctuations in Argentina and Brazil transmit directly to roasted soy nut input costs, compressing processor margins during drought cycles.
- Processing infrastructure concentration:Crushing and roasting capacity clusters in the United States Midwest and select Chinese provinces, creating geographic single-point vulnerabilities.
- Digestibility perception barriers:Consumer associations between soy and phytoestrogen content limit penetration in hormone-conscious demographic segments despite clinical counter-evidence.
Strategic Opportunities
- India organized retail penetration:Modern trade formats in Mumbai, Bangalore, and Delhi NCR remain underdeveloped for packaged plant-protein snacks, offering first-mover positioning.
- Sports nutrition application expansion:Endurance athletes and CrossFit communities are adopting portable soy nut packs as mid-workout amino acid sources, displacing whey-based alternatives.
- USDA organic certification pathways:Premium price realization for certified organic roasted products exceeds conventional margins by meaningful spreads, incentivizing acreage conversion.
Industry Challenges
- Roasting technician skill scarcity:Precision temperature control for flavor development and texture consistency requires specialized operators that contract manufacturers struggle to retain.
- Dual jurisdiction compliance:Simultaneous FDA allergen labeling and USDA organic audits extend product launch timelines and increase documentation overhead.
- Legacy ERP integration:Lot-level traceability requirements for clean-label claims force mid-tier processors to replace inventory systems, straining capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Nut Market |
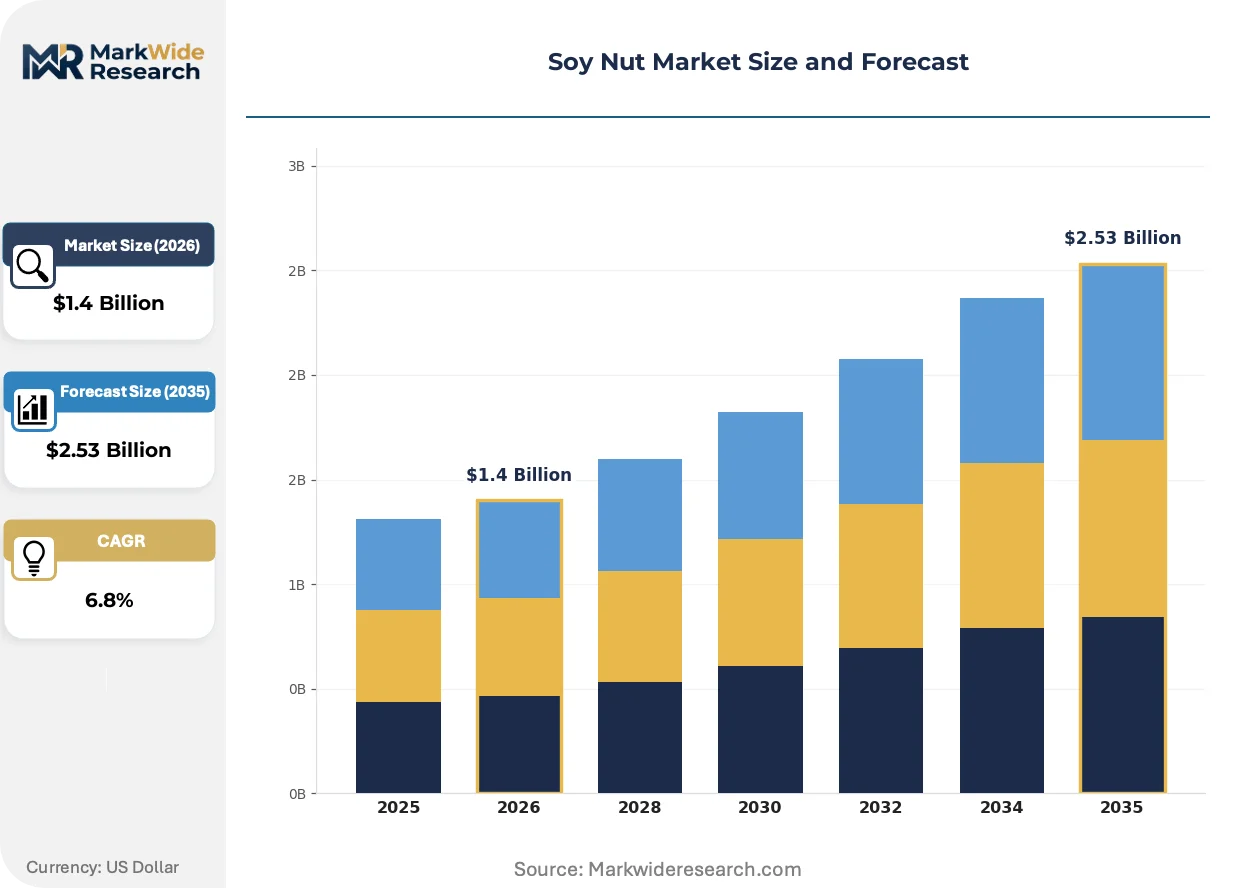
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
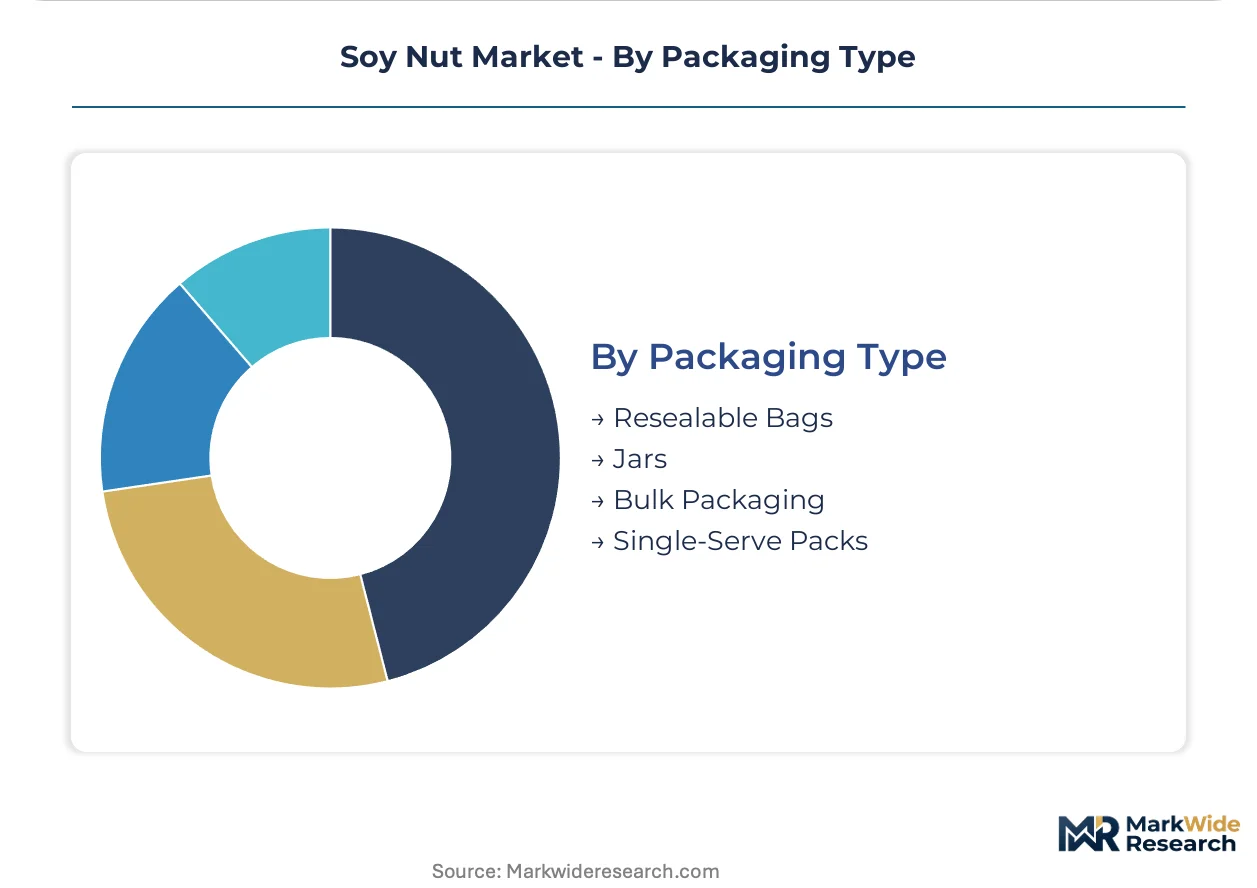
| Segmentation | Product Type: Roasted Soy Nuts, Chocolate Covered Soy Nuts, Soy Nut Butter, Soy Nut Snacks Distribution Channel: Online Retailers, Supermarkets, Health Food Stores, Specialty Food Stores End User: Health-Conscious Consumers, Athletes, Vegans, Diabetic Individuals Packaging Type: Resealable Bags, Jars, Bulk Packaging, Single-Serve Packs |
| Companies Covered | Archer Daniels Midland (ADM), Cargill Incorporated, Life Health Foods India Pvt. Ltd., Alpro, Diamond Foods, Inc., Tate and Lyle, Richardson International, Sincerely Nuts, Agro Fresh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Nut Market Trends and Innovations
Precision roasting technology and digital supply chain verification are converging to transform how soy nut processors demonstrate quality consistency and origin transparency to institutional buyers.
Controlled atmosphere roasting with real-time moisture sensing is rewriting the economics of small-batch production. Artisanal snack manufacturers in Portland, Copenhagen, and Melbourne are adopting these systems to achieve industrial-scale uniformity without capital-intensive continuous lines. The technology is compressing the minimum efficient scale for flavor-customized product lines, enabling regional players to challenge national brands on shelf rotation speed.
REACH chemical safety registrations and forthcoming EU packaging waste directives are tightening material specifications for soy nut retail pouches. Biodegradable barrier films must now demonstrate oxygen permeability rates matching conventional metallized structures. German and Dutch co-packers are absorbing the compliance burden fastest, securing preferred supplier status with pan-European retail banners.
Direct subscription fulfillment is displacing traditional distributor relationships for allergen-sensitive household segments. Parents of children with peanut allergies in Texas, Florida, and Washington state are bypassing supermarket intermediaries to secure consistent supply of verified peanut-free production runs. This channel rotation concentrates buyer data with specialized e-commerce operators, fragmenting demand intelligence across the value chain.
Soy Nut Market Segmentation
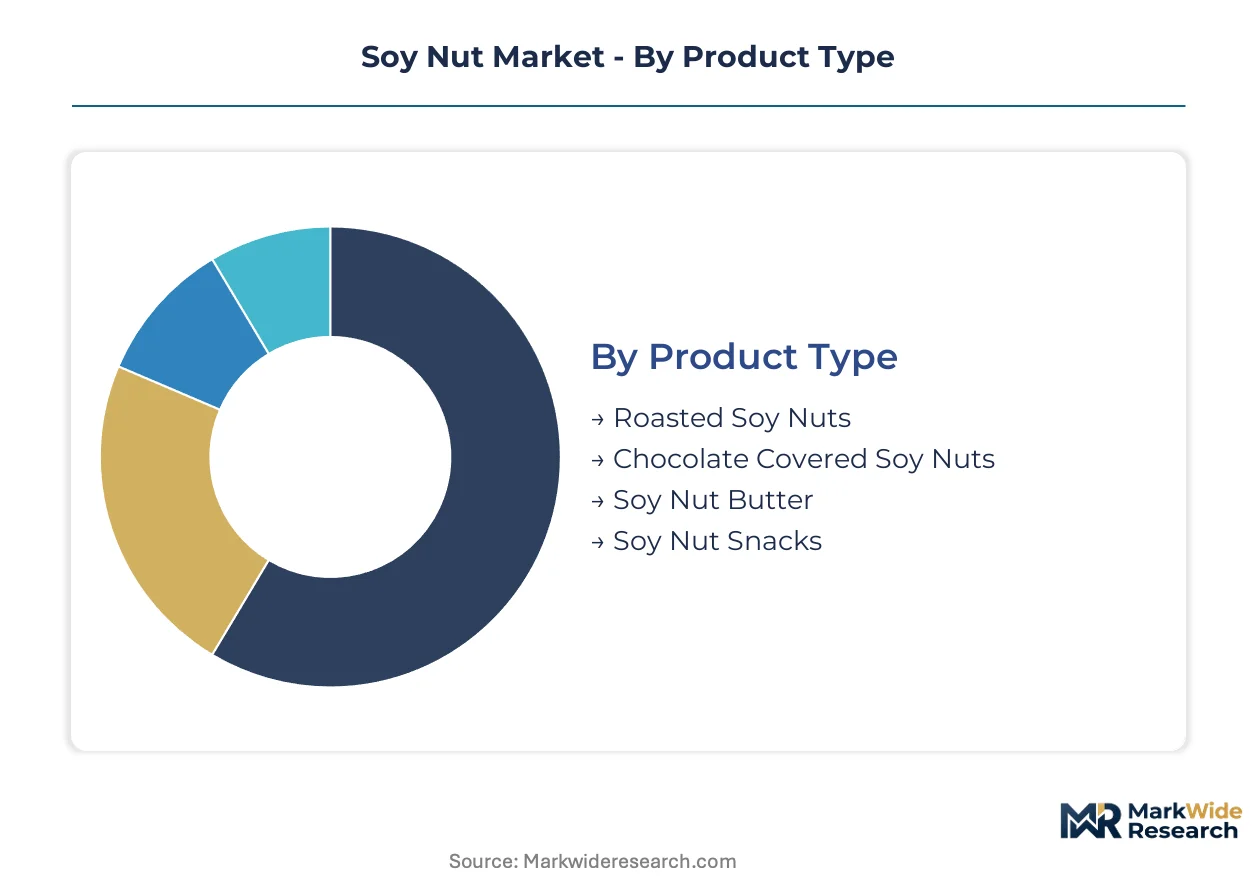
Soy nut processors navigate divergent regulatory pathways across product formats, with allergen labeling requirements from the FDA and organic certification from the USDA creating tiered compliance burdens. Segmentation reveals where certification investments concentrate margin pressure and which channels reward premium positioning.
Product Type:
FDA allergen disclosure mandates apply universally across all formats, while USDA organic certification unlocks price premiums selectively. Roasted soy nuts face additional scrutiny under EFSA nutrition profiling standards when exported to European markets.
- Roasted Soy Nuts:Mature soybeans undergo controlled thermal processing to achieve protein content exceeding 35% by weight with crunchy texture. Demand concentrates in United States specialty food stores and German curated retail formats, driven by clean-label snack rotation requirements and EFSA-compliant formulation standards.
- Soy Nut Butter:Ground roasted soybeans form spreadable pastes serving as peanut butter alternatives in allergen-sensitive households. United States school lunchbox demand is accelerating fastest in Texas and Florida, where peanut-free policies redirect protein sourcing toward verified peanut-free production runs.
- Chocolate Covered Soy Nuts:Confectionery coating adds sugar content that complicates EFSA nutrition profiling compliance for European export.
- Soy Nut Snacks:Value-added formulations combining multiple ingredients face compounded allergen disclosure requirements.
Leading the category by volume: Roasted Soy Nuts. Growing fastest: Soy Nut Butter.
Distribution Channel:
Channel selection determines traceability investment intensity, with direct-to-consumer formats demanding lot-level verification systems that supermarket private-label contracts rarely require.
- Online Retailers:E-commerce platforms capture fastest-expanding revenue share through subscription fulfillment models. Parents of children with peanut allergies in Washington state and Florida bypass supermarket intermediaries, concentrating buyer data with specialized operators.
- Supermarkets:Impulse-purchase placement and private-label expansion sustain largest absolute revenue position. Shelf space allocation in United States conventional grocery chains favors established roasting brands with national distribution infrastructure.
- Health Food Stores:Curated assortments reward transparent supply chains and organic certification premiums.
- Specialty Food Stores:German and United Kingdom formats devote incremental space to functional snack categories with verified origin documentation.
Supermarkets dominate absolute revenue. Online Retailers expand most quickly through subscription concentration.
End User:
User segmentation maps directly to nutritional claim substantiation requirements, with athletic performance positioning demanding protein content verification beyond standard food labeling.
- Health-Conscious Consumers:Clean-label prioritization drives purchasing toward organic-certified products with minimal processing disclosure.
- Athletes:Endurance and CrossFit communities adopt portable soy nut packs as mid-workout amino acid sources, displacing whey-based alternatives. United States sports nutrition application is expanding fastest among endurance athletes seeking portable protein.
- Vegans:Plant-based protein seekers validate complete amino acid profiles through third-party certification.
- Diabetic Individuals:Low-glycemic positioning requires clinical substantiation for health claim permissibility.
Athletes represent the steepest expansion trajectory. Health-Conscious Consumers anchor volume through routine snacking frequency.
Packaging Type:
Material specifications tighten under REACH chemical safety registrations and forthcoming EU packaging waste directives, with biodegradable barrier films now required to match conventional oxygen permeability rates.
- Resealable Bags:Convenience-driven format dominates retail shelf presence with zipper closure technology.
- Jars:Soy nut butter standard container faces glass weight penalties in e-commerce fulfillment economics.
- Bulk Packaging:Foodservice and ingredient supply applications minimize per-unit material cost.
- Single-Serve Packs:Portion-controlled format aligns with school lunchbox requirements and athletic nutrition timing. German and Dutch co-packers absorb compliance burden fastest for biodegradable barrier specifications.
Resealable Bags lead volume. Single-Serve Packs gain share fastest through institutional and athletic adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households with peanut allergies are redirecting lunchbox protein demand toward soy nut alternatives, while German and Dutch co-packers absorb the fastest compliance burdens for biodegradable packaging mandates.
United States
Texas and Florida school districts enforce peanut-free policies that accelerate soy nut butter adoption in institutional feeding programs. FDA allergen labeling requirements govern all retail formats, with USDA organic certification unlocking premium price realization. Pacific Northwest artisanal manufacturers in Portland deploy precision roasting systems to achieve industrial-scale uniformity without continuous line investments.
Germany
Curated retail formats in Berlin and Hamburg devote incremental shelf space to functional snack categories with transparent supply chains. EFSA nutrition profiling standards under the EU Green Deal accelerate reformulation toward higher-protein, lower-additive products. German co-packers lead European adoption of biodegradable barrier films that match conventional metallized oxygen permeability rates.
India
Modern trade formats in Mumbai, Bangalore, and Delhi-NCR remain underdeveloped for packaged plant-protein snacks, offering first-mover positioning for organized retail penetration. FSSAI labeling requirements govern domestic market entry, with BIS standards applying to imported equipment. Maharashtra-based food processors are expanding roasting capacity to serve emerging urban demand.
Netherlands
Dutch co-packers absorb compliance burden fastest for REACH chemical safety registrations and forthcoming EU packaging waste directives. ECHA material specifications tighten retail pouch requirements, favoring processors with established biodegradable film relationships. Rotterdam logistics clusters facilitate pan-European distribution of certified organic soy nut products.
Australia
Melbourne artisanal snack manufacturers adopt controlled atmosphere roasting with real-time moisture sensing to challenge national brands on shelf rotation speed. TGA nutrition claim substantiation requirements apply to sports nutrition positioning targeting endurance athletes. Sydney and Melbourne specialty food stores expand functional snack assortments with verified origin documentation.
Soy Nut Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue allergen-sensitive household segments through direct subscription fulfillment. The vendor base distributes across integrated agribusiness conglomerates, regional roasting specialists, and direct-to-consumer operators. Three archetypes dominate: upstream processors with crushing infrastructure, mid-tier contract manufacturers with organic certification pathways, and niche e-commerce operators controlling verified peanut-free production data. Competitive intensity concentrates on M&A activity for roasting capacity and strategic partnerships for biodegradable packaging compliance.
Within the integrated processor tier, Archer Daniels Midland and Cargill Incorporated exemplify upstream infrastructure dominance through origination and crushing assets. Sincerely Nuts occupies a position within the direct-to-consumer archetype, controlling niche channel access with curated product assortments. These three entities represent the competitive spectrum from commodity-scale supply to specialized e-commerce fulfillment.
| Leading Market Players |
|---|
| Archer Daniels Midland (ADM) |
| Cargill Incorporated |
| Life Health Foods India Pvt. Ltd. |
| Alpro |
| Diamond Foods, Inc. |
| Tate and Lyle |
| Richardson International |
| Sincerely Nuts |
| Agro Fresh |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal packaging waste directives gate qualified supply and premium-tier pricing access for soy nut processors seeking biodegradable barrier film certification. Manufacturers absorbing REACH compliance burdens fastest secure preferred supplier status with pan-European retail banners and command organic-certified price premiums.
Pricing Analysis
Roasted soy nuts anchor volume at commodity-adjacent margins while soy nut butter captures expanding margin pools as allergen-sensitive households pay premiums for verified peanut-free production runs. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic-certified products from conventional clean-label offerings and private-label economy tiers. Price differentiation stems from certification grade and volume scale, with organic premiums exceeding conventional spreads meaningfully. Cost compression in conventional roasted products is intensifying because Argentine and Brazilian weather-driven yield fluctuations transmit directly to input costs, while subscription-based direct-to-consumer buyers demonstrate lowest price sensitivity.
Supply Chain Analysis
Soybean supply rests on origination networks concentrated in Argentina, Brazil, and the United States Midwest, where crushing and roasting infrastructure clusters create geographic single-point vulnerabilities. Raw material dependencies include non-GMO seed stock, precision roasting equipment, and biodegradable barrier films that match conventional oxygen permeability rates. Single-source vulnerability concentrates in United States Midwest and select Chinese provinces for thermal processing capacity. Distribution runs through fragmented online retailers and specialty food stores that are decoupling from traditional supermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over crushing infrastructure and certified organic acreage conversion determines margin capture. Players pursuing upstream origination assets or downstream subscription channel data are consolidating competitive position.
For Market Incumbents: Deepen backward integration into non-GMO soybean origination to insulate margin from Argentine and Brazilian weather volatility. Acquire precision roasting technician capabilities through targeted hiring or contract manufacturer partnerships to address skill scarcity threatening batch consistency. Secure biodegradable film supplier relationships ahead of EU packaging waste directive enforcement to maintain pan-European retail access.
For New Entrants and Emerging Players: Direct subscription fulfillment routes offer lowest competitive intensity for allergen-sensitive household segments in Texas, Florida, and Washington state. Target India organized retail penetration in Mumbai, Bangalore, and Delhi NCR where modern trade formats remain underdeveloped for packaged plant-protein snacks. Launch with sports nutrition positioning toward CrossFit and endurance athlete communities seeking portable amino acid sources.
For Investors and Strategic Acquirers: USDA organic certification pathway completion is the leading indicator that mid-tier processors have absorbed compliance documentation overhead and are positioned for premium price realization. Long-term viability favors vertically integrated specialists with crushing infrastructure and direct-to-consumer data assets over pure-play contract manufacturers. Acquisition target archetype: regional roasting specialists with organic certification and established biodegradable packaging compliance. Watch for precision roasting technology adoption rates as inflection signal for quality consistency capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Roasting Technology Adoption | Controlled atmosphere systems with real-time moisture sensing enable small-batch uniformity without continuous line capital. |
| USDA Organic Certification Pathway | Certified organic roasted products unlock premium price realization exceeding conventional margins across United States specialty retail. |
| Direct-to-Consumer Subscription Launch | Allergen-sensitive household data concentration bypasses supermarket intermediaries and fragments demand intelligence. |
| Biodegradable Packaging Compliance | German and Dutch co-packers absorbing REACH and EU packaging waste burdens fastest secure preferred supplier status. |
| India Organized Retail Penetration | Modern trade formats in Mumbai, Bangalore, and Delhi NCR offer first-mover positioning for packaged plant-protein snacks. |
Research Methodology
Trade databases, agricultural commodity exchanges, and food regulatory filings formed the secondary backbone for supply-side and pricing intelligence. Primary interviews with roasting plant managers, specialty food store category buyers, organic certification auditors, and direct-to-consumer operators combined with secondary validation through bottom-up and top-down triangulation.
Historical trendline analysis across roasted soy nut and soy nut butter volume trajectories informed baseline growth assumptions over the projection horizon. Segmentation dimensions modeled include product format, distribution channel, end-user application, and packaging type alongside geographic regulatory cluster variations. CAGRs were derived from demand elasticity coefficients and supply capacity expansion schedules, with soybean yield volatility and clean-label enforcement intensity serving as key forecast inputs.
The model holds under stable EU Green Deal implementation timelines and steady allergen-sensitive household formation rates; deviation in EFSA nutrition profiling stringency or peanut-free policy adoption would shift volume trajectories. Forecasts reflect documented assumptions about certification pathway completion rates and biodegradable film cost curves. A small set of named triggers—Argentine drought cycles, precision roasting technician wage inflation, and FDA allergen labeling reinterpretation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Nuts and Nut Products Market
Nuts and Seeds
Almond Butter Market
Nuts and Seeds
Europe Hazelnut Market
Nuts and Seeds
Butyrospermum Parkii Market
Nuts and Seeds
Rubus Fructicosus (Blackberry) Seed Market
Nuts and Seeds
Carob Market
Nuts and Seeds
Macadamia Market
Nuts and Seeds
United States Nuts Market
Nuts and Seeds
Hickory Nut Market
Nuts and Seeds
Asia-Pacific Cashew Market
Nuts and Seeds
Europe Nut-Based Spreads Market
Nuts and Seeds
Breadnut Market
Nuts and Seeds
Hazelnut Market
Nuts and Seeds
Blackcurrant Seed Oil Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Fat Free Peanut Butter Market