
 India Processed Cashew Market | 2026-2036
India Processed Cashew Market Size, Share, and Industry Trends Forecast 2026-2036
India Processed Cashew Market Foresight
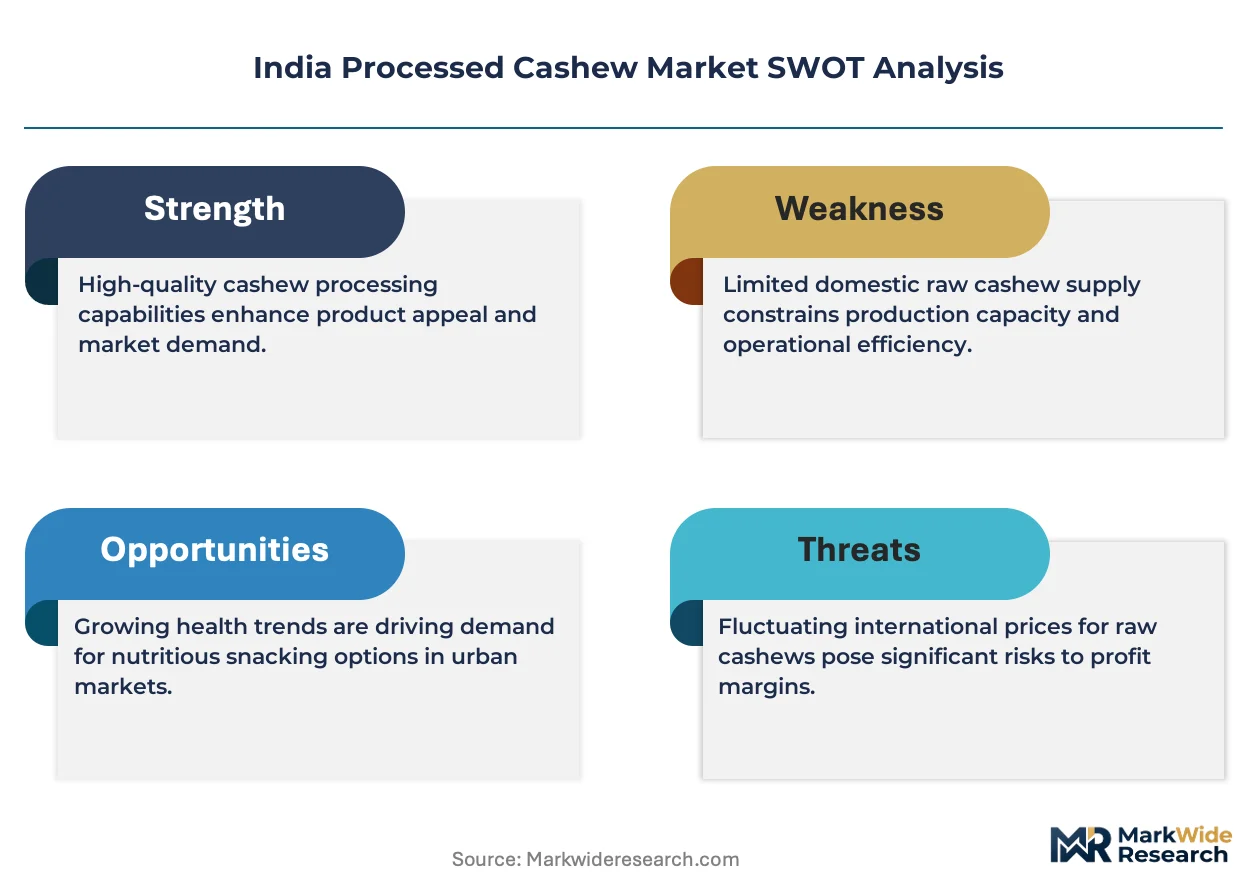
Multi-source procurement from African origins and domestic western-India orchards is repositioning supply security for Indian processors. Haldirams leverages its pan-India distribution network to sustain branded snack dominance. Kalbavi Cashews anchors its position through integrated shelling and export-grade sorting operations in Karnataka. Wonderland Foods competes via premium roasted and flavored SKUs targeting modern retail shelves.
Processed cashew denotes shelled, roasted, flavored, or value-added kernels meeting moisture, aflatoxin, and size-grade specifications for direct consumption or industrial formulation. Steam-based shelling and vacuum-assisted peeling preserve kernel integrity while reducing breakage rates below industry thresholds. Whole nuts command premium shelf positioning in gift and export channels, while broken nuts and powder concentrate margin pools within bakery and confectionery ingredient supply. E-commerce distribution is expanding fastest among channels as direct-to-consumer brands bypass traditional wholesale tiers.
FSSAI mandates on maximum permissible aflatoxin levels and BIS grading standards for kernel size and moisture content shape product specifications and market access across domestic and export-bound output. CDSCO oversight intersects where processors market fortified or functional claims on roasted and flavored variants. Stakeholders must monitor evolving BIS notification timelines and FSSAI label claim enforcement to align certification investments with channel eligibility requirements.
Market Dynamics
FSSAI fortification mandates and BIS quality protocols are compressing processing margins while forcing capital upgrades across Maharashtra and Kerala shelling clusters. Kernel breakage rates and aflatoxin compliance now determine market access more than raw volume throughput.
Growth Catalysts
- Urban Household Demand:Quick-service restaurants in western and southern states are scaling roasted and flavored cashew purchases for menu premiumization. Direct consumption formats are displacing traditional loose kernel trade.
- FSSAI Fortification Guidelines:Mandatory micronutrient enrichment protocols are creating compliant product tiers that command shelf preference in modern retail. Fortified SKUs unlock institutional procurement channels.
- Steam-Based Shelling:Vacuum-assisted peeling technology is reducing kernel breakage below legacy mechanical thresholds. Processors deploying this method capture export-grade sorting premiums.
Market Restraints
- Raw Nut Import Dependence:African origin supply concentration exposes processors to freight volatility and currency fluctuation. Tanzanian and Ivorian crop shortfalls transmit directly to Indian unit economics.
- Aflatoxin Testing Burden:FSSAI maximum permissible limits require laboratory infrastructure that small-scale shellers cannot sustain. Compliance costs favor integrated operators with captive testing capacity.
- Palm Kernel Substitution:Bakery and confectionery formulators are blending lower-cost oilseeds where cashew powder serves as filler. Ingredient substitution pressure concentrates in broken nut and powder segments.
Strategic Opportunities
- E-Commerce Direct Distribution:Direct-to-consumer brands are bypassing wholesale tiers through platform-native fulfillment. This channel expansion captures urban household demand without distributor margin stacking.
- Karnataka Processing Expansion:Integrated shelling and sorting investments in non-traditional western-India locations are diversifying geographic capacity concentration. New clusters reduce logistics drag to port infrastructure.
- PLI Scheme Alignment:Food processing incentive frameworks subsidize capital equipment for export-grade kernel operations. Eligible investments accelerate compliance with destination market phytosanitary protocols.
Industry Challenges
- Skilled Grader Scarcity:Manual kernel size classification requires trained labor pools that are migrating to alternative employment. Automated sorting capital demands exceed cooperative processor balance sheets.
- CDSCO Fortification Claim Verification:Functional roasted and flavored variant labels require clinical substantiation timelines that delay product launches. Regulatory filing backlogs compress commercialization windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Processed Cashew Market |
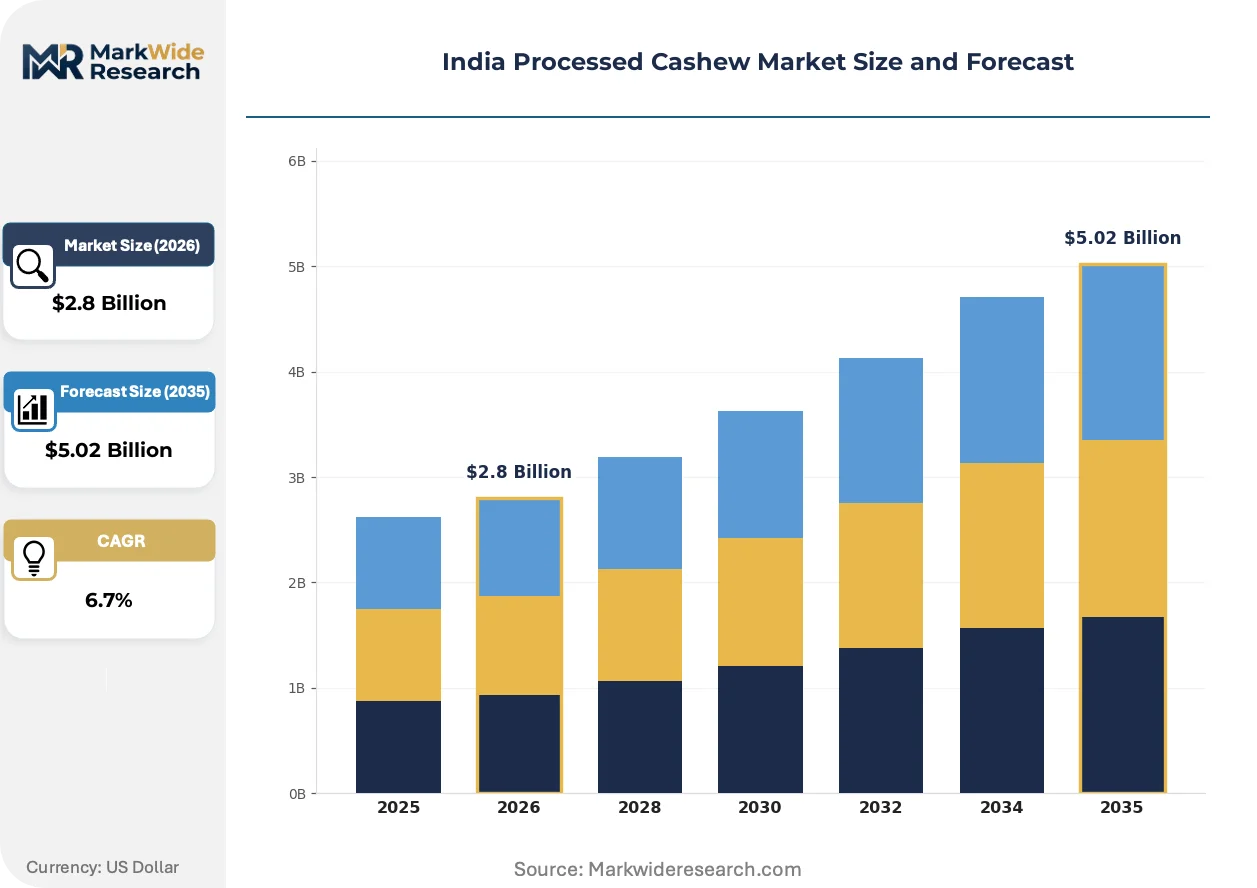
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Nuts, Split Nuts, Broken Nuts, Powder Packaging Type: Bags, Tins, Boxes, Bulk Distribution Channel: Retail, Wholesale, E-commerce, Direct Sales End User: Households, Food Service, Bakeries, Confectioneries |
| Companies Covered | Royal Dry Fruits Pvt. Ltd (Rostaa), Haldirams, Delicious Cashew Co., Athav Products, Kalbavi Cashews, Wonderland Foods, Nutty Yogi, Shakti Dry Foods, Greendot Health Foods Pvt. Ltd (Cornitos), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Processed Cashew Market Shifts & Advancements
Processing technology and distribution architecture are undergoing parallel transformation. Steam shelling, regulatory fortification, and channel disintermediation are compressing legacy operational models while opening premium positioning pathways.
Vacuum-assisted peeling systems are expanding into mid-scale Karnataka and Maharashtra facilities. Urban private-label buyers are specifying sub-5% breakage rates for gift-pack channels. This technology diffusion is compressing the margin advantage previously held by manually sorted export houses.
FSSAI notification timelines on aflatoxin testing frequency are tightening enforcement protocols nationwide. Integrated processors with in-house laboratory infrastructure are capturing channel eligibility that smaller shellers forfeit. Roasted and flavored SKU producers face the steepest compliance recalibration under CDSCO functional claim oversight.
Platform-native brands are disintermediating traditional wholesale tiers through direct-to-consumer fulfillment. Modern retail shelf access now requires e-commerce velocity proof rather than distributor relationship depth. Western and southern urban corridors display the fastest channel pivot as quick-commerce apps absorb impulse snack purchases.
India Processed Cashew Market Segmentation
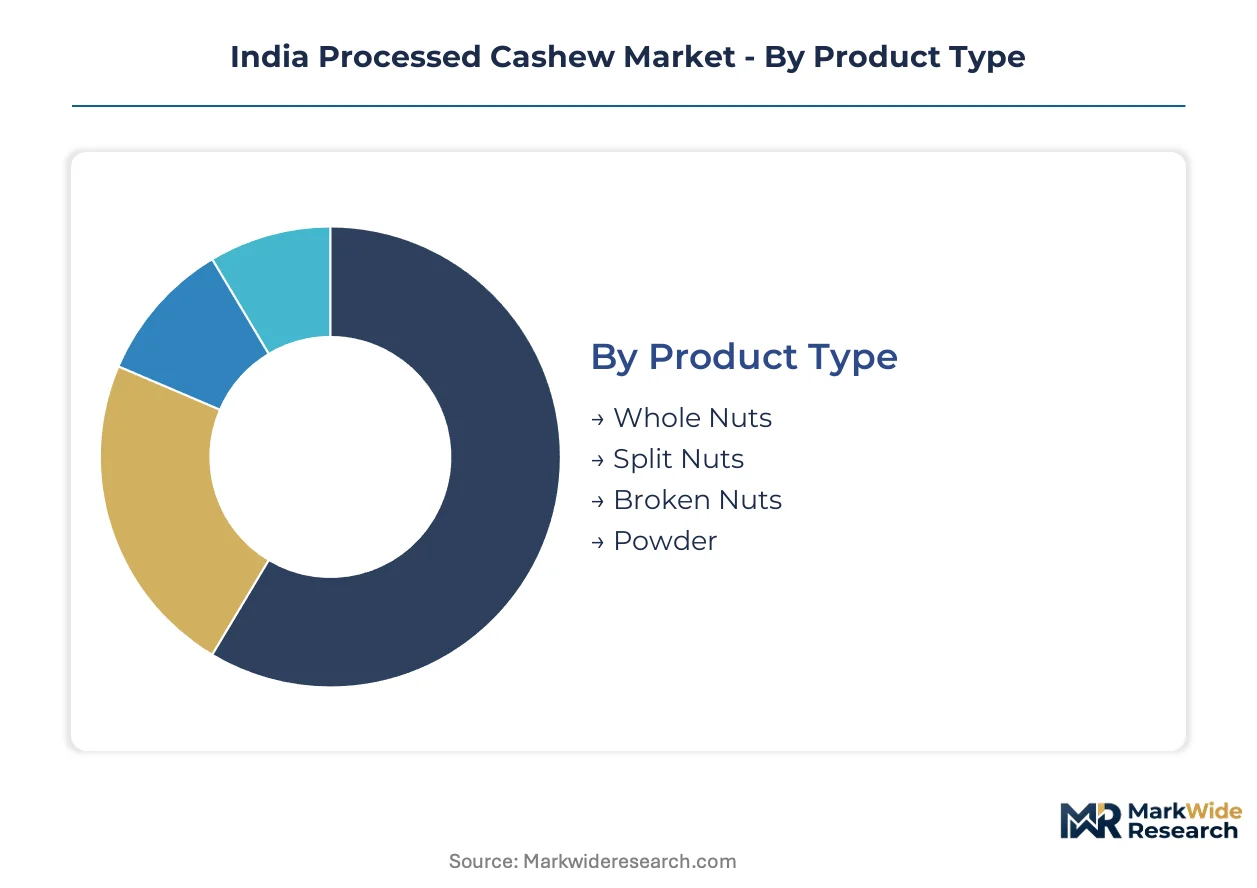
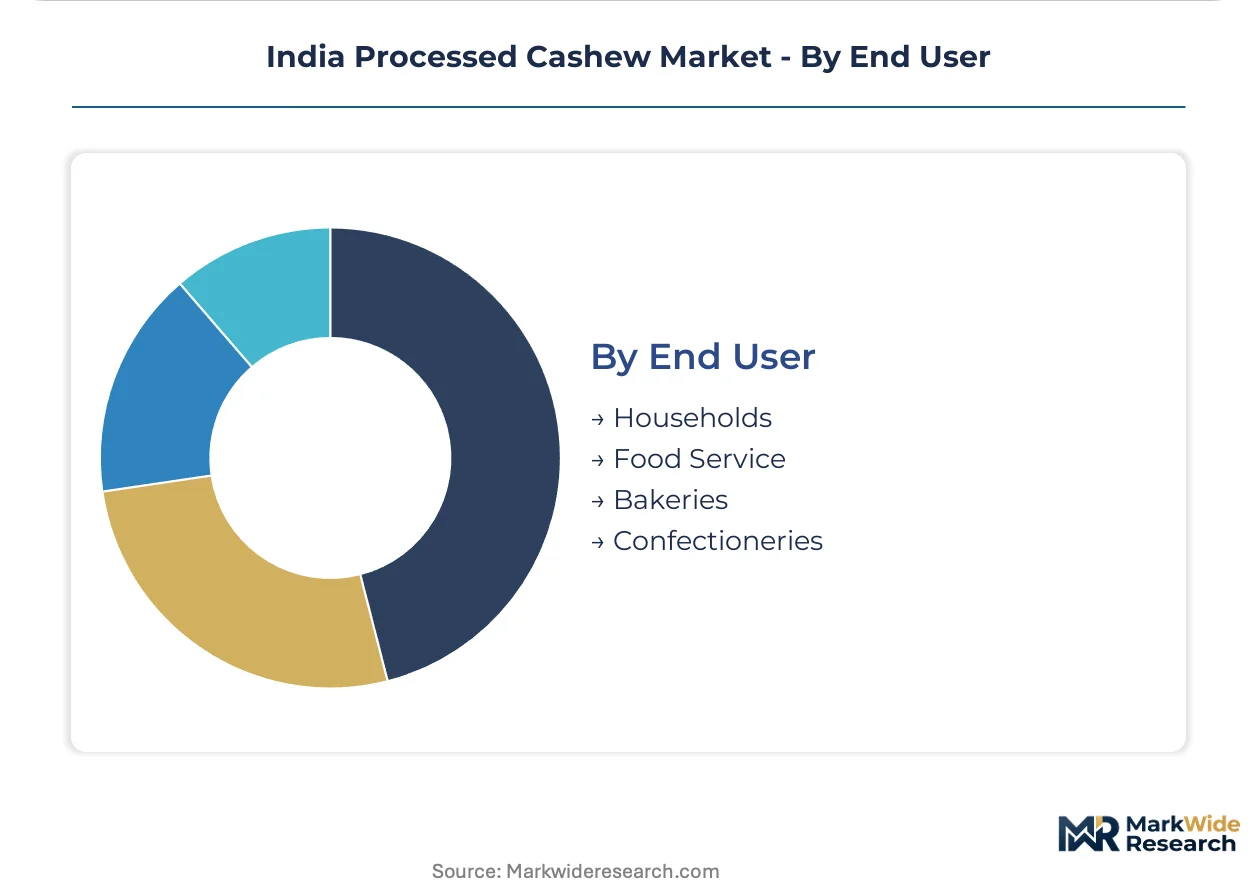
Kernel form, packaging integrity, and channel access determine margin capture across Maharashtra and Kerala processing clusters. Specification compliance with FSSAI moisture limits and BIS size grades shapes procurement decisions for export houses and domestic modern retail buyers.
Product Type:
Steam shelling and vacuum-assisted peeling technology differentiate kernel integrity across grade tiers.
- Whole Nuts:Intact kernels exceeding BIS W320 grade specifications command premium positioning in gift channels and export consignments. Urban households in Mumbai and Bangalore drive demand for visually uniform whole nuts in festive packaging.
- Split Nuts:Halved kernels meeting moisture content below 5% retain substantial value for roasting and flavoring applications. Quick-service restaurants in western states specify split nuts for portion-controlled menu integration.
- Broken Nuts:Fragmented kernels concentrate in ingredient supply for bakery and confectionery formulators seeking cost-optimized inputs.
- Powder:Finely milled material serves as filler and texture agent across industrial food manufacturing, facing substitution pressure from palm kernel alternatives.
Whole nuts lead on scale; split nuts lead on momentum.
Packaging Type:
Cost-to-protection ratios and shelf-life extension requirements shape material selection across channel tiers.
- Bags:Flexible laminate pouches with nitrogen flushing dominate modern retail and e-commerce fulfillment for roasted SKUs. Karnataka processors are converting bagging lines to vacuum-sealed formats for extended shelf stability.
- Tins:Metal canisters preserve kernel integrity through humidity exposure in coastal Kerala distribution, sustaining gift-channel premiums.
- Boxes:Rigid paperboard formats concentrate in corporate gifting and premium retail placement.
- Bulk:Loose kernel shipments in jute or polypropylene containers supply industrial bakeries and confectioneries with volume-scaled procurement.
Bulk shipments anchor volume throughput; bags are climbing the fastest.
Distribution Channel:
Margin stacking elimination and velocity proof requirements are restructuring access pathways.
- Retail:Modern trade shelves in western and southern urban corridors require FSSAI-compliant labeling and BIS certification documentation. Metro Cash and Carry and Reliance Fresh specify aflatoxin test certificates for branded cashew listings.
- Wholesale:Traditional mandi networks in Mumbai and Kochi continue handling loose kernel aggregation for regional redistribution.
- E-commerce:Platform-native fulfillment through Amazon India and Blinkit absorbs impulse snack purchases with direct-to-consumer velocity. Direct-to-consumer brands bypass distributor margins through this channel expansion.
- Direct Sales:Processor-to-institution contracts supply quick-service restaurants and bakery chains with specification-locked volumes.
Retail maintains revenue concentration; e-commerce shows steepest expansion trajectory.
End User:
Application specificity and formulation integration depth determine specification stringency.
- Households:Direct consumption demand concentrates in urban western and southern states, displacing loose kernel trade with packaged branded formats.
- Food Service:Quick-service restaurants deploy roasted and flavored variants for menu premiumization, requiring consistent kernel size for portion standardization.
- Bakeries:Broken nut and powder segments integrate into dough and filling formulations where cost optimization competes with oilseed substitutes.
- Confectioneries:Whole and split nuts anchor praline and chocolate inclusion specifications, with aflatoxin compliance mandatory for export-oriented confectionery supply.
Households dominate absolute demand; food service is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's Kollam and Palghar shelling clusters anchor national processing capacity. Kerala's Kochi corridor sustains legacy grading expertise. Karnataka's emerging integrated facilities are diversifying geographic concentration.
Maharashtra
Mumbai and Pune metropolitan demand drives premium roasted SKU consumption. FSSAI fortification mandates require laboratory infrastructure investments across Palghar processing zones. Kollam corridor shellers are deploying steam-based equipment to reduce kernel breakage below 5% thresholds for export-grade sorting.
Kerala
Kochi and Thiruvananthapuram urban households displace loose kernel trade with packaged branded formats. BIS grading standards enforcement tightens moisture content specifications statewide. Alappuzha coastal processors are converting bagging lines to vacuum-sealed formats for extended shelf stability in humid distribution conditions.
Karnataka
Bangalore quick-service restaurants scale roasted and flavored cashew purchases for menu premiumization. PLI scheme subsidies accelerate capital equipment deployment for export-grade operations. Kalbavi integrated shelling and sorting facilities in non-traditional western locations reduce logistics drag to port infrastructure.
Tamil Nadu
Chennai modern retail chains specify aflatoxin test certificates for branded cashew listings. CDSCO functional claim oversight applies to fortified roasted variants marketed through institutional channels. Coimbatore bakery and confectionery formulators concentrate broken nut and powder procurement for cost-optimized ingredient supply.
Gujarat
Surat and Ahmedabad food service operators demand consistent kernel size for portion standardization. DGFT export protocols shape phytosanitary certification requirements for destination market access. Vadodara processors are expanding e-commerce fulfillment capacity to capture direct-to-consumer velocity through platform-native distribution.
India Processed Cashew Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer channels and fortified SKU differentiation. The vendor base stratifies across integrated shelling-sorting operators, branded snack specialists, and private-label suppliers. Three archetypes dominate: legacy snack houses with pan-India distribution, export-grade processors with captive testing infrastructure, and platform-native brands bypassing wholesale tiers. Competitive moves concentrate on e-commerce velocity proof and PLI-aligned capacity expansion.
Within the branded snack tier, Haldirams leverages its established distribution architecture, while Wonderland Foods and Kalbavi Cashews exemplify contrasting positioning strategies. Haldirams represents the legacy house with channel breadth across modern retail and traditional wholesale. Wonderland Foods occupies a position emphasizing premium roasted and flavored variants for urban shelf placement. Kalbavi Cashews anchors the integrated processor archetype through Karnataka-based shelling and export-grade sorting operations. These three entities collectively illustrate the competitive vectors shaping procurement decisions among quick-service restaurants, modern retail buyers, and direct-to-consumer platforms.
| Leading Market Players |
|---|
| Royal Dry Fruits Pvt. Ltd (Rostaa) |
| Haldirams |
| Delicious Cashew Co. |
| Athav Products |
| Kalbavi Cashews |
| Wonderland Foods |
| Nutty Yogi |
| Shakti Dry Foods |
| Greendot Health Foods Pvt. Ltd (Cornitos) |
| Others |
Supply & Pricing Matrix
African raw nut procurement costs cascade through Indian processing clusters into three distinct pricing tiers. FSSAI compliance investments and steam-shelling capital requirements stratify margins between integrated operators and small-scale shellers. Maharashtra and Kerala processors absorb freight volatility from Tanzanian and Ivorian origins before passing differential costs to export houses, modern retail buyers, and direct-to-consumer platforms.
Pricing Analysis
Input-cost pass-through from African raw nut origins determines baseline kernel pricing across export-grade and domestic consumption tiers. Three-tier pricing structure across premium, standard, and economy levels separates W320 whole nuts with BIS certification from broken grades and unbranded loose kernels. Pricing pressure stems from palm kernel substitution in bakery and confectionery ingredient channels, compressing broken nut and powder segment margins. Quick-service restaurants exhibit lowest price sensitivity due to menu premiumization requirements, while industrial bakery formulators demonstrate highest sensitivity to cost differentials against oilseed alternatives.
Supply Chain Analysis
Single-source vulnerability sits with Tanzanian and Ivorian raw nut supply concentration, exposing Indian processors to crop shortfall transmission. Processing capacity draws from Maharashtra shelling clusters, Kerala grading corridors, and emerging Karnataka integrated facilities. Raw material dependencies include African in-shell cashew, domestic western-India orchard supply, and imported processing equipment. Tariff exposure on raw nut imports constitutes the dominant supply chain risk. Distribution runs through platform-native e-commerce fulfillment, modern retail chains, and traditional mandi networks for loose kernel aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSSAI fortification mandates function as a regulatory compounder, transforming compliance infrastructure into competitive moats that reshape procurement eligibility across modern retail and institutional channels.
For Market Incumbents: Deepen captive laboratory testing capacity to capture channel eligibility that smaller shellers forfeit under tightening aflatoxin enforcement. Expand steam-based shelling deployment in Karnataka to reduce logistics drag to port infrastructure while defending against emerging platform-native brands. Vertical integration into African origin sourcing mitigates freight volatility exposure from Tanzanian and Ivorian supply concentration. For New Entrants and Emerging Players: PLI scheme subsidies in India open a window for capital-efficient entry through export-grade equipment deployment in non-traditional western-India locations. Target direct-to-consumer e-commerce velocity as the most penetrable channel, bypassing distributor margin stacking that encumbers legacy wholesale-dependent operators. Position fortified roasted SKUs for quick-service restaurant procurement, leveraging FSSAI compliance as entry credential against unbranded loose kernel trade. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale integrated processors with captive testing infrastructure because regulatory compliance costs are consolidating channel access around operators with laboratory investments. Acquisition focus should center on Karnataka and Maharashtra shelling-sorting facilities with BIS certification and port proximity. Monitor CDSCO functional claim filing backlogs as inflection indicator for commercialization velocity in fortified SKU segments.| Strategic Initiative | Industry Significance |
|---|---|
| Steam Shelling Technology Deployment | Vacuum-assisted peeling reduces kernel breakage below 5% thresholds for export-grade sorting premiums. |
| Captive Laboratory Infrastructure Investment | In-house aflatoxin testing capacity secures FSSAI channel eligibility that smaller operators forfeit. |
| Direct-to-Consumer E-Commerce Launch | Platform-native fulfillment bypasses wholesale margin stacking while capturing urban household demand velocity. |
| African Origin Backward Integration | Upstream control over Tanzanian and Ivorian raw nut supply mitigates freight volatility and currency fluctuation exposure. |
| Fortified SKU Development | Micronutrient enrichment protocols unlock institutional procurement channels under CDSCO functional claim oversight. |
Research Methodology
Direct dialogue with processing plant managers, FSSAI compliance officers, modern retail category buyers, and quick-service restaurant procurement heads grounded qualitative findings in operational reality. Secondary validation drew from DGFT export protocol notifications, BIS grading standard updates, FSSAI fortification guidelines, and customs trade data on raw nut imports. Bottom-up triangulation across processor capacity assessments and top-down demand modeling from urban household consumption patterns converged on market sizing.
Segment-level value and volume trajectories across the analysis window reflect kernel form, packaging integrity, and channel access dimensions. Modeled segmentation spanned product type, packaging format, distribution channel, and end-user application tiers. CAGRs were derived from regression analysis against historical procurement volumes and projected urbanization-driven consumption shifts. Forecast inputs incorporated PLI scheme subsidy uptake rates and e-commerce platform penetration curves in western and southern states.
Forecast precision tightens around the base case; tail outcomes carry wider variance under African crop failure scenarios or abrupt FSSAI notification timeline acceleration. Projections assume sustained raw nut import dependence and gradual steam-shelling technology diffusion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Global Edible Nuts Market
Nuts and Seeds
Almond Butter Market
Nuts and Seeds
North America Moringa Products Market
Nuts and Seeds
Almond with Shell Snack Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
Germany Cashew Market
Nuts and Seeds
Almond Extract Market
Nuts and Seeds
Middle East and Africa Hazelnut Market
Nuts and Seeds
Thailand Fox Nuts Market
Nuts and Seeds
Japan Fox Nuts Market
Nuts and Seeds
Peanuts Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Asia-Pacific Cashew Market
Nuts and Seeds
Europe Cashew Market
Nuts and Seeds
Seed Butter Market
Nuts and Seeds
Tree Nuts Market