
 Low-Cal Nuts Market | 2026-2036
Low-Cal Nuts Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Cal Nuts Market Analytics
Precision dry-roasting and controlled oil-infusion technology is rewriting how low-calorie nut profiles achieve flavor without caloric penalty. Blue Diamond Growers leverages California almond cultivation to dominate raw material sourcing for reduced-calorie product lines. Tierra Farm differentiates through organic certification and small-batch roasting infrastructure. Mariani Nut Company anchors its position in private-label supply for health-focused retail chains.
Low-cal nuts are tree nuts and legumes processed to deliver reduced energy density per serving, typically achieved through defatting, air-popping, or minimal-oil roasting to maintain protein and micronutrient content while limiting caloric load to 120-160 kcal per ounce. Almonds lead product type segmentation due to established consumer familiarity and favorable fat-to-protein ratios that support clean-label positioning. Online retail channels represent the fastest-growing distribution pathway, driven by subscription models targeting fitness enthusiasts and diabetics seeking consistent supply of portion-controlled formats.
The FDA governs nutrition fact panel accuracy and health claim substantiation for low-calorie positioning, while USDA organic standards shape premium tier access. EFSA in Europe enforces calorie declaration tolerances that influence export formulation decisions. Stakeholders must monitor evolving front-of-pack labeling mandates and sweetener substitution regulations that will determine which processing innovations secure shelf placement in regulated channels.
Market Dynamics
FDA's updated nutrition labeling requirements for calorie transparency are forcing reformulation across the entire snack food supply chain, with precision dry-roasting and controlled oil-infusion technology now determining which products secure retail placement.
Growth Catalysts
- Air-popping defatting systems:This processing technology enables 120-160 kcal per ounce targets while preserving protein density, allowing clean-label positioning that commands premium shelf space in fitness-oriented retail channels.
- USDA organic standards:Certification requirements for premium tier access are accelerating investment in small-batch roasting infrastructure among processors seeking diabetic-friendly product line differentiation.
- United States demand concentration:Portion-controlled format preferences among health-conscious consumers are pulling subscription model innovation through online retail channels targeting consistent supply needs.
Market Restraints
- California almond sourcing concentration:Raw material dependence on a single growing region creates climate vulnerability and price volatility for defatted nut processors.
- EFSA calorie declaration tolerances:European export formulation requirements impose testing costs that compress margins for mid-scale producers lacking in-house analytical capabilities.
- Protein-fortified snack bar substitution:Alternative low-calorie protein delivery formats are capturing shelf space in convenience retail, constraining nut category expansion velocity.
Strategic Opportunities
- Subscription direct-to-consumer channels:Recurring revenue models targeting fitness enthusiasts and diabetics offer margin protection against retail slotting fee escalation.
- Front-of-pack labeling mandates:Evolving regulatory requirements for sweetener substitution transparency favor processors with advanced formulation R&D infrastructure.
- Private-label health chain supply:Anchor positioning with health-focused retail chains provides volume stability as branded competitors face promotional pressure.
Industry Challenges
- Precision roasting technician scarcity:Specialized skill requirements for controlled oil-infusion equipment operation outpace vocational training program output.
- Dual certification timeline compression:Simultaneous FDA nutrition panel accuracy and USDA organic standard compliance creates bottlenecks in new product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Cal Nuts Market |
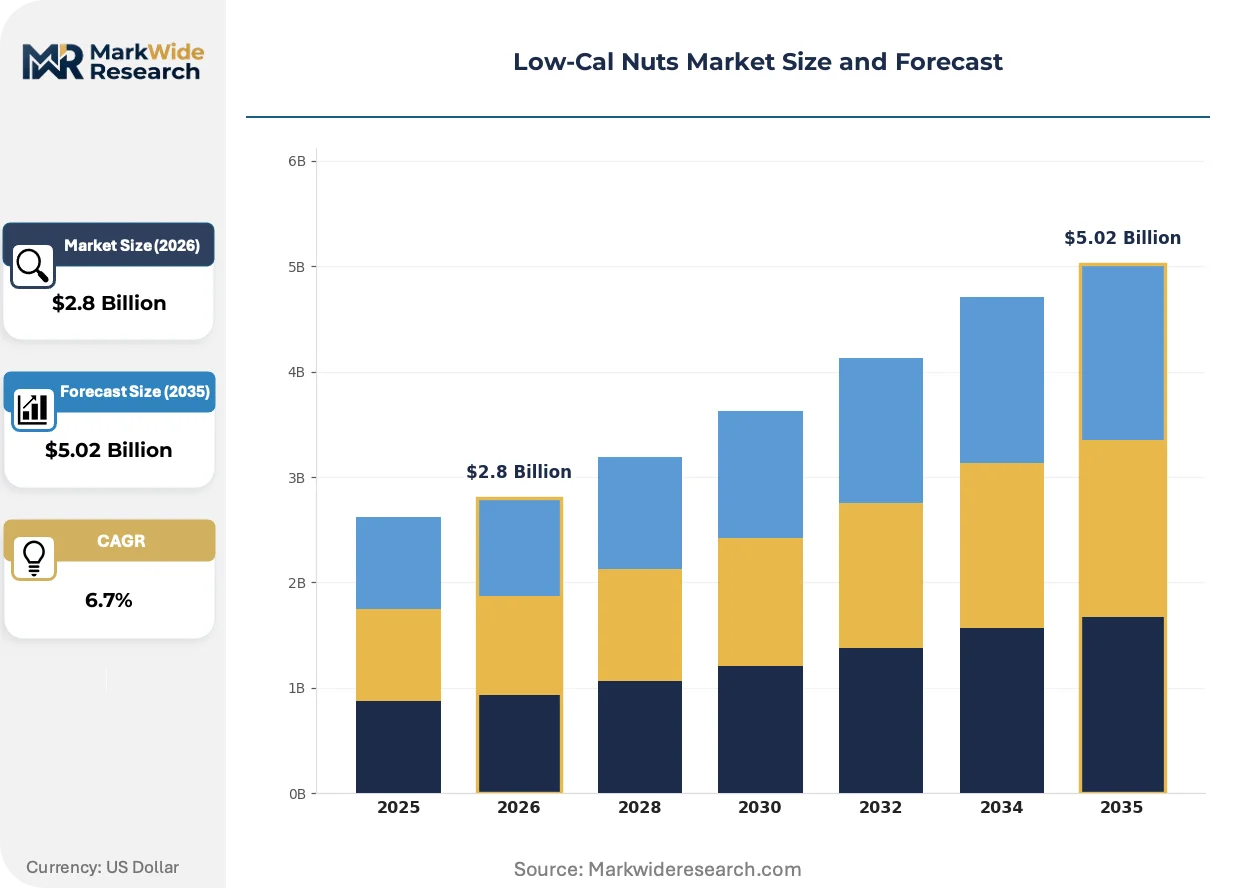
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almonds, Cashews, Peanuts, Walnuts Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale End User: Fitness Enthusiasts, Diabetics, Health-Conscious Consumers, Snack Lovers Packaging Type: Resealable Bags, Bulk Packages, Snack Packs, Canisters |
| Companies Covered | Global Nut Company AG, Tierra Farm, Sun Organic Farm, Royal Nut Company, Bob’s Red Mill Natural Foods, Honeyville Inc, Blue Diamond Growers, Waterford Nut Company, Mariani Nut Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Cal Nuts Market Evolving Landscape
Processing technology virtualization and regulatory disclosure mandates are compressing traditional formulation-to-shelf timelines while reshaping how nutritional claims achieve substantiation across distribution channels.
Precision dry-roasting with real-time moisture sensing is virtualizing the traditional oil-roasting paradigm by enabling flavor development without caloric penalty. Fitness-oriented retail buyers are adopting this equipment at accelerated replacement cycles. The technology is virtualizing capital allocation patterns as smaller processors achieve premium product parity without legacy infrastructure investments.
EFSA calorie declaration tolerance enforcement is tightening export formulation standards for reduced-energy nut products. European-bound shipments now require redundant analytical verification that adds 15-20 days to production scheduling. Private-label suppliers serving health-focused retail chains are most affected, responding through captive laboratory investments to maintain cross-Atlantic shipment eligibility.
Subscription-based procurement is consolidating purchase decisions among fitness enthusiasts and diabetic consumers into predictable quarterly patterns. Traditional wholesale distributors serving conventional grocery are losing volume to direct fulfillment models. This behavioral shift is most visible in United States metropolitan markets where same-day delivery infrastructure supports perishable nut product logistics.
Low-Cal Nuts Market Segmentation
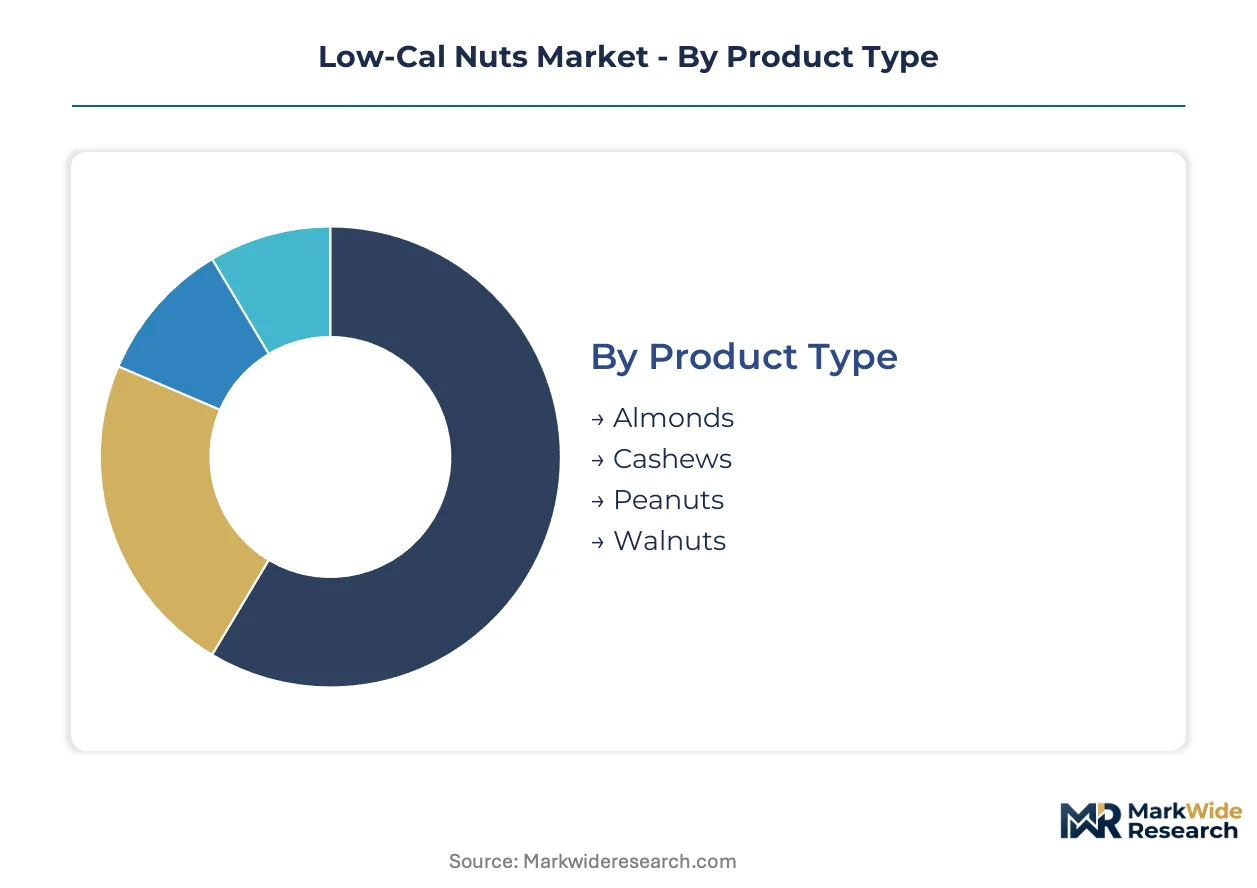
Segmentation in low-cal nuts reveals how processing technology and channel economics create divergent margin profiles across consumer touchpoints. Understanding these partitions exposes where precision roasting investments yield returns and where commodity pressure concentrates.
Product Type:
After-sales service intensity varies sharply across nut categories, with almonds requiring minimal technical support while walnuts demand moisture-management guidance for shelf-life optimization.
- Almonds:California-sourced kernels undergo precision dry-roasting to achieve 120-160 kcal per ounce targets while preserving favorable fat-to-protein ratios. Fitness-oriented retail channels in the United States command premium shelf space for defatted almond lines targeting diabetic-friendly positioning.
- Cashews:Higher inherent oil content necessitates controlled oil-infusion technology to hit reduced-calorie specifications without flavor degradation. Health food stores in metropolitan clusters favor cashew SKUs for their clean-label appeal among subscription-model subscribers seeking variety rotation.
- Peanuts:Legume classification enables air-popping defatting systems at lower processing cost, serving wholesale channels with volume-driven pricing.
- Walnuts:Omega-3 sensitivity requires modified atmosphere packaging integration, concentrating demand in premium-tier health food stores.
Almonds hold the largest share; momentum sits with cashews as flavor versatility expands diabetic-friendly product line applications.
Distribution Channel:
Channel cost tiers stratify sharply, with online retail absorbing logistics overhead while supermarkets extract slotting fees that compress processor margins.
- Online Retail:Subscription models targeting fitness enthusiasts and diabetics generate recurring revenue streams that insulate against wholesale price volatility. Same-day delivery infrastructure in United States metropolitan markets supports perishable nut product logistics for direct-to-consumer fulfillment.
- Supermarkets:Slotting fee escalation and promotional pressure dominate this channel, favoring private-label suppliers with volume stability from health-focused retail chain contracts.
- Health Food Stores:Premium positioning and certified organic SKUs concentrate here, with smaller processors leveraging small-batch roasting infrastructure for differentiation.
- Wholesale:Bulk format demand from institutional buyers and foodservice operators drives air-popped peanut volume through cost-minimized processing lines.
Supermarkets retain volume dominance; online retail climbs fastest as subscription procurement consolidates purchase decisions into predictable quarterly patterns.
End User:
Customer type maturity varies, with fitness enthusiasts driving innovation adoption while snack lovers remain price-sensitive and format-flexible.
- Fitness Enthusiasts:Protein density requirements and portion-control preferences pull precision dry-roasted products through subscription channels with minimal price elasticity.
- Diabetics:Glycemic management needs concentrate demand in resealable snack packs with explicit calorie transparency, commanding premium positioning in health food stores.
- Health-Conscious Consumers:Broad demographic spanning multiple channels, responsive to front-of-pack labeling mandates and USDA organic certification signals.
- Snack Lovers:Taste-driven purchasing with lower loyalty, accessible through supermarket promotional cycles and bulk format value positioning.
Fitness enthusiasts anchor premium tier development; diabetics represent the steepest expansion trajectory as FDA calorie transparency requirements reshape product formulation standards.
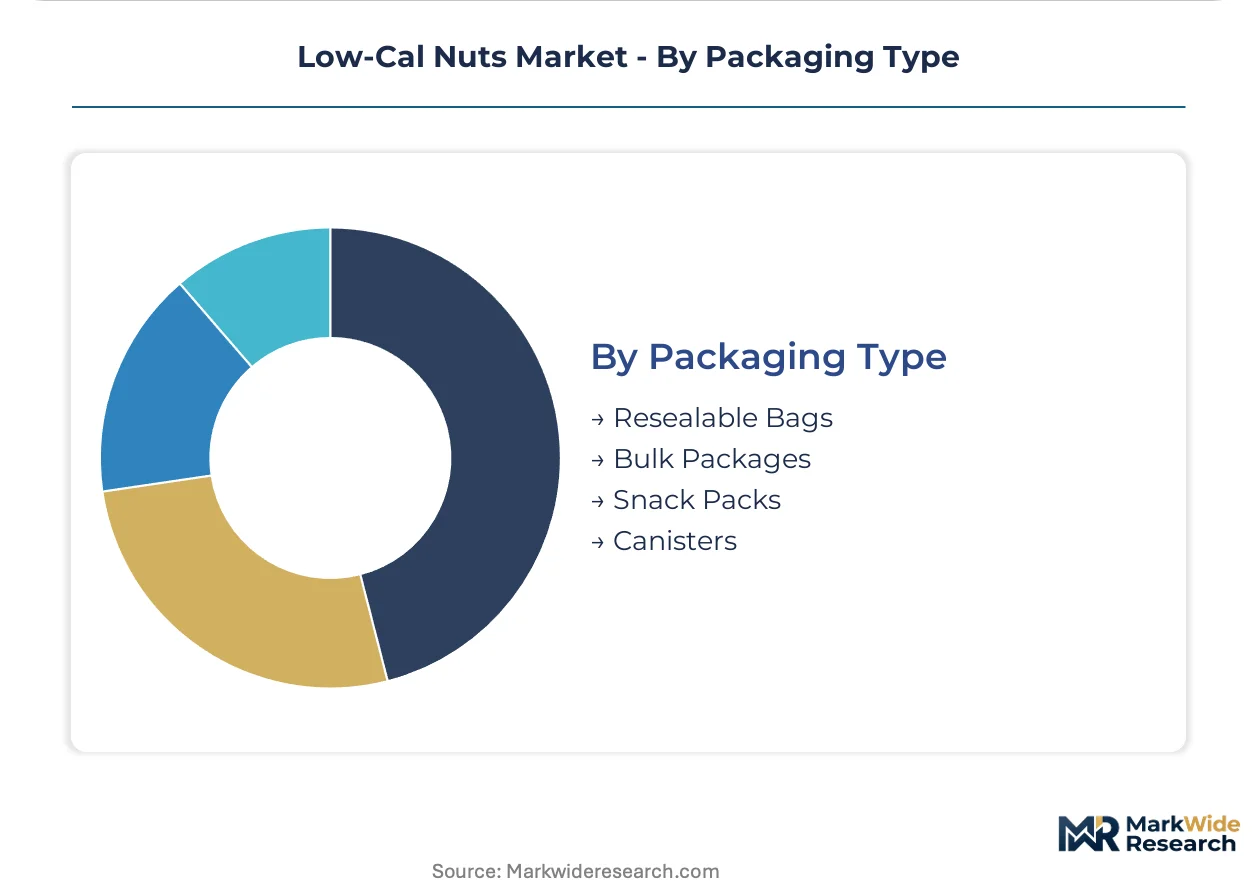
Packaging Type:
Supply concentration in flexible packaging equipment shapes which formats achieve cost efficiency at scale.
- Resealable Bags:Consumer convenience and portion control alignment drive adoption across online retail and supermarket channels, with zipper technology adding marginal cost.
- Snack Packs:Single-serve formats target fitness enthusiasts and diabetic consumers with explicit 120-160 kcal portion declarations, favored by subscription models.
- Canisters:Premium shelf presence and extended shelf-life protection concentrate in health food stores, requiring higher structural packaging investment.
- Bulk Packages:Wholesale channel economics favor this format, with minimal unit packaging cost and foodservice-oriented logistics.
Resealable bags capture the broadest adoption; snack packs gain share fastest as portion-controlled formats align with regulatory disclosure mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness enthusiasts and diabetic consumers cluster disproportionately in metropolitan markets with established health-food retail infrastructure and direct-to-consumer delivery networks. Subscription procurement patterns concentrate purchase decisions in specific urban corridors where same-day logistics support perishable product fulfillment. Regulatory frameworks for calorie transparency and organic certification vary sharply across national boundaries, shaping where processors locate formulation and packaging operations.
United States
Fitness-oriented retail channels and diabetic-friendly product lines command premium shelf space in coastal metropolitan markets. FDA nutrition labeling requirements for calorie transparency are forcing reformulation investments among domestic processors. California's Central Valley anchors raw material sourcing for almond-based reduced-calorie lines, with precision dry-roasting infrastructure concentrated in Sacramento and Fresno processing clusters.
Germany
Health-conscious consumers in metropolitan regions drive demand for USDA-equivalent organic certification and explicit portion-controlled formats. EFSA calorie declaration tolerances impose redundant analytical verification requirements on imported reduced-energy nut products. Bavaria's food processing corridor around Munich hosts private-label suppliers serving health-focused retail chains across German-speaking Europe.
United Kingdom
Subscription model adoption among fitness enthusiasts concentrates in Greater London and Southeast England where same-day delivery infrastructure supports direct fulfillment. Front-of-pack labeling mandates under evolving domestic regulations favor processors with advanced formulation R&D capabilities. The Midlands manufacturing belt houses air-popping defatting system operators serving wholesale channels with volume-driven peanut processing.
Australia
Clean-label positioning and organic certification requirements shape premium tier access in Sydney and Melbourne health food store networks. TGA-aligned nutritional claim substantiation standards influence product formulation for both domestic consumption and Asia-Pacific export. Queensland's nut cultivation regions supply raw material to processors in Brisbane focused on controlled oil-infusion technology for reduced-calorie cashew lines.
Japan
Portion-controlled format preferences among health-conscious aging demographics concentrate demand in Tokyo-Osaka metropolitan corridors. METI standards for functional food claims create regulatory pathways for protein-density positioning in reduced-energy nut products. The Chubu region around Nagoya hosts packaging equipment specialists serving domestic processors with modified atmosphere technology for omega-3-sensitive walnut lines.
Low-Cal Nuts Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered access points defined by retail slotting capacity and direct-to-consumer infrastructure ownership. The vendor base stratifies between scale-driven processors with captive raw material sourcing and smaller certified-organic operators with small-batch roasting differentiation. Three archetypes dominate: California-anchored almond specialists with backward integration into cultivation, subscription-optimized direct-to-consumer brands, and private-label suppliers with health-chain contract stability. Competitive moves center on M&A for roasting technology acquisition and strategic partnerships for metropolitan same-day delivery network access.
Within the cultivation-integrated tier, Blue Diamond Growers represents the archetype of raw material control through California almond operations. Tierra Farm exemplifies the certified-organic specialist model with small-batch differentiation. Mariani Nut Company anchors private-label supply positioning for health-focused retail chain volume stability. These three entities collectively illustrate how sourcing control, certification premium, and channel contract security define competitive positioning in reduced-calorie nut processing.
| Leading Market Players |
|---|
| Global Nut Company AG |
| Tierra Farm |
| Sun Organic Farm |
| Royal Nut Company |
| Bob's Red Mill Natural Foods |
| Honeyville Inc |
| Blue Diamond Growers |
| Waterford Nut Company |
| Mariani Nut Company |
| Others |
Value Network & Pricing Analysis
Undercapacity in California almond processing infrastructure drives aggressive contract negotiations between growers and defatting operators, compressing margins for mid-scale processors while concentrating pricing power among cultivation-integrated players with captive supply.
Pricing Analysis
Cost-plus contracts indexed to California almond spot markets dominate procurement between growers and processors, with premium tiers commanding USDA organic certification markups. Three-tier pricing structure across certified-organic, conventional-defatted, and commodity-raw levels reflects quality grade and certification level differentiation. Pricing pressure stems from EFSA calorie declaration tolerance compliance costs eroding European export margins. Snack lovers in supermarket channels exhibit highest price sensitivity, while fitness enthusiasts in subscription channels accept minimal price elasticity.
Supply Chain Analysis
Contract manufacturing concentration sits with Blue Diamond Growers, Mariani Nut Company, and Tierra Farm holding precision dry-roasting capacity. Raw material sourcing draws from California's Central Valley, Queensland in Australia, and Spain's Valencia region for almond supply. Controlled oil-infusion equipment, modified atmosphere packaging films, and analytical verification services constitute critical input dependencies. Single-source vulnerability concentrates in California almond cultivation exposure to drought cycles. Distribution runs through direct-to-consumer subscription platforms, health-focused retail chains, and wholesale foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where subscription fulfillment and portion-control customization layers expand faster than commodity nut processing, rewarding recurring-revenue infrastructure over transactional volume.
For Market Incumbents: Entrench position through backward integration into precision dry-roasting equipment fleets and captive laboratory investments for dual FDA-USDA certification compliance. Protein-fortified snack bar substitution threatens category expansion velocity; defend against displacement by locking health-focused retail chains into private-label exclusivity with volume stability guarantees.
For New Entrants and Emerging Players: Metropolitan Australia and Japan's Chubu region offer underpenetration for diabetic-friendly product lines with explicit calorie transparency. Health food stores in Sydney and Melbourne present the most penetrable channel tier for certified-organic positioning. Pursue go-to-market entry through direct-to-consumer subscription models targeting fitness enthusiasts with same-day delivery infrastructure partnerships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-optimized direct-to-consumer brands with portion-control customization capabilities. Long-term viability favors acquisition targets with small-batch roasting infrastructure and health-chain contract stability over commodity-scale processors. Watch for inflection in front-of-pack labeling mandate enforcement as signal for formulation R&D valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Roasting Technology Acquisition | Controlled oil-infusion equipment purchases enable 120-160 kcal per ounce targets without flavor degradation. |
| Subscription Direct-to-Consumer Launch | Recurring revenue models targeting fitness enthusiasts and diabetics insulate against retail slotting fee escalation. |
| USDA Organic Certification Investment | Premium tier access requires small-batch roasting infrastructure and analytical verification capabilities. |
| Health-Focused Retail Chain Partnership | Private-label supply contracts with fitness-oriented channels provide volume stability amid promotional pressure. |
| Metropolitan Same-Day Delivery Network Access | Same-day logistics partnerships in United States coastal markets support perishable nut product fulfillment. |
Research Methodology
Operator-level perspectives from precision roasting technicians, health food store category buyers, almond cultivation managers, and FDA regulatory consultants anchored the qualitative base. Secondary validation drew from USDA organic certification databases, FDA nutrition labeling guidance documents, EFSA calorie tolerance enforcement records, and customs trade data for almond import flows. Bottom-up volume estimates from processing facility throughput combined with top-down retail audit triangulation established market sizing.
Scenario-bracketing around regulatory enforcement intensity and substitution threat velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end user archetype, and packaging format. CAGRs derived from historical processing capacity expansion rates and subscription adoption curves. Industry-specific forecast inputs incorporated precision dry-roasting equipment replacement cycles and health-chain private-label contract renewal patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by protein-fortified snack bar manufacturers or accelerated FDA front-of-pack labeling mandates would shift outcomes. Quarterly review of EFSA enforcement actions, California drought severity indices, and subscription churn rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Australia Fox Nuts Market
Nuts and Seeds
Almond Products Market
Nuts and Seeds
Soy Nut Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Tree Nuts Market
Nuts and Seeds
Europe Hazelnut Market
Nuts and Seeds
Nut Products Market
Nuts and Seeds
Vietnam Cashew Market
Nuts and Seeds
Seed Butter Market
Nuts and Seeds
Asia-Pacific Cashew Market
Nuts and Seeds
United States Cashew Market
Nuts and Seeds
Pecans Market
Nuts and Seeds
Low Fat Nut Butter Market
Nuts and Seeds
Asia-Pacific Hazelnut Market
Nuts and Seeds
Global Almond Powder Market
Nuts and Seeds
Saudi Arabia Nuts Market