
 Global Patient Safety and Risk Management Softwares Market | 2026-2036
Global Patient Safety and Risk Management Softwares Market Size, Share, and Industry Trends Forecast 2026-2036
Global Patient Safety and Risk Management Softwares Market Foresight
The United States is reconfiguring how health systems approach enterprise risk infrastructure through accelerated digitization of safety protocols. RLDatix leverages its specialized incident management platform to anchor North American hospital network contracts. Riskonnect, Inc. competes across broader enterprise risk categories beyond healthcare, while symplr sustains workflow automation depth in clinical operations software.
Patient safety and risk management softwares constitute integrated digital platforms that capture, analyze, and escalate adverse events, near-misses, and compliance deviations through configurable workflows and real-time dashboards. These systems employ rule-based algorithms and natural language processing to classify incident severity and route notifications to appropriate clinical governance committees. Cloud-based deployment dominates new procurement as hospitals prioritize remote accessibility and reduced IT infrastructure burden, while on-premise solutions retain share among organizations with stringent data sovereignty requirements. Incident management functionality captures the largest addressable spend pool given regulatory mandates for root cause analysis, though compliance management modules are expanding fastest as jurisdictions tighten reporting obligations.
FDA post-market surveillance requirements, OSHA workplace safety mandates, and HIPAA breach notification rules collectively shape product specifications and sales cycles across the United States. The European EMA vigilance framework and MDR adverse event reporting standards create parallel compliance burdens for multinational health systems and device manufacturers operating across jurisdictions. Stakeholders must monitor how AI-enabled predictive risk scoring alters procurement criteria and vendor selection benchmarks as algorithms gain regulatory scrutiny.
Market Dynamics
Cloud-native architectures are displacing legacy on-premise deployments as hospital systems consolidate IT infrastructure and prioritize remote accessibility for distributed clinical governance committees.
Growth Catalysts
- FDA post-market surveillance mandates:Medical device manufacturers must integrate adverse event tracking systems, forcing software procurement across the United States.
- Hospital consolidation:Health system mergers create enterprise-scale contracts for integrated risk platforms spanning multiple facilities.
- Natural language processing:AI-driven severity classification automates incident routing and reduces manual triage bottlenecks in clinical workflows.
Market Restraints
- Data sovereignty requirements:Stringent localization rules in Germany and France block cloud migration for certain public hospital networks.
- Interoperability gaps:Legacy EHR systems lack standardized APIs, forcing expensive middleware development for incident data exchange.
- Specialized talent scarcity:Shortage of clinical informaticists trained in both patient safety protocols and software configuration limits implementation velocity.
Strategic Opportunities
- EU MDR compliance surge:The European Medical Device Regulation's adverse event reporting standards create replacement demand for outdated vigilance systems.
- Workplace safety convergence:OSHA reporting integration with clinical incident platforms opens cross-departmental sales within US hospital systems.
- AI predictive scoring:Machine learning models that forecast sentinel events before occurrence represent unpenetrated functionality for early adopters.
Industry Challenges
- Algorithmic validation timelines:FDA scrutiny of AI-enabled risk scoring prolongs certification cycles and delays product launches.
- Legacy system integration:Custom connectors for 1990s-era mainframe patient record systems consume disproportionate implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Patient Safety and Risk Management Softwares Market |
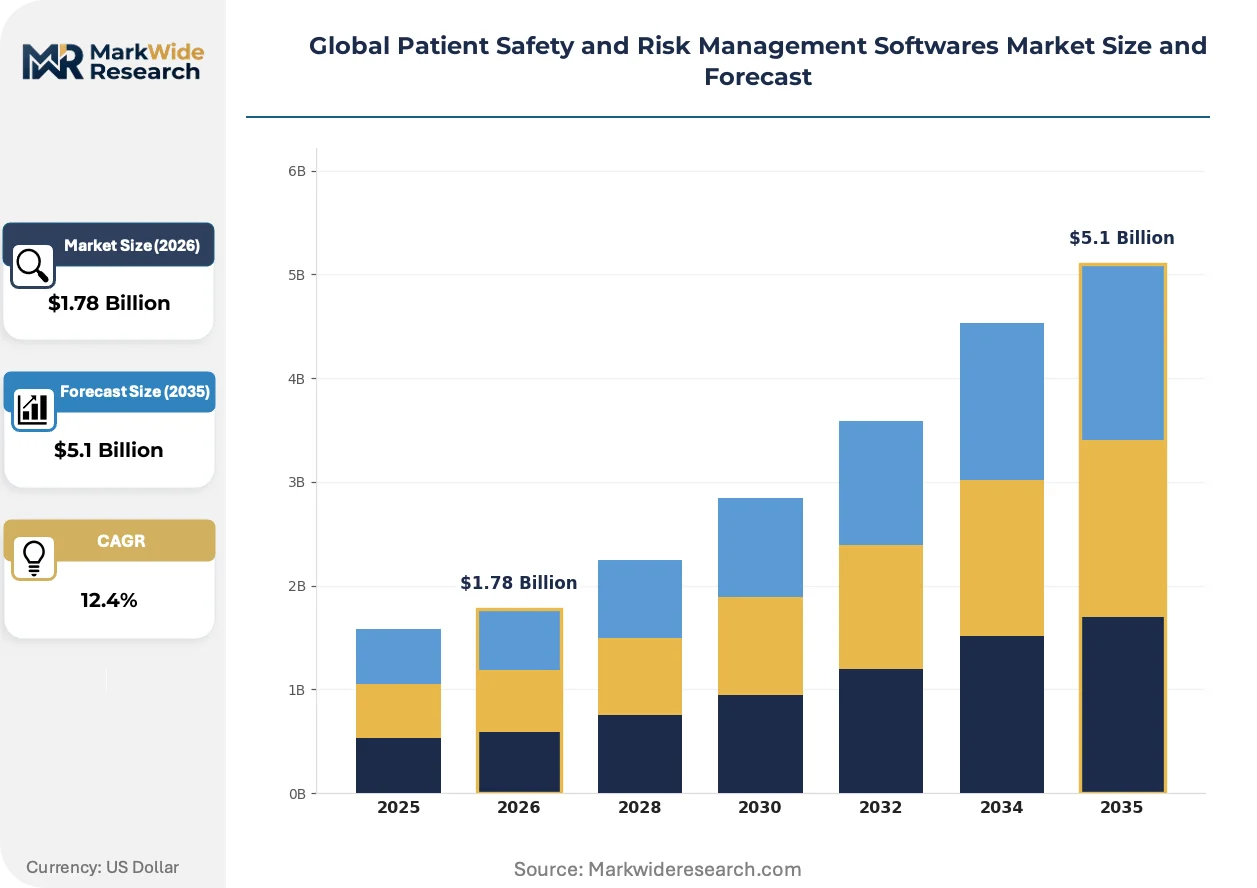
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $5.1 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reporting Tools, Workflow Management, Incident Management, Compliance Management Technology: Cloud-Based, On-Premise, Hybrid, Mobile Applications End User: Hospitals, Clinics, Long-Term Care Facilities, Ambulatory Surgical Centers Deployment: Public Cloud, Private Cloud, On-Premise Solutions, Hybrid Solutions |
| Companies Covered | RLDatix, Riskonnect, Inc., Origami Risk LLC, symplr, Clarity Group, Inc., Health Catalyst, Conduent, Inc., Becton, Dickinson and Company, Cority, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Patient Safety and Risk Management Softwares Market Shifts & Advancements
Artificial intelligence is embedding into core platform functions, altering how vendors differentiate and how buyers evaluate total cost of ownership beyond traditional licensing metrics.
Natural language processing engines are hybridizing structured incident forms with free-text clinical narratives, enabling automated severity classification without forcing workflow changes on time-constrained nursing staff. Early adopters in academic medical centers report reduced reporting abandonment rates. The technology is hybridizing rule-based governance with probabilistic risk models, compressing vendor competitive advantage timelines.
The European Union's AI Act imposes conformity assessment requirements on clinical decision-support algorithms, forcing software vendors to document training data provenance and bias mitigation protocols. Risk scoring modules face reclassification as high-risk AI systems under Annex III. US-based vendors with European deployments are responding by segregating EU-specific algorithm versions and establishing dedicated conformity documentation teams.
Subscription pricing for modular functionality is displacing perpetual licenses for monolithic suites, particularly among mid-size community hospital networks with constrained capital budgets. Vendors unbundle incident management, compliance tracking, and governance analytics into separately purchasable tiers. This shift is most visible in the United States, where private equity-backed health systems prioritize operational expenditure predictability over upfront software investments.
Global Patient Safety and Risk Management Softwares Market Segmentation
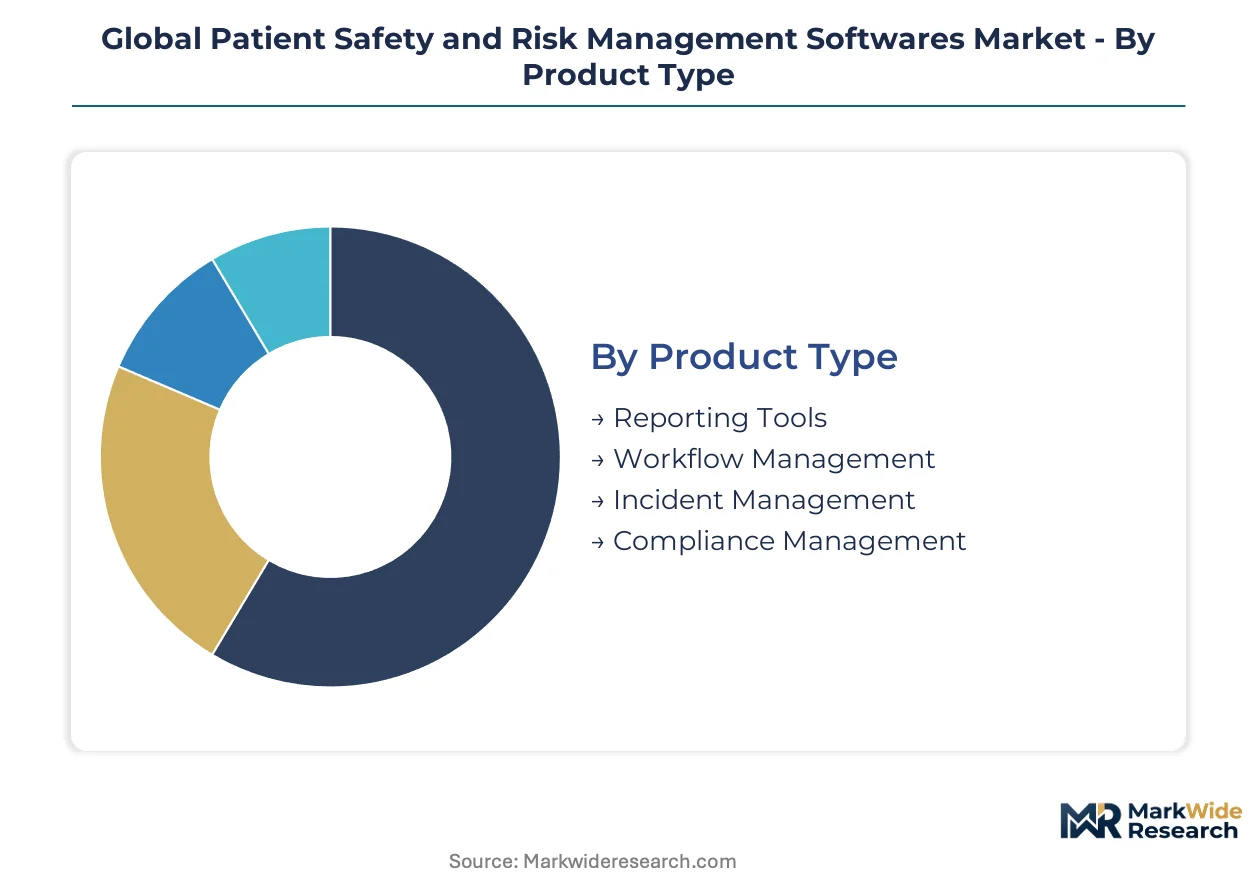
Patient safety software procurement patterns diverge sharply across organizational scale, regulatory exposure, and IT infrastructure maturity. Understanding these segment boundaries clarifies why cloud-native vendors capture academic medical centers while hybrid architectures persist among consolidated community networks.
Product Type:
Use-case spectrum spans reactive incident capture through proactive compliance orchestration, with workflow automation bridging operational silos.
- Incident Management:Core functionality automates adverse event capture, root cause analysis workflows, and sentinel event escalation to clinical governance committees. United States health systems with Joint Commission accreditation mandates drive concentrated demand, prioritizing real-time dashboards over batch reporting.
- Compliance Management:Modules track regulatory deadlines, automate FDA adverse event submissions, and manage OSHA workplace safety documentation. European health systems under EMA vigilance and EU MDR reporting obligations are expanding procurement fastest as jurisdictional requirements tighten.
- Reporting Tools:Standardized forms and analytics engines for regulatory submission and internal quality review.
- Workflow Management:Configurable routing engines that direct incidents to appropriate review committees based on severity algorithms.
The dominant share belongs to Incident Management, while Compliance Management is closing the gap fastest.
Technology:
Deployment architecture choices reflect data sovereignty constraints against accessibility imperatives for distributed clinical teams.
- Cloud-Based:Multi-tenant SaaS platforms with automatic updates, elastic scaling, and remote access for regional hospital networks. United States private equity-backed health systems prioritize operational expenditure predictability and reduced IT infrastructure burden.
- On-Premise:Single-tenant installations behind institutional firewalls with full data control. German and French public hospital networks with stringent localization requirements retain this architecture despite higher total cost of ownership.
- Hybrid:Sensitive patient data resides on-premise while analytics and reporting leverage cloud processing.
- Mobile Applications:Point-of-care capture interfaces for nursing staff and rapid response teams.
Cloud-Based architectures command the largest installed base, though Hybrid deployments are gaining share fastest among mid-tier systems.
End User:
Facility type determines incident complexity, regulatory scrutiny intensity, and governance committee structure.
- Hospitals:Enterprise-scale platforms integrating multiple service lines, emergency departments, and surgical suites with 24/7 incident coverage. United States academic medical centers with Level I trauma designations generate the highest per-facility software spend.
- Long-Term Care Facilities:Specialized modules for fall prevention, medication error tracking, and CMS compliance reporting. United States nursing homes facing heightened survey scrutiny are accelerating digitization of safety protocols.
- Clinics:Streamlined incident capture for outpatient settings with lower event volume but similar documentation requirements.
- Ambulatory Surgical Centers:Procedure-specific risk tracking aligned with state licensing and accreditation standards.
Hospitals retain the dominant procurement volume, while Long-Term Care Facilities are expanding most quickly as regulatory pressure intensifies.
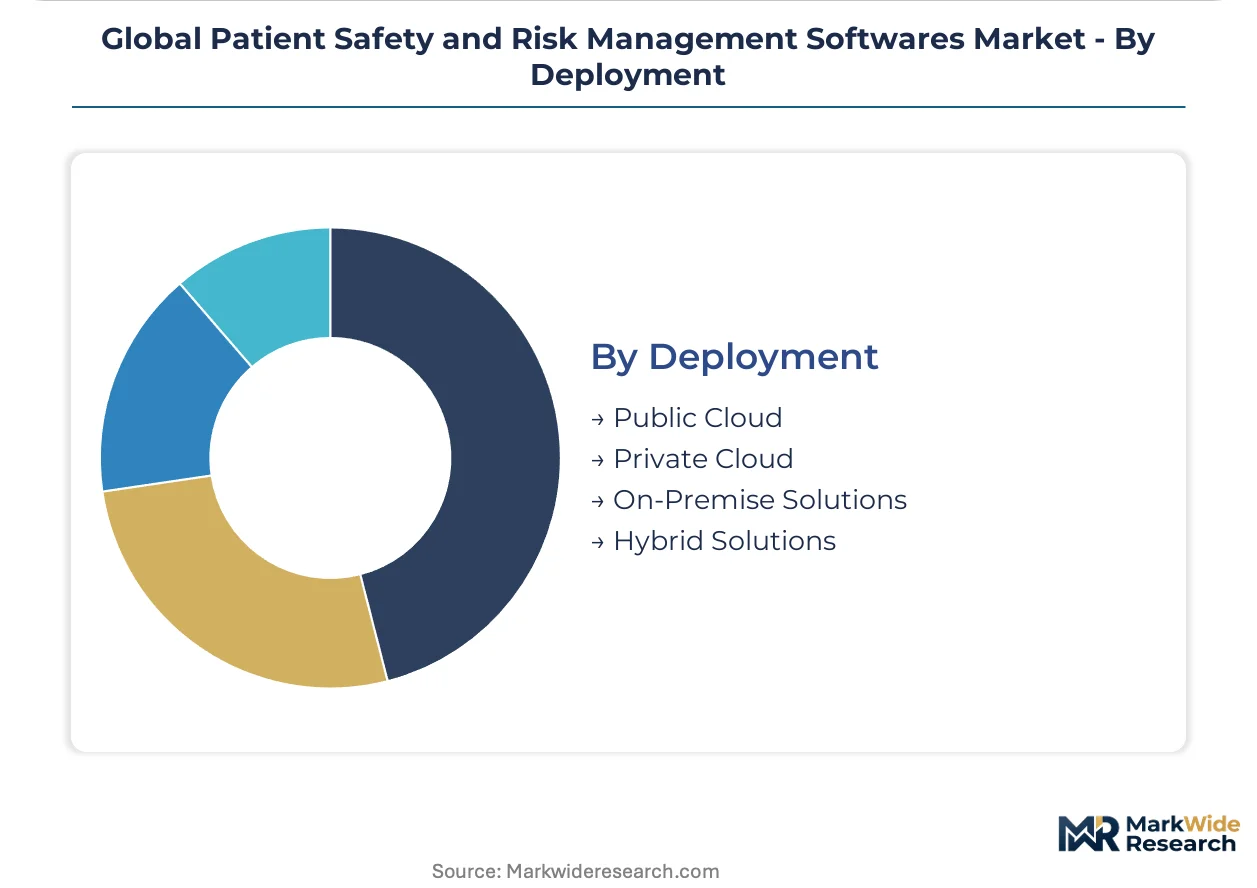
Deployment:
Infrastructure ownership models segment along capital availability, risk tolerance, and internal technical capacity.
- Public Cloud:Shared infrastructure with vendor-managed security patching and automatic feature releases. United States community hospital networks with constrained IT staffing favor this model for fastest implementation timelines.
- Private Cloud:Dedicated single-tenant environments with customizable security configurations. Health systems in Switzerland and the United Arab Emirates with strict data residency requirements select this architecture.
- On-Premise Solutions:Full institutional control over hardware, networking, and data storage location.
- Hybrid Solutions:Selective cloud migration preserving sensitive workloads on institutional servers.
Public Cloud deployments lead in new contract value, while Private Cloud is climbing the fastest among international health systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development for patient safety platforms concentrates in the United States, where venture capital flows into health IT and hospital consolidation creates enterprise-scale procurement opportunities. Regulatory complexity across multiple jurisdictions shapes where vendors establish compliance documentation teams and localized algorithm versions.
United States
Health system mergers and private equity-backed hospital networks drive concentrated demand for cloud-native risk platforms. FDA post-market surveillance mandates for medical devices force manufacturers to integrate adverse event tracking systems. The Boston-Cambridge corridor hosts specialized clinical informatics firms developing NLP engines for automated severity classification.
Germany
Public hospital networks maintain stringent data sovereignty requirements that sustain on-premise deployment preferences despite higher total cost of ownership. The national hospital IT modernization program accelerates digitization of safety protocols across state-owned facilities. Berlin and Munich anchor vendor service centers supporting DACH-region compliance configurations.
United Kingdom
NHS England's patient safety incident response framework mandates standardized reporting across integrated care systems. The Medicines and Healthcare products Regulatory Agency enforces vigilance requirements for device manufacturers operating in British markets. London's health tech cluster attracts vendors establishing European headquarters post-Brexit.
France
Regional hospital agencies enforce localization rules that block full cloud migration for certain public networks. ANSM pharmacovigilance obligations create parallel compliance burdens for multinational device manufacturers. The Paris-Saclay medical technology corridor concentrates vendor implementation partnerships with academic hospital centers.
Japan
PMDA adverse event reporting standards for pharmaceuticals and devices shape software specifications for Asia-Pacific deployments. METI digital health initiatives subsidize safety platform adoption among regional medical associations. Tokyo and Osaka anchor vendor localization efforts for Japanese-language NLP and severity classification algorithms.
Global Patient Safety and Risk Management Softwares Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in workflow automation and analytics modules. The vendor landscape organizes around three archetypes: specialized healthcare risk platforms, cross-industry enterprise risk suites, and clinical operations software extenders. Consolidation pressures intensify as hospital systems demand unified governance dashboards spanning incident capture, compliance tracking, and predictive analytics. Strategic moves concentrate on cloud migration acceleration and AI-enabled severity scoring differentiation.
Within the specialized healthcare tier, RLDatix anchors North American hospital network contracts through incident management depth. Riskonnect, Inc. exemplifies the cross-industry enterprise risk archetype, competing across broader categories beyond healthcare with configurable governance frameworks. symplr occupies a position among clinical operations extenders, leveraging workflow automation heritage to embed safety functionality into existing hospital IT stacks.
| Leading Market Players |
|---|
| RLDatix |
| Riskonnect, Inc. |
| Origami Risk LLC |
| symplr |
| Clarity Group, Inc. |
| Health Catalyst |
| Conduent, Inc. |
| Becton, Dickinson and Company |
| Cority |
| Others |
Supply & Pricing Matrix
The Trans-Pacific cable corridor's bandwidth cost dynamics compress margins for cloud-native platform vendors while amplifying price differentiation between SaaS tiers and on-premise perpetual licenses. Supply concentration among three hyperscale infrastructure providers in the United States, Ireland, and Singapore feeds this pricing asymmetry, as hospital systems with stringent data sovereignty requirements absorb freight-equivalent premiums for localized hosting.
Pricing Analysis
EU AI Act conformity assessment requirements dictate the pricing tier structure for algorithm-enabled risk scoring modules, separating premium validated-AI offerings from standard rule-based configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and customization depth. Cost compression in the economy tier is intensifying because mid-size community hospitals prioritize operational expenditure predictability over advanced analytics. Long-term care facilities exhibit highest price sensitivity due to constrained Medicaid reimbursement environments, while academic medical centers with NIH funding demonstrate lowest sensitivity to per-seat licensing costs.
Supply Chain Analysis
Upstream cloud infrastructure feeds from concentrated hyperscale capacity in the United States, Ireland, and Singapore, with secondary nodes emerging in Frankfurt and Tokyo. Natural language processing engines draw from open-source transformer architectures and proprietary clinical corpora, while severity classification algorithms rest on annotated incident databases from Joint Commission-accredited institutions. Single-source vulnerability pervades the NLP training data layer, where three academic medical centers supply the majority of labeled sentinel event records. Distribution runs through direct enterprise sales teams for hospital systems above 500 beds, with value-added resellers penetrating ambulatory surgical centers and long-term care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through health system consolidation, as private equity-backed hospital networks extract volume discounts from vendors while demanding unified governance dashboards across acquired facilities.
For Market Incumbents: Harden cloud-native architecture moats through exclusive partnerships with Epic and Cerner integration layers, insulating against API-standardization threats from FHIR-native challengers. Deepen vertical integration into clinical NLP training data through exclusive licensing agreements with academic medical centers, securing algorithmic differentiation that regulatory validation timelines would otherwise erode. For New Entrants and Emerging Players: French public hospital networks represent the most penetrable white-space target, as ANSM localization requirements have slowed incumbent cloud migration and preserved on-premise replacement cycles. German state-owned facilities under the national hospital IT modernization program offer parallel entry points for hybrid deployment architectures. A compliance-first go-to-market angle emphasizing EU MDR adverse event reporting automation outflanks generalist risk platforms lacking jurisdiction-specific workflow templates. For Investors and Strategic Acquirers: FDA scrutiny of AI-enabled risk scoring reshapes the acquisition landscape, elevating targets with completed 510(k) pathways above pre-clinical algorithm developers. Long-term viability centers on vendors bridging incident management depth with predictive analytics capabilities across a 5-10 year regulatory maturation window. Acquisition target archetype: specialized healthcare risk platforms with 50+ hospital system references and existing FDA quality system documentation. The signal to watch is Joint Commission certification of AI-augmented root cause analysis workflows as a standard survey expectation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic and Cerner EHR embedding accelerates hospital procurement cycles through existing vendor relationships. |
| Regulatory Certification Pathway | FDA 510(k) clearance for AI severity scoring creates defensible pricing premiums against unvalidated competitors. |
| Acquisition of Specialist Firm | Clinical NLP startups with annotated sentinel event databases address training data scarcity constraining algorithm development. |
| Geographic Expansion | EU MDR compliance surge in Germany and France drives replacement demand for outdated vigilance systems. |
| Strategic Partnership | Joint Commission co-development of AI-augmented survey standards locks in reference customer status for platform vendors. |
Research Methodology
Cross-validation between primary interviews with hospital risk managers, clinical informaticists, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, CMS Medicare cost reports, and hospital procurement database extracts. Bottom-up triangulation against top-down regulatory mandate impact modeling ensures segmentation integrity across deployment architectures and facility types.
Calibration against historical adoption curves for cloud-based clinical systems informs the projection framework across the analysis window. Segmentation dimensions include product type, deployment model, organization size tier, and regional regulatory cluster. CAGRs derive from fitted diffusion models incorporating EMA vigilance framework expansion timelines and OSHA workplace safety convergence patterns. Forecast inputs encompass health system merger velocity indices and AI Act conformity assessment cost estimates for algorithm-enabled modules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by FHIR-native API-first entrants or hyperscaler direct healthcare verticalization would shift outcomes beyond modeled ranges. Cross-checking against CMS Hospital Compare safety metric trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Europe Governance, Risk and Compliance Platform Market
Risk Management and Compliance
NPL Management Market
Risk Management and Compliance
Legal Advisory Service Market
Risk Management and Compliance
Healthcare Safety and Risk Management Solutions Market
Risk Management and Compliance
Treasury and Risk Management Application Market
Risk Management and Compliance
Global Strategy Consulting Market
Risk Management and Compliance
Regtech Market
Risk Management and Compliance
Europe Strategy Consulting Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Global Risk and Compliance Consulting Services Market
Risk Management and Compliance
Stress Testing Services Market
Risk Management and Compliance
Risk Management Market
Risk Management and Compliance
Enterprise Risk Management Market
Risk Management and Compliance
Asia-Pacific Compliance and Traceability Solutions Market
Risk Management and Compliance
Global Risk Management Software Market
Risk Management and Compliance
Sell-Side Due Diligence Services Market