
 Gas Scrubber Market | 2026-2036
Gas Scrubber Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Scrubber Market Intelligence
Demand from specialized end-users in pharmaceuticals and food processing is bifurcating the market away from its traditional base in large-scale power generation and heavy industry. Mitsubishi Heavy Industries sustains its leadership in high-capacity systems for power plants and chemical processing facilities. In contrast, Parker Hannifin specializes in modular filtration technologies suited for smaller operational footprints. GEA Group leverages its process engineering expertise to serve the food and beverage sector with integrated solutions.
A gas scrubber is an air pollution control device designed to remove harmful particulates and gases from industrial exhaust streams. These systems function by dissolving or absorbing pollutants into a scrubbing liquid, or by reacting them with a solid sorbent. Wet scrubbers remain the dominant product type, especially for controlling industrial emissions from chemical processing. However, dry scrubbers utilizing advanced adsorption technologies are gaining traction in applications where water conservation is critical.
Regulatory frameworks such as the US EPA's National Emission Standards for Hazardous Air Pollutants (NESHAP) and the EU's Industrial Emissions Directive are primary demand drivers. In China, the Ministry of Ecology and Environment (MEE) enforces stringent limits on sulfur dioxide and nitrogen oxide emissions, mandating scrubber installations. Vendor selection will increasingly hinge on the ability to guarantee compliance with evolving regional air quality standards and specific pollutant removal efficiencies.
Market Dynamics
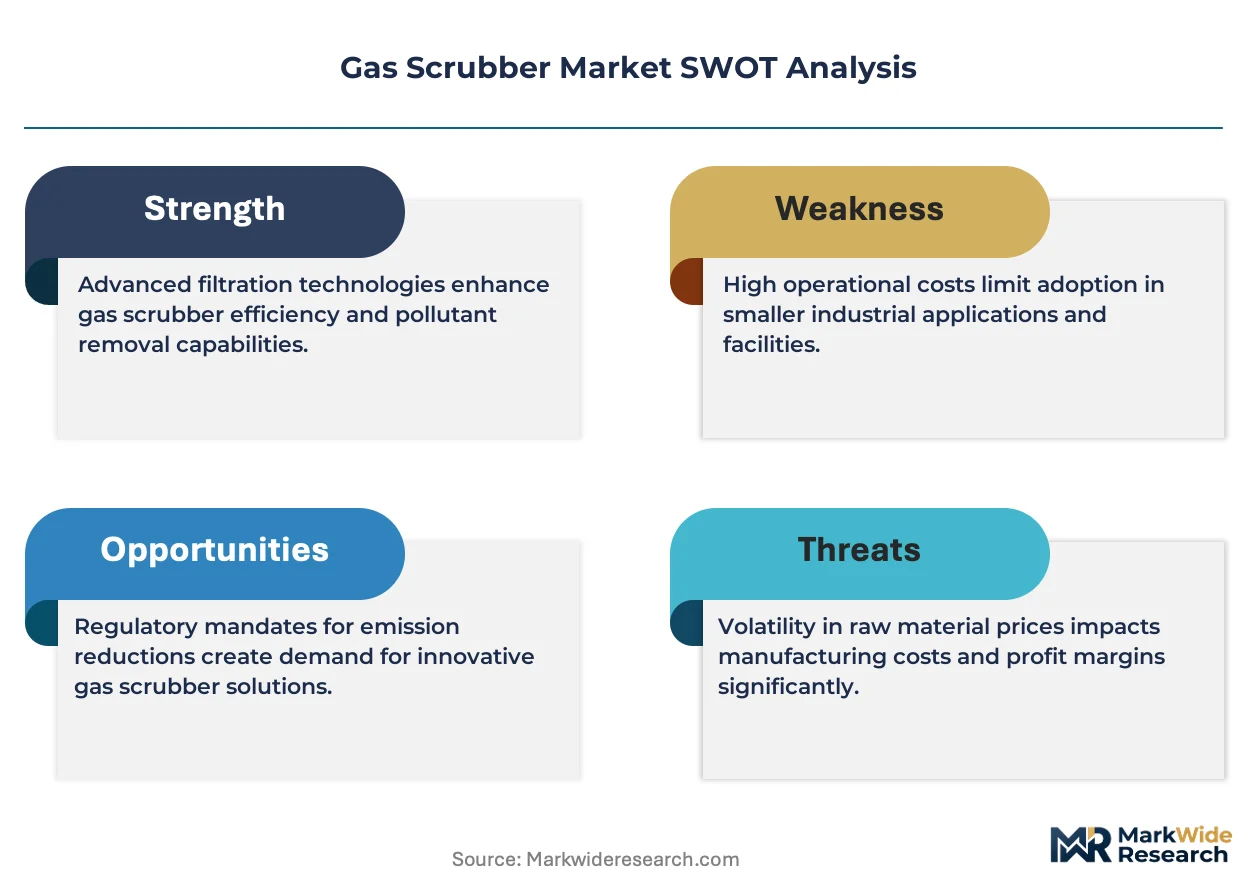
Demand bifurcation between large-scale industrial applications and specialized, smaller-footprint end-uses is the central force shaping the market. This divergence drives distinct technology roadmaps for high-capacity systems versus modular, application-specific filtration solutions for sectors like pharmaceuticals and food processing.
Growth Catalysts
- Stringent Emission Mandates:China's Ministry of Ecology and Environment (MEE) continues to tighten limits on sulfur dioxide and nitrogen oxides, compelling installations across heavy industries like steel and cement manufacturing.
- Industrial Expansion:Rapid development of manufacturing facilities in industrial corridors across India and Southeast Asia necessitates the integration of modern air pollution controls to meet environmental standards from inception.
- Process Optimization:The Oil & Gas sector requires advanced scrubbers to manage hazardous air pollutants from refining and petrochemical processing, protecting assets and ensuring regulatory compliance.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for high-capacity wet scrubber systems presents a major barrier for smaller operators, particularly in the metals and mining sector.
- Water Consumption of Wet Scrubbers:The substantial water usage and subsequent wastewater treatment needs of wet scrubbers create operational and cost challenges in arid regions or areas with strict water-use regulations.
- Technical Expertise Scarcity:A shortage of skilled technicians capable of maintaining, operating, and optimizing complex scrubber systems can lead to performance degradation and compliance risks for industrial facilities.
Strategic Opportunities
- Modular Systems for Niche Sectors:There is a growing opportunity for standardized, modular scrubbers tailored to the specific emission profiles of the pharmaceutical and food processing industries.
- Advanced Dry Sorbents:Developing and commercializing high-efficiency dry sorbents offers a path to penetrate markets where water scarcity makes traditional wet scrubbers impractical, such as in parts of the Middle East.
- Carbon Capture Integration:Integrating carbon capture functionalities with existing scrubber designs provides a pathway for vendors to serve power generation and cement clients addressing both pollutant and CO2 emissions.
Industry Challenges
- Retrofitting Legacy Facilities:Integrating modern, large-scale scrubber systems into existing industrial plants with space and structural constraints is a significant engineering and cost challenge for asset owners.
- Material Durability and Corrosion:The highly corrosive nature of scrubbing liquids and captured pollutants requires advanced alloys and composites, posing a continuous material science and maintenance challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Scrubber Market |
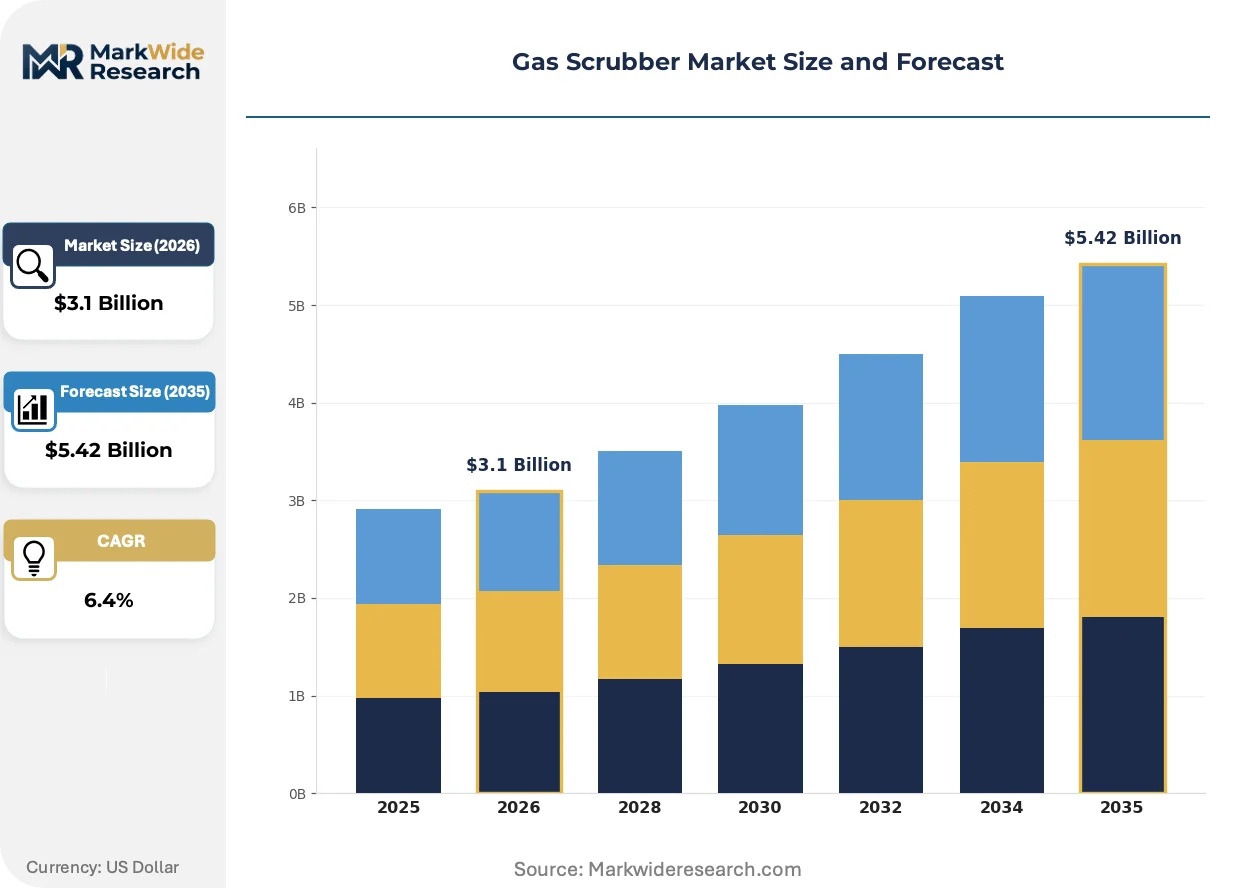
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Scrubbers, Dry Scrubbers, Chemical Scrubbers, Electrostatic Precipitators Application: Industrial Emissions, Power Generation, Waste Management, Chemical Processing Technology: Adsorption, Absorption, Ion Exchange, Filtration End User: Manufacturing, Oil & Gas, Pharmaceuticals, Food & Beverage |
| Companies Covered | Alfa Laval, Ecolab, GEA Group, Mitsubishi Heavy Industries, Wartsila, Babcock & Wilcox Enterprises, Thermax, Parker Hannifin, DuPont de Nemours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Scrubber Market Strategic Shifts & Innovations
A fundamental shift towards application-specific performance and resource efficiency is defining the next generation of gas scrubber technology. This evolution moves beyond simple compliance to focus on total cost of ownership, water conservation, and integration with broader plant processes.
Dry scrubber systems utilizing advanced adsorption media are gaining significant traction for targeted pollutant removal. Industries such as waste-to-energy and cement manufacturing, particularly in water-stressed regions, are adopting this technology at an accelerating rate. This trend is displacing the market dominance of traditional wet scrubbers in applications where water consumption and wastewater treatment are prohibitive cost factors.
The European Union's Industrial Emissions Directive (IED) mandates the use of Best Available Techniques (BAT) for pollution control across member states. This regulatory framework forces operators of chemical plants and power generation facilities to continuously evaluate and upgrade their abatement systems to meet evolving standards. Consequently, the replacement market for older, less efficient scrubbers is particularly active within the EU.
Client purchasing behavior is moving beyond one-time capital equipment sales towards long-term service agreements that guarantee emissions compliance. This model, where vendors take responsibility for maintenance, media replacement, and performance monitoring, is disrupting traditional equipment-only sales channels. The shift is most prominent in the waste incineration and marine sectors, where uptime and guaranteed regulatory adherence are paramount.
Gas Scrubber Market Segmentation
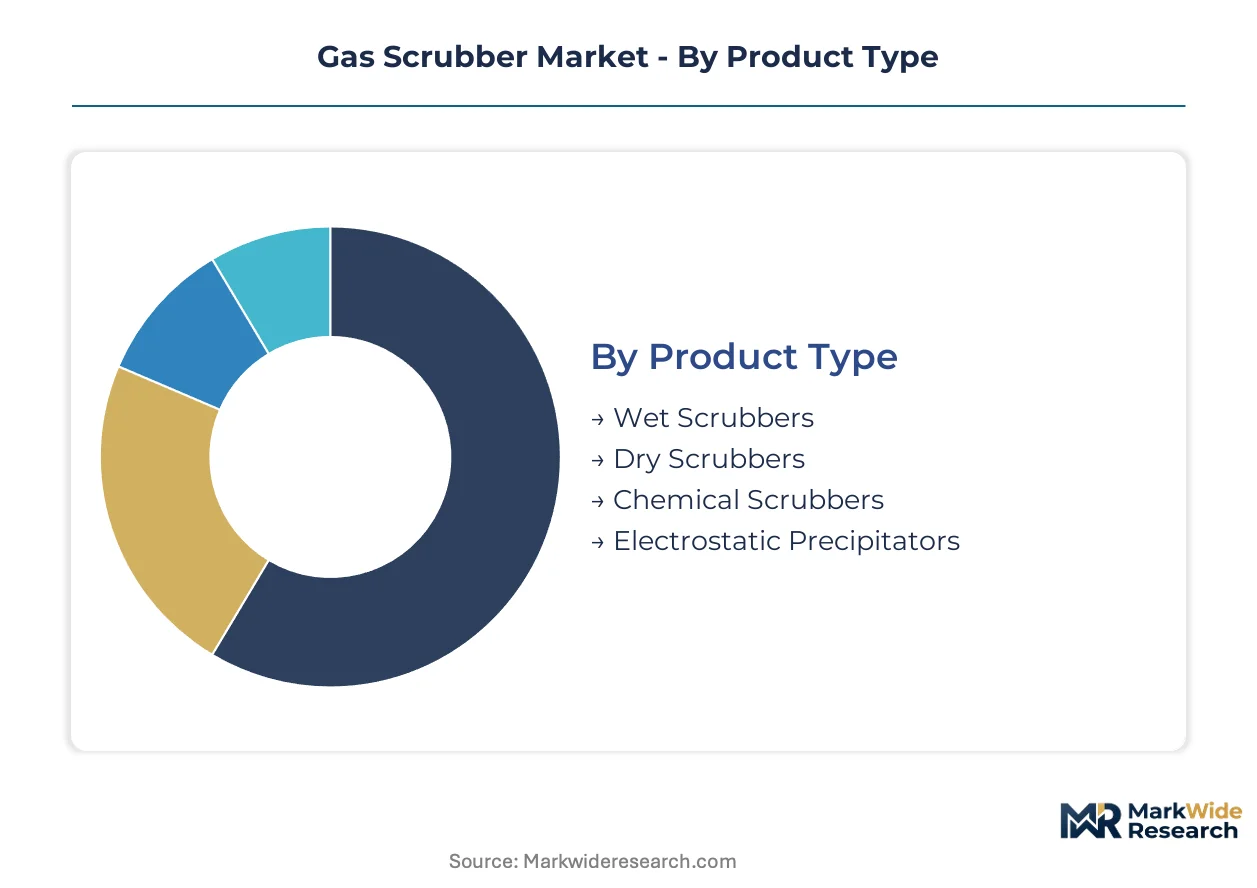
The gas scrubber market's segmentation provides a granular view of how diverse technologies and applications converge to meet evolving air quality standards. Analyzing these distinct segments reveals specific growth pockets and technological preferences, guiding strategic investments for vendors and end-users alike.
Product Type:
The market's product type segmentation highlights how different scrubber designs are distributed across industrial applications, influencing procurement channels and engineering specifications.
- Wet Scrubbers:These systems remove pollutants by bringing exhaust gases into contact with a scrubbing liquid, dissolving or absorbing contaminants like sulfur dioxide and particulate matter. Demand for wet scrubbers concentrates in chemical processing and large-scale power generation facilities, driven by their high efficiency in removing soluble gases.
- Dry Scrubbers:Dry scrubbers utilize solid sorbents or powdered reagents injected into the gas stream to neutralize pollutants, forming a dry byproduct. Demand for dry scrubbers is concentrating in waste-to-energy and cement manufacturing, particularly in water-stressed regions where water conservation is critical.
- Chemical Scrubbers:These units employ chemical reactions with specialized reagents to neutralize specific gaseous pollutants, often targeting highly toxic or corrosive compounds. Chemical scrubbers find application in semiconductor manufacturing and pharmaceutical production for precise emission control.
- Electrostatic Precipitators:Electrostatic precipitators remove fine particulate matter from gas streams using an electrostatic charge to collect particles on charged plates. They are widely used in power plants and metal processing industries for particulate control.
By volume, Wet Scrubbers lead the product type category. By growth pace, Dry Scrubbers are gaining share fastest.
Application:
Analyzing gas scrubber applications reveals distinct operational requirements and emission profiles, directly impacting technology selection and system sizing across diverse industrial settings.
- Industrial Emissions:This broad category encompasses pollution control across various manufacturing and heavy industrial processes, including steel, glass, and textiles, managing a wide spectrum of hazardous air pollutants. Demand for industrial emission scrubbers is concentrating in rapidly industrializing corridors across India and China, driven by stringent MEE mandates.
- Chemical Processing:Gas scrubbers in chemical processing specifically target acid gases, volatile organic compounds, and corrosive fumes generated during synthesis, refining, and manufacturing operations. Demand for these systems is strong in petrochemical complexes and specialty chemical plants, ensuring compliance with NESHAP and IED regulations.
- Power Generation:Scrubbers for power generation facilities primarily focus on reducing sulfur dioxide and nitrogen oxide emissions from coal and gas-fired plants. These systems are critical for meeting regional air quality standards and carbon reduction targets.
- Waste Management:Applications in waste management involve treating exhaust gases from incinerators, landfills, and waste-to-energy facilities to remove dioxins, furans, and other harmful byproducts. Waste management applications are expanding most quickly.
Industrial Emissions applications account for the largest share in this segment. Waste Management applications are climbing the fastest.
Technology:
The technology segmentation reflects varying client needs for pollutant removal efficiency and operational flexibility, influencing procurement decisions for specialized and general-purpose systems.
- Adsorption:Adsorption technologies use porous solid materials, such as activated carbon or zeolites, to capture gaseous pollutants on their surface. This technology is critical for targeted volatile organic compound removal and dry scrubber systems in water-scarce regions.
- Absorption:Absorption involves dissolving gaseous pollutants into a liquid solvent, typically water or a chemical solution, within a contactor vessel. This technology is foundational for wet scrubbers, particularly in high-volume industrial and chemical processing applications.
- Ion Exchange:Ion exchange technology employs resin beads to selectively remove specific ionic contaminants from gas streams through a reversible chemical process. Ion exchange is utilized in niche applications requiring ultra-high purity gas or specific heavy metal removal.
- Filtration:Filtration technologies physically remove particulate matter from gas streams using fibrous or porous media, preventing the release of solid aerosols. Filtration is a common component in multi-stage air pollution control systems, particularly for fine dust control.
Absorption technology maintains a dominant position within the market. Adsorption technology exhibits the steepest expansion trajectory.
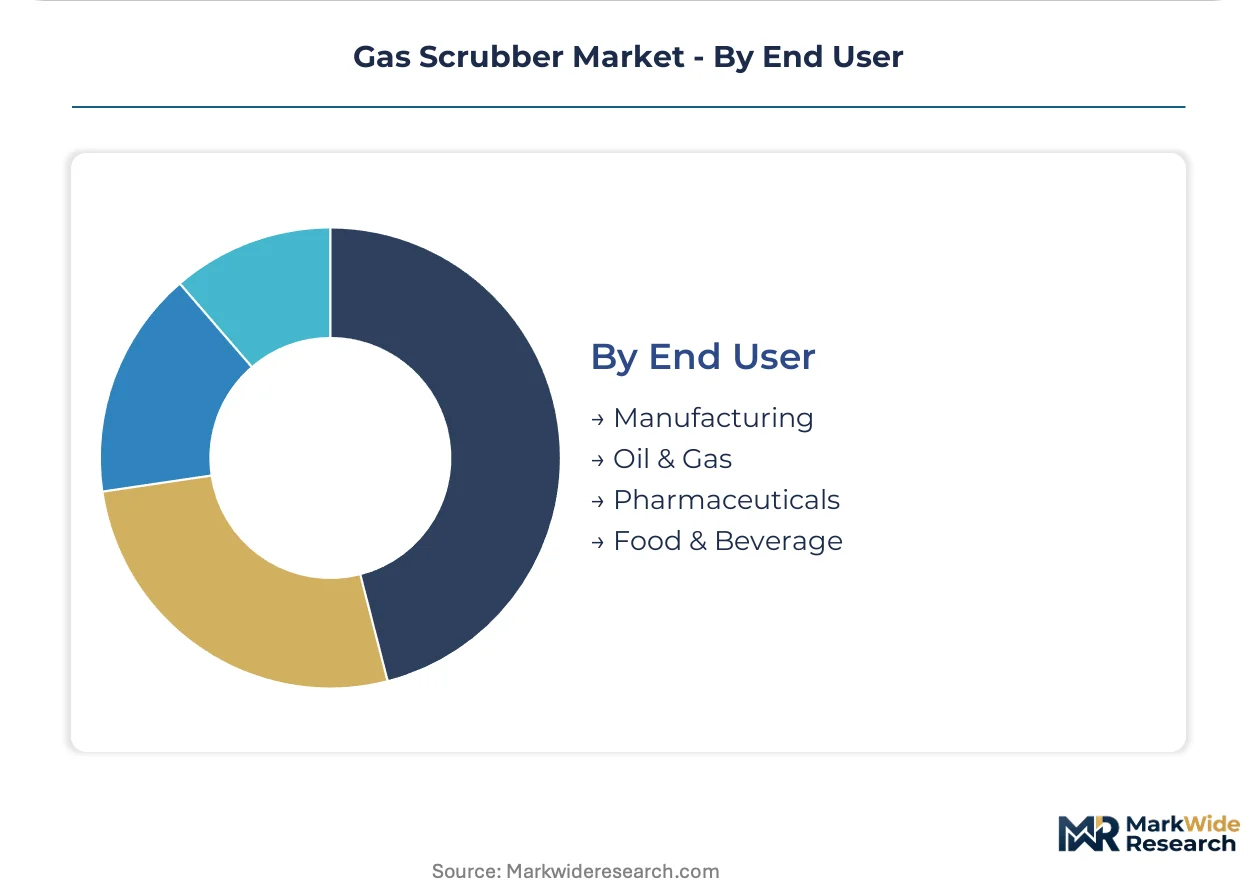
End User:
End-user categories highlight the maturity of pollution control adoption across industries, from established heavy industrial players to emerging specialized sectors requiring tailored solutions.
- Manufacturing:The manufacturing sector broadly utilizes gas scrubbers to control emissions from diverse processes like metal fabrication, electronics production, and general industrial operations. Demand in manufacturing is driven by regional environmental agencies like the US EPA and China's MEE.
- Oil & Gas:The Oil & Gas sector deploys scrubbers to manage hazardous air pollutants, acid gases, and particulate matter from upstream, midstream, and downstream operations, including refineries and petrochemical plants. Oil & Gas facilities require advanced scrubbers for regulatory compliance and asset protection.
- Pharmaceuticals:Pharmaceutical companies employ specialized scrubbers to control solvent emissions, odors, and fine particulate matter from drug manufacturing processes, ensuring product purity and worker safety. These applications often require modular, high-efficiency systems.
- Food & Beverage:The Food & Beverage sector uses scrubbers to eliminate odors, control steam plumes, and remove particulate matter from cooking, drying, and fermentation processes. GEA Group leverages its expertise for integrated solutions in this sector.
Manufacturing end-users represent a foundational demand base for gas scrubbers. Pharmaceuticals and Food & Beverage are gaining momentum most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global gas scrubber market's regional dynamics are shaped by critical industrial infrastructure. Extensive port networks facilitate material import and export, driving demand for pollution control in manufacturing and processing hubs. This infrastructure underpins industrial expansion and regulatory enforcement.
United States
Demand for gas scrubbers in the United States stems from robust industrial activity across the Gulf Coast region. The US EPA's National Emission Standards for Hazardous Air Pollutants (NESHAP) compel chemical processing and refining facilities to install advanced abatement systems. Major petrochemical complexes in Houston and Baton Rouge are upgrading existing scrubbers to meet stringent air quality mandates.
China
Stringent environmental policies in China are a primary driver for gas scrubber installations within heavy industries. The Ministry of Ecology and Environment (MEE) enforces strict limits on sulfur dioxide and nitrogen oxide emissions. Manufacturing hubs in the Yangtze River Delta rapidly adopt modern pollution controls for new and existing facilities.
Germany
European industrial powerhouses like Germany require sophisticated gas scrubbers for their advanced manufacturing and chemical sectors. The EU's Industrial Emissions Directive (IED) mandates Best Available Techniques (BAT) for pollution control across member states. Chemical clusters along the Rhine-Ruhr region invest in high-efficiency systems to comply with evolving environmental standards.
India
Rapid industrialization across India's manufacturing corridors fuels the adoption of gas scrubber technologies. The country's environmental protection agencies are tightening emission norms for new and expanding industrial facilities. Major industrial zones in Gujarat and Maharashtra integrate modern air pollution controls from inception.
Japan
Demand in Japan for gas scrubbers is driven by both advanced manufacturing processes and environmental stewardship. The country's environmental regulations emphasize continuous improvement in air quality from industrial operations. Key industrial areas in the Kanto region deploy specialized scrubbers for semiconductor and precision chemical production.
Gas Scrubber Market Key Industry Players
Concentration sits with established industrial conglomerates offering high-capacity systems for heavy industry. The market exhibits a tiered structure, with a few large players dominating traditional segments alongside a growing number of specialized providers. Archetypes include general industrial solution providers, niche modular technology specialists, and integrated process engineering firms. Strategic partnerships and technology licensing are common competitive moves for expanding product portfolios and geographic reach.
Companies like Mitsubishi Heavy Industries, a Japanese industrial giant, exemplify leadership in high-capacity systems for power plants and chemical processing facilities. Parker Hannifin, a US-based corporation, occupies a position in modular filtration technologies suited for smaller operational footprints across various sectors. GEA Group AG, a German-headquartered company, represents process engineering expertise, particularly serving the food and beverage sector with integrated solutions. These firms anchor distinct segments of the gas scrubber market, from large-scale infrastructure to specialized industrial applications.
| Leading Market Players |
|---|
| Alfa Laval |
| Ecolab |
| GEA Group |
| Mitsubishi Heavy Industries |
| Wartsila |
| Babcock & Wilcox Enterprises |
| Thermax |
| Parker Hannifin |
| DuPont de Nemours |
| Others |
Cost & Logistics Intelligence
Average inventory holding periods for critical scrubber components, often exceeding 90 days, reflect complex supply chain logistics and contribute to stable, albeit higher, pricing structures across the market.
Pricing Analysis
Volume-based tiered pricing structures characterize the gas scrubber market, especially for large industrial clients requiring high-capacity systems. Price differentiation stems from customization levels for specific pollutant removal efficiencies and the inclusion of comprehensive after-sales service agreements. Pricing pressure stems from the increasing availability of modular, standardized solutions, particularly affecting the mid-tier segment. Pharmaceutical and food processing end-users exhibit lower price sensitivity due to stringent compliance requirements, while smaller manufacturing operators are more price-conscious.
Supply Chain Analysis
Extended lead times for custom-engineered scrubber units, often reaching 6-9 months, highlight global manufacturing dependencies and logistical challenges. Geographic supply concentration for core components centers on China for basic fabrication, Germany for advanced control systems, and Japan for specialized materials. Raw material dependencies include corrosion-resistant alloys, advanced sorbent media, and specialized chemical reagents. Commodity price volatility for these materials presents a structural supply chain risk. Distribution runs primarily through direct sales channels for large projects and specialized engineering, procurement, and construction (EPC) contractors for integrated solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gas scrubber market is experiencing high-growth disruption, driven by increasingly stringent global environmental regulations like the EU's Industrial Emissions Directive.
For Market Incumbents:
Consolidate market share through strategic acquisitions of niche technology providers specializing in advanced dry sorbents. This move addresses the growing threat from water-efficient solutions and expands product portfolios. Invest in regional manufacturing hubs in India and Southeast Asia to mitigate logistics risks and capitalize on industrial expansion. Develop long-term service agreements that guarantee emissions compliance, shifting from transactional sales to recurring revenue models.
For New Entrants and Emerging Players:
Differentiate on application-specific performance and resource efficiency, targeting the rapidly expanding pharmaceutical and food processing sectors. These industries present white-space opportunities for modular, smaller-footprint systems with precise emission control. Focus on developing integrated solutions that combine scrubber technology with process optimization for a compelling value proposition. A go-to-market angle emphasizing rapid deployment and lower total cost of ownership will resonate with specialized end-users.
For Investors and Strategic Acquirers:
Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core environmental technology divisions, offering established product lines and client bases. Acquisition targets should possess strong intellectual property in advanced adsorption technologies or specialized chemical scrubbing for high-value applications. The market demonstrates long-term viability over the next 5-10 years, driven by continuous regulatory tightening. The signal to watch is the increasing investment in carbon capture integration capabilities by incumbent players.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Advanced Dry Sorbents | Addresses water scarcity concerns and expands market reach into arid regions. |
| Expand Modular System Offerings | Captures demand from specialized end-users in pharmaceuticals and food processing. |
| Integrate Carbon Capture Functionalities | Serves power generation and cement clients addressing both pollutant and CO2 emissions. |
| Establish Regional Manufacturing Hubs | Mitigates supply chain risks and supports rapid industrialization in emerging markets. |
| Offer Long-term Compliance Service Agreements | Shifts revenue models and strengthens client relationships through guaranteed performance. |
Research Approach
Cross-validation between primary interviews with plant managers and secondary data from EPA reports anchors the qualitative findings of this analysis. Industry stakeholders interviewed included environmental compliance officers, procurement leads at chemical processing facilities, and technical directors of scrubber manufacturers. Secondary sources comprised government environmental agency mandates, industry association publications, and company financial filings. The study employed both bottom-up and top-down triangulation to ensure data consistency.
Sensitivity analysis across the modeling period reveals the impact of varying industrial output growth rates and regulatory enforcement levels on market trajectory. The analytical framework modeled segmentation dimensions including product type, application, technology, end-user, and regional regulatory environments. Compound annual growth rates were derived from historical data trends and projected future demand scenarios. Key forecast inputs included projected industrial capital expenditure and anticipated updates to national air quality standards.
Material uncertainties — geopolitical shifts and unforeseen technological breakthroughs — sit outside the modeled envelope of this study. Forecasts reflect assumptions regarding stable regulatory environments and consistent industrial development. Unforeseen raw material supply disruptions or significant shifts in energy policy could revise future projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Engineering
Silt Curtain Market
Environmental Engineering
Rainwater Harvesting Market
Environmental Engineering
Aerobic Treatment Units Market
Environmental Engineering
Wet Scrubber Market
Environmental Engineering
North America Rainwater Harvesting Market
Environmental Engineering
Fume Hoods Market
Environmental Engineering
Global Rainwater Harvesting System Market
Environmental Engineering
Outdoor Noise Barrier Market
Environmental Engineering
Septic Tanks Market
Environmental Engineering
Outdoor Sound Barrier Market
Environmental Engineering
Dust Control Systems Market
Environmental Engineering
Secondary Water and Wastewater Treatment Equipment Market
Environmental Engineering
Global Built and Natural Environment Consulting Market
Environmental Engineering
Tunnel Ventilation and Environmental Monitoring Systems Market