
 Outdoor Noise Barrier Market | 2026-2036
Outdoor Noise Barrier Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Noise Barrier Market Outlook
Aftermarket service revenue is fragmenting as manufacturers compete on installation support and acoustic performance warranties. Saint-Gobain leverages its building materials portfolio to offer integrated noise barrier systems with adjacent envelope solutions. Kinetics Noise Control anchors its position through specialized vibration-isolation expertise that extends into barrier foundation engineering. Sound Seal differentiates via custom-fabricated acoustic panels serving industrial and transportation verticals.
Outdoor noise barriers are engineered structures, typically 3 to 8 meters in height, constructed from concrete, steel, wood, or polyethylene composites to attenuate sound transmission from highways, railways, and industrial sources to sensitive receptors. These systems incorporate absorptive facing materials, perforated metal skins, or porous concrete mixes to achieve noise reduction coefficients exceeding 0.70 across critical octave bands. Concrete dominates material selection for permanent highway installations due to durability and fire resistance, while polyethylene gains traction in temporary construction and event-based deployments where rapid deployment and reuse drive procurement economics. The end-user landscape tilts toward highways and railways as governments fund corridor expansion, yet residential area applications accelerate fastest where community opposition to noise pollution intensifies planning approvals.
The Federal Highway Administration (FHWA) and state departments of transportation enforce noise abatement criteria under 23 CFR 772, compelling project sponsors to evaluate barrier feasibility when traffic noise approaches 67 decibels. Europe's Environmental Noise Directive (2002/49/EC) obliges member states to produce strategic noise maps and action plans, directly stimulating barrier procurement in France, Germany, and Italy. ISO 140 series standards for environmental noise measurement provide cross-border testing protocols that facilitate product certification. Stakeholders must monitor evolving lifecycle assessment requirements that increasingly embed embodied carbon thresholds into public infrastructure tender specifications.
Market Dynamics
Highway modernization mandates across Germany, France, and the United States are compressing procurement timelines while elevating acoustic performance thresholds, forcing material suppliers to certify systems against ISO 140 testing protocols before tender eligibility.
Growth Catalysts
- FHWA 23 CFR 772 enforcement:Federal and state transportation departments must evaluate barrier feasibility when traffic noise approaches 67 decibels, creating mandatory demand triggers for highway expansion projects.
- Germany's BImSchG amendments:Stricter immission limits near transport corridors mandate absorptive barrier installation, compelling corridor upgrades in Bavaria and North Rhine-Westphalia.
- Polyethylene composite maturation:Rapid-deployment temporary barriers now achieve noise reduction coefficients above 0.65, opening event-based and construction-phase applications.
Market Restraints
- Steel and cement input volatility:Permanent concrete barrier production faces margin pressure from construction-grade steel rebar and Portland cement price swings.
- Acoustic certification backlog:ISO 140-4 testing queue delays at accredited European laboratories extend product validation cycles by four to eight months.
- Earthen berm substitution:Landscape-integrated noise mitigation using soil and vegetation competes for residential-adjacent contracts where aesthetic concealment matters.
Strategic Opportunities
- India corridor densification:National highway expansion between Mumbai and Delhi lacks legacy barrier infrastructure, creating first-mover positioning for absorptive system suppliers.
- EU Green Deal embodied carbon thresholds:Tender specifications in France and Italy now weight lifecycle carbon in scoring, favoring recycled-content polyethylene and low-carbon concrete mixes.
- Rail electrification synergies:Overhead catenary installation projects in Spain and Italy bundle noise barrier procurement, creating integrated contract vehicles.
Industry Challenges
- Acoustic engineering talent scarcity:Barrier foundation design requires vibration-isolation expertise that overlaps with structural and geotechnical disciplines, narrowing qualified candidate pools.
- Legacy highway retrofit integration:Existing post-and-panel concrete installations resist modification for absorptive facing attachment without full reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Noise Barrier Market |
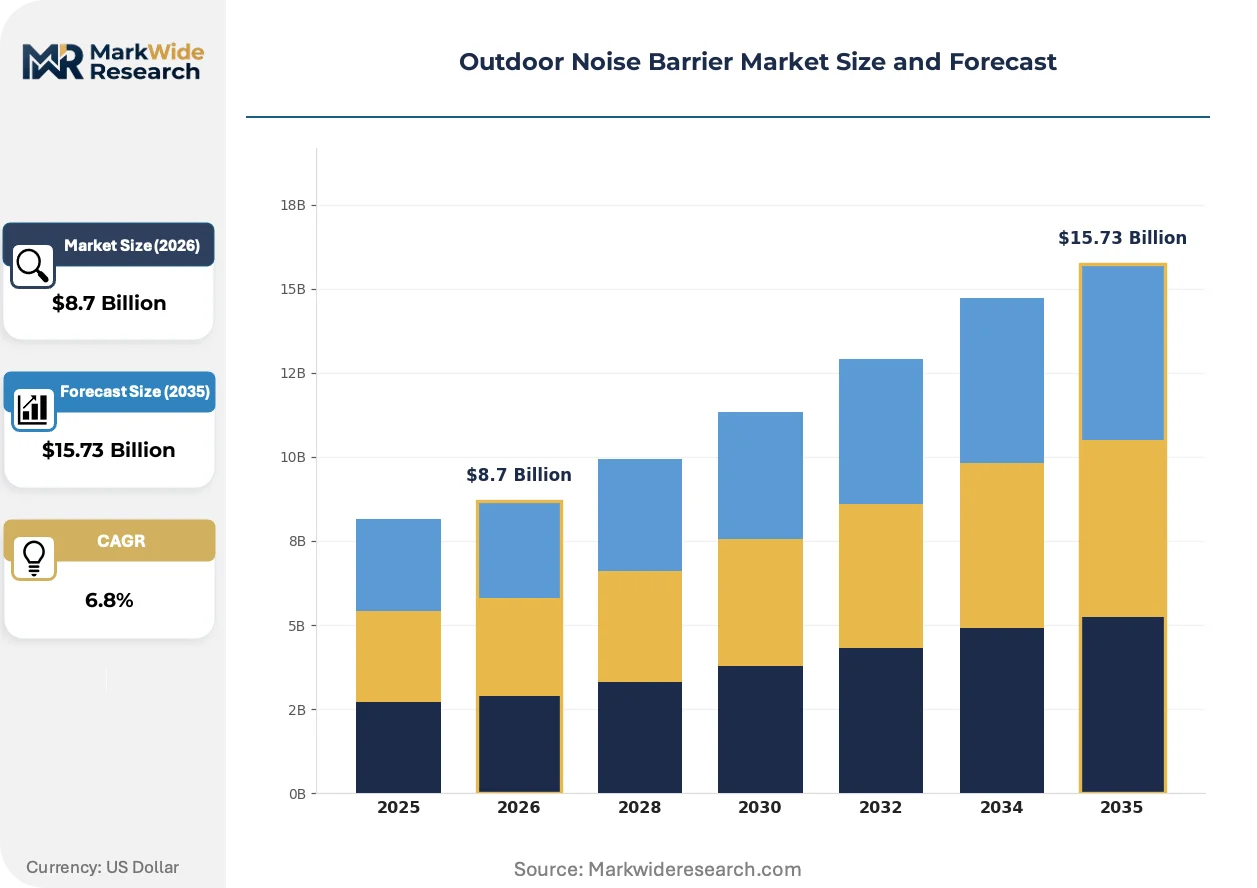
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Concrete, Wood, Steel, Polyethylene Installation Type: Permanent, Temporary, Portable, Fixed End User: Highways, Railways, Industrial Zones, Residential Areas Design Type: Aesthetic, Functional, Acoustic, Environmental |
| Companies Covered | Faddis Concrete Products, Kinetics Noise Control, Sound Seal, Saint-Gobain, Valmont Industries, IAC Acoustics, Sound Fighter Systems, Echo Barrier USA, Noise Barriers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Noise Barrier Market Strategic Shifts
Material science advances and procurement digitization are compressing traditional specification cycles. Suppliers now compete on installation velocity and carbon disclosure rather than unit cost alone.
Micro-perforated aluminum facing bonded to mineral wool cores is rendering obsolete solid reflective concrete panels in high-end highway segments. German state DOTs specify these systems for autobahn residential interfaces. The shift compresses supplier margins on legacy precast lines while rewarding acoustic-performance warranties.
Europe's Environmental Noise Directive mandates strategic noise mapping and action plans, compelling member states to quantify barrier needs before funding allocation. France's ANSES now requires health-impact assessments linking noise exposure to cardiovascular outcomes. Municipal planners in Lyon and Marseille prioritize absorptive systems to meet dual acoustic and air-quality targets.
Buyers increasingly unbundle installation from material supply, contracting directly with regional civil contractors rather than turnkey barrier vendors. State DOTs in Texas and California now separate acoustic-panel procurement from foundation and erection scopes. This fragmentation compresses manufacturer margins while elevating aftermarket service contracts for performance verification.
Outdoor Noise Barrier Market Segmentation
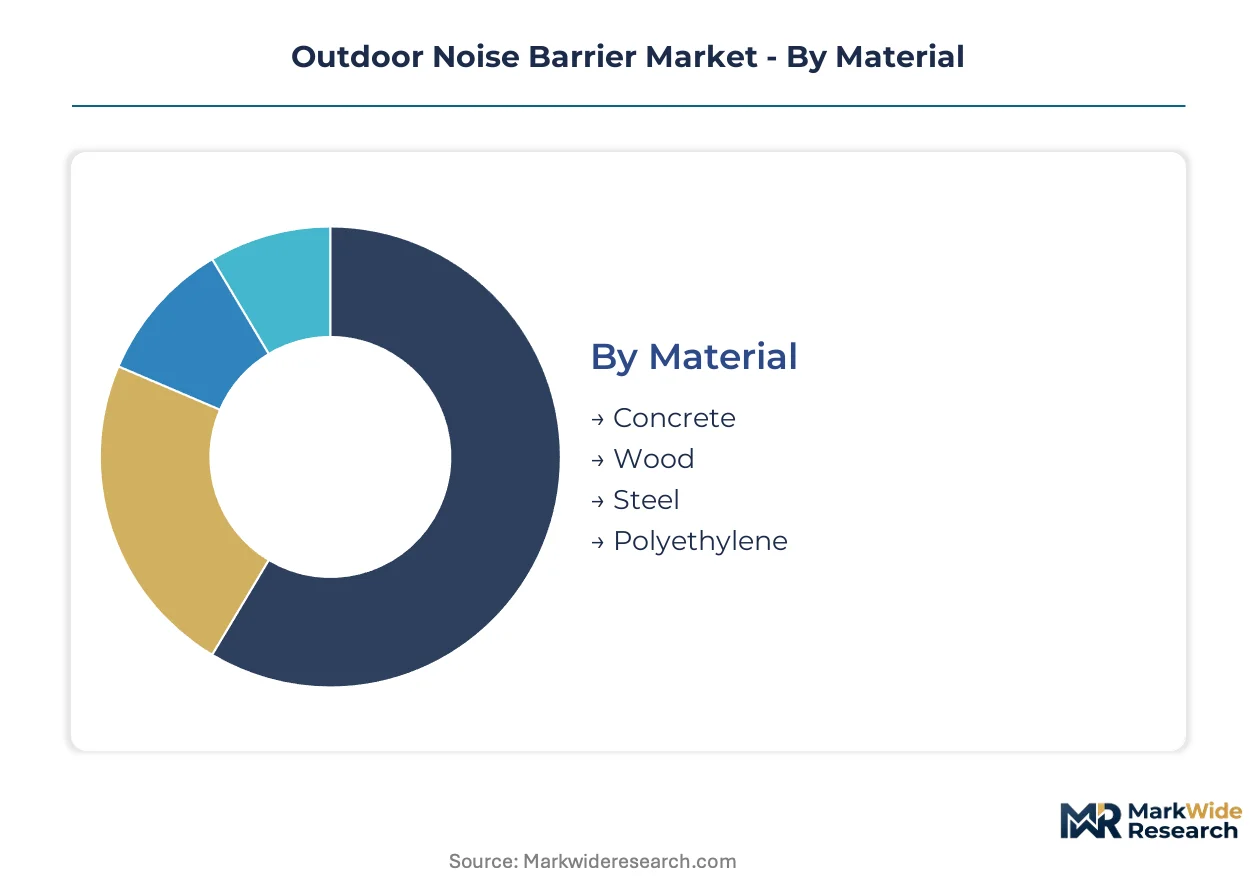
Material selection dictates lifecycle economics and acoustic performance ceilings, while installation type determines procurement velocity and reuse potential. End-user concentration shapes regulatory compliance requirements, and design orientation reflects tradeoffs between community acceptance and engineering efficiency.
Material:
Mature concrete formulations dominate permanent infrastructure, while emerging polyethylene composites capture temporary deployment economics.
- Concrete:Precast reinforced panels with Portland cement binders achieve noise reduction coefficients above 0.70 through porous aggregate mixes. German autobahn projects and US state DOT specifications favor concrete for fire resistance and 50-year service life expectations under FHWA 23 CFR 772 mandates.
- Polyethylene:Recycled-content composite barriers deliver rapid-deployment flexibility with modular connection systems. France and Italy now weight lifecycle carbon thresholds in tender scoring, accelerating polyethylene specification for construction-phase and event-based applications.
- Wood:Timber barriers with pressure-treated lumber or glulam construction serve residential-adjacent corridors where aesthetic integration matters.
- Steel:Corrugated metal panels with absorptive facing layers span curved alignments and retrofit existing post structures.
Concrete retains volume leadership; polyethylene holds the steepest expansion curve.
Installation Type:
Cost tier separation runs from capital-intensive permanent foundations to rental-model portable systems.
- Permanent:Cast-in-place or driven-pile foundations with embedded panel anchoring systems define highway corridor standards. Bavaria and North Rhine-Westphalia mandate permanent absorptive barriers under BImSchG amendments near residential zones.
- Temporary:Ballasted or anchored modular systems deploy without geotechnical excavation. Texas and California DOTs now separate temporary barrier procurement from civil scopes, fragmenting vendor margins while elevating regional contractor relationships.
- Portable:Trailer-mounted or forklift-deployable units serve construction-phase noise management with weekly rental economics.
- Fixed:Surface-mounted systems on existing retaining walls or bridge parapets minimize foundation costs for retrofit applications.
Permanent installations anchor revenue concentration; temporary systems gain share fastest in urban construction corridors.
End User:
Application concentration tilts toward transport infrastructure, with residential proximity driving specification intensity.
- Highways:Federal and state transportation departments represent the core procurement channel, with noise abatement criteria triggering mandatory barrier evaluation at 67 decibels. US state DOTs and European national road agencies compress procurement timelines through design-build contracts.
- Railways:Overhead catenary electrification projects in Spain and Italy bundle noise barrier procurement with traction power installation, creating integrated contract vehicles.
- Industrial Zones:Manufacturing facilities and logistics hubs deploy barriers to meet occupational noise limits and community relations targets.
- Residential Areas:Municipal planners in Lyon and Marseille prioritize absorptive systems to meet dual acoustic and air-quality targets, with health-impact assessments now required under French ANSES protocols.
Highways dominate absolute volume; residential applications climb fastest where community opposition intensifies planning approvals.
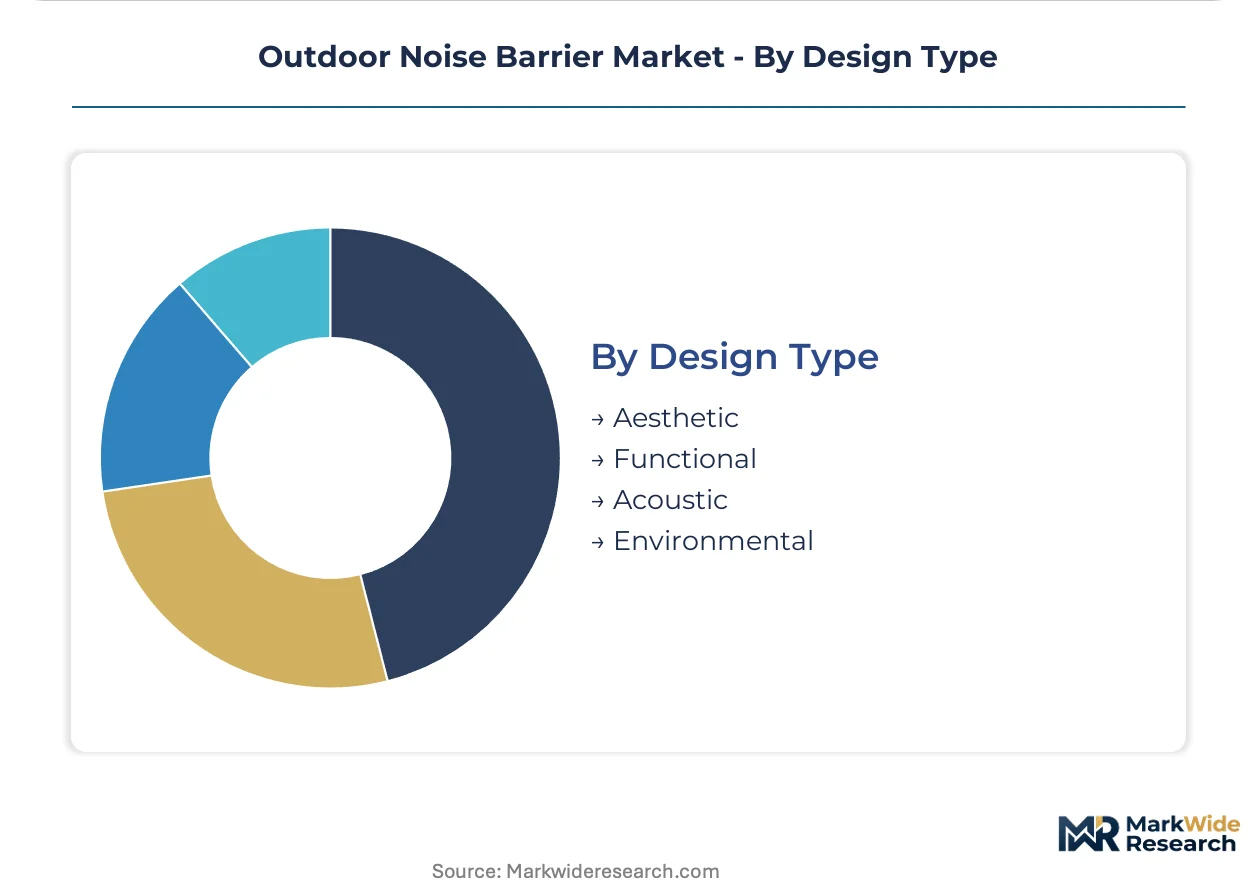
Design Type:
Margin structure separates commodity functional barriers from premium aesthetic and environmental specifications.
- Functional:Standardized reflective or absorptive panels optimized for noise reduction coefficient performance dominate procurement volume. ISO 140-4 testing protocols certify acoustic performance for tender eligibility.
- Acoustic:Micro-perforated aluminum facing bonded to mineral wool cores achieves superior broadband attenuation. German state DOTs specify these systems for autobahn residential interfaces, compressing margins on legacy precast lines.
- Aesthetic:Custom finishes, color matching, and architectural profiling serve sensitive visual corridors where community acceptance determines project approval.
- Environmental:Living walls, solar-integrated facings, and air-quality co-benefit designs respond to EU Green Deal embodied carbon thresholds and municipal sustainability targets.
Functional designs retain procurement volume dominance; environmental configurations expand most quickly under carbon-integrated tender scoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barrier procurement patterns diverge sharply across geographies. Germany and France prioritize permanent absorptive systems under strict immission controls, while the United States fragments procurement between state DOTs and municipal authorities. India and China represent emerging volume centers where first-mover positioning remains unsettled.
United States
FHWA 23 CFR 772 mandates barrier feasibility studies at 67 decibel thresholds, triggering systematic evaluation across highway expansion corridors. Texas and California DOTs now unbundle material supply from installation scopes, elevating regional contractor relationships. The I-35 corridor through Austin and San Antonio exemplifies compressed procurement timelines under federal highway modernization funding.
Germany
BImSchG amendments impose stricter noise limits near transport corridors, compelling absorptive barrier upgrades in dense residential adjacencies. Bavaria and North Rhine-Westphalia lead implementation volume. The A3 autobahn corridor through Frankfurt-Rhine-Main represents concentrated demand for micro-perforated aluminum systems with mineral wool cores.
France
ANSES health-impact assessments now link noise exposure to cardiovascular outcomes, tightening municipal planning approvals. Lyon and Marseille prioritize absorptive barriers meeting dual acoustic and air-quality targets. The A7 corridor through Rhône-Alpes demonstrates integrated procurement bundling noise mitigation with urban air quality improvement programs.
India
National highway expansion between Mumbai and Delhi lacks legacy barrier infrastructure, creating greenfield procurement opportunities. The country's national road transport authority lacks equivalent mandatory noise abatement criteria, leaving adoption to state-level initiative. The Delhi-Mumbai Industrial Corridor represents the most advanced planning integration for corridor-scale noise mitigation.
Italy
Overhead catenary rail electrification projects bundle noise barrier procurement with traction power installation, creating integrated contract vehicles. Spain and Italy jointly demonstrate this procurement pattern across Mediterranean corridor upgrades. The Milan-Genoa rail axis shows concentrated activity where electrification and noise mitigation proceed in parallel construction phases.
Outdoor Noise Barrier Market Competitive Environment
Capability concentration sits with specialized acoustic engineering firms; scale advantage sits with diversified building materials conglomerates. The vendor base separates into three functional tiers: integrated materials suppliers with adjacent envelope portfolios, vibration-isolation specialists extending into foundation engineering, and custom fabricators serving project-specific acoustic requirements. Dominant competitive moves include geographic expansion through regional distributor networks and portfolio diversification into temporary deployment systems.
Within the integrated materials tier, Saint-Gobain exemplifies diversification strategy through building materials portfolio leverage. Kinetics Noise Control and Sound Seal occupy distinct specialization positions—Kinetics anchors vibration-isolation expertise extending into barrier foundation engineering, while Sound Seal represents custom-fabricated acoustic panel capability serving industrial and transportation verticals. These three companies illustrate the structural segmentation between scale-driven materials integration and technical specialization.
| Leading Market Players |
|---|
| Faddis Concrete Products |
| Kinetics Noise Control |
| Sound Seal |
| Saint-Gobain |
| Valmont Industries |
| IAC Acoustics |
| Sound Fighter Systems |
| Echo Barrier USA |
| Noise Barriers |
| Others |
Value Chain & Pricing Dynamics
Steel rebar and Portland cement price volatility compresses margin structures across permanent barrier tiers while simultaneously forcing procurement officers toward polyethylene alternatives with shorter capital cycles. This input-cost instability widens the spread between concrete and composite pricing, reshaping supplier mix and inventory strategies simultaneously.
Pricing Analysis
Project-based contracting dominates highway and rail procurement, with state DOTs and national road agencies bundling material supply, foundation engineering, and acoustic certification into single tender awards. Price differentiation hinges on ISO 140-4 certification tier and after-sales performance warranty duration, with premium absorptive systems commanding substantial spreads over reflective concrete panels. Cost compression in standard precast lines is intensifying because European laboratories face four-to-eight-month testing backlogs that delay revenue recognition. Municipal authorities in residential-adjacent corridors show highest price sensitivity, while German autobahn projects under BImSchG mandates absorb premium pricing for micro-perforated aluminum systems.
Supply Chain Analysis
Contract manufacturing for acoustic cores concentrates with specialized mineral wool processors in Germany, France, and Belgium, while polyethylene composite extrusion capacity clusters in Italy and Spain. Raw material flows draw from construction-grade steel rebar sourced through European mill networks, Portland cement from regional integrated producers, and recycled polymer feedstocks from post-industrial waste streams. Single-source vulnerability sits with accredited ISO 140-4 testing laboratories in France and Germany, where validation bottlenecks constrain product launch velocity. Distribution runs through regional civil contractor networks rather than turnkey vendor channels, reflecting the unbundling trend in Texas and California procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified acoustic engineering talent scarcity constrains barrier foundation design capabilities, creating defensive moats for incumbents with captive vibration-isolation expertise while elevating acquisition premiums for specialized geotechnical firms.
For Market Incumbents: Insulate core positioning by deepening backward integration into mineral wool core production and securing exclusive partnerships with accredited European testing laboratories. The ISO 140-4 certification backlog threatens to strand competitor products in validation queues, rewarding those with established laboratory relationships. Capacity addition in polyethylene composite extrusion addresses the steepest-expansion material segment while hedging against steel and cement input volatility. For New Entrants and Emerging Players: Build out rapid-deployment temporary barrier offerings targeting construction-phase noise management in urban corridors, where weekly rental economics and deployment velocity outweigh brand recognition. India's Mumbai-Delhi highway expansion lacks legacy infrastructure and mandatory abatement criteria, creating first-mover positioning for absorptive system suppliers willing to educate state-level transport authorities. Direct contracting with regional civil contractors rather than turnkey competition bypasses established vendor relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized acoustic engineering firms with vibration-isolation expertise extending into foundation design. Long-term viability rests on carbon-integrated tender scoring becoming standard across EU member states, embedding lifecycle assessment capabilities into competitive positioning. Acquisition target archetype: mid-cap custom fabricators with ANSES health-impact assessment experience and established relationships with French municipal planners. The signal to watch is BImSchG-style immission limit adoptions outside Germany, particularly in Austria and Switzerland transport corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Wool Production | Captive core supply secures margins against raw material volatility while accelerating product development cycles. |
| ISO 140-4 Testing Laboratory Partnership | Exclusive validation relationships compress time-to-tender eligibility and strand competitor launches. |
| Polyethylene Composite Capacity Expansion | Recycled-content production aligns with EU Green Deal embodied carbon thresholds in French and Italian tenders. |
| Regional Civil Contractor Network Development | Direct installation relationships capture value from unbundled procurement trends in Texas and California DOTs. |
| Acoustic Engineering Talent Acquisition | Vibration-isolation expertise scarcity creates defensive moats in barrier foundation design competitions. |
Study Parameters
Desk research of customs trade databases, SEC 10-K filings from building materials conglomerates, and FHWA highway project award records preceded structured interviews with state DOT procurement officers, acoustic engineering consultants, mineral wool plant managers, and regional civil contractor executives. Primary fieldwork combined with secondary validation through BImSchG regulatory filings, ANSES health-impact assessment protocols, and ISO 140 series documentation. Bottom-up project pipeline enumeration triangulated against top-down infrastructure budget allocations across Germany, France, the United States, and India.
Assumptions regarding FHWA 23 CFR 772 enforcement continuity and BImSchG amendment implementation timelines were held fixed across the analysis window, while polyethylene composite performance maturation and EU Green Deal carbon threshold adoption were modeled as scenario-dependent variables. Segmentation modeling incorporated material type, installation permanence, end-user vertical, and design orientation dimensions. CAGRs were derived from infrastructure budget trajectory analysis and corridor expansion project pipelines. Industry-specific inputs included highway traffic noise projection models and rail electrification bundling patterns in Mediterranean markets.
Practitioners should monitor steel rebar and cement price indices, ISO 140-4 laboratory queue lengths, and BImSchG-equivalent regulatory adoptions for early signals of forecast revision. Quarterly review of state DOT procurement unbundling trends and EU tender scoring weight shifts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Engineering
Fume Hoods Market
Environmental Engineering
Global Rainwater Harvesting System Market
Environmental Engineering
Rainwater Harvesting Market
Environmental Engineering
Outdoor Sound Barrier Market
Environmental Engineering
Gas Scrubber Market
Environmental Engineering
Global Built and Natural Environment Consulting Market
Environmental Engineering
Silt Curtain Market
Environmental Engineering
Secondary Water and Wastewater Treatment Equipment Market
Environmental Engineering
Aerobic Treatment Units Market
Environmental Engineering
Dust Control Systems Market
Environmental Engineering
North America Rainwater Harvesting Market
Environmental Engineering
Wet Scrubber Market
Environmental Engineering
Septic Tanks Market
Environmental Engineering
Tunnel Ventilation and Environmental Monitoring Systems Market