
 Wet Scrubber Market | 2026-2036
Wet Scrubber Market Size, Share, and Industry Trends Forecast 2026-2036
Wet Scrubber Market Intelligence
The substitution of traditional steel with advanced corrosion-resistant alloys and fiberglass-reinforced plastics in scrubber construction is rebalancing equipment lifecycle economics. Babcock & Wilcox Enterprises, Inc. leverages its long-standing expertise in large-scale power generation projects. CECO Environmental Corp. competes by offering a diversified portfolio of air quality and fluid handling solutions. GEA Group AG differentiates through its focus on integrated process engineering for the chemical and food processing industries.
A wet scrubber is an air pollution control device that utilizes a liquid spray to remove contaminants from an exhaust gas stream. The system functions by bringing the gas into contact with a scrubbing liquid, which can absorb gaseous pollutants or capture particulate matter through impaction. Packed bed scrubbers dominate applications requiring high-efficiency gas absorption, such as in chemical manufacturing. In contrast, Venturi scrubbers are preferred in power plants and metal processing for their effectiveness in removing fine particulate matter.
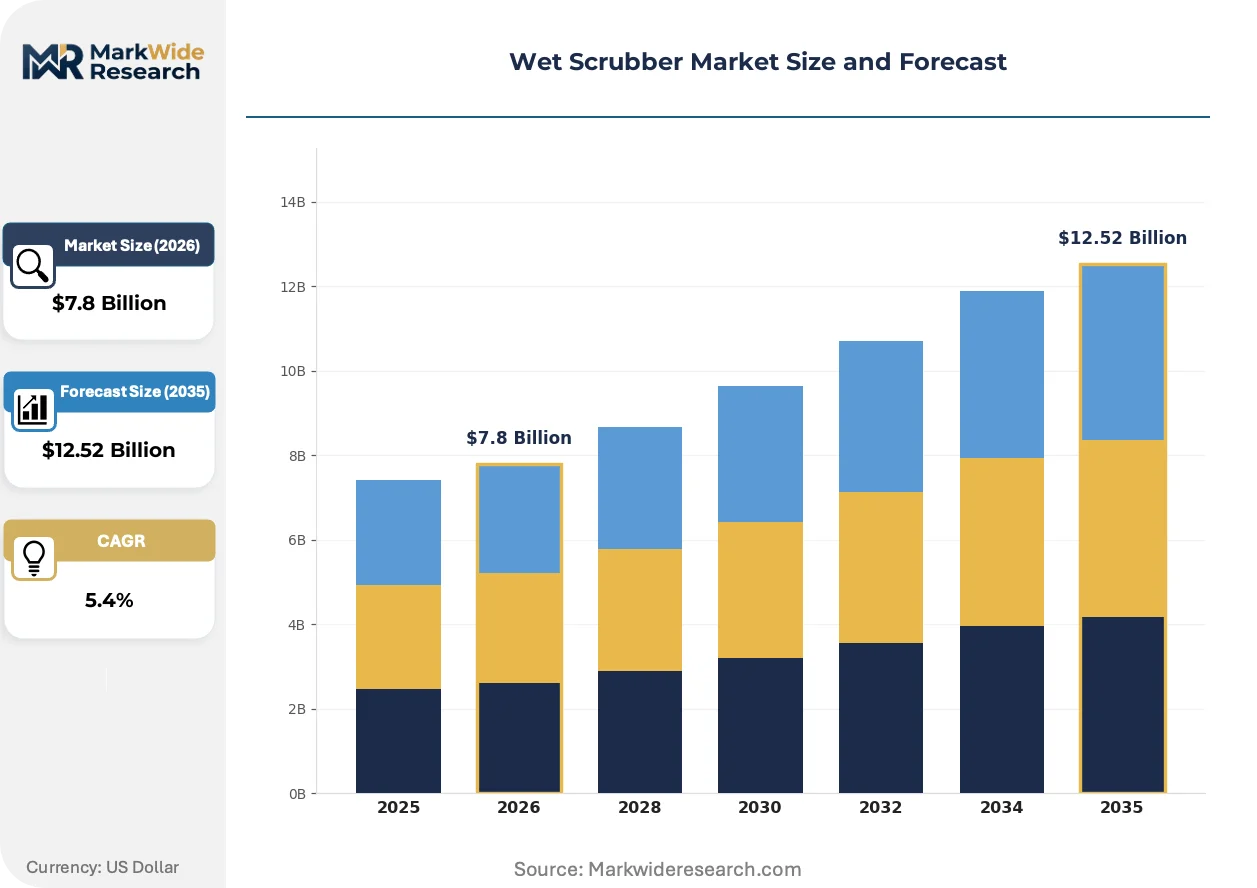
Regulatory frameworks from the US EPA, compliance with the EU's Industrial Emissions Directive, and standards set by China's MEE are primary market accelerators. These regulations enforce stringent emission limits on sulfur oxides (SOx) and particulate matter, mandating the use of effective gas cleaning systems. Future investment decisions for operators will pivot on balancing the initial capital cost of high-efficiency systems against the long-term operational expenses related to water and reagent consumption.
Market Dynamics
The market's fundamental structure is defined by a global regulatory push for cleaner industrial emissions. Mandates from agencies like the US EPA and China's MEE compel operators in heavy industries to install effective flue gas treatment technologies to control pollutants.
Growth Catalysts
- Stringent Regulations:China's dual carbon goals and standards from its MEE are accelerating investment in advanced flue gas desulfurization technologies, particularly within the nation's vast chemical manufacturing and power generation sectors.
- Industrial Expansion:Rapid industrialization in India, especially in its power and metal processing industries, creates sustained demand for systems like Venturi scrubbers to control fine particulate matter emissions from new facilities.
- Technology Specialization:The dominance of packed bed scrubbers for high-efficiency gas absorption applications in the chemical processing industry continues to drive adoption as companies seek to meet specific pollutant removal targets.
Market Restraints
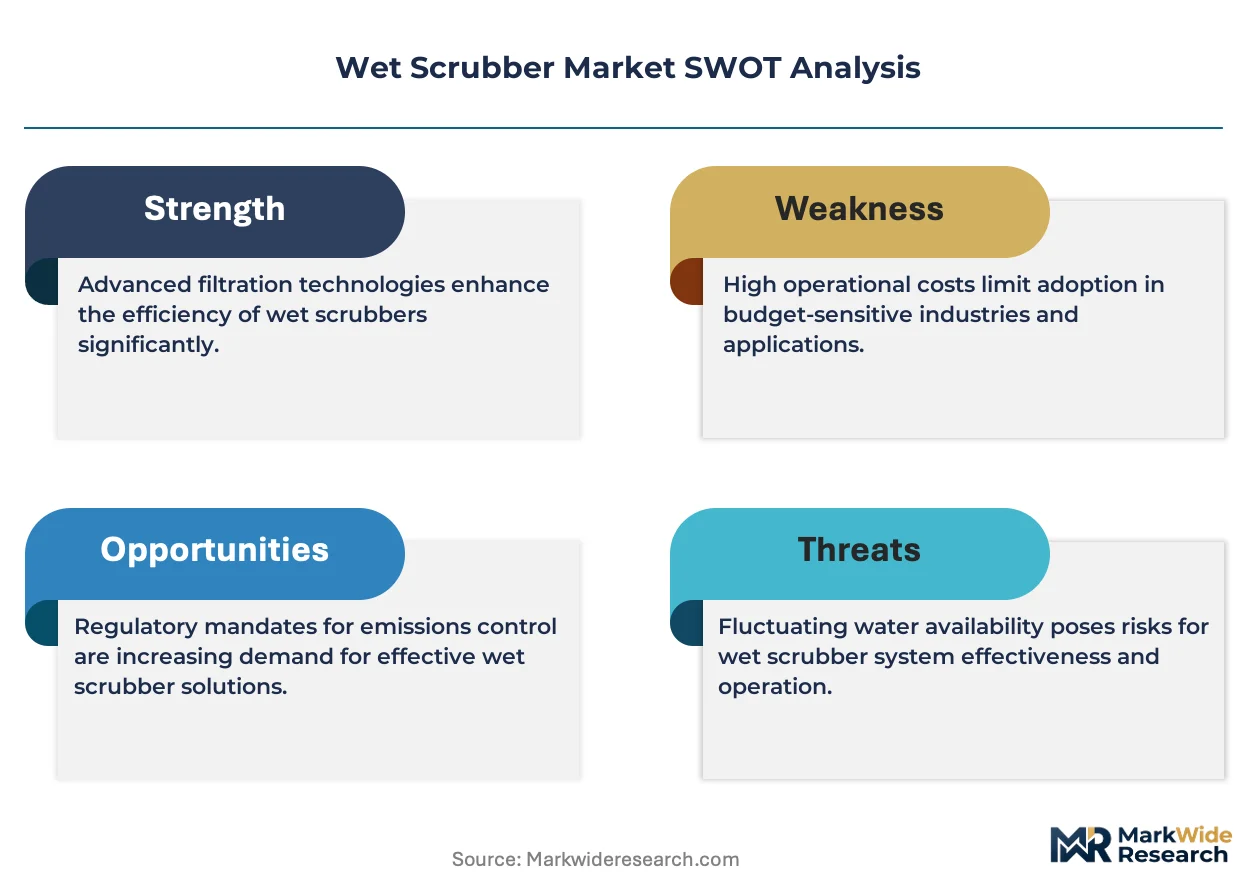
- Capital Expenditure:The high initial investment required for systems built with advanced corrosion-resistant alloys or fiberglass-reinforced plastics presents a significant financial barrier for small and medium-sized industrial enterprises.
- Operational Costs:Long-term operational expenses associated with high water consumption and the continuous procurement of scrubbing reagents, such as lime and caustic soda, can negatively impact lifecycle economics for operators.
- Waste Management:The generation of contaminated liquid slurry as a byproduct creates a disposal challenge, often necessitating investment in secondary wastewater treatment infrastructure, which adds complexity and cost.
Strategic Opportunities
- System Innovation:Development of closed-loop wet scrubber systems that can regenerate and reuse scrubbing liquids offers a path to reduce water consumption and reagent costs, appealing to environmentally conscious operators.
- Geographic Penetration:Expanding into developing economies in Southeast Asia and Latin America, as they begin to implement and enforce more stringent industrial air pollution laws, opens new frontiers for market growth.
- Application Diversification:Targeting emerging sectors such as waste-to-energy, biogas upgrading, and battery manufacturing provides opportunities to adapt wet scrubber technology for novel and complex air purification challenges.
Industry Challenges
- Retrofitting Complexity:Integrating large wet scrubber systems into existing industrial plants with constrained physical space and legacy infrastructure poses significant engineering and logistical hurdles for operators and installers.
- Material Supply Volatility:Price fluctuations and supply chain disruptions for critical corrosion-resistant materials, including specific grades of stainless steel and high-nickel alloys, create uncertainty in project costing and timelines.
- Talent Scarcity:A shortage of process engineers and skilled technicians with expertise in the design, operation, and maintenance of advanced, high-efficiency air pollution control systems can hinder effective deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wet Scrubber Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Venturi Scrubbers, Packed Bed Scrubbers, Spray Tower Scrubbers, Cyclone Scrubbers, Electrostatic Scrubbers Application: Power Plants, Metal Processing, Chemical Manufacturing, Food Processing, Waste Incineration End User Industry: Energy Generation, Metal Fabrication, Chemical Production, Food & Beverage, Waste Management Technology: Absorption, Neutralization, Adsorption, Oxidation, Flue Gas Desulfurization |
| Companies Covered | Ducon Technologies Inc., FLSmidth & Co. A/S, Alfa Laval AB, Thermax Limited, GEA Group AG, Babcock & Wilcox Enterprises, Inc., Evoqua Water Technologies LLC, Sly Inc., CECO Environmental Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wet Scrubber Market Strategic Shifts & Innovations
Material science advancements and the integration of digital controls are creating a new generation of more efficient, reliable, and economically viable wet scrubber systems. This evolution addresses both stricter environmental regulations and the operational demands of industrial end-users.
The integration of smart sensors and IoT connectivity for real-time performance monitoring is a significant technological shift. Chemical plants and power generators are adopting these systems to track metrics like pH, pressure, and flow rates continuously. This move toward data-driven automation is rewriting the economics of operational efficiency and predictive maintenance for pollution control assets.
Regulatory frameworks, such as the EU's Industrial Emissions Directive, continue to be a primary market accelerator. The directive's enforcement of Best Available Techniques (BAT) compels operators of large combustion plants to invest in high-performance gas cleaning equipment. The chemical sector is particularly affected, driving demand for multi-pollutant scrubbers to achieve compliance with integrated pollution control standards.
A distinct behavioral change is the move away from purchasing standalone components toward procuring fully integrated, skid-mounted process solutions. This pattern disrupts the traditional sales channel, favoring system integrators who can deliver a complete, pre-engineered gas cleaning package. The trend is most visible in new-build specialty chemical and pharmaceutical facilities where project velocity and single-source accountability are critical.
Wet Scrubber Market Segmentation
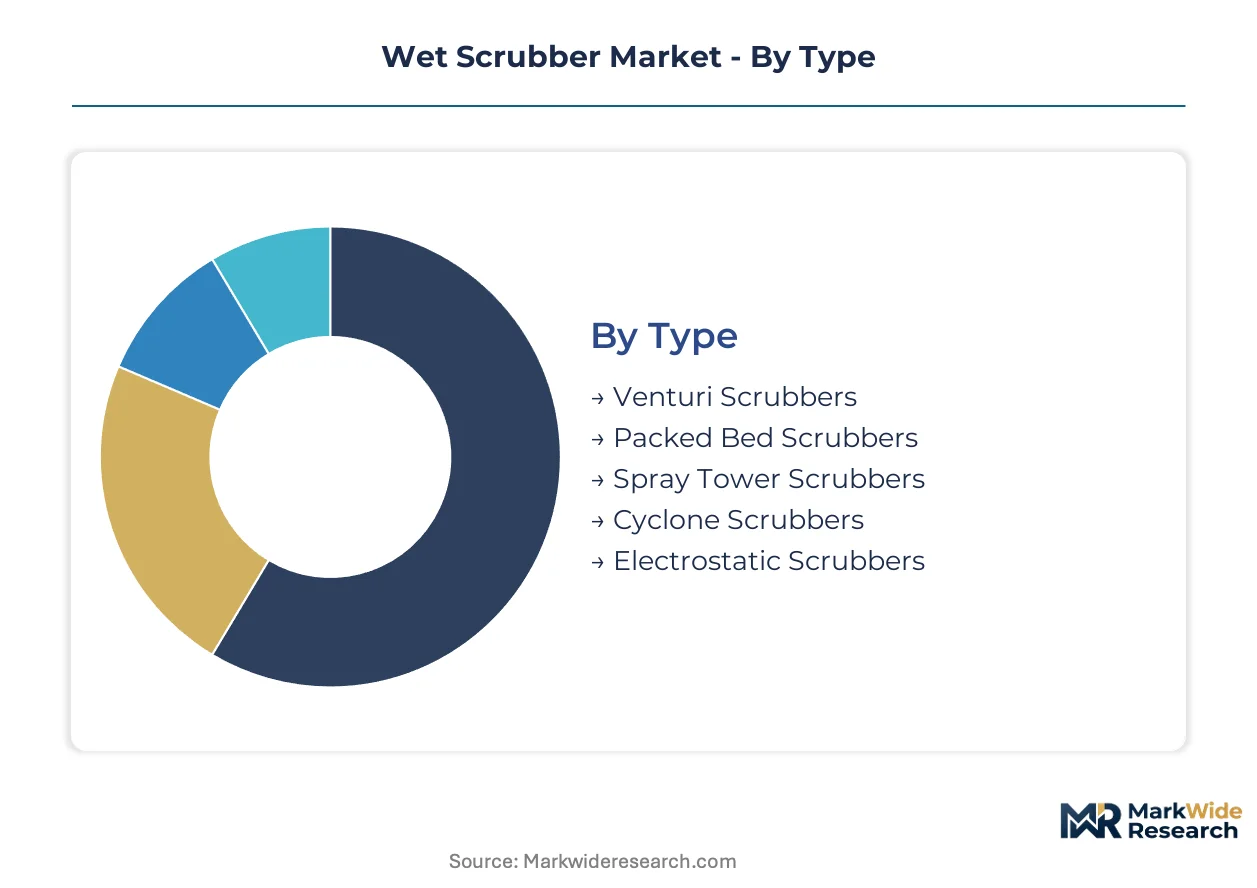
The wet scrubber market's segmentation reveals diverse technological approaches and end-use applications driving its expansion. Understanding these divisions helps delineate where specific solutions offer greatest value for industrial air pollution control. This analysis highlights specialized requirements across various sectors and corresponding scrubber designs.
Type:
The type segmentation illustrates a split between high-volume particulate removal and specialized gas absorption systems. Equipment selection balances capital cost with efficiency demands.
- Venturi Scrubbers:These devices accelerate gas through a constricted throat, atomizing liquid for efficient fine particulate removal. Power plants in India utilize them extensively to meet emission limits.
- Packed Bed Scrubbers:Featuring a packed column, these maximize gas-liquid contact for highly efficient gas absorption, particularly for soluble gaseous pollutants. Chemical manufacturing depends on them for effective acid gas removal.
- Spray Tower Scrubbers:Utilizing spray nozzles, these effectively remove large particulates and absorb gases.
- Cyclone Scrubbers:Combining centrifugal force with liquid sprays, these remove larger particulate matter.
- Electrostatic Scrubbers:Integrating electrostatic precipitation, these capture fine particulates by electrical charging.
Mature deployment sits with Spray Tower Scrubbers. Newer deployment is concentrated in Electrostatic Scrubbers.
Application:
Application-specific demands dictate wet scrubber design and operational parameters, reflecting unique pollutant profiles and regulatory pressures. Tailored solutions ensure optimal performance and compliance.
- Power Plants:These facilities require large-scale flue gas desulfurization systems to control sulfur oxides (SOx) emissions. China's dual carbon goals compel investment in advanced wet scrubbers for its coal-fired power generation sector.
- Chemical Manufacturing:This sector demands robust scrubbers for removing corrosive and toxic gaseous pollutants, including acid gases. European chemical producers deploy multi-pollutant scrubbers to comply with the EU's Industrial Emissions Directive.
- Metal Processing:Operations like smelting generate particulate matter and heavy metal emissions.
- Food Processing:This industry employs wet scrubbers for odor control, fine particulates, and steam abatement.
- Waste Incineration:These plants require sophisticated multi-stage wet scrubbers to remove acid gases, dioxins, and heavy metals.
The largest volume of wet scrubber applications occurs in Power Plants. Waste Incineration applications are expanding most quickly due to stricter environmental mandates.
End User Industry:
End-user industry segmentation highlights diverse economic sectors relying on wet scrubber technology for environmental compliance and operational efficiency. Each presents distinct pollution control challenges.
- Energy Generation:This sector, encompassing thermal power plants, is a primary market for large-scale wet scrubbers focused on SOx and particulate control. India's expanding energy infrastructure creates substantial demand.
- Chemical Production:Manufacturers of bulk and specialty chemicals are significant end-users, requiring custom-engineered scrubbers for complex gas streams. US chemical plants invest in systems to meet EPA air quality standards.
- Metal Fabrication:Foundries and steel mills utilize wet scrubbers to manage emissions of dust, fumes, and acid gases.
- Food & Beverage:This industry deploys scrubbers for odor control, particulate removal, and steam abatement.
- Waste Management:Incineration plants, landfills, and wastewater treatment facilities employ wet scrubbers to neutralize acidic gases and remove odors.
Demand concentration within end-user industries is highest in Energy Generation. Chemical Production exhibits a steady requirement for advanced pollution control.
Technology:
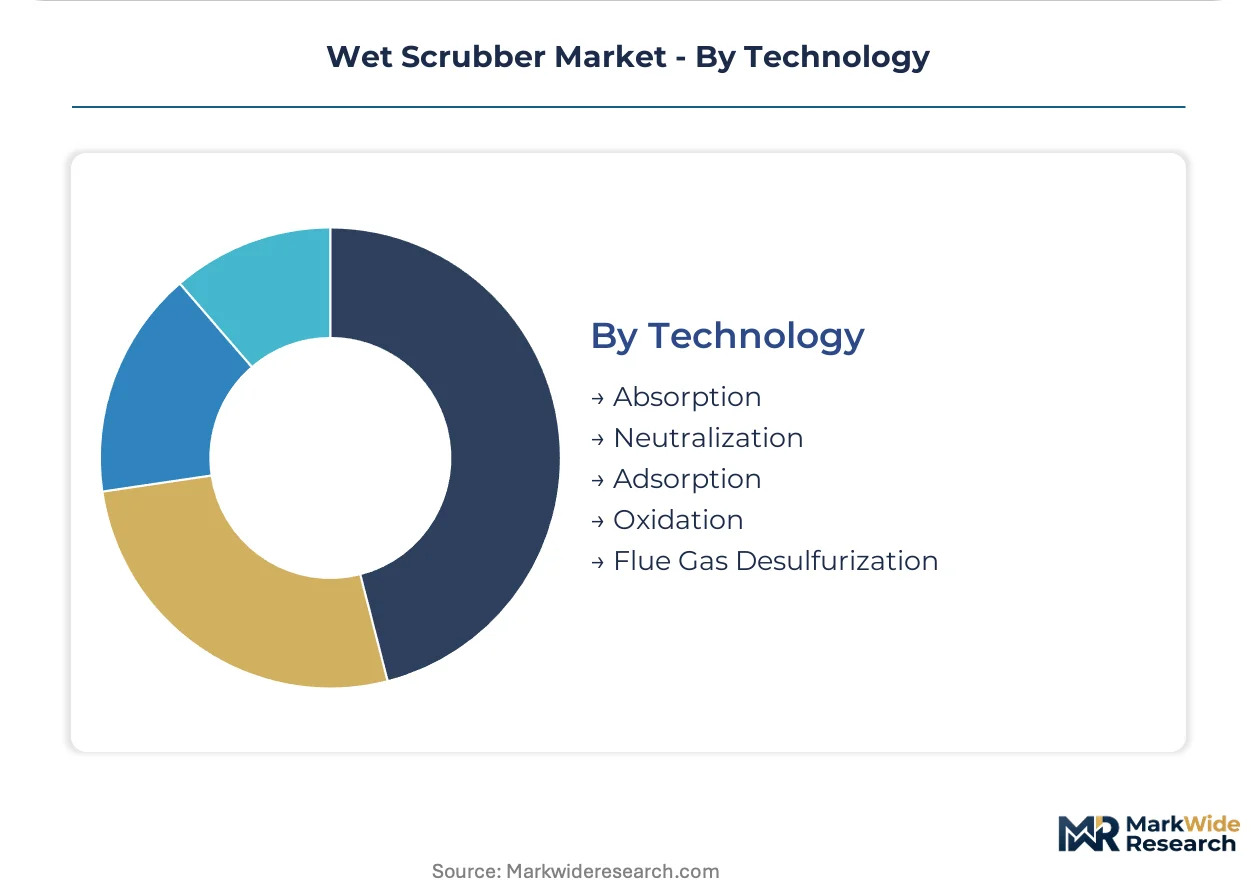
The underlying technology defines a wet scrubber's primary mechanism for pollutant removal, from physical capture to chemical transformation. Innovation enhances efficiency and reduces operational costs.
- Flue Gas Desulfurization:This technology primarily targets sulfur dioxide (SO2) removal from combustion exhaust, often employing lime or limestone as scrubbing reagents. Large combustion plants in Europe integrate advanced FGD systems to comply with the Industrial Emissions Directive.
- Absorption:This process involves dissolving gaseous pollutants into a liquid solvent, often water or a chemical solution, based on their solubility. Chemical facilities frequently use absorption scrubbers for acid gas and ammonia removal.
- Neutralization:This technique uses alkaline scrubbing liquids to chemically react with and neutralize acidic gaseous pollutants.
- Adsorption:Some hybrid systems integrate adsorption media to capture specific organic compounds.
- Oxidation:This technology employs strong oxidizing agents to chemically convert pollutants like hydrogen sulfide or VOCs into less toxic forms.
The most mature wet scrubber technology is Absorption. Flue Gas Desulfurization technology continues to evolve rapidly due to global regulatory pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for wet scrubbers concentrates significantly in rapidly industrializing economies. China's stringent dual carbon goals compel industrial facilities to invest heavily in advanced flue gas desulfurization technologies. India's expanding power generation and metal processing sectors also create substantial demand.
China
China's vast chemical manufacturing and power generation sectors drive significant wet scrubber demand. The nation's MEE enforces stringent emission limits, aligning with its ambitious dual carbon goals. Industrial facilities across the Yangtze River Delta are upgrading to advanced flue gas desulfurization systems.
India
Rapid industrialization in India fuels consistent demand for air pollution control. The Central Pollution Control Board (CPCB) sets emission standards for power and metal processing industries. New facilities in Gujarat's industrial corridors integrate Venturi scrubbers to manage fine particulate matter.
United States
US chemical production facilities require robust wet scrubbers for complex gas streams. The US EPA mandates strict air quality standards, driving investment in advanced systems. Chemical plants along the Gulf Coast consistently upgrade their pollution control infrastructure for compliance.
Germany
Germany's large combustion plants and chemical sector demand high-performance gas cleaning equipment. The EU's Industrial Emissions Directive compels operators to adopt Best Available Techniques for pollutant control. Industrial sites in North Rhine-Westphalia frequently deploy multi-pollutant scrubbers for compliance.
Wet Scrubber Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, influencing the market's competitive structure. The wet scrubber market exhibits a tiered structure, with large engineering firms alongside specialized technology providers. Strategic archetypes include integrated solution providers, niche technology developers, and regional service-focused companies, each addressing distinct client needs. Portfolio diversification and strategic partnerships represent dominant competitive moves among market participants.
Integrated solution providers, such as Babcock & Wilcox Enterprises, Inc., leverage extensive experience in large-scale industrial projects, particularly within the energy generation sector. CECO Environmental Corp. exemplifies diversified portfolio strategies, offering broad air quality and fluid handling solutions across multiple heavy industries. GEA Group AG occupies a distinct position by focusing on integrated process engineering, particularly for the chemical and food processing industries, serving specialized requirements. These companies represent varied approaches to meeting complex industrial air pollution control needs and navigating stringent regulatory frameworks.
| Leading Market Players |
|---|
| Ducon Technologies Inc. |
| FLSmidth & Co. A/S |
| Alfa Laval AB |
| Thermax Limited |
| GEA Group AG |
| Babcock & Wilcox Enterprises, Inc. |
| Evoqua Water Technologies LLC |
| Sly Inc. |
| CECO Environmental Corp. |
| Others |
Cost & Logistics Intelligence
Skilled process engineers in China's industrial hubs influence pricing tiers, as labor-cost differentials impact manufacturing expenses. This regional concentration of expertise directly affects the cost structure of wet scrubber systems.
Pricing Analysis
Volume-driven segments for standard wet scrubber components often experience tighter margins, while custom-engineered systems command premium pricing. Project-based pricing dominates the market, reflecting the bespoke nature of large-scale installations and their customization level. Price differentiation also stems from the integration of advanced corrosion-resistant alloys and comprehensive after-sales service. Pricing pressure stems from high initial capital expenditure and ongoing operational costs, making small and medium-sized industrial enterprises highly price-sensitive compared to large chemical producers.
Supply Chain Analysis
Reverse logistics for wet scrubbers primarily involve refurbishment and replacement of wear parts, extending equipment lifecycles. Supply concentration centers on manufacturing hubs in China, specialized component production in Germany, and advanced system integration in the United States. The market draws heavily from corrosion-resistant alloys and specialized sensors, where material supply volatility presents a structural risk. Distribution runs through direct sales channels and specialized system integrators for complex projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wet scrubber market is fundamentally a cost-of-compliance story, where stringent regulatory frameworks dictate investment. The EU's Industrial Emissions Directive, mandating Best Available Techniques, creates a significant barrier-to-entry moat for less compliant players.
For Market Incumbents:Hedge against rising operational costs by investing in closed-loop wet scrubber systems that regenerate scrubbing liquids. Diversify technology portfolios towards multi-pollutant scrubbers to meet evolving integrated pollution control standards, especially in the chemical sector. Pursue strategic partnerships to mitigate material supply volatility for critical corrosion-resistant alloys. This also addresses the talent scarcity in process engineering.
For New Entrants and Emerging Players:Launch via integrated, skid-mounted process solutions, targeting new-build specialty chemical and pharmaceutical facilities. Focus on underpenetrated developing economies in Southeast Asia, as they begin to implement stricter air pollution laws. Adapt wet scrubber technology for emerging sectors like waste-to-energy and biogas upgrading to capture novel application diversification opportunities. This approach leverages project velocity and single-source accountability.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized technology providers offering integrated digital controls and material science advancements, given the persistent regulatory push for efficiency. The long-term viability of the wet scrubber market is anchored by global emission reduction mandates and industrial expansion. Target acquisition archetypes include firms innovating in smart sensor integration and advanced corrosion-resistant materials. Practitioners should monitor the adoption rate of closed-loop systems for early signals of market transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secures supply of critical corrosion-resistant alloys, mitigating material supply volatility for manufacturers. |
| Strategic Partnership | Accelerates development of smart sensors and IoT connectivity, enhancing real-time performance monitoring. |
| Geographic Expansion | Penetrates developing economies in Southeast Asia, capturing demand from new industrialization projects. |
| Acquisition of Specialist Firm | Integrates expertise in advanced digital controls, offering more efficient and reliable scrubber systems. |
| Green Manufacturing Transition | Develops closed-loop wet scrubber systems, reducing water consumption and operational costs for end-users. |
Research Approach
Trade association data, regulatory filings from the US EPA and EU IED, and technical journals anchored secondary inputs for this analysis. Primary research involved interviews with process engineers, plant managers, and environmental compliance officers across key industrial sectors. This approach combined bottom-up market sizing with top-down validation, triangulating data points for robust market estimates.
Data-stream reconciliation across disparate sources formed the basis for the forecast framework over the projection horizon. Segmentation dimensions modeled included wet scrubber type, end-user application, underlying technology, and regional regulatory intensity. Compound Annual Growth Rates were derived through regression analysis and expert consensus. Key forecast inputs included industrial production indices and emission control technology adoption curves.
The model assumes a particular technology adoption path; alternative pathways for advanced corrosion-resistant alloys or closed-loop systems would alter the outlook. Forecasts reflect assumptions concerning industrial expansion and regulatory stability. Practitioners should monitor material supply chain disruptions and shifts in regulatory enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Engineering
Rainwater Harvesting Market
Environmental Engineering
Outdoor Sound Barrier Market
Environmental Engineering
Secondary Water and Wastewater Treatment Equipment Market
Environmental Engineering
Tunnel Ventilation and Environmental Monitoring Systems Market
Environmental Engineering
Aerobic Treatment Units Market
Environmental Engineering
Global Rainwater Harvesting System Market
Environmental Engineering
Septic Tanks Market
Environmental Engineering
North America Rainwater Harvesting Market
Environmental Engineering
Silt Curtain Market
Environmental Engineering
Dust Control Systems Market
Environmental Engineering
Gas Scrubber Market
Environmental Engineering
Outdoor Noise Barrier Market
Environmental Engineering
Global Built and Natural Environment Consulting Market
Environmental Engineering
Fume Hoods Market