
 Rainwater Harvesting Market | 2026-2036
Rainwater Harvesting Market Size, Share, and Industry Trends Forecast 2026-2036
Rainwater Harvesting Market Analysis
EPA stormwater management guidelines is restructuring the cost-of-entry calculus for commercial-scale system providers across the United States. Kingspan Group leverages its insulated tank manufacturing scale to dominate above-ground installations in North American industrial parks. Grundfos anchors its position through pump technology leadership in pressurized distribution systems for multi-building complexes. Wisy AG differentiates via German-engineered filtration modules that meet stringent potable reuse thresholds in European municipal tenders.
Rainwater harvesting encompasses the capture, storage, treatment, and distribution of precipitation runoff from impervious surfaces, typically employing UV-stabilized polyethylene or reinforced concrete vessels rated for hydrostatic loads exceeding 150 kPa. The primary purpose centers on reducing potable water withdrawals for non-consumptive applications while attenuating peak stormwater discharge to sewer networks. Cisterns and below-ground vessels command the deepest margin pools where excavation logistics and structural engineering requirements filter out commodity competitors. Filtration systems represent the fastest-growing product category as jurisdictions tighten turbidity standards for harvested water reuse in cooling towers and irrigation loops. Agricultural irrigation applications remain volume-heavy but price-competitive, whereas industrial process segments reward certified system integrators with longer contract tenures.
The US EPA and Germany's DIN standards institute jointly shape product certification pathways, with the former governing pollutant runoff containment and the latter prescribing tank material leaching limits that determine market access. India's Central Public Health and Environmental Engineering Organisation mandates rainwater harvesting provisions in building bylaws for structures exceeding defined footprint thresholds, creating compliance-driven demand in Bengaluru and Hyderabad construction markets. Stakeholders must monitor how municipal rebate program eligibility criteria evolve from simple tank volume thresholds toward whole-system efficiency metrics that favor integrated pump and filtration offerings over standalone storage hardware.
Market Dynamics
Municipal water managers in drought-prone jurisdictions are mandating below-ground cistern systems for new commercial developments, compressing demand timelines and elevating filtration performance thresholds that favor engineered solutions over commodity hardware.
Growth Catalysts
- EPA Stormwater Guidelines:The US EPA's updated stormwater management protocols for commercial developments now specify retention volumes that accelerate below-ground system specifications across Texas, Arizona, and California construction markets.
- Polyethylene Vessel Technology:UV-stabilized rotational molding advances have reduced per-liter storage costs while extending service life beyond 25 years, opening residential adoption in Australian rebate corridors.
- India Building Bylaws:The Central Public Health and Environmental Engineering Organisation mandates rainwater harvesting provisions for structures exceeding defined footprints, creating compliance-driven demand in Bengaluru and Hyderabad.
Market Restraints
- Excavation Logistics Costs:Below-ground cistern installation requires specialized geotechnical assessment and dewatering in high water-table regions, adding 15-30% to total project costs versus above-ground alternatives.
- Concrete Supply Concentration:Reinforced concrete vessel production clusters in regional precast facilities within 200km of demand centers, limiting supplier choice in remote Australian and North American markets.
- Cross-Contamination Risk:Inadequate first-flush diversion in basic residential systems creates liability exposure that municipal insurers in European markets increasingly exclude from coverage terms.
Strategic Opportunities
- Industrial Process Water:Cooling tower make-up and boiler feed applications in food processing and semiconductor fabrication offer 3-5 year contract tenures for certified system integrators with potable reuse certification.
- Pump-Filtration Integration:Municipal rebate programs in Melbourne and Sydney are pivoting from volume-based incentives toward whole-system efficiency metrics that favor packaged pump and filtration offerings.
- Smart Monitoring Convergence:IoT-enabled level sensing and turbidity monitoring is creating recurring revenue streams for vendors capable of bundling hardware with predictive maintenance subscriptions.
Industry Challenges
- Geotechnical Engineering Talent:Below-ground cistern specification requires licensed structural engineers familiar with hydrostatic load calculations exceeding 150 kPa, a skill set concentrated among aging professionals in regional markets.
- Multi-Jurisdiction Certification:Vendors seeking access to both EPA-governed US markets and DIN 1989-compliant European tenders must maintain parallel testing protocols, extending product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rainwater Harvesting Market |
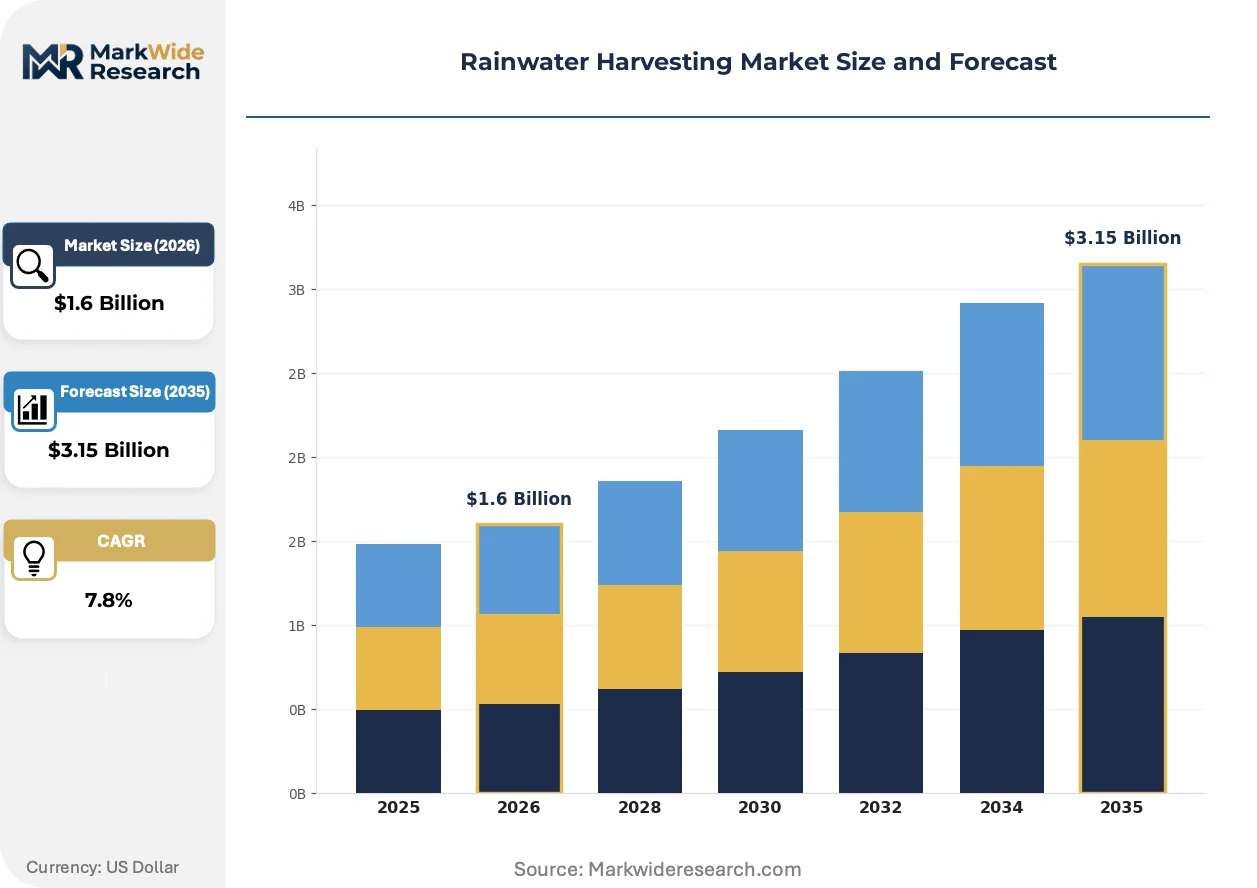
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rain Barrels, Cisterns, Filtration Systems, Pumps Application: Agricultural Irrigation, Residential Use, Urban Landscaping, Industrial Processes Installation Type: Above Ground, Below Ground, Modular Systems, Centralized Distribution Channel: Retail Stores, Online Sales, Direct Sales, Wholesale |
| Companies Covered | Stormsaver Ltd, CST Industries, Kingspan Group, Norwesco, Snyder Industries, Watts Water Technologies, Wisy AG, Grundfos, Graf Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rainwater Harvesting Market Emerging Trajectories
System architecture is converging around modular filtration trains and pressurized distribution networks that displace passive gravity-fed designs, while digital monitoring layers create new service revenue streams.
Membrane bioreactor filtration is consolidating downstream treatment stages into single-vessel configurations that achieve turbidity thresholds below 5 NTU without sequential cartridge replacement. Industrial cooling tower operators in Australian and German markets are specifying these integrated units to reduce maintenance intervals from quarterly to annual cycles. This consolidation is compressing the addressable market for standalone sand-filter and activated-carbon suppliers that previously captured separate procurement decisions.
Germany's updated DIN 1989 standards now prescribe tank material leaching limits and filtration performance thresholds that determine market access for potable reuse applications. The industrial consequence is a bifurcation between certified system integrators eligible for municipal tenders and commodity barrel manufacturers restricted to non-potable irrigation segments. Above-ground polyethylene tank producers are responding by acquiring filtration module capabilities or exiting the commercial specification channel entirely.
Buyers are consolidating procurement authority from facilities managers to corporate sustainability officers with mandate alignment to science-based water targets. This shift is displacing transactional hardware purchases with performance-contracting models where vendors guarantee volumetric offsets against municipal withdrawals. The transformation is most visible in North American industrial park developments where Kingspan Group and Grundfos anchor multi-building installations through 10-15 year service agreements rather than equipment-only sales.
Rainwater Harvesting Market Segmentation
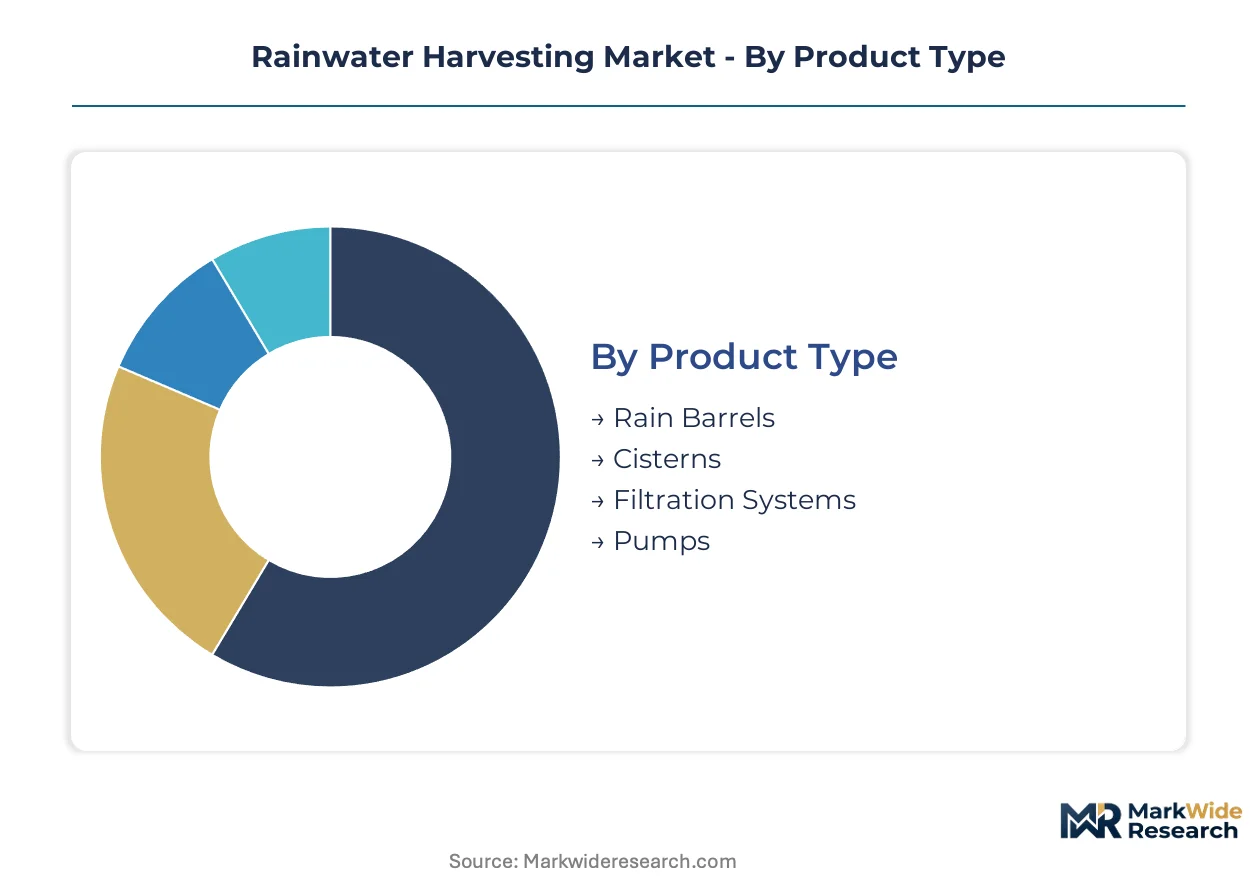
Rainwater harvesting vendors must align product architectures with distinct buyer capabilities and compliance obligations. Specification authority varies sharply between municipal procurement offices, industrial facilities managers, and residential end-users.
Product Type:
Buyers in this category separate by project scale and regulatory exposure — commercial developers face engineered-system mandates while residential purchasers prioritize unit cost.
- Cisterns:Reinforced concrete or polyethylene vessels engineered for hydrostatic loads exceeding 150 kPa. Below-ground specifications dominate Texas, Arizona, and California commercial developments where municipal water managers mandate retention volumes for stormwater compliance.
- Filtration Systems:Engineered trains incorporating first-flush diversion, activated carbon, and membrane stages to achieve turbidity thresholds below 5 NTU. German industrial operators specify these for cooling tower make-up under DIN 1989 potable reuse standards.
- Rain Barrels:UV-stabilized polyethylene units for residential downspout connection. Australian rebate programs in Melbourne and Sydney corridors drive volume through volume-based incentives.
- Pumps:Pressurized distribution equipment for multi-building complexes and irrigation loops. Grundfos anchors this segment through variable-speed technology for demand-responsive flow.
Volume sits with cisterns; growth tilts toward filtration systems.
Application:
End-use economics determine contract tenure and certification requirements — industrial buyers pay premiums for guaranteed volumetric offsets.
- Industrial Processes:Cooling tower make-up, boiler feed, and semiconductor fabrication rinse water. Food processing and electronics manufacturers in Germany and Australia sign 3-5 year performance contracts with certified integrators.
- Agricultural Irrigation:Vineyard and orchard operations in Australia's Murray-Darling basin. Price competition limits margins despite substantial per-farm storage volumes.
- Residential Use:Toilet flushing, laundry, and garden irrigation in rebate-eligible urban corridors. Melbourne and Sydney utilities subsidize tank installations exceeding defined capacity thresholds.
- Urban Landscaping:Municipal parks, golf courses, and commercial grounds maintenance. EPA stormwater guidelines accelerate below-ground system specifications in drought-prone US states.
Revenue concentrates in industrial processes; residential applications expand most quickly through municipal incentive programs.
Installation Type:
Site geology and structural engineering talent availability filter supplier participation — high water-table regions impose cost penalties that reshape competitive sets.
- Below Ground:Excavated cistern systems with geotechnical assessment and dewatering protocols. Texas and California commercial developments specify these for stormwater retention compliance despite 15-30% cost premiums versus above-ground alternatives.
- Above Ground:Polyethylene or steel tank configurations for industrial parks and residential properties. Kingspan Group dominates North American installations through insulated vessel manufacturing scale.
- Modular Systems:Pre-assembled pump and filtration skids for rapid deployment. Remote Australian and North American markets favor these where concrete supply concentrates within 200km of demand centers.
- Centralized:Single large-capacity installations serving multi-building complexes. German municipal tenders specify these for district-scale non-potable distribution networks.
Above-ground installations capture current volume; below-ground specifications gain share fastest as drought-prone jurisdictions tighten retention mandates.
Distribution Channel:
Buyer sophistication and project complexity determine channel selection — engineered systems bypass retail entirely while residential hardware fragments across multiple pathways.
- Direct Sales:Specification-led procurement for commercial and industrial developments. System integrators engage corporate sustainability officers with performance-contracting models guaranteeing volumetric offsets.
- Wholesale:Bulk tank and component supply to regional installers. Australian and North American precast concrete vessels move through this channel to construction contractors.
- Online Sales:Residential rain barrels and basic pump units. Melbourne and Sydney rebate program eligibility drives search-driven purchasing for sub-10,000 liter systems.
- Retail Stores:Big-box and specialty hardware outlets for homeowner self-installation. Limited to non-potable irrigation segments without filtration complexity.
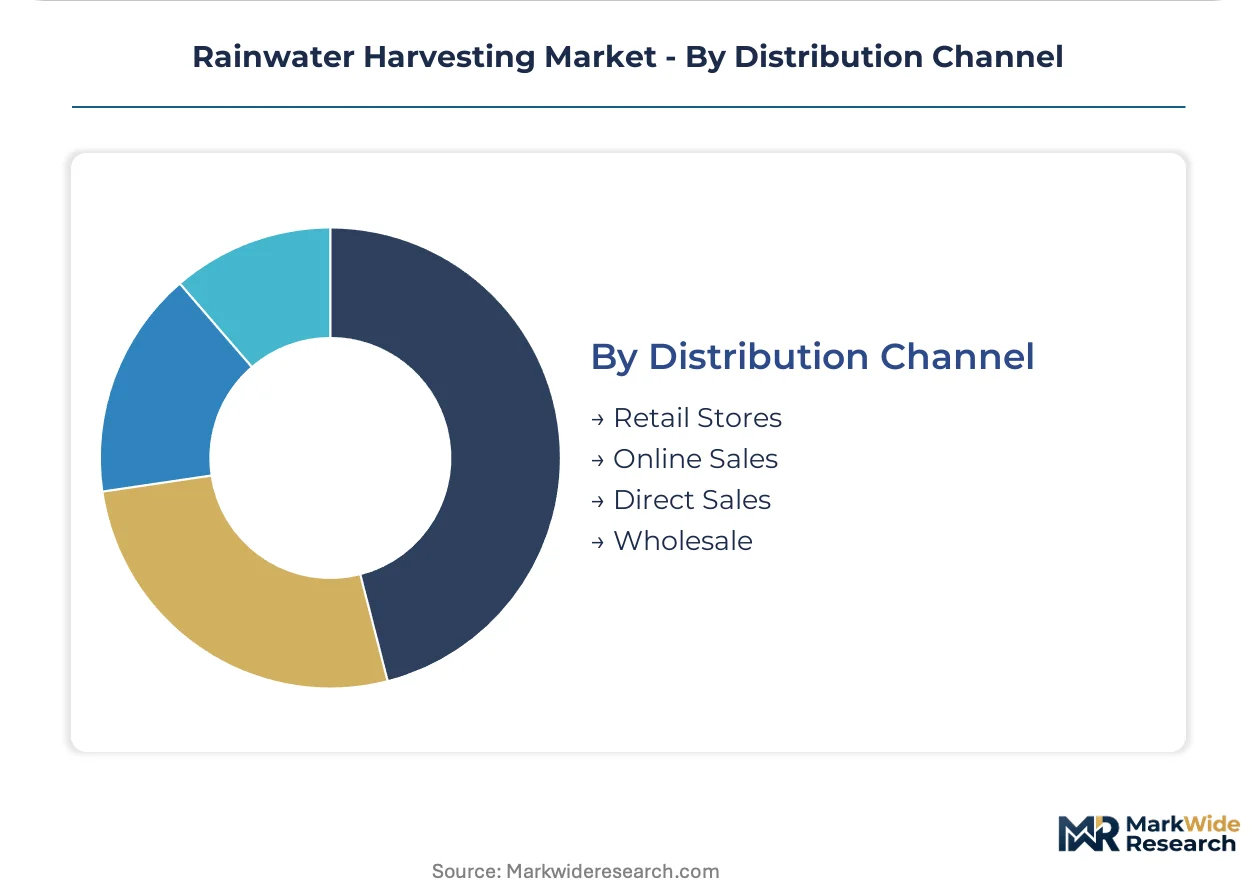
Transaction value concentrates in direct sales; online channels climb the fastest as rebate program digitization streamlines eligibility verification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in drought-prone jurisdictions where municipal rebate programs and stormwater mandates accelerate specification timelines. Australia, Germany, and the southwestern United States anchor volume through distinct regulatory pathways.
United States
Texas, Arizona, and California commercial developments drive below-ground cistern specifications under EPA stormwater retention mandates. Municipal water managers in these states now require engineered systems for new construction permits. The Central Valley agricultural corridor and Phoenix-Tucson metro area concentrate installations for irrigation compliance.
Germany
Industrial cooling tower operators specify membrane bioreactor filtration under DIN 1989 potable reuse standards. The updated regulation mandates tank material leaching limits that filter commodity competitors from municipal tenders. Bavaria and Baden-Württemberg manufacturing clusters anchor demand for pressurized distribution systems.
Australia
Melbourne and Sydney utilities offer volume-based rebates for residential tank installations exceeding defined thresholds. The Murray-Darling basin vineyard operations sustain agricultural irrigation demand despite price-competitive procurement. Victoria and New South Wales urban corridors dominate residential adoption through streamlined eligibility verification.
India
Bengaluru and Hyderabad construction markets face compliance-driven demand under Central Public Health and Environmental Engineering Organisation building bylaws. Structures exceeding defined footprint thresholds must incorporate rainwater harvesting provisions. Karnataka and Telangana software corridor expansion accelerates commercial system specifications.
United Kingdom
Stormsaver Ltd anchors domestic specification capacity for below-ground commercial installations. Southeast England water stress prompts municipal interest in whole-system efficiency metrics over simple volume incentives. Greater London commercial developments increasingly specify integrated pump and filtration packages.
Rainwater Harvesting Market Vendor Landscape
German specialists anchor the premium filtration tier; North American fabricators dominate volume manufacturing through polyethylene rotational molding scale. The vendor base splits between certified system integrators eligible for municipal tenders and commodity barrel producers restricted to non-potable segments. Three archetypes predominate: insulated tank manufacturers, pump technology leaders, and filtration module specialists. Capacity expansion and filtration capability acquisition represent the dominant competitive vectors as rebate programs pivot toward whole-system efficiency metrics.
Among UK-based system integrators, Stormsaver Ltd occupies a position within the commercial specification channel. Kingspan Group and Grundfos exemplify the scale-driven and technology-led archetypes respectively, with the former representing insulated vessel manufacturing capacity and the latter anchoring pressurized distribution expertise. These three entities collectively illustrate how geographic specialization and capability depth determine access to performance-contracting models with corporate sustainability officers.
| Leading Market Players |
|---|
| Stormsaver Ltd |
| CST Industries |
| Kingspan Group |
| Norwesco |
| Snyder Industries |
| Watts Water Technologies |
| Wisy AG |
| Grundfos |
| Graf Group |
| Others |
Supply Flow & Price Mechanics
Captive filtration module production anchors pricing power for certified system integrators competing in German DIN 1989 tenders and Australian municipal rebate programs, while polyethylene rotational molders without downstream treatment capabilities face margin compression in commoditized rain barrel segments.
Pricing Analysis
Volume concentrates in above-ground polyethylene tanks where Kingspan Group and Norwesco compete on manufacturing scale, while margins pool in below-ground cisterns and integrated pump-filtration systems where geotechnical engineering requirements filter out commodity suppliers. Pricing stratifies across certified potable-reuse tiers, DIN 1989-compliant industrial specifications, and non-potable residential irrigation levels. Cost compression in basic rain barrel segments is intensifying as Australian rebate programs pivot from volume thresholds toward whole-system efficiency metrics. Municipal procurement offices exhibit lowest price sensitivity due to stormwater compliance mandates, whereas residential self-install buyers drive aggressive unit-cost negotiations.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rotational molding equipment suppliers and German membrane bioreactor component manufacturers, creating tariff exposure for North American tank fabricators and Australian system integrators alike. Production draws from the United States, Germany, and Australia for engineered cisterns and pressurized distribution equipment, while polyethylene resin feeds from Gulf Coast petrochemical complexes and Middle Eastern feedstock exporters. Logistics chokepoints concentrate in regional precast concrete facilities within 200km of demand centers, limiting supplier choice in remote Australian and North American markets. Distribution runs through direct specification sales for commercial developments and wholesale channels for residential hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where Germany's DIN 1989 potable reuse standards and EPA stormwater retention mandates erect barrier-to-entry moats that reward certified system integrators while excluding commodity barrel manufacturers from premium specification channels.
For Market Incumbents: Deepen backward integration into membrane bioreactor filtration modules to capture municipal tender premiums in Germany and Australia, while expanding geotechnical engineering capacity in Texas and California to defend below-ground cistern margins against regional precast competitors. Threat concentration sits with polyethylene rotational molders acquiring filtration capabilities and rebate program digitization favoring online channels. For New Entrants and Emerging Players: Launch via modular pump-filtration skids targeting remote Australian and North American markets where concrete supply concentration creates service gaps, while pursuing industrial process water performance contracts in food processing and semiconductor fabrication segments. The most penetrable white space concentrates in IoT-enabled monitoring subscriptions bundled with predictive maintenance. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to building materials conglomerates seeking water management platform assets, with long-term viability hinging on 5-10 year service agreement penetration rather than transactional hardware sales. Acquisition targets should display DIN 1989 or EPA certification depth paired with installed base scale for recurring revenue conversion. The signal to watch is municipal rebate program eligibility criteria evolution from volume thresholds toward whole-system efficiency metrics.| Strategic Initiative | Industry Significance |
|---|---|
| Filtration Capability Acquisition | DIN 1989 compliance unlocks German municipal tender access previously restricted to certified integrators. |
| Geotechnical Engineering Talent Recruitment | Licensed structural engineers familiar with 150 kPa hydrostatic loads enable below-ground cistern specification in drought-prone US states. |
| IoT Monitoring Platform Development | Predictive maintenance subscriptions create recurring revenue streams displacing transactional hardware sales. |
| Performance Contracting Model Adoption | Guaranteed volumetric offset agreements align vendor incentives with corporate sustainability officer mandates. |
| Regional Precast Concrete Capacity Expansion | Proximity production within 200km of demand centers mitigates logistics penalties in remote Australian markets. |
Methodological Framework
Multi-period observation of municipal rebate program uptake rates, DIN 1989 certification timelines, and EPA stormwater permit issuance anchored the trend analysis, supplemented by interviews with system integrators, municipal water managers, geotechnical engineers, and polyethylene tank manufacturers. Secondary validation drew from EPA stormwater guideline documents, DIN standards institute technical bulletins, Australian Bureau of Statistics water utility data, and Indian Central Public Health and Environmental Engineering Organisation building bylaw filings. Bottom-up project pipeline tracking across Texas, California, Bavaria, and Victoria triangulated against top-down regulatory mandate analysis.
Segment-weighting approaches modeled cistern, filtration system, rain barrel, and pump categories across installation type, application, and distribution channel dimensions, with additional weighting for potable reuse certification tiers. CAGRs were derived from regression analysis of historical permit issuance correlated with regulatory enforcement intensity and rebate program funding levels across the analysis window. Industry-specific inputs included hydrostatic load engineering requirements, membrane bioreactor adoption curves, and IoT sensor penetration in commercial installations.
Regulatory enforcement delays, rebate program funding suspensions, and geotechnical engineering talent shortages are the dominant revision risks that could compress adoption timelines or shift specification authority toward lower-margin alternatives. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Engineering
Outdoor Noise Barrier Market
Environmental Engineering
Silt Curtain Market
Environmental Engineering
Outdoor Sound Barrier Market
Environmental Engineering
Aerobic Treatment Units Market
Environmental Engineering
Global Rainwater Harvesting System Market
Environmental Engineering
North America Rainwater Harvesting Market
Environmental Engineering
Global Built and Natural Environment Consulting Market
Environmental Engineering
Tunnel Ventilation and Environmental Monitoring Systems Market
Environmental Engineering
Dust Control Systems Market
Environmental Engineering
Secondary Water and Wastewater Treatment Equipment Market
Environmental Engineering
Septic Tanks Market
Environmental Engineering
Fume Hoods Market
Environmental Engineering
Gas Scrubber Market
Environmental Engineering
Wet Scrubber Market