
 Aerobic Treatment Units Market | 2026-2036
Aerobic Treatment Units Market Size, Share, and Industry Trends Forecast 2026-2036
Aerobic Treatment Units Market Analytics
Multi-source component procurement is rebalancing toward vertically integrated domestic manufacturing among aerobic treatment unit suppliers. Fluence Corporation leverages its membrane technology portfolio to anchor premium system configurations across commercial and municipal deployments. Orenco Systems Inc. sustains engineering leadership in decentralized pressure-dosed designs for challenging site conditions. Bio-Microbics Inc. specializes in compact residential packaged units that compete on installation footprint and operational simplicity.
Aerobic treatment units are engineered biological wastewater systems that introduce forced air to maintain dissolved oxygen levels between 1.5 and 2.5 mg/L, accelerating microbial decomposition of organic matter for effluent discharge meeting secondary treatment standards. Packaged units dominate residential applications where pre-engineered skid-mounted configurations reduce field assembly complexity and shorten commissioning timelines. Sequencing batch reactors command premium positioning in commercial and small municipal installations due to their batch-operated flexibility and reduced footprint compared to continuous-flow activated sludge alternatives. Activated sludge processes retain cost advantages in centralized systems serving larger population equivalents where economies of scale offset higher civil infrastructure requirements.
EPA Office of Water oversees decentralized wastewater management guidelines under the Clean Water Act, while NSF International administers ANSI/NSF Standard 40 for residential wastewater treatment systems, creating dual compliance pathways that manufacturers must navigate for market access. State environmental agencies in Florida, North Carolina, and Texas impose supplementary performance standards that exceed federal baselines, fragmenting certification requirements and elevating regional product adaptation costs. Stakeholders must monitor evolving nutrient removal mandates in Chesapeake Bay and Great Lakes watershed jurisdictions, as these regulations will determine whether membrane bioreactor technology displaces conventional activated sludge in next-generation system specifications.
Market Dynamics
Membrane bioreactor technology is converging with conventional activated sludge designs, compressing the performance gap between decentralized and centralized treatment economics while forcing incumbent suppliers to recalibrate R&D roadmaps.
Growth Catalysts
- EPA decentralized wastewater guidelines:Federal standards under the Clean Water Act mandate secondary treatment performance for rural residential developments, creating baseline demand pull across southeastern states with clay soil constraints.
- Sequencing batch reactor flexibility:Commercial property developers specify batch-operated systems for variable flow conditions, reducing footprint requirements in retail and hospitality applications.
- NSF/ANSI Standard 40 certification:Third-party validation protocols accelerate municipal approval timelines for packaged residential units, shortening commissioning cycles for installers.
Market Restraints
- Stainless steel and polymer input costs:Membrane module housings and diffuser assemblies face commodity price volatility that compresses gross margins on fixed-price municipal contracts.
- Regional certification fragmentation:Florida, North Carolina, and Texas impose supplementary performance standards exceeding federal baselines, elevating product adaptation costs for multi-state suppliers.
- Conventional septic tank substitution:Gravity-fed anaerobic systems retain cost advantages in permeable soil conditions, limiting aerobic unit penetration in midwestern and western markets.
Strategic Opportunities
- Nutrient removal mandates:Chesapeake Bay and Great Lakes watershed jurisdictions are advancing total nitrogen and phosphorus limits that favor membrane bioreactor adoption over conventional activated sludge in next-generation specifications.
- Pressure-dosed distribution:Challenging site conditions in coastal plain developments create demand for engineered drip field integration, opening service revenue streams for specialized installers.
- Remote monitoring convergence:IoT-enabled dissolved oxygen sensors and cloud-based maintenance alerts are creating subscription revenue models for equipment OEMs serving dispersed residential fleets.
Industry Challenges
- Cross-trained technician scarcity:Field service requires simultaneous competency in electrical controls, biological process optimization, and hydraulic troubleshooting, constraining installer network expansion.
- NSF/ANSI Standard 245 nutrient certification timelines:Extended laboratory testing protocols for nitrogen reduction claims delay product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerobic Treatment Units Market |
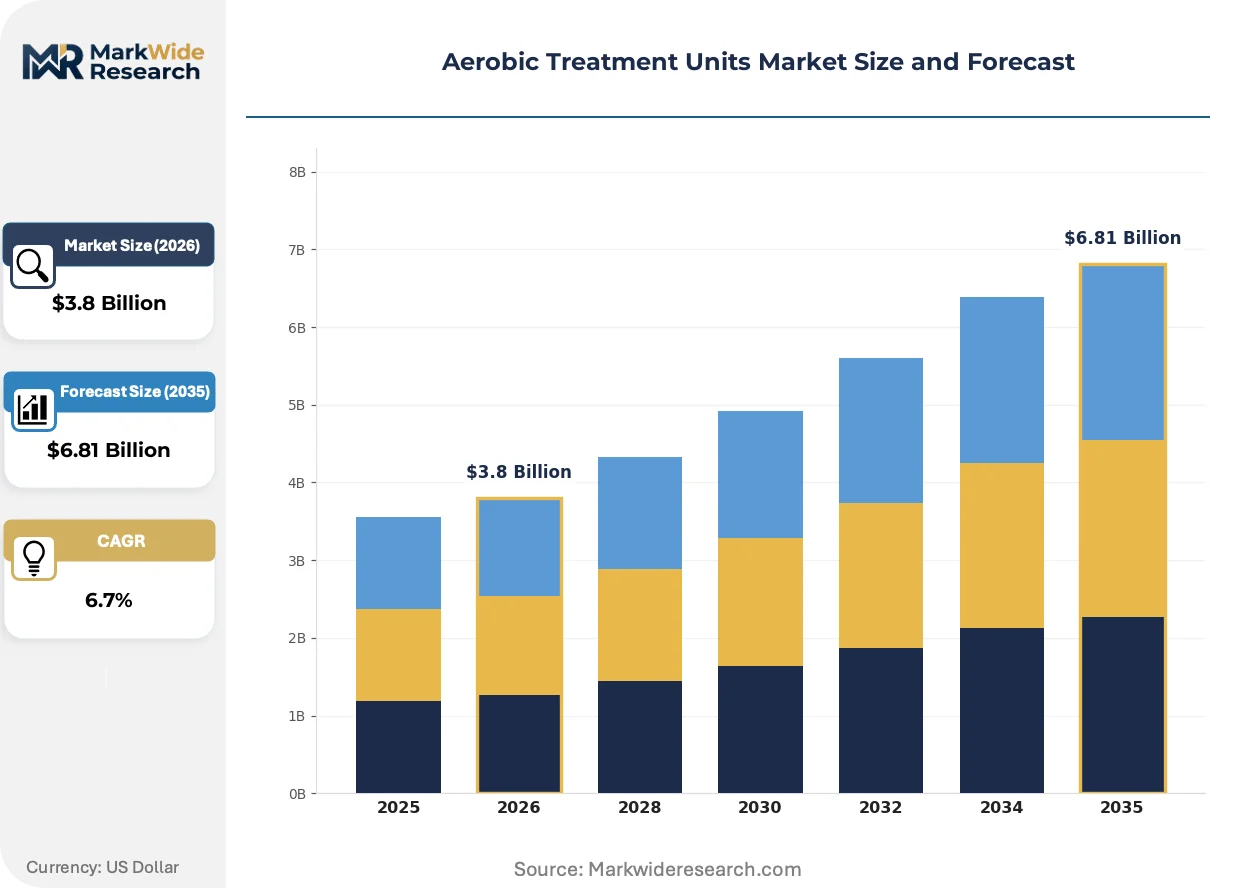
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Packaged Units, Modular Units, Centralized Systems, Decentralized Systems Technology: Membrane Bioreactors, Sequencing Batch Reactors, Activated Sludge Processes, Trickling Filters End User: Residential, Commercial, Industrial, Municipal Application: Wastewater Treatment, Sewage Management, Sludge Processing, Nutrient Removal |
| Companies Covered | Fluence Corporation, Orenco Systems Inc., Bio-Microbics Inc., Norweco Inc., Clearstream Wastewater Systems Inc., Jet Inc., Kingspan Environmental Ltd., 3M Purification Inc., Veolia Water Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerobic Treatment Units Market Evolving Landscape
Forced aeration control systems are integrating real-time sensor feedback, transforming fixed-speed blowers into variable-output assets that match oxygen delivery to diurnal load patterns.
Membrane bioreactor technology is converging with sequencing batch reactor architectures, enabling commercial-scale systems to achieve tertiary effluent quality within footprints comparable to conventional secondary treatment. Hospitality and retail property managers specify these hybrid configurations for water reuse applications. The convergence is compressing civil infrastructure requirements and shifting competitive advantage toward membrane module suppliers with proprietary fouling control chemistries.
EPA Office of Water is tightening enforcement of secondary treatment standards for small community systems under the Clean Water Act. The policy shift elevates compliance risk for non-performing decentralized installations and accelerates replacement cycles in legacy markets. Municipal utilities in Florida and North Carolina are responding by pre-approving packaged aerobic units with certified nitrogen removal capabilities.
Buyers are consolidating procurement authority among regional engineering firms that bundle design, equipment specification, and long-term service contracts. This channel concentration displaces traditional distributor networks and shifts margin capture toward turnkey providers. The pattern is most visible in Texas and Georgia, where rural residential developers prefer single-source accountability over fragmented vendor management.
Aerobic Treatment Units Market Segmentation
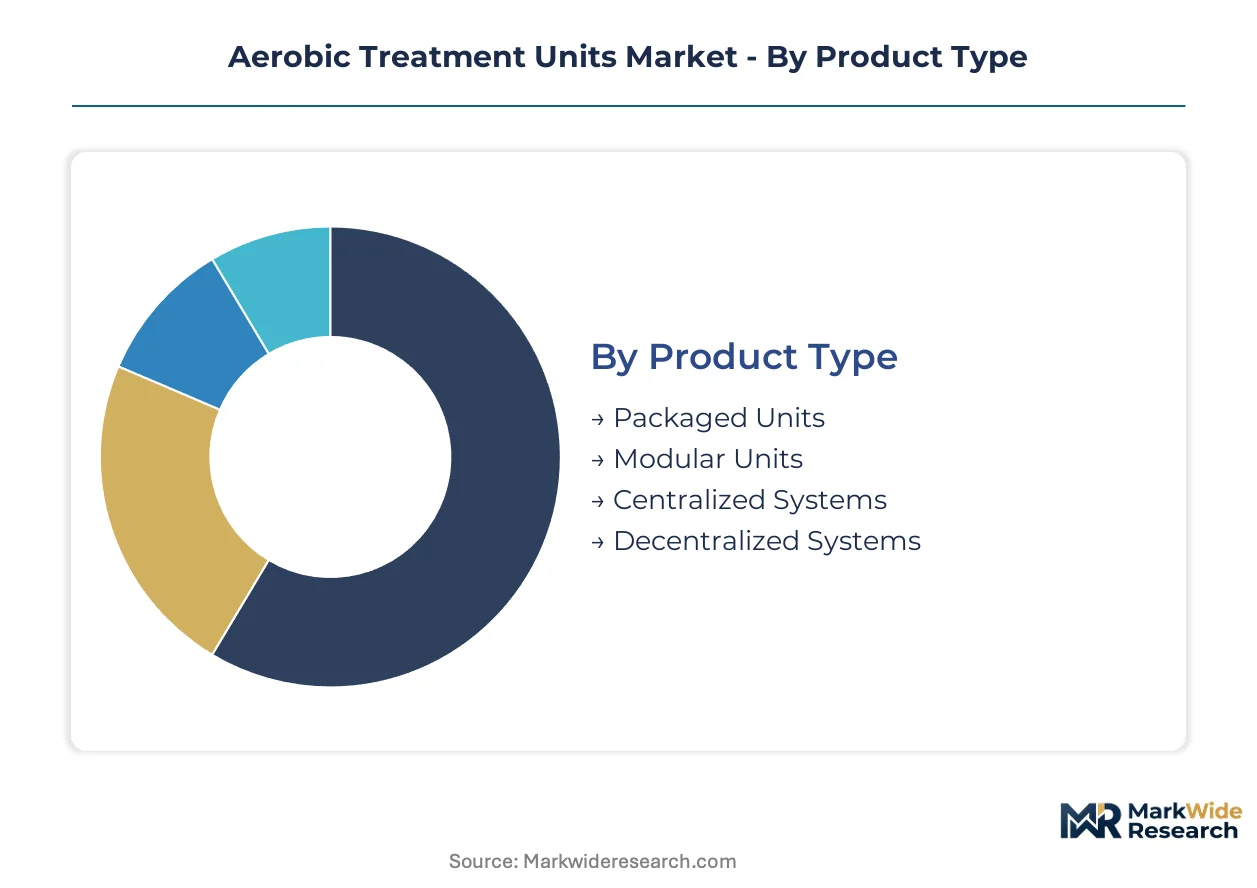
Product configuration dictates procurement pathways in the aerobic treatment units market, with residential buyers prioritizing installation simplicity while commercial and municipal operators emphasize operational flexibility and regulatory compliance margins.
Product Type:
Installation footprint and civil infrastructure requirements drive buyer selection across rural residential, commercial retail, and small municipal deployments.
- Packaged Units:Pre-engineered skid-mounted systems integrate aeration basins, clarifiers, and control panels into factory-assembled configurations. Demand concentrates in southeastern United States residential developments where clay soils mandate engineered alternatives to conventional septic systems.
- Modular Units:Scalable component architectures permit phased capacity expansion without system replacement. Commercial property developers in Texas and Georgia specify these for retail and hospitality applications with variable occupancy patterns.
- Centralized Systems:Continuous-flow activated sludge designs serve larger population equivalents where economies of scale offset civil infrastructure investments.
- Decentralized Systems:Pressure-dosed distribution configurations address challenging site conditions in coastal plain developments with limited drainfield area.
Volume sits with packaged units; growth tilts toward modular configurations.
Technology:
Effluent quality specifications and footprint constraints determine technology selection, with nutrient removal mandates reshaping competitive positioning in Chesapeake Bay and Great Lakes watershed jurisdictions.
- Membrane Bioreactors:Ultrafiltration membranes integrated with biological treatment achieve tertiary effluent quality within secondary treatment footprints. Municipal utilities in Florida and North Carolina pre-approve these for nitrogen removal compliance.
- Sequencing Batch Reactors:Batch-operated fill-and-draw cycles provide operational flexibility for variable flow conditions. Hospitality and retail property managers specify these to reduce footprint requirements in space-constrained sites.
- Activated Sludge Processes:Conventional continuous-flow designs retain cost advantages in centralized systems serving stable load profiles.
- Trickling Filters:Fixed-film biological towers offer passive aeration alternatives for small-scale installations with limited electrical infrastructure.
Activated sludge processes dominate installed base; membrane bioreactors are expanding most quickly.
End User:
Regulatory compliance risk and operational complexity separate residential self-maintained systems from commercially managed fleets with service contract dependencies.
- Residential:Single-family and small multi-family dwellings in rural unsewered areas drive demand for NSF/ANSI Standard 40 certified packaged units with simplified control interfaces.
- Commercial:Retail, hospitality, and office properties specify sequencing batch reactor and membrane bioreactor configurations for variable occupancy and water reuse applications.
- Industrial:Food processing and light manufacturing facilities require pretreatment-compatible designs for high-strength organic loads.
- Municipal:Small community systems under EPA Clean Water Act jurisdiction replace failing decentralized installations with certified nitrogen removal capabilities.
Residential segment holds volume leadership; commercial applications show steepest expansion trajectory.
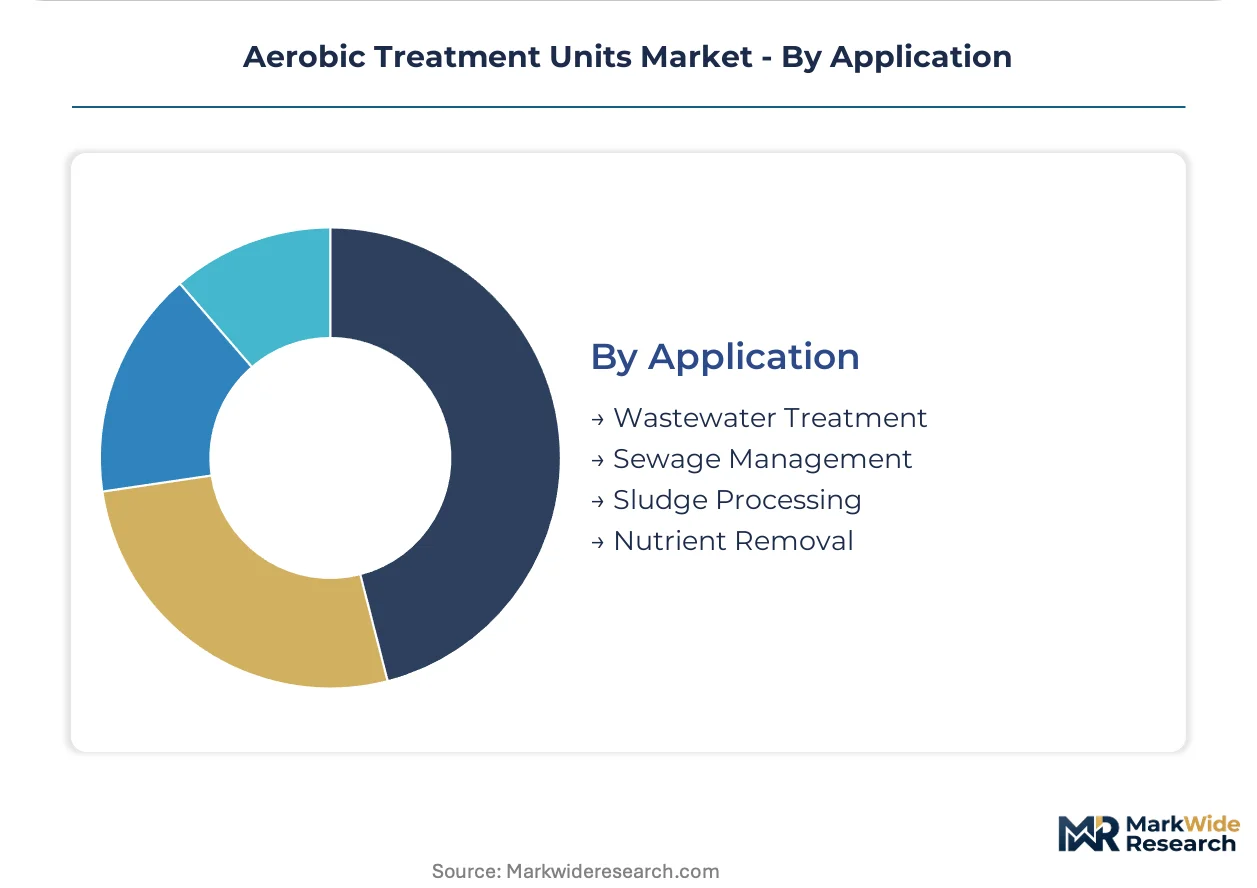
Application:
Performance tier requirements separate secondary treatment baselines from advanced nutrient removal specifications emerging in watershed-specific regulations.
- Wastewater Treatment:Secondary treatment standards for biochemical oxygen demand and total suspended solids define baseline system configurations across all product categories.
- Sewage Management:Collection and preliminary treatment functions integrate with aerobic units in decentralized cluster systems for rural residential developments.
- Sludge Processing:Waste activated solids handling and dewatering requirements influence aeration basin design and operational protocols.
- Nutrient Removal:Total nitrogen and phosphorus limits in Chesapeake Bay and Great Lakes jurisdictions drive membrane bioreactor specification for next-generation compliance.
Wastewater treatment commands current volume; nutrient removal specifications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clay deposits across the southeastern United States anchor the geographic concentration of aerobic treatment unit demand. This soil constraint drives specification patterns that extend into comparable hydrogeological conditions internationally.
United States
Rural residential developments in Florida, Georgia, and North Carolina generate sustained demand for NSF/ANSI Standard 40 certified packaged units. EPA Office of Water enforcement of Clean Water Act secondary treatment standards accelerates replacement cycles for failing decentralized systems. The Texas Hill Country corridor exhibits fastest growth as developers specify pressure-dosed configurations for rocky substrate conditions.
Germany
Small municipalities in Bavaria and Baden-Württemberg deploy membrane bioreactor systems to meet EU Urban Wastewater Treatment Directive nutrient limits. REACH compliance requirements shape polymer and membrane material selection for equipment suppliers. The Stuttgart industrial cluster hosts engineering firms specializing in compact sequencing batch reactor designs for commercial hospitality applications.
China
Rural revitalization programs in Zhejiang and Jiangsu provinces drive decentralized wastewater infrastructure investment. MEE enforcement of GB 18918 discharge standards elevates technical specifications for village-scale treatment systems. The Yangtze River Delta manufacturing corridor concentrates domestic packaged unit production capacity serving East Asian export markets.
Australia
Coastal developments in Queensland and New South Wales specify aerobic units where sandy soils compromise conventional septic performance. State environmental regulators impose supplementary nitrogen removal requirements in Great Barrier Reef catchment zones. The Brisbane-Gold Coast corridor exhibits strongest demand growth for remote-monitored residential systems with cloud-based maintenance alerts.
Canada
Cottage country developments in Ontario and British Columbia drive seasonal occupancy system specifications with variable flow handling. Health Canada guidelines for decentralized wastewater influence provincial approval protocols for imported equipment. The Okanagan Valley cluster concentrates regional distributor networks serving high-density lake community installations.
Aerobic Treatment Units Market Competitive Landscape
Global majors compete with regional champions across technology integration and service reach. The vendor base organizes into three tiers: membrane technology specialists, packaged system fabricators, and turnkey service providers. Two strategic archetypes dominate competitive positioning—engineering-led firms emphasizing process design expertise, and manufacturing-scale operators competing on unit economics. Consolidation pressure manifests through strategic partnerships between membrane suppliers and skid fabricators, alongside geographic expansion via regional distributor acquisitions.
Among technology-anchored specialists, Fluence Corporation exemplifies the membrane-forward archetype, while Orenco Systems Inc. and Bio-Microbics Inc. occupy positions within the engineered packaged systems tier. These three firms represent contrasting approaches to market access—technology licensing versus direct manufacturing versus hybrid configurations—illustrating how competitive positioning fragments across business model choices rather than converging on uniform scale strategies.
| Leading Market Players |
|---|
| Fluence Corporation |
| Orenco Systems Inc. |
| Bio-Microbics Inc. |
| Norweco Inc. |
| Clearstream Wastewater Systems Inc. |
| Jet Inc. |
| Kingspan Environmental Ltd. |
| 3M Purification Inc. |
| Veolia Water Technologies |
| Others |
Value Network & Pricing Analysis
Municipal pre-approval requirements for nitrogen removal capabilities in Florida and North Carolina are compressing supplier margins as engineering documentation costs mount, forcing membrane module fabricators to absorb certification overhead or cede share to vertically integrated rivals with captive testing facilities.
Pricing Analysis
Warranty and service bundling separates premium membrane bioreactor configurations from unbundled packaged residential units where third-party installation risk transfers to local contractors. Three-tier pricing structure across premium, standard, and economy levels reflects NSF/ANSI Standard 40 certification grade and membrane module origin, with Florida state environmental agency approval status commanding measurable premiums. Pricing pressure stems from stainless steel and polymer input cost volatility that erodes fixed-price municipal contract profitability. Residential self-installer segments exhibit highest price sensitivity, while commercial property developers with water reuse mandates prioritize performance guarantees over upfront capital expenditure.
Supply Chain Analysis
NSF/ANSI Standard 245 nutrient certification timelines gate supplier access to Chesapeake Bay and Great Lakes watershed markets, with 18-24 month laboratory testing protocols favoring incumbents with dedicated validation infrastructure. Manufacturing concentrates in the United States, China, and Germany, with the Yangtze River Delta corridor hosting domestic packaged unit production for East Asian export markets. Membrane module housings, diffuser assemblies, and polymer aeration basins draw from petrochemical feedstock chains exposed to commodity price swings. Single-source vulnerability concentrates in ultrafiltration membrane chemistry suppliers with proprietary fouling control formulations. Distribution runs through regional engineering firms bundling design, equipment specification, and long-term service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around turnkey service providers as buyer procurement authority concentrates among regional engineering firms capable of bundling design, equipment, and maintenance accountability.
For Market Incumbents: Extend membrane technology licensing partnerships into captive skid fabrication capabilities to defend against distributor disintermediation by engineering-led turnkey providers. Secure NSF/ANSI Standard 245 pre-approvals in Florida and North Carolina to lock out challengers facing 18-24 month certification timelines. Backward integration into polymer aeration basin manufacturing mitigates commodity cost volatility exposure on fixed-price municipal contracts. For New Entrants and Emerging Players: Enter via remote monitoring subscription services for dispersed residential fleets, leveraging IoT-enabled dissolved oxygen sensors to capture recurring revenue without competing on upfront equipment capital. Target the Texas Hill Country corridor where rocky substrate conditions favor pressure-dosed distribution configurations underserved by incumbent service networks. Partner with regional installers for certified commissioning rather than building captive field technician capacity. For Investors and Strategic Acquirers: The window for entry favors membrane module suppliers with proprietary fouling control chemistries facing downstream integration pressure from skid fabricators seeking technology differentiation. Long-term viability hinges on nutrient removal mandate expansion beyond Chesapeake Bay and Great Lakes watersheds into additional EPA jurisdictions. Watch for EPA Office of Water enforcement intensity signals as replacement cycle acceleration indicators for legacy decentralized system markets.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Licensing | Fluence Corporation anchors premium positioning through proprietary ultrafiltration module supply to skid fabricators. |
| Regional Engineering Firm Acquisition | Turnkey providers capture margin from design-specification-service bundling displacing traditional distributor networks. |
| NSF/ANSI Standard 245 Certification Investment | Pre-approval in Florida and North Carolina creates 18-24 month competitive moats against uncertified challengers. |
| Remote Monitoring Platform Development | IoT-enabled dissolved oxygen sensors generate subscription revenue from dispersed residential fleet maintenance contracts. |
| Pressure-Dosed Distribution Capability Buildout | Texas Hill Country and coastal plain developments demand engineered drip field integration opening service revenue streams. |
Research Methodology
Document review covered EPA Office of Water decentralized wastewater guidelines, NSF International certification protocols, and state environmental agency supplementary standards in Florida, North Carolina, and Texas, complemented by interviews with equipment OEM product managers, regional engineering firm principals, municipal utility planning officers, and specialized installation contractors. Secondary validation drew from Clean Water Act enforcement records, NSF/ANSI Standard 40 and 245 testing documentation, and customs data on membrane module imports. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across rural residential, commercial, and small municipal segments.
Cross-referencing historical certification timeline patterns with expert panel input on nutrient removal mandate diffusion shaped the projection framework across the analysis window. Segmentation dimensions modeled include product configuration, technology type, end-user category, and application performance tier, with geographic regulatory cluster as an additional industry-specific dimension. CAGRs were derived from install base replacement cycle analysis and new construction penetration assumptions, incorporating EPA enforcement intensity scenarios and membrane bioreactor cost curve trajectories as sector-specific forecast inputs.
Revisions become necessary when EPA Office of Water enforcement priorities shift, state environmental agencies impose supplementary performance standards exceeding federal baselines, or membrane module input costs experience sustained volatility outside historical bands. Forecasts reflect documented assumptions regarding certification timeline durations, installer network expansion constraints, and buyer procurement consolidation trends. A model refresh is warranted upon material change in Chesapeake Bay or Great Lakes watershed nutrient removal mandate adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Engineering
Outdoor Noise Barrier Market
Environmental Engineering
Silt Curtain Market
Environmental Engineering
Outdoor Sound Barrier Market
Environmental Engineering
Fume Hoods Market
Environmental Engineering
Global Built and Natural Environment Consulting Market
Environmental Engineering
North America Rainwater Harvesting Market
Environmental Engineering
Tunnel Ventilation and Environmental Monitoring Systems Market
Environmental Engineering
Rainwater Harvesting Market
Environmental Engineering
Septic Tanks Market
Environmental Engineering
Wet Scrubber Market
Environmental Engineering
Dust Control Systems Market
Environmental Engineering
Secondary Water and Wastewater Treatment Equipment Market
Environmental Engineering
Gas Scrubber Market
Environmental Engineering
Global Rainwater Harvesting System Market