
 Sustainable Personal Care Market | 2026-2036
Sustainable Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Personal Care Market Analysis
European biotech fermentation facilities is realigning supply chains for squalane and plant-derived actives used across sustainable personal care formulations. L'Oréal leverages its Green Sciences research platform to anchor biotechnology-derived ingredient pipelines. Unilever competes through its Clean Future program, which targets fossil-fuel-free cleaning and personal care formulations by mid-decade. Biossance specializes in sugarcane-derived squalane, occupying a distinct position in the biotechnology segment of the ingredient market.
Sustainable personal care encompasses cosmetic and hygiene products formulated with renewable, minimally processed ingredients and designed for reduced environmental impact across their lifecycle, typically excluding parabens, sulfates, and synthetic fragrances in favor of plant-derived or biotechnology-produced alternatives. Organic Skincare leads product type revenue due to established consumer willingness to pay premium prices for certified formulations, while Bioplastics packaging is expanding fastest as refill infrastructure scales in specialty retail. Plant-Based ingredient sourcing dominates volume, though Recycled material streams are gaining structural importance as post-consumer resin quality improves for cosmetic-grade applications.
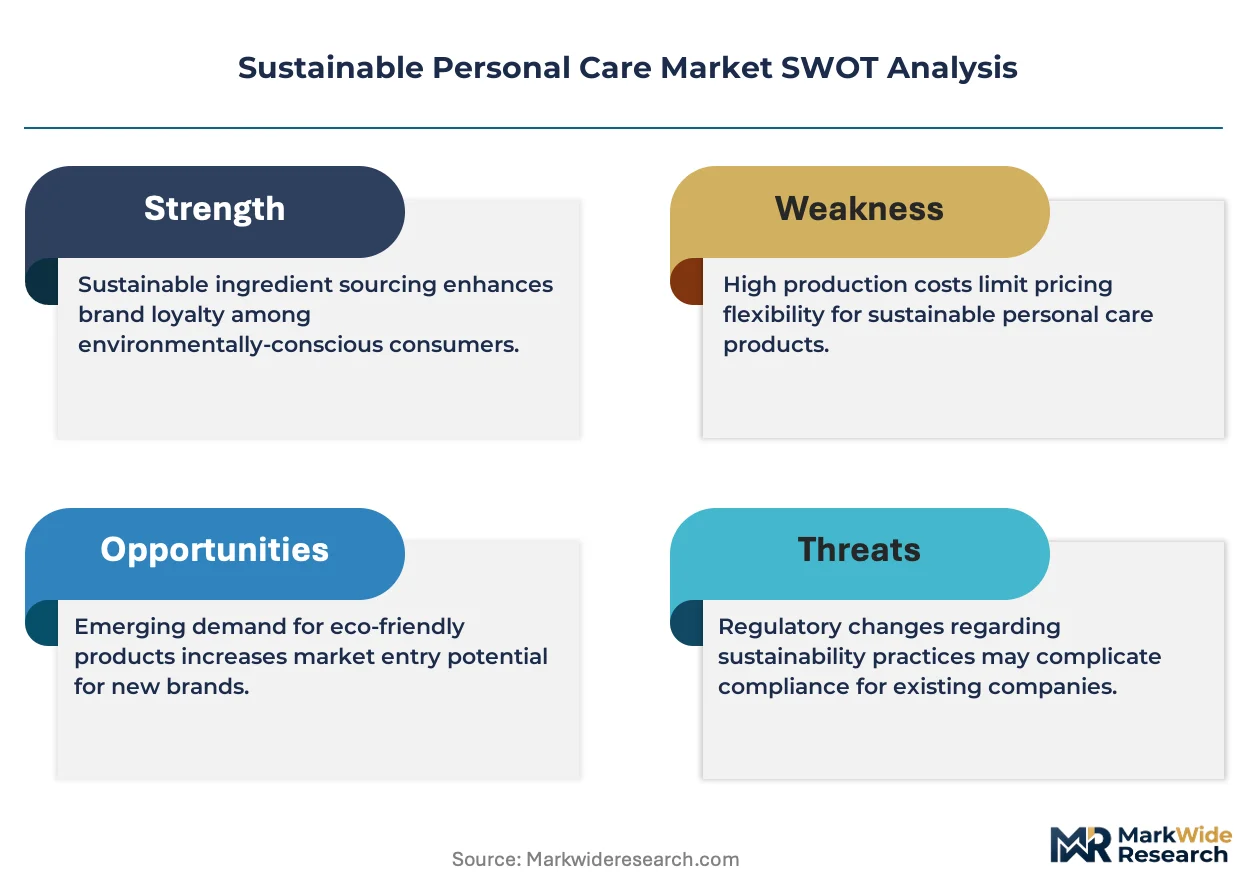
REACH in Europe and the FDA's oversight of cosmetic safety in the United States are tightening chemical disclosure requirements, directly shaping formulation choices and raw material qualification timelines for brands entering these markets. California's Safer Consumer Products regulations and the EU Green Deal's circular economy targets are forcing packaging redesign investments across the value chain. Stakeholders must monitor how evolving extended producer responsibility frameworks in multiple jurisdictions will redistribute cost burdens between brands, contract manufacturers, and packaging suppliers.
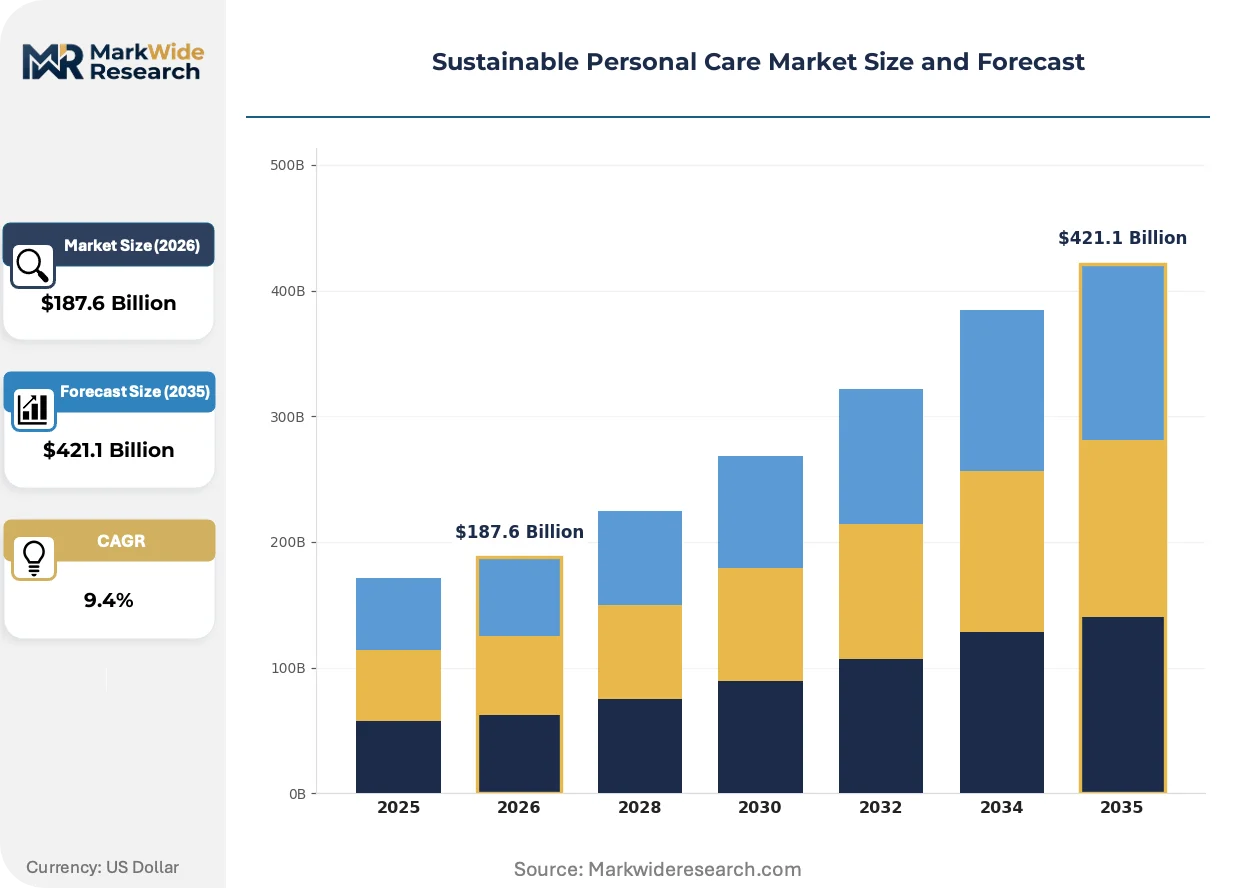
Market Dynamics
Biotechnology-derived ingredient pipelines are restructuring competitive advantage in sustainable personal care, as fermentation-based squalane and plant-derived actives displace petroleum-sourced alternatives across premium formulations.
Growth Catalysts
- REACH compliance deadlines:ECHA disclosure requirements are accelerating reformulation cycles across European brands, pulling through demand for pre-qualified biotech ingredients.
- Refill infrastructure expansion:Specialty retailers in Germany and South Korea are deploying dedicated refill stations, reducing single-use packaging intensity for repeat purchasers.
- Waterless formulation chemistry:Solid shampoo and anhydrous skincare concentrates are cutting shipping volumes and preservative loads for direct-to-consumer brands.
Market Restraints
- Sugarcane feedstock volatility:Brazilian ethanol market fluctuations transmit directly to squalane production costs, squeezing margin structures for biotech ingredient specialists.
- Post-consumer resin quality gaps:Cosmetic-grade recycled plastic streams remain concentrated among European reprocessors, creating supply bottlenecks for North American brands.
- Preservative efficacy limitations:Natural antimicrobial alternatives struggle to match paraben shelf-life performance in water-based formulations, constraining product format options.
Strategic Opportunities
- Brazil retail ecosystem development:São Paulo and Rio de Janeiro are emerging as Latin American hubs for sustainable beauty retail, with local brands capturing unmet demand for certified organic formulations.
- AI-driven personalization:Machine learning tools for skin microbiome analysis are converging with biotech ingredient libraries to enable bespoke product matching at scale.
- Extended producer responsibility frameworks:France's AGEC law and similar measures in Italy are creating compliance-driven demand for packaging-as-a-service business models.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial biologists with cosmetic-grade GMP experience command premium compensation, constraining mid-tier brand R&D expansion.
- Multi-certification timeline compression:Simultaneous pursuit of COSMOS, USDA Organic, and B Corp status extends product launch windows by 12-18 months.
- Legacy ERP integration friction:Batch-level ingredient traceability requirements for EU Green Deal compliance clash with established manufacturing software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Personal Care Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $421.1 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Skincare, Natural Haircare, Eco-Friendly Makeup, Biodegradable Hygiene Ingredient Source: Plant-Based, Mineral, Synthetic-Free, Recycled Packaging Type: Glass, Refillable, Compostable, Bioplastics Target Audience: Eco-Conscious Consumers, Millennials, Wellness Enthusiasts, Luxury Users |
| Companies Covered | Kao Corporation, Biossance, L'Oréal, Ursa Major, Youth to the People, Unilever, Oriflame Cosmetics, OSEA, Estée Lauder Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Personal Care Market Emerging Trajectories
Active fermentation technology is compressing raw material qualification timelines while regulatory disclosure mandates and direct-to-consumer channel expansion are rewiring how sustainable personal care reaches end users.
Precision fermentation for rare plant actives is electrifying ingredient sourcing strategies across premium skincare. Bioreactor-produced bakuchiol and resveratrol are achieving batch consistency impossible with agricultural extraction. Luxury brands in South Korea and France are integrating these inputs into anti-aging lines at 3-5x conventional ingredient premiums.
California's Safer Consumer Products regulations are forcing ingredient disclosure depth that exceeds federal FDA cosmetic safety standards. Brands selling into the state must document full supply chain chemistry or face reformulation mandates. This regulatory drag is accelerating pre-qualification of European REACH-compliant ingredient streams for US market entry.
Subscription-based refill programs are displacing conventional retail replenishment for core personal care categories. Direct-to-consumer brands in Germany and the United Kingdom are bundling aluminum vessel purchases with automated pod shipments. This channel shift concentrates customer data ownership with brands while reducing packaging cost recovery uncertainty.
Sustainable Personal Care Market Segmentation
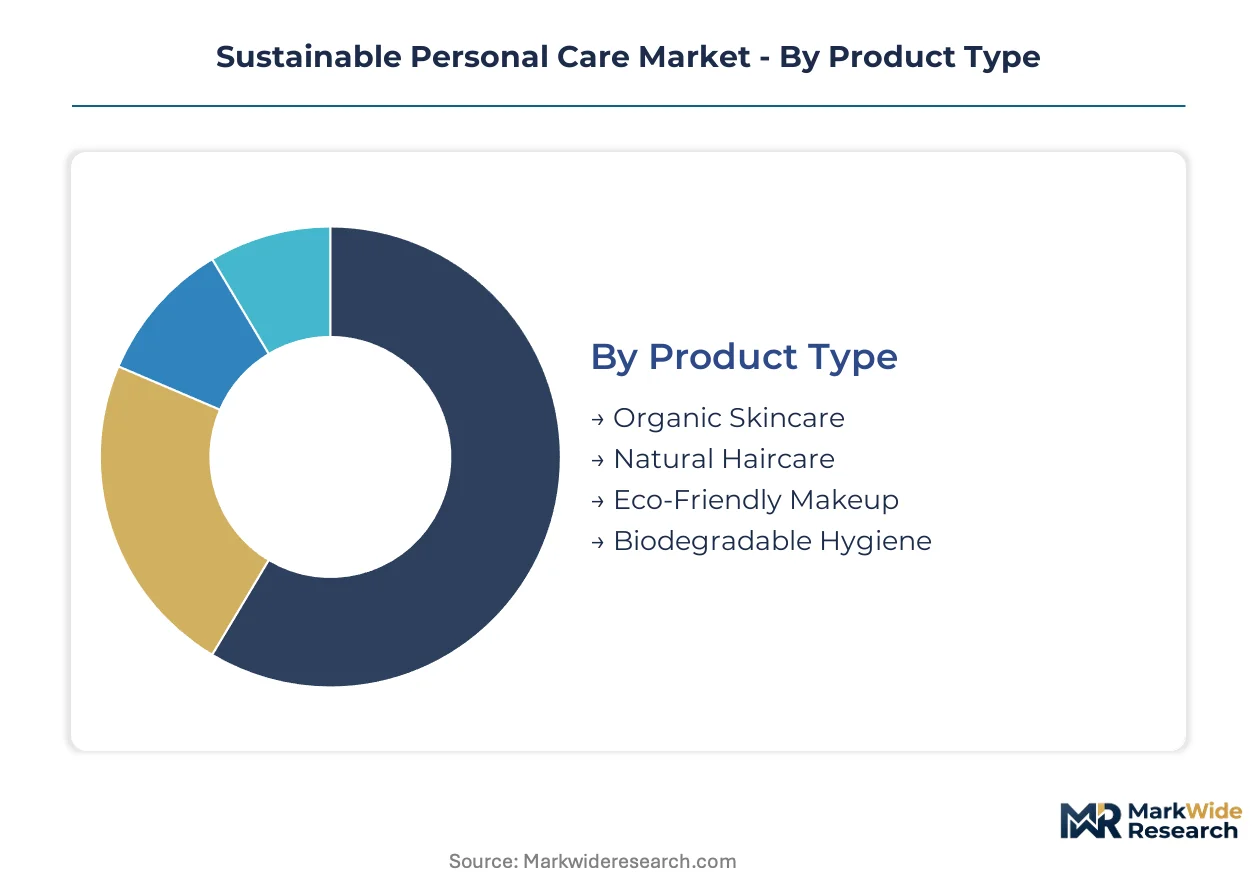
Segmentation in sustainable personal care reveals where capital commitments concentrate and how formulation complexity varies across consumer tiers. Manufacturers allocate R&D budgets differently depending on which segments they target, with certification requirements and packaging infrastructure driving divergent investment profiles.
Product Type:
Capital intensity peaks where certification infrastructure and specialized manufacturing equipment requirements intersect most heavily.
- Organic Skincare:Formulations rely on COSMOS or USDA Organic certified inputs with restricted preservative palettes and cold-process manufacturing. German and French specialty retailers command premium shelf placement for certified lines, though multi-certification timelines extend product development cycles.
- Natural Haircare:Sulfate-free surfactant systems demand specialized emulsion chemistry and pH stabilization protocols. Solid shampoo bars are cutting shipping volumes for direct-to-consumer brands in the United Kingdom and Germany.
- Eco-Friendly Makeup:Mineral pigment sourcing and refillable compact engineering require dual investment in formulation and packaging design.
- Biodegradable Hygiene:Flushable wet wipe alternatives and period products using plant-based absorbent cores face composting infrastructure gaps in most markets.
Organic Skincare absorbs the bulk of installed capacity; Natural Haircare is expanding most quickly.
Ingredient Source:
Supply security considerations dominate procurement strategies as feedstock volatility reshapes sourcing priorities.
- Plant-Based:Agricultural extraction and fermentation-derived actives from sugarcane, algae, and oilseed feedstocks. Brazilian ethanol market fluctuations transmit directly to squalane production economics, squeezing margin structures for biotech specialists.
- Mineral:Zinc oxide, titanium dioxide, and clay-based inputs with established cosmetic-grade purification infrastructure.
- Synthetic-Free:Formulations excluding petroleum-derived inputs entirely, requiring full supply chain documentation for California Safer Consumer Products compliance.
- Recycled:Post-consumer resin streams and upcycled agricultural byproducts, with cosmetic-grade quality concentrated among European reprocessors.
Plant-Based commands the deepest supplier relationships; Recycled is climbing the fastest as post-consumer resin quality improves.
Packaging Type:
Extended producer responsibility frameworks are redistributing cost burdens between brands and packaging suppliers across jurisdictions.
- Glass:Inert barrier properties suit preservative-free formulations but carry weight penalties in shipping economics. French AGEC law compliance is accelerating refill infrastructure deployment for glass vessels.
- Refillable:Aluminum and durable plastic systems with automated pod replenishment. German specialty retailers are deploying dedicated refill stations, concentrating customer data ownership with brands.
- Compostable:Cellulose-based films and molded fiber applications limited by industrial composting facility availability.
- Bioplastics:Fermentation-derived polymers with batch consistency advantages over agricultural alternatives. South Korean luxury brands are integrating these into premium lines at substantial markups.
Glass retains the largest existing installed base; Bioplastics is gaining share fastest as refill infrastructure scales.
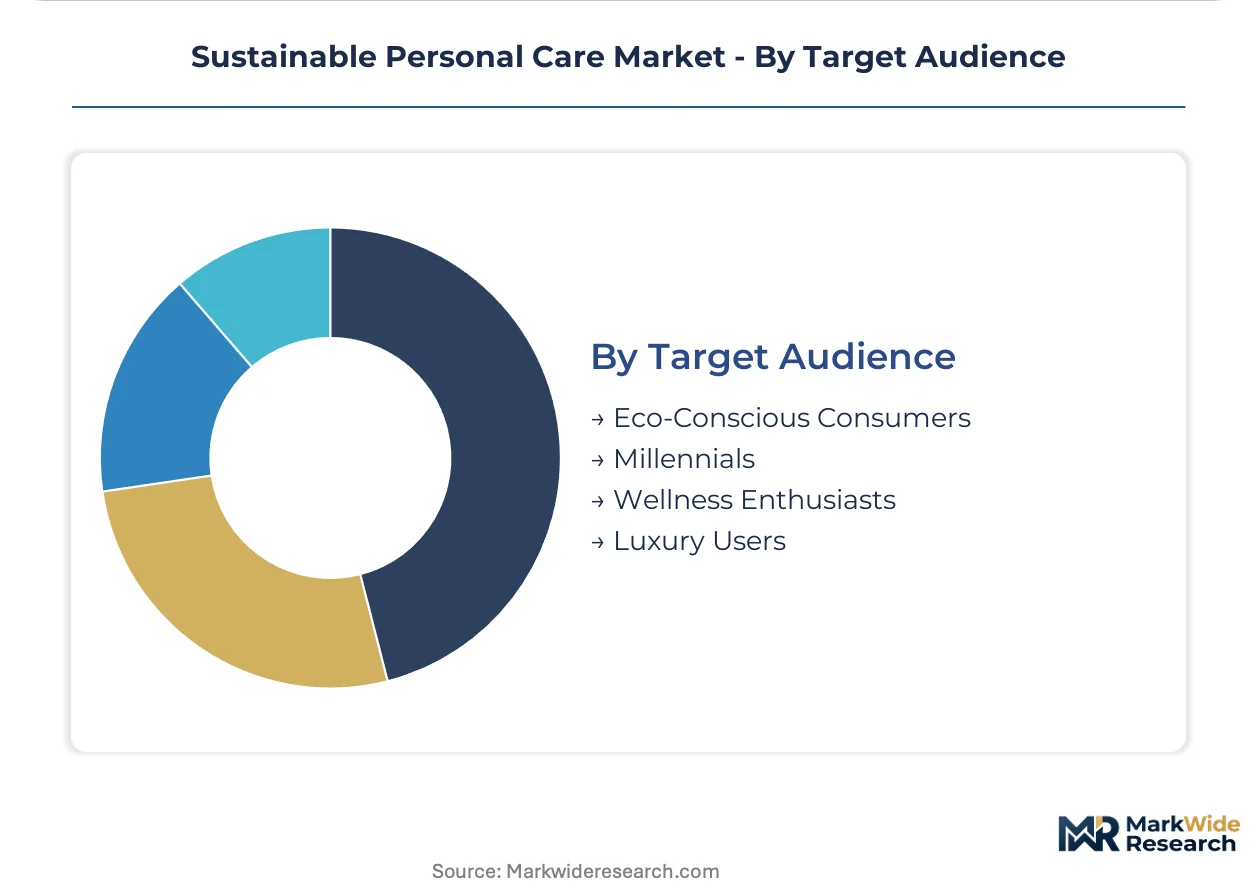
Target Audience:
Pricing power varies sharply across consumer segments based on willingness to pay for certification depth and channel convenience.
- Eco-Conscious Consumers:Certification-driven purchasers prioritizing COSMOS, B Corp, and carbon-neutral claims with price elasticity concentrated in mass retail.
- Millennials:Subscription-oriented buyers responding to direct-to-consumer refill programs with automated replenishment in Germany and the United Kingdom.
- Wellness Enthusiasts:Skin microbiome analysis and personalized formulation matching through AI-driven diagnostic tools.
- Luxury Users:Precision fermentation-derived rare actives at substantial premiums, with South Korean and French brands leading integration of bioreactor-produced bakuchiol and resveratrol.
Eco-Conscious Consumers represent the broadest addressable base; Luxury Users show the steepest expansion trajectory for biotechnology-derived ingredient pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sugarcane plantations in Brazil's São Paulo state anchor the biotechnology feedstock base for fermentation-derived squalane, while German specialty retailers and South Korean luxury brands concentrate demand for premium sustainable formulations.
Germany
Refill station deployment in Berlin and Hamburg specialty stores is accelerating repeat purchase cycles for aluminum vessel systems. ECHA REACH disclosure deadlines are forcing reformulation timelines that favor pre-qualified biotech ingredient streams. The Cologne-Düsseldorf corridor hosts concentrated contract manufacturing capacity for COSMOS-certified skincare lines.
South Korea
Luxury consumers in Seoul's Gangnam district are integrating precision fermentation-derived bakuchiol into anti-aging routines at substantial markups. MFDS cosmetic safety standards are tightening parallel to EU disclosure requirements, creating regulatory alignment for European ingredient imports. Busan-based bioreactor facilities are scaling capacity for rare plant actives.
Brazil
São Paulo and Rio de Janeiro retail ecosystems are capturing unmet Latin American demand for certified organic formulations. ANVISA is advancing ingredient disclosure rules that mirror California's Safer Consumer Products framework. Brazilian ethanol market volatility transmits directly to sugarcane-derived squalane production economics.
United States
California's Safer Consumer Products regulations are forcing full supply chain chemistry documentation that exceeds federal FDA cosmetic safety standards. Direct-to-consumer brands in Los Angeles and New York are bundling aluminum vessel purchases with automated pod replenishment. The Pacific Northwest is emerging as a hub for solid shampoo and waterless formulation chemistry.
France
AGEC law compliance is accelerating refill infrastructure deployment for glass vessels across Parisian specialty retail. L'Oréal's Green Sciences research platform in Clichy is anchoring biotechnology-derived ingredient pipelines for premium skincare. The Provence-Alpes-Côte d'Azur region concentrates agricultural extraction capacity for lavender and botanical actives.
Sustainable Personal Care Market Vendor Landscape
Global majors compete with regional champions across certification depth and biotechnology ingredient access, producing a tiered structure where scale-driven conglomerates, mid-tier specialists, and niche biotech pure-plays occupy distinct competitive positions. Market structure consolidates around three strategic archetypes: fermentation-based ingredient specialists, multi-brand portfolio owners with clean beauty platforms, and direct-to-consumer refill innovators. Dominant competitive moves include backward integration into sugarcane feedstock contracts and strategic partnerships with European reprocessors for cosmetic-grade recycled resin streams.
Within the biotechnology specialist tier, Biossance exemplifies the fermentation-pure-play archetype through its sugarcane-derived squalane positioning, while L'Oréal and Unilever represent scale-driven conglomerates leveraging Green Sciences and Clean Future programs respectively to anchor biotechnology-derived ingredient pipelines across mass and premium segments.
| Leading Market Players |
|---|
| Kao Corporation |
| Biossance |
| L'Oréal |
| Ursa Major |
| Youth to the People |
| Unilever |
| Oriflame Cosmetics |
| OSEA |
| Estée Lauder Companies |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists across Provence and Tuscany anchor premium ingredient supply, their estate-controlled lavender and olive groves enabling pricing discipline through captive botanical sourcing that resists commodity volatility. This ownership pattern concentrates margin capture upstream while forcing contract manufacturers into transparent cost-plus negotiations for certified organic inputs.
Pricing Analysis
Subscription bundling of aluminum vessel purchases with automated pod replenishment separates service-inclusive pricing from transactional retail, with German direct-to-consumer brands capturing recurring revenue streams. Certification depth drives price differentiation, with COSMOS- and B Corp-certified lines commanding substantial premiums over conventional natural claims. Cost compression in mass retail channels is intensifying as private-label entrants replicate core formulation architectures. Eco-conscious consumers in mass retail exhibit highest price elasticity, while luxury users in Seoul and Paris show lowest sensitivity to biotechnology-derived ingredient markups.
Supply Chain Analysis
Squalane production rests on Brazilian sugarcane ethanol processors, German fermentation equipment fabricators, and South Korean bioreactor operators for precision-derived actives. Key inputs include sugarcane feedstock, pharmaceutical-grade fermentation nutrients, and cosmetic-grade post-consumer resin streams. Single-source vulnerability concentrates in European reprocessors qualified for cosmetic-grade recycled plastic. Distribution runs through specialty retail refill stations in Germany, direct-to-consumer subscription platforms in the United Kingdom, and luxury department store counters in South Korea and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation technology is displacing agricultural extraction for rare actives, compressing raw material qualification timelines while restructuring competitive advantage around biotech access rather than land ownership.
For Market Incumbents: Anticipate margin compression from private-label replication of sulfate-free surfactant systems by locking in multi-year sugarcane feedstock contracts before Brazilian ethanol volatility intensifies. Prioritize backward integration into fermentation capacity in the Cologne-Düsseldorf corridor to secure COSMOS-certified manufacturing slots. Defend market position through exclusive partnerships with Busan-based bioreactor facilities for bakuchiol and resveratrol supply security.
For New Entrants and Emerging Players: Specialty retailers with dedicated refill infrastructure offer immediate channel access without slotting fee burdens, particularly in São Paulo and Rio de Janeiro where certified organic demand outpaces local supply. White-space concentrates in waterless formulation chemistry for solid shampoo and anhydrous skincare concentrates. Target wellness enthusiasts through AI-driven skin microbiome personalization tools bundled with biotechnology-derived ingredient subscriptions.
For Investors and Strategic Acquirers: REACH compliance deadline acceleration is the leading indicator that European contract manufacturing capacity will consolidate around qualified biotech ingredient pipelines. Long-term viability favors fermentation-pure-plays with established GMP cosmetic-grade production over agricultural extraction-dependent assets. Acquisition targets should demonstrate locked Brazilian feedstock contracts and active MFDS or ANVISA pre-qualification submissions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Locked sugarcane contracts with São Paulo ethanol processors insulate squalane margins from commodity swings. |
| Refill Infrastructure Partnership | Collaboration with Berlin and Hamburg specialty retailers concentrates customer data ownership and repeat purchase velocity. |
| Precision Fermentation Scale-Up | Busan bioreactor capacity expansion enables batch-consistent bakuchiol supply for South Korean luxury brands. |
| Multi-Certification Investment | Simultaneous COSMOS, B Corp, and EU Green Deal compliance extends product launch timelines but secures premium shelf placement. |
| Direct-to-Consumer Platform Launch | Subscription bundling of aluminum vessels with automated pod replenishment displaces conventional retail replenishment economics. |
Methodological Framework
Independent corroboration across brand R&D directors, specialty retail category buyers, contract manufacturing procurement leads, and biotechnology fermentation scientists underwrites the qualitative findings in this study. Primary interviews with these stakeholders combined with secondary validation from ECHA REACH disclosure databases, ANVISA regulatory filings, and MFDS cosmetic safety standards. Bottom-up triangulation across ingredient supplier revenue disclosures and top-down reconciliation with retail audit data from German and South Korean specialty channels anchored the market sizing envelope.
Comparable-period anchoring to historical certification timeline data and refill infrastructure deployment rates structured the forecast window across the analysis window. Segmentation dimensions modeled include product type complexity, ingredient source dependency, packaging format circularity, and target audience willingness-to-pay tier. CAGRs were derived from regression-weighted growth rate convergence across these segments. Industry-specific inputs incorporated Brazilian ethanol market volatility indices and post-consumer resin quality improvement trajectories from European reprocessors.
Caveats apply where ANVISA disclosure rule acceleration, Brazilian sugarcane harvest failures, or sudden REACH enforcement tightening could materially shift the outlook. Forecasts reflect documented assumptions about certification timeline compression and refill station deployment velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
Bangladesh Shampoo Market
Beauty & Personal Care
Facial Steamer Market
Beauty & Personal Care
Deodorant Wipes Market
Beauty & Personal Care
Global Bath Bomb Market
Beauty & Personal Care
BB Cushions Market
Beauty & Personal Care
Asia Pacific Beauty Fridges Market
Beauty & Personal Care
Aluminium-Free Deodorants Market
Beauty & Personal Care
Luxury Bath and Body Products Market
Beauty & Personal Care
GCC Male Grooming Products Market
Beauty & Personal Care
Canada Dermocosmetics Market
Beauty & Personal Care
DIY Face Mask Machine Market
Beauty & Personal Care
Facial Care Market
Beauty & Personal Care
Natural Cosmetics Market
Beauty & Personal Care
Asia-Pacific Perms and Relaxants Market
Beauty & Personal Care
Cosmetics and Toiletries Market