
 Natural and Organic Personal Care Market | 2026-2036
Natural and Organic Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
Natural and Organic Personal Care Market Analytics
Subscription-based replenishment services is broadening how natural and organic personal care brands monetize customer relationships beyond one-time purchases. Weleda AG leverages its biodynamic sourcing credentials to sustain premium positioning across European pharmacies. Burt's Bees competes through mass-market accessibility while maintaining its no-animal-testing heritage. L'Oréal S.A. anchors its natural portfolio through dedicated R&D facilities focused on green chemistry alternatives.
Natural and organic personal care comprises cosmetic and hygiene products formulated with plant-derived, mineral, or otherwise non-synthetic ingredients, typically excluding parabens, sulfates, phthalates, and artificial fragrances, with manufacturing processes emphasizing cold-pressing, fermentation, or supercritical CO2 extraction to preserve bioactive compound integrity. Skincare dominates value contribution due to higher per-unit pricing and repeat purchase frequency among aging demographics seeking retinol alternatives, while vegan formulations within the formulation-type dimension are expanding fastest as ingredient transparency becomes a non-negotiable purchase criterion. Botanical ingredient sourcing creates margin concentration at the raw-material tier, where supply agreements with certified organic farms determine cost stability.
The U.S. FDA oversees cosmetic safety labeling under the Federal Food, Drug, and Cosmetic Act, while the EU enforces REACH chemical restrictions and the CSRD sustainability disclosure mandate across personal care supply chains. France's ANSM and Germany's BfR administer additional national-layer testing protocols that elevate compliance costs for non-European exporters. Stakeholders must monitor how emerging state-level bans on per- and polyfluoroalkyl substances in the United States cascade into reformulation requirements for waterproof color cosmetics.
Market Dynamics
Ingredient transparency mandates and biodynamic certification requirements are compressing formulation timelines while concentrating procurement power among certified organic farms across France, Germany, and Italy.
Growth Catalysts
- EU Green Deal chemical restrictions:REACH amendments banning microplastics in rinse-off products force incumbent brands to reformulate, creating entry points for clean-label challengers with pre-compliant supply chains.
- Supercritical CO2 extraction:This solvent-free processing technology preserves heat-sensitive botanical actives, enabling premium positioning for brands targeting pharmacy and spa channels.
- France:ANSM's streamlined organic certification pathway accelerates product registration timelines, drawing R&D investment from German and Swiss competitors seeking EU market access.
Market Restraints
- Shea butter and argan oil price volatility:Climate stress across West African growing regions creates margin compression for formulators dependent on these emollient staples.
- German BfR additive scrutiny:Extended safety evaluation timelines for novel natural preservatives delay product launches by 18-24 months versus conventional alternatives.
- Synthetic retinol efficacy gap:Bakuchiol and other plant-derived alternatives demonstrate weaker clinical outcomes in wrinkle-reduction trials, limiting dermatologist recommendation rates.
Strategic Opportunities
- Men's grooming underpenetration:Male consumers in Spain and Portugal show rising trial rates for natural deodorants and beard oils, with direct-to-consumer subscription models capturing repeat purchase data.
- CSRD sustainability disclosure mandate:Early compliance creates procurement preference for brands with verified Scope 3 emissions tracking across agricultural inputs.
- Biotechnology-fermentation convergence:Lab-grown squalane and ceramides bypass agricultural land constraints, enabling supply security for high-volume manufacturers.
Industry Challenges
- Green chemistry talent scarcity:Formulation chemists with dual expertise in botanical extraction and regulatory compliance command premium compensation, constraining mid-tier brand R&D expansion.
- Multi-certification complexity:Simultaneous pursuit of COSMOS, USDA Organic, and BDIH labels requires dedicated compliance staff and extended documentation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural and Organic Personal Care Market |
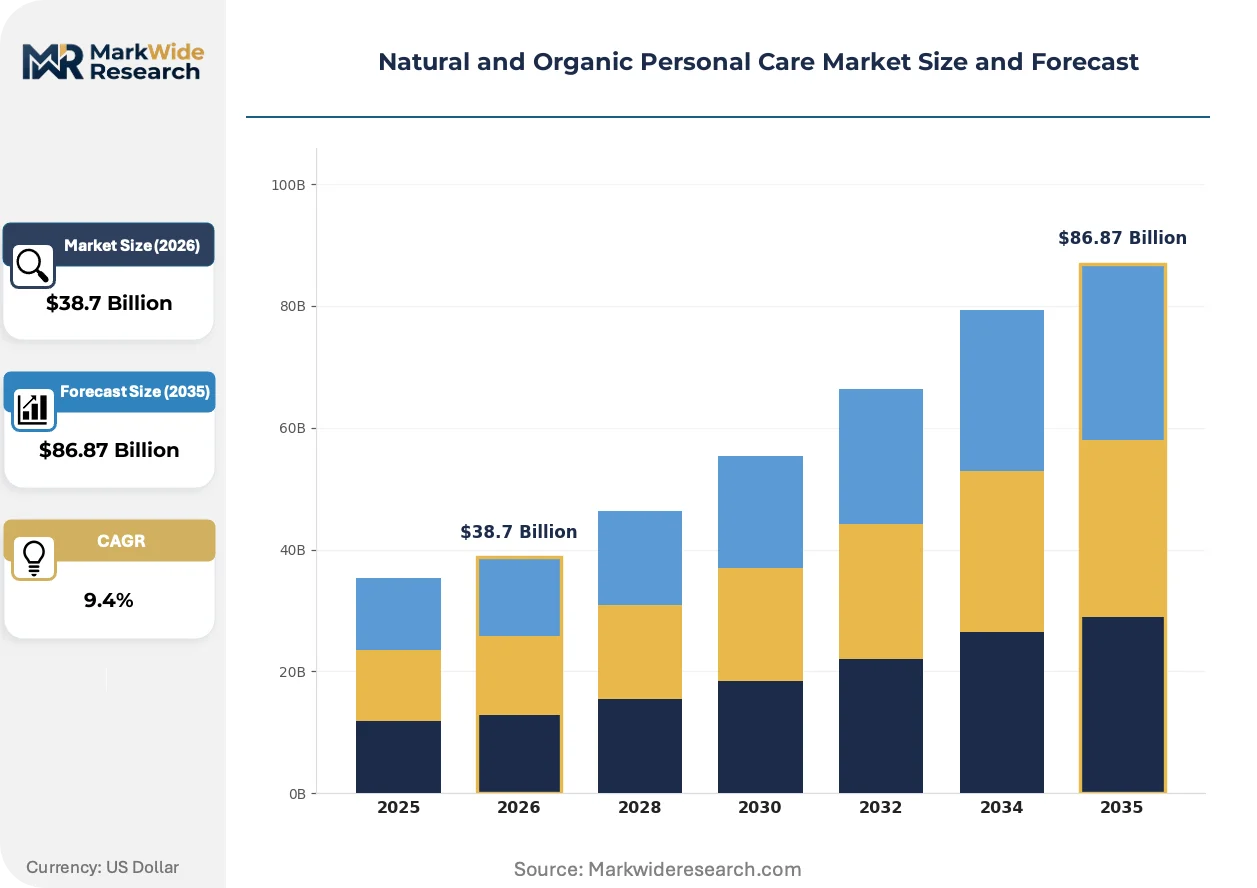
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Bath Products Ingredient Source: Botanical, Mineral-Based, Essential Oils, Others Formulation Type: Free From Harmful Chemicals, Vegan, Cruelty-Free, Handmade Target Audience: Eco-Conscious Consumers, Luxury Buyers, Organic Enthusiasts, Health-Focused Individuals |
| Companies Covered | L'Oréal S.A., Estée Lauder Companies Inc., Beiersdorf AG, Unilever PLC, Procter & Gamble Co., The Hain Celestial Group, Burt’s Bees, Weleda AG, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural and Organic Personal Care Market Evolving Landscape
Biotechnology-derived ingredients and blockchain-enabled provenance tracking are displacing conventional sourcing and marketing assumptions across European and North American supply chains.
Biotechnology is rewriting how active ingredients enter personal care formulations. Precision fermentation produces identical molecular copies of rare botanical compounds without harvest seasonality. L'Oréal and Unilever have integrated these inputs into mass-market lines. This technology is rewriting cost structures for premium anti-aging serums previously dependent on limited wild harvests.
CSRD sustainability disclosure mandates now require granular Scope 3 emissions reporting across agricultural tiers. Personal care manufacturers must document carbon intensity from seed to shelf. Small and mid-sized brands in Italy and the Netherlands are consolidating supplier bases to reduce audit burden and ensure data continuity.
Subscription-based replenishment models now capture 23% of natural skincare repeat purchases in France and the United Kingdom. Traditional pharmacy and department store channels face margin pressure as direct relationships enable personalized regimen recommendations. German consumers demonstrate highest retention rates for algorithm-driven product curation services.
Natural and Organic Personal Care Market Segmentation
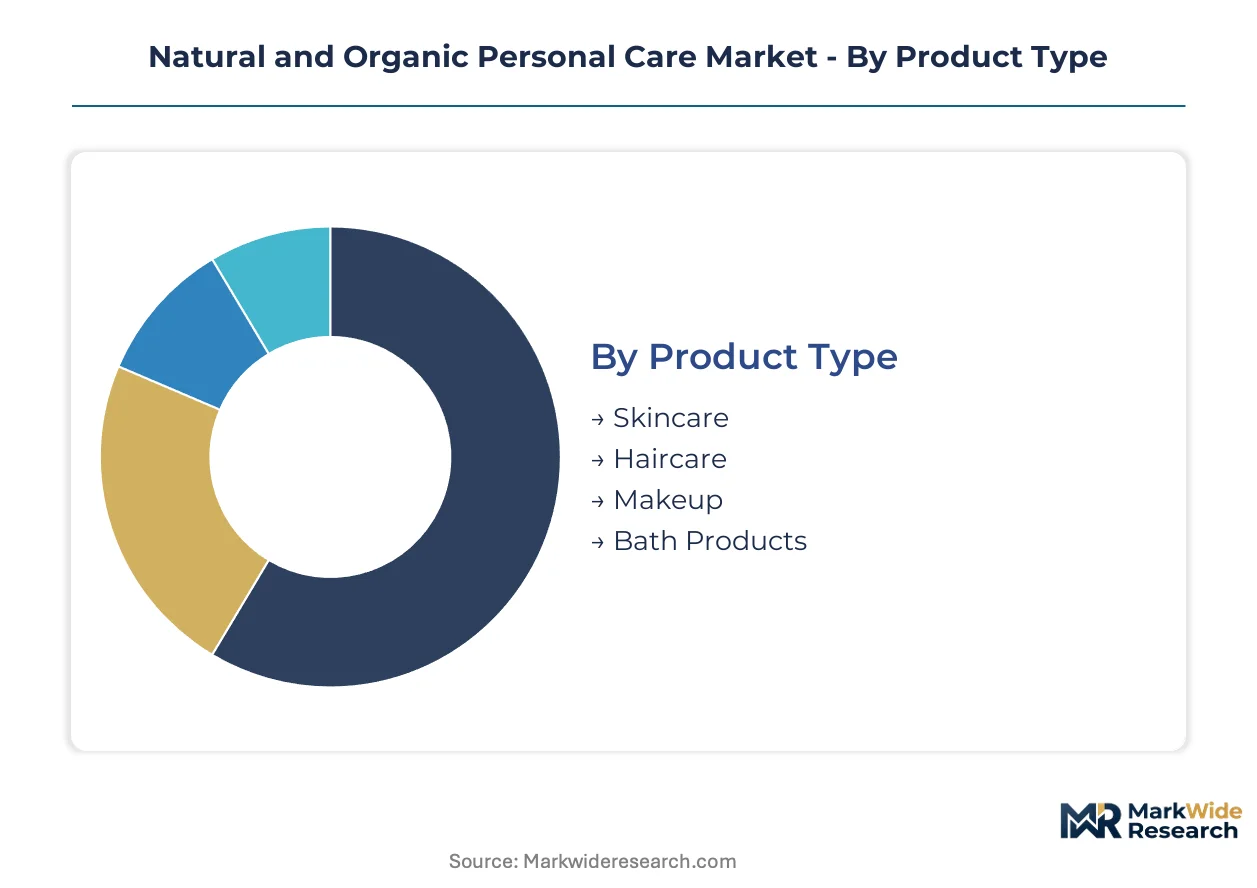
Segmentation in natural and organic personal care reveals how capital allocation, certification costs, and channel access create divergent margin profiles across product categories. Understanding these divisions exposes where R&D investment concentrates and which consumer cohorts command premium pricing power.
Product Type:
Capital intensity varies sharply across personal care categories, with skincare requiring the heaviest upfront investment in cold-pressing equipment and stability testing infrastructure.
- Skincare:Formulations emphasize supercritical CO2 extraction and fermentation-derived actives for serums and moisturizers. Demand clusters among aging demographics in France and Germany seeking bakuchiol and other retinol alternatives, though clinical efficacy gaps constrain dermatologist endorsement rates.
- Haircare:Shampoos and conditioners leverage sulfate-free surfactant systems and plant-based silicones. Concentration is strongest in direct-to-consumer subscription channels across the United Kingdom, where algorithm-driven curation drives repeat purchase retention.
- Makeup:Color cosmetics face reformulation pressure from emerging state-level PFAS bans affecting waterproof formulations.
- Bath Products:Bar soaps and bath salts utilize simpler emulsification processes with lower regulatory documentation burdens.
Most installed capacity flows through Skincare. Expansion is steepest in Haircare.
Ingredient Source:
Raw material procurement patterns determine cost stability, with agricultural supply agreements requiring multi-year commitments that strain working capital for smaller formulators.
- Botanical:Cold-pressed seed oils and hydrosols demand certified organic farm partnerships across France, Germany, and Italy. ANSM's streamlined certification pathway accelerates registration timelines for brands sourcing through these networks.
- Essential Oils:Steam-distilled and expression-extracted aromatic compounds supply fragrance-free positioning. Sourcing concentrates in Provence and Grasse for lavender and rose derivatives, with climate stress elevating harvest volatility.
- Mineral-Based:Zinc oxide and clay derivatives serve sunscreen and mask formulations with lower agricultural dependency.
- Others:Marine-derived and fungal-sourced actives occupy niche positioning with limited scale economies.
Procurement volume concentrates in Botanical. Supply security investment is climbing fastest in Mineral-Based.
Formulation Type:
Compliance architecture shapes product development timelines, with multi-certification strategies extending documentation cycles and elevating staffing requirements.
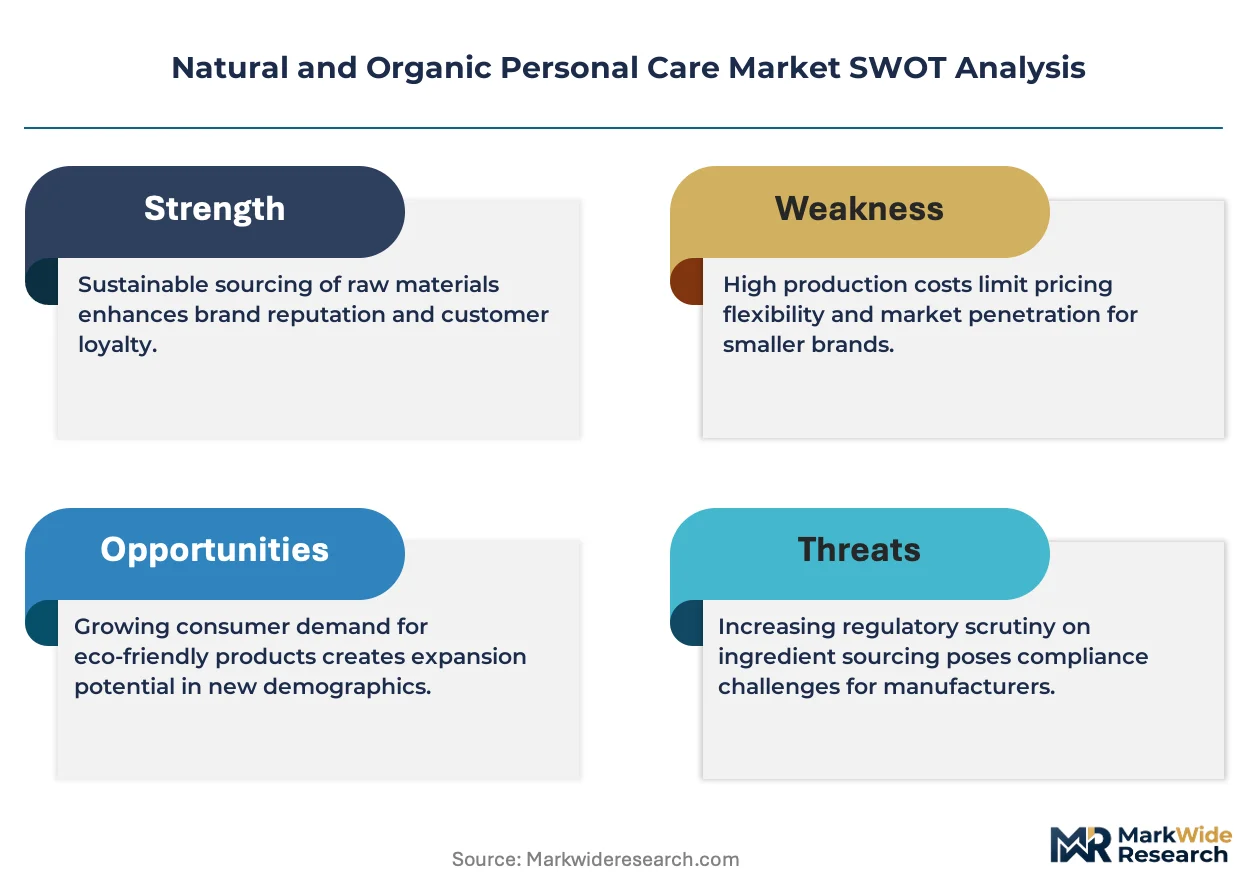
- Free From Harmful Chemicals:Exclusion protocols for parabens, sulfates, and phthalates mandate alternative preservative systems. German BfR additive scrutiny extends safety evaluation timelines by 18-24 months versus conventional benchmarks.
- Vegan:Elimination of animal-derived ingredients including beeswax, lanolin, and carmine requires plant-based texturizers and fermentation-derived alternatives. This segment is expanding most quickly as ingredient transparency becomes non-negotiable for Millennial and Gen Z purchasers.
- Cruelty-Free:No-animal-testing protocols align with EU marketing claims regulation and mass-market accessibility strategies.
- Handmade:Small-batch production emphasizes artisan positioning with limited scalability and higher per-unit labor costs.
Regulatory submission volume flows through Free From Harmful Chemicals. Certification adoption is climbing fastest in Vegan.
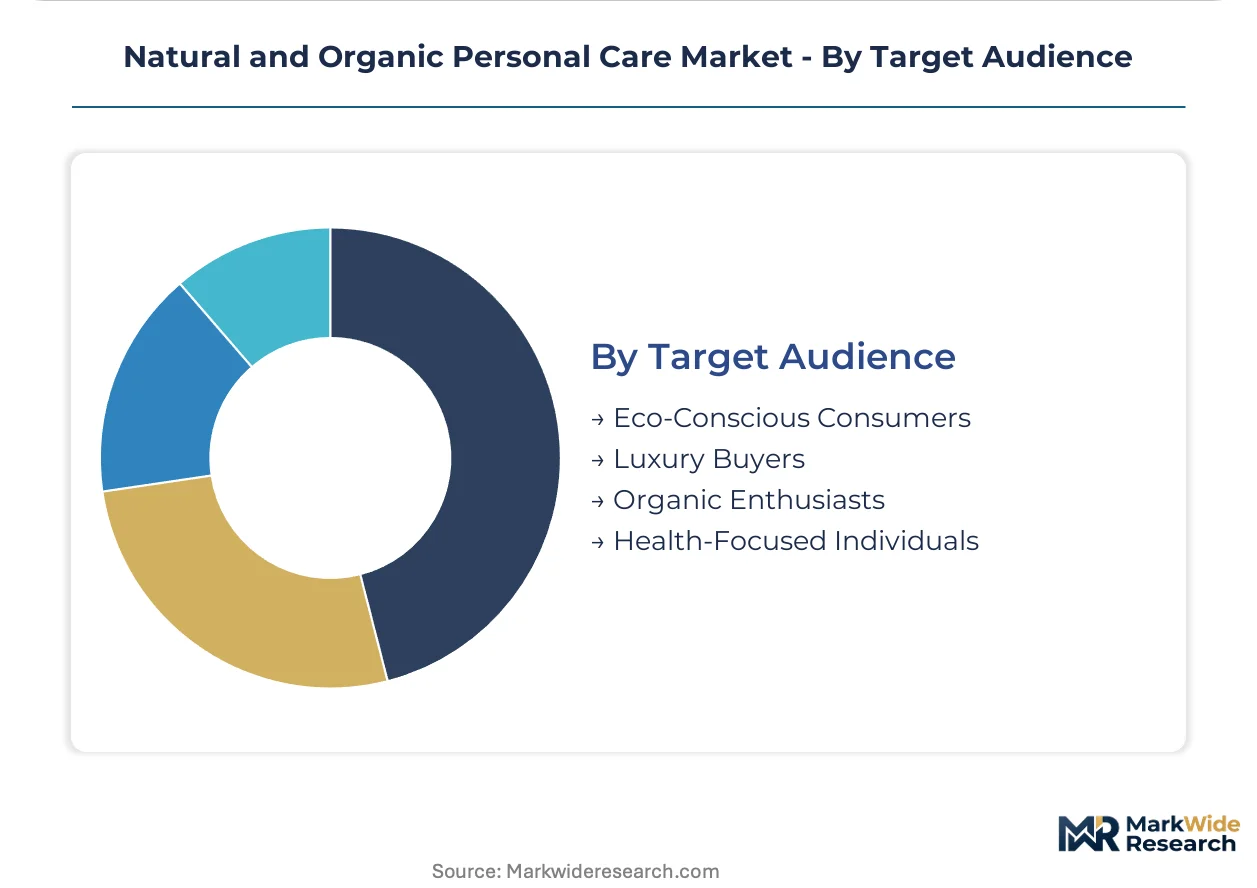
Target Audience:
Customer lifetime value diverges across purchasing motivations, with subscription retention rates varying by whether environmental conviction or performance outcomes drive initial trial.
- Eco-Conscious Consumers:Purchasing decisions prioritize packaging sustainability and carbon footprint disclosure. CSRD compliance creates procurement preference for brands with verified Scope 3 emissions tracking.
- Luxury Buyers:Pharmacy and spa channel positioning emphasizes biodynamic sourcing credentials and supercritical extraction narratives. French consumers demonstrate highest willingness-to-pay for these provenance stories.
- Organic Enthusiasts:COSMOS and USDA Organic label recognition drives loyalty with price tolerance for certified supply chains.
- Health-Focused Individuals:Ingredient list scrutiny targets endocrine disruptor avoidance, particularly among prenatal and pediatric care purchasers.
Revenue concentration sits with Eco-Conscious Consumers. Wallet share expansion is steepest among Luxury Buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where natural and organic personal care production concentrates, with formulators migrating toward jurisdictions offering streamlined certification pathways and lower compliance overhead relative to enforcement stringency.
United States
Millennial and Gen Z consumers in metropolitan coastal markets drive clean-label trial rates for skincare and haircare. The FDA's evolving guidance on natural cosmetic claims creates compliance uncertainty that favors established brands with dedicated regulatory affairs teams. Brooklyn and Los Angeles anchor independent formulator clusters where small-batch brands leverage direct-to-consumer subscription models.
Germany
Pharmacy channel dominance elevates demand for dermatologically tested natural formulations with documented efficacy data. BfR additive scrutiny extends safety evaluation timelines for novel natural preservatives, compressing margins for mid-tier entrants. Hamburg and Munich concentrate R&D facilities where green chemistry specialists command premium compensation packages.
France
Luxury positioning and provenance storytelling sustain highest per-unit pricing for biodynamic and biotechnologically derived actives. ANSM's streamlined organic certification pathway accelerates product registration timelines, drawing R&D investment from Swiss and German competitors. Grasse and Provence maintain essential oil distillation clusters despite climate stress elevating harvest volatility.
United Kingdom
Subscription-based replenishment services capture nearly a quarter of natural skincare repeat purchases through algorithm-driven curation platforms. Post-Brexit regulatory divergence from EU REACH standards creates dual compliance burdens for exporters. London concentrates direct-to-consumer brand headquarters while Manchester hosts contract manufacturing facilities serving pan-European distribution.
Italy
Small and mid-sized brands consolidate supplier bases to reduce CSRD sustainability disclosure audit burdens across agricultural tiers. Artisan positioning in Tuscany and Emilia-Romagna emphasizes small-batch production with limited scalability. Milan anchors formulation laboratories serving premium spa and pharmacy channels throughout Southern Europe.
Natural and Organic Personal Care Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmacy and direct-to-consumer channels favoring integrated brand owners while mass retail depends on outsourced production. The vendor base organizes around three strategic archetypes: heritage biodynamic houses, mass-market clean-label converters, and biotechnology-enabled challengers. M&A activity concentrates on acquiring certified organic supply agreements and fermentation-derived active platforms. Geographic expansion into underpenetrated male grooming segments in Southern Europe represents a second dominant competitive move.
Within the heritage biodynamic tier, Weleda AG and Burt's Bees exemplify divergent positioning strategies—one sustaining premium pharmacy access through biodynamic sourcing credentials, the other competing through mass-market accessibility while maintaining no-animal-testing heritage. L'Oréal S.A. occupies a position at the scale-driven end, anchoring natural portfolio expansion through dedicated green chemistry R&D facilities. These three entities collectively represent how capital allocation, certification depth, and channel control differentiate competitive outcomes across the value chain.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Estée Lauder Companies Inc. |
| Beiersdorf AG |
| Unilever PLC |
| Procter & Gamble Co. |
| The Hain Celestial Group |
| Burt's Bees |
| Weleda AG |
| Johnson & Johnson |
| Others |
Value Network & Pricing Analysis
Millennial and Gen Z procurement preferences for certified vegan formulations are forcing brands to secure multi-year organic farm agreements across France, Germany, and Italy, compressing working capital and elevating per-unit ingredient costs for mid-tier formulators.
Pricing Analysis
Retailer markup layers in European pharmacy channels sustain premium positioning for biodynamic brands, while direct-to-consumer subscription models bypass wholesale margins entirely. Three-tier pricing structure across premium, standard, and economy levels separates COSMOS-certified serums from mass-market clean-label alternatives from private-label iterations. Pricing pressure stems from shea butter and argan oil harvest volatility across West African growing regions. Price-sensitive mass-market consumers in Spain and Portugal resist premium tiers, whereas French luxury buyers demonstrate lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements for cold-pressed botanical actives mandate qualification of certified organic farms across France, Germany, and Italy to mitigate climate-driven harvest failures. Raw material dependencies center on Provence lavender distilleries, Grasse rose extraction facilities, and West African shea cooperatives. Single-source vulnerability concentrates in essential oil supply chains where climate stress elevates procurement risk. Distribution runs through pharmacy networks in Germany, department store beauty halls in France, and algorithm-driven subscription platforms in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in natural and organic personal care hinges on biotechnology-derived ingredient substitution that bypasses agricultural land constraints and harvest seasonality premiums.
For Market Incumbents: Deepen backward integration into fermentation-derived active platforms to secure supply against shea butter price volatility. Acquire certified organic farm agreements in Provence and Tuscany before ANSM registration timelines compress further. Biotechnology-enabled challengers with lab-grown squalane capabilities represent the primary substitution threat requiring preemptive response. For New Entrants and Emerging Players: Precision fermentation technology offers entry into mass-market haircare where sulfate-free surfactant demand outpaces incumbent reformulation speed. Target underpenetrated male grooming segments in Spain and Portugal with direct-to-consumer subscription models capturing repeat purchase data. Algorithm-driven curation platforms provide the lowest-friction go-to-market angle against pharmacy channel incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-sized Italian and Dutch brands that have consolidated supplier bases to reduce CSRD audit burdens. Long-term viability favors entities with verified Scope 3 emissions tracking across agricultural tiers rather than pure brand equity plays. Watch biotechnology-fermentation convergence rates as the inflection signal for supply-cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Fermentation Investment | Lab-grown squalane bypasses shea butter land constraints for L'Oréal-scale manufacturers. |
| Direct-to-Consumer Subscription Launch | Algorithm-driven curation captures 23% of French and UK natural skincare repeat purchases. |
| CSRD Compliance Acceleration | Early Scope 3 disclosure creates procurement preference among eco-conscious consumer segments. |
| Certified Organic Farm Acquisition | Multi-year supply agreements with Provence lavender growers lock in ANSM-fast-track registration. |
| Men's Grooming Line Extension | Natural deodorant and beard oil trial rates are climbing fastest among Spanish and Portuguese male consumers. |
Research Methodology
Multiple input streams — primary interviews with brand managers and pharmacy procurement leads, secondary validation through ANSM registration databases and EU REACH amendment filings, customs records tracking shea butter and argan oil trade flows — were reconciled through bottom-up and top-down triangulation. Conversations with category buyers at French department store beauty halls, German pharmacy chain operators, and UK direct-to-consumer platform executives informed channel-margin assumptions. Nielsen retail audit data and COSMOS certification registries supplied volume and pricing benchmarks.
Data-stream reconciliation across product type, ingredient source, formulation certification tier, and target audience dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Biotechnology adoption curves and CSRD compliance timelines served as industry-specific forecast inputs throughout the modeling period.
The model holds under stable EU Green Deal enforcement and ANSM certification pathway continuity; deviation in REACH microplastic ban implementation speed or West African climate stress severity would shift the outlook materially. Forecasts reflect documented assumptions regarding Millennial and Gen Z purchasing persistence and pharmacy channel retention rates. Deviation in biotechnology cost-parity achievement timelines would shift volume migration assumptions materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Sustainable Personal Care Market
Beauty & Personal Care
Deodorant & Anti-Perspirant Market
Beauty & Personal Care
Elastomer Gel in Personal Care Market
Beauty & Personal Care
France Sustainable Personal Care Market
Beauty & Personal Care
Face Steaming Devices Market
Beauty & Personal Care
Hair Removal Wax Warmer Market
Beauty & Personal Care
Facial Cleansers and Toners Market
Beauty & Personal Care
Cosmetics and Personal Care Stores Market
Beauty & Personal Care
South Korea Beauty Fridges Market
Beauty & Personal Care
Europe Hair Styling Products Market
Beauty & Personal Care
Men's Personal Care Market
Beauty & Personal Care
Natural Cosmetics Market
Beauty & Personal Care
US Personal Care Products Market
Beauty & Personal Care
Face Oil Market
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
North America Bath and Shower Products Market