
 Beauty Tools Market | 2026-2036
Beauty Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Beauty Tools Market Analysis
Professional salons and certified aestheticians are reorganizing procurement priorities toward ergonomically optimized implements. L'Oréal Group leverages its dermatological research infrastructure to anchor premium tool development. Koninklijke Philips N.V. dominates electronic cleansing and massaging devices through patented micro-vibration platforms. Estée Lauder extends brand equity from color cosmetics into coordinated brush systems that occupy dedicated retail fixtures.
Beauty tools comprise handheld implements and powered devices engineered from synthetic filaments, medical-grade silicone, sustainably harvested wood, or anodized aluminum, designed for product application, skin preparation, or hair manipulation. Manufacturing tolerances for ferrule crimping and bristle density directly determine pigment pickup efficiency and surface contact uniformity. Brushes and sponges sustain the largest revenue footprint due to replacement cycles and shade-specific accumulation by consumers. Electronic functionality segments centered on exfoliating and massaging modalities are recording the fastest trajectory as at-home device protocols gain adherence. Material differentiation around silicone and metal compositions is concentrating margin pools where antimicrobial claims and thermal conductivity properties command price premiums.
The FDA regulates powered beauty tools as Class I or II medical devices when therapeutic claims attach, while the EU MDR and REACH frameworks govern biocompatibility and chemical substance restrictions across European distribution channels. The FTC monitors advertising substantiation for clinical efficacy claims in the United States, creating compliance cost barriers for entrants lacking established regulatory affairs capacity. Stakeholders must monitor evolving classification boundaries between cosmetic and medical device jurisdictions as jurisdictions recalibrate oversight frameworks for LED and microcurrent technologies.
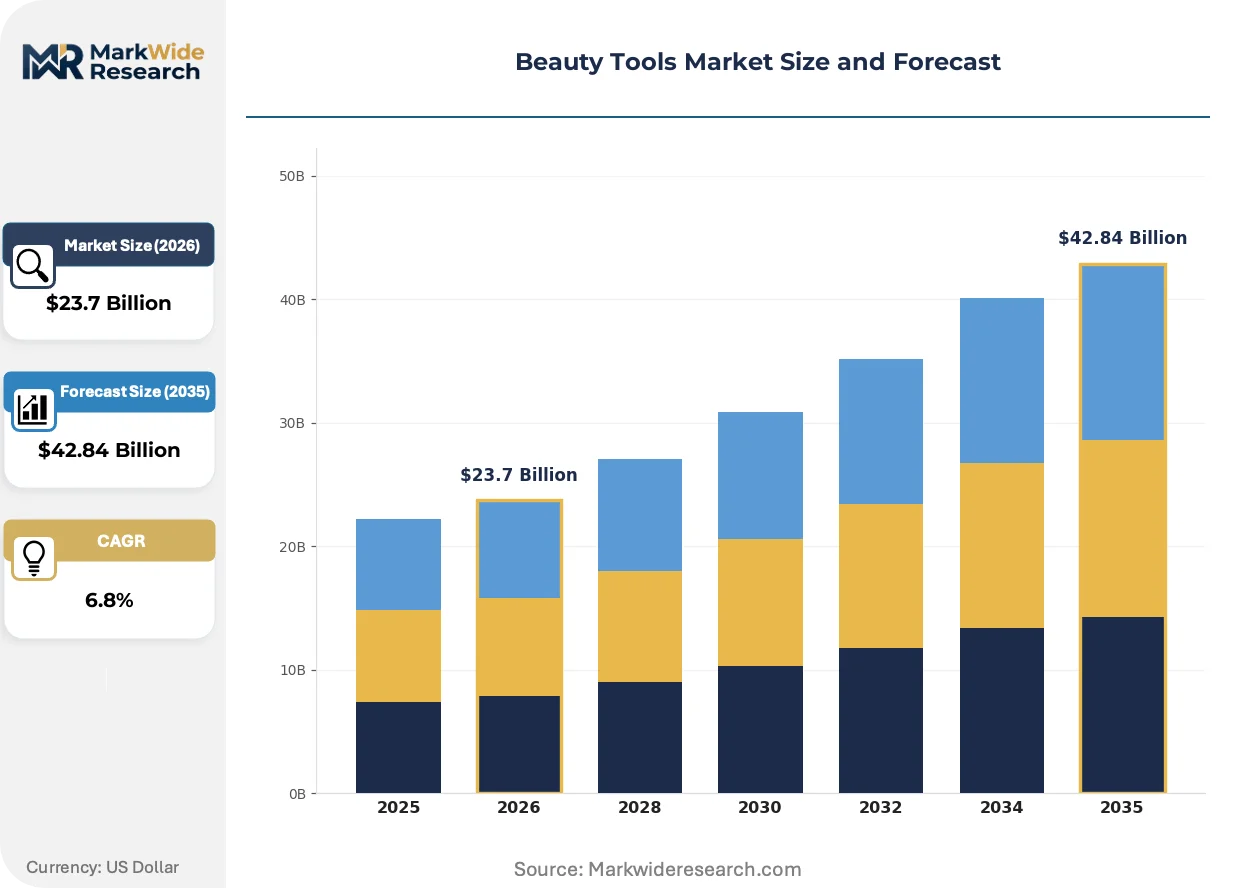
Market Dynamics
Professional salon procurement is reorganizing around precision-engineered implements as EU MDR and REACH frameworks tighten material compliance requirements, forcing manufacturers to recertify component supply chains and elevating barriers for undifferentiated commodity suppliers.
Growth Catalysts
- EU MDR material compliance:Regulatory pressure on biocompatibility and chemical substance restrictions is accelerating technician upgrades to certified implements, creating replacement demand across European professional channels.
- Silicone thermal conductivity:Antimicrobial claims and heat-transfer properties in medical-grade silicone compositions command price premiums, concentrating margin pools for differentiated suppliers.
- United States specialty retail:Direct-to-consumer channels and dedicated shelf space expansion for premium tool assortments is pulling inventory allocation toward higher-margin electronic cleansing and massaging devices.
Market Restraints
- Anodized aluminum supply concentration:Ferrule crimping precision depends on consistent metal sourcing, with limited qualified suppliers creating input vulnerability for brush manufacturers.
- FDA classification ambiguity:Therapeutic claims on powered exfoliating tools trigger Class II medical device pathways, extending approval timelines and compliance costs for LED and microcurrent technologies.
- Synthetic filament substitution:Sustainably harvested wood and biodegradable alternatives threaten conventional nylon bristle demand as environmental claims reshape consumer preference hierarchies.
Strategic Opportunities
- At-home device protocols:Electronic functionality segments in exfoliating and massaging modalities are recording accelerated trajectory as consumers adopt professional-grade routines outside salon settings.
- FTC substantiation pathways:Clinical efficacy claim frameworks create compliance cost barriers that favor established regulatory affairs capacity, consolidating position for incumbent dermatological research infrastructures.
- Micro-vibration platform convergence:Patented oscillation technologies are cross-applying from cleansing devices into hair manipulation and skin preparation tools, opening adjacent category entry points.
Industry Challenges
- ISO 10993 biocompatibility certification:Material testing timelines for skin-contact devices compress product development cycles, forcing trade-offs between innovation speed and regulatory clearance confidence.
- Ferrule crimping tolerance control:Manufacturing precision requirements for bristle density uniformity demand capital-intensive automation, disadvantaging smaller tool assemblers dependent on manual processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beauty Tools Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushes, Sponges, Applicators, Rollers Material: Plastic, Silicone, Wood, Metal Functionality: Exfoliating, Cleansing, Massaging, Styling End User: Professionals, Consumers, Salons, Spa |
| Companies Covered | Nu Skin Enterprises Inc., Estée Lauder, L'Oréal Group, Home Skinovations Ltd., Shiseido, Koninklijke Philips N.V., Tria Beauty Inc., Photomedex Inc., Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beauty Tools Market Emerging Trajectories
Micro-vibration and LED technologies are compressing the boundary between cosmetic convenience and therapeutic efficacy, forcing regulatory recalibration while creating new competitive arenas for precision-engineered implements.
Microcurrent stimulation technology is miniaturizing from clinic-grade equipment into handheld facial toning devices, enabling at-home protocols previously restricted to aesthetician offices. Professional technicians are adopting these implements as retail adjuncts, extending service revenue through device-assisted maintenance programs. The technology is miniaturizing circuit boards and electrode configurations to battery-powered form factors, collapsing the price-performance gap between consumer and professional tiers.
REACH substance restriction amendments are expanding controlled chemical lists for cosmetic device materials, compelling manufacturers to reformulate adhesives and coatings used in ferrule assembly. The industrial consequence is accelerated substitution toward medical-grade silicone bonding agents with pre-certified compliance documentation. Electronic cleansing device categories face the most intensive retesting burden, with EU distributors demanding batch-level traceability certificates that smaller Asian assemblers struggle to furnish.
Certified aestheticians are consolidating procurement through authorized distributor networks rather than open-market sourcing, prioritizing warranty-backed implements with documented sterilization compatibility. This channel consolidation displaces gray-market tool flows that previously undercut manufacturer pricing discipline. The United States exhibits the most pronounced shift, where state licensing boards are tightening equipment standards for salon insurance eligibility, forcing independent technicians toward compliant supply chains.
Beauty Tools Market Segmentation
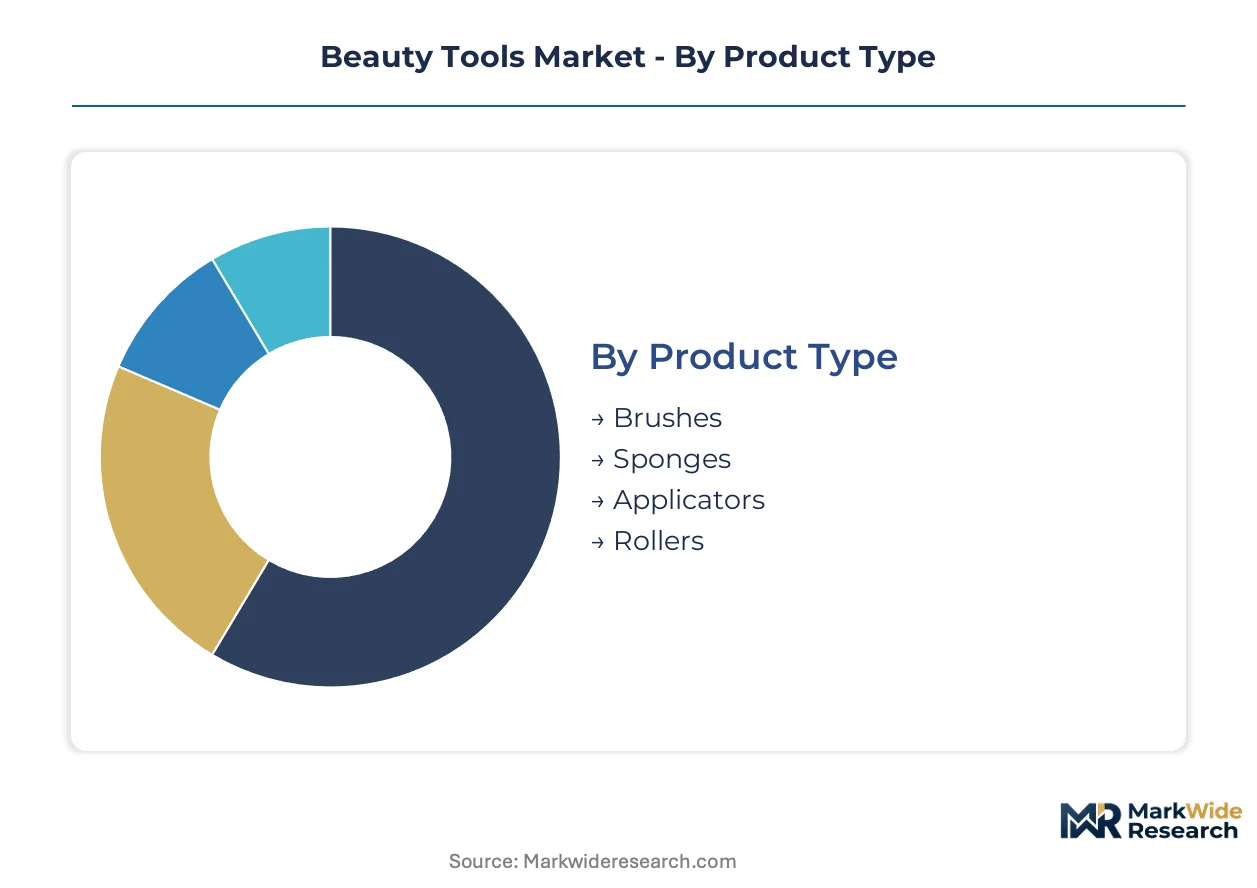
Beauty tools fragment across four intersecting dimensions that determine margin capture and regulatory exposure. Material composition and functionality drive the steepest price stratification, while end-user channel dynamics dictate warranty structures and sterilization compliance burdens.
Product Type:
Substitution pressure from reusable alternatives and disposable convenience formats reshapes competitive intensity across implement categories, with synthetic applicators facing the most acute displacement from silicone and biodegradable alternatives.
- Brushes:Ferrule-crimped assemblies with synthetic or natural filaments dominate pigment pickup precision for foundation and eye color application. United States specialty retailers allocate expanding shelf space to coordinated brush systems with dedicated fixtures, driven by shade-specific accumulation patterns among consumers.
- Sponges:Hydrophilic polyurethane foam and silicone variants enable seamless blending through controlled product absorption and release. Professional salons in the United States reorganize procurement toward ergonomically optimized implements as state licensing boards tighten equipment standards for insurance eligibility.
- Applicators:Disposable wands and single-use spatulas serve sanitary protocols in clinical and retail settings. Demand concentrates in spa environments requiring documented sterilization compatibility.
- Rollers:Handheld massage and micro-needling implements target lymphatic drainage and product penetration. FDA classification ambiguity around therapeutic claims extends approval timelines for powered variants.
Brushes retain volume leadership; rollers hold the steepest expansion curve as at-home device protocols gain adherence.
Material:
Cost tier stratification separates medical-grade certified inputs from commodity substitutes, with REACH and EU MDR compliance documentation becoming the primary price discriminator.
- Plastic:Injection-molded handles and ferrules from ABS or polycarbonate enable mass-market price points. REACH substance restriction amendments compel reformulation of adhesives and coatings, elevating retesting burdens for European distribution.
- Silicone:Medical-grade compositions with antimicrobial properties and thermal conductivity command price premiums in electronic cleansing devices. Koninklijke Philips N.V. leverages patented micro-vibration platforms to anchor margin concentration in this segment.
- Wood:Sustainably harvested birch and bamboo handles respond to environmental claim hierarchies reshaping consumer preference. ISO 10993 biocompatibility certification compresses product development cycles for skin-contact variants.
- Metal:Anodized aluminum ferrules deliver crimping precision for bristle density uniformity. Limited qualified suppliers create input vulnerability for brush manufacturers dependent on consistent metal sourcing.
Plastic dominates unit volume; silicone captures the steepest margin expansion as antimicrobial claims harden into purchase requirements.
Functionality:
Application maturity separates replacement-driven categories from technology-led segments where professional protocols migrate to consumer settings.
- Exfoliating:Physical scrubs, chemical peel applicators, and sonic cleansing devices remove dead skin cells and debris. FTC substantiation pathways for clinical efficacy claims favor established dermatological research infrastructures like L'Oréal Group's development capacity.
- Cleansing:Electronic face brushes and manual implements prepare skin for product absorption. Micro-vibration platform convergence from cleansing into adjacent categories opens entry points for oscillation technology specialists.
- Massaging:Facial rollers, gua sha implements, and microcurrent devices stimulate circulation and muscle tone. Miniaturization of clinic-grade equipment into handheld form factors collapses the price-performance gap between consumer and professional tiers.
- Styling:Hair brushes, combs, and thermal tools manipulate texture and shape. Ferrule crimping tolerance requirements demand capital-intensive automation, disadvantaging smaller assemblers.
Cleansing maintains the largest installed base; massaging climbs the fastest as certified aestheticians adopt retail adjunct programs.
End User:
Channel consolidation through authorized distributor networks displaces gray-market flows, with procurement authority concentrating in certified professional segments.
- Professionals:Licensed aestheticians and makeup artists prioritize warranty-backed implements with documented sterilization compatibility. United States state licensing boards force independent technicians toward compliant supply chains.
- Consumers:Direct-to-purchaser channels expand shelf space for premium tool assortments, pulling inventory allocation toward higher-margin electronic devices. Estée Lauder extends brand equity into coordinated brush systems for this segment.
- Salons:Institutional procurement reorganizes around precision-engineered implements as EU MDR and REACH frameworks tighten material compliance requirements. Technicians upgrade to certified implements, creating replacement demand across European professional channels.
- Spa:Clinical and wellness environments demand batch-level traceability certificates for electronic cleansing devices. Smaller Asian assemblers struggle to furnish documentation required by EU distributors.
Consumers represent the broadest addressable base; salons drive the steepest value-per-unit expansion through certified procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-engineered beauty implements to United States specialty retailers, establishing the primary transatlantic trade corridor for professional-grade tools.
United States
State licensing boards in California and New York tighten equipment standards for salon insurance eligibility, forcing independent technicians toward compliant supply chains. The FTC monitors advertising substantiation for clinical efficacy claims, elevating compliance costs for LED and microcurrent device entrants. Los Angeles and Manhattan concentrate procurement authority among certified aestheticians reorganizing toward authorized distributor networks.
Germany
REACH substance restriction amendments expand controlled chemical lists for cosmetic device materials, compelling manufacturers to reformulate adhesives used in ferrule assembly. The EU MDR framework governs biocompatibility requirements across European distribution channels. Baden-Württemberg hosts precision metalworking clusters supplying anodized aluminum ferrules to brush manufacturers facing input vulnerability from limited qualified suppliers.
China
Synthetic filament production clusters serve global brush assembly demand while facing displacement pressure from sustainably harvested wood alternatives. NMPA classification protocols for powered beauty tools with therapeutic claims create regulatory friction for export-oriented manufacturers. Guangdong Province concentrates electronic cleansing device assembly operations struggling with batch-level traceability documentation demanded by EU distributors.
Japan
METI standards for household electrical appliances govern safety certification for micro-vibration facial devices targeting at-home protocol adherence. PMDA oversight extends to therapeutic claims on microcurrent stimulation technologies miniaturizing from clinic-grade equipment. Osaka-based manufacturers anchor premium tier positioning through dermatological research partnerships.
South Korea
MFDS regulates LED and microcurrent beauty devices as medical devices when therapeutic claims attach, compressing product development timelines for skin-contact innovations. Seoul Capital Area clusters dominate K-beauty tool export flows to Southeast Asian markets. Gyeonggi Province facilities specialize in medical-grade silicone bonding agents with pre-certified REACH compliance documentation.
Beauty Tools Market Vendor Landscape
Player mix skews toward diversified personal care conglomerates with dermatological research infrastructure alongside specialized electronic device fabricators. Market structure exhibits tiered consolidation with premium positioning anchored by patented oscillation platforms and mass-market penetration driven by coordinated brush system retail fixtures. Strategic archetypes include beauty conglomerates extending color cosmetics brand equity into tool categories, electronics specialists leveraging micro-vibration patents across adjacent applications, and professional salon suppliers reorganizing around sterilization-compatible warranty-backed implements. Dominant competitive moves center on cross-category technology licensing for vibration platforms and backward integration into medical-grade silicone supply chains.
Within the beauty conglomerate tier, L'Oréal Group and Estée Lauder occupy positions exemplifying brand equity extension into precision-engineered implements. Koninklijke Philips N.V. represents the electronics specialist archetype leveraging patented platforms across cleansing and massaging modalities. These three entities anchor the competitive structure through divergent strategic vectors: dermatological research infrastructure, color cosmetics retail fixture coordination, and micro-vibration technology convergence.
| Leading Market Players |
|---|
| Nu Skin Enterprises Inc. |
| Estée Lauder |
| L'Oréal Group |
| Home Skinovations Ltd. |
| Shiseido |
| Koninklijke Philips N.V. |
| Tria Beauty Inc. |
| Photomedex Inc. |
| Procter & Gamble |
| Others |
Supply Flow & Price Mechanics
EU MDR biocompatibility certification gates both supplier qualification and price stratification, forcing manufacturers to absorb retesting costs or pass them through as tiered premiums while professional buyers demand documented sterilization compatibility as a non-negotiable procurement threshold.
Pricing Analysis
Next-generation micro-vibration platforms command 40-60% premiums over prior-generation sonic cleansing devices, while legacy manual implements face commoditization pressure from silicone alternatives. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade certified electronic devices from uncertified imports and disposable applicators. Cost compression in the standard tier is intensifying because REACH substance restriction amendments force adhesive reformulation. Professional salons exhibit the lowest price sensitivity due to insurance eligibility requirements, while direct-to-consumer channels show acute responsiveness to promotional bundling.
Supply Chain Analysis
Anodized aluminum ferrule sourcing from Baden-Württemberg precision metalworking clusters creates a chokepoint for brush manufacturers dependent on crimping tolerance consistency. Medical-grade silicone feedstock concentrates in Gyeonggi Province and Guangdong Province, while synthetic filament production clusters in Zhejiang Province face displacement from sustainably harvested birch alternatives. Single-source vulnerability runs through qualified EU MDR certification laboratories, extending lead times for new product introductions. Distribution runs through authorized professional distributor networks in the United States and Germany, displacing gray-market flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The beauty tools market is cycling through a professional equipment replacement wave as state licensing boards tighten insurance eligibility standards, compressing upgrade timelines for independent technicians.
For Market Incumbents: Consolidate procurement relationships with certified aestheticians through warranty-backed sterilization-compatible implements before REACH substance restriction amendments elevate compliance costs for smaller competitors. Deepen backward integration into medical-grade silicone supply chains to secure pre-certified bonding agents. Defend against silicone substitution threats by accelerating micro-vibration platform convergence into adjacent hair manipulation categories. For New Entrants and Emerging Players: Differentiate on at-home device protocol adherence by miniaturizing clinic-grade microcurrent technologies into handheld form factors with consumer-accessible price positioning. White-space targets include spa environments requiring batch-level traceability certificates that incumbent Asian assemblers struggle to furnish. The most penetrable segment is certified aesthetician retail adjunct programs in the United States. Pursue direct-to-consumer launch with dermatological research partnerships to substantiate clinical efficacy claims under FTC scrutiny. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified personal care conglomerates seeking to divest non-core tool manufacturing assets amid regulatory compliance cost escalation. Long-term viability favors entities with captive dermatological research infrastructure and established FDA regulatory affairs capacity. Watch for inflection signals around EU MDR recertification deadlines that will force consolidation among undifferentiated commodity suppliers lacking compliance documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Supply | Captures margin concentration in antimicrobial medical-grade compositions with pre-certified REACH documentation. |
| Micro-Vibration Platform Licensing | Cross-applies patented oscillation technologies from cleansing into hair manipulation and skin preparation categories. |
| Professional Distributor Network Consolidation | Displaces gray-market tool flows while securing warranty-backed procurement relationships with state-licensed technicians. |
| Clinical Efficacy Claim Substantiation | Creates FTC-compliant advertising frameworks that favor established dermatological research infrastructures over entrants. |
| At-Home Device Protocol Development | Collapses price-performance gaps between consumer and professional tiers through miniaturized circuit board configurations. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with professional salon owners, certified aestheticians, beauty tool procurement managers at specialty retailers, regulatory affairs directors at cosmetic device manufacturers, and electronic component sourcing leads. Secondary validation drew from FDA 510(k) filings for powered beauty tools, EU MDR technical documentation databases, REACH substance restriction amendment registers, and United States state licensing board equipment standard updates. Bottom-up demand modeling triangulated against top-down market sizing across material composition and functionality segments.
Across the analysis window, projections integrated replacement cycle dynamics for brushes and sponges, professional salon upgrade trajectories tied to insurance eligibility tightening, and consumer adoption curves for at-home electronic device protocols. Segmentation dimensions modeled include product type, material composition, functionality modality, and end-user channel with regulatory compliance burden weighting. CAGRs derived from historical penetration rates adjusted for EU MDR implementation timelines and FTC substantiation pathway evolution. Industry-specific inputs captured ferrule crimping automation capital requirements and ISO 10993 biocompatibility testing duration benchmarks.
Decision-makers should treat outputs as directional under assumptions of sustained professional salon equipment replacement demand and stable REACH substance restriction implementation timelines; material deviation would warrant model refresh. Specific risk factors that could revise forecasts include FDA reclassification of LED and microcurrent technologies as Class II medical devices, abrupt anodized aluminum supply disruptions from qualified ferrule suppliers, and accelerated synthetic filament substitution from biodegradable alternatives. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and state-level licensing board standard evolution unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
ASEAN Organic Cosmetics Market
Beauty & Personal Care
Asia-Pacific Hair Conditioner Market
Beauty & Personal Care
Personal Care Products Market
Beauty & Personal Care
Lip and Cheek Tint Market
Beauty & Personal Care
Global Probiotic Cosmetic Products Market
Beauty & Personal Care
South Korea Beauty and Personal Care Products Market
Beauty & Personal Care
Deodorant Products Market
Beauty & Personal Care
Anti-Aging Cosmetics Market
Beauty & Personal Care
Personal Care Contract Manufacturing Market
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
Aftershave Market
Beauty & Personal Care
United States Bath Soap Market
Beauty & Personal Care
China Electric Face Cleanser Market
Beauty & Personal Care
Men's Skincare Products Market
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
E-Pharmacy Beauty and Personal Care (BPC) Market