
 Saudi Arabia Beauty and Personal Care Market | 2026-2036
Saudi Arabia Beauty and Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Beauty and Personal Care Market Outlook
Travel-size and sampler bundling is broadening trial access across Saudi Arabia's beauty sector. Unilever PLC leverages its mass-market distribution network to sustain volume leadership in haircare and personal cleansing. Abdul Samad Al Qurashi anchors its position through captive oud distillation and heritage perfumery expertise. L'Oréal S.A. differentiates via dermatological skincare lines calibrated for regional climate conditions.
Beauty and personal care encompasses formulated topical products designed for skin conditioning, hair maintenance, color enhancement, and scent application, typically incorporating emulsifiers, active ingredients, and preservation systems at pH ranges between 4.5 and 7.0 for cutaneous compatibility. Skincare commands the largest margin pool as consumers prioritize sun damage prevention and anti-aging regimens suited to desert climates. Fragrance experiences the fastest velocity among product types, driven by oud-based prestige offerings and gift-giving culture. Specialty stores and pharmacies capture premium price realization through consultation-assisted selling, while online channels expand reach into secondary cities.
SFDA registration requirements and halal certification protocols administered by accredited Islamic bodies govern ingredient permissibility, labeling accuracy, and import clearance for all cosmetic products sold in the Kingdom. SASO technical regulations for product safety and the Saudi Green Initiative's emerging sustainability standards are reshaping packaging material specifications and supply chain documentation requirements. Stakeholders must monitor regulatory alignment between local halal mandates and evolving EU-inspired ingredient restrictions to preserve market access and consumer trust.
Market Dynamics
SFDA ingredient disclosure mandates and halal certification protocols are compressing formulation timelines while elevating compliance costs for international suppliers entering the Kingdom.
Growth Catalysts
- Halal certification alignment:Islamic body accreditation opens distribution through pharmacy and duty-free channels previously restricted to verified products. Domestic distillers leverage captive oud supply chains to accelerate prestige fragrance launches.
- Riyadh-Jeddah retail infrastructure:Premium mall development and dedicated beauty zones in luxury retail clusters concentrate high-margin consumer traffic. Specialty store formats enable consultation-assisted selling for dermatological skincare lines.
- Digital commerce penetration:Social commerce integration via localized platforms extends trial-size sampling into secondary cities beyond the main metropolitan corridors. Young urban women drive platform-native discovery behaviors.
Market Restraints
- SFDA registration timelines:Extended documentation requirements for novel ingredients delay product launches by 12-18 months versus comparable Gulf Cooperation Council markets.
- Packaging material compliance:Saudi Green Initiative sustainability standards restrict conventional plastic formats, forcing supply chain reconfiguration for imported goods.
- Oud supply concentration:Captive distillation capacity clusters with heritage perfumers in Asir and Taif regions, limiting independent brand access to authentic raw material.
Strategic Opportunities
- Asir and Eastern Province expansion:Underpenetrated urban centers outside Riyadh-Jeddah axis present whitespace for pharmacy-channel skincare distribution.
- Climate-adapted dermatological formulations:Product development targeting desert-specific photodamage and dehydration regimens addresses unmet functional needs.
- Subscription and replenishment models:Automated delivery platforms for core personal cleansing and haircare categories reduce customer acquisition costs in repeat-purchase segments.
Industry Challenges
- Formulation chemist scarcity:Limited domestic talent pool for halal-compliant cosmetic chemistry extends R&D cycle times for international market entrants.
- Legacy ERP integration:SFDA track-and-trace serialization requirements force expensive system upgrades for distributors managing multi-brand portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Beauty and Personal Care Market |
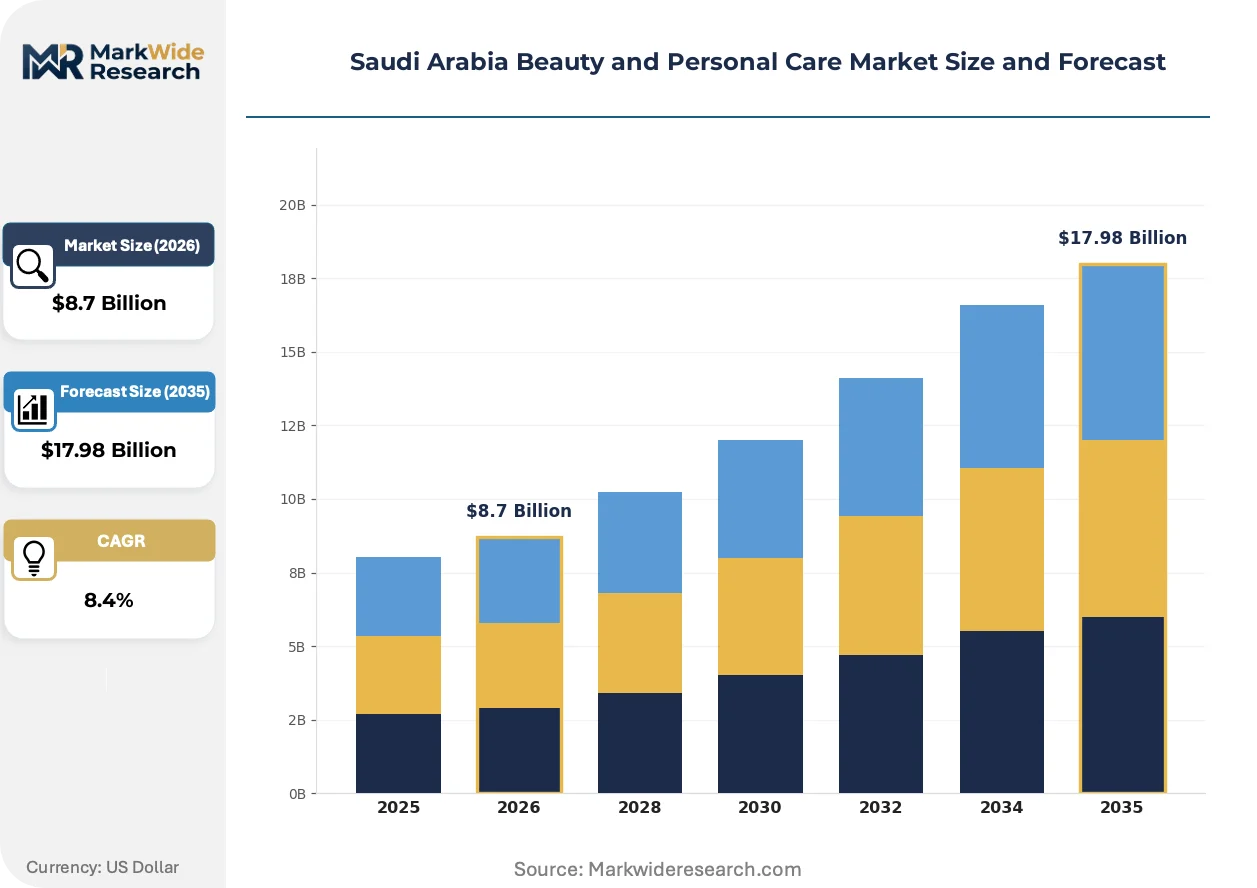
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Customer Type: Men, Women, Teens, Seniors Packaging Type: Bottles, Jars, Tubes, Single-use Packs Distribution Channel: Online, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | L'Oréal S.A., Unilever PLC, The Procter & Gamble Company, Beiersdorf AG, The Estée Lauder Companies Inc., Johnson & Johnson, Al Haramain Perfumes, Abdul Samad Al Qurashi, Coty Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Beauty and Personal Care Market Strategic Shifts
Digital-first discovery and climate-specific product development are compressing traditional brand-building timelines while fragmenting consumer loyalty patterns across the Kingdom.
Artificial intelligence-driven skin diagnostic tools are automating personalized regimen recommendations in retail environments. Pharmacy chains and specialty beauty stores deploy camera-based analysis systems to match consumers with targeted skincare protocols. This technology is automating the traditional beauty consultant role while capturing preference data for private-label development.
SFDA tightening of preservative and fragrance allergen labeling requirements is forcing reformulation of legacy personal care imports. International suppliers must resubmit dossiers for products containing specified sensitizing compounds. Color cosmetics and premium skincare segments face the steepest compliance burden as ingredient disclosure granularity expands.
Trial-size bundling and sampler economies are displacing full-size first purchases among digitally native consumers. Social commerce platforms and influencer-curated discovery boxes reduce perceived risk for new brand experimentation. Young urban women in Riyadh and Jeddah exhibit the highest conversion rates from sample to full-size repurchase.
Saudi Arabia Beauty and Personal Care Market Segmentation
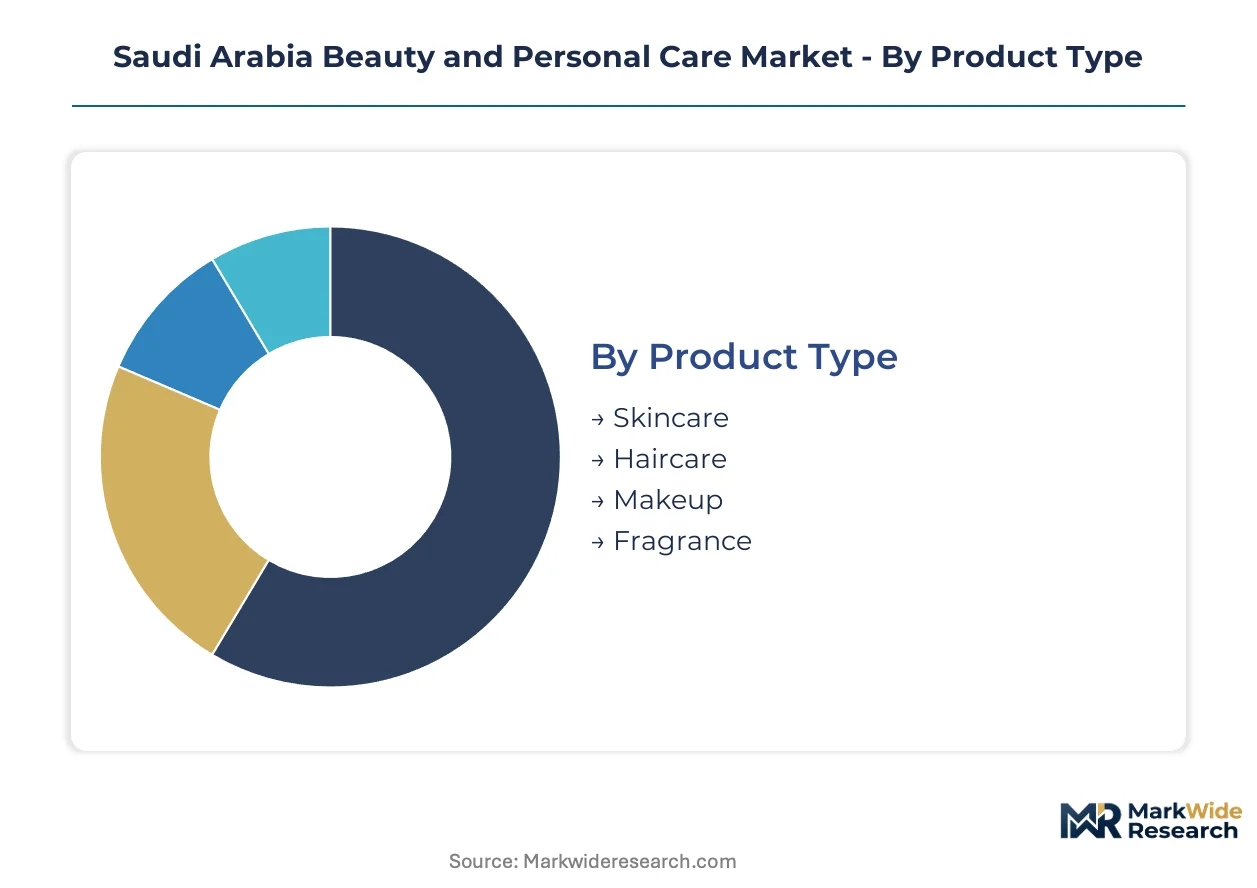
Segmentation in Saudi Arabia's beauty and personal care market reveals distinct consumption patterns shaped by halal compliance requirements, climate-adapted formulation needs, and generational shifts in channel preference. Understanding these divides enables targeted positioning across Riyadh-Jeddah premium corridors and emerging secondary cities.
Product Type:
Replacement cycles vary dramatically across product categories, with daily-use items driving predictable replenishment while prestige segments depend on occasion-based gifting calendars.
- Skincare:Emulsion-based formulations with SPF integration and humectant systems dominate Riyadh pharmacy counters, where photodamage prevention regimens anchor consumer loyalty. Jeddah's coastal humidity drives distinct hydration-focused protocols, creating geographic formulation splits within the same national market.
- Fragrance:Oud-based extrait concentrations and alcohol-free attars command premium placement in duty-free and heritage retail, with captive distillation capacity in Asir and Taif regions constraining independent brand supply. Gifting occasions around Ramadan and Eid compress purchase timing into predictable seasonal spikes.
- Haircare:Keratin-aligned treatments and scalp hydration lines address hard-water mineral deposit concerns prevalent across central Saudi municipalities.
- Makeup:Long-wear foundations and smudge-resistant eye formulations calibrated for desert heat conditions gain traction among professional women in metropolitan employment centers.
Volume placements concentrate in Skincare; the faster expansion belongs to Fragrance.
Customer Type:
Pricing tolerance stratifies sharply across demographic cohorts, with professional women absorbing premium dermatological positioning while teen entry points depend on sampler accessibility.
- Women:Young urban professionals in Riyadh and Jeddah drive premium skincare adoption through consultation-assisted pharmacy channels, with regimen complexity increasing through age thirty-five. SFDA-mandated ingredient transparency resonates most strongly with this cohort's purchase deliberation.
- Teens:Social commerce discovery behaviors and influencer-curated trial boxes lower trial barriers for first brand relationships, with TikTok-native platforms capturing attention ahead of traditional retail exposure.
- Men:Grooming line extensions from heritage fragrance houses and dedicated men's skincare ranges gain share in Eastern Province professional corridors.
- Seniors:Anti-aging concentrate formulations and targeted pigmentation correction address specific dermal concerns, with pharmacy consultation dependency remaining elevated versus younger segments.
Revenue concentration sits with Women; Teens are climbing the fastest toward material share.
Packaging Type:
Sustainability mandates from the Saudi Green Initiative are forcing material transitions that disadvantage conventional formats while creating first-mover advantage for compliant alternatives.
- Bottles:Post-consumer recycled PET and glass formats face SASO technical specification updates, with pump-dispenser shampoo and body wash containers dominating supermarket replenishment purchases.
- Jars:Wide-mouth configurations for cream and balm textures concentrate in premium skincare, where airless pump jars gain preference for retinol and vitamin C stability.
- Tubes:Laminate and aluminum squeeze formats suit travel-size regulations and sampler bundling strategies prevalent in digital commerce channels.
- Single-use Packs:Hotel amenity specifications and airline-compliant sachet formats serve hospitality and travel retail segments with distinct procurement cycles.
Standard-size Bottles dominate unit placements; Single-use Packs are gaining share fastest through trial-economy expansion.
Distribution Channel:
Channel selection directly determines margin realization, with assisted-selling formats capturing price premiums while digital routes sacrifice service intensity for geographic reach.
- Specialty Stores:Dedicated beauty zones in Riyadh's luxury mall clusters and Jeddah's Red Sea retail corridors enable skin diagnostic technology deployment and private-label development data capture.
- Pharmacies:SFDA registration requirements and halal verification protocols channel dermatological skincare through this format, where pharmacist consultation substitutes for traditional beauty advisor roles.
- Online:Social commerce integration and subscription replenishment models extend reach into Asir and Eastern Province cities beyond the main metropolitan infrastructure.
- Supermarkets:Mass-market haircare and personal cleansing volumes concentrate here, with Unilever and regional players leveraging existing FMCG distribution density.
Pharmacy and Specialty Store placements capture highest margin per unit; Online channels are expanding most quickly into previously unserved geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City and other special economic zones are concentrating manufacturing and logistics infrastructure for beauty and personal care distribution across the Kingdom. Riyadh and Jeddah anchor premium retail development, while secondary urban centers present expansion whitespace for pharmacy-channel skincare penetration.
Riyadh
Young urban professionals drive dermatological skincare adoption through consultation-assisted pharmacy channels in Riyadh's luxury mall clusters. SFDA registration requirements channel premium products through verified retail formats, elevating compliance standards for international entrants. King Abdullah Financial District and Diriyah Gate developments concentrate specialty store formats with skin diagnostic technology deployment.
Eastern Province
Professional male grooming segments gain traction in Dammam and Khobar employment corridors, with heritage fragrance houses extending dedicated men's skincare ranges. The Saudi Green Initiative's sustainability standards reshape packaging specifications for goods entering through King Fahd Industrial Port. Dhahran's corporate residential zones sustain demand for premium personal cleansing and haircare replenishment.
Western Region
Jeddah's coastal humidity drives distinct hydration-focused skincare protocols versus central desert formulations, creating geographic product splits within the national market. Historic pilgrimage traffic sustains duty-free fragrance volumes, with oud-based prestige offerings commanding placement in Red Sea retail corridors. Taif's captive rose and oud distillation capacity anchors heritage perfumer supply chains for authentic raw material access.
Asir Region
Underpenetrated urban centers including Abha present whitespace for pharmacy-channel skincare distribution beyond the Riyadh-Jeddah axis. Domestic distillers leverage regional agarwood resources to accelerate prestige fragrance launches with halal certification alignment. Asir's mountainous climate creates niche demand for specialized photodamage prevention regimens distinct from desert formulations.
NEOM Northwest
The linear city's emerging retail infrastructure plans dedicated beauty zones targeting international resident demographics with sustainability-certified product ranges. NEOM's regulatory sandbox framework may streamline SFDA alignment pathways for innovative ingredient formulations. The project's zero-carbon commitments accelerate demand for Saudi Green Initiative-compliant packaging materials across supplier networks.
Saudi Arabia Beauty and Personal Care Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Saudi Arabia's beauty and personal care sector, creating a tiered competitive structure. Mass-market distribution density concentrates with multinational FMCG portfolios, while prestige fragrance and dermatological skincare segments fragment across heritage houses and specialized dermatology brands. Three archetypes dominate: scale-driven volume players, heritage authenticity anchors, and clinical-positioned skincare specialists. Competitive moves center on halal certification acceleration and climate-adapted formulation development.
Within the heritage authenticity tier, Abdul Samad Al Qurashi exemplifies captive supply chain control through regional oud distillation assets. L'Oréal S.A. and Unilever PLC occupy positions representing divergent scale strategies—specialized premium dermatology versus mass-market personal cleansing density. These three entities anchor distinct competitive vectors without overlapping core positioning.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Unilever PLC |
| The Procter & Gamble Company |
| Beiersdorf AG |
| The Estée Lauder Companies Inc. |
| Johnson & Johnson |
| Al Haramain Perfumes |
| Abdul Samad Al Qurashi |
| Coty Inc. |
| Others |
Value Chain & Pricing Dynamics
Young urban women in Riyadh and Jeddah anchor the dominant pricing model through their preference for consultation-assisted pharmacy channels and trial-size digital discovery. This buyer concentration compresses margin realization for mass-market entrants while rewarding heritage fragrance houses and dermatological specialists with pricing power tied to captive supply and halal certification.
Pricing Analysis
Short lead-time premiums attach to SFDA-registered stock already cleared through Kingdom customs, while spot inventory from parallel import channels trades at markdowns. Three-tier pricing structure across premium oud-based fragrances, standard pharmacy-channel skincare, and economy personal cleansing segments reflects halal certification grade and consultation service bundling. Cost compression in mass haircare intensifies as Unilever leverages existing FMCG distribution density against specialized entrants. Teens exhibit highest price sensitivity through social commerce trial boxes, while professional women absorb premium positioning for climate-adapted dermatological regimens.
Supply Chain Analysis
Dual-sourcing requirements from Saudi pharmacy chains and luxury mall operators mandate multi-supplier qualification for oud distillates, active pharmaceutical-grade ingredients, and sustainable packaging substrates. Manufacturing gravity centers on India and China for cosmetic chemical inputs, France and Switzerland for prestige fragrance compounds, and domestic Asir-Taif corridors for captive agarwood distillation. Single-source vulnerability concentrates in heritage oud supply chains where independent brands lack distillation access. Distribution runs through King Abdullah Economic City logistics hubs into Riyadh-Jeddah retail clusters, with secondary city penetration increasingly tethered to digital commerce fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in Saudi Arabia's beauty sector has become a vertical-integration race, with players pursuing upstream control over halal-certified oud distillation and downstream capture of pharmacy consultation channels.
For Market Incumbents: Hedge against formulation chemist scarcity by establishing captive R&D partnerships with GCC universities and technical institutes. Lock in multi-year oud supply agreements with Asir and Taif distillers before independent brands secure allocation. SFDA serialization requirements for track-and-trace compliance threaten distributors with legacy ERP upgrade costs exceeding SAR 2 million per facility. For New Entrants and Emerging Players: Enter via climate-adapted dermatological skincare targeting Abha and Eastern Province pharmacy whitespace outside Riyadh-Jeddah saturation. Subscription replenishment models for core personal cleansing categories reduce customer acquisition costs below specialty store consultation economics. Social commerce integration with localized platforms enables geographic arbitrage into secondary cities without physical retail infrastructure. For Investors and Strategic Acquirers: The window for entry favors heritage fragrance houses with captive distillation assets and halal certification infrastructure already aligned with SFDA protocols. Acquisition targets should demonstrate established pharmacy-channel relationships and climate-specific formulation libraries. Watch for inflection when Saudi Green Initiative packaging mandates force supply chain reconfiguration among import-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Acceleration | SFDA registration and Islamic body accreditation unlock pharmacy and duty-free distribution channels previously restricted. |
| Climate-Adapted Formulation Development | Desert-specific photodamage and hydration regimens address unmet functional needs in Riyadh's arid conditions. |
| Captive Oud Distillation Investment | Upstream control over Asir and Taif agarwood resources secures authentic raw material access for prestige fragrance launches. |
| Pharmacy Channel Expansion | Consultation-assisted selling in Eastern Province and Asir cities captures margin premiums beyond saturated Riyadh-Jeddah corridors. |
| Sustainability Packaging Transition | Saudi Green Initiative compliance with post-consumer recycled formats creates first-mover advantage against conventional plastic-dependent imports. |
Study Parameters
Independent corroboration across primary interviews with SFDA regulatory affairs specialists, pharmacy chain procurement directors, heritage fragrance house supply planners, and dermatological brand managers underwrites the qualitative findings. Secondary validation draws from SFDA registration databases, SASO technical specification filings, Saudi Customs import records, and Nielsen retail audit data covering pharmacy and specialty store channels. Bottom-up SKU-level demand modeling triangulates against top-down category expenditure estimates from household consumption surveys.
Rate-of-change decomposition separates volume expansion from value mix shift across the projection horizon. Segmentation dimensions modeled include product type, customer demographic, packaging format, and distribution channel, with additional granularity on halal certification tier and climate-adaptation claim status. CAGRs derive from trend-line extrapolation of historical registration volumes adjusted for regulatory timeline compression and digital commerce penetration curves. Forecast inputs incorporate SFDA staff capacity constraints on novel ingredient dossier review and Saudi Green Initiative implementation schedules for packaging material transitions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended SFDA registration delays or abrupt oud supply disruption from regional climate events. Deviation in halal certification body accreditation timelines or Saudi Green Initiative enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Nail Care Products Market
Beauty & Personal Care
Canada Dermocosmetics Market
Beauty & Personal Care
Nail Polish Remover Market
Beauty & Personal Care
Spray Tanning Market
Beauty & Personal Care
Body Firming Creams Market
Beauty & Personal Care
South America E-Commerce Skin Care Products Market
Beauty & Personal Care
Beard Oil Market
Beauty & Personal Care
France Sustainable Personal Care Market
Beauty & Personal Care
Hair Removal Spray Market
Beauty & Personal Care
Asia-Pacific Hair Conditioner Market
Beauty & Personal Care
Slimming Cream Market
Beauty & Personal Care
Organic Baby Shampoo Market
Beauty & Personal Care
Luxury Cosmetics Market
Beauty & Personal Care
Anti-Acne Facial Serum Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
Deodorant Products Market