
 Intensive Conditioner Market | 2026-2036
Intensive Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
Intensive Conditioner Market Foresight
Asset-light contract manufacturing and third-party formulation leasing is narrowing the capital barrier for new entrants in intensive hair care. Procter & Gamble Co. leverages captive R&D infrastructure to sustain formulation leadership across multiple product tiers. L'Oréal S.A. anchors its position through deep specialization in professional salon channels. Unilever Plc competes by extending its mass-market distribution control into premium treatment segments.
Intensive conditioner denotes a high-viscosity hair treatment formulation containing concentrated emollients, proteins, and lipids designed to penetrate the cuticle layer and restore structural integrity to damaged hair; manufacturing typically employs cold-process emulsification to preserve heat-sensitive actives like hydrolyzed keratin and plant-derived oils. The leave-in and deep conditioning categories command the widest margin pools due to their positioning as treatment-grade rather than maintenance products. Natural and organic ingredient segments are attracting reformulation investment as regulatory scrutiny of synthetic preservatives intensifies across key markets. Cream-based formulations dominate salon professional channels while spray formats are gaining traction among home users seeking convenience without sacrificing treatment intensity.
FDA cosmetic labeling requirements, EU REACH chemical safety protocols, and the EU Green Deal sustainability frameworks are collectively elevating compliance costs and reshaping ingredient sourcing strategies for intensive conditioner manufacturers. ISO 16128 natural and organic cosmetics standards are becoming a de facto market access threshold for premium positioning in North America and Europe. Stakeholders must monitor evolving bioprospecting regulations and traceability mandates that will determine which ingredient supply chains remain commercially viable.
Market Dynamics
Clean beauty mandates under EU REACH and the EU Green Deal are forcing intensive conditioner manufacturers to rebuild supply chains around traceable, biobased inputs while maintaining treatment efficacy standards.
Growth Catalysts
- Professional salon channel expansion:High-margin treatment-grade formulations are penetrating salon backbars as stylists seek retail-complementary service revenue streams.
- ISO 16128 standardization:Natural and organic cosmetics certification is becoming a de facto market access threshold for premium positioning in North America and Europe.
- Leave-in format innovation:Spray and lightweight cream vehicles are capturing convenience-oriented home users without sacrificing ingredient load.
Market Restraints
- Plant-derived oil price volatility:Argan, marula, and cupuacu butter supply concentrates in Morocco, South Africa, and Brazil respectively, exposing formulators to climate and currency risk.
- Cold-process emulsification capex:Heat-sensitive active preservation requires specialized mixing infrastructure that contract manufacturers in emerging markets rarely possess.
- Synthetic preservative substitution timeline:EU regulatory scrutiny of parabens and formaldehyde releasers is compressing reformulation windows before compliance deadlines.
Strategic Opportunities
- Bioprospecting regulatory tailwinds:Nagoya Protocol access and benefit-sharing frameworks in Brazil and India are opening previously restricted botanical supply chains to compliant extractors.
- Direct-to-consumer subscription channels:Personalized hair diagnostic tools paired with auto-replenishment models are capturing lifetime value from premium home users.
- Scalp microbiome convergence:Prebiotic and postbiotic ingredient platforms from adjacent skincare categories are migrating into treatment-grade hair care formulations.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging natural ingredient stability and salon-performance standards concentrates in Western Europe and the United States.
- Dual certification complexity:Simultaneous pursuit of ISO 16128 natural content claims and salon professional efficacy benchmarks extends product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intensive Conditioner Market |
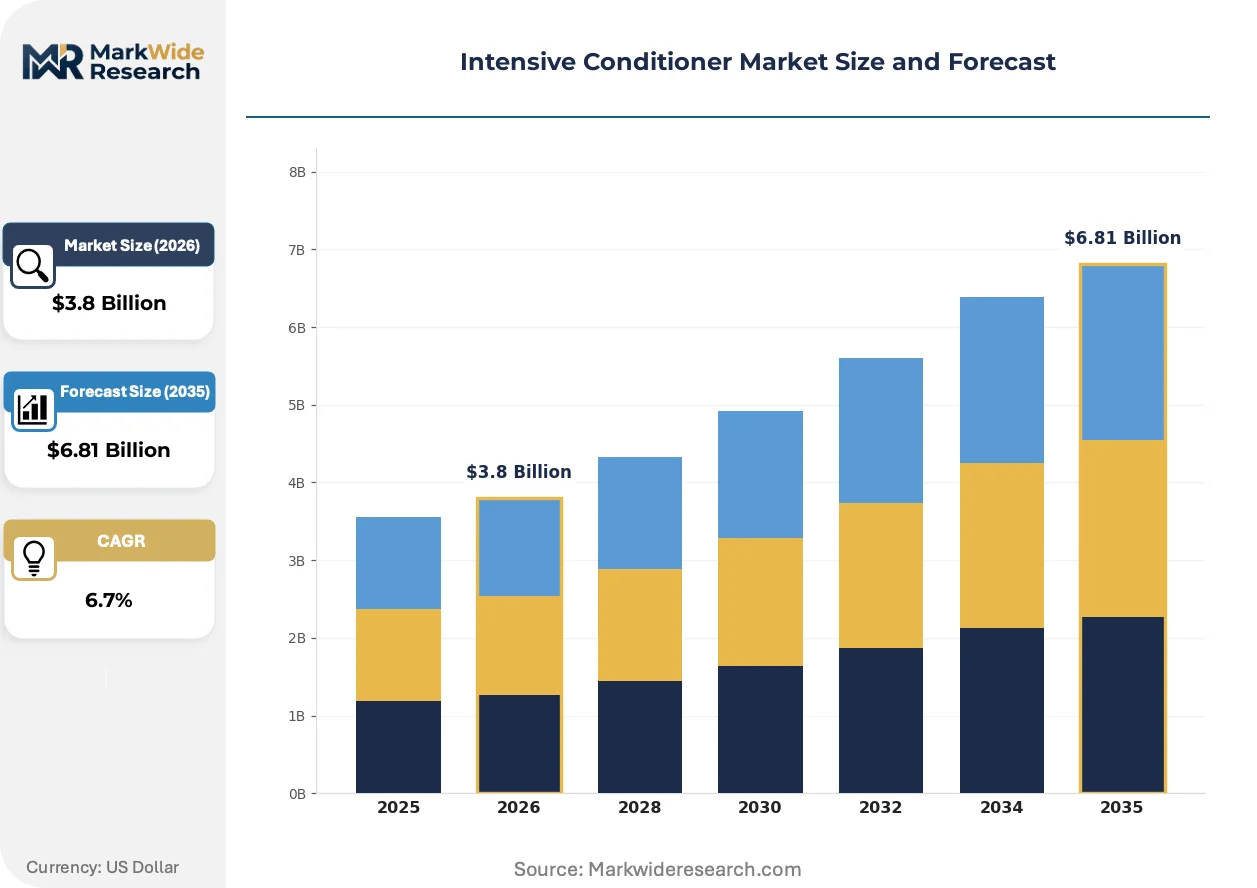
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leave-in, Rinse-out, Deep Conditioning, Treatment Ingredient Type: Natural, Synthetic, Organic, Herbal Formulation: Cream, Gel, Spray, Oil End User: Salons, Home Users, Beauty Professionals, Barbers |
| Companies Covered | Procter & Gamble Co., L'Oréal S.A., Unilever Plc, Henkel AG and Co KGaA, Kao Corporation, Beiersdorf AG, Johnson & Johnson Services Inc, Estée Lauder Companies Inc., Revlon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intensive Conditioner Market Shifts & Advancements
Formulation science is pivoting from synthetic conditioning quats to fermentation-derived biomimetics while regulatory transparency requirements reshape how ingredient stories reach end consumers.
Biotechnology-derived alternatives to traditional silicones and quaternary ammonium compounds are achieving commercial scale. Specialty chemical suppliers in Germany and Switzerland are commercializing yeast-fermented ceramides and rhamnolipid biosurfactants that replicate the sensory profile of dimethicone without petrochemical feedstocks. Professional salon brands in France and Italy are digitizing their technical training platforms to accelerate stylist education on these unfamiliar ingredient narratives.
EU Green Deal sustainability frameworks are extending beyond carbon accounting into full lifecycle disclosure. The European Chemicals Agency is preparing substance-specific environmental footprint data requirements that will force intensive conditioner manufacturers to quantify water use, biodegradability, and ecotoxicity for every ingredient above 0.1% concentration. German and Dutch formulators are responding by pre-emptively redesigning around the twelve principles of green chemistry.
Home users are unbundling the salon experience into component services purchased through divergent channels. Diagnostic hair analysis—once exclusive to professional consultations—is migrating to smartphone apps and at-home test kits, with results driving algorithmic product recommendations. This pattern is most visible in the United States, where premium consumers are treating intensive conditioners as prescription-grade solutions rather than impulse beauty purchases.
Intensive Conditioner Market Segmentation
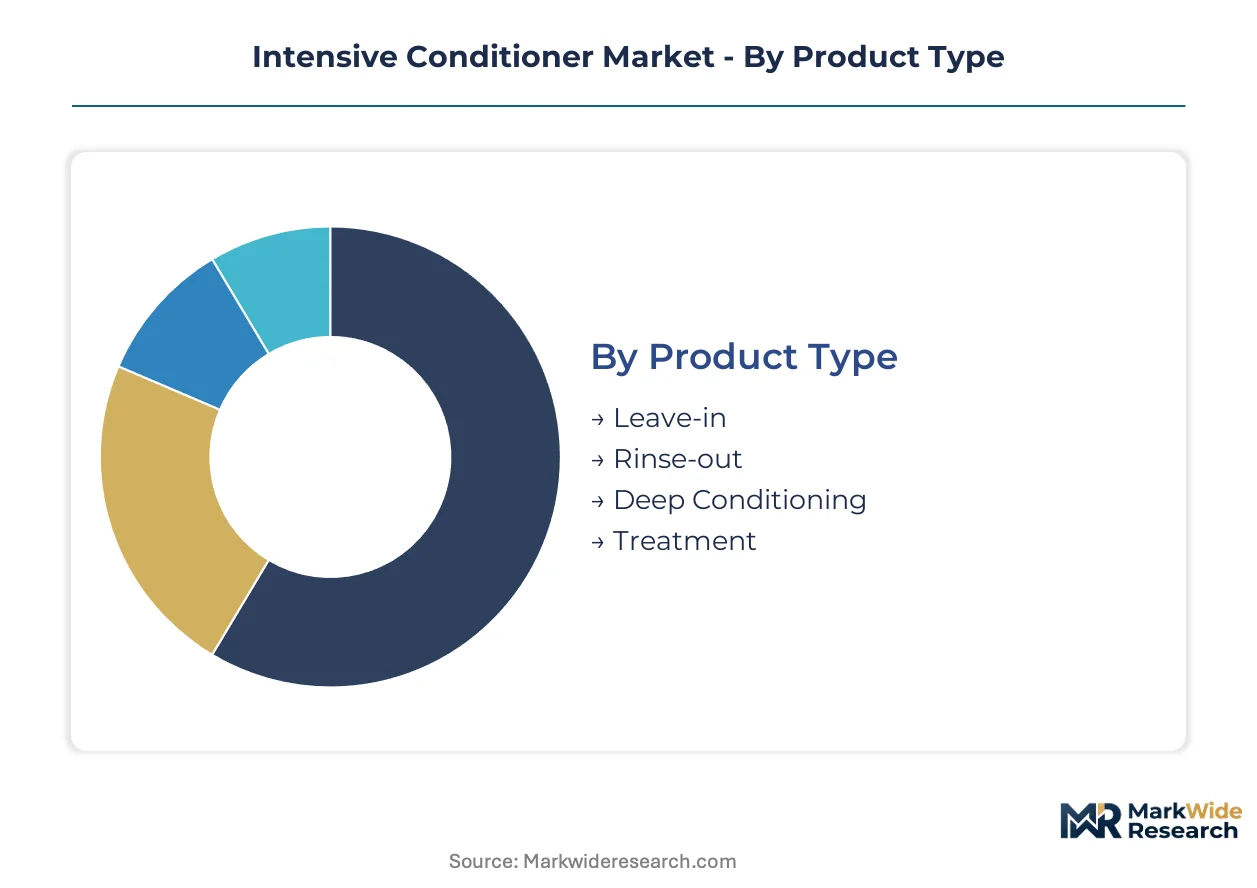
Intensive conditioner segmentation reveals divergent replenishment rhythms across product formats, with leave-in treatments restocking monthly while deep conditioning masks cycle quarterly. Ingredient sourcing constraints and formulation stability requirements further stratify inventory turnover across the value chain.
Product Type:
Leave-in formats turn inventory fastest due to daily-use frequency, whereas deep conditioning treatments exhibit the longest replacement cycles tied to weekly or biweekly application protocols.
- Leave-in:Lightweight emulsions designed for post-wash application without rinsing, typically incorporating heat-protectant silicones or plant-derived sealants. Demand clusters among United States home users seeking time-compressed morning routines, with spray vehicles gaining preference over pump creams for even distribution.
- Deep Conditioning:High-viscosity treatments requiring extended dwell time under heat or steam to enable cuticle penetration and cortex-level protein deposition. Salon backbars in France and Italy drive volume, where stylists bundle these as add-on services to chemical processing appointments.
- Rinse-out:Standard post-shampoo conditioners with elevated active loads compared to maintenance variants, designed for immediate rinse after brief application. Mass-market retail channels in Germany and the United Kingdom favor these for shelf-space efficiency.
- Treatment:Prescription-grade formulations targeting specific damage mechanisms—protein reconstruction, moisture replenishment, or porosity correction. Professional-only distribution in Japan restricts access to licensed stylists, preserving premium positioning.
Leave-in dominates installed base. Deep conditioning is where expansion concentrates.
Ingredient Type:
Cost tier stratification runs sharpest here, with synthetic quaternary ammonium compounds anchoring economy positioning while certified organic botanicals command triple-digit price multiples.
- Natural:Formulations leveraging minimally processed plant oils, butters, and hydrolyzed proteins without synthetic functional additives. Brazilian cupuacu and Moroccan argan supply chains face climate volatility, compressing margin predictability for formulators dependent on these inputs.
- Synthetic:Petrochemical-derived conditioning agents including behentrimonium chloride and amodimethicone, prized for batch consistency and cost stability. Regulatory pressure from EU REACH is accelerating substitution timelines, with formulators in Switzerland and Germany leading biomimetic alternatives development.
- Organic:Certified inputs meeting ISO 16128 or COSMOS standards for agricultural sourcing and processing integrity. United States premium home users treat this certification as a non-negotiable filter, driving allocation of scarce organic shea and coconut oil supplies.
- Herbal:Traditional botanical preparations rooted in Ayurvedic, Traditional Chinese Medicine, or Amazonian ethnobotanical knowledge. Nagoya Protocol compliance requirements in India and Brazil are opening previously restricted supply chains to verified extractors.
Natural ingredients anchor volume. Organic certification is climbing the fastest.
Formulation:
Application method determines packaging format, distribution channel compatibility, and stylist training requirements across professional and home use contexts.
- Cream:Emulsion-based vehicles with lamellar gel network structures enabling high active loading without phase separation. Salon professional channels in France and Italy standardize on these for controlled application during seated treatments.
- Spray:Aerosol or pump-dispersed fine mists delivering lightweight conditioning to dry or damp hair. Convenience-oriented home users in the United States are expanding this segment fastest, particularly for detangling and heat protection use cases.
- Gel:Water-based hydrocolloid systems offering transparent aesthetic and rapid absorption, favored for coily and tightly textured hair types. Specialty retailers in the United Kingdom and Germany curate these for textured hair segments underserved by cream formats.
- Oil:Anhydrous or minimal-water blends of plant-derived triglycerides and essential fatty acids, requiring distinct packaging to prevent oxidation. Prestige positioning in Japanese and South Korean markets treats these as multi-use face-hair-body treatments.
Cream formulations dominate installed base. Spray vehicles are expanding most quickly.
End User:
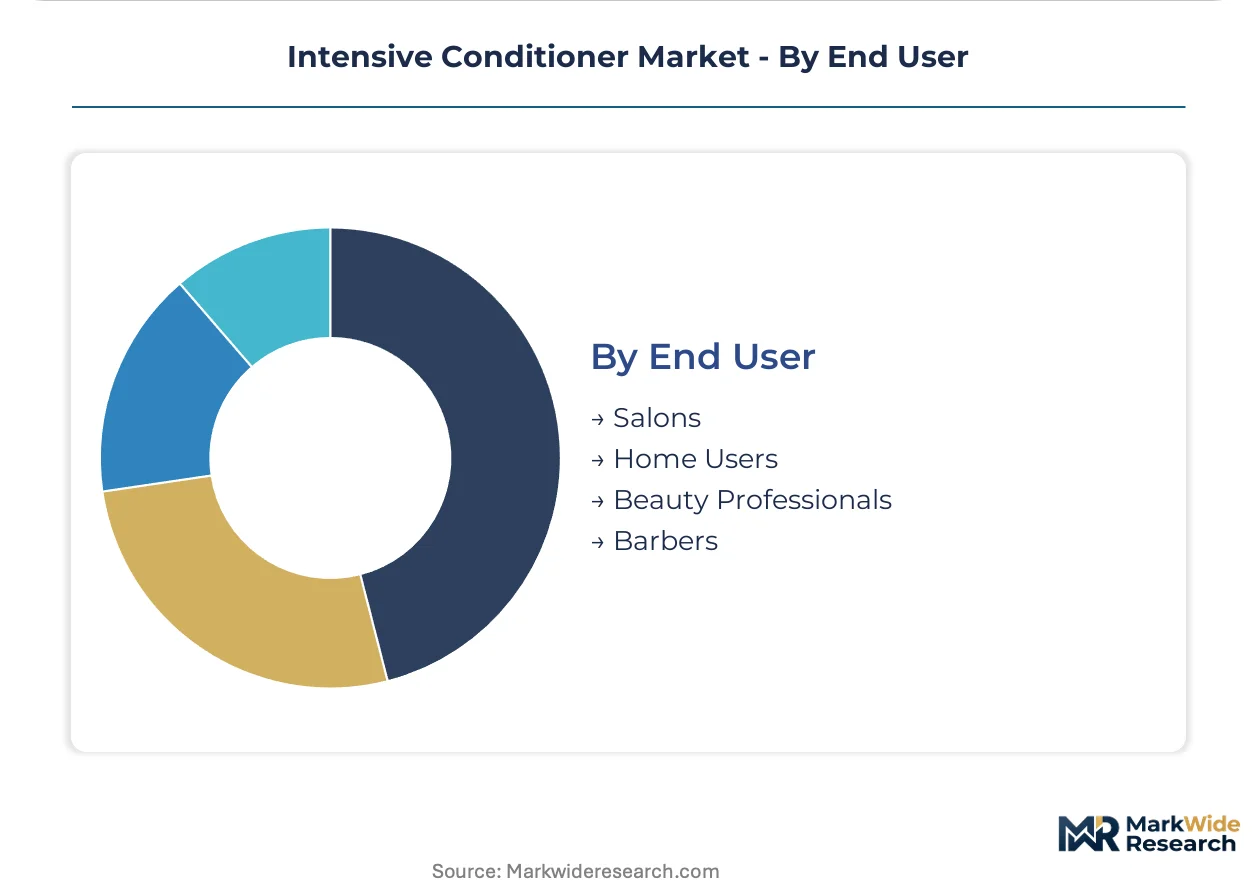
Customer type segmentation maps directly to pricing authority, with salons capturing service-bundled premiums and home users driving volume through recurring replenishment.
- Salons:Licensed establishments purchasing treatment-grade formulations through professional-only distribution, often tied to exclusive territory agreements. Backbar inventory in Italy and Spain turns slowly due to service-appointment dependency, but per-unit margins exceed retail by factors of three to five.
- Home Users:Individual consumers purchasing through mass retail, specialty beauty, or direct-to-consumer channels. United States premium segments exhibit highest trial rates for diagnostic-personalization tools that algorithmically match formulations to hair analysis results.
- Beauty Professionals:Freelance stylists and session artists operating outside fixed salon locations, purchasing through professional supply stores or mobile sales representatives. This segment in Brazil and Mexico shows fastest growth as independent contractor models displace traditional employment.
- Barbers:Male-grooming specialists incorporating conditioning treatments into beard and scalp services. United Kingdom and United States urban barbershops are expanding this application, treating intensive conditioners as differentiation from commodity shaving products.
Home users dominate installed base. Beauty professionals are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing authority concentrates in the United States and France, where salon-equivalent home formulations command unit multiples three times higher than mass-market equivalents in Brazil and India. Regulatory compliance costs in Germany and Switzerland compress margins for exporters serving those markets. Formulation talent scarcity in Western Europe creates a supply bottleneck that Asian contract manufacturers have yet to bridge.
United States
Diagnostic-personalization tools and subscription auto-replenishment models capture premium home users seeking prescription-grade hair solutions. FDA cosmetic labeling requirements and FTC substantiation standards elevate compliance burdens for imported formulations. New York and Los Angeles anchor the professional salon channel, where stylists bundle intensive treatments with color services to capture service revenue.
Germany
Green chemistry adoption and ISO 16128 certification requirements reshape ingredient sourcing for brands serving the premium segment. ECHA substance-specific environmental footprint data mandates under EU REACH force full lifecycle disclosure for formulations above 0.1% concentration. The Rhine-Ruhr industrial cluster hosts specialty chemical suppliers commercializing fermentation-derived biomimetics as silicone alternatives.
France
Professional salon backbars drive deep conditioning treatment volume, with stylists positioning these as add-on services to chemical processing appointments. EU Green Deal sustainability frameworks extend compliance obligations beyond carbon accounting into water use and ecotoxicity quantification. Paris and Lyon concentrate formulation R&D talent bridging natural ingredient stability with salon-performance benchmarks.
Brazil
Nagoya Protocol access and benefit-sharing frameworks open previously restricted Amazonian botanical supply chains to verified extractors serving the herbal ingredient segment. ANVISA cosmetic registration requirements create regulatory friction for imported premium formulations. São Paulo anchors independent contractor growth among freelance stylists and session artists purchasing through professional supply stores.
Japan
Professional-only distribution restrictions preserve premium positioning for treatment-grade formulations targeting specific damage mechanisms. METI chemical management policies and PMDA consultation on quasi-drug boundaries influence formulation classification decisions. Tokyo and Osaka concentrate licensed stylist networks where intensive conditioners remain service-bundled rather than retail-displaced.
Intensive Conditioner Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying fermentation-derived actives and botanical extracts to finished goods manufacturers. The vendor base stratifies across three tiers: multinational consumer goods conglomerates with captive R&D infrastructure, mid-cap professional salon specialists with exclusive distribution agreements, and contract manufacturers offering asset-light formulation leasing. Strategic moves concentrate on backward integration into specialty chemical supply and geographic licensing of professional-only distribution rights.
Within the multinational platform tier, Procter & Gamble Co. and L'Oréal S.A. occupy positions defined by scale advantages in R&D amortization and channel control. L'Oréal S.A. exemplifies deep specialization in professional salon channels through exclusive territory agreements with licensed establishments. Unilever Plc represents the mass-market extension archetype, leveraging retail distribution density to push premium treatment formulations downmarket.
| Leading Market Players |
|---|
| Procter & Gamble Co. |
| L'Oréal S.A. |
| Unilever Plc |
| Henkel AG and Co KGaA |
| Kao Corporation |
| Beiersdorf AG |
| Johnson & Johnson Services Inc |
| Estée Lauder Companies Inc. |
| Revlon |
| Others |
Supply & Pricing Matrix
Undercapacity in cold-process emulsification infrastructure across Southeast Asian contract manufacturers is compressing supplier bargaining power while elevating pricing premiums for heat-sensitive active preservation. This utilization gap forces formulators to accept longer lead times or pay capacity reservation fees, reshaping procurement economics for premium treatment-grade formulations.
Pricing Analysis
The customization-premium spread between salon-exclusive formulations and mass-market equivalents spans factors of three to five, with professional-only distribution rights commanding the widest spreads. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 16128 certification grade and stylist training bundling. Cost compression in synthetic quaternary ammonium tiers is intensifying because EU REACH substitution deadlines compress reformulation windows. Home users exhibit highest price sensitivity, while licensed salons accept premium positioning for service-bundled treatments.
Supply Chain Analysis
Contract manufacturing concentration among German and Swiss specialty chemical suppliers anchors fermentation-derived biomimetic capacity for silicone alternatives. Raw material sourcing draws from Moroccan argan cooperatives, Brazilian cupuacu extractors, and South African marula processors. Single-source vulnerability concentrates in Amazonian botanical supply chains subject to Nagoya Protocol access negotiations. Distribution runs through professional-only salon channels in France and Italy, mass retail in Germany and the United Kingdom, and direct-to-consumer subscription platforms in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EU REACH compliance costs and ISO 16128 certification timelines create structural barriers that favor incumbents with amortized R&D infrastructure.
For Market Incumbents: Harden formulation leadership through captive supply of fermentation-derived ceramides and rhamnolipid biosurfactants. Expand cold-process emulsification capacity in the Rhine-Ruhr cluster to offset Southeast Asian undercapacity. Lock exclusive professional salon distribution rights in France and Italy before mid-cap specialists consolidate territorial agreements. For New Entrants and Emerging Players: Independent contractor stylists in Brazil and Mexico represent the most penetrable channel, with professional supply stores serving fragmented freelance networks. Target herbal ingredient segments leveraging Nagoya Protocol compliance as a differentiation wedge. Deploy diagnostic-personalization tools paired with auto-replenishment models to bypass incumbent retail shelf dominance. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light contract manufacturing and third-party formulation leasing. Acquisition candidates include mid-cap professional salon specialists with ISO 16128 certification and exclusive territory agreements. Monitor bioprospecting regulatory developments in India and Brazil as signal for botanical supply chain viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation-Derived Actives | German specialty chemical suppliers commercialize yeast-fermented ceramides replacing petrochemical silicones. |
| Direct-to-Consumer Subscription Launch | Algorithmic hair diagnostics paired with auto-replenishment capture lifetime value from United States premium users. |
| ISO 16128 Certification Investment | Natural and organic cosmetics standards become de facto market access threshold for North American and European premium positioning. |
| Professional Salon Channel Expansion | Exclusive territory agreements with licensed establishments in France and Italy preserve service-bundled margin premiums. |
| Scalp Microbiome Platform Migration | Prebiotic and postbiotic ingredients from adjacent skincare categories enter treatment-grade hair care formulations. |
Research Methodology
The analysis maps leave-in, deep conditioning, rinse-out, and treatment-grade formulations, each validated through cosmetic chemists, professional salon owners, contract manufacturing procurement leads, and specialty chemical R&D directors. Primary interviews triangulate with secondary sources including ECHA substance databases, EU Green Deal regulatory filings, ANVISA registration records, and customs trade data for plant-derived oil imports. Bottom-up volume builds from salon backbar inventory turns and home user replenishment rhythms cross-check against top-down market sizing.
Assumptions hold EU REACH enforcement timelines, ISO 16128 adoption curves, and cold-process emulsification capacity expansion as fixed boundary conditions across the projection horizon. Segmentation dimensions span product format, ingredient certification tier, formulation vehicle, and end-user channel. CAGR derivation incorporates pricing elasticity by tier, inventory turnover differentials between leave-in and deep conditioning formats, and regulatory compliance cost pass-through rates.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by multinational consumer goods conglomerates would shift outcomes. Quarterly review of ECHA environmental footprint data mandates, Nagoya Protocol implementation rulings, and fermentation-derived active commercialization timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Europe Halal Cosmetics Market
Beauty & Personal Care
Colombia Hair Care Market
Beauty & Personal Care
Deodorant and Antiperspirants Market
Beauty & Personal Care
Global Bath Salts Market
Beauty & Personal Care
Asia-Pacific Beauty and Personal Care Products Market
Beauty & Personal Care
Facial Care Products Market
Beauty & Personal Care
Beauty Salon Market
Beauty & Personal Care
Beauty Fridge Market
Beauty & Personal Care
Dry Shampoo Market
Beauty & Personal Care
Hair Conditioner Market
Beauty & Personal Care
Switzerland Cosmetics Market
Beauty & Personal Care
Lip Care Market
Beauty & Personal Care
GCC Male Grooming Products Market
Beauty & Personal Care
ASEAN Organic Cosmetics Market
Beauty & Personal Care
Powdered Hand Soap Market
Beauty & Personal Care
Beauty Tools Market