

Heat-Resistant Inks for EV Motor Nameplates and Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Heat-Resistant Inks for EV Motor Nameplates and Labels Market Insights
The heat-resistant ink supply base is pivoting between premium silicone-fluoropolymer formulations that withstand continuous operation above 180°C and commodity acrylic systems serving ambient-temperature labeling. Sun Chemical leverages captive pigment synthesis to sustain margin control across high-temperature epoxy grades. Siegwerk Druckfarben anchors European automotive supplier relationships through dedicated EV ink laboratories. Nazdar Ink Technologies specializes in UV-curable platforms that compete on throughput speed for battery marking lines.
Heat-resistant inks for EV motor nameplates and labels comprise engineered resin-pigment systems formulated to maintain legibility, adhesion, and color stability under sustained thermal load, vibration, and dielectric stress in electric drivetrain environments. Silicone-modified formulations dominate the ink type category due to their elastomeric recovery after thermal cycling, while fluoropolymer grades command premium positioning in permanent magnet motor applications where chemical resistance is paramount. Among curing technologies, UV systems represent the fastest-growing segment as automotive suppliers eliminate thermal oven footprints from compact battery plant layouts, whereas thermal curing retains volume leadership in heavy-duty industrial equipment motor rebuild operations.
NHTSA motor identification traceability rules, EPA volatile organic compound limits for coating operations, and REACH substance restrictions on heavy-metal pigments collectively reshape formulation roadmaps and regional market access conditions. The EU Green Deal's embedded carbon reporting requirements are extending upstream to ink raw material sourcing, compelling reformulation investments. Stakeholders must monitor the divergence between regional chemical registration regimes and the accelerating specification pull from Tier 1 motor suppliers consolidating their approved vendor lists around dual-certified ink platforms.
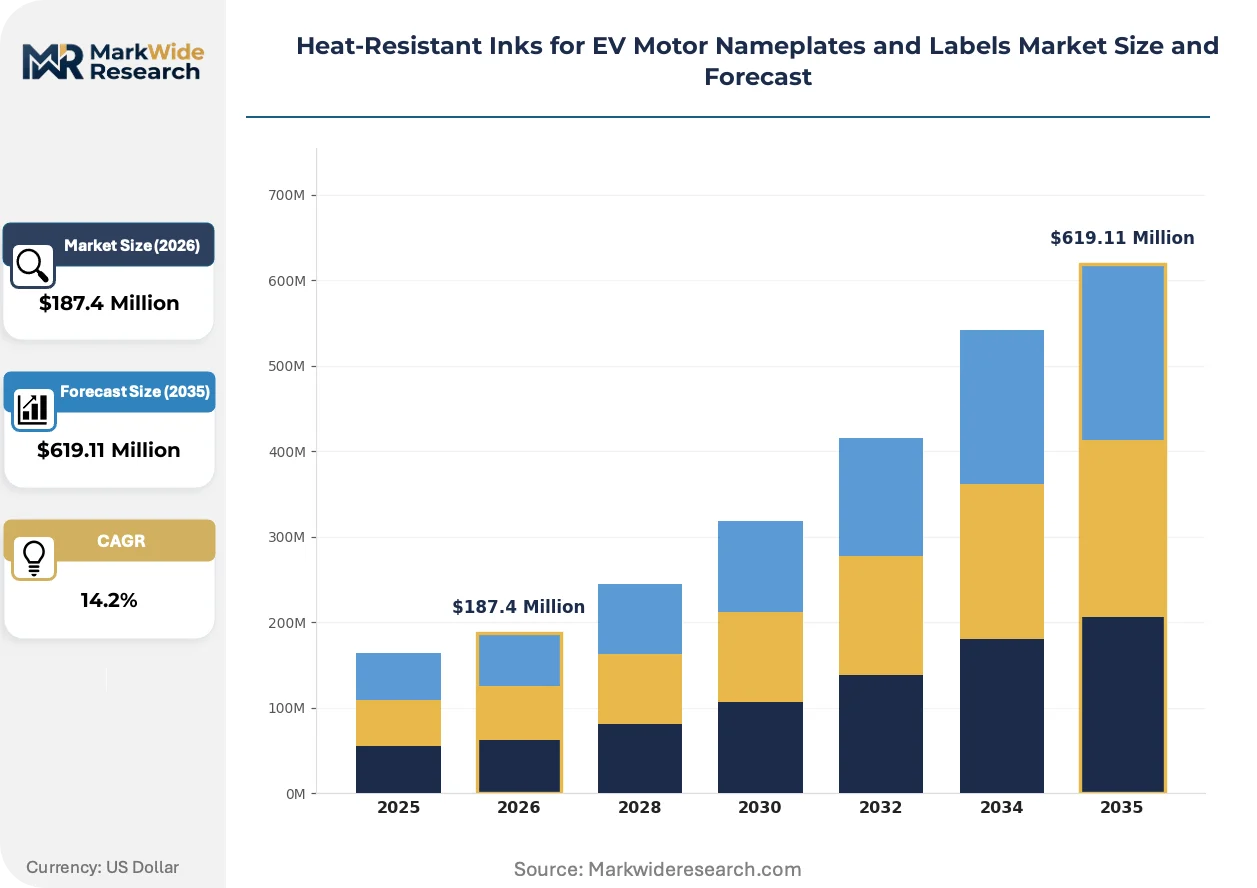
Market Dynamics
Permanent magnet motor architectures are forcing ink suppliers to reformulate for continuous 180°C operation as OEMs eliminate thermal management redundancy from compact drivetrain packages.
Growth Catalysts
- NHTSA Traceability Mandates:Motor identification durability rules now require nameplate legibility across 15-year vehicle lifespans, compelling OEMs to specify silicone-fluoropolymer ink systems for all permanent magnet motor lines.
- Silicone-Modified Formulations:Elastomeric recovery after thermal cycling enables single-pass printing on curved stator housings, eliminating secondary labeling operations at Tesla, BYD, and Volkswagen assembly plants.
- China Domestic Capacity:MIIT localization requirements for EV supply chains are redirecting ink procurement toward certified domestic formulators serving NIO, XPeng, and BYD motor manufacturing clusters in Shenzhen and Hefei.
Market Restraints
- Fluoropolymer Feedstock Concentration:PTFE and PVDF resin supply concentrates among three Japanese chemical conglomerates, exposing ink formulators to price volatility and allocation risk during semiconductor-grade fluoropolymer demand spikes.
- REACH Heavy-Metal Restrictions:Cadmium-based red and lead-chromate yellow pigments face phase-out timelines under EU substance authorization, forcing reformulation of color-stable motor grade inks with inferior thermal performance.
- Laser Marking Substitution:Fiber laser direct-part marking on aluminum motor housings eliminates ink entirely in premium EV platforms, constraining addressable volume in Mercedes-Benz and BMW permanent magnet motor programs.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for domestic EV manufacturing are attracting motor assembly investments from Tata Motors and Mahindra, creating first-mover advantage for ink suppliers establishing local blending operations.
- UV-LED Curing Convergence:Instant polymerization at ambient temperature enables inline printing on battery pack labels and motor nameplates within shared compact production cells, compressing footprint requirements for new Gigafactory installations.
- EU Green Deal Embedded Carbon:Upstream carbon reporting requirements for automotive suppliers are creating preference for bio-based resin inks with verified supply chain transparency, differentiating premium formulators from commodity competitors.
Industry Challenges
- Dual-Certification Talent Scarcity:Formulation chemists capable of navigating simultaneous NHTSA durability validation and REACH substance compliance command premium compensation, constraining R&D bandwidth at mid-tier ink suppliers.
- Thermal Cycling Test Timeline:OEM qualification protocols require 2,000-hour continuous exposure validation, extending new product introduction cycles and freezing formulation innovation during platform lock-in periods.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat-Resistant Inks for EV Motor Nameplates and Labels Market Trends and Innovations
Formulation chemistry is bifurcating between premium fluorosilicone systems for permanent magnet motors and cost-optimized acrylic-urethane hybrids for induction motor rebuild markets, with curing technology selection determining production line economics.
Nano-pigment dispersion technology is electrifying color stability in silicone-based inks, enabling sub-micron particle distribution that maintains chromatic consistency across 10,000 thermal shock cycles. Tier 1 motor suppliers in Germany and the United States are specifying these grades for flagship EV platforms. The technology is electrifying competitive positioning by compressing qualification timelines from 18 months to 9 months for new color formulations.
EPA volatile organic compound limits under the National Emission Standards for Hazardous Air Pollutants are forcing automotive coating operations to eliminate solvent-borne ink systems. Assembly plants in Michigan, Tennessee, and South Carolina are retrofitting print stations for 100% solids UV or water-reducible thermal cure alternatives. Heavy-duty motor rebuild operations retain solvent tolerance under equipment manufacturer exemption categories, creating a two-tier regulatory environment.
Consolidated vendor list requirements from Tier 1 motor suppliers are compressing approved ink sources from 12-15 formulators to 3-4 dual-certified platforms. Buyers now demand unified supply contracts covering North American, European, and Chinese production sites with harmonized specification documents. This concentration is most visible at Bosch, Continental, and Nidec motor manufacturing operations where procurement teams prioritize logistics integration over unit cost negotiation.
Heat-Resistant Inks for EV Motor Nameplates and Labels Market Segmentation
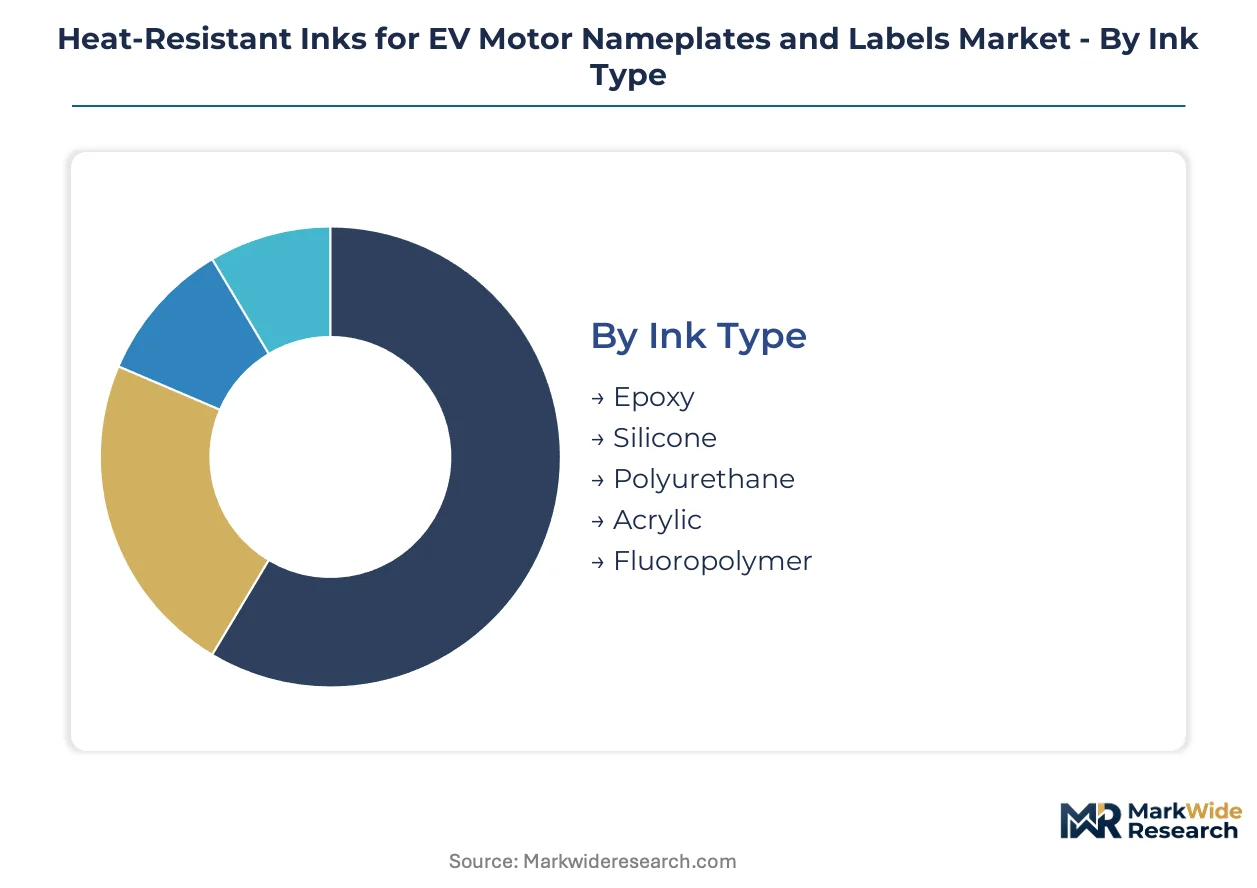
Segmentation in heat-resistant inks determines which formulations qualify for specific motor architectures and which curing systems fit constrained plant footprints. Procurement teams at Tier 1 suppliers segment their vendor lists by certification tier rather than chemistry alone.
Ink Type:
REACH substance authorization and NHTSA thermal durability validation create divergent compliance burdens across resin chemistries, with fluoropolymer and silicone grades requiring the most extensive documentation.
- Silicone:Elastomeric modified polysiloxane resins recover dimensional stability after thermal cycling between -40°C and 200°C. Tesla and BYD specify these grades for curved stator housings in permanent magnet motor lines, eliminating secondary labeling operations.
- Fluoropolymer:PTFE and PVDF-based systems deliver chemical resistance against battery electrolyte exposure and dielectric stress. Bosch and Nidec procurement teams reserve these for flagship EV platforms where 15-year legibility is non-negotiable.
- Epoxy:Rigid thermoset formulations serve industrial motor rebuild markets with lower thermal cycling frequency.
- Polyurethane:Flexible aliphatic grades balance cost and performance for consumer appliance motor labels.
- Acrylic:Cost-optimized systems dominate ambient-temperature induction motor applications with minimal regulatory overhead.
Silicone sits at the top of the volume ranking, with fluoropolymer climbing the fastest.
Application:
Cost tier segmentation separates single-pass inline printing from multi-stage labeling operations, with premium EV motor lines absorbing higher ink costs to eliminate process steps.
- Electric Motor Labels:Continuous 180°C operation requirements dominate formulation specifications. Volkswagen and NIO assembly plants specify silicone-fluoropolymer hybrid inks for permanent magnet stator housings, compressing qualification timelines through nano-pigment dispersion adoption.
- Battery Marking:UV-curable platforms enable inline printing on pack labels within compact Gigafactory cells. Michigan and Tennessee plants prioritize these systems to eliminate thermal oven footprints.
- Circuit Identification:Lower thermal load applications accommodate acrylic-urethane cost optimization.
- Safety Warning Plates:Regulatory visibility mandates drive specification rigidity regardless of cost tier.
- Control Panel Markers:Industrial equipment applications retain solvent-borne tolerance under OEM exemption categories.
Electric motor labels command the dominant revenue share, while battery marking gains share fastest through UV platform adoption.
End User Industry:
Customer type segmentation concentrates procurement power among automotive suppliers consolidating approved vendor lists around dual-certified platforms spanning multiple production sites.
- Automotive Suppliers:Tier 1 motor manufacturers at Bosch, Continental, and Nidec operations demand unified supply contracts covering German, Chinese, and US production with harmonized specifications. These buyers prioritize logistics integration over unit cost negotiation.
- Electronics Manufacturing:Contract assemblers serving battery pack production require UV-LED compatible inks for inline printing at ambient temperature, compressing footprint requirements for new Gigafactory installations.
- Renewable Energy Producers:Wind turbine generator rebuild operations specify thermal-cure epoxy systems for heavy-duty equipment with extended service intervals.
- Industrial Equipment Makers:Motor rebuild shops retain solvent-borne ink tolerance under equipment manufacturer exemption categories.
- Consumer Appliance Builders:Cost-sensitive induction motor applications drive acrylic system specification with minimal compliance overhead.
Automotive suppliers anchor the volume base, with electronics manufacturing expanding most quickly through battery production scaling.
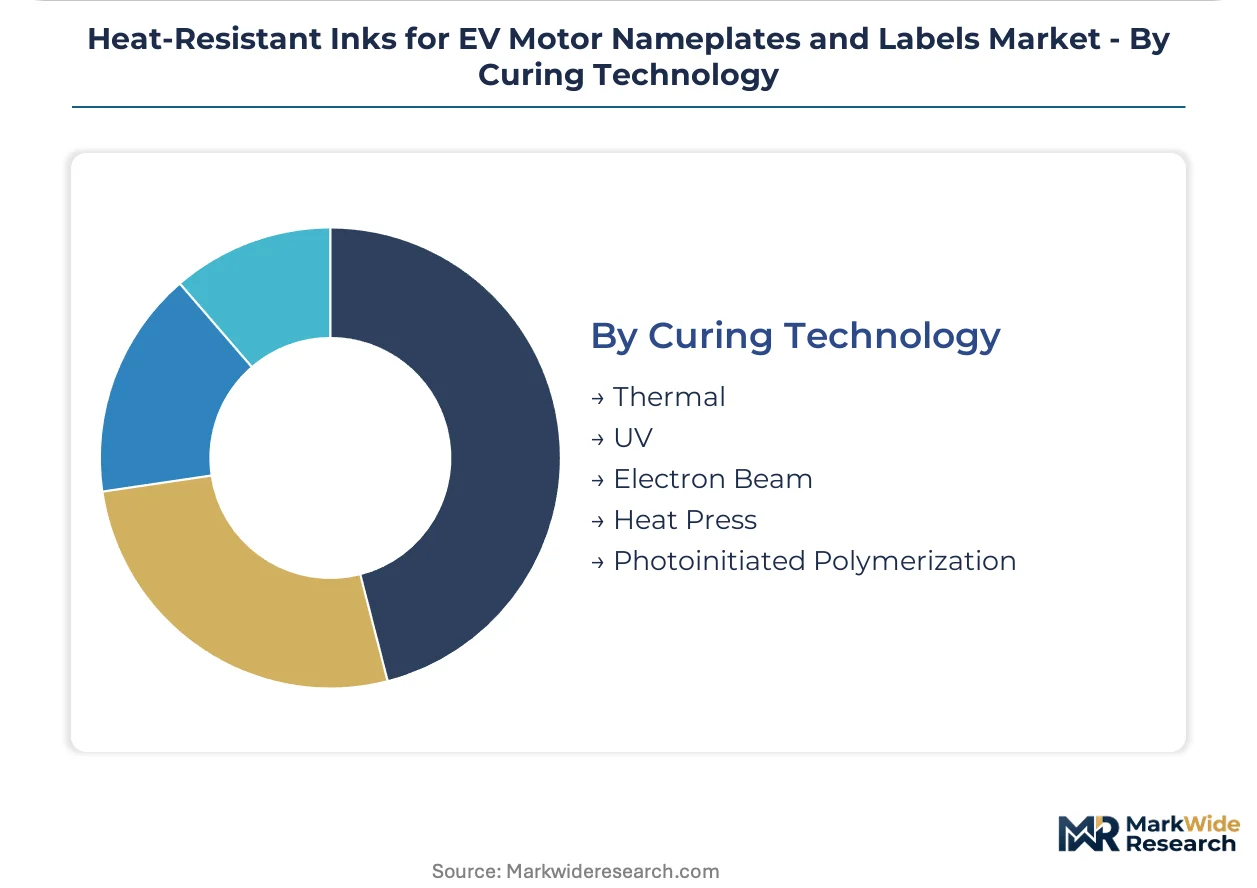
Curing Technology:
Plant footprint constraints and EPA volatile organic compound limits under NESHAP reshape technology selection, with 100% solids alternatives displacing solvent-borne systems in new automotive installations.
- UV:Photoinitiated polymerization at ambient temperature enables inline printing on shared battery and motor production cells. South Carolina and Michigan assembly plants retrofit print stations for these systems to meet EPA emission standards.
- Thermal:Convection and infrared ovens retain volume leadership in heavy-duty industrial equipment motor rebuild operations where thermal mass and cure depth outweigh speed requirements.
- Electron Beam:High-capital systems serve specialized applications requiring instant cure without photoinitiator residues.
- Heat Press:Transfer applications accommodate legacy labeling equipment in consumer appliance manufacturing.
- Photoinitiated Polymerization:Broad category capturing UV-LED and conventional mercury arc systems with varying spectral output optimization.
Thermal curing retains the installed base lead, with UV technology gaining share fastest through new Gigafactory specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists capable of navigating dual-certification requirements concentrate in Germany, China, and the United States, anchoring regional capability clusters where OEM procurement teams source qualified ink platforms.
United States
NHTSA motor identification traceability rules requiring 15-year nameplate legibility drive silicone-fluoropolymer specification at Tesla and General Motors assembly plants. EPA volatile organic compound limits under NESHAP force automotive coating operations toward 100% solids UV alternatives. Michigan and Tennessee motor manufacturing clusters retrofit print stations to eliminate thermal oven footprints from compact battery plant layouts.
Germany
Bosch and Continental procurement teams consolidate approved vendor lists around dual-certified ink platforms spanning multiple production sites. REACH substance restrictions on heavy-metal pigments force reformulation of color-stable motor grade inks with verified supply chain transparency. Bavaria-based motor manufacturing operations prioritize logistics integration over unit cost negotiation in unified supply contracts.
China
MIIT localization requirements for EV supply chains redirect ink procurement toward certified domestic formulators serving NIO, XPeng, and BYD motor manufacturing. Shenzhen and Hefei industrial clusters scale permanent magnet motor production with silicone-modified formulations specified for curved stator housings. The country's national chemical regulator tightens substrate compliance requirements for imported resin systems.
Japan
PTFE and PVDF resin supply concentrates among domestic chemical conglomerates, exposing ink formulators to price volatility during semiconductor-grade fluoropolymer demand spikes. METI industrial standards shape qualification protocols for thermal cycling validation extending new product introduction cycles. Nagoya-area motor component suppliers specify fluoropolymer grades for flagship EV platforms where chemical resistance against battery electrolyte exposure is paramount.
India
Production-linked incentives for domestic EV manufacturing attract motor assembly investments from Tata Motors and Mahindra, creating first-mover advantage for ink suppliers establishing local blending operations. The Bureau of Indian Standards develops thermal durability benchmarks mirroring NHTSA validation timelines. Maharashtra and Gujarat automotive corridors specify silicone-based systems for induction motor rebuild markets with lower regulatory overhead.
Heat-Resistant Inks for EV Motor Nameplates and Labels Market Competitive Landscape
Capital-heavy producers compete with asset-light designers as integrated resin manufacturers sustain margin control through captive pigment synthesis while specialty formulators anchor European automotive supplier relationships through dedicated application laboratories. The supply base concentrates among three strategic tiers: multinational chemical conglomerates with backward integration into fluoropolymer feedstocks, mid-sized regional specialists with dual-certification capabilities, and UV-curable platform innovators competing on throughput speed. Competitive moves center on geographic expansion into battery manufacturing clusters and portfolio diversification toward bio-based resin systems with verified carbon transparency.
Within the multinational tier, Sun Chemical and DIC Corporation exemplify integrated producers with upstream control over high-temperature epoxy pigment synthesis. Siegwerk Druckfarben occupies a position among European specialists leveraging dedicated EV ink laboratories to anchor Tier 1 automotive supplier relationships. Nazdar Ink Technologies represents the UV-curable innovation vector, with its platform specialization aligning with battery marking line throughput requirements at compact Gigafactory installations.
| Leading Market Players |
|---|
| Sun Chemical |
| INX International Ink |
| Siegwerk Druckfarben |
| Flint Group |
| DIC Corporation |
| Toyo Ink SC Holdings |
| Nazdar Ink Technologies |
| Huber Group |
| Wikoff Color |
| Others |
Pricing and Supply Chain Analysis
UV-LED curing platform adoption across compact Gigafactory layouts simultaneously compresses thermal oven capital costs and concentrates procurement power among ink formulators offering 100% solids systems. This technology transition feeds back into supply chain restructuring as Tier 1 motor suppliers consolidate approved vendor lists around dual-certified platforms capable of serving multiple production sites.
Pricing Analysis
Bundled technical service contracts covering qualification support and thermal cycling validation command premium positioning against unbundled commodity ink supply. Pricing stratifies across premium silicone-fluoropolymer, standard epoxy-urethane, and economy acrylic tiers based on certification grade and volume scale. Cost compression in the acrylic segment intensifies as Chinese domestic formulators expand capacity under MIIT localization mandates. Contract assemblers serving battery pack production exhibit highest price sensitivity, while Bosch and Continental procurement teams prioritize logistics integration over unit cost negotiation.
Supply Chain Analysis
MIIT localization requirements and India's PLI scheme are redirecting resin sourcing toward certified domestic blenders in China and emerging formulators in Maharashtra. PTFE and PVDF feedstock draws from Japanese chemical conglomerates, while silicone resin supply centers on German and Chinese specialty chemical producers. Single-source vulnerability concentrates in semiconductor-grade fluoropolymer allocation during demand spikes. Distribution runs through Tier 1 motor supplier consolidated vendor lists with unified supply contracts spanning German, Chinese, and US production sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where formulation chemists capable of simultaneous NHTSA and REACH compliance command premium compensation in Germany and the United States versus emerging cost-competitive capability development in India and China.
For Market Incumbents: To counter laser marking substitution on aluminum motor housings at Mercedes-Benz and BMW, deepen captive pigment synthesis capabilities and anchor Tier 1 relationships through dedicated EV ink laboratories with accelerated qualification timelines. Certification investment represents the critical defensive lever as OEM procurement teams freeze vendor lists around dual-certified platforms. For New Entrants and Emerging Players: Launch via UV-curable platform specialization targeting battery marking lines at compact Gigafactory installations in Michigan and Tennessee. The most penetrable white space sits in bio-based resin systems with verified supply chain transparency for EU Green Deal compliance, with secondary opportunity in domestic blending operations serving India's PLI-driven motor assembly investments. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized regional specialists possessing dual-certification capabilities but lacking geographic scale. Long-term viability hinges on 5-10 year OEM platform lock-in cycles where qualification timelines extend new product introduction windows. Watch nano-pigment dispersion technology adoption as the inflection signal compressing qualification timelines from 18 months to 9 months.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Synthesis | Sun Chemical sustains margin control across high-temperature epoxy grades through captive raw material production. |
| Dedicated EV Ink Laboratory Investment | Siegwerk Druckfarben anchors European automotive supplier relationships through application-specific technical centers. |
| UV-LED Platform Specialization | Nazdar Ink Technologies competes on throughput speed for battery marking lines at Tesla and BYD installations. |
| Domestic Blending Facility Establishment | First-mover suppliers capture India's PLI-driven motor assembly investments from Tata Motors and Mahindra. |
| Bio-Based Resin Reformulation Program | Premium formulators differentiate from commodity competitors under EU Green Deal embedded carbon reporting requirements. |
Research Methodology
Direct dialogue with ink formulation chemists, Tier 1 motor supplier procurement directors, and automotive platform engineers grounded qualitative assessment, cross-referenced with customs and trade data, SEC filings from chemical conglomerates, and vehicle production databases. Bottom-up and top-down triangulation validated volume estimates across resin chemistry segments, curing technology platforms, and regional manufacturing clusters.
Bottom-up modeling aggregated segment-level volume and value outputs across the projection horizon by ink type, application, end user industry, curing technology, and regional production hub. CAGRs derived from fitted growth curves incorporating OEM platform launch schedules, regulatory mandate implementation timelines, and thermal cycling qualification protocol durations. Industry-specific inputs included NHTSA traceability rule compliance costs and REACH substance authorization phase-out schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under fluoropolymer feedstock allocation shocks or accelerated laser marking substitution in premium EV platforms. Forecasts reflect assumptions around OEM vendor list consolidation trajectories and dual-certification talent availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.