
 Rift Sawn Lumber Market | 2026-2036
Rift Sawn Lumber Market Size, Share, and Industry Trends Forecast 2026-2036
Rift Sawn Lumber Market Analytics
Custom millwork shops and boutique furniture studios is redrawing procurement patterns across the rift sawn lumber value chain. Baillie Lumber leverages its hardwood distribution network to secure consistent rift and quartered stock for specialized buyers. Columbia Forest Products sustains vertically integrated plywood and veneer operations that anchor premium-grade feedstock flows. Hickman Lumber specializes in Appalachian and Northern hardwood sourcing, competing on species breadth and kiln-drying precision.
Rift sawn lumber denotes boards cut at a 30- to 60-degree angle to the growth rings, producing straight, parallel grain with minimal fleck and superior dimensional stability against cupping. The process wastes more material than flat sawing, restricting output to premium applications where appearance and stability justify cost. Hardwood rift sawn stock leads flooring and cabinetry segments, where white oak and red oak command premium positioning among specifiers. Engineered wood variants represent the fastest-growing product type, as cross-laminated and veneer-core constructions extend rift grain aesthetics into cost-sensitive commercial interiors. Thin and standard thickness grades dominate volume, while custom thicknesses capture concentrated margin pools in architectural millwork.
The Lacey Act and EU Timber Regulation enforce chain-of-custody documentation, compelling importers to verify species declarations and harvest legality. EPA formaldehyde emission standards and California Air Resources Board Phase 2 requirements shape panel and composite substrate specifications, indirectly filtering rift sawn veneer applications. Stakeholders must monitor enforcement intensity around illegal logging prohibitions and evolving green building certification thresholds to calibrate sourcing geography and species mix.
Market Dynamics
Chain-of-custody documentation requirements under the EU Timber Regulation and the US Lacey Act are compressing supplier networks toward certified hardwood distributors with verifiable harvest legality. This regulatory tightening is amplifying procurement power for vertically integrated millwork operations that control their own drying and grading infrastructure.
Growth Catalysts
- Green building code escalation:California Air Resources Board Phase 2 formaldehyde standards and LEED v4.1 wood sourcing credits are filtering specification pools toward FSC-certified rift sawn stock in commercial interiors.
- White oak specification surge:High-end residential furniture makers are expanding procurement of rift sawn white oak for dining and bedroom collections, drawn to its straight grain stability and light-reflecting properties.
- Engineered wood technology maturation:Cross-laminated timber and veneer-core constructions are extending rift grain aesthetics into cost-sensitive flooring and wall panel applications previously served by solid stock.
Market Restraints
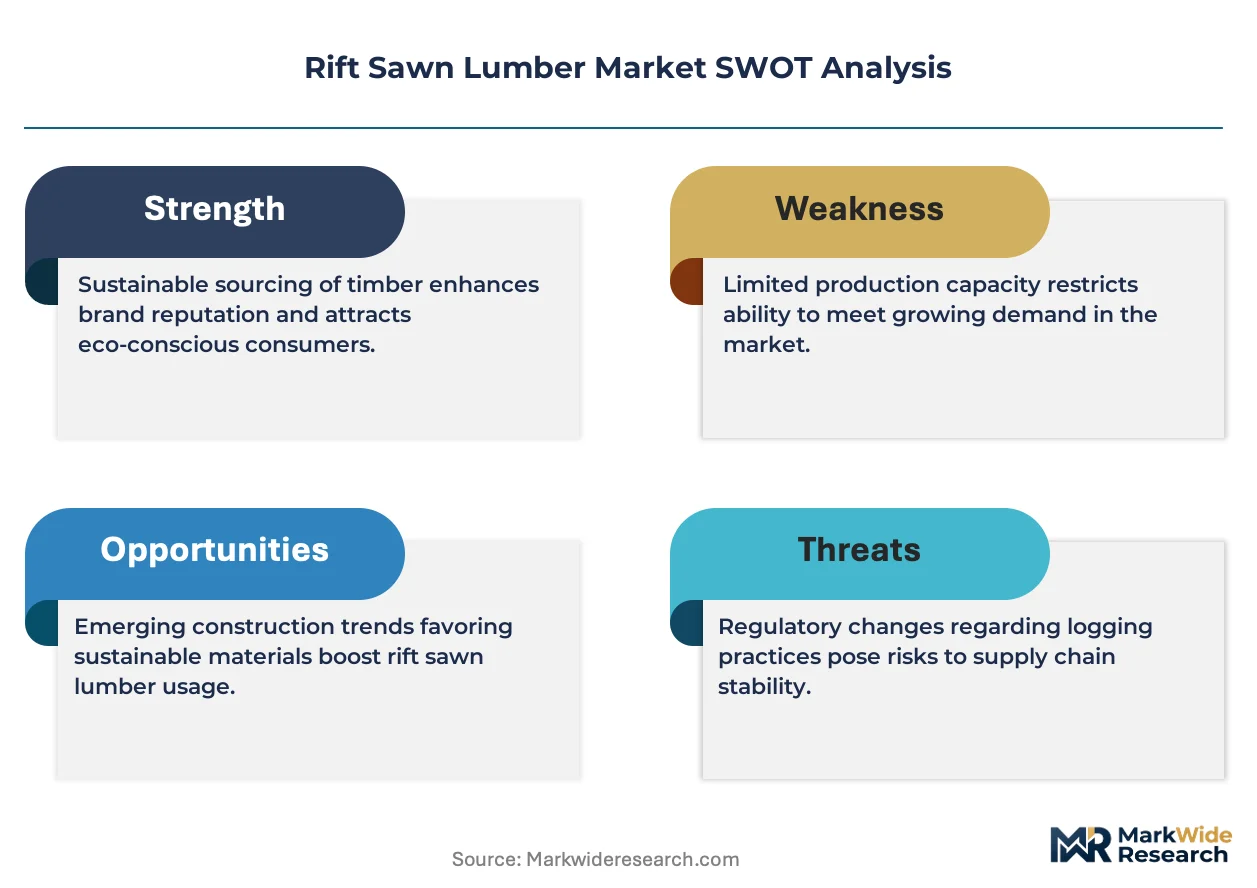
- Raw material yield penalty:Rift sawing wastes 25-40% more log volume than flat sawing, elevating per-board-foot costs and restricting output to premium price-tolerant segments.
- Pacific Northwest supply concentration:Primary white oak rift sawn production clusters in Oregon and Washington create geographic vulnerability to regional weather disruptions and transport bottlenecks.
- Substitution by thermally modified ash:Heat-treated European ash offers comparable dimensional stability at lower cost, capturing specification share in exterior cladding and window frame applications.
Strategic Opportunities
- Underpenetrated German mill cluster expansion:Bavarian and Black Forest hardwood processors are investing in precision rift sawing capacity to serve Central European luxury furniture export markets.
- Mass timber commercial construction:Glue-laminated and nail-laminated timber systems incorporating rift sawn veneer faces are penetrating mid-rise office and hospitality verticals seeking biophilic design elements.
- Digital chain-of-custody platforms:Blockchain-enabled timber tracking systems are reducing compliance documentation burdens for importers navigating EU Timber Regulation due diligence requirements.
Industry Challenges
- Kiln-drying specialist scarcity:Precision moisture content control for rift sawn stock requires experienced operators, and apprenticeship pipelines in Appalachian and Northern hardwood regions are failing to replenish retiring technicians.
- FSC group certification complexity:Small independent sawmills face prohibitive audit costs and administrative burdens to maintain chain-of-custody credentials required by major architectural millwork specifiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rift Sawn Lumber Market |
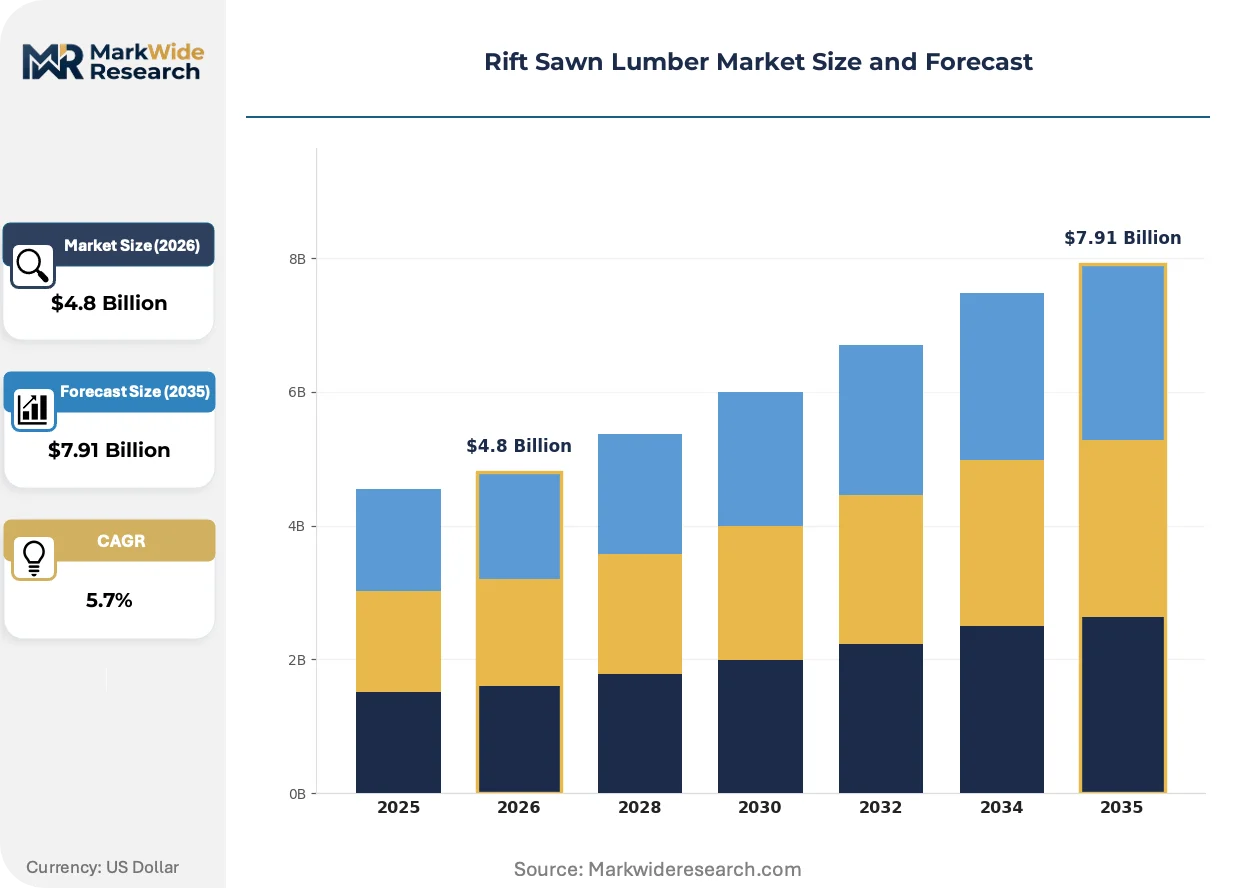
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardwood, Softwood, Engineered Wood, Composite Application: Furniture, Flooring, Cabinetry, Millwork End Use Industry: Construction, Interior Design, Landscaping, Manufacturing Thickness: Thin, Standard, Thick, Custom |
| Companies Covered | Alan McIlvain Company, Church and Church Lumber, Hickman Lumber, Osborne Wood Products, Wood-Mizer, Industrial Hardwood Products, North American Hardwoods, Columbia Forest Products, Baillie Lumber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rift Sawn Lumber Market Evolving Landscape
Automation in hardwood grading and defect detection is compressing quality variance while expanding the addressable market for premium rift sawn products. These developments are reshaping how mills allocate log inventory across sawing patterns.
Computer vision grading systems equipped with multispectral cameras and machine learning algorithms are bifurcating the hardwood sorting process. Large-scale Appalachian sawmills are deploying this technology to separate rift-grain boards at line speed, reducing manual inspection labor by half. The structural consequence is compressing price premiums for mid-grade rift stock while amplifying spreads between defect-free clears and character-grade material.
EU Timber Regulation enforcement intensification is tightening due diligence obligations on US hardwood exporters. The European Commission's 2023 guidance on risk assessment methodologies is compelling importers to verify species declarations through DNA barcoding or isotope analysis. German and Dutch distributors are responding by consolidating supplier relationships toward vertically integrated US mills with in-house forestry operations and documented harvest permits.
Architects and interior designers are rotating specification preferences toward lighter-toned hardwoods with minimal grain variation. This behavioral shift is elevating rift sawn white oak over traditional plainsawn red oak in corporate headquarters and hospitality renovations. The pivot is most visible in Manhattan and Los Angeles commercial interiors, where specifiers pair rift sawn flooring with neutral palettes and matte finishes.
Rift Sawn Lumber Market Segmentation
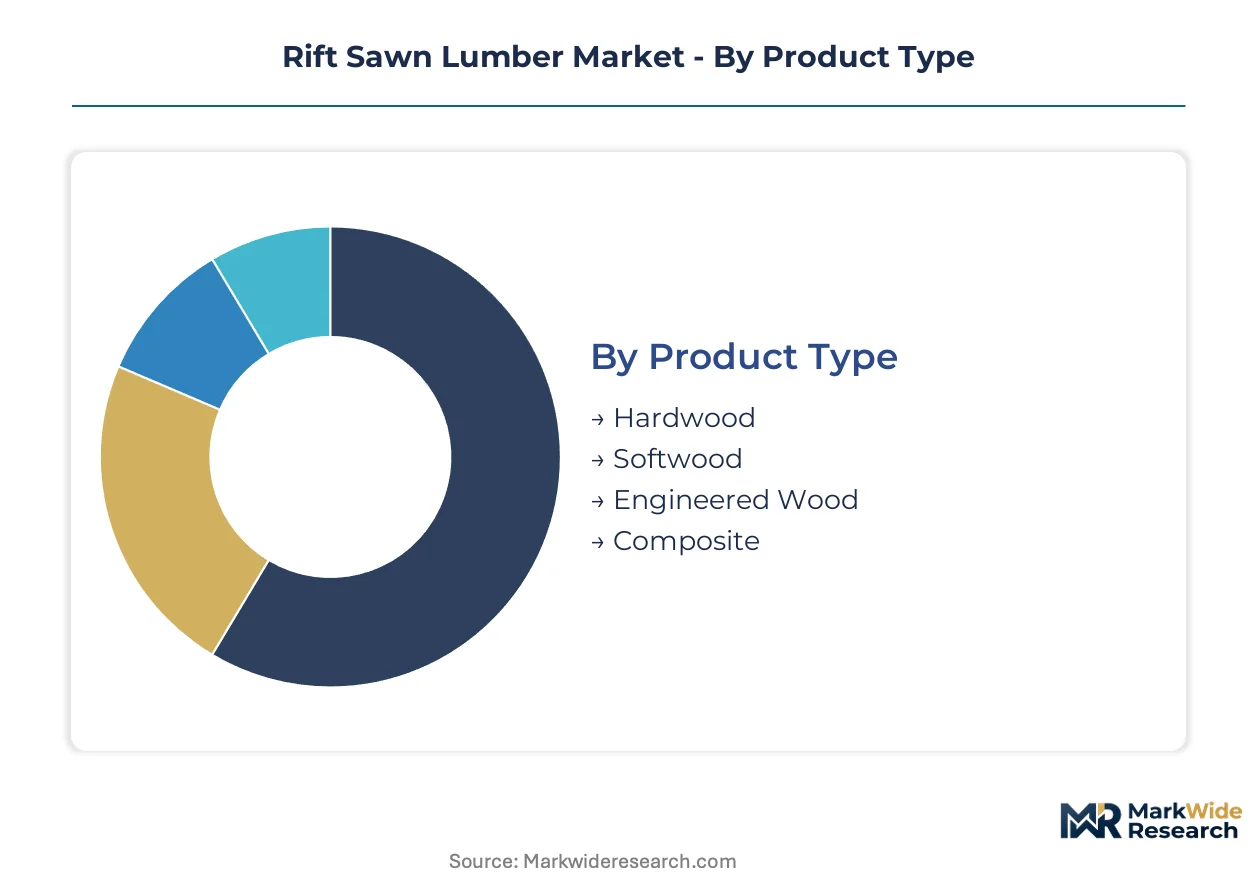
Segmentation in rift sawn lumber reveals how regulatory pressure and yield economics split demand across material grades. Specification requirements for chain-of-custody documentation and dimensional stability standards filter procurement toward particular product types and thickness grades.
Product Type:
EPA formaldehyde emission standards and California Air Resources Board Phase 2 requirements create compliance tiers that separate solid hardwood from engineered alternatives, with certification complexity driving specification divergence across commercial and residential channels.
- Hardwood:White oak and red oak rift sawn stock delivers straight, parallel grain with minimal fleck and superior dimensional stability against cupping. Demand concentrates in high-end residential furniture and premium flooring segments across the United States Pacific Northwest, where specifiers prioritize appearance and stability over cost.
- Engineered Wood:Cross-laminated and veneer-core constructions extend rift grain aesthetics into cost-sensitive commercial interiors through composite substrates. This segment is gaining share fastest in mid-rise office and hospitality verticals seeking biophilic design elements without solid stock premiums.
- Softwood:Limited rift sawn production focuses on specialty architectural applications requiring consistent grain orientation.
- Composite:Wood-plastic and mineral-composite substrates incorporate rift sawn veneer faces for surface aesthetics.
Hardwood handles the majority of throughput; engineered wood is expanding most quickly on share.
Application:
Cost tier stratification separates specification pools, with premium architectural millwork commanding custom thickness premiums while standardized flooring absorbs volume throughput.
- Flooring:Thin and standard thickness grades dominate volume, with rift sawn white oak commanding premium positioning among specifiers in Manhattan and Los Angeles commercial interiors. LEED v4.1 wood sourcing credits filter specification pools toward FSC-certified stock in corporate headquarters renovations.
- Furniture:Dining and bedroom collections from high-end residential furniture makers drive rift sawn white oak procurement for straight grain stability and light-reflecting properties. German luxury furniture export markets anchor demand concentration for precision-cut stock.
- Cabinetry:Dimensional stability requirements favor rift grain orientation in built-in storage and kitchen systems.
- Millwork:Custom thicknesses capture concentrated margin pools in architectural trim, molding, and panel applications.
Flooring moves the highest volume; furniture shows the steepest expansion trajectory on specification value.
End Use Industry:
Customer type fragmentation splits procurement between project-based construction flows and recurring manufacturing contracts, with inventory turnover speed determining margin structure.
- Construction:Mass timber commercial construction penetrates mid-rise office and hospitality verticals through glue-laminated and nail-laminated timber systems incorporating rift sawn veneer faces. German and Dutch distributors consolidate supplier relationships toward vertically integrated US mills with documented harvest permits.
- Interior Design:Boutique studios and custom millwork shops rotate specification preferences toward lighter-toned hardwoods with minimal grain variation, elevating rift sawn white oak over traditional plainsawn alternatives.
- Landscaping:Exterior applications face substitution pressure from thermally modified ash offering comparable dimensional stability.
- Manufacturing:Production furniture and fixture makers absorb standard thickness grades at contract volumes.
Construction absorbs the bulk of tonnage; interior design is climbing the fastest on per-project specification value.
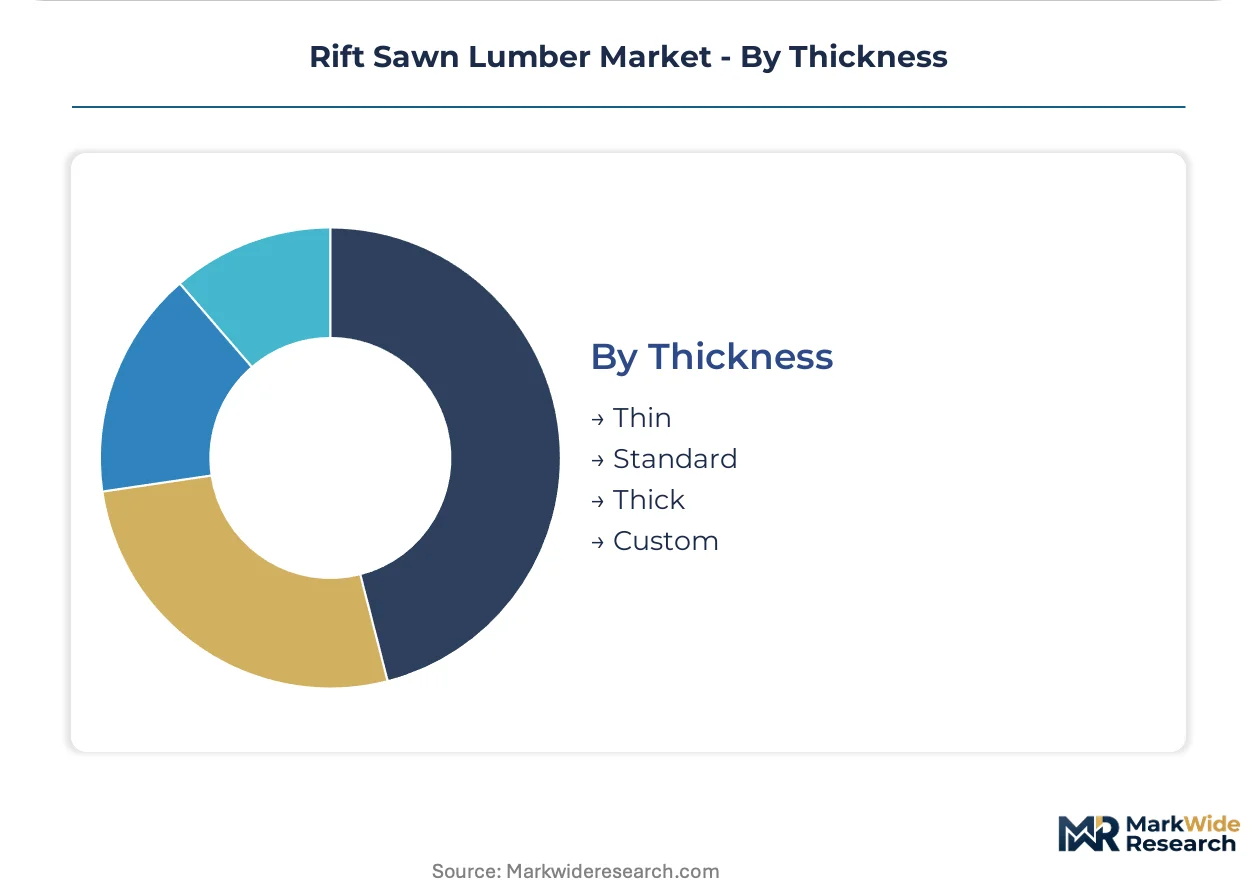
Thickness:
Supply concentration in Appalachian and Northern hardwood kiln-drying infrastructure determines which thickness grades achieve consistent moisture content control.
- Standard:4/4 and 5/4 thickness grades anchor volume production for flooring and furniture manufacturing, with precision moisture content control from experienced kiln operators in Appalachian mill clusters. Yield penalties from rift sawing restrict output to premium price-tolerant segments.
- Custom:Architectural millwork specifications demand non-standard dimensions that capture concentrated margin pools, though FSC group certification complexity creates barriers for small independent sawmills serving this channel.
- Thin:Veneer and lamination feedstock for engineered wood substrates.
- Thick:Heavy timber and structural applications requiring extended drying cycles.
Standard thickness handles the majority of board-foot volume; custom thickness is gaining share fastest on margin contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Custom millwork shops and boutique furniture studios concentrate procurement power in specific geographic clusters where kiln-drying infrastructure and certified hardwood supply chains align. Buyer archetypes split between high-end residential furniture makers seeking white oak stability and commercial specifiers demanding FSC-certified stock for LEED projects.
United States
Manhattan and Los Angeles commercial interiors drive rift sawn white oak specification for corporate headquarters renovations. EPA formaldehyde emission standards and California Air Resources Board Phase 2 requirements filter panel and composite substrate applications. Pacific Northwest mill clusters in Oregon and Washington anchor primary white oak production, though regional weather disruptions create periodic supply vulnerability.
Germany
Luxury furniture export markets in Bavaria and the Black Forest absorb precision-cut rift sawn stock for dining and bedroom collections. EU Timber Regulation enforcement intensification through 2023 risk assessment guidance compels DNA barcoding verification of species declarations. German distributors consolidate supplier relationships toward vertically integrated US mills with documented harvest permits and in-house forestry operations.
Canada
Cross-laminated timber and mass timber commercial construction in British Columbia and Ontario penetrates mid-rise office verticals seeking biophilic design elements. Health Canada and PMRA oversee wood product safety standards that align with US EPA emission benchmarks. Quebec hardwood processors compete on species breadth and kiln-drying precision for architectural millwork feedstock.
Netherlands
Dutch distributors serve as Central European consolidation points for FSC-certified rift sawn imports from North American sources. EU Timber Regulation due diligence obligations shape procurement documentation requirements across Rotterdam and Amsterdam trading hubs. Randstad-based millwork specialists demand custom thickness grades for concentrated margin pools in trim and molding applications.
United Kingdom
London and Southeast commercial renovation projects specify lighter-toned hardwoods with minimal grain variation for neutral palette interiors. UK timber regulations enforce chain-of-custody documentation parallel to EU Timber Regulation standards post-Brexit. Midlands furniture manufacturers source Appalachian and Northern hardwood through established import channels.
Rift Sawn Lumber Market Competitive Landscape
Player mix skews toward regional hardwood distributors with captive drying infrastructure and vertically integrated forest products groups. Market structure concentrates procurement power among certified suppliers capable of documenting harvest legality under Lacey Act and EU Timber Regulation requirements. Three archetypes dominate: Appalachian kiln-drying specialists, Pacific Northwest white oak processors, and multi-species hardwood distributors with cross-regional sourcing networks. Competitive moves center on backward integration into forestry operations and strategic partnerships with mass timber fabricators seeking veneer-grade feedstock.
Among North American hardwood distributors, Baillie Lumber and Columbia Forest Products occupy positions anchoring premium-grade feedstock flows to specialized buyers. Hickman Lumber represents the Appalachian kiln-drying specialist archetype, competing on species breadth and precision moisture content control. These three exemplify how documented chain-of-custody credentials and in-house grading infrastructure separate tier-one suppliers from commodity-positioned competitors.
| Leading Market Players |
|---|
| Alan McIlvain Company |
| Church and Church Lumber |
| Hickman Lumber |
| Osborne Wood Products |
| Wood-Mizer |
| Industrial Hardwood Products |
| North American Hardwoods |
| Columbia Forest Products |
| Baillie Lumber |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Pacific Northwest white oak mills and high-end furniture manufacturers lock in supply access while providing price visibility against volatile log auction markets. These contracts index to regional stumpage benchmarks plus fixed processing premiums, insulating buyers from spot market spikes while committing suppliers to certified chain-of-custody documentation.
Pricing Analysis
Cost-plus contracts with stumpage indexation dominate rift sawn lumber procurement, tying board-foot prices to regional log auction benchmarks plus kiln-drying and grading premiums. Three-tier pricing structure across premium clears, standard grade, and character-grade stock separates FSC-certified architectural millwork from commodity flooring. Pricing pressure stems from thermally modified ash substitution in exterior applications, compressing margins on dimensional stability-driven specifications. Commercial interior designers show lowest price sensitivity, prioritizing LEED v4.1 compliance and grain consistency over per-board-foot cost.
Supply Chain Analysis
Oregon and Washington anchor primary white oak rift sawn production, while Bavarian and Black Forest mill clusters serve Central European luxury furniture export markets. Raw material flows draw from Appalachian and Northern hardwood forests, with kiln-drying capacity concentrated in Pennsylvania and Ohio mill networks. Single-source vulnerability runs through Pacific Northwest weather disruptions and transport bottlenecks along I-5 corridors. Distribution feeds through certified hardwood distributors with documented harvest permits, consolidating toward vertically integrated operations with in-house forestry and drying infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the rift sawn lumber value chain creates acquisition opportunities as regulatory documentation requirements and kiln-drying specialist scarcity force consolidation. Boutique furniture studios and custom millwork shops are fragmenting procurement patterns, opening niches for specialized suppliers.
For Market Incumbents: Consolidate backward integration into Appalachian and Northern hardwood forestry operations to secure captive log supply and harvest permit documentation. Acquire precision kiln-drying facilities in Pennsylvania and Ohio to replace retiring technician expertise. Certification investment in FSC group credentials separates tier-one suppliers from commodity-positioned competitors facing audit cost barriers. For New Entrants and Emerging Players: Lead with digital chain-of-custody platforms targeting German and Dutch distributors burdened by EU Timber Regulation due diligence documentation. Underpenetrated Bavarian and Black Forest mill clusters offer geographic white space for precision rift sawing capacity. Mass timber fabricators seeking veneer-grade feedstock provide a direct go-to-market channel bypassing traditional distributor networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated hardwood distributors with documented harvest legality and captive drying infrastructure. Five-to-ten-year viability rests on regulatory enforcement intensity around illegal logging prohibitions and green building certification thresholds. Watch for EU Timber Regulation enforcement intensification and DNA barcoding verification mandates as inflection indicators accelerating supplier network compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forestry Operations | Captive log supply secures harvest permit documentation required by EU Timber Regulation and US Lacey Act enforcement. |
| Precision Kiln-Drying Capacity Expansion | Experienced operator scarcity in Appalachian regions creates defensive moat around moisture content control capabilities. |
| FSC Group Certification Investment | Audit cost barriers exclude small independent sawmills from architectural millwork specification pools. |
| Digital Chain-of-Custody Platform Deployment | Blockchain-enabled timber tracking reduces compliance documentation burdens for EU and US importers navigating due diligence. |
| Mass Timber Fabricator Partnership | Biophilic design demand in mid-rise office verticals extends rift grain aesthetics through veneer-core constructions. |
Research Methodology
A standing panel of hardwood mill operators, kiln-drying technicians, architectural millwork procurement managers, and luxury furniture production directors provided ongoing calibration across primary interview rounds. Secondary validation drew from US Forest Service timber output data, EPA formaldehyde emission standard filings, EU Timber Regulation enforcement guidance, and California Air Resources Board Phase 2 compliance records. Bottom-up volume modeling across product types, thickness grades, and end-use industries triangulated against top-down macroeconomic indicators.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across hardwood, engineered wood, softwood, and composite product types; flooring, furniture, cabinetry, and millwork applications; construction, interior design, landscaping, and manufacturing end-use industries; and standard, custom, thin, and thick thickness grades. CAGRs derived from log supply constraints, yield penalty economics, and specification trend trajectories in commercial interiors and residential furniture.
Forecasts assume regulatory continuity in EU Timber Regulation enforcement and US Lacey Act chain-of-custody requirements; material policy shifts would require re-modeling harvest legality verification protocols and green building certification thresholds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
US Mattress Bases Market
Homecare and Decor
Asia-Pacific Decorative Laminates Market
Homecare and Decor
Japan Sustainable Home Decor Market
Homecare and Decor
Global Decorative Laminates Market
Homecare and Decor
India Wallpapers Market
Homecare and Decor
Christmas Tree Market
Homecare and Decor
Bulletin Board Market
Homecare and Decor
Curtains and Window Blinds Market
Homecare and Decor
USA Bed Pillow Market
Homecare and Decor
Door Stopper Market
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
Wall Covering Products Market
Homecare and Decor
Asia-Pacific Sustainable Home Decor Market
Homecare and Decor
Asia-Pacific Interior Doors Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
Pillow Market