
 Sheet Face Mask Market | 2026-2036
Sheet Face Mask Market Size, Share, and Industry Trends Forecast 2026-2036
Sheet Face Mask Market Intelligence
Subscription-based replenishment programs for sheet face masks is realigning how brands monetize recurring consumer relationships. Amorepacific anchors its market presence through premium biocellulose lines tied to loyalty-driven auto-delivery models. L'Oréal leverages its mass-market distribution scale to compete in single-use hydration segments across multiple retail channels. Estée Lauder Companies differentiates through clinical-positioned anti-aging sheet treatments that command higher per-unit margins.
A sheet face mask consists of a pre-cut fabric or gel substrate saturated with active serum, designed for occlusive delivery of humectants, peptides, and botanical extracts to facial skin through sustained contact. Biocellulose variants, fermented from microbial cellulose, achieve superior adhesion and serum retention compared to traditional cotton or fiber substrates. The biocellulose product type captures premium positioning due to manufacturing complexity and enhanced efficacy claims. Hydrating feature formulations dominate volume sales, while anti-aging treatments concentrate margin pools through peptide-infused positioning. Eco-friendly packaging is gaining structural importance as regulatory pressure and consumer preference converge on reduced plastic waste.
FDA cosmetic labeling requirements and the EU REACH framework govern ingredient disclosure and safety substantiation for sheet face masks sold in the United States and Europe. South Korea's MFDS maintains stringent standards for functional cosmetics claims, creating compliance barriers that favor established R&D-intensive manufacturers. China's NMPA registration process for imported cosmetics adds procedural depth for brands seeking access to that consumer base. Stakeholders must monitor evolving biodegradability mandates and ingredient blacklists across these jurisdictions to anticipate reformulation costs and market access timelines.
Market Dynamics
Biocellulose fermentation technology is compressing manufacturing cycles while elevating efficacy benchmarks, forcing substrate suppliers to retool or exit as Seoul-based R&D clusters tighten their grip on premium fiber supply.
Growth Catalysts
- EU REACH compliance pressure:Manufacturers are accelerating cleaner formulation development to meet ECHA ingredient disclosure mandates, opening premium positioning for biocellulose alternatives that satisfy safety substantiation requirements.
- Salon channel expansion:Professional skincare clinics are bundling clinical-grade sheet masks into post-treatment retail protocols, creating pull-through demand for at-home maintenance SKUs.
- Seoul fermentation clusters:Concentrated R&D infrastructure in South Korea's capital region continues advancing microbial cellulose yields, lowering unit costs for next-generation substrate production.
Market Restraints
- Biocellulose supply concentration:Fermentation-derived substrate manufacturing remains concentrated among a handful of South Korean and Japanese suppliers, creating input vulnerability for brands outside Northeast Asia.
- EU packaging waste directives:The EU Green Deal's plastics reduction mandates are forcing costly packaging redesigns for single-use sachet formats that dominate mass-market distribution.
- Cotton substrate commoditization:Traditional fiber-based masks face margin compression as private-label manufacturers flood mass channels with undifferentiated hydration products.
Strategic Opportunities
- Men's grooming penetration:Male skincare adoption in urban China and Southeast Asian metros remains underdeveloped relative to female cohorts, offering first-mover positioning for targeted biocellulose formulations.
- Subscription auto-replenishment:Direct-to-consumer platforms are capturing recurring revenue through algorithmic skin assessment tools that personalize monthly mask curation.
- Biodegradable substrate innovation:Regulatory tailwinds from China's dual carbon goals and EU biodegradability mandates are accelerating investment in compostable fiber alternatives to petroleum-derived materials.
Industry Challenges
- Fermentation scale-up complexity:Translating lab-grade biocellulose yields to industrial production requires specialized bioreactor engineering talent that remains scarce outside established Korean manufacturing hubs.
- Cross-border registration timelines:China's NMPA cosmetics filing process creates extended market access delays for imported functional claims, compressing first-mover windows for innovation-led brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheet Face Mask Market |
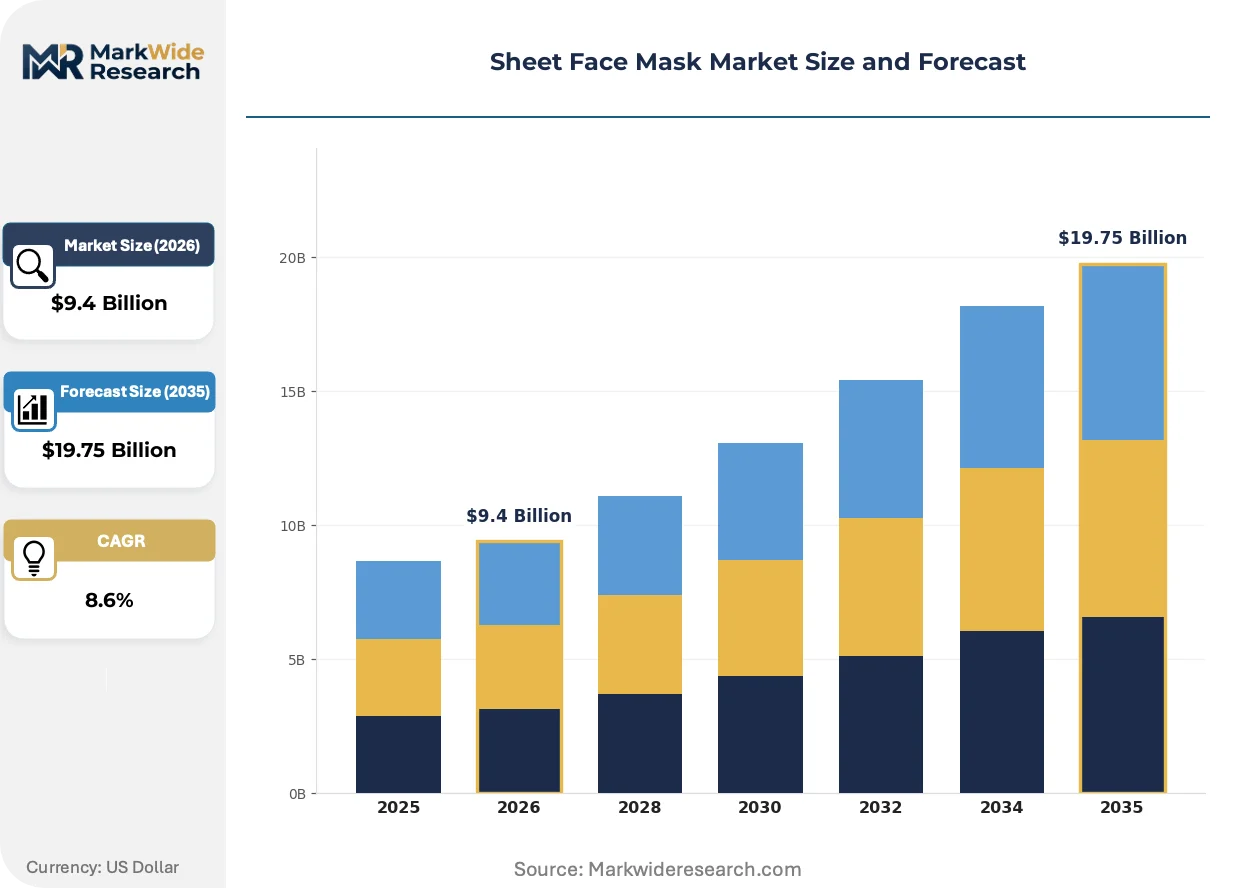
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $19.75 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogel, Fiber, Cotton, Biocellulose Feature: Nourishing, Brightening, Hydrating, Anti-Aging End User: Women, Men, Teens, Salons Packaging Type: Single-use, Multi-pack, Refill, Eco-friendly |
| Companies Covered | Taiki, Estée Lauder Companies, Procter & Gamble, BioRepublic, Shiseido, Amorepacific, ELOV Cosmetics, Tonymoly, L'Oréal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheet Face Mask Market Strategic Shifts & Innovations
Fermentation-derived manufacturing processes are rewriting substrate economics while regulatory pressure on ingredient transparency and packaging waste accelerates format innovation across premium and mass tiers.
Biocellulose substrates grown from Acetobacter xylinum bacterial cultures are electrifying adhesion performance standards in clinical and premium home-use segments. Dermatology clinics and medi-spa chains are adopting these masks for post-procedure protocols where serum retention and skin contact uniformity drive outcomes. The technology is electrifying competitive pressure on cotton and hydrogel alternatives, compressing their viable positioning to price-sensitive mass retail.
EU REACH framework amendments on nanomaterial classification are forcing reformulation of peptide-delivery systems used in anti-aging sheet treatments. Manufacturers must now submit extended safety dossiers for active ingredients previously grandfathered under earlier cosmetic directives. Premium biocellulose lines targeting European distribution are responding by sourcing fermentation-derived actives with pre-cleared toxicological profiles.
Direct-to-consumer skin diagnostic platforms are fragmenting traditional retail dependency for mask replenishment. Algorithmic facial analysis tools on mobile applications are displacing in-store sampling as the primary trial mechanism, particularly among millennial and Gen-Z cohorts in South Korea and urban China. This behavioral pivot is most visible in Seoul's digitally native brand ecosystem, where subscription attach rates now exceed conventional e-commerce repurchase frequency.
Sheet Face Mask Market Segmentation
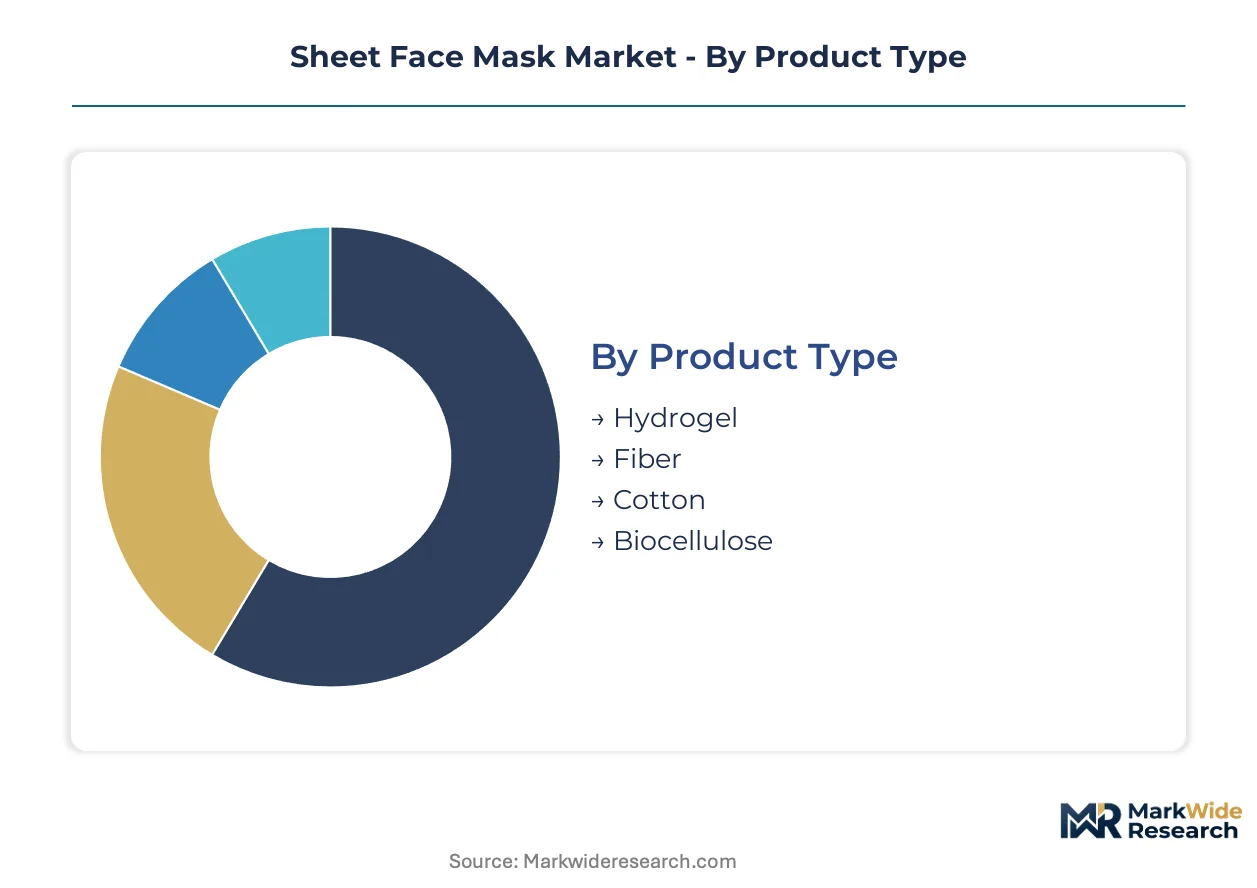
Sheet face mask segmentation reveals how substrate technology, functional positioning, and distribution format determine regulatory pathway complexity and margin architecture. Manufacturers must align formulation claims with jurisdiction-specific approval requirements while managing divergent cost structures across material tiers.
Product Type:
FDA cosmetic labeling and EU REACH substance restrictions apply differentially across substrate categories, with fermentation-derived materials facing heightened ECHA scrutiny for novel ingredient classification.
- Biocellulose:Microbial cellulose grown from Acetobacter xylinum cultures delivers superior serum retention and skin adhesion through nanofiber network density. Seoul-based fermentation facilities supply premium substrate to dermatology clinics in South Korea and Japan seeking post-procedure protocols with validated occlusion performance. ECHA's evolving nanomaterial guidance creates compliance overhead for European market entry.
- Hydrogel:Cross-linked polymer matrices provide cooling sensation and sustained moisture release through gel-phase water retention. Demand concentrates in Japanese professional channels where medi-spa operators prioritize temperature-modulated treatments for sensitive skin protocols. China's NMPA registration timeline for imported hydrogel formulations extends market access windows versus domestic alternatives.
- Fiber:Synthetic or semi-synthetic nonwoven substrates offer cost-efficient manufacturing with adjustable porosity for serum loading.
- Cotton:Natural cellulose fiber from Gossypium species provides breathable, biodegradable substrate for mass-market hydration positioning.
Leading the category by volume: Cotton. Expanding most quickly: Biocellulose.
Feature:
Functional claim substantiation requirements vary sharply across benefit categories, with anti-aging positioning triggering stricter MFDS and NMPA documentation burdens than basic hydration.
- Anti-Aging:Peptide-infused formulations targeting collagen synthesis and wrinkle reduction require clinical validation dossiers for functional cosmetics classification in South Korea and China. Seoul-based brands leverage fermentation-derived actives with pre-cleared toxicological profiles to accelerate MFDS approval timelines. Premium pricing power depends on peptide concentration transparency and delivery mechanism patents.
- Hydrating:Hyaluronic acid and glycerin-based humectant formulations dominate unit sales through lower regulatory barriers and broader demographic appeal. Mass-market penetration in urban China and Southeast Asian metros relies on single-use sachet affordability and impulse retail placement. EU packaging waste directives are forcing format innovation away from multi-layer plastic sachets.
- Brightening:Niacinamide and vitamin C derivatives target melanin regulation and tone uniformity through antioxidant pathways.
- Nourishing:Botanical oil and ceramide complexes emphasize barrier repair and lipid replenishment for dry or compromised skin conditions.
Capturing the largest volume share: Hydrating. Steepest expansion trajectory: Anti-Aging.
End User:
Customer archetype determines channel strategy, with professional salon procurement favoring bulk biocellulose formats while teen segments drive social commerce trial through influencer-curated assortments.
- Women:Established core demographic with mature purchase patterns across all distribution channels and price tiers. Subscription auto-replenishment platforms in South Korea and urban China achieve highest attach rates among professional women aged 25-40 seeking algorithmic skin assessment personalization.
- Salons:Professional skincare clinics and medi-spa chains require clinical-grade biocellulose with validated post-procedure protocols and wholesale pricing structures. Post-treatment retail bundling creates pull-through demand for at-home maintenance SKUs with matched ingredient positioning.
- Men:Underpenetrated cohort in urban China and Southeast Asian metros with rising grooming routine sophistication.
- Teens:Social-native consumers discovering sheet masks through short-form video platforms and peer recommendation algorithms.
Driving absolute volume: Women. Gaining share fastest: Salons.
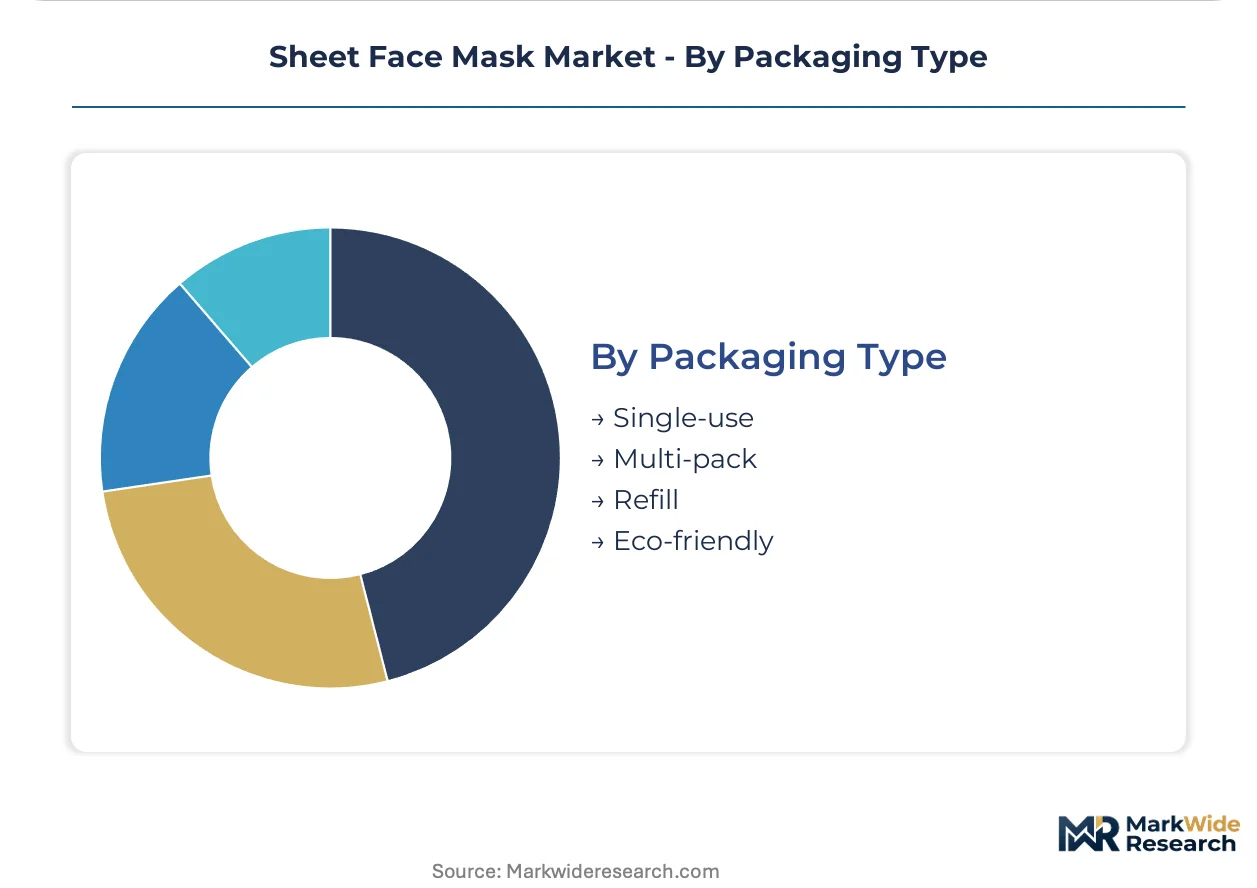
Packaging Type:
Format economics and environmental compliance are converging as EU Green Deal mandates and China's dual carbon goals reshape single-use sachet viability.
- Eco-friendly:Compostable films, recycled paperboard, and refillable vessel systems address regulatory pressure from EU packaging waste directives and consumer preference shifts in German and French markets. Biodegradable substrate pairing creates premium positioning with substantiated sustainability claims. Manufacturing cost premiums of 15-30% versus conventional formats compress margins without price repositioning.
- Single-use:Individual sachet formats dominate mass-market distribution through low trial cost and travel convenience. China's NMPA labeling requirements and EU ECHA substance disclosure mandates add compliance overhead per SKU variant. Plastics reduction timelines under EU Green Deal are forcing material transitions to aluminum-laminate or paper-based alternatives.
- Multi-pack:Bundled assortments reduce per-unit packaging cost and support subscription economics.
- Refill:Concentrate or dry mask formats with separate serum activation reduce shipping weight and packaging material intensity.
Highest unit volume: Single-use. Climbing the fastest: Eco-friendly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors biocellulose substrate innovation through concentrated fermentation R&D clusters that supply premium fiber to dermatology clinics worldwide. The city's manufacturing infrastructure shapes global efficacy benchmarks and cost structures for next-generation mask production.
United States
Professional medi-spa chains in Los Angeles and New York Metro drive clinical-grade biocellulose adoption for post-procedure retail protocols. FDA cosmetic labeling requirements govern ingredient disclosure for peptide-infused anti-aging treatments. Miami's aesthetic clinic corridor generates pull-through demand for at-home maintenance SKUs with matched ingredient positioning.
South Korea
Seoul Capital Area fermentation facilities achieve industrial-scale Acetobacter xylinum yields that compress manufacturing cycles for premium substrate. MFDS functional cosmetics standards create compliance barriers favoring established R&D-intensive manufacturers with pre-cleared toxicological dossiers. Busan-Ulsan packaging innovation clusters develop compostable film alternatives to conventional plastic sachets.
China
Urban consumers in Shanghai and Beijing accelerate subscription auto-replenishment through algorithmic skin assessment platforms. NMPA registration timelines for imported functional claims compress first-mover windows for foreign brands seeking market access. Guangzhou's cosmetics manufacturing belt produces cost-efficient cotton substrates for mass-market hydration segments.
Japan
Tokyo-based medi-spa operators prioritize temperature-modulated hydrogel treatments for sensitive skin protocols in professional channels. METI standards influence regional packaging waste reduction timelines that pressure single-use format redesign. Osaka-Kobe industrial corridors supply cross-linked polymer matrices with adjustable porosity for serum loading optimization.
Germany
EU REACH nanomaterial classification amendments force reformulation of peptide-delivery systems targeting the European market. ECHA substance disclosure mandates accelerate cleaner biocellulose development for brands seeking premium positioning. Frankfurt's logistics hub distributes eco-friendly compostable formats to French and Benelux markets facing stringent plastics reduction timelines.
Sheet Face Mask Market Key Industry Players
Capital-heavy fermentation facilities compete with asset-light brand designers for margin capture in the sheet face mask sector. The market structure concentrates premium substrate supply among a handful of Northeast Asian manufacturers while brand portfolios fragment across mass, prestige, and professional tiers. Three archetypes dominate: Seoul-based fermentation specialists controlling fiber economics, multinational beauty conglomerates leveraging distribution scale, and digitally native direct-to-consumer labels capturing subscription attach rates. Competitive intensity centers on bioreactor capacity expansion and algorithmic personalization platform development.
Among Seoul-based R&D anchors, Amorepacific and Tonymoly exemplify the fermentation-to-brand integration archetype that tightens grip on premium fiber supply chains. Shiseido occupies a position bridging Japanese professional channel depth with mass-market Asian distribution. At the scale-driven end, L'Oréal and Estée Lauder Companies represent multinational conglomerates competing through clinical-positioned anti-aging treatments and mass-market hydration volume respectively. These players illustrate how geographic R&D concentration translates into divergent margin architectures across substrate technology tiers.
| Leading Market Players |
|---|
| Taiki |
| Estée Lauder Companies |
| Procter & Gamble |
| BioRepublic |
| Shiseido |
| Amorepacific |
| ELOV Cosmetics |
| Tonymoly |
| L'Oréal |
| Others |
Cost & Logistics Intelligence
Family-owned fermentation specialists in South Korea's Gyeonggi Province anchor premium biocellulose substrate supply, translating concentrated ownership into pricing discipline that resists commoditization pressure from mass-market cotton alternatives. Their captive control over Acetobacter xylinum cultivation facilities allows margin defense through volume-restricted premium positioning, while EU REACH compliance costs and Chinese NMPA registration timelines amplify price differentiation between clinical-grade and consumer-tier formats.
Pricing Analysis
Outcome-based pricing anchored to post-procedure skin recovery metrics dominates professional channel transactions, with dermatology clinics in Seoul and Los Angeles paying premiums for validated occlusion performance. Three-tier pricing structure across premium biocellulose, mid-tier hydrogel, and economy cotton tiers separates clinical efficacy claims from basic hydration positioning. Pricing pressure stems from private-label cotton mask proliferation in Southeast Asian mass retail, compressing margins at the economy tier. Salon procurement teams exhibit lowest price sensitivity, while teen social commerce buyers drive aggressive discounting through influencer-curated flash promotions.
Supply Chain Analysis
China's dual carbon goals and domestic-content preferences for green manufacturing certification are reshaping sourcing patterns for compostable packaging films and fermentation-derived actives. Raw material flows draw from South Korean biocellulose substrate, Japanese hydrogel polymer matrices, and Chinese cotton fiber processing clusters. Single-source vulnerability concentrates in Seoul Capital Area fermentation facilities, where specialized bioreactor engineering talent scarcity limits rapid capacity replication. Distribution runs through professional clinic wholesale networks in Northeast Asia, direct-to-consumer subscription platforms in urban China, and multi-brand beauty retailers in European metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream substrate control and downstream algorithmic personalization platforms represent the decisive levers for margin capture. Players pursuing captive fermentation capacity or proprietary skin assessment tools are consolidating structural advantage over asset-light brand competitors.
For Market Incumbents: Lock in exclusive fermentation capacity agreements with Seoul-based substrate suppliers before bioreactor expansion constraints tighten further. Prioritize MFDS pre-clearance dossiers for peptide-infused anti-aging lines to accelerate Chinese NMPA registration timelines against emerging domestic challengers. Defend salon channel relationships through co-developed post-procedure protocol bundles that create switching costs for clinic procurement teams. For New Entrants and Emerging Players: Male urban professionals in Shanghai and Jakarta represent an underserved buyer archetype with rising grooming sophistication and minimal existing sheet mask loyalty. Target biodegradable substrate innovation paired with aluminum-laminate sachet formats to satisfy EU Green Deal compliance without incumbent legacy packaging conversion costs. Launch through men's lifestyle vertical platforms rather than competing for shelf space in female-dominated beauty retail. For Investors and Strategic Acquirers: Accelerating NMPA approval timelines for Korean fermentation-derived actives is the leading indicator that regulatory arbitrage windows for imported functional claims are narrowing. Long-term viability favors targets with integrated substrate production and algorithmic personalization platforms rather than pure brand marketing plays. Watch for Seoul-based fermentation specialists seeking capital to scale bioreactor capacity beyond current Korean manufacturing hub concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captive Acetobacter xylinum bioreactor investment secures premium substrate supply against Korean supplier concentration risk. |
| Algorithmic Skin Assessment Platform | Direct-to-consumer personalization tools in Seoul and Shanghai drive subscription attach rates above conventional e-commerce repurchase frequency. |
| Biodegradable Substrate Development | Compostable fiber alternatives align with EU packaging waste directives and China's dual carbon manufacturing mandates. |
| Professional Channel Partnership | Post-procedure protocol co-development with Los Angeles medi-spa chains creates pull-through demand for at-home maintenance SKUs. |
| Regulatory Pre-Clearance Investment | MFDS toxicological dossier preparation accelerates Chinese NMPA access timelines against domestic functional cosmetics competitors. |
Research Approach
Document review covered MFDS functional cosmetics registration databases, EU ECHA substance disclosure filings, and Chinese NMPA imported cosmetics approval records, complemented by interviews with Seoul-based fermentation facility technical directors, Los Angeles medi-spa procurement managers, and Shanghai direct-to-consumer platform category leads. Secondary validation drew from South Korean customs export data, Japanese METI packaging waste reduction reports, and EU Green Deal implementation guidance documents. Bottom-up substrate production capacity estimates triangulated against top-down regional consumption modeling.
Segment-level projections across biocellulose, hydrogel, cotton, and synthetic fiber substrates integrated functional claim intensity, regulatory pathway complexity, and channel distribution economics throughout the forecast period. Anti-aging, hydrating, brightening, and nourishing benefit categories were modeled against MFDS and NMPA approval timeline differentials. CAGRs derived from fermentation yield improvement curves, salon channel penetration rates, and subscription platform attach rate trajectories in Seoul and urban China.
Revisions become necessary when EU REACH nanomaterial classification amendments expand peptide-delivery system documentation requirements, Chinese NMPA streamlines domestic functional cosmetics approval timelines, or biodegradable substrate manufacturing achieves cost parity with petroleum-derived alternatives. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Hand Care Market
Skincare
Skincare Cdmo and Cmo Market
Skincare
Skin Barrier Market
Skincare
Facial Massage Cream Market
Skincare
CBD Skincare Products Market
Skincare
Facial Mist Market
Skincare
Skin Bioactive Market
Skincare
Rice Water Skincare Market
Skincare
Skin Replacement Market
Skincare
Skin Care Supplements Market
Skincare
Moisturizing Cream Market
Skincare
Medicine Skin Care Market
Skincare
Allantoin Extract for Skincare Products Market
Skincare
Skin Care Body Products Market
Skincare
Marine Retinol Market
Skincare
Retinoids Market