
 Electronic Stability Control System Market | 2026-2036
Electronic Stability Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Stability Control System Market Analysis
Software-defined vehicle architectures is fragmenting traditional ESC hardware hierarchies into distributed compute nodes. Robert Bosch GmbH leverages its integrated sensor-to-actuator portfolio to maintain design-in dominance across European OEM programs. Continental AG anchors high-volume production through captive semiconductor sourcing and foundry partnerships in Germany. ZF Friedrichshafen AG competes on mechatronic integration density, bundling ESC modules with brake-by-wire systems for premium electric platforms.
An electronic stability control system constitutes a closed-loop active safety mechanism that modulates individual wheel brake pressure and engine torque to maintain directional control during understeer or oversteer events, typically integrating yaw rate sensors, lateral accelerometers, steering angle encoders, and hydraulic modulator valves operating at loop frequencies exceeding 100 Hz. Its primary commercial purpose is to prevent loss-of-control crashes in passenger and commercial vehicles, particularly on low-friction surfaces or during emergency maneuvers. Active systems command the fastest expansion trajectory as OEMs bundle ESC with automated emergency braking and lane-keeping assist, while sensor-based technology leads unit volume due to mature gyroscopic MEMS supply chains and declining per-axis costs. Factory-fitted installation dominates revenue capture because regulatory homologation requirements in major automotive markets prohibit deletion of certified ESC hardware from new vehicle type approvals.
NHTSA's Federal Motor Vehicle Safety Standard 126 mandates ESC on all light vehicles sold in the United States, while UN ECE R13-H extends equivalent technical requirements across European type-approval jurisdictions and Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces comparable rollover stability provisions. These frameworks eliminate aftermarket deletion options and force Tier-1 suppliers to maintain dual-homologation testing capacity. Stakeholders must monitor how brake-by-wire standardization and central vehicle compute consolidation alter ESC module form factors and supplier margin structures.
Market Dynamics
Software-defined vehicle architectures are dismantling legacy ESC hardware hierarchies into distributed compute nodes, forcing suppliers to rearchitect sensor-to-actuator signal paths and compress module form factors.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard 126:Mandates ESC installation on all light vehicles sold in the United States, eliminating deletion options and securing baseline demand for certified hardware.
- Electric vehicle platform proliferation:OEMs bundle ESC with brake-by-wire and automated emergency braking systems, expanding per-vehicle content value on dedicated EV architectures.
- UN ECE R13-H harmonization:Extends rollover stability requirements across European type-approval jurisdictions, creating dual-homologation testing demand that favors established Tier-1 suppliers.
Market Restraints
- Semiconductor supply concentration:Foundry capacity constraints in Taiwan and Germany limit gyroscopic MEMS sensor output, creating order backlog volatility for ESC module manufacturers.
- Brake fluid hydraulic modulator cost structure:Stainless steel valve bodies and precision solenoid coils face nickel and copper price swings that compress supplier margins on fixed-price OEM contracts.
- Central vehicle compute consolidation:Domain controller integration threatens standalone ESC module volumes as braking functions migrate into consolidated chassis control units.
Strategic Opportunities
- India's expanding passenger vehicle safety mandate:Pending adoption of UN ECE R13-H equivalent standards creates first-fit ESC demand in a market previously dominated by ABS-only configurations.
- Sensor fusion convergence:Integration of yaw rate, lateral acceleration, and steering angle data into unified perception stacks enables ESC algorithm licensing to autonomous driving software vendors.
- Aftermarket fleet retrofit channels:Commercial vehicle operators in Brazil and Mexico face insurance premium penalties for non-ESC equipped trucks, creating certified retrofit kit demand outside factory installation.
Industry Challenges
- Embedded software functional safety certification:ISO 26262 ASIL-D compliance for ESC control algorithms demands specialized automotive safety engineers, creating talent scarcity in Eastern European development centers.
- Legacy vehicle electrical architecture integration:Retrofitting modern ESC modules into 12V electrical systems with limited CAN bandwidth requires signal conditioning hardware that extends development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Stability Control System Market |
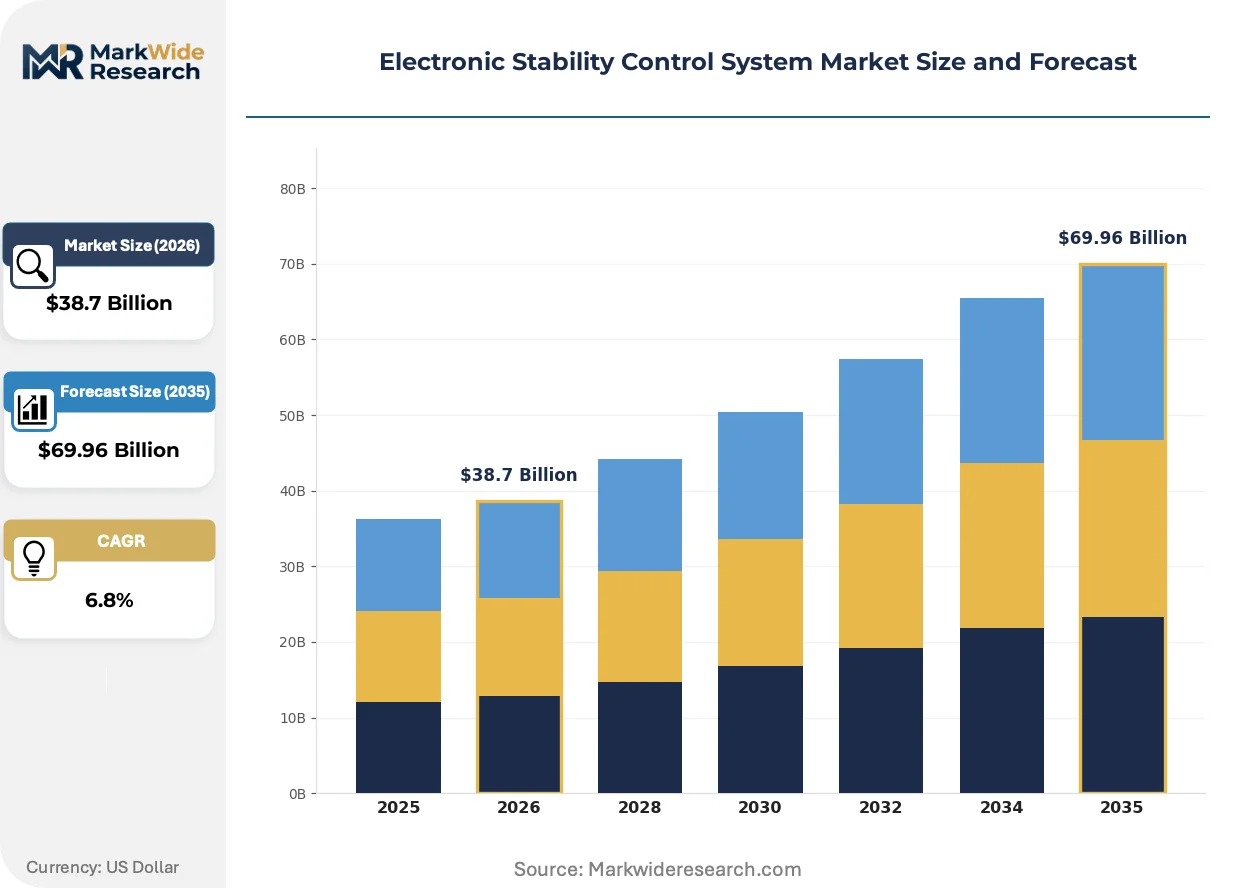
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Systems, Active Systems, Hybrid Systems, Advanced Control Systems End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Sensor-Based, Computer Vision, Radar-Based, Machine Learning Installation: Aftermarket, Factory-Fitted, Retrofitted, Custom Installed |
| Companies Covered | Denso Corporation, Hyundai Mobis Co., Ltd., Robert Bosch GmbH, Hitachi Automotive Systems Ltd., Knorr-Bremse AG, Continental AG, Autoliv Inc., Mando Corporation, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Stability Control System Market Emerging Trajectories
Brake-by-wire standardization and central compute consolidation are compressing ESC module boundaries, forcing suppliers to reposition around software IP and sensor integration density rather than standalone hydraulic hardware.
Electro-hydraulic brake actuation is migrating from conventional vacuum-boosted systems to fully integrated brake-by-wire modules. Premium electric vehicle OEMs in Germany and Japan are adopting these systems at scale for regenerative braking coordination. This migration from discrete hydraulic modulators toward integrated mechatronic units is collapsing the traditional Tier-1 supplier boundary between braking and chassis control functions.
UN ECE R13-H and its Japanese MLIT equivalent are tightening rollover stability test protocols for vehicle categories previously exempt from full ESC requirements. Commercial van and light truck manufacturers must now engineer higher-capacity yaw rate sensors and faster valve response times. European OEMs are responding by pre-certifying modular ESC hardware across multiple vehicle weight classes to streamline homologation.
Fleet procurement departments are unbundling ESC hardware from bundled active safety packages, negotiating direct module sourcing for standardized vehicle configurations. Rental and logistics operators in the United States are driving this specification fragmentation, demanding open-architecture interfaces for telematics integration. This pattern is most visible in high-volume light commercial vehicle segments where total cost of ownership calculations dominate supplier selection.
Electronic Stability Control System Market Segmentation
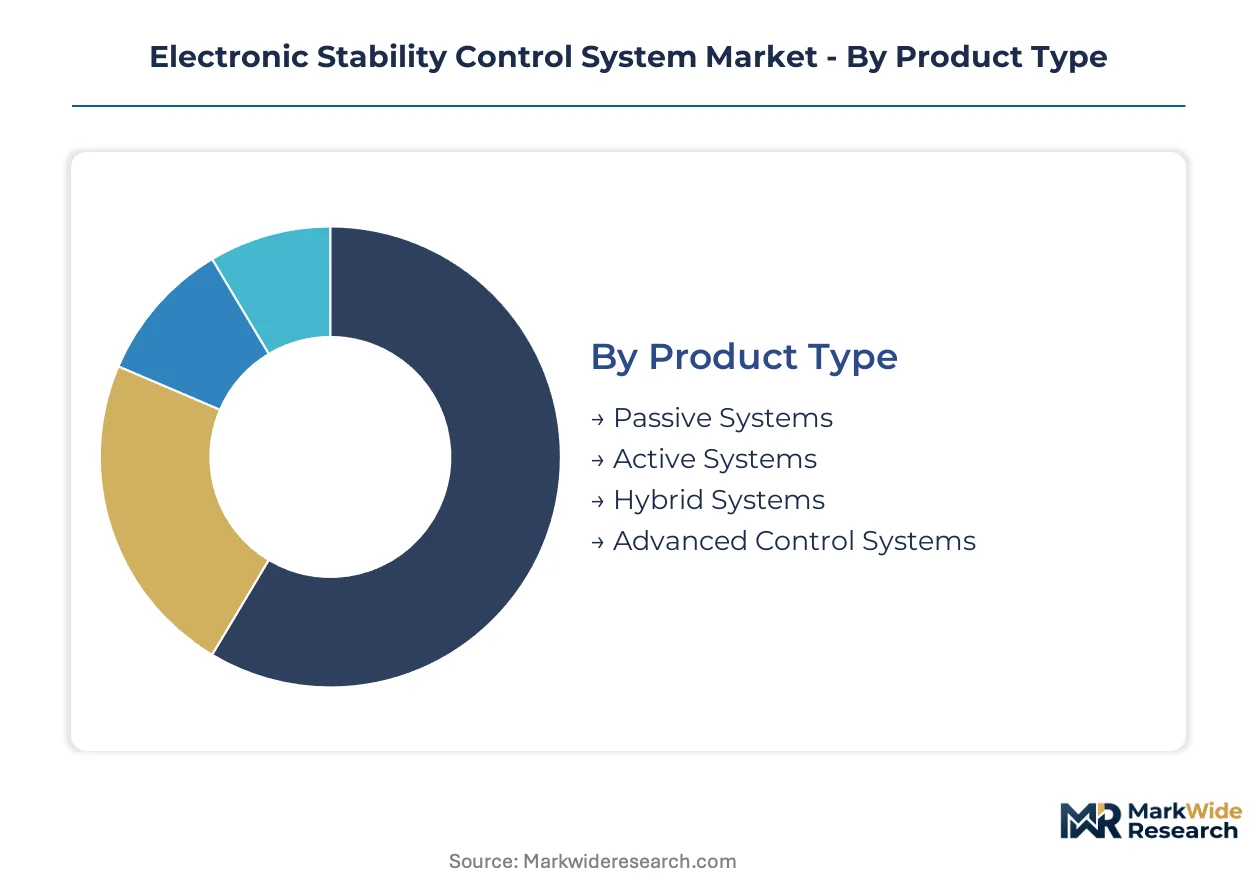
ESC module suppliers calibrate portfolio depth across four distinct segmentation axes. Product architecture determines hardware-software bundling ratios, while installation channel dictates margin structure and regulatory compliance burden.
Product Type:
Cost tier differentiation separates legacy hydraulic architectures from software-intensive integrated platforms.
- Active Systems:Closed-loop configurations modulate individual wheel brake pressure and engine torque through yaw rate sensors and lateral accelerometers operating above 100 Hz loop frequencies. OEMs in Germany and Japan bundle these with automated emergency braking on dedicated electric vehicle platforms, expanding per-vehicle content value.
- Hybrid Systems:Dual-mode architectures combine conventional hydraulic modulators with predictive brake-by-wire actuation for regenerative braking coordination. Demand concentrates in premium electric vehicle segments where mechatronic integration density commands supplier selection.
- Passive Systems:Open-loop stability aids without active brake intervention, retained in emerging market entry-level vehicles facing cost pressure.
- Advanced Control Systems:AI-augmented predictive stability algorithms processing multi-sensor fusion inputs for autonomous driving readiness.
Active Systems holds installed capacity. Hybrid Systems is rotating up the share rankings.
End User:
Application concentration varies sharply between regulatory-mandated factory installation and discretionary fleet procurement.
- OEMs:Original equipment manufacturers in the United States, Germany, and Japan drive specification authority through NHTSA FMVSS 126 and UN ECE R13-H homologation requirements. Factory-fitted ESC deletion is prohibited, securing baseline demand for certified hardware across light vehicle programs.
- Tier-1 Suppliers:Robert Bosch GmbH, Continental AG, and ZF Friedrichshafen AG maintain design-in dominance through integrated sensor-to-actuator portfolios and captive semiconductor sourcing.
- Aftermarket Providers:Certified retrofit kit demand emerges in Brazil and Mexico where commercial vehicle operators face insurance premium penalties for non-ESC equipped trucks.
- Vehicle Assemblers:Contract manufacturers in India and Southeast Asia integrate ESC modules into localized production for domestic market type-approval.
OEMs command specification authority. Aftermarket Providers are gaining traction in regulatory-lagging jurisdictions.
Technology:
Volume concentration tracks sensor cost curves and MEMS supply chain maturity.
- Sensor-Based:Gyroscopic MEMS yaw rate sensors and lateral accelerometers dominate unit volume through declining per-axis costs and established automotive-grade supply chains. Foundry capacity constraints in Taiwan and Germany create order backlog volatility for module manufacturers.
- Machine Learning:Predictive algorithms processing vehicle dynamics data for anticipatory stability intervention before yaw rate deviation occurs.
- Computer Vision:Camera-based road surface friction estimation augmenting traditional inertial measurement.
- Radar-Based:Doppler sensors detecting vehicle slip angles through ground speed differential measurement.
Sensor-Based technology anchors current production volumes. Machine Learning is climbing the fastest as software-defined vehicle architectures mature.
Installation:
Customer type segmentation reflects divergent regulatory treatment and margin structures.
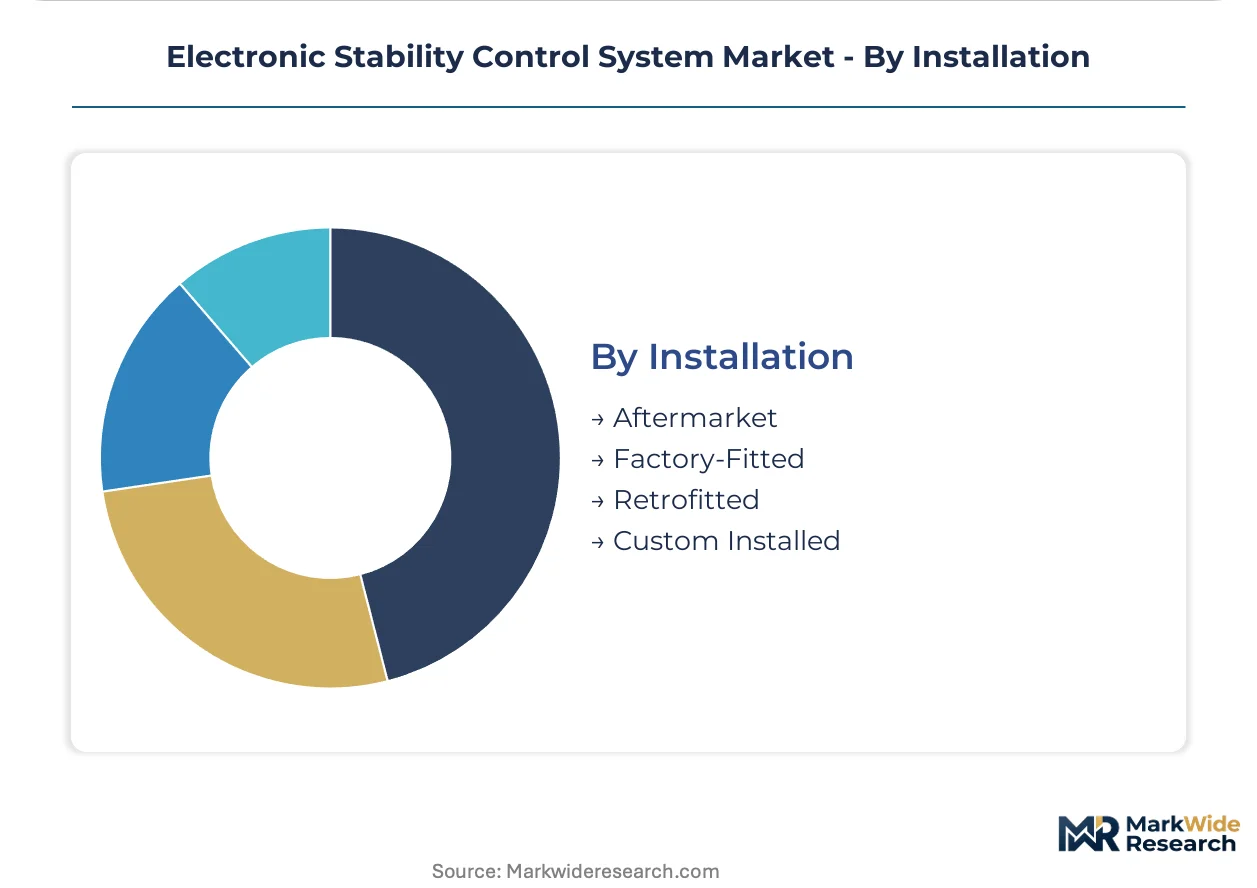
- Factory-Fitted:New vehicle type-approval mandates in the United States, Europe, and Japan prohibit deletion of certified ESC hardware, capturing the dominant revenue share. NHTSA FMVSS 126 and UN ECE R13-H frameworks eliminate aftermarket alternatives for light vehicle compliance.
- Retrofitted:Commercial van and light truck operators in European markets upgrade previously exempt vehicle categories under tightened MLIT and UN ECE rollover stability protocols.
- Aftermarket:Independent installation channels serve fleet operators in Brazil, Mexico, and India seeking insurance premium reductions or pending regulatory adoption.
- Custom Installed:Specialized vehicle modifiers integrate ESC modules into modified chassis for motorsport or extreme duty applications.
Factory-Fitted installation captures regulatory-secured demand. Retrofitted channels are expanding most quickly as commercial vehicle mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports ESC modules to United States assembly plants serving Detroit Three electrification programs. Japanese suppliers ship sensor-integrated hardware to European OEMs for premium EV platforms. South Korean component houses feed Hyundai-Kia global production networks.
United States
NHTSA Federal Motor Vehicle Safety Standard 126 mandates factory-fitted ESC on all light vehicles, eliminating deletion options for Detroit Three and transplant OEMs. Insurance Institute for Highway Safety ratings pressure commercial fleet operators toward higher-spec stability systems. Michigan's automotive corridor hosts brake-by-wire integration labs for next-generation electric truck platforms.
Germany
UN ECE R13-H homologation requirements drive specification authority for Volkswagen Group, BMW, and Mercedes-Benz programs. KBA type-approval enforcement eliminates aftermarket alternatives for export-bound vehicles. Stuttgart and Munich anchor Continental AG and Robert Bosch GmbH sensor-to-actuator development centers.
Japan
MLIT rollover stability provisions tighten test protocols for commercial vans and kei-car segments previously exempt from full ESC. Toyota and Honda bundle stability control with automated emergency braking on dedicated EV architectures. Nagoya and Tokyo metropolitan areas concentrate Hitachi Automotive Systems and Denso Corporation engineering facilities.
South Korea
Ministry of Land, Infrastructure and Transport adopts UN ECE R13-H equivalent standards for domestic type-approval, forcing Hyundai and Kia to standardize ESC across entry-level segments. Hyundai Mobis Co., Ltd. and Mando Corporation supply integrated chassis modules from Gyeonggi-do production complexes.
India
Pending adoption of UN ECE R13-H equivalent standards creates first-fit ESC demand in a market historically dominated by ABS-only configurations. Bureau of Indian Vehicles safety consultations pressure Maruti Suzuki and Tata Motors toward regulatory pre-compliance. Maharashtra and Tamil Nadu vehicle assembly corridors integrate ESC modules into localized production for domestic market homologation.
Electronic Stability Control System Market Vendor Landscape
Channel-controlling players compete with product-specialist players across sensor, hydraulic, and software integration layers. The vendor base clusters around three strategic archetypes: integrated chassis suppliers with captive semiconductor sourcing, brake-system specialists extending into mechatronic modules, and sensor-focused houses licensing algorithm IP. Consolidation pressures mount as domain controllers threaten standalone ESC module volumes. Strategic moves center on brake-by-wire partnerships and foundry capacity reservations for gyroscopic MEMS.
Within the integrated chassis tier, Robert Bosch GmbH and Continental AG exemplify full-stack sensor-to-actuator control. ZF Friedrichshafen AG occupies a position at the mechatronic integration end, bundling ESC functions with brake-by-wire systems. These three German entities anchor European OEM design-in authority through dual-homologation testing capacity and captive supply relationships.
| Leading Market Players |
|---|
| Denso Corporation |
| Hyundai Mobis Co., Ltd. |
| Robert Bosch GmbH |
| Hitachi Automotive Systems Ltd. |
| Knorr-Bremse AG |
| Continental AG |
| Autoliv Inc. |
| Mando Corporation |
| ZF Friedrichshafen AG |
| Others |
Supply Flow & Price Mechanics
Foundry undercapacity in Taiwan and Germany is compressing supplier margins and hardening pricing postures across ESC module tiers. Tier 1 suppliers are passing through MEMS sensor cost inflation while absorbing hydraulic modulator commodity volatility on fixed-price OEM contracts.
Pricing Analysis
Prior-generation hydraulic ESC modules trade at substantial discounts to integrated brake-by-wire platforms, while next-generation AI-augmented predictive systems command software licensing premiums. Three-tier pricing structure across premium, standard, and economy levels separates AI-augmented predictive platforms from conventional sensor-based active systems from entry-level passive stability aids. Pricing pressure stems from nickel and copper price swings affecting stainless steel valve bodies and precision solenoid coils. Fleet procurement departments exhibit highest price sensitivity, negotiating direct module sourcing for standardized vehicle configurations.
Supply Chain Analysis
Extended payment terms from German and Japanese OEMs are forcing Tier 1 suppliers to utilize supply-chain finance facilities, compressing working capital cycles. Manufacturing concentrates in Germany, Japan, and South Korea, with gyroscopic MEMS sensors drawing from Taiwanese and German foundries. Raw material dependencies center on nickel for valve bodies, copper for solenoid coils, and rare earth elements for sensor magnetics. Single-source vulnerability in Taiwanese MEMS foundry capacity creates order backlog volatility. Distribution runs through captive OEM supply agreements and authorized Tier 1 distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ESC market is recovering from semiconductor supply cyclicality as automotive production normalizes and EV platform proliferation sustains content value expansion.
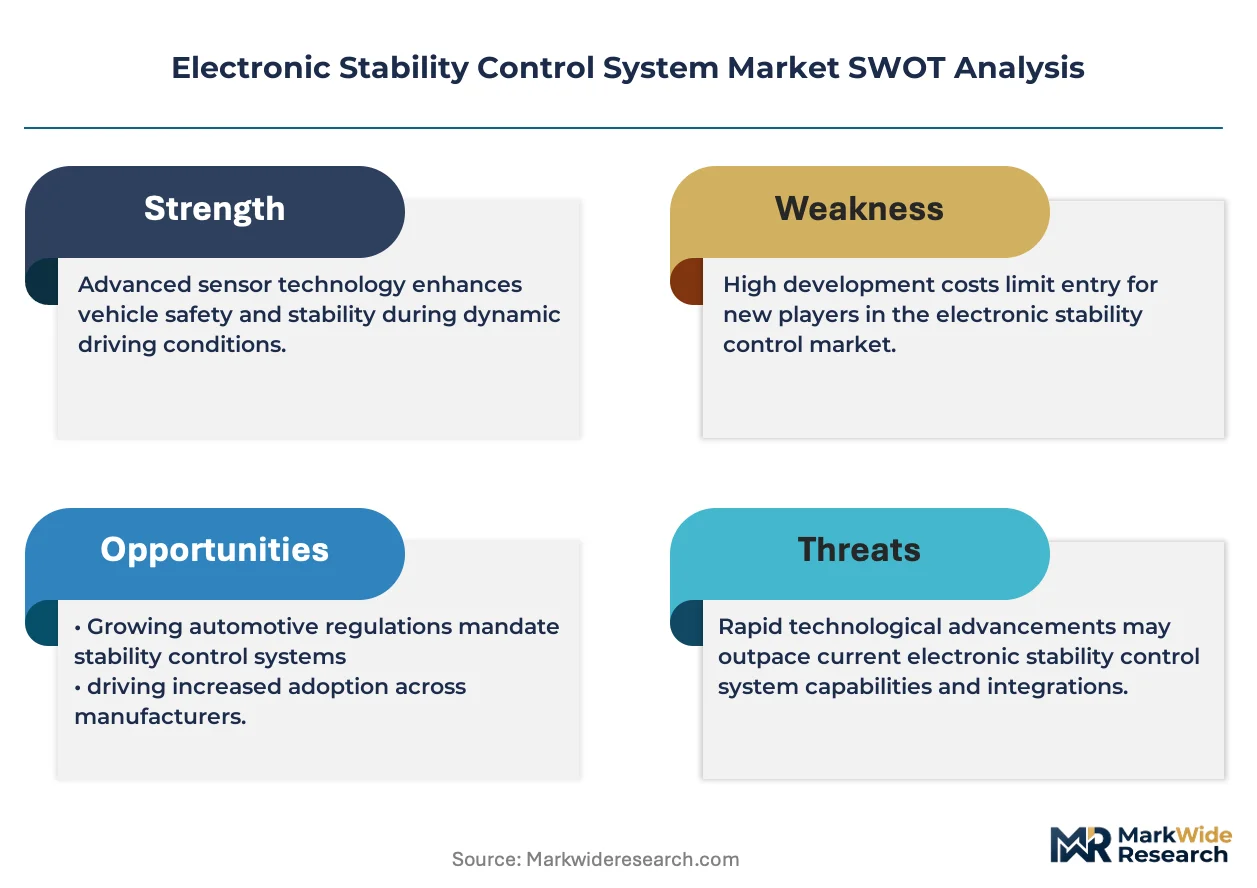
For Market Incumbents: Pre-empt domain controller consolidation by licensing ESC algorithm IP to autonomous driving software vendors before braking functions migrate into consolidated chassis control units. Secure captive semiconductor sourcing through foundry partnerships in Germany to defend against MEMS sensor supply volatility. Reinforce dual-homologation testing capacity across NHTSA and UN ECE jurisdictions as regulatory harmonization tightens. For New Entrants and Emerging Players: India's pending UN ECE R13-H equivalent adoption offers first-fit ESC demand in a market historically dominated by ABS-only configurations. Commercial vehicle retrofit channels in Brazil and Mexico present white-space opportunity where insurance premium penalties drive certified kit demand. Target aftermarket fleet procurement with open-architecture telematics integration as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across sensor-based ESC hardware as software-defined vehicle architectures shift value toward algorithm IP. Long-term viability favors suppliers with integrated sensor-to-actuator portfolios and brake-by-wire integration capabilities. Watch for brake-by-wire standardization milestones as inflection indicators for module form factor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Brake-by-Wire Integration | Bundles ESC with electro-hydraulic actuation for premium EV platforms from German and Japanese OEMs. |
| Foundry Partnership Reservation | Secures captive MEMS sensor capacity in Germany and Taiwan against order backlog volatility. |
| Algorithm IP Licensing | Positions ESC software in autonomous driving perception stacks for sensor fusion convergence. |
| Dual-Homologation Investment | Maintains NHTSA FMVSS 126 and UN ECE R13-H testing capacity for export-bound vehicle programs. |
| Aftermarket Retrofit Certification | Captures commercial fleet demand in Brazil and Mexico facing insurance premium penalties. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and ESC module engineering directors; and secondary validation through vehicle production databases, IHS Markit registration data, NHTSA FMVSS 126 filings, UN ECE R13-H type-approval records, and SEC 10-K disclosures from listed automotive suppliers. Bottom-up unit volume estimates triangulated against top-down market value assessments.
Forecast inputs considered vehicle production volumes by propulsion architecture, content per vehicle trajectories across active, hybrid, and passive ESC tiers, and regional regulatory adoption curves. Segmentation dimensions modeled include product architecture, installation channel, technology generation, and OEM tier classification. CAGRs were derived from regression analysis of historical content value expansion and projected EV platform penetration.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese brake-system specialists or software-defined vehicle platform vendors would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
India Airbag Systems Market
Automotive Safety and Security Systems
Automotive Airbags Market
Automotive Safety and Security Systems
Global Airbag Systems Market
Automotive Safety and Security Systems
Global Emergency Locking Retractor Seatbelt Market
Automotive Safety and Security Systems
Biometric Vehicle Access System Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Automotive Battery Pack Fire Barrier Pad Market
Automotive Safety and Security Systems
Automotive Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Asia Pacific Lane Departure Warning Systems Market
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Park Assist System Market
Automotive Safety and Security Systems
Automotive Anti Lock Braking System and Electronic Stability Control Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market
Automotive Safety and Security Systems
Highway Crash Cushion Market
Automotive Safety and Security Systems
Trailer Assist System Market
Automotive Safety and Security Systems
Driving Helmet Market