
 Voice Analytics Market | 2026-2036
Voice Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Voice Analytics Market Analysis
Multi-source procurement of AI speech models is pivoting as enterprises balance cloud API flexibility against data sovereignty requirements. NICE Ltd anchors its position through proprietary real-time transcription engines deployed across regulated contact centers. Verint Systems competes via integrated workforce optimization suites that embed voice analytics into broader operational dashboards. Amazon Web Services extends reach through AWS Transcribe and Amazon Connect, leveraging hyperscale infrastructure to undercut specialized vendor pricing.
Voice analytics encompasses the computational analysis of acoustic signals, linguistic content, and paralinguistic features to extract actionable intelligence from spoken interactions, operating through pipelines that integrate mel-frequency cepstral coefficient extraction with transformer-based natural language models. The technology serves commercial and security purposes ranging from real-time agent coaching to speaker identification and emotional state inference. Natural language processing and machine learning together constitute the fastest-expanding technology layer, as foundation models reduce training data requirements for domain-specific deployments. Cloud-based delivery dominates new implementations, though hybrid architectures retain traction among financial institutions and healthcare providers subject to strict data residency mandates.
The EU AI Act classifies certain voice biometrics applications as high-risk, compelling providers to demonstrate conformity with transparency and accuracy benchmarks before market access. In the United States, HIPAA governs voice data handling in healthcare contexts, while the FTC scrutinizes claims regarding emotion recognition efficacy for consumer protection compliance. Stakeholders must monitor evolving algorithmic accountability standards across jurisdictions, as divergent regulatory timelines threaten to fragment product development roadmaps and certification costs.
Market Dynamics
Transformer-based foundation models are compressing training timelines for domain-specific voice analytics deployments, enabling financial institutions and healthcare providers to operationalize speech intelligence without proprietary acoustic engineering teams.
Growth Catalysts
- EU AI Act high-risk classification:Mandates for algorithmic transparency and accuracy benchmarking are accelerating procurement of auditable, explainable speech analytics systems across European contact centers and biometric authentication providers.
- Healthcare digitization:HIPAA-compliant voice data handling requirements in the United States are driving enterprise investment in on-premise and hybrid transcription infrastructure for clinical documentation and patient interaction analysis.
- Contact center modernization:Real-time agent coaching applications leveraging paralinguistic feature extraction are expanding deployment of emotion inference and conversational intelligence platforms in the United States.
Market Restraints
- GPU compute cost volatility:Foundation model inference and fine-tuning for speech-to-text pipelines remain tethered to NVIDIA datacenter accelerator pricing and cloud provider reservation economics.
- Data residency fragmentation:Divergent national cloud sovereignty mandates—particularly Germany's Gaia-X alignment requirements and China's data localization rules—are forcing redundant infrastructure deployment.
- Emotion recognition efficacy limitations:FTC scrutiny of claims regarding affective computing accuracy is constraining marketing and deployment of psychological state inference tools in consumer-facing applications.
Strategic Opportunities
- India BIS standards convergence:Emerging domestic certification frameworks for AI-enabled voice systems are creating first-mover positioning for localized speech model providers serving regional language markets.
- Edge deployment architectures:On-device transformer compression and neural audio codec integration are enabling offline voice analytics for field workforce applications in mining, logistics, and remote healthcare.
- CSRD sustainability reporting:European corporate sustainability disclosure requirements are generating demand for voice analytics to audit supplier compliance and ESG-related communications at scale.
Industry Challenges
- Computational linguistics talent scarcity:Shortage of engineers with combined expertise in acoustic signal processing and transformer architecture optimization is elongating deployment timelines for custom voice pipelines.
- Legacy telephony integration friction:SIP trunk compatibility and real-time streaming protocol adaptation with decades-old private branch exchange infrastructure is consuming disproportionate implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice Analytics Market |
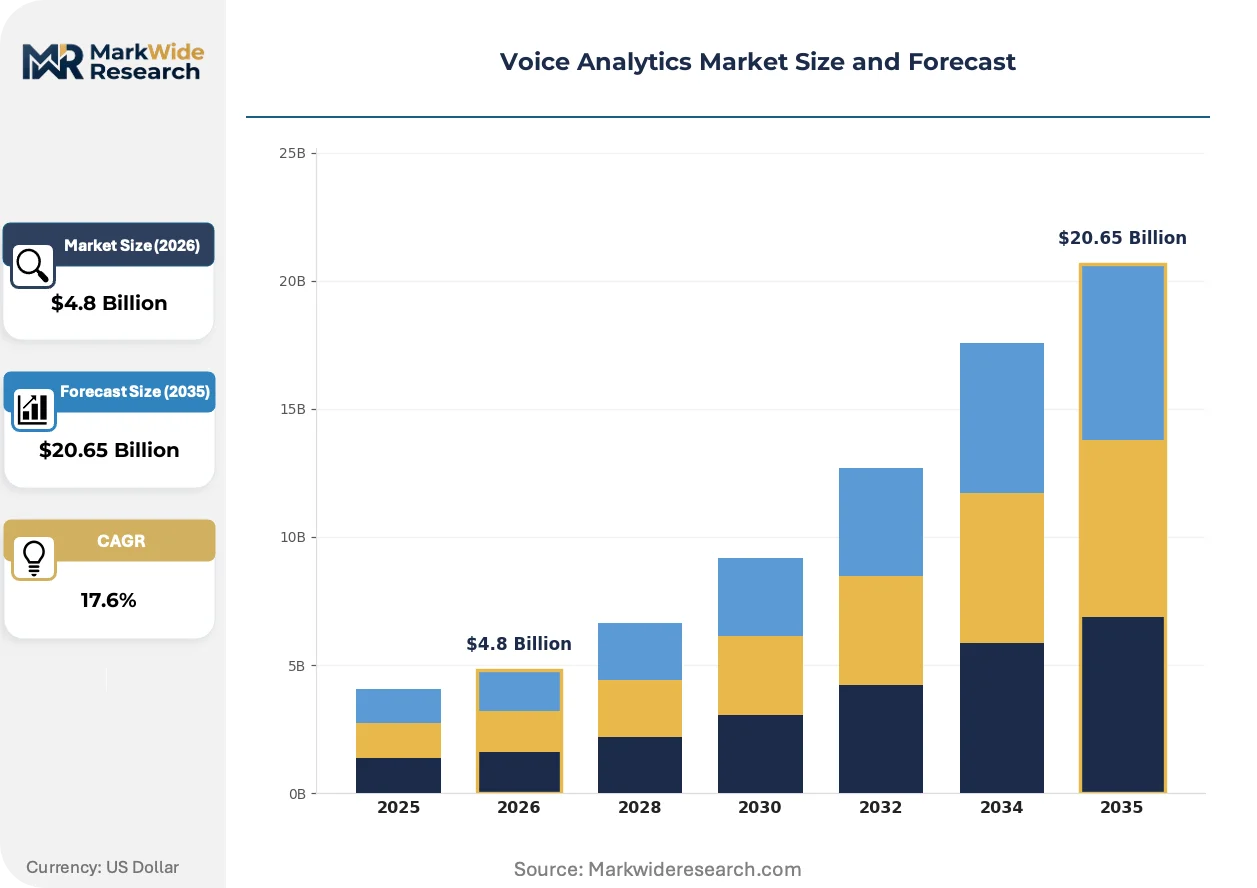
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.65 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Speech Recognition, Natural Language Processing, Machine Learning, Voice Biometrics End User: Call Centers, Healthcare Providers, Financial Institutions, Retail Application: Customer Service Optimization, Fraud Detection, Sentiment Analysis, Compliance Monitoring Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Solutions |
| Companies Covered | NICE Ltd, Verint Systems, CallMiner, Google Cloud, Amazon Web Services, IBM, Genesys, Avaya, Uniphore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice Analytics Market Emerging Trajectories
Foundation model architectures are redefining competitive economics in voice analytics by collapsing the historical trade-off between transcription accuracy and deployment cost, with implications rippling across cloud provider strategies and specialized vendor positioning.
Whisper-class open-weight speech recognition models are automating real-time transcription and translation workflows previously requiring proprietary engine licensing. Financial services contact centers in Singapore and London are deploying these systems for compliance archiving and cross-border client servicing. The technology is automating downstream agent quality assurance and dispute resolution documentation, compressing operational expenditure structures.
The EU AI Act's high-risk system designation for remote biometric identification is compelling providers to implement conformity assessment procedures and post-market monitoring frameworks before commercial deployment. Voice biometrics vendors are restructuring product roadmaps to segregate speaker verification from emotion recognition functionalities. Healthcare and banking applications in France, Germany, and the Netherlands face the most immediate compliance timeline pressure.
Subscription-based API consumption is displacing perpetual license models as the dominant commercial structure for enterprise speech analytics procurement. Mid-market buyers in the United States are consolidating vendor relationships around hyperscaler platforms offering bundled transcription, storage, and analytics compute. This pattern is most pronounced among Series B and C technology companies modernizing customer success operations.
Voice Analytics Market Segmentation
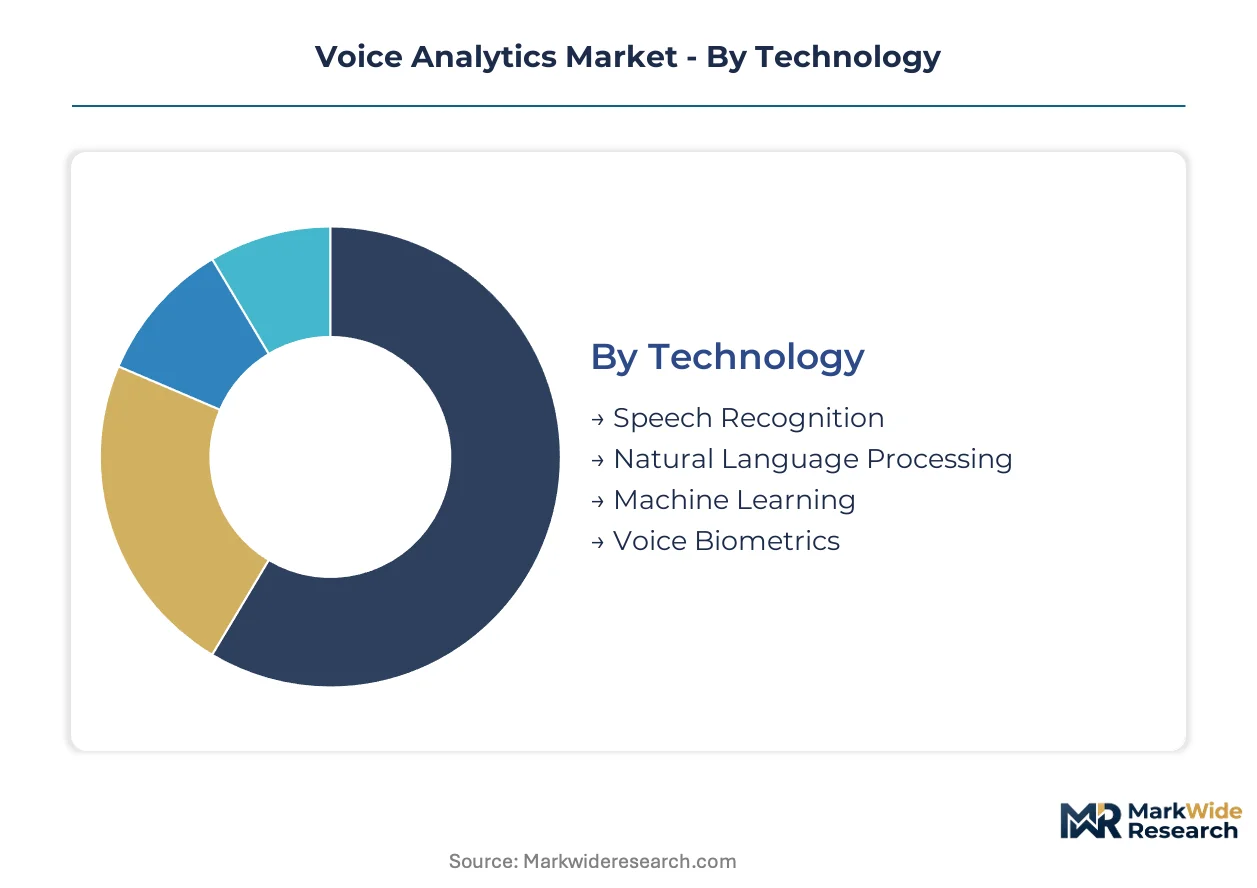
Voice analytics procurement varies sharply by deployment complexity and regulatory exposure. Buyers segment investments across technology layers, operational use cases, and infrastructure models to balance accuracy requirements against data sovereignty constraints.
Technology:
Capital intensity concentrates in acoustic modeling and biometric engine development, where GPU clusters and proprietary training datasets create steep barriers to entry.
- Speech Recognition:Converts acoustic signals into machine-readable text using mel-frequency cepstral coefficients and deep neural networks. Demand clusters in United States contact centers modernizing legacy interactive voice response systems under FTC consumer protection oversight. Real-time latency requirements below 300 milliseconds drive premium pricing for edge-optimized deployments.
- Natural Language Processing:Extracts intent, entities, and semantic relationships from transcribed utterances through transformer architectures. Financial institutions in Singapore and London deploy these systems for compliance archiving and cross-border client servicing, compressing operational expenditure structures through automated downstream quality assurance.
- Machine Learning:Enables adaptive model refinement from interaction feedback loops without explicit reprogramming.
- Voice Biometrics:Speaker verification engines face EU AI Act high-risk classification, compelling conformity assessment investments.
Most installed capacity flows through Speech Recognition. Expansion is steepest in Natural Language Processing.
End User:
Operational maturity determines procurement sophistication, with regulated industries leading adoption of hybrid architectures.
- Call Centers:Real-time agent coaching and automated quality management drive deployment of paralinguistic feature extraction. United States enterprises prioritize emotion inference platforms integrated with workforce optimization suites, though FTC scrutiny of psychological state claims constrains marketing.
- Healthcare Providers:HIPAA-compliant transcription infrastructure for clinical documentation requires on-premise or hybrid deployments. Patient interaction analysis applications face strict data residency mandates, elongating sales cycles but securing long-term contracts.
- Financial Institutions:Voice biometrics authentication and fraud prevention absorb the largest security budgets in this segment.
- Retail:Post-call sentiment tracking and campaign effectiveness measurement dominate use cases with lighter regulatory burden.
Healthcare Providers command the highest per-seat pricing. Call Centers account for the steepest volume expansion trajectory.
Application:
Functional ROI visibility shapes buying committee composition and procurement timeline urgency.
- Customer Service Optimization:Real-time guidance systems and automated scoring reduce average handle time and escalation rates. United States mid-market technology companies consolidate vendor relationships around hyperscaler platforms offering bundled transcription, storage, and analytics compute.
- Fraud Detection:Voice biometrics liveness detection and synthetic speech identification protect authentication channels. Financial institutions in France, Germany, and the Netherlands face immediate EU AI Act compliance timeline pressure, restructuring product roadmaps to segregate verification from emotion recognition.
- Sentiment Analysis:Aggregate emotion trending informs product development and marketing strategy.
- Compliance Monitoring:Archival searchability and dispute resolution documentation satisfy regulatory examination requirements.
Fraud Detection captures the largest security-specific budgets. Customer Service Optimization is gaining share fastest through API-based consumption models.
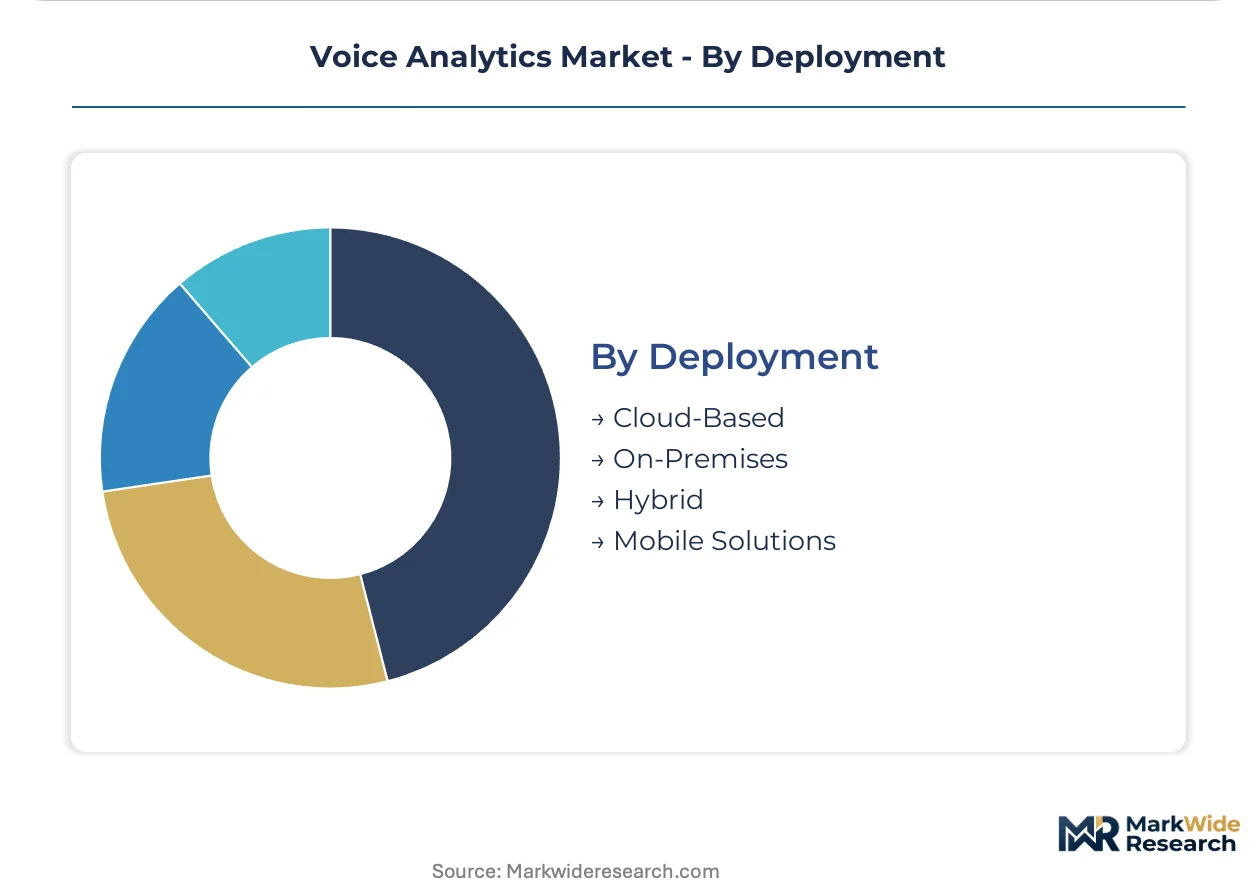
Deployment:
Infrastructure location decisions trade elasticity against jurisdictional control, with regulated buyers accepting cost premiums for data sovereignty.
- Cloud-Based:Hyperscaler API consumption dominates new implementations through subscription economics and rapid scaling. Mid-market buyers prioritize bundled offerings from AWS Transcribe and Amazon Connect, displacing perpetual license models.
- On-Premises:Air-gapped transcription engines serve financial institutions and healthcare providers subject to strict data residency mandates. Germany's Gaia-X alignment requirements and China's data localization rules force redundant infrastructure deployment.
- Hybrid:Sensitive processing on-premise with burst compute to cloud balances control and cost.
- Mobile Solutions:On-device transformer compression enables offline voice analytics for field workforce applications in mining, logistics, and remote healthcare.
Cloud-Based hosts the majority of new seat additions. Mobile Solutions are climbing the fastest as edge AI silicon matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors voice analytics demand through hyperscaler headquarters and enterprise software clusters. Financial institutions in New York and healthcare systems in Boston drive specialized procurement for regulated deployments. Contact center modernization across the United States absorbs the largest share of real-time transcription infrastructure investment.
United States
HIPAA-compliant transcription for clinical documentation and FTC-scrutinized emotion recognition platforms dominate healthcare and consumer-facing procurement. The FDA maintains oversight of software-as-medical-device classifications for diagnostic voice applications. Boston's healthcare AI corridor concentrates hybrid deployment expertise for hospital network integrations.
Germany
Gaia-X alignment requirements and EU AI Act high-risk system mandates force redundant infrastructure for financial voice biometrics. The BSI publishes technical guidelines for secure speech processing in critical infrastructure. Frankfurt's banking cluster drives demand for auditable, on-premise speaker verification systems with conformity assessment documentation.
Singapore
Cross-border client servicing and MAS regulatory technology guidelines accelerate multilingual transcription deployment. The Monetary Authority of Singapore mandates audit trails for voice communications in wealth management. Raffles Place financial district hosts regional headquarters for vendors serving ASEAN compliance archiving requirements.
United Kingdom
FCA conduct recording rules and post-Brexit data adequacy negotiations shape cloud procurement decisions for trading floor analytics. The Information Commissioner's Office scrutinizes emotion recognition claims under UK GDPR enforcement. London's insurance market drives specialized demand for claims call sentiment analysis and fraud pattern detection.
India
BIS certification frameworks for AI-enabled voice systems and RBI digital banking guidelines stimulate domestic speech model development. The Telecom Regulatory Authority of India mandates quality benchmarks for cloud communication services. Bangalore's enterprise software ecosystem concentrates regional language model training for Indic speech recognition deployment.
Voice Analytics Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-optimized and vertical-specific specializations. The vendor landscape stratifies between hyperscaler API platforms, integrated workforce optimization suites, and standalone biometric engine specialists. Three archetypes dominate: cloud-native infrastructure providers, legacy contact center modernizers, and security-focused authentication vendors. Competitive moves concentrate on strategic partnerships for legacy telephony integration and portfolio diversification into adjacent conversational AI segments.
Among Israel-based security specialists, NICE Ltd exemplifies the integrated workforce optimization archetype through its proprietary real-time transcription engines. Verint Systems occupies a comparable position in operational intelligence platforms embedding voice analytics into broader dashboards. Amazon Web Services represents the hyperscale infrastructure vector, leveraging AWS Transcribe and Amazon Connect to undercut specialized vendor pricing through bundled consumption economics. These three anchors illustrate the tension between vertical integration depth and horizontal platform breadth defining competitive positioning.
| Leading Market Players |
|---|
| NICE Ltd |
| Verint Systems |
| CallMiner |
| Google Cloud |
| Amazon Web Services |
| IBM |
| Genesys |
| Avaya |
| Uniphore |
| Others |
Supply Flow & Price Mechanics
GPU datacenter accelerator pricing from NVIDIA and cloud reservation economics cascade through voice analytics tiers, compressing margins for real-time transcription vendors while hyperscalers absorb cost volatility through bundled consumption models. Subscription API economics now dominate enterprise procurement, displacing perpetual licenses as buyers prioritize elasticity over capital deployment.
Pricing Analysis
Input-cost pass-through from GPU compute and proprietary training data licensing compresses margins for specialized engine vendors. Pricing stratifies across real-time latency tiers, with sub-300-millisecond edge deployments commanding premiums over batch transcription services. Cost pressure intensifies in the mid-market as AWS Transcribe and Google Cloud undercut standalone providers through bundled storage and analytics compute. Healthcare providers exhibit lowest price sensitivity due to HIPAA compliance premiums, while retail call centers drive hardest bargain on per-seat rates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for AWS Transcribe and Google Cloud Speech-to-Text, while value-added resellers serve regulated financial and healthcare deployments requiring on-premise integration. Supply concentrates in the United States for transformer model development, Taiwan for edge AI silicon fabrication, and Ireland for EU data residency infrastructure. The pipeline draws from NVIDIA datacenter GPUs, proprietary speech corpora, and SIP trunking hardware. Single-source vulnerability in GPU supply creates delivery risk for real-time inference deployments. Distribution runs through hyperscaler marketplaces, systems integrators, and specialized contact center modernization consultancies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Voice analytics procurement arbitrages regulatory compliance costs between EU AI Act jurisdictions and lighter-regulated markets, with German conformity assessment investments running threefold above Singapore deployment economics.
For Market Incumbents: To counter open-weight Whisper-class model commoditization, NICE Ltd and Verint Systems should deepen proprietary real-time engine differentiation through vertical integration into acoustic signal processing IP. Certification investments for EU AI Act high-risk system designation create switching costs that protect enterprise contract renewals. Capacity expansion in India addresses BIS emerging framework positioning before domestic competitors consolidate regional language markets. For New Entrants and Emerging Players: Mid-market Series B and C technology companies in the United States represent the most penetrable buyer archetype, as these firms consolidate vendor relationships around hyperscaler platforms but retain unmet needs for vertical-specific emotion inference. Edge deployment architectures for mining and logistics field workforces offer white-space expansion with lighter competitive density. Go-to-market execution should emphasize API-first consumption with rapid time-to-value demonstration against incumbent implementation timelines. For Investors and Strategic Acquirers: Roll-up economics work for workforce optimization platform consolidation because contact center modernization budgets are fragmenting across point solutions for transcription, quality management, and agent coaching. Long-term viability centers on vendors controlling proprietary acoustic engines rather than API-reselling hyperscaler infrastructure. Acquisition targets should demonstrate installed base density in regulated industries with multi-year contract visibility. The signal to watch is EU AI Act conformity assessment completion rates as a proxy for vendor survival in European banking and healthcare verticals.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding voice analytics into workforce optimization suites deepens NICE Ltd and Verint Systems enterprise stickiness. |
| Geographic Expansion | India BIS certification investments position early movers for Indic language model dominance in digital banking. |
| Acquisition of Specialist Firm | Biometric engine specialists with EU AI Act conformity documentation command scarcity premiums in Frankfurt banking. |
| Product Launch | On-device transformer compression for offline voice analytics unlocks mining and remote healthcare field applications. |
| Strategic Partnership | Legacy telephony integration partnerships reduce SIP trunk friction that elongates contact center deployment timelines. |
Methodological Framework
Multiple input streams — primary interviews with contact center operations directors, healthcare CIOs, and financial services compliance officers; secondary validation through SEC hyperscaler filings, EU AI Act implementation guidance, and FDA software-as-medical-device classifications; plus customs data on GPU import flows — were reconciled through bottom-up and top-down triangulation. Stakeholder perspectives from NICE Ltd and Verint Systems product strategists, Amazon Web Services partner ecosystem leads, and German BSI technical guideline authors informed deployment architecture assumptions.
Historical adoption curves for speech recognition in United States contact centers were cross-referenced against panel input from Singapore MAS-regulated wealth managers and India RBI digital banking leads. The analytical framework models technology layer, end-user vertical, application function, and deployment topology across the analysis window. CAGRs were derived from segment-level buildups incorporating GPU cost trajectory assumptions and regulatory compliance timeline differentials. Forecast inputs include EU AI Act high-risk system designation rollout pace and edge AI silicon maturity curves.
Underlying measurement precision varies by segment; cloud-based deployment volumes carry tighter precision than on-premise hybrid configurations where data residency mandates fragment comparability. Forecasts reflect documented assumptions regarding transformer model commoditization timelines and hyperscaler pricing discipline. Model risk concentrates in emotion recognition efficacy limitations under FTC scrutiny and GPU supply concentration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Big Data Market
Analytics
Global Development Analytics Tools Market
Analytics
Embedded Analytics Software Market
Analytics
Business Value Dashboard Market
Analytics
Data Discovery Market
Analytics
Global Data Fusion Market
Analytics
Marketing Analytics Market
Analytics
IT Operation Analytics (ITOA) Software Market
Analytics
AI Performance Marketing Market
Analytics
FMCG Spending on Analytics Market
Analytics
Practice Analytics Market
Analytics
Asia-Pacific Edge Analytics Market
Analytics
Iraq ICT Market
Analytics
Investigative Analytics Market
Analytics
Asia-Pacific Contact Center Analytics Market
Analytics
Customer Analytics in E-Commerce Market