

Marketing Mix Optimization Market Size, Share, and Industry Trends Forecast 2026-2036
Marketing Mix Optimization Market Insights
The capability gap between cloud-native platforms and legacy measurement providers is unwinding competitive stability in this space. Adobe leverages its Creative Cloud-to-Analytics pipeline to anchor enterprise clients seeking unified creative performance data. Kantar competes through specialized brand equity modeling that extends beyond digital touchpoints into broadcast and out-of-home channels. NielsenIQ controls substantial CPG client relationships but navigates pressure as advertisers diversify measurement vendors.
Marketing mix optimization encompasses statistical modeling techniques that quantify sales impact across advertising channels, pricing levers, and promotional activities using multivariate regression and Bayesian hierarchical methods. The discipline serves commercial purpose by enabling reallocation of marketing spend toward highest-ROI channels while simulating scenario outcomes before budget commitment. Software as a Service deployment dominates new bookings because subscription economics reduce upfront implementation barriers for mid-market brands. Attribution modeling represents the fastest-expanding solution type as cookie deprecation accelerates demand for multi-touch probabilistic approaches. Channel optimization retains mature margin pools in telecommunications and financial services where legacy contract structures sustain longer sales cycles.
The Federal Trade Commission and state attorneys general in California and Virginia enforce evolving consumer privacy frameworks that constrain granular tracking and reshape data availability for model inputs. The European Data Protection Board interprets GDPR provisions that limit cross-border data flows, compelling multinationals to localize analytics infrastructure. ISO standards for data quality management provide baseline governance that procurement teams increasingly require in vendor selection. Stakeholders must decide whether to build in-house Bayesian inference capabilities or accept vendor black-box methodologies as regulatory scrutiny intensifies.
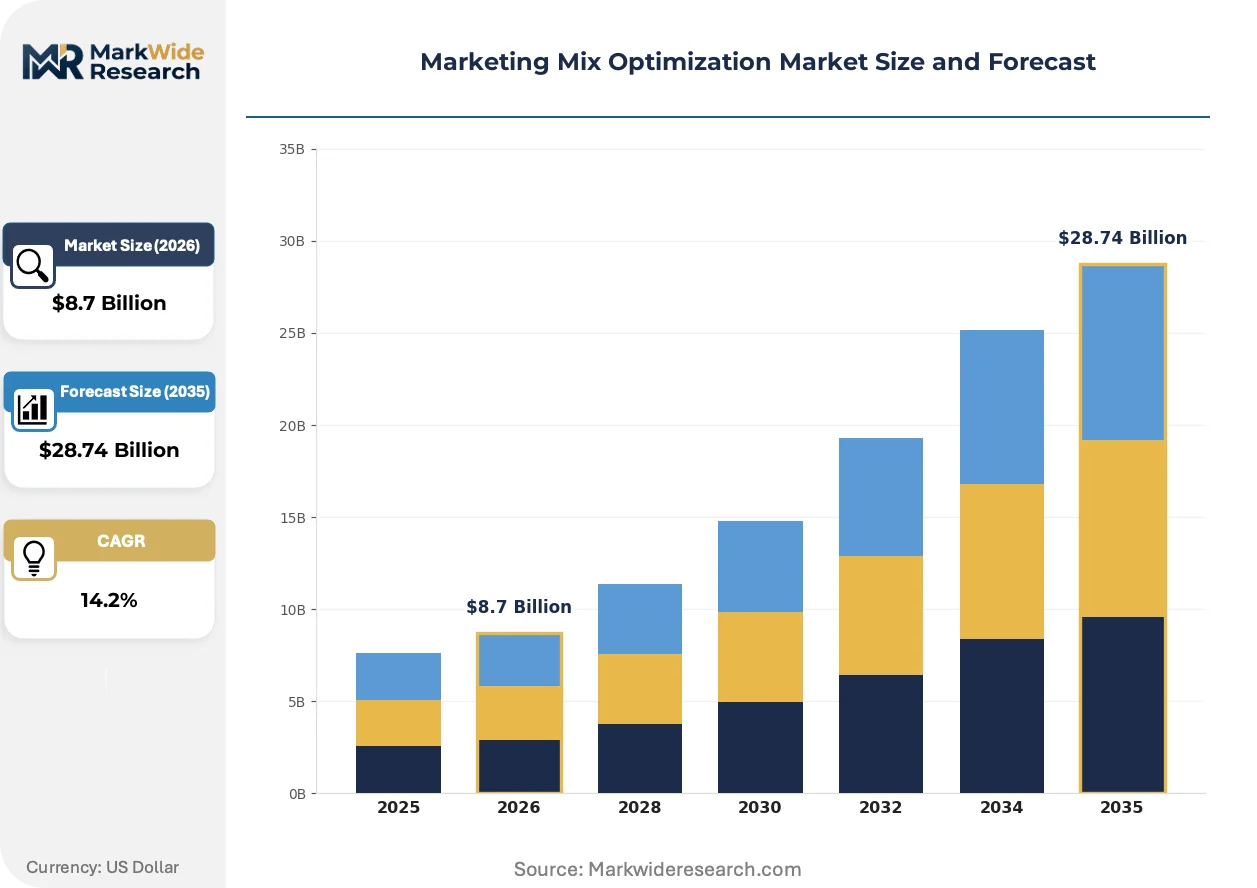
Market Dynamics
Privacy regulations across the United States, European Union, and United Kingdom are forcing CPG advertisers to abandon deterministic attribution and reinvest in first-party data infrastructure, compressing model input availability while elevating probabilistic methods.
Growth Catalysts
- Retail media networks:Closed-loop transaction data from Walmart Connect and Amazon Advertising enables granular sales attribution that bypasses cookie-dependent tracking. CPG brands now access purchase-level signals previously unavailable to external analytics vendors.
- GDPR enforcement:The European Data Protection Board's cross-border data flow restrictions compel multinationals to localize analytics infrastructure, creating demand for region-specific modeling platforms with compliant data residency.
- Bayesian hierarchical methods:These statistical techniques handle sparse data more effectively than frequentist approaches, allowing smaller brands with limited transaction history to deploy optimization at mid-market scale.
Market Restraints
- First-party data infrastructure costs:Building compliant data lakes and identity resolution systems requires substantial upfront investment that excludes sub-$50M revenue brands from advanced modeling deployment.
- Attribution window compression:Apple's App Tracking Transparency and similar mobile privacy controls reduce observable conversion paths, degrading model accuracy for direct-to-consumer channels.
- Probabilistic method skepticism:Finance executives at Fortune 500 CPG firms frequently reject black-box Bayesian outputs in favor of simpler but less accurate last-touch metrics for budget justification.
Strategic Opportunities
- Connected TV measurement:Streaming platforms lack standardized impression-to-sale linkage, creating white space for vendors that integrate smart TV data with retail transaction logs.
- ISO 8000 data quality certification:Procurement teams at telecommunications and financial services firms increasingly mandate certified data governance, favoring vendors with documented quality management systems.
- Audio and podcast channels:These formats remain undermodeled relative to digital display and search, offering first-mover advantage to platforms that solve signal-to-sale attribution for host-read advertising.
Industry Challenges
- Bayesian inference talent scarcity:The specialized statistical programming skills required for hierarchical model development command premium compensation, constraining vendor scaling and in-house team building.
- Legacy system integration friction:Enterprise clients demand API connections to decades-old ERP and trade promotion management systems, extending implementation timelines and elevating professional services dependency.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marketing Mix Optimization Market Trends and Innovations
Attribution methodology is splitting between privacy-compliant probabilistic approaches and deterministic closed-loop systems, with vendor competitive advantage hinging on data access rather than statistical sophistication alone.
Multi-touch attribution technology is bifurcating the vendor landscape. Platforms with direct retail data partnerships now deliver sales impact measurement without third-party cookies, while pure-play analytics firms without data assets compete on methodological transparency. Mid-market CPG brands gravitate toward the former despite higher subscription costs, compressing margins for methodology-only providers.
GDPR Article 44 transfer mechanism rulings are reshaping cross-border analytics deployment. The European Data Protection Board's Schrems II enforcement has invalidated Privacy Shield successor frameworks, compelling US-based SaaS vendors to establish EU-isolated infrastructure. Multinational CPG advertisers now operate bifurcated modeling environments, increasing total cost of ownership while creating compliance-driven switching costs for established vendors.
Buyer procurement patterns favor outcome-linked pricing over seat-based subscriptions. Enterprise marketing procurement teams at telecommunications and financial services firms now negotiate contracts tying vendor fees to documented ROI improvement, displacing traditional annual recurring revenue structures. This shift concentrates most visibly in the United Kingdom, where procurement function maturity exceeds continental European benchmarks and finance-marketing collaboration on vendor selection is most formalized.
Marketing Mix Optimization Market Segmentation
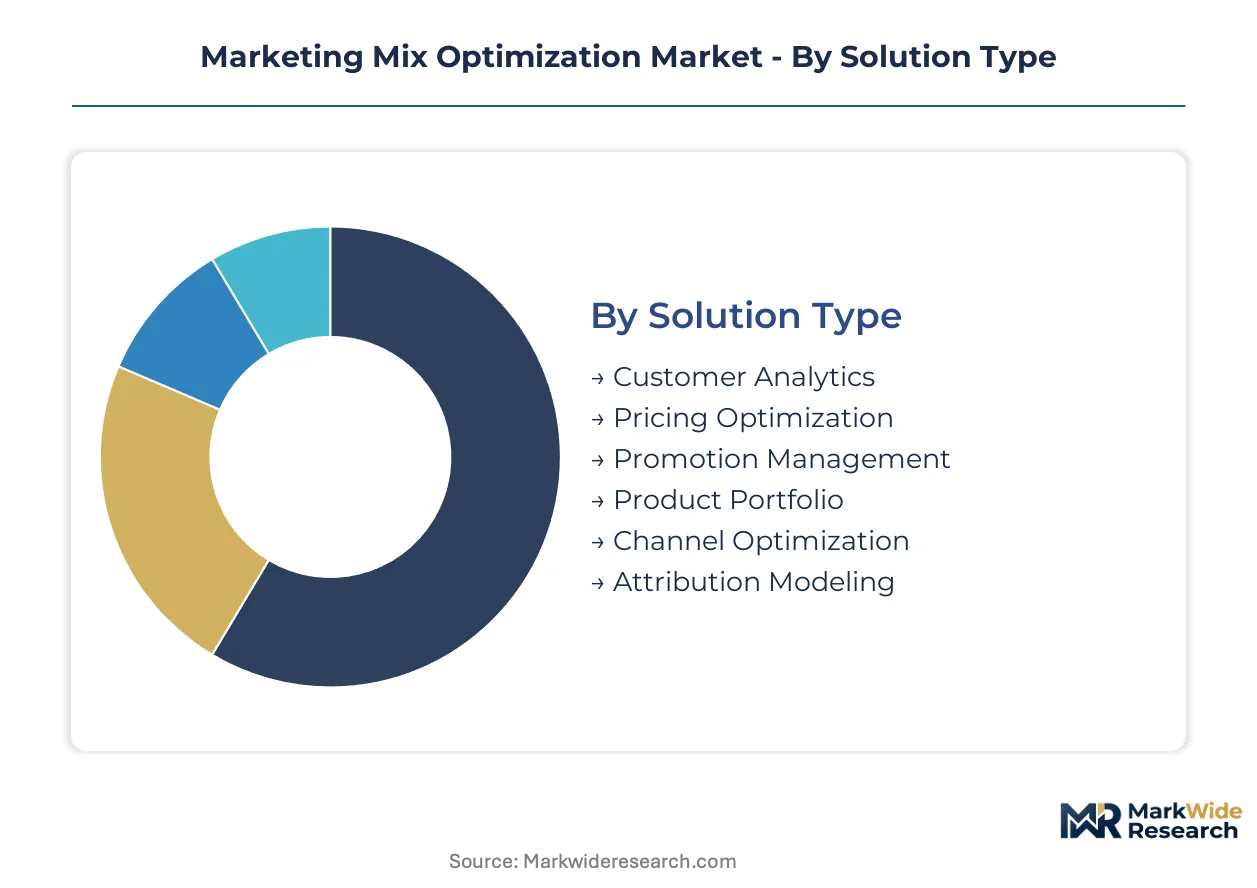
Marketing mix optimization vendors structure offerings around distinct solution architectures, deployment economics, and integration depths. Each segmentation dimension carries different geographic demand patterns and regulatory compliance burdens that shape vendor go-to-market priorities.
Solution Type:
Attribution Modeling and Pricing Optimization concentrate demand in North America and Western Europe where privacy regulations have forced methodological reinvention, while Promotion Management retains stronger traction in Asia-Pacific markets with less restrictive data governance.
- Attribution Modeling:Multi-touch probabilistic frameworks quantify channel contribution across non-linear customer journeys. Demand clusters among CPG advertisers in the United States and United Kingdom as cookie deprecation compels alternative measurement approaches. Bayesian hierarchical methods now dominate new deployments for sparse data handling.
- Pricing Optimization:Elasticity-driven algorithms recommend price points across product hierarchies and regional markets. Financial services and telecommunications firms in Germany and France deploy these tools for tariff architecture, constrained by GDPR limitations on competitor price scraping.
- Channel Optimization:Allocates spend across digital and physical touchpoints using marginal return analysis.
- Customer Analytics:Segmentation and lifetime value modeling for retention and acquisition targeting.
- Promotion Management:Trade promotion planning and post-event analytics for retail execution.
- Product Portfolio:SKU rationalization and innovation pipeline prioritization tools.
Attribution Modeling commands the established base. The steepest expansion runs through Pricing Optimization as inflation volatility elevates elasticity sensitivity.
Deployment Mode:
Cost tier differentiation separates enterprise-grade implementations from mid-market accessible alternatives, with subscription economics displacing perpetual licenses across revenue bands.
- Software as a Service:Browser-accessible platforms with standardized configurations reduce upfront implementation barriers. Mid-market CPG brands in the United States and United Kingdom favor this model for faster time-to-value and predictable operating expenditure treatment.
- Cloud Based:Scalable infrastructure with API extensibility supports high-volume transaction processing. Large retailers and telecommunications operators in China deploy these environments for real-time optimization at population-scale data volumes.
- On-Premise:Licensed software installed within client data centers for maximum control.
- Hybrid:Split architectures keeping sensitive data on-premise while leveraging cloud compute.
- Managed Hosting:Vendor-operated single-tenant infrastructure for clients requiring isolation without operational burden.
Software as a Service holds the volume base. Cloud Based deployments are climbing the fastest as data gravity shifts toward retail media networks.
End User Industry:
Application maturity varies sharply across verticals, with Fast-Moving Goods and Financial Services representing contrasting adoption profiles shaped by purchase cycle length and data richness.
- Fast-Moving Goods:High-frequency purchase cycles generate abundant training data for model refinement. CPG conglomerates headquartered in the United States, United Kingdom, and Switzerland deploy enterprise-wide optimization for billion-dollar brand portfolios with weekly replenishment patterns.
- Financial Services:Long consideration periods and regulatory disclosure requirements create distinct modeling challenges. Retail banks and insurers in Germany and Japan apply optimization to branch network allocation and digital acquisition spend with extended attribution windows.
- Telecommunications:Subscription economics and churn prediction drive optimization priorities.
- Consumer Electronics:Seasonal launch cycles and retailer dependency shape deployment patterns.
- Hospitality:Occupancy-based yield management with fragmented distribution channels.
- Education:Enrollment funnel optimization for institutional marketing departments.
Fast-Moving Goods maintains the revenue concentration. Financial Services is expanding most quickly as neobanks and fintech lenders adopt agile marketing infrastructure.
Integration Level:
Customer type segmentation separates standalone analytics purchases from embedded capabilities within broader enterprise software ecosystems.
- CRM Integrated:Native connections to Salesforce, HubSpot, and Microsoft Dynamics enable closed-loop lead-to-revenue measurement. B2B technology vendors in the United States and Israel prioritize this configuration for account-based marketing orchestration and sales alignment.
- ERP Connected:Direct data feeds from SAP, Oracle, and NetSuite unify financial and marketing planning. Manufacturing and industrial firms in Germany and Japan require this integration for cost-center accountability and procurement compliance.
- Standalone:Independent platforms requiring manual data ingestion and export.
- Marketing Automation:Embedded within Adobe, Salesforce Marketing Cloud, or Oracle Eloqua workflows.
- Data Management Platform:Audience and identity resolution infrastructure integration.
CRM Integrated solutions dominate new bookings. ERP Connected deployments are gaining share fastest as finance-marketing collaboration formalizes in procurement processes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price sensitivity for marketing mix optimization platforms, while mid-market brands in India and Southeast Asia negotiate aggressively on subscription terms. Western European procurement teams occupy a middle position, prioritizing compliance certifications over cost minimization.
United States
CPG conglomerates headquartered in Chicago and Cincinnati drive enterprise demand for closed-loop attribution connecting retail media networks to sales outcomes. The FTC enforces Section 5 consumer protection standards that constrain cross-context behavioral tracking, elevating first-party data infrastructure investments. New York and San Francisco anchor the vendor ecosystem, with SaaS platforms clustering around real-time bidding exchanges and cloud computing infrastructure.
United Kingdom
Telecommunications and financial services firms in London deploy outcome-linked vendor contracts that tie fees to documented ROI improvement. The Information Commissioner's Office applies GDPR-derived standards through the UK GDPR framework, mandating explicit consent for marketing analytics data processing. Manchester and Edinburgh host mid-market CPG brands adopting Bayesian hierarchical methods for sparse data environments with limited transaction history.
Germany
Automotive and industrial manufacturers in Munich and Stuttgart apply pricing optimization algorithms to tariff architecture across export markets. The Federal Cartel Office monitors data pooling arrangements between competitors under competition law, constraining collaborative modeling initiatives. Frankfurt concentrates banking sector demand for branch network allocation tools with extended attribution windows matching long consideration cycles.
China
E-commerce platforms and retail media networks in Shanghai and Shenzhen generate population-scale data volumes requiring real-time cloud optimization. The Personal Information Protection Law establishes data localization requirements that compel multinationals to deploy region-specific analytics infrastructure. Beijing anchors state-owned enterprise adoption for trade promotion management with centralized procurement compliance protocols.
India
FMCG brands in Mumbai and Bangalore negotiate SaaS subscriptions on per-seat economics rather than outcome-based structures. The Digital Personal Data Protection Act creates consent-layer requirements for marketing analytics that increase implementation complexity for foreign vendors. Gurugram hosts mid-market demand for attribution modeling as direct-to-consumer brands scale digital acquisition spend with compressed measurement budgets.
Marketing Mix Optimization Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in this market. Cloud-native platforms with direct retail data partnerships command premium pricing for closed-loop measurement capabilities, while methodology-focused vendors compete on statistical transparency at lower subscription tiers. The structure separates data-asset holders from pure-play analytics firms. Three archetypes dominate: integrated creative-to-analytics suites, specialized brand equity modelers, and retail-media-embedded attribution providers. Competitive moves concentrate on data partnership formation and regional infrastructure localization for compliance.
Within the integrated suite tier, Adobe leverages its Creative Cloud-to-Analytics pipeline to anchor enterprise clients seeking unified creative performance data. Kantar occupies a position among specialized modelers extending measurement beyond digital touchpoints into broadcast and out-of-home channels. NielsenIQ sits within the CPG relationship tier, navigating pressure as advertisers diversify measurement vendors across probabilistic and deterministic methodologies. These three exemplify how competitive positioning hinges on data access breadth and cross-channel integration depth rather than statistical sophistication alone.
| Leading Market Players |
|---|
| Adobe |
| Measured |
| Kantar |
| Sellforte |
| Analytic Edge |
| Ipsos |
| NielsenIQ |
| QuantSpark |
| Others |
Pricing and Supply Chain Analysis
First-party data infrastructure replacing third-party cookie inputs is redrawing vendor cost structures and client willingness-to-pay across the United States, United Kingdom, and Germany. This substitution simultaneously compresses margins for pure-play analytics firms while elevating pricing power for platforms with direct retail data partnerships.
Pricing Analysis
Outcome-linked service contracts now drive lifetime value for enterprise vendors serving telecommunications and financial services procurement teams in London and New York. SaaS-tiered subscription models dominate new bookings, with price differentiation resting on Bayesian methodological transparency and ISO 8000 data quality certification. Cost compression in the mid-market tier intensifies as sub-$50M revenue brands demand per-seat economics over ROI-linked structures. Fortune 500 CPG advertisers in Chicago and Cincinnati exhibit lowest price sensitivity; Indian direct-to-consumer brands in Gurugram negotiate most aggressively.
Supply Chain Analysis
Implementation lead times stretch to 8-14 months for ERP-connected deployments requiring legacy system integration. Vendor capability concentrates in the United States, United Kingdom, and China, with cloud-native platforms in San Francisco and London drawing from AWS, Azure, and Alibaba Cloud infrastructure. Specialized Bayesian statistical programming talent scarcity in Munich and New York creates single-source vulnerability for hierarchical model development. Distribution runs through direct enterprise sales teams and systems integrators serving CPG and financial services verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marketing mix optimization functions as a defensive-moat business where regulatory entrenchment around GDPR-compliant data residency creates sticky, high-switching-cost client relationships.
For Market Incumbents: Consolidate data partnership exclusivity with Walmart Connect and Amazon Advertising to lock out methodology-only competitors. Deepen EU-isolated infrastructure investments in Frankfurt and Dublin before Schrems II enforcement hardens further. Vertical integration into first-party identity resolution systems defends against emerging retail-media-embedded attribution providers. For New Entrants and Emerging Players: Anchor in audio and podcast channel measurement where host-read advertising lacks standardized signal-to-sale linkage. Connected TV impression-to-sale attribution offers the most penetrable white space; smart TV data integration with retail transaction logs provides a defensible go-to-market angle against established digital-native platforms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Bayesian specialist firms commanding premium talent compensation in London and New York. Long-term viability favors platforms with demonstrated retail data partnerships and regional compliance infrastructure. Watch for App Tracking Transparency enforcement tightening as the inflection signal for deterministic attribution obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Retail Data Partnership Formation | Closed-loop measurement capabilities with Walmart Connect bypass cookie-dependent tracking for CPG advertisers. |
| EU Infrastructure Localization | GDPR Article 44 compliance in Frankfurt and Dublin creates switching costs for multinational enterprise clients. |
| Bayesian Talent Acquisition | Hierarchical modeling expertise in London and New York addresses the primary scaling constraint for vendor expansion. |
| ISO 8000 Certification Investment | Documented data quality management satisfies procurement mandates at Deutsche Telekom and BT Group. |
| Connected TV Measurement Development | Smart TV-retail transaction integration solves attribution gaps for streaming platforms lacking standardized linkage. |
Research Methodology
Operator-level perspectives from marketing science directors, procurement officers at telecommunications firms, CPG brand managers, and cloud platform engineers anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings, hyperscaler capex disclosures, and retail media network partnership announcements. Bottom-up deployment estimates triangulated against top-down digital advertising spend allocations.
Sensitivity analysis tested forecast outputs across privacy regulation enforcement scenarios and retail media network expansion rates. Segmentation dimensions modeled include solution type, deployment mode, end-user industry, integration level, and regional regulatory cluster. CAGRs derived from multivariate regression of historical adoption curves against privacy-driven methodological transition timelines. Bayesian hierarchical method penetration and first-party data infrastructure investment velocity served as key forecast inputs.
Decision-makers should treat outputs as directional under sustained GDPR enforcement and cookie deprecation assumptions; material deviation in App Tracking Transparency scope or retail data partnership exclusivity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.