
 Fluorosilicone (FVMQ) Rubber Market | 2026-2036
Fluorosilicone (FVMQ) Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorosilicone (FVMQ) Rubber Market Foresight
Multi-source procurement for specialty fluoropolymers is consolidating as compounders seek supply security amid volatile siloxane feedstock markets. Dow anchors North American production through integrated silane-to-elastomer manufacturing. Shin-Etsu Chemical Co., Ltd dominates Asian supply chains with captive chlorosilane capacity. Wacker Chemie AG competes in European markets through precision blending operations for aerospace-grade specifications.
Fluorosilicone (FVMQ) rubber combines siloxane backbone flexibility with fluorinated side-chain chemical resistance, typically containing 25-35% fluorine content by weight and operating across temperatures from -60°C to 200°C. Hydrosilylation cure technology leads volume production for medical and aerospace applications due to platinum-catalyzed precision and absence of peroxide byproducts. Aerospace seals command premium positioning within the application matrix, while fuel systems represent the fastest-growing demand cluster as automotive OEMs adopt biofuel-compatible elastomers.
EPA oversight of fluoropolymer emissions and REACH restrictions on perfluorinated substances are reshaping formulation requirements across the value chain. ECHA's evolving PFAS restrictions threaten conventional FVMQ chemistries, forcing compounders toward low-fluorine alternatives or bio-based silicone hybrids. Stakeholders must monitor regulatory divergence between EU hazard-based frameworks and US risk-assessment approaches when allocating R&D budgets and qualifying new material platforms.
Market Dynamics
Siloxane feedstock volatility is compressing compounder margins while forcing qualification cycles for alternative cure systems. Aerospace OEMs now mandate dual-source elastomer certification, restructuring supplier relationships across the value chain.
Growth Catalysts
- Biofuel-compatible formulations:Automotive fuel systems require elastomers resisting ethanol and biodiesel permeation. FVMQ's fluorinated side chains meet swelling resistance specifications that conventional silicone fails.
- REACH chemical authorization:European aerospace seal manufacturers face mandatory substitution timelines for legacy fluoroelastomers. Low-fluorine FVMQ variants qualify under restricted substance protocols.
- Platinum-catalyzed hydrosilylation:Medical device manufacturers adopt peroxide-free cure systems for implantable applications. FDA biocompatibility pathways favor platinum-cured elastomers over peroxide residues.
Market Restraints
- Chlorosilane supply concentration:Asian chlorosilane producers control 70% of global siloxane monomer capacity. European compounders face freight cost exposure and currency hedging complexity.
- PFAS regulatory friction:ECHA's universal PFAS restriction proposal threatens conventional 30% fluorine FVMQ grades. Reformulation timelines outpace certification renewal cycles.
- Fluoropolymer cost structure:Fluorinated monomer prices track fluorspar mining volatility and Chinese export quotas. Compounders cannot pass full input cost swings to aerospace contract customers.
Strategic Opportunities
- Underpenetrated medical tubing:Germany's industrial corridor hosts catheter manufacturers seeking platinum-cured elastomers. Local compounders can bypass Asian import lead times.
- EV thermal management:Battery pack coolant seals require -60°C cold-flex performance. FVMQ outperforms HNBR in glycol-based coolant compatibility.
- EU Green Deal procurement mandates:Public aerospace tenders now weight lifecycle carbon footprint. Low-energy cure systems qualify for preferential scoring.
Industry Challenges
- Formulation chemist scarcity:Hydrosilylation kinetics expertise concentrates at Dow and Shin-Etsu. Mid-tier compounders struggle to recruit platinum-cure specialists.
- AS9100D certification timelines:Aerospace material qualification requires 18-24 month OEM validation cycles. New entrants face working capital strain during pre-revenue periods.
- Legacy peroxide cure integration:Existing mixing equipment requires retrofit for platinum catalyst handling. Capital expenditure decisions delay product line transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorosilicone (FVMQ) Rubber Market |
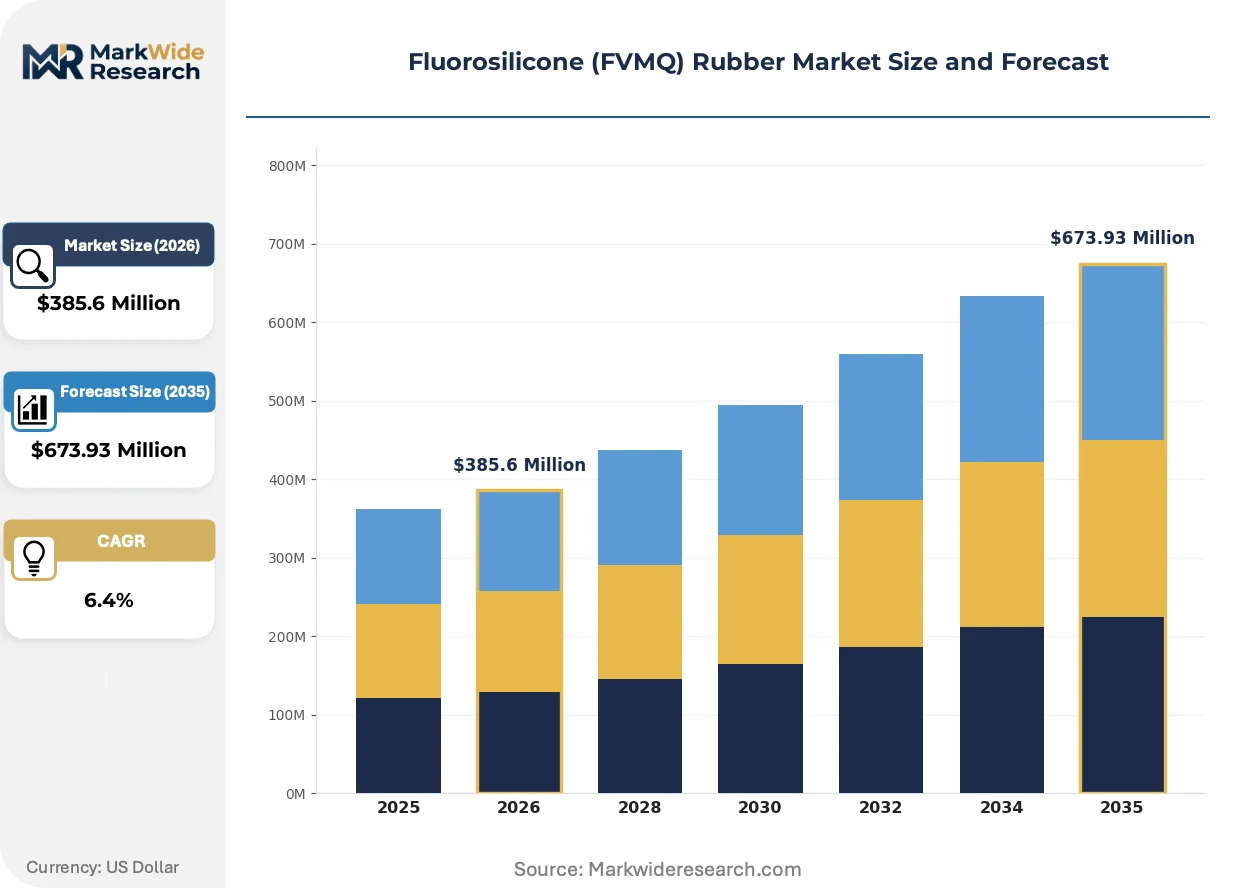
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorosilicone Base, Fluorosilicone Composite, Fluorosilicone Foam, Fluorosilicone Elastomer Technology: Hydrosilylation Cure, Condensation Cure, Peroxide Cure, Addition Cure, Radiation Cure Application: Aerospace Seals, Electric Connector Housings, Fuel Systems, Chemical Equipment, HVAC Components End User Industry: Oilfield Equipment Manufacturers, Semiconductor Fabricators, Marine Engineering, Defense Contractors, Renewable Energy Providers |
| Companies Covered | Shin-Etsu Chemical Co., Ltd, Rogers Corporation, Dow, STOCKWELL ELASTOMERICS, INC, Shanghai Fluoron Chemicals, Wacker Chemie AG, James Walker, Shanghai 3F New Materials Co., Ltd, Momentive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorosilicone (FVMQ) Rubber Market Shifts & Advancements
Formulation science is diverging along regulatory fault lines, with European compounders pursuing low-fluorine alternatives while North American suppliers optimize legacy high-fluorine grades for exempted applications.
Low-fluorine FVMQ hybrids are absorbing reformulation investment as ECHA's PFAS restrictions advance through committee review. German aerospace seal manufacturers now specify sub-20% fluorine content for new platform designs. This chemistry pivot is compressing demand for conventional 30-35% fluorine grades in European procurement.
EPA fluoropolymer emissions oversight is tightening stack monitoring requirements at Ohio and Michigan compounding facilities. Aerospace suppliers must demonstrate destruction efficiency for volatile siloxane byproducts. Medical device extruders in Massachusetts face supplemental reporting under state-level TURA protocols.
Dual-source qualification mandates from Boeing and Airbus are fragmenting procurement patterns. Tier-1 seal fabricators now maintain approved supplier lists across three continents. German industrial buyers lead this behavioral shift, requiring compounders to demonstrate redundant mixing capacity before contract award.
Fluorosilicone (FVMQ) Rubber Market Segmentation
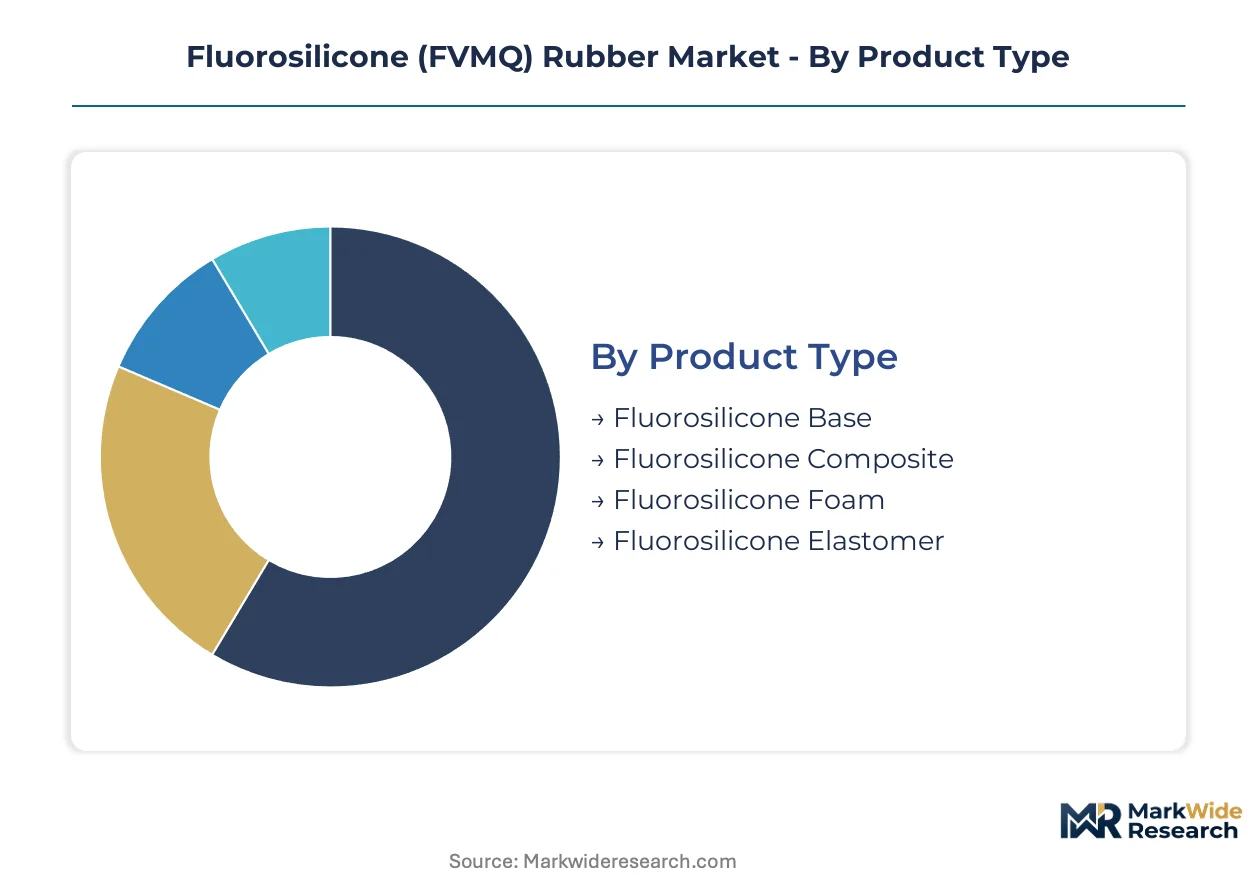
Segmentation in fluorosilicone rubber markets reveals how formulation chemistry, cure technology, and end-use certification requirements partition value capture. Each axis carries distinct margin structures and qualification barriers that reshape procurement patterns.
Product Type:
Material form determines processing equipment requirements and shapes the geographic distribution of compounding capacity.
- Fluorosilicone Base:Unfilled polymer gum serves as the feedstock for captive compounding operations at major seal manufacturers. Dow and Shin-Etsu dominate merchant supply, with German aerospace compounders now qualifying secondary sources to satisfy dual-source mandates.
- Fluorosilicone Composite:Pre-compounded grades incorporating mineral fillers and pigments command premium positioning in medical tubing applications. Massachusetts-based extruders specify platinum-cured composites for FDA biocompatibility pathways.
- Fluorosilicone Foam:Cellular structures provide thermal insulation in aircraft cabin applications. Density control during hydrosilylation cure requires specialized mixing equipment.
- Fluorosilicone Elastomer:Fully formulated ready-to-mold compounds target small-batch aerospace seal fabricators lacking in-house compounding capabilities.
Mature deployment sits with Fluorosilicone Base for large-volume seal manufacturers. Newer deployment is concentrated in Fluorosilicone Composite for medical device OEMs seeking turnkey material solutions.
Technology:
Cure chemistry selection governs regulatory compliance pathways and determines which compounders can serve medical versus aerospace demand clusters.
- Hydrosilylation Cure:Platinum-catalyzed addition curing eliminates peroxide byproducts, satisfying FDA biocompatibility requirements for implantable devices. German catheter manufacturers specify this technology exclusively.
- Condensation Cure:Tin-catalyzed moisture cure systems suit field repair applications where oven curing proves impractical. Marine engineering contractors in Hamburg specify condensation-cure sealants for vessel maintenance.
- Peroxide Cure:Traditional organic peroxide systems retain cost advantage in non-medical industrial gasketing. EPA emissions oversight is forcing Ohio compounders to install thermal oxidizers for volatile byproduct destruction.
- Addition Cure:Room-temperature vulcanizing variants target rapid prototyping workflows at defense contractors. Munich-based fabricators use addition-cure tooling compounds for seal geometry validation.
- Radiation Cure:Electron beam processing enables solvent-free coating applications on wire insulation. Semiconductor fabricators in Dresden evaluate radiation-cured FVMQ for cleanroom compatibility.
Established volume concentrates in Peroxide Cure for cost-sensitive industrial applications. Steepest expansion trajectory belongs to Hydrosilylation Cure as medical device qualification cycles accelerate.
Application:
End-use performance specifications create tiered pricing structures based on temperature range, chemical resistance, and certification burden.
- Aerospace Seals:AS9100D-certified materials must demonstrate -60°C cold-flex performance and 200°C continuous service. Boeing and Airbus dual-source mandates fragment procurement across German, US, and Japanese compounders.
- Electric Connector Housings:Dielectric stability requirements favor medium-fluorine grades balancing chemical resistance with electrical properties. Automotive OEMs in Stuttgart specify these for EV battery pack connectors.
- Fuel Systems:Biofuel compatibility specifications demand swelling resistance to ethanol and biodiesel permeation. FVMQ outperforms conventional silicone for automotive fuel line seals.
- Chemical Equipment:Aggressive media resistance drives specification of high-fluorine grades in process industry gasketing. REACH chemical authorization timelines are forcing substitution of legacy fluoroelastomers.
- HVAC Components:Refrigerant compatibility with low-GWP alternatives shapes formulation requirements. EU F-Gas Regulation is accelerating FVMQ adoption in heat pump systems.
Revenue concentration remains with Aerospace Seals. Gaining share fastest is Fuel Systems as automotive biofuel mandates expand across European markets.
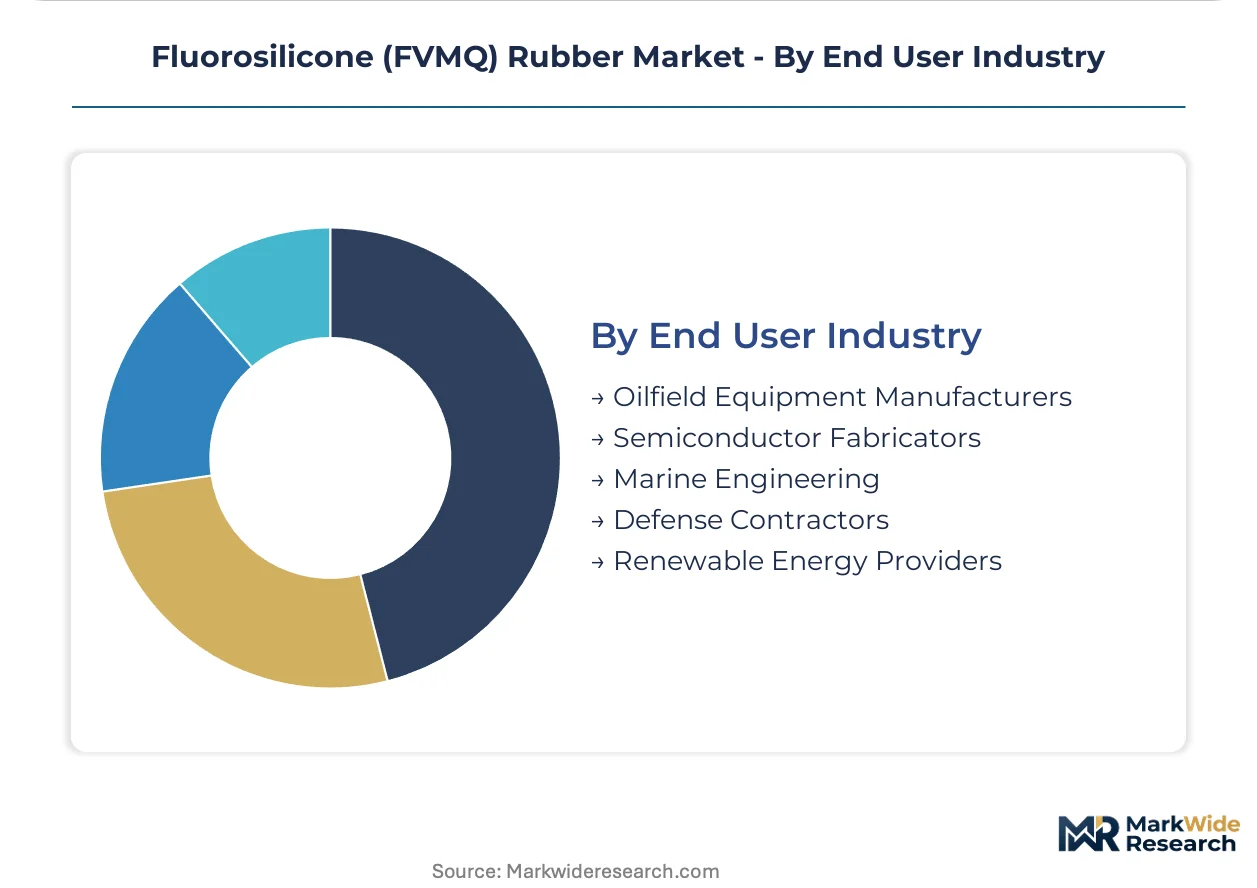
End User Industry:
Customer industry determines certification requirements, volume scale, and the geographic locus of compounding capacity.
- Oilfield Equipment Manufacturers:Downhole sealing applications require H2S resistance and rapid gas decompression performance. Aberdeen-based suppliers specify high-consistency FVMQ for North Sea drilling equipment.
- Semiconductor Fabricators:Ultra-high purity requirements restrict extractable content in chamber seals. Dresden and Munich fabs drive demand for low-outgassing platinum-cured grades.
- Marine Engineering:Saltwater immersion and fuel compatibility specifications govern material selection. Hamburg shipyards specify FVMQ for diesel engine gaskets and fuel system components.
- Defense Contractors:MIL-SPEC qualification requirements create long validation cycles but stable procurement volumes. German defense procurement favors domestic compounders with NATO security clearance.
- Renewable Energy Providers:Wind turbine gearbox seals and solar thermal system gaskets require UV and glycol resistance. Bavarian wind energy clusters specify FVMQ for cold-climate turbine installations.
Contract stability concentrates in Defense Contractors. Volume expansion is accelerating fastest among Semiconductor Fabricators as wafer fab capacity expands across Germany's industrial corridor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Siloxane feedstock availability concentrates manufacturing capacity near chlorosilane production clusters in Germany, Japan, and the United States. Aerospace seal demand and tightening PFAS regulations are redrawing procurement maps across these three markets.
Germany
Bavarian aerospace fabricators specify low-fluorine FVMQ grades under ECHA's evolving PFAS restrictions. REACH chemical authorization timelines force substitution of legacy fluoroelastomers in Stuttgart automotive fuel systems. The industrial corridor between Munich and Hamburg hosts catheter manufacturers seeking platinum-cured elastomers with shortened import lead times.
United States
EPA emissions oversight tightens stack monitoring at Ohio and Michigan compounding facilities serving Boeing and Airbus supply chains. FDA biocompatibility pathways favor platinum-cured elastomers for Massachusetts medical device extruders. Defense contractors in the Midwest specify MIL-SPEC qualified materials through domestic compounders with NATO security clearance.
Japan
Shin-Etsu's captive chlorosilane capacity anchors Asian supply security amid volatile feedstock markets. METI industrial standards govern material qualification for semiconductor fabricators in Kyushu and Kansai regions. Nagoya-based automotive OEMs adopt biofuel-compatible FVMQ seals for ethanol-blended gasoline systems.
China
MIIT standards and dual carbon goals reshape formulation requirements for domestic EV battery pack coolant seals. Shanghai compounders serve regional medical tubing demand while navigating GB standards compliance. The Yangtze River Delta concentrates fluoropolymer blending capacity for export-oriented aerospace component suppliers.
Fluorosilicone (FVMQ) Rubber Market Competitive Landscape
Global majors compete with regional champions across integrated silane-to-elastomer manufacturing versus precision blending specializations. Market structure tilts toward consolidated upstream supply with fragmented downstream compounding. Three archetypes dominate: integrated chemical conglomerates with captive feedstock, specialty elastomer compounders serving aerospace certification requirements, and regional distributors qualifying secondary sources for dual-source mandates. Capacity expansion and portfolio diversification toward low-fluorine alternatives represent the dominant competitive vectors.
Among integrated chemical producers, Dow and Shin-Etsu Chemical Co., Ltd exemplify the feedstock-anchored archetype with siloxane monomer control. Wacker Chemie AG occupies a position within European precision blending specialists serving aerospace-grade specifications. These three entities represent distinct geographic and capability poles that structure procurement options for tier-1 seal fabricators.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd |
| Rogers Corporation |
| Dow |
| STOCKWELL ELASTOMERICS, INC |
| Shanghai Fluoron Chemicals |
| Wacker Chemie AG |
| James Walker |
| Shanghai 3F New Materials Co., Ltd |
| Momentive |
| Others |
Supply & Pricing Matrix
Dual-source qualification mandates from Boeing and Airbus are forcing compounders to absorb redundant capacity costs without corresponding price relief. This procurement pressure compresses margins while siloxane feedstock volatility prevents cost pass-through to aerospace contract customers.
Pricing Analysis
Warranty-backed AS9100D certification bundles command premium positioning over unbundled base polymer supply. Pricing stratifies across aerospace-grade certified compounds, medical-device biocompatibility tiers, and industrial peroxide-cured grades. Cost compression in standard industrial formulations is intensifying because European compounders discount legacy high-fluorine inventory ahead of ECHA restrictions. Medical device OEMs exhibit lowest price sensitivity due to FDA pathway requirements and liability exposure.
Supply Chain Analysis
Scrap FVMQ from aerospace seal fabrication feeds regional recompounding operations in Germany and Ohio. Manufacturing gravity centers on Germany, Japan, and the United States near chlorosilane production clusters. Feedstock draws from fluorspar mining operations and captive siloxane monomer capacity controlled by Asian producers. Single-source vulnerability concentrates in platinum catalyst supply chains. Distribution runs through authorized distributor networks serving Tier 1 seal fabricators with AS9100D traceability requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as compounders pursue captive chlorosilane capacity to escape feedstock price volatility and supply disruption.
For Market Incumbents: Acquire chlorosilane production assets or secure long-term offtake agreements with Shin-Etsu or Dow. Expand mixing capacity in Germany's industrial corridor to satisfy dual-source mandates from Airbus and Stuttgart automotive OEMs. Defend against low-fluorine substitute technologies by accelerating ECHA-compliant formulation certification. For New Entrants and Emerging Players: Regional catheter manufacturers in Bavaria represent an underserved buyer archetype seeking shortened lead times for platinum-cured medical tubing. Establish toll compounding partnerships with existing AS9100D-certified facilities rather than building greenfield capacity. Target semiconductor fabricators in Dresden with ultra-high-purity low-outgassing grades as wafer fab expansion accelerates. For Investors and Strategic Acquirers: The window for entry favors specialty compounders with existing aerospace certification and hydrosilylation expertise. Five-to-ten year viability hinges on successful navigation of PFAS regulatory divergence between EU hazard-based and US risk-assessment frameworks. Monitor ECHA committee voting timelines and EPA stack monitoring enforcement actions as inflection indicators for formulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Supply | Captive feedstock secures margin stability against fluorspar export quota volatility. |
| Low-Fluorine Formulation Development | ECHA PFAS restriction compliance opens European aerospace procurement to qualified suppliers. |
| AS9100D Certification Investment | Dual-source mandates from Boeing and Airbus require redundant qualified capacity. |
| Platinum-Cure Capacity Expansion | FDA biocompatibility pathways favor peroxide-free systems for implantable devices. |
| Regional Mixing Footprint in Germany | Local presence satisfies import substitution preferences from Munich-to-Hamburg industrial corridor. |
Research Methodology
Trade databases, regulatory filings, and industry association reports formed the secondary backbone of this analysis. Primary interviews with compounder plant managers, aerospace procurement leads at Tier 1 seal fabricators, medical device R&D directors, and chlorosilane supply specialists validated quantitative assumptions. Bottom-up volume estimates from end-use application segments triangulated against top-down value projections from raw material input cost structures.
Historical trendline analysis of fluorosilicone pricing and volume movements informed projection modeling across the analysis window. Segmentation dimensions included cure technology type, fluorine content grade, end-use industry certification tier, and regional production hub. CAGRs derived from elasticity-adjusted demand curves incorporating biofuel mandate expansion rates and semiconductor fab capacity buildout schedules. Siloxane monomer price volatility indices and ECHA regulatory timeline scenarios served as key forecast inputs.
Revisions become necessary when PFAS restriction scope expands beyond current ECHA proposals or when fluorspar export quotas tighten unexpectedly. Forecasts reflect assumptions about platinum catalyst supply continuity and aerospace OEM dual-source mandate stability. Practitioners should monitor ECHA committee voting outcomes and EPA enforcement actions in Ohio and Michigan for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Metallurgical Rubber Roller Market
Rubber
Global Rubber Coated Fabrics Market
Rubber
Europe Silicone Rubber Market
Rubber
Rubber Tapes Market
Rubber
Ethylene Propylene Rubber Cable Market
Rubber
Rubber Rollers Market
Rubber
Rubber Plated Hose Market
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
Synthetic Rubber Market
Rubber
Global Rubber Process Oil Market
Rubber
Solution Styrene Butadiene Rubber (S-SBR) Market
Rubber
Industrial Rubber Market
Rubber
Performance Elastomers Market
Rubber
Europe Rubber Derived Unrefined Pyrolysis Oil Market
Rubber
Chloro-Sulfonated Polyethylene Market
Rubber
Polyisoprene Rubber Market