
 China Food Colorants Market | 2026-2036
China Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
China Food Colorants Market Outlook
Modular colorant dosing systems is realigning procurement patterns among mid-sized food processors seeking batch flexibility without inventory bloat. Chr. Hansen Holding A/S leverages its fermentation-derived pigment portfolio to dominate premium natural colorant supply. Zhejiang Weile Biotechnology Co., Ltd. anchors its position through captive extraction capabilities in plant-based anthocyanin production. Sensient Technologies Corporation competes via integrated emulsion technologies that reduce downstream formulation steps for beverage clients.
Food colorants comprise chromophoric compounds—whether carotenoids, anthocyanins, azo dyes, or aluminum lakes—dispersed or dissolved to impart visual identity to edible products, with stability measured by heat tolerance, pH sensitivity, and lightfastness across processing conditions. Natural colorants now command disproportionate R&D investment as SAMR tightens artificial additive approvals, though synthetic colorants retain volume leadership in cost-sensitive confectionery applications. Dairy represents an emerging margin pool where clean-label pressure intersects with fat-matrix compatibility challenges that favor specialized emulsion concentrates over standard liquid dyes.
GB 2760 standards and SAMR oversight define permitted additive lists, maximum usage levels, and labeling requirements that directly determine which colorant classes gain formulation access. NMPA alignment with international Codex frameworks is accelerating safety reassessment timelines for legacy synthetic dyes. Stakeholders must monitor regulatory harmonization signals between China's national standards and evolving EU EFSA evaluations to anticipate reformulation mandates before compliance deadlines crystallize.
Market Dynamics
GB 2760 tightening on synthetic additive limits is compressing formulation options while forcing R&D investment toward fermentation-derived and plant-extracted alternatives across dairy and beverage manufacturing clusters.
Growth Catalysts
- Clean-label mandates:SAMR's stricter labeling requirements for artificial colorants are accelerating natural pigment adoption in premium dairy applications.
- Fermentation technology maturation:Microbial pigment production is reducing batch-to-batch color variance that previously constrained natural colorant scale-up.
- Coastal manufacturing concentration:Shanghai and Guangzhou processing hubs are aggregating demand sufficient to justify dedicated natural colorant extraction facilities.
Market Restraints
- Raw material volatility:Anthocyanin feedstock from purple sweet potato and grape skins faces agricultural price swings that compress natural colorant margins.
- Technical performance gaps:Natural carotenoids exhibit inferior heat stability versus azo dyes, limiting deployment in high-temperature confectionery processing.
- Regulatory friction:NMPA's alignment with Codex frameworks is accelerating safety reassessment timelines that force premature reformulation cycles.
Strategic Opportunities
- Underpenetrated inland provinces:Sichuan and Shaanxi food processors remain reliant on synthetic dyes, creating first-mover openings for natural colorant suppliers with technical service capabilities.
- Regulatory tailwind:China's dual carbon goals are incentivizing bio-based pigment production through preferential energy pricing and carbon credit mechanisms.
- Technology convergence:Encapsulation technologies combined with emulsion systems are unlocking fat-matrix compatibility that expands natural colorant addressability in cheese and ice cream.
Industry Challenges
- Formulation chemistry expertise scarcity:Food technologists capable of stabilizing natural pigments across pH and temperature ranges command premium compensation that strains mid-processor R&D budgets.
- Certification timeline compression:SAMR's accelerated safety data requirements are extending new colorant approval cycles, freezing product pipeline velocity for 18-24 month windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Food Colorants Market |
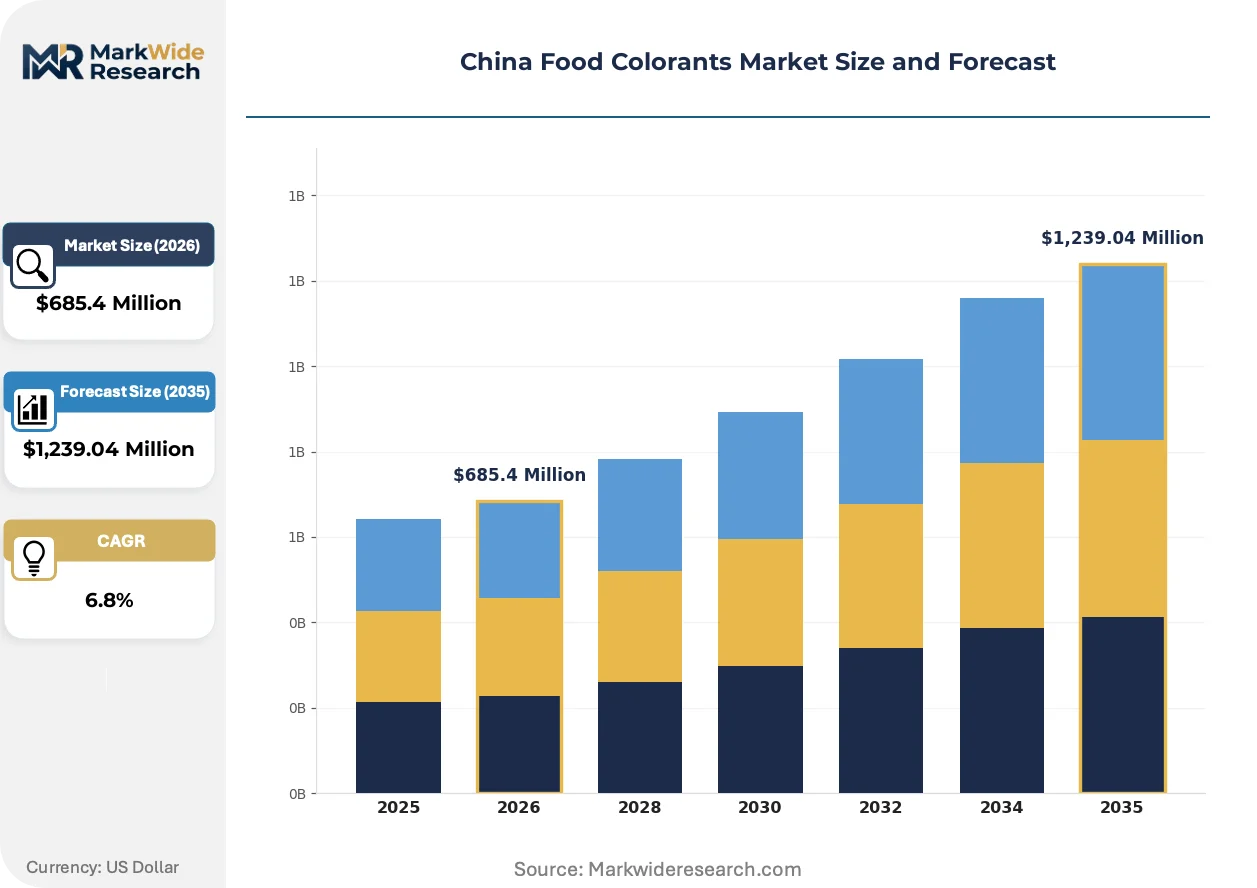
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colorants, Synthetic Colorants, Concentrates, Liquid Dyes Source: Plant-Based, Animal-Based, Mineral-Based, Artificial Application: Beverages, Bakery Products, Confectionery, Dairy End User: Food Manufacturers, Restaurants, Retailers, Household |
| Companies Covered | Chr. Hansen Holding A/S, Koninklijke DSM N.V., Sensient Technologies Corporation, D.D. Williamson & Co, Dohler Group, Givaudan, Zhejiang Weile Biotechnology Co., Ltd., Shaanxi Fuheng Biotechnology Co., Ltd., Guangzhou ZIO Chemical Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Food Colorants Market Strategic Shifts
Fermentation-derived pigment systems are absorbing capital and technical talent at the expense of traditional extraction methods, while regulatory harmonization pressures and procurement centralization reshape competitive positioning.
Microbial fermentation platforms for carotenoid and anthocyanin production are absorbing investment from both specialty chemical and food ingredient suppliers seeking supply security independent of agricultural harvest cycles. Beverage manufacturers in Guangdong and Zhejiang are adopting these bio-produced colorants at pilot scale, with full production integration anticipated within 24 months. The technology is absorbing market share from plant-extraction specialists who lack comparable batch consistency and year-round supply assurance.
GB 2760-2024 revisions and SAMR's alignment with Codex Alimentarius frameworks are compressing the approved synthetic colorant list while elevating documentation requirements for natural additive safety substantiation. Manufacturers face reformulation mandates with 12-18 month compliance windows that strain technical resources. Confectionery segment participants are responding by accelerating partnerships with fermentation-derived pigment suppliers capable of delivering performance parity to legacy azo dyes.
Direct procurement relationships between colorant suppliers and large beverage processors are displacing traditional distributor intermediaries in coastal manufacturing zones. Procurement teams at functional drink manufacturers are consolidating supplier panels to three-to-four preferred partners with integrated technical service capabilities. This concentration is most visible in Shanghai's Pudong and Minhang districts, where multinational beverage R&D centers co-locate with colorant formulation laboratories.
China Food Colorants Market Segmentation
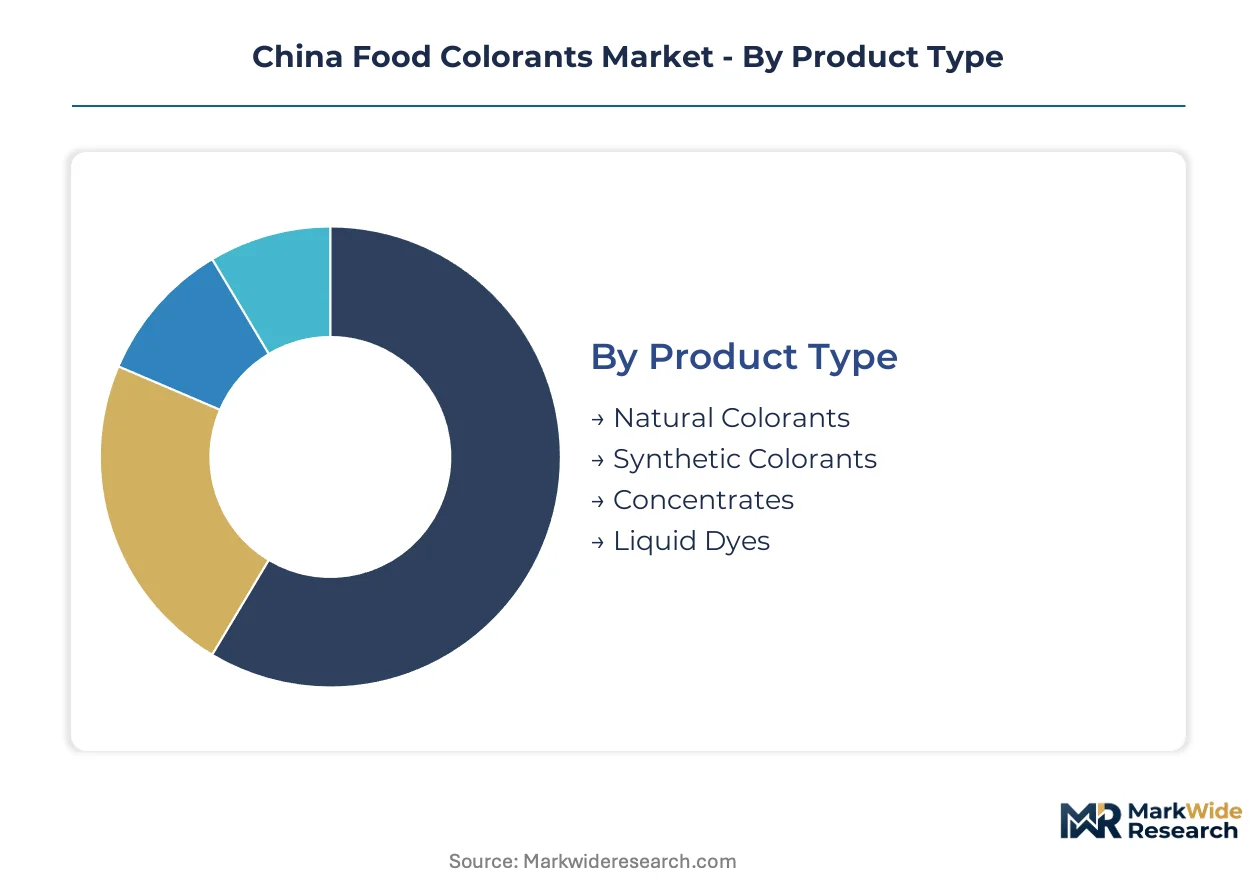
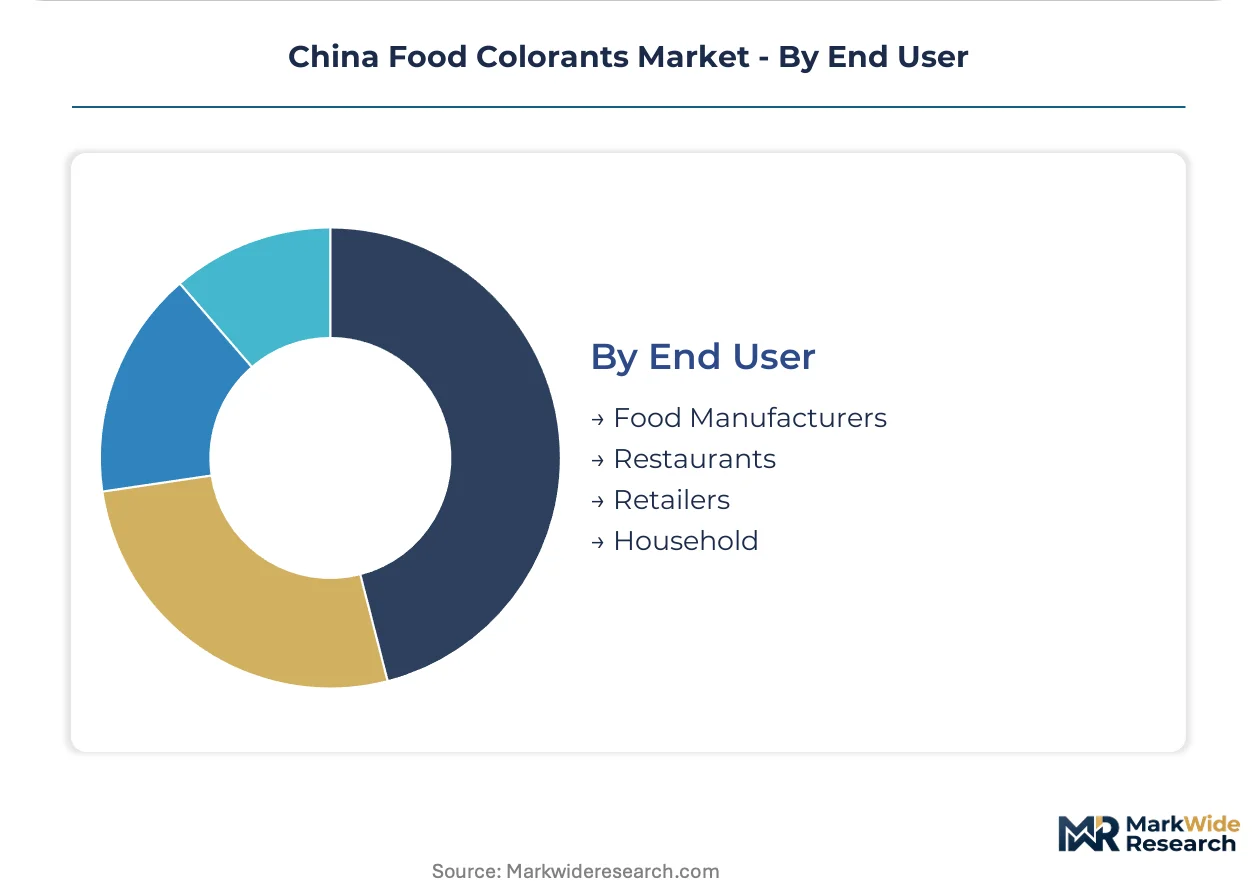
Segmentation in China's food colorants market reveals divergent procurement priorities across buyer types. Natural colorant demand clusters in premium dairy and functional beverage manufacturing, while synthetic dyes retain footholds in cost-driven confectionery segments.
Product Type:
Buyers differentiate primarily by formulation flexibility requirements and clean-label positioning mandates.
- Natural Colorants:Anthocyanins, carotenoids, and curcuminoids extracted from plant matrices dominate premium applications. Shanghai and Guangzhou beverage manufacturers are expanding procurement of fermentation-derived natural pigments to meet SAMR labeling requirements.
- Synthetic Colorants:Azo dyes and aluminum lakes deliver batch-to-batch consistency at unit costs 40-60% below natural equivalents. GB 2760 tightening is compressing approved synthetic lists, forcing reformulation investment among legacy users.
- Concentrates:High-solids dispersions reduce shipping volumes and storage footprints for coastal processors with constrained warehouse capacity.
- Liquid Dyes:Ready-to-dose solutions serve mid-sized bakeries lacking technical staff for colorant reconstitution.
Volume sits with Synthetic Colorants; growth tilts toward Natural Colorants.
Source:
Supply security and price volatility tolerance separate procurement strategies in this dimension.
- Plant-Based:Anthocyanin extraction from purple sweet potato and grape skins anchors China's natural colorant supply. Agricultural harvest variability drives margin compression that fermentation alternatives are beginning to offset.
- Animal-Based:Carmine and cochineal derivatives serve niche applications requiring heat stability beyond plant pigment capabilities. Religious dietary restrictions limit addressability in halal-certified product lines.
- Mineral-Based:Titanium dioxide and iron oxides provide opacity and metallic tones in decorative confectionery with minimal pH sensitivity.
- Artificial:Petrochemical-derived chromophores retain volume leadership in mass-market candy production where cost minimization outweighs clean-label pressure.
Plant-Based sources dominate procurement attention; Artificial maintains shipment volume leadership.
Application:
Processing temperature regimes and pH exposure dictate colorant selection across end-use categories.
- Beverages:Acidic pH environments in functional drinks favor anthocyanin stability, while tea and coffee applications demand lightfastness that carotenoid systems provide. Guangdong processors are piloting fermentation-derived pigments at commercial scale.
- Bakery Products:Maillard reaction temperatures exceeding 180°C degrade most natural pigments, preserving synthetic dye penetration in bread and cake decoration.
- Confectionery:Hard candy manufacturing requires heat stability that azo dyes deliver; gummy segments show faster natural colorant conversion due to lower processing temperatures.
- Dairy:Fat-matrix compatibility challenges favor specialized emulsion concentrates over standard liquid dyes in cheese and ice cream applications.
Beverages command R&D investment intensity; Dairy shows steepest expansion trajectory as clean-label pressure intersects with formulation innovation.
End User:
Technical capability and volume scale determine whether buyers self-formulate or outsource colorant specification.
- Food Manufacturers:Large processors in Shanghai and Guangzhou maintain in-house color labs and direct supplier relationships, consolidating panels to three-to-four preferred partners with integrated technical service.
- Restaurants:Chain operators with centralized procurement specify colorant systems for menu consistency; independent establishments rely on distributor-formulated blends.
- Retailers:Private-label product development teams are expanding natural colorant specifications to differentiate shelf positioning.
- Household:Consumer-packaged decorating colors represent minimal volume but highest per-unit margins.
Food Manufacturers concentrate absolute demand; Retailers are gaining procurement sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in coastal manufacturing belts while inland provinces remain dependent on imported colorant supplies. Yangtze River Delta and Pearl River Delta processing clusters consume over half of national colorant volumes. SAMR's regional enforcement intensity varies, creating compliance arbitrage opportunities that coastal processors exploit through direct supplier relationships.
Yangtze River Delta
Shanghai beverage manufacturers drive anthocyanin procurement for functional drink lines targeting clean-label positioning. GB 2760-2024 enforcement here exceeds national averages, accelerating synthetic dye phase-outs. Pudong and Minhang districts host co-located R&D centers where multinational beverage developers test fermentation-derived pigments at pilot scale.
Pearl River Delta
Guangzhou confectionery and dairy processors command specialized emulsion concentrates for fat-matrix applications. SAMR Guangdong branch maintains stricter documentation requirements for natural additive safety substantiation than inland counterparts. Foshan and Dongguan industrial zones are attracting fermentation-derived pigment suppliers seeking proximity to dairy manufacturing clusters.
Sichuan-Chongqing
Spice and sauce manufacturers in Chengdu represent underpenetrated demand for heat-stable natural colorants in processed food applications. Provincial regulators lag coastal counterparts in GB 2760 implementation timelines, preserving synthetic dye usage in cost-sensitive segments. Chongqing's emerging food processing belt is drawing technical service teams from coastal suppliers seeking first-mover positioning.
Shandong Peninsula
Qingdao and Yantai seafood processors utilize carotenoid systems for surimi and fish cake visual enhancement. Local MEE offices are piloting carbon credit mechanisms for bio-based pigment production under national dual carbon goals. Weihai marine ingredient extractors are diversifying into food-grade colorant supply to leverage existing separation infrastructure.
Beijing-Tianjin-Hebei
State-owned dairy conglomerates in this corridor are mandating natural colorant specifications for premium product lines ahead of national deadlines. SAMR Beijing maintains accelerated safety reassessment timelines that force premature reformulation cycles among legacy synthetic dye users. Tianjin port infrastructure supports import-dependent supply chains for fermentation-derived pigments lacking domestic production scale.
China Food Colorants Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct capability vectors. The vendor base separates into fermentation technology leaders, plant-extraction specialists, and synthetic dye incumbents defending volume positions. Strategic archetypes include integrated emulsion technology providers, captive extraction operators, and microbial pigment platform developers. Competitive intensity is producing supplier panel consolidation among large processors and technical service capability investments among mid-tier players.
Among European-based fermentation specialists, Chr. Hansen Holding A/S and Koninklijke DSM N.V. occupy positions exemplifying microbial pigment platform strategies. Sensient Technologies Corporation represents the integrated emulsion technology archetype. Zhejiang Weile Biotechnology Co., Ltd. anchors the captive plant-extraction specialist tier within domestic supply chains. These named entities illustrate how competitive positioning stratifies across technology origin, geographic proximity to demand clusters, and regulatory compliance depth rather than scale alone.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| Koninklijke DSM N.V. |
| Sensient Technologies Corporation |
| D.D. Williamson & Co |
| Dohler Group |
| Givaudan |
| Zhejiang Weile Biotechnology Co., Ltd. |
| Shaanxi Fuheng Biotechnology Co., Ltd. |
| Guangzhou ZIO Chemical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap extraction specialists in Zhejiang and Shandong provinces anchor China's natural colorant supply base, their concentrated ownership structures enabling patient capital deployment into multi-year agricultural contracts that synthetic dye traders cannot match. This ownership pattern translates into pricing discipline through controlled feedstock release rather than spot-market liquidation, while GB 2760 tightening on artificial additives amplifies their bargaining power against reformulation-desperate processors.
Pricing Analysis
Margin tightening in fermentation-derived pigments reflects capital intensity barriers that plant-extraction incumbents exploit through premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates SAMR-certified natural colorants from uncertified imports and legacy synthetic dyes. Price differentiation hinges on batch consistency certification and technical service bundling. Cost-down pressure on standard-tier natural pigments accelerates because beverage manufacturers consolidate supplier panels. Food manufacturers with in-house formulation labs exhibit lowest price sensitivity; independent bakeries and restaurants show highest.
Supply Chain Analysis
Skilled fermentation technicians and plant-extraction chemists concentrate in Shanghai and Guangzhou coastal clusters, creating workforce scarcity that inland processors cannot readily overcome. Supply draws from China, India, and select European fermentation specialists for starter cultures and precision equipment. Raw material dependencies include purple sweet potato anthocyanin feedstock, microbial chassis strains for carotenoid production, and specialized emulsion stabilizers. Single-source vulnerability sits with fermentation-derived pigment platforms lacking geographic redundancy. Distribution runs through direct technical-service relationships between suppliers and large beverage processors, displacing traditional distributor intermediaries in coastal zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's food colorants market reads as supply-constrained: fermentation capacity expansion lags demand acceleration by 18-24 months, propping natural pigment premiums against synthetic alternatives facing regulatory phase-out.
For Market Incumbents: Hedge synthetic dye exposure by accelerating captive fermentation partnerships before GB 2760-2024 enforcement windows crystallize. Defend margin position through backward integration into purple sweet potato cultivation in Shandong and Hebei rather than spot-market feedstock procurement. Prioritize technical service team expansion into Sichuan-Chongqing processing belts where formulation expertise scarcity creates stickier customer relationships. For New Entrants and Emerging Players: Launch via technical-service-forward direct sales to mid-sized dairy processors in Pearl River Delta manufacturing zones. Target underpenetrated cheese and ice cream applications where fat-matrix compatibility challenges favor specialized emulsion capabilities over commodity liquid dyes. Anchor go-to-market positioning around SAMR pre-certification documentation support that accelerates customer reformulation timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation platform developers with validated microbial chassis strains and existing SAMR filing pipelines in Yangtze River Delta corridor. Long-term viability frames around 5-10 year regulatory harmonization trajectory between China's GB standards and evolving EU EFSA evaluations. Watch NMPA accelerated safety reassessment announcements as inflection signal for synthetic dye stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Builds supply security independent of agricultural harvest cycles that constrain plant-extraction competitors. |
| Backward Integration into Feedstock | Captures margin compression from purple sweet potato price volatility through Shandong cultivation control. |
| Technical Service Geographic Expansion | Establishes first-mover positioning in Sichuan-Chongqing where formulation expertise scarcity commands premium pricing. |
| SAMR Pre-Certification Investment | Accelerates customer reformulation timelines ahead of GB 2760-2024 compliance deadlines. |
| Emulsion Technology Partnership | Unlocks dairy fat-matrix applications through integrated dispersion systems that reduce downstream processing steps. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with fermentation technology directors, beverage formulation scientists, dairy procurement leads, and SAMR regulatory affairs specialists. China Food Additives Association production statistics, NMPA additive approval databases, and provincial MEE environmental compliance disclosures supplied volume and facility-level validation. Bottom-up facility capacity modeling triangulated against top-down end-use consumption estimates across beverage, dairy, confectionery, and bakery segments.
Granularity-level framing applied product-type, source-origin, application, and end-user dimensions at the provincial level for demand modeling, with technology-route segmentation distinguishing fermentation-derived from plant-extracted natural pigments. CAGRs derived from regression analysis of historical additive approval trajectories and processor reformulation investment cycles across the analysis window. Industry-specific forecast inputs included GB 2760 revision implementation timelines and dual carbon policy incentive structures affecting bio-based production economics.
Regulatory enforcement intensity variation, agricultural feedstock harvest volatility, and fermentation platform scale-up failure rates are the dominant revision risks to demand and pricing assumptions. Forecasts reflect documented assumptions on SAMR alignment pace with Codex frameworks and coastal manufacturing cluster concentration persistence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
France Food Colorants Market
Flavorings and Food Additives
United States Food Flavor Market
Flavorings and Food Additives
Natural Flavors and Fragrances Market
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
Beverage Flavoring Market
Flavorings and Food Additives
Coconut Syrup Market
Flavorings and Food Additives
Natural Acerola Cherry Extract Market
Flavorings and Food Additives
Citrus Aromatic Fractions for Mood Support Market
Flavorings and Food Additives
Orange Essential Oil Market
Flavorings and Food Additives
Europe Food Flavor Market
Flavorings and Food Additives
Farnesol Market
Flavorings and Food Additives
Natural Flavor Extract Market
Flavorings and Food Additives
Smoked Condensates Market
Flavorings and Food Additives
Food Flavors Market
Flavorings and Food Additives
Global Sterols Market
Flavorings and Food Additives
Chicory Extract Market