
 Global Sports Bottle Market | 2026-2036
Global Sports Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sports Bottle Market Outlook
End-use demand is shifting toward outdoor adventurers and casual fitness participants as post-pandemic recreational activity normalizes at higher baselines. Nike Inc. leverages its apparel-to-accessory ecosystem to bundle sports bottles with athletic wear collections. CamelBak Products LLC anchors its position through specialized hydration systems for cycling and trail running. Hydro Flask dominates the premium insulated segment with powder-coated stainless steel construction and color-driven brand identity.
A sports bottle is a portable liquid container engineered from polymers, metals, or glass, typically incorporating threaded closures, vacuum insulation layers, or integrated drinking valves to maintain beverage temperature and prevent leakage during physical exertion. Stainless steel variants with double-wall vacuum construction now lead value pools due to durability and thermal performance, while collapsible silicone designs compete on packability for ultralight backpacking. The distribution channel structure shows online platforms capturing margin-rich direct sales, though specialty shops sustain higher attachment rates for premium feature sets such as built-in straw mechanisms and eco-certified materials.
The US FDA governs food-contact substance safety under 21 CFR, while EU REACH restricts phthalate and bisphenol content in consumer plastics, compelling reformulation across Asian contract manufacturers. China's SAMR enforces GB standards for food-container migration limits, creating a three-jurisdiction compliance threshold for export-oriented suppliers. Stakeholders must monitor evolving state-level restrictions in California and pending EU packaging waste regulations that could mandate recycled content minimums.
Market Dynamics
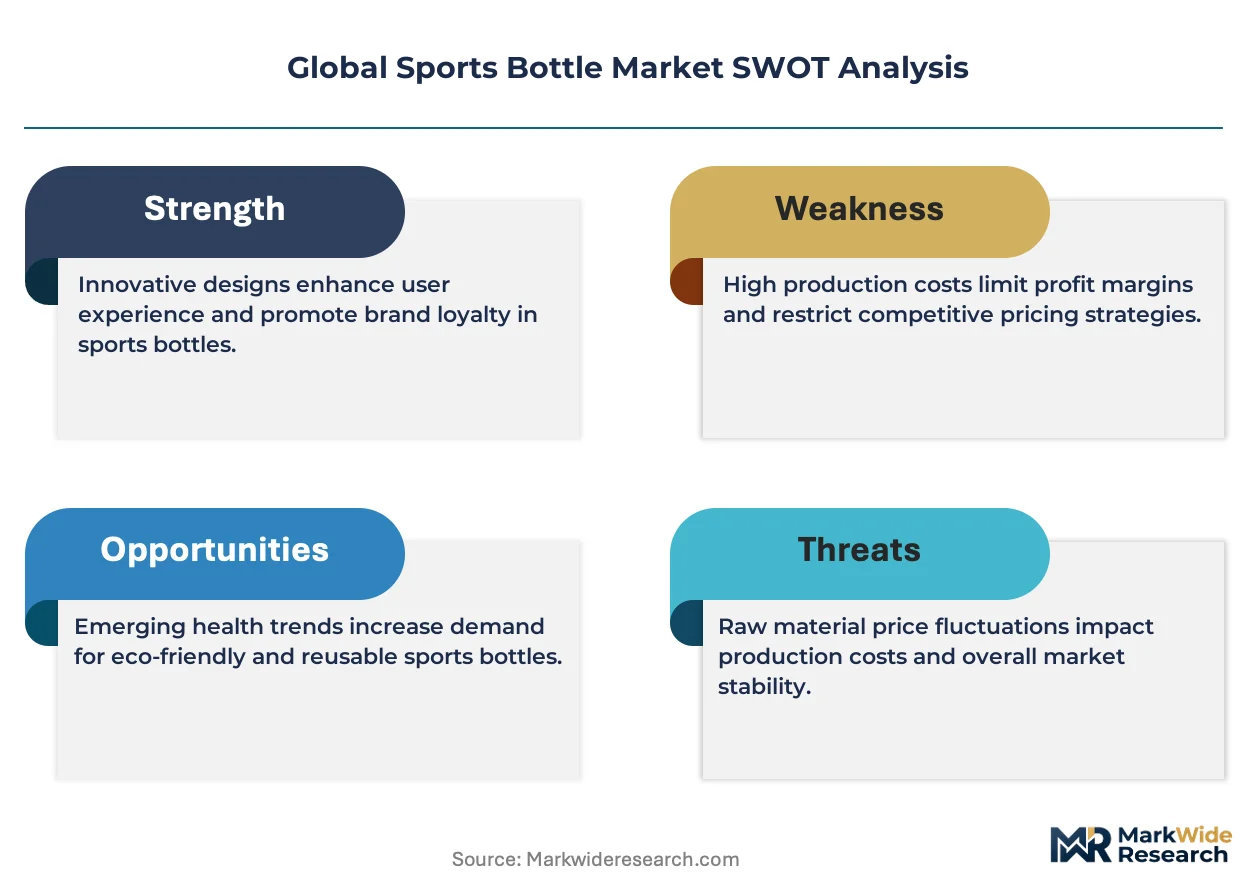
BPA-free material mandates from the US FDA and EU EFSA are forcing wholesale reformulation across Asian contract manufacturers, redirecting polymer supply chains toward Tritan copolyester and stainless steel alternatives.
Growth Catalysts
- EU REACH compliance:Restrictions on phthalate and bisphenol content in consumer plastics accelerate adoption of certified-safe alternatives among European distributors.
- Outdoor adventurers:Post-pandemic recreational activity baselines normalize at elevated levels, expanding addressable demand beyond professional athletics into casual fitness participation.
- Double-wall vacuum construction:Thermal performance advantages in stainless steel variants command premium shelf positioning in specialty retail channels.
Market Restraints
- Raw material volatility:Nickel and chromium price swings in stainless steel inputs compress margin predictability for vacuum-insulated product lines.
- Supply concentration risk:Zhejiang and Guangdong provinces dominate polymer molding capacity, creating single-region dependency for Western brand owners.
- Technical limitation:Silicone collapsible designs sacrifice thermal retention versus rigid-wall alternatives, constraining addressable use cases.
Strategic Opportunities
- Direct-to-consumer channels:Online platforms capture margin-rich sales previously intermediated by wholesale distributors.
- EU packaging waste regulations:Pending recycled content minimums create first-mover advantage for suppliers with closed-loop material flows.
- Smart hydration convergence:Integration of Bluetooth-enabled consumption tracking with vacuum-insulated vessels opens premium price tiers.
Industry Challenges
- Migration testing timelines:GB standard compliance for China's SAMR extends product development cycles for export-oriented suppliers.
- Polymer formulation IP:Patent thickets around Tritan copolyester alternatives complicate independent material sourcing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sports Bottle Market |
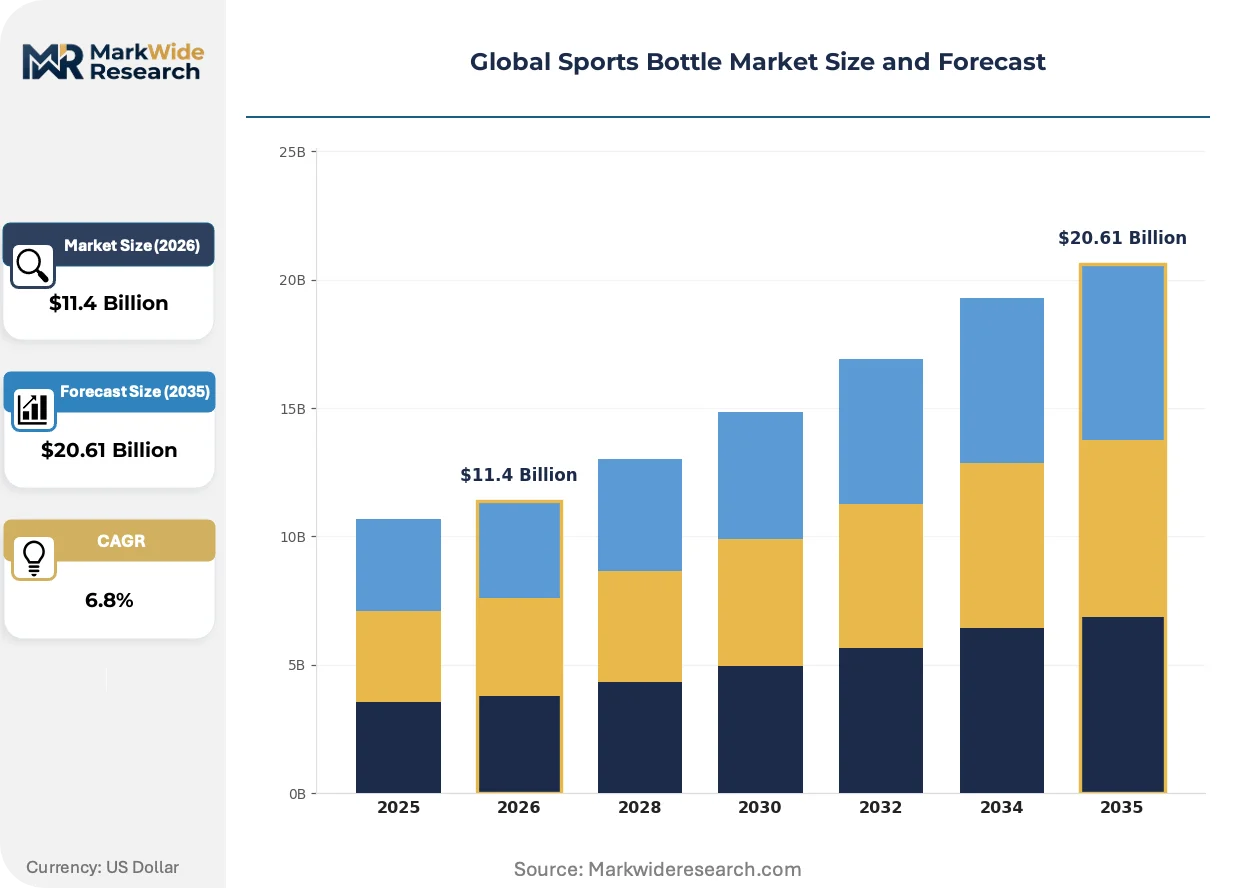
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Stainless Steel, Glass, Collapsible Customer Type: Athletes, Fitness Enthusiasts, Casual Users, Outdoor Adventurers Distribution Channel: Retail Stores, Online Platforms, Supermarkets, Specialty Shops Feature: Insulated, Built-in Straw, Eco-friendly, BPA-free |
| Companies Covered | Nike Inc., Adidas AG, CamelBak Products LLC, Thermos LLC, Yeti Holdings Inc., Hydro Flask, Klean Kanteen, Contigo, Zojirushi Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sports Bottle Market Strategic Shifts
Material science advances and regulatory tightening are compressing product development cycles while fragmenting buyer expectations across thermal performance, packability, and connected functionality.
Modular lid systems with interchangeable straw, chug, and sip configurations are modularizing how manufacturers manage SKU proliferation. Ultralight backpacking segments adopt these platforms fastest, reducing inventory carrying costs for specialty retailers. The approach collapses what previously required three distinct bottle designs into one core vessel with attachment ecosystems.
REACH restrictions on food-contact substances are compelling reformulation of colorants and additives across European-bound production lines. Asian contract manufacturers face dual-compliance overhead serving both GB-standard domestic markets and EU-export requirements. Stainless steel suppliers with pre-certified material streams capture displaced polymer volume in German and French distribution.
Certification-driven purchasing now dominates institutional procurement for university athletic programs and corporate wellness initiatives. Buyers require third-party validation of BPA-free claims, displacing self-attested manufacturer declarations. California and New York state-level restrictions amplify this pattern in North American education and government verticals.
Global Sports Bottle Market Segmentation
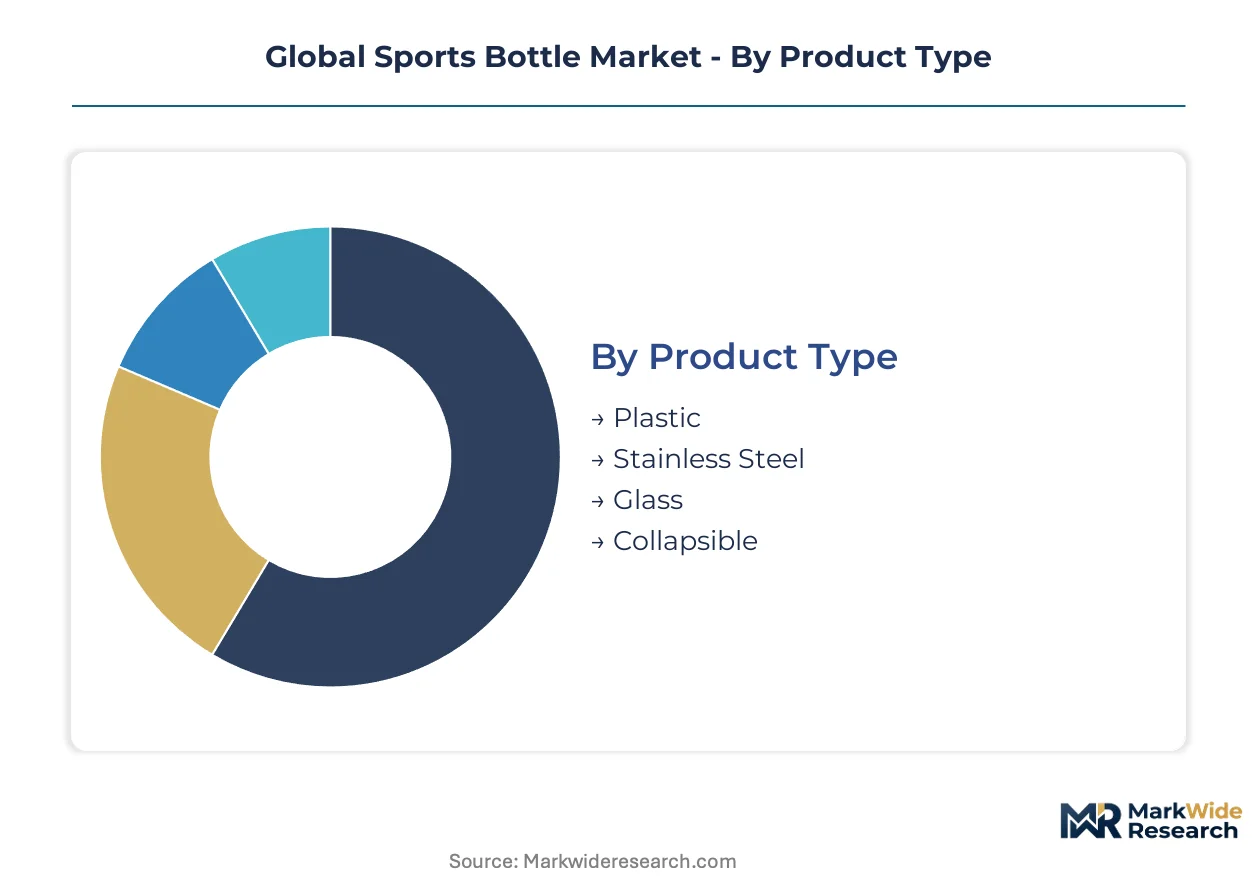
Product differentiation in sports bottles follows distinct upgrade cycles driven by material durability concerns, thermal performance expectations, and regulatory compliance thresholds. Segmentation reveals how replacement demand concentrates in premium material tiers while entry-level volumes sustain mass-market channels.
Product Type:
Replacement cycles accelerate as BPA-free mandates and thermal performance standards render older polymer designs obsolete.
- Plastic:Polypropylene and Tritan copolyester formulations dominate entry-level positioning due to moldability and cost efficiency. Demand concentrates in United States mass retail and Asian convenience channels where price sensitivity outweighs durability concerns; FDA compliance costs compress margin pools for non-specialized suppliers.
- Stainless Steel:Double-wall vacuum construction delivers 12-24 hour temperature retention through copper-lined inner chambers. German and French specialty retailers command premium shelf positioning; EU REACH certification requirements displace unverified Asian suppliers from European distribution.
- Glass:Borosilicate and soda-lime variants serve yoga studios and wellness programs prioritizing taste neutrality over impact resistance.
- Collapsible:Food-grade silicone walls fold to pocket-size for ultralight backpacking segments in Colorado and Pacific Northwest trail systems.
Volume placements concentrate in Plastic; the faster expansion belongs to Stainless Steel.
Customer Type:
Application intensity determines price tolerance and feature requirements across usage scenarios.
- Athletes:Team sports programs and individual competitors require rapid-access valve mechanisms and volume markings for hydration protocol compliance. United States university athletic departments drive institutional procurement with certification mandates; California state restrictions on food-contact substances amplify third-party validation requirements.
- Outdoor Adventurers:Trail runners and cyclists prioritize packability and one-handed operation during technical terrain traversal. Demand clusters in Germany's Black Forest and Switzerland's Alpine regions where weather exposure necessitates thermal retention; collapsible designs compete on gram-count optimization.
- Fitness Enthusiasts:Gym members and studio participants balance aesthetics with functional straw mechanisms for treadmill use.
- Casual Users:Workplace and commuter segments emphasize color customization and leak-proof guarantees over performance specifications.
Procurement volume clusters with Athletes; Outdoor Adventurers are climbing the fastest.
Distribution Channel:
Channel selection determines margin capture and brand control intensity for manufacturers.
- Online Platforms:Direct-to-consumer storefronts bypass wholesale markups while enabling subscription replenishment and customization interfaces. United States and Chinese e-commerce ecosystems concentrate order flow; logistics integration with regional fulfillment networks determines delivery speed competitiveness.
- Specialty Shops:Running stores and outdoor retailers sustain higher attachment rates for premium feature sets through staff consultation and hands-on testing. German and Austrian alpine equipment chains maintain curated assortments; technical staff training on vacuum insulation properties drives conversion.
- Retail Stores:Big-box sporting goods chains provide national reach with standardized planogram placement.
- Supermarkets:Grocery channels capture impulse replacement purchases through checkout-adjacent placement.
Unit economics favor Online Platforms for margin; Specialty Shops retain the steepest expansion trajectory in premium tiers.
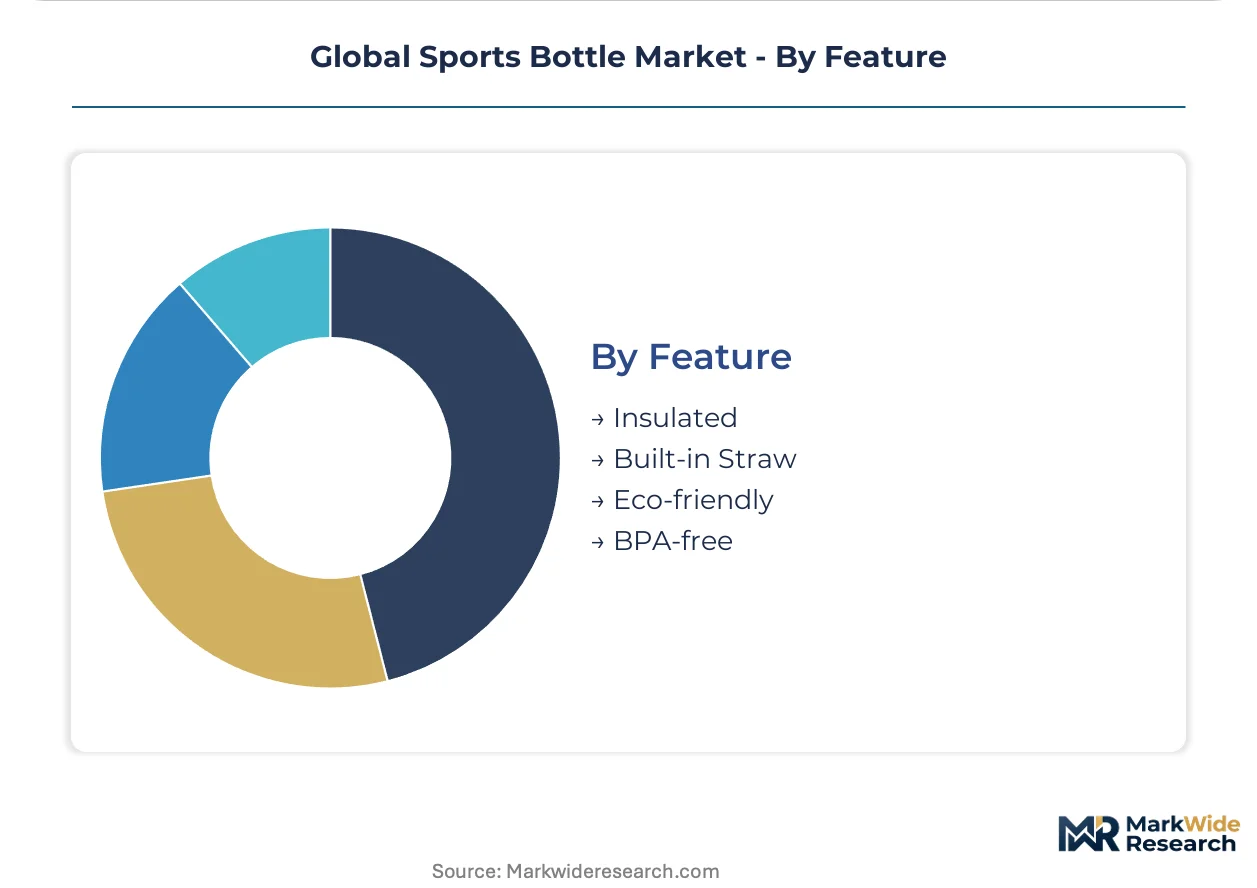
Feature:
Certification and performance attributes increasingly determine shelf access and procurement eligibility.
- BPA-free:Regulatory mandates from FDA and EFSA have normalized this attribute to baseline expectation rather than differentiation. United States and EU-bound production lines require reformulation verification; Asian contract manufacturers face dual-compliance overhead serving domestic GB-standard markets alongside export requirements.
- Insulated:Vacuum-layer construction commands price premiums through demonstrable thermal performance in ambient temperature variation. German outdoor retailers and United States specialty coffee chains drive specification escalation; powder-coated finishes enable color-driven brand identity.
- Eco-friendly:Recycled content claims and end-of-life takeback programs address corporate sustainability procurement criteria.
- Built-in Straw:Integrated sip mechanisms reduce spill risk during vehicle and equipment operation.
BPA-free claims dominate unit placements; Insulated features are gaining share fastest in revenue terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Zhejiang and Guangdong provinces concentrate polymer molding capacity for export-oriented sports bottle manufacturing, while premium insulated demand clusters in German alpine retail and United States specialty channels.
United States
University athletic programs and corporate wellness initiatives drive institutional procurement with third-party BPA-free certification mandates. FDA food-contact substance regulations under 21 CFR govern import compliance for Asian contract manufacturers. California and Colorado anchor demand clusters, with Denver-based outdoor retailers sustaining premium attachment rates for vacuum-insulated vessels.
Germany
Black Forest trail runners and Alpine cyclists prioritize thermal retention and gram-count optimization in technical terrain applications. EU REACH restrictions on phthalates and bisphenols accelerate adoption of certified-safe stainless steel alternatives. Bavarian outdoor equipment chains maintain curated assortments with staff consultation driving conversion on powder-coated finishes.
China
SAMR-enforced GB standards for food-container migration limits create dual-compliance overhead for export-oriented suppliers serving both domestic and EU markets. Yangtze River Delta molding clusters in Zhejiang province dominate polymer capacity, while Pearl River Delta fabricators pivot toward Tritan copolyester formulations. Shanghai and Shenzhen direct-to-consumer platforms capture margin-rich online sales.
Japan
METI industrial standards and JIS certification requirements sustain premium positioning for domestic stainless steel fabricators. Kanto region metropolitan consumers emphasize design aesthetics alongside functional straw mechanisms for commuter use. Osaka-based specialty retailers curate insulated assortments targeting studio fitness and workplace hydration segments.
Australia
TGA-aligned food-contact safety expectations and arid climate conditions amplify demand for extended thermal retention in outdoor recreation. Victoria and New South Wales hiking communities prioritize collapsible silicone designs for ultralight backpacking in Blue Mountains and Grampians trail systems. Sydney and Melbourne e-commerce platforms aggregate direct sales for premium insulated brands.
Global Sports Bottle Market Competitive Environment
Top-tier vendors anchor premium insulated positioning, while mid-scale polymer specialists and direct-to-consumer entrants populate lower tiers. The vendor base stratifies across three concentration levels: established sporting goods conglomerates with apparel-to-accessory ecosystems, specialized hydration system fabricators, and insulated vessel pure-plays with color-driven brand identity. Strategic archetypes include vertical integration into polymer supply chains, backward integration toward captive stainless steel sourcing, and technology licensing for smart hydration convergence. Geographic expansion into EU distribution and portfolio diversification across material substrates represent dominant competitive vectors.
Within the apparel-ecosystem tier, Nike Inc. and Adidas AG exemplify conglomerate strategies leveraging athletic wear collections to bundle accessory sales. Among specialized hydration fabricators, CamelBak Products LLC occupies a position representing technical cycling and trail running applications. On the premium insulated vector, Hydro Flask and Yeti Holdings Inc. anchor archetypes built around powder-coated stainless steel construction and color differentiation. Thermos LLC represents legacy thermal retention expertise, while Klean Kanteen exemplifies eco-certification positioning. Zojirushi Corp. and Contigo sit within metropolitan commuter-focused design specializations.
| Leading Market Players |
|---|
| Nike Inc. |
| Adidas AG |
| CamelBak Products LLC |
| Thermos LLC |
| Yeti Holdings Inc. |
| Hydro Flask |
| Klean Kanteen |
| Contigo |
| Zojirushi Corp. |
| Others |
Value Chain & Pricing Dynamics
BPA-free certification mandates from the FDA and EFSA are forcing contract manufacturers to reformulate polymer inputs and absorb migration testing costs, compressing margin pools for non-specialized suppliers while rewarding pre-certified stainless steel fabricators with pricing power in German and United States specialty channels.
Pricing Analysis
Short lead-time premiums now dominate procurement negotiations as university athletic programs and corporate wellness buyers demand rapid fulfillment of certified-safe inventory. Three-tier pricing structure across premium, standard, and economy levels separates powder-coated vacuum-insulated vessels from single-wall stainless steel and basic polypropylene alternatives. Price differentiation hinges on thermal performance certification and EU REACH compliance tier. Cost compression in entry-level polymer tiers is intensifying because Asian contract manufacturers face dual-compliance overhead serving both GB-standard domestic markets and export requirements. Casual users in United States mass retail exhibit highest price sensitivity; outdoor adventurers in Alpine regions demonstrate lowest sensitivity due to performance prioritization.
Supply Chain Analysis
Direct-to-brand channels handle hyperscale demand from Nike and Adidas accessory ecosystems, while specialty outdoor retailers sustain curated assortment models for premium insulated vendors. Manufacturing gravity centers on Zhejiang and Guangdong provinces for polymer molding, with Japanese and German fabricators dominating vacuum-insulated stainless steel assembly. Raw material flows draw from nickel and chromium suppliers for double-wall construction, Tritan copolyester feedstock for BPA-free polymer alternatives, and food-grade silicone for collapsible designs. Single-region dependency in Yangtze River Delta molding clusters creates vulnerability to regional logistics disruption or regulatory enforcement actions. Distribution runs through direct-to-consumer platforms capturing margin-rich sales, specialty shops enabling hands-on testing, and mass retail for replacement volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance cost escalation is accelerating consolidation as smaller polymer specialists lack capital to fund dual-jurisdiction certification and migration testing infrastructure.
For Market Incumbents: To counter margin erosion from raw material volatility in nickel and chromium inputs, deepen backward integration into captive stainless steel sourcing or secure long-term offtake agreements with pre-certified Tritan copolyester suppliers. Channel control through exclusive specialty retail partnerships in Germany and Colorado outdoor markets preserves premium positioning against direct-to-consumer entrants. For New Entrants and Emerging Players: Begin with modular lid system platforms serving ultralight backpacking segments in Pacific Northwest and Australian trail systems, where SKU proliferation pain points create white-space opportunity for attachment-ecosystem vendors. Target institutional procurement channels in California and New York state university systems with third-party certified BPA-free positioning that displaces self-attested manufacturer declarations. For Investors and Strategic Acquirers: The window for entry favors insulated vessel pure-plays with established powder-coated brand identity and pre-certified material streams serving EU distribution. Over the medium-term horizon, acquisition targets should demonstrate closed-loop recycling capabilities aligned with pending packaging waste regulations. Monitor state-level restriction enactment velocity in California and New York as inflection indicator for certification-driven purchasing acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Sourcing | Captive nickel and chromium supply secures margin predictability against commodity price swings in vacuum-insulated tiers. |
| Direct-to-Consumer Platform Launch | United States and Chinese e-commerce ecosystems enable subscription replenishment and customization interfaces bypassing wholesale markups. |
| EU REACH Pre-Certification Investment | Third-party validation of food-contact substance safety displaces unverified Asian suppliers from German and French distribution. |
| Modular Lid System Development | Attachment ecosystems collapse three distinct bottle designs into one core vessel, reducing inventory carrying costs for specialty retailers. |
| Closed-Loop Recycling Program | End-of-life takeback capabilities address corporate sustainability procurement criteria and pending EU recycled content minimums. |
Study Parameters
Document review covered customs and trade databases, FDA 21 CFR filings, EU REACH substance restrictions, and SAMR GB standards documentation, complemented by interviews with brand managers at sporting goods conglomerates, category buyers at specialty outdoor retailers, procurement leads at university athletic departments, and technical directors at Asian contract manufacturers. Secondary validation drew from SEC 10-K accessory segment disclosures, Nielsen retail audit data, and ECHA substance restriction updates. Bottom-up demand modeling across end-use segments triangulated against top-down market sizing from production capacity and import-export flows.
Segment-level projections across material substrate, customer archetype, distribution channel, and thermal performance tier fed into analytical framework outputs over the projection horizon. CAGRs were derived from replacement cycle acceleration patterns, regulatory compliance cost trajectories, and channel shift elasticity parameters. Forecast inputs incorporated BPA-free mandate enforcement timelines, nickel price volatility indices, and e-commerce penetration rates in United States and Chinese markets.
Underlying measurement precision varies by segment; stainless steel insulated and direct-to-consumer channel projections carry tighter precision than collapsible silicone and supermarket channel estimates due to data availability. Forecasts reflect assumptions around regulatory enforcement consistency, raw material price stabilization, and consumer willingness-to-pay for certified-safe alternatives. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Infrared Sauna Heaters Market
Household Items
Ironing Boards Market
Household Items
Commercial Locker Market
Household Items
Indoor Humidifier Market
Household Items
Permanent Marker Market
Household Items
Dishwasher Tablets Market
Household Items
Enameled Cookware Market
Household Items
Europe Coin-Operated Laundries Market
Household Items
Disposable Cutlery Market
Household Items
Book Light Market
Household Items
UV Sanitizer Travel Wand Market
Household Items
Smart Pool Skimmer Market
Household Items
Canada Digital Showers Market
Household Items
Copper Water Bottle Market
Household Items
Electric Brooms Market
Household Items
Toilet Care Wipes Market