
 Europe Pilates & Yoga Studios Market | 2026-2036
Europe Pilates & Yoga Studios Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pilates & Yoga Studios Market Insights
France is reconfiguring its urban wellness infrastructure through dedicated Pilates and yoga studio clusters in Paris, Lyon, and Marseille. Core Pilates leverages instructor certification depth to sustain premium positioning in London and Manchester. Sandstone Yoga & Pilates anchors its network across English mid-sized cities with localized class scheduling. Flex Studio competes through boutique format control in Dublin and Edinburgh.
Pilates and yoga studios constitute dedicated movement facilities offering mat-based and apparatus-assisted exercise systems, typically operating reformer machines, Cadillac tables, and suspension equipment for neuromuscular conditioning and joint stability. These studios serve commercial purposes by delivering structured group instruction, personal training protocols, and progressive skill certification to consumer and corporate buyer segments. Independent studios occupy the largest service footprint across European capitals, while corporate wellness classes generate the fastest enrollment velocity as employers integrate movement breaks into hybrid work policies. Franchise studios concentrate margin pools through standardized instructor training and centralized booking technology.
France's national health regulator ANSM monitors complementary medicine advertising claims affecting studio marketing, while the EU Green Deal building renovation requirements shape studio location decisions through energy performance standards. GDPR compliance governs biometric wearable data collection from heart-rate tracking during sessions. Stakeholders must weigh instructor labor availability against automated class delivery platforms as the sector scales.
Market Dynamics
The EU Green Deal's building renovation mandates are forcing studio operators across Germany, France, and the United Kingdom to reconfigure physical infrastructure, compressing capital deployment timelines and reshaping location economics for premium mat-based and apparatus-assisted facilities.
Growth Catalysts
- Corporate Wellness Integration:White-collar employers in London, Paris, and Berlin are subsidizing studio memberships as hybrid work policies normalize movement breaks during business hours.
- GDPR-Compliant Biometric Tracking:Wearable heart-rate monitors and motion sensors are generating granular performance data that studios leverage for personalized programming and retention analytics.
- Metropolitan Clustering:Premium studio development concentrates in Paris, Lyon, and Marseille where disposable income density supports reformer machine and Cadillac table investments.
Market Restraints
- Certified Instructor Scarcity:Comprehensive Pilates apparatus training requires 450+ hour certification programs, constraining labor supply expansion in Manchester and Edinburgh.
- Energy Performance Compliance:EU Green Deal renovation standards impose thermal efficiency thresholds that retrofitting historic studio buildings in Rome and Barcelona cannot economically meet.
- Subscription Fatigue:Digital fitness platforms including Peloton and Apple Fitness+ are capturing discretionary wellness spending from price-sensitive consumer segments in Dublin and Copenhagen.
Strategic Opportunities
- Mid-Sized City Penetration:Leeds, Bristol, and Toulouse exhibit underserved demand for boutique reformer studios with localized class scheduling and community anchoring.
- CSRD Reporting Integration:Corporate wellness contracts are expanding as EU sustainability disclosure rules incentivize employers to document employee wellbeing investments.
- Hybrid Delivery Convergence:Studios are blending in-person apparatus instruction with asynchronous digital content to capture remote workers in Birmingham and Glasgow.
Industry Challenges
- Reformer Machine Maintenance:Spring replacement cycles and frame calibration require specialized technical expertise that studio operators struggle to source outside London and Paris.
- ANSM Marketing Scrutiny:France's national health regulator monitors advertising claims around therapeutic benefits, forcing studios to reword promotional materials and staff training protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pilates & Yoga Studios Market |
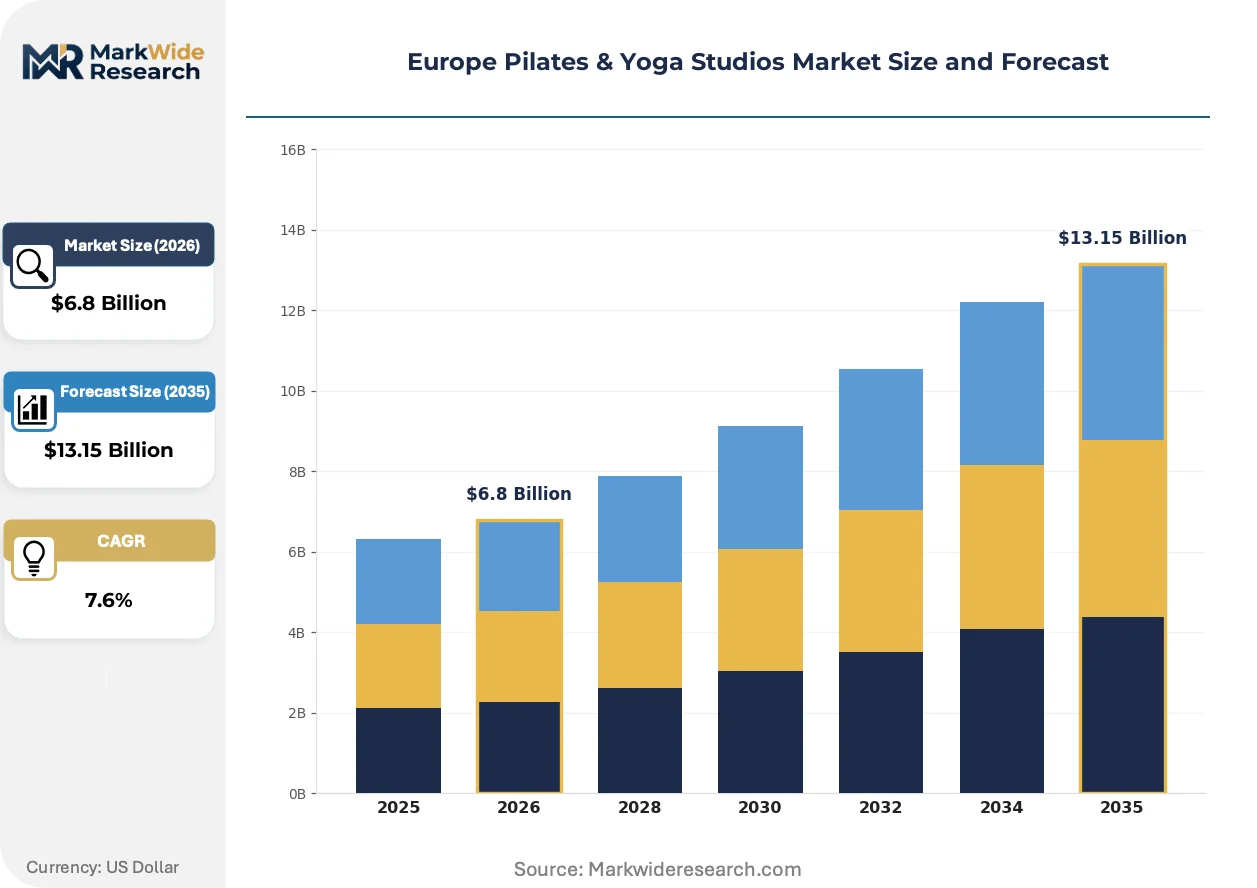
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Studio Type: Independent Studios, Franchise Studios, Wellness Centers, Community Centers Class Type: Beginner Classes, Advanced Classes, Corporate Wellness, Private Sessions Customer Demographic: Adults, Seniors, Youth, Couples Service Offering: Group Classes, Personal Training, Workshops, Online Sessions |
| Companies Covered | Body & Soul Yoga Club, Core Pilates, Sandstone Yoga & Pilates, Pilates Plus, M Pilates+Yoga, Cheltenham Pilates & Yoga, Fitness Unlimited, Flex Studio, Hummingbird Pilates & Yoga, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pilates & Yoga Studios Market Trends and Innovations
Technology convergence, regulatory pressure on physical infrastructure, and shifting employer-employee wellness relationships are compressing traditional studio operating models and opening new service architectures across European metropolitan markets.
AI-powered form correction cameras are collapsing the economics of personalized instruction by delivering real-time posture feedback without dedicated instructor attention. Mid-market studios in Amsterdam and Vienna are deploying computer vision systems to maintain class sizes above twelve participants while preserving quality perception. This compression is enabling price points that undercut premium boutique competitors without sacrificing perceived customization depth.
The EU Green Deal's building performance standards are mandating thermal efficiency upgrades and renewable energy integration for commercial lease renewals. Studio operators in Brussels and Stockholm face capital-intensive HVAC and insulation investments that threaten independent single-location viability. Franchise networks with centralized procurement are absorbing these compliance costs through economies of scale unavailable to owner-operators.
Employer-sponsored wellness stipends are displacing direct consumer payment as the dominant membership acquisition channel. Human resources departments in Frankfurt and Zurich are negotiating corporate rates that bundle studio access with mental health and nutrition services. This procurement consolidation concentrates buyer power with benefits platforms and erodes studios' direct consumer relationships and pricing autonomy.
Europe Pilates & Yoga Studios Market Segmentation
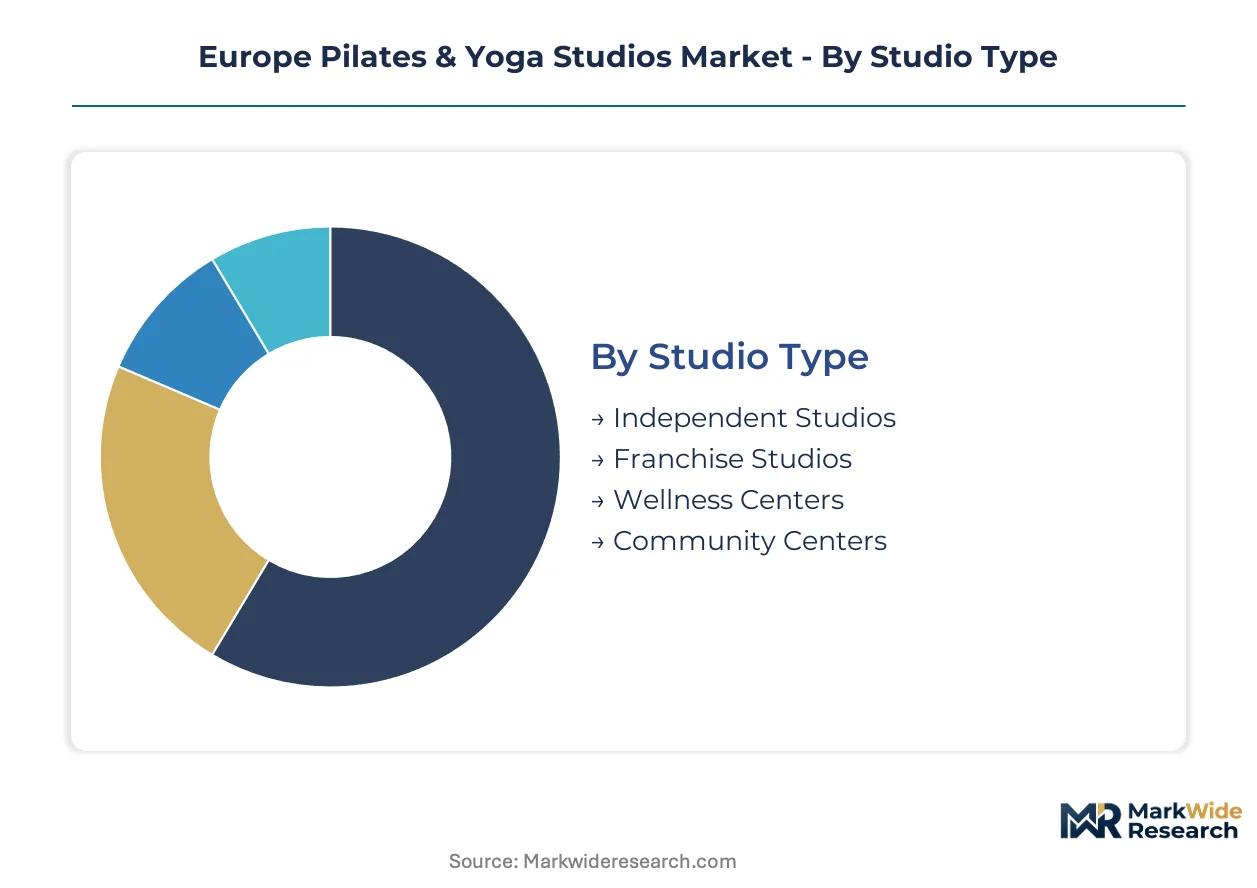
Studio operators across Germany, France, and the United Kingdom segment their offerings to match divergent capital intensity, instructor labor models, and customer acquisition economics. Each segmentation dimension reveals distinct margin structures and regulatory exposure that shape investment decisions.
Studio Type:
Cost tier differentiation separates owner-operated facilities from capital-backed networks with centralized procurement and compliance systems.
- Independent Studios:Single-location owner-operators dominate Paris, Berlin, and Amsterdam with bespoke class scheduling and neighborhood anchoring. These studios absorb EU Green Deal retrofit costs directly, compressing cash reserves in historic building stock across Rome and Barcelona.
- Franchise Studios:Standardized instructor training and booking technology platforms concentrate margin pools through volume purchasing of reformer machines and centralized marketing compliance. Networks like those operating across English mid-sized cities leverage economies of scale to absorb building efficiency mandates.
- Wellness Centers:Integrated facilities combining Pilates with spa and nutrition services command premium positioning in Zurich and Geneva.
- Community Centers:Municipal subsidized spaces in Lyon and Manchester serve price-sensitive demand with limited apparatus investment.
Independent studios hold installed capacity. Franchise studios are rotating up the share rankings.
Class Type:
Application-based segmentation tracks how instruction intensity maps to pricing power and retention economics.
- Corporate Wellness:Employer-subsidized movement breaks during hybrid work hours generate the fastest enrollment velocity across London, Frankfurt, and Dublin. Human resources departments negotiate bundled rates that displace direct consumer payment as the dominant acquisition channel.
- Private Sessions:One-to-one apparatus instruction with Cadillac tables and reformer machines sustains premium pricing in metropolitan France where disposable income density supports personalized programming.
- Beginner Classes:Mat-based fundamentals attract trial membership in Leeds and Bristol with lower instructor certification requirements.
- Advanced Classes:Progressive skill certification protocols retain committed practitioners in Edinburgh and Copenhagen.
Corporate wellness commands contract volume. Private sessions are climbing the fastest in revenue per member.
Customer Demographic:
Volume concentration varies by age cohort and household structure, shaping class timing and equipment specifications.
- Adults:White-collar professionals aged 25-45 constitute the core membership base across all major European capitals, driving evening and early-morning class demand.
- Seniors:Joint stability and neuromuscular conditioning programs expand in Stuttgart and Vienna with modified apparatus protocols.
- Youth:School-age programming remains underdeveloped outside London and Paris due to liability constraints and instructor specialization gaps.
- Couples:Partner session packages generate ancillary revenue in romantic tourism corridors of Barcelona and Lisbon.
Adults sustain baseline utilization. Seniors are gaining share fastest among age-defined segments.
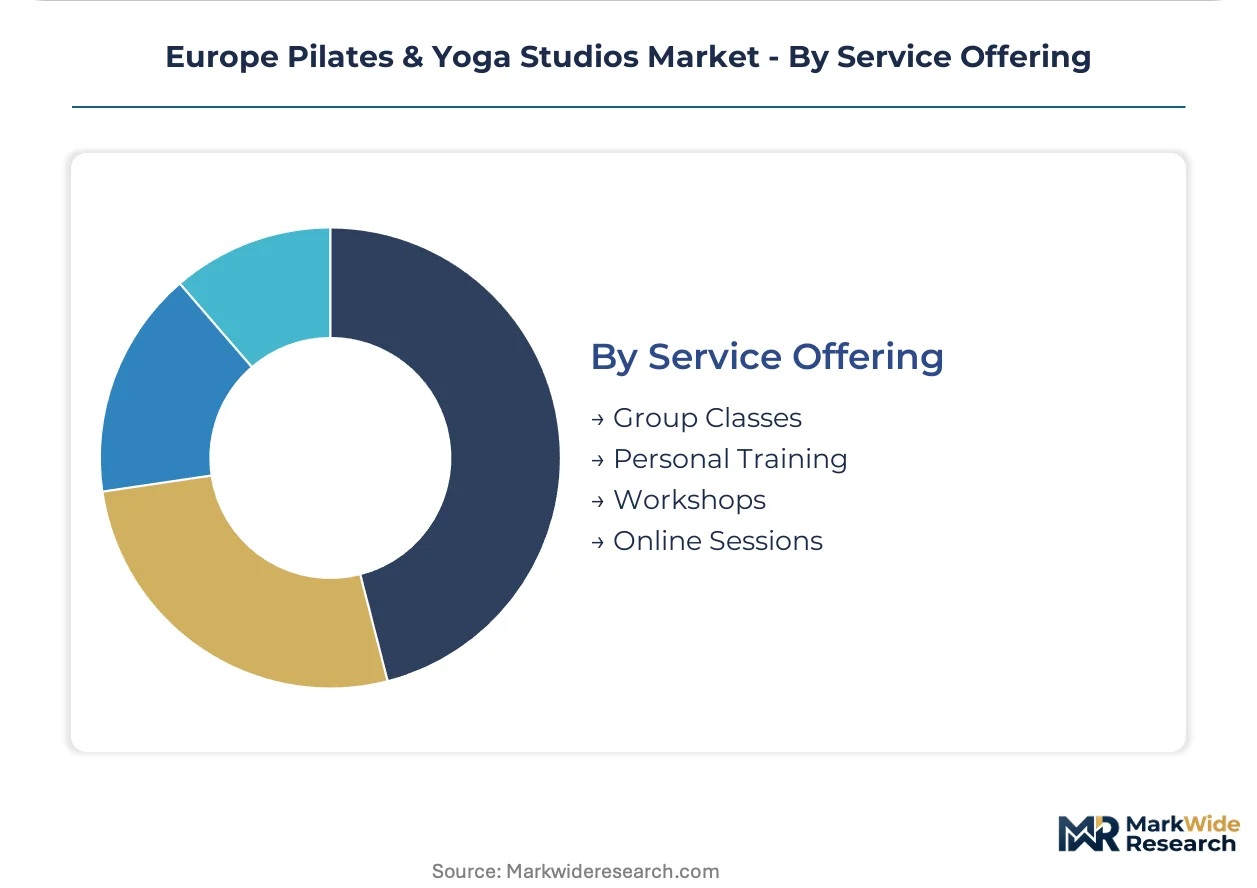
Service Offering:
Margin structure diverges between synchronous in-person delivery and asynchronous digital content with diverging capital and labor intensities.
- Group Classes:Twelve-participant reformer sessions with AI-powered form correction cameras enable mid-market price positioning in Amsterdam and Vienna without dedicated instructor attention per participant.
- Personal Training:Individual protocol design with biometric wearable integration commands premium fees in Dublin and Edinburgh where GDPR-compliant heart-rate tracking supports retention analytics.
- Workshops:Intensive certification weekends concentrate revenue in single transactions across Manchester and Glasgow.
- Online Sessions:Asynchronous content captures remote workers in Birmingham with minimal marginal cost per additional viewer.
Group classes hold throughput capacity. Online sessions are expanding most quickly in member acquisition economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANSM monitors complementary medicine advertising claims affecting studio marketing across France, while the EU Green Deal building renovation requirements shape studio location decisions through energy performance standards. GDPR compliance governs biometric wearable data collection from heart-rate tracking during sessions across the region.
France
Paris and Lyon anchor premium studio development with dedicated Pilates and yoga studio clusters. ANSM advertising scrutiny forces studios to reword promotional materials around therapeutic claims. Marseille emerges as a secondary concentration point for boutique reformer investments.
Germany
Corporate wellness programs in Berlin and Frankfurt expand studio memberships among white-collar professionals. KBA and federal building codes intersect with EU Green Deal mandates for thermal efficiency upgrades. Stuttgart develops specialized joint stability programming for senior demographics.
United Kingdom
London and Manchester sustain premium positioning through instructor certification depth. GDPR biometric compliance shapes wearable heart-rate tracking deployment. Leeds and Bristol exhibit underserved demand for boutique reformer studios with localized scheduling.
Netherlands
Amsterdam deploys AI-powered form correction cameras to maintain class sizes above twelve participants. EU Green Deal HVAC investments challenge independent single-location viability. Mid-market studios compress economics through computer vision systems.
Ireland
Dublin hosts Flex Studio's boutique format control with GDPR-compliant retention analytics. Corporate wellness stipends displace direct consumer payment as the dominant acquisition channel. Subscription fatigue from digital fitness platforms pressures price-sensitive segments.
Europe Pilates & Yoga Studios Market Competitive Landscape
Boutique specialists and franchise networks split the market between bespoke neighborhood anchoring and standardized scalability. Independent owner-operators dominate Paris, Berlin, and Amsterdam with personalized class scheduling. Franchise studios concentrate margin pools through volume purchasing of reformer machines and centralized booking technology. Competitive moves center on corporate wellness contract consolidation and EU Green Deal compliance cost absorption through scale.
Within the certification-depth tier, Core Pilates occupies a position exemplifying premium instructor training investment. Sandstone Yoga & Pilates anchors English mid-sized city penetration with localized community scheduling. Flex Studio represents boutique format control in secondary metropolitan markets.
| Leading Market Players |
|---|
| Body & Soul Yoga Club |
| Core Pilates |
| Sandstone Yoga & Pilates |
| Pilates Plus |
| M Pilates+Yoga |
| Cheltenham Pilates & Yoga |
| Fitness Unlimited |
| Flex Studio |
| Hummingbird Pilates & Yoga |
| Others |
Pricing and Supply Chain Analysis
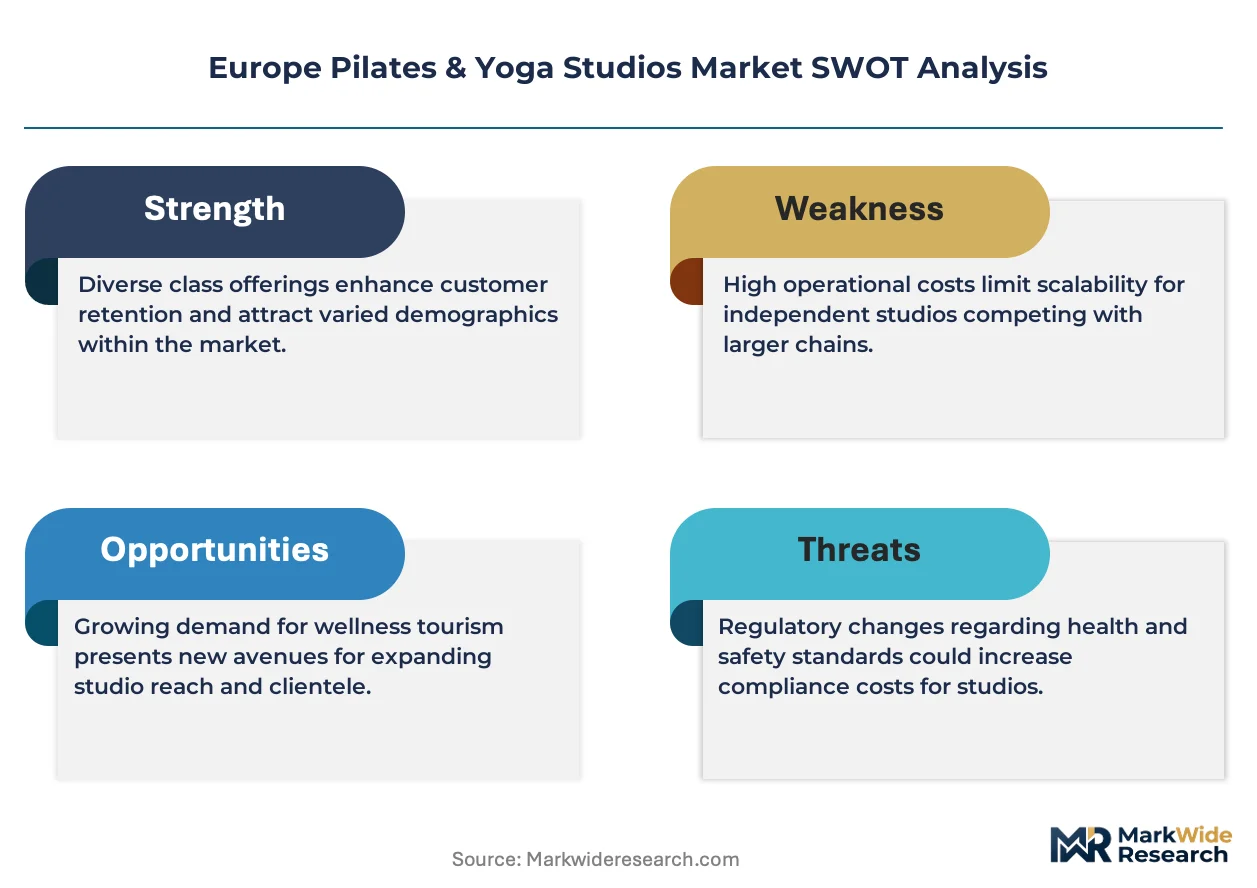
London and Manchester instructor certification clusters concentrate premium pricing power through 450-hour apparatus training depth that smaller markets cannot replicate. This supply-side credential scarcity feeds directly into membership rate structures, with metropolitan studios commanding multiples over mid-sized city competitors while franchise networks compress price points through standardized labor models.
Pricing Analysis
Paris-London price spreads of roughly forty percent separate premium boutique positioning from mid-market franchise penetration. Three-tier pricing structure across premium, standard, and economy levels segments by instructor certification grade and apparatus density per square meter. Pricing pressure stems from digital fitness platform subscription fatigue capturing discretionary wellness spending in Dublin and Copenhagen. Corporate wellness buyers exhibit lowest price sensitivity through employer-subsidized contracts, while independent trial members in Leeds and Bristol show highest elasticity.
Supply Chain Analysis
Tariff exposure between German engineering suppliers and UK studio operators dominates equipment procurement risk for reformer machines and Cadillac tables. Manufacturing concentrates in Germany, Italy, and China for specialized spring components, upholstery materials, and precision metal framing. Single-source vulnerability sits with spring replacement cycles requiring technical expertise unavailable outside London and Paris service networks. Distribution runs through franchise procurement consortia and independent studio direct import channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where recurring corporate wellness contracts expand faster than hardware-dependent membership models. Instructor certification programs and biometric data analytics layers generate subscription-like revenue streams with superior retention economics.
For Market Incumbents: Entrench corporate wellness relationships through CSRD reporting integration that documents employee wellbeing investments for sustainability disclosure compliance. Absorb EU Green Deal retrofit costs through centralized procurement scale unavailable to owner-operators, while defending against AI-powered form correction cameras by emphasizing hands-on apparatus safety protocols that automated systems cannot replicate.
For New Entrants and Emerging Players: Establish a beachhead in Leeds, Bristol, and Toulouse where underserved boutique reformer demand meets lower real estate entry costs than saturated Paris and London clusters. Target senior demographic programming in Stuttgart and Vienna with modified joint stability protocols, leveraging the fastest-growing age segment while incumbent studios remain youth-focused.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because franchise networks with standardized booking technology and instructor training pipelines will absorb independent studios facing EU Green Deal compliance cost shocks. Target mid-sized city operators with localized community anchoring but without capital reserves for energy performance upgrades. Watch corporate wellness contract renewal rates as the inflection signal for platform shift from direct consumer to employer-procured membership models.
| Strategic Initiative | Industry Significance |
|---|---|
| Corporate Wellness Contract Consolidation | Employer procurement platforms in Frankfurt and Zurich bundle studio access with mental health services, concentrating buyer power. |
| AI-Powered Form Correction Deployment | Computer vision systems in Amsterdam and Vienna enable twelve-participant reformer classes without per-staffing cost escalation. |
| EU Green Deal Compliance Investment | Thermal efficiency upgrades and renewable HVAC integration secure lease renewals in Brussels and Stockholm commercial properties. |
| Instructor Certification Pipeline Expansion | 450-hour apparatus training programs address labor scarcity constraining Manchester and Edinburgh studio growth. |
| GDPR-Compliant Biometric Integration | Wearable heart-rate tracking in Dublin and Edinburgh generates retention analytics while satisfying data protection mandates. |
Research Methodology
Operator-level perspectives from studio owners, instructor certification program directors, corporate HR benefits managers, and reformer equipment distributors anchored the qualitative base. Secondary validation drew from EU building renovation permit databases, ANSM advertising enforcement records, GDPR biometric data processing filings, and franchise disclosure documents. Bottom-up enrollment data triangulated against top-down metropolitan disposable income estimates across the analysis window.
Scenario-bracketing framed projections across corporate wellness penetration rates, EU Green Deal implementation timelines, and digital fitness platform competitive intensity. Segmentation dimensions modeled include studio ownership structure, class delivery format, customer age cohort, and service offering type. CAGRs derived from enrollment velocity trends, pricing power trajectories, and capital deployment cycle analysis. Instructor labor availability curves and building retrofit cost schedules served as industry-specific forecast inputs.
Stress conditions across GDPR enforcement severity, corporate wellness budget elasticity, and certified instructor graduation rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hybrid work policy permanence and EU building efficiency mandate adherence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gyms and Fitness Centers
Europe Climbing Gym Market
Gyms and Fitness Centers
Health and Fitness Club Market
Gyms and Fitness Centers
South Korea Health and Fitness Club Market
Gyms and Fitness Centers
Global Climbing Gym Market
Gyms and Fitness Centers
Boutique Fitness Studio Market
Gyms and Fitness Centers
Saudi Arabia Health and Fitness Club Market
Gyms and Fitness Centers
South America Health and Fitness Club Market
Gyms and Fitness Centers
Southeast Asia Health and Fitness Club Market
Gyms and Fitness Centers
Global Pilates and Yoga Studios Market
Gyms and Fitness Centers
Fitness and Recreational Sports Centers Market