
 Global Climbing Gym Market | 2026-2036
Global Climbing Gym Market Size, Share, and Industry Trends Forecast 2026-2036
Global Climbing Gym Market Analysis
Franchise expansion is reshaping how climbing gym brands reach new metropolitan markets. Movement Climbing Centers leverages its multi-state footprint to dominate the U.S. Sun Belt. Walltopia anchors European supply through its Sofia-based manufacturing of engineered climbing surfaces. Brooklyn Boulders differentiates via hybrid creative-workspace-gym concepts in dense urban cores.
A climbing gym is a purpose-built indoor facility featuring artificial rock walls, bouldering structures, and training apparatus designed to simulate outdoor rock climbing with standardized hold placements, fall-protection systems, and load-rated anchor points; these installations serve both recreational fitness and competitive athlete development through controlled environments. Indoor climbing centers capture the largest revenue pool due to higher capital thresholds and membership stickiness, while bouldering gyms attract faster footprint growth with lower build-out costs and reduced staffing requirements. Personal training services generate premium margin tiers as climbers seek technique coaching for outdoor transition goals.
ISO 21101 adventure tourism safety management and ASTM F1772 wall standards govern structural integrity and operational protocols across major markets. OSHA workplace safety rules apply to gym staff rigging and maintenance procedures in the United States, while CE marking requirements under EU construction product regulation shape wall system imports into Europe. Stakeholders must monitor evolving national building codes for seismic and occupancy classifications as climbing gyms scale into mixed-use developments.
Market Dynamics
Franchise consolidation is compressing the competitive landscape as multi-state operators deploy standardized wall systems and unified membership platforms across metropolitan clusters, displacing independent single-location gyms.
Growth Catalysts
- ISO 21101 Safety Management:Standardized risk protocols reduce liability premiums and accelerate insurance underwriting for new gym developments across North America and Western Europe.
- Urban Fitness Migration:Post-pandemic relocation patterns concentrate affluent millennials in dense city cores where climbing gyms anchor mixed-use retail developments.
- Competition Climbing:Sport climbing's Olympic inclusion drives municipal investment in training facilities and youth development programs.
Market Restraints
- Engineered Plywood Volatility:Wall panel substrate costs fluctuate with Baltic birch supply disruptions and shipping rate spikes from Baltic Sea ports.
- Specialized Route-Setting Labor:Certified setters command premium wages; talent pools concentrate in established climbing regions, constraining expansion into secondary markets.
- ASTM F1772 Compliance Burden:Third-party load testing and documentation requirements extend pre-opening timelines by four to eight months.
Strategic Opportunities
- India Tier-II Cities:Hyderabad, Pune, and Chandigarh show rising disposable income and limited indoor recreation infrastructure.
- Corporate Wellness Integration:HR departments add climbing memberships to benefits packages; B2B contracting reduces customer acquisition costs.
- CE Marking Harmonization:Simplified EU import procedures for prefabricated wall systems lower cross-border expansion barriers for Bulgarian and French manufacturers.
Industry Challenges
- Route-Setting Certification Backlogs:CWA and IFSC credentialing queues stretch twelve to eighteen months, throttling staffing for new locations.
- Legacy HVAC Incompatibility:Retrofitted warehouses require complete climate system replacement to manage chalk dust and humidity loads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Climbing Gym Market |
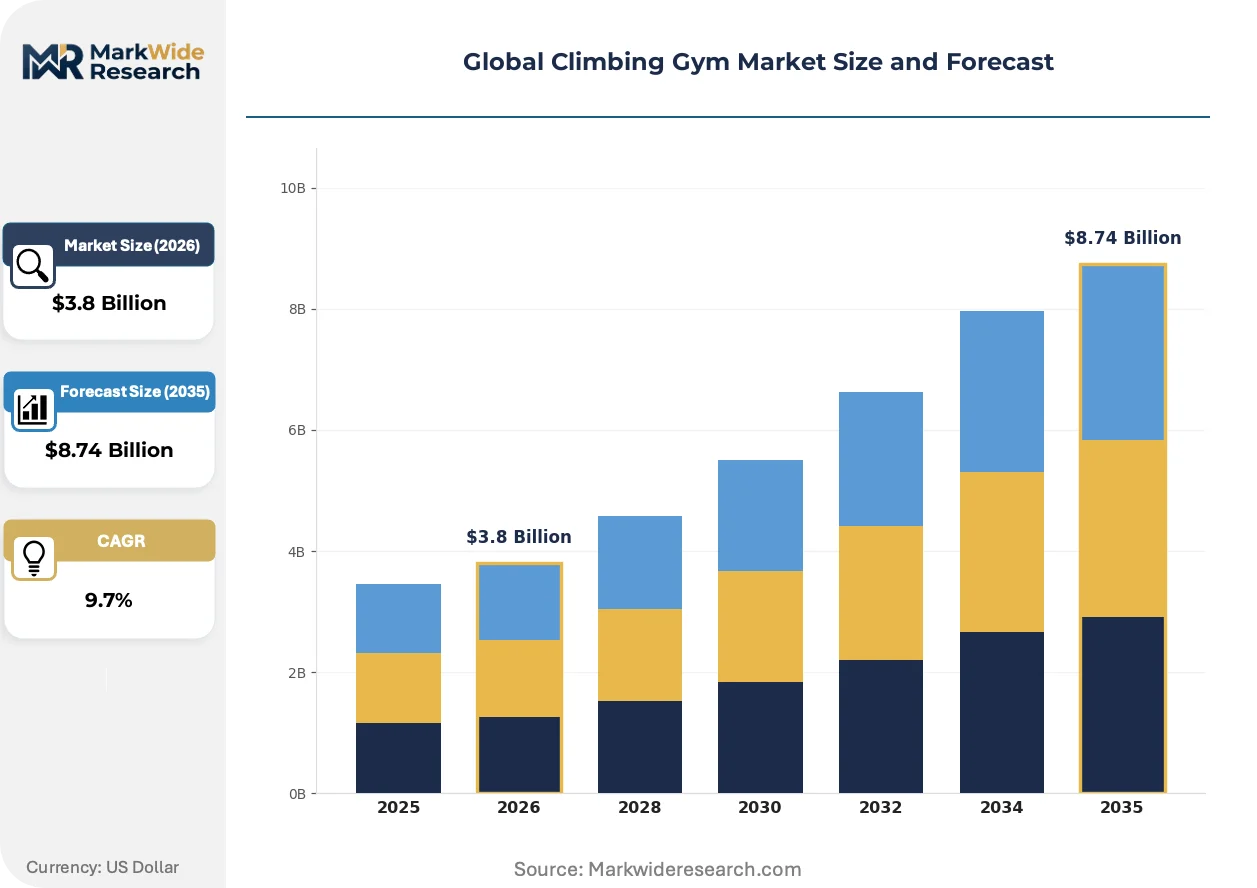
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Indoor Climbing Centers, Bouldering Gyms, Olympic Training Facilities, Adventure Parks Target Audience: Recreational Climbers, Competitive Athletes, Children, Fitness Enthusiasts Service Offering: Climbing Courses, Personal Training, Equipment Rentals, Events Membership Model: Monthly Memberships, Day Passes, Family Packages, Student Discounts |
| Companies Covered | Movement Climbing Centers, Brooklyn Boulders, Central Rock Gym (CRG), Vertical Endeavors, Walltopia, MetroRock, Touchstone Climbing, Climb So iLL, Momentum Climbing Gym, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Climbing Gym Market Emerging Trajectories
Digital immersion is rewiring how climbers train, compete, and socialize inside facilities. Three converging developments are compressing the gap between physical movement and data-driven feedback loops.
Augmented reality hold systems project real-time route sequences onto physical walls, enabling dynamic difficulty adjustment without manual reset. Competitive youth programs and university teams adopt these installations fastest, treating virtualized coaching analytics as essential infrastructure for talent development pipelines.
EU Construction Product Regulation updates now mandate extended producer responsibility for wall system end-of-life disposal. German and French gym operators face mandatory material recovery quotas, driving manufacturers toward recyclable composite substrates and modular bolt-free designs that simplify decommissioning.
Subscription-based access models displace traditional monthly memberships, with climbers purchasing tiered credits for peak-hour reservations and premium coaching slots. This behavior shift concentrates revenue in urban coastal markets where disposable income supports flexible pricing, while price-sensitive inland markets cling to conventional annual contracts.
Global Climbing Gym Market Segmentation
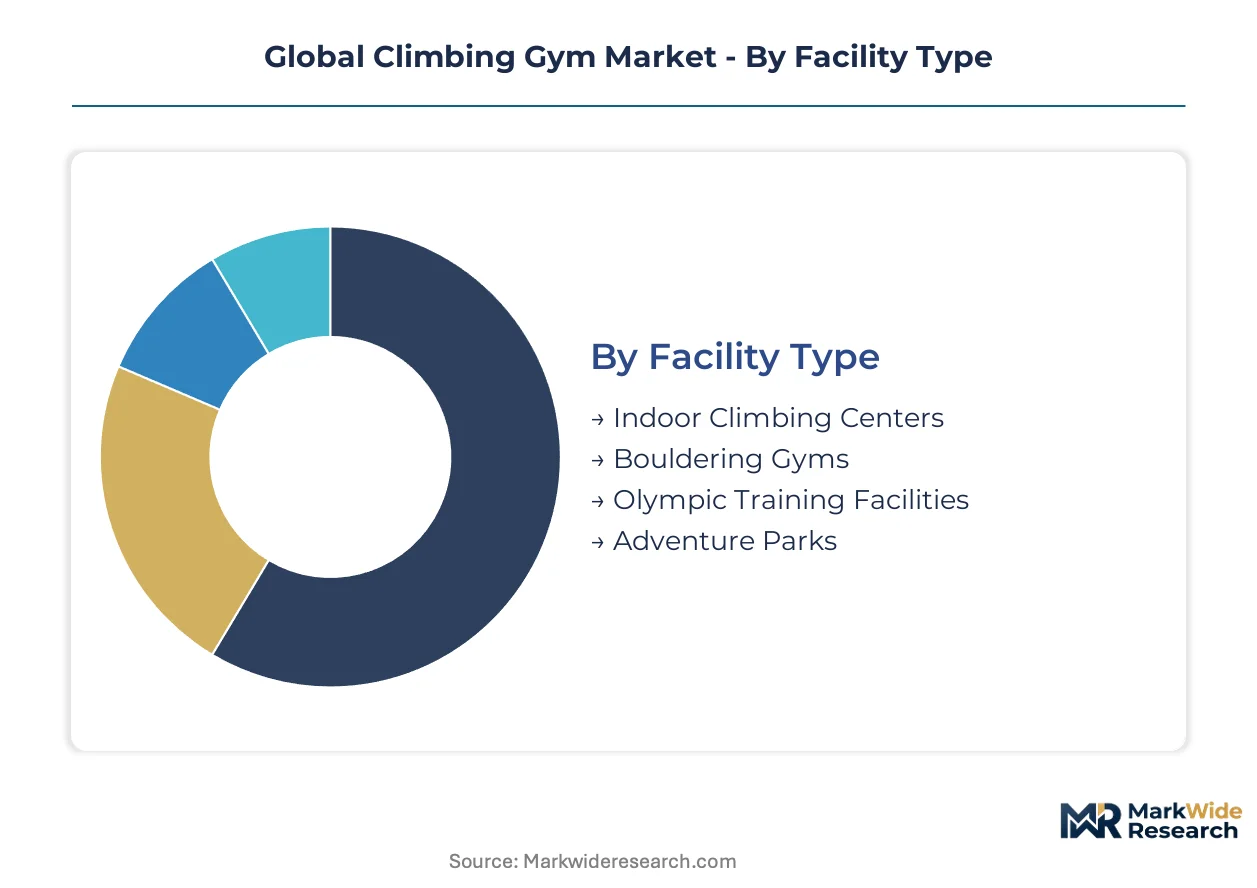
Climbing gym operators configure facility specifications, programming depth, and pricing architecture around distinct user profiles and usage patterns. Segment-level differentiation determines capital deployment intensity, staffing ratios, and revenue per square foot across metropolitan markets.
Facility Type:
Cost tier separates purpose-built installations from repurposed industrial conversions, with build-out expenses ranging across an order of magnitude.
- Indoor Climbing Centers:Full-service installations combine roped climbing walls up to 20 meters, auto-belay systems, and dedicated training zones with campus boards and hangboards. These facilities concentrate in affluent U.S. suburbs and German metropolitan clusters where household recreation budgets support premium membership tiers.
- Bouldering Gyms:Lower-ceiling facilities emphasize unroped climbing on engineered volumes with extensive crash pad coverage and reduced staffing overhead. Operators in Lyon, Bristol, and Austin exploit faster lease negotiations and modular wall systems to compress opening timelines.
- Olympic Training Facilities:IFSC-certified competition walls with standardized hold configurations and video analysis infrastructure serve national federation programs and elite athlete pipelines.
- Adventure Parks:Hybrid outdoor-indoor concepts integrate climbing structures with zip lines and obstacle courses, targeting family entertainment spending in secondary leisure markets.
Indoor Climbing Centers hold installed capacity. Bouldering Gyms is rotating up the share rankings.
Target Audience:
Application focus shifts from technique acquisition to performance optimization based on participant commitment level and competitive ambition.
- Recreational Climbers:Casual participants seeking social fitness experiences and stress relief through low-commitment drop-in access. Demand clusters in London, Melbourne, and Vancouver where dense urban cores limit outdoor climbing access.
- Competitive Athletes:Structured training regimens incorporating periodized strength protocols, video movement analysis, and sport-specific nutrition coaching. Japanese and Slovenian national programs drive municipal investment in dedicated training infrastructure.
- Children:Birthday party programming and youth league development emphasizing motor skill acquisition and confidence building through gamified progression systems.
- Fitness Enthusiasts:Cross-training athletes from running, cycling, and functional fitness backgrounds attracted by climbing's full-body engagement metrics and low-impact joint loading.
Fitness Enthusiasts holds installed capacity. Competitive Athletes is rotating up the share rankings.
Service Offering:
Margin contribution varies dramatically across programming depth, with human-delivered instruction commanding premium pricing against self-directed facility access.
- Climbing Courses:Progressive curriculum from belay certification through lead climbing competence, typically delivered in six-week blocks with instructor ratios of 4:1. Dutch and Swiss operators report highest course attachment rates among European markets.
- Personal Training:One-on-one technique coaching and outdoor transition preparation for climbers targeting specific alpine objectives or redpoint projects.
- Equipment Rentals:Harness, shoe, and chalk bag provision reducing barrier to entry for trial users and traveling climbers.
- Events:Corporate team-building contracts and private facility buyouts generating off-peak revenue utilization.
Climbing Courses holds installed capacity. Personal Training is rotating up the share rankings.
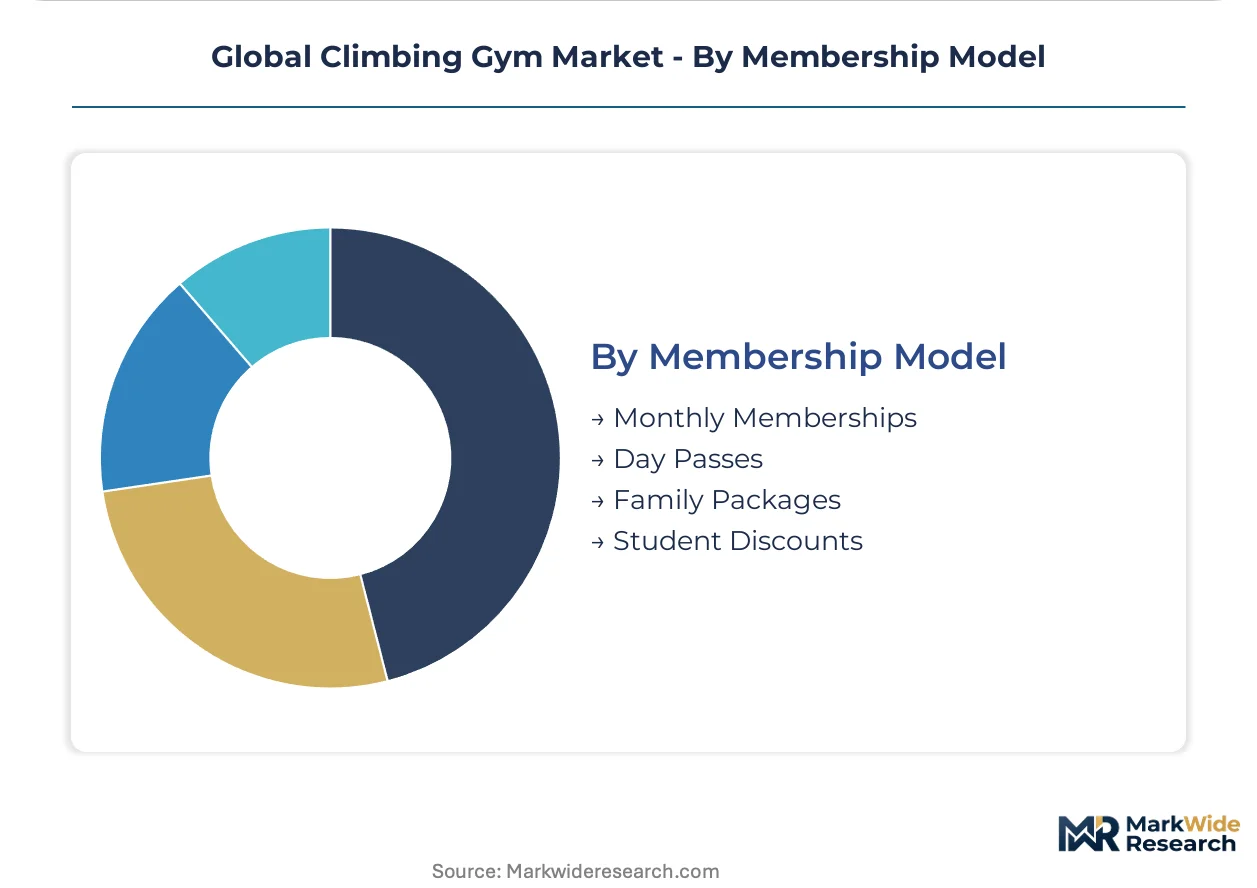
Membership Model:
Customer type and commitment duration determine pricing architecture, with hybrid models emerging to capture both sporadic and habitual usage patterns.
- Monthly Memberships:Unlimited access subscriptions with auto-renewal terms and multi-month commitment discounts. U.S. coastal operators in San Francisco and New York command 40-60% premiums over inland markets.
- Day Passes:Single-visit access for tourists, occasional users, and prospective members evaluating facility fit before subscription commitment.
- Family Packages:Multi-user household pricing with dependent age restrictions and shared visit credits.
- Student Discounts:Verified enrollment pricing targeting university-adjacent locations in Boulder, Innsbruck, and Sheffield.
Monthly Memberships holds installed capacity. Day Passes is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Climbing gym membership rates in San Francisco and New York command premiums exceeding inland U.S. markets by 40-60 percent, while operators in Lyon and Bristol exploit faster lease cycles to compress facility build-out timelines. This pricing-power asymmetry reflects divergent real estate pressures and household recreation budget elasticity across metropolitan clusters.
United States
Urban fitness migration concentrates affluent millennials in dense coastal cores where climbing gyms anchor mixed-use retail developments. OSHA workplace safety rules govern staff rigging and maintenance procedures nationwide. Brooklyn Boulders and Movement Climbing Centers dominate Sun Belt expansion through standardized wall systems and unified membership platforms across metropolitan clusters.
Germany
Municipal investment in youth development programs accelerates following sport climbing's Olympic inclusion, driving demand for IFSC-certified training infrastructure. EU Construction Product Regulation updates mandate extended producer responsibility for wall system end-of-life disposal, compelling manufacturers toward recyclable composite substrates. Berlin and Munich operators face mandatory material recovery quotas under German federal implementation of EPR frameworks.
Japan
National federation programs channel public funding into elite athlete pipelines, creating concentrated demand for competition-grade facilities with video analysis infrastructure. METI industrial standards influence equipment import protocols for artificial climbing structures. Tokyo and Osaka metropolitan areas host the densest concentration of Olympic training facilities serving competitive youth programs.
United Kingdom
Recreational climbers seeking social fitness experiences cluster in London where dense urban cores limit outdoor climbing access. CE marking requirements under EU construction product regulation shape wall system imports, though post-Brexit alignment remains in transition. Bristol operators exploit modular wall systems to accelerate lease negotiations and compress opening timelines in secondary metropolitan markets.
Australia
Fitness enthusiasts from running and cycling backgrounds drive cross-training demand for full-body engagement metrics and low-impact joint loading. The country's national building codes govern seismic and occupancy classifications as climbing gyms scale into mixed-use developments. Melbourne and Sydney climbing centers capture premium membership tiers through purpose-built installations combining roped walls with dedicated training zones.
Global Climbing Gym Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying engineered surfaces and hold systems to facility operators. The competitive landscape compresses around multi-state franchise networks deploying standardized infrastructure, while independent single-location gyms face displacement pressure. Two strategic archetypes dominate: vertically integrated facility operators controlling wall design and membership platforms, and specialized equipment fabricators supplying modular systems across geographic markets. Consolidation through franchise expansion and strategic partnerships between gym networks and equipment suppliers reshapes competitive positioning.
Among U.S.-based facility operators, Movement Climbing Centers, Brooklyn Boulders, and Central Rock Gym exemplify the vertically integrated archetype, combining multi-state footprints with captive route-setting labor pools and unified digital membership platforms. Walltopia anchors the European supply tier through Sofia-based manufacturing of engineered climbing surfaces, representing the component specialist model that supplies wall systems to franchise networks and independent operators across continental markets. These named entities occupy positions reflecting broader structural patterns: facility scale concentration in North American metropolitan clusters and manufacturing gravity in Eastern European industrial zones.
| Leading Market Players |
|---|
| Movement Climbing Centers |
| Brooklyn Boulders |
| Central Rock Gym (CRG) |
| Vertical Endeavors |
| Walltopia |
| MetroRock |
| Touchstone Climbing |
| Climb So iLL |
| Momentum Climbing Gym |
| Others |
Supply Flow & Price Mechanics
Baltic birch plywood supply disruptions from Baltic Sea ports compress both margin structures and sourcing geography for climbing wall manufacturers, forcing tiered pricing spreads between premium engineered substrates and standard panel grades while reshaping supplier networks toward alternative fiber sources.
Pricing Analysis
The customization-premium spread separates IFSC-certified competition wall systems from standard recreational installations, with Olympic-grade configurations commanding substantial uplifts over baseline bouldering gym packages. Pricing stratifies across premium, standard, and economy tiers based on hold density specifications and auto-belay integration levels. Cost compression in the standard tier is intensifying because modular wall system imports from Eastern European manufacturers compress domestic fabricator margins. Boutique urban operators in San Francisco and New York exhibit lowest price sensitivity, while secondary market franchisees in inland U.S. metros face acute budget constraints.
Supply Chain Analysis
Export-control regimes on engineered composite substrates limit cross-border flows of proprietary resin formulations used in recyclable wall panel manufacturing. Manufacturing gravity centers on Bulgaria, Germany, and China for prefabricated wall systems, while hold production concentrates in Slovenia and the United States. Raw material dependencies span Baltic birch plywood, polyurethane foam cores, and specialized climbing-grade resins. Single-source vulnerability runs through Baltic Sea shipping lanes for plywood substrate delivery. Distribution runs through franchise network procurement hubs and direct-to-gym contracts for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Climbing Gym Market sits in an early-cycle expansion phase driven by Olympic sport climbing adoption accelerating municipal facility investment and youth program development.
For Market Incumbents: Harden route-setting labor pipelines through captive certification academies and apprenticeship programs to offset CWA credentialing backlogs throttling multi-state expansion. Lock in long-term Baltic birch supply contracts with Estonian and Finnish mills before shipping rate volatility escalates. Deepen backward integration into hold manufacturing to reduce dependency on Slovenian specialist suppliers. For New Entrants and Emerging Players: Establish a beachhead in India's Tier-II cities where Hyderabad and Pune show rising disposable income and minimal indoor recreation infrastructure penetration. Target corporate wellness B2B contracting channels to bypass saturated consumer membership markets and reduce customer acquisition costs. Exploit modular bouldering gym formats with compressed build-out timelines to outpace legacy indoor climbing center competition. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-integrated facility networks with unified membership systems over standalone independent operations. Long-term viability hinges on scalable route-setting labor models and digital coaching platform integration. Acquisition targets should demonstrate captive certification pipelines or exclusive metropolitan real estate positions. The signal to watch is municipal bond issuance for sport climbing infrastructure as an inflection indicator for public capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Route-Setting Certification Pipeline Investment | CWA and IFSC credentialing backlogs constrain staffing for new locations across North America. |
| Modular Wall System Manufacturing Scale-Up | Bulgarian and German producers expand capacity to serve franchise network standardization demands. |
| Digital Coaching Platform Integration | Augmented reality hold systems attract university teams and competitive youth program adoption. |
| Corporate Wellness B2B Contracting | HR benefits packages reduce customer acquisition costs and stabilize recurring revenue streams. |
| Recyclable Composite Substrate Development | German EPR mandates under EU Construction Product Regulation drive material innovation investment. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with climbing gym franchise executives, route-setting certification directors, municipal recreation planners, wall system manufacturing engineers, and commercial real estate developers specializing in mixed-use fitness retail. Secondary validation drew from IFSC competition infrastructure guidelines, CWA operational standards documentation, EU Construction Product Regulation filings, ASTM F1772 testing protocols, and municipal bond prospectuses for sport facility development. Bottom-up facility count modeling and top-down recreation spending allocation were triangulated to anchor market sizing.
Calibration against historical facility opening rates and membership penetration benchmarks shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include facility type, target audience commitment level, service offering depth, and membership contract structure alongside regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation moderated by capacity constraint analysis and labor supply elasticity. Forecast inputs incorporated route-setting certification queue lengths and Baltic birch shipping rate indices as industry-specific variables.
Stress conditions across engineered plywood price volatility, credentialing backlog duration, and municipal funding commitment levels were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding ISO 21101 adoption timelines and franchise expansion velocity. Material shifts in Olympic sport climbing funding allocations or Baltic Sea trade route disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gyms and Fitness Centers
South Korea Health and Fitness Club Market
Gyms and Fitness Centers
Global Pilates and Yoga Studios Market
Gyms and Fitness Centers
South America Health and Fitness Club Market
Gyms and Fitness Centers
Europe Pilates & Yoga Studios Market
Gyms and Fitness Centers
Health and Fitness Club Market
Gyms and Fitness Centers
Saudi Arabia Health and Fitness Club Market
Gyms and Fitness Centers
Europe Climbing Gym Market
Gyms and Fitness Centers
Boutique Fitness Studio Market
Gyms and Fitness Centers
Fitness and Recreational Sports Centers Market
Gyms and Fitness Centers
Southeast Asia Health and Fitness Club Market