
 Global Pilates and Yoga Studios Market | 2026-2036
Global Pilates and Yoga Studios Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pilates and Yoga Studios Market Foresight
Certified instructor shortages across major metropolitan markets is unwinding capacity expansion plans for several studio chains. CorePower Yoga leverages its proprietary teacher training pipeline to sustain national franchise growth. YogaWorks anchors its coastal presence with specialized teacher development programs. Life Time Fitness competes through integrated wellness campus formats that bundle Pilates and yoga with medical and spa services.
Pilates and yoga studios deliver structured movement instruction through mat-based and apparatus-based exercise systems utilizing spring resistance, bodyweight leverage, and breath-controlled sequencing to improve core stability, flexibility, and neuromuscular coordination. Franchise studios capture economies of scale in branding and equipment procurement while independent studios dominate hyperlocal neighborhood positioning. Online classes represent the fastest-growing service offering as asynchronous delivery reduces real estate dependency and extends geographic reach beyond studio catchment zones.
FDA oversight of wellness claims intersects with state-level health facility licensing to shape service marketing boundaries and liability frameworks across the United States. OSHA ergonomic guidelines influence equipment design standards and instructor workplace safety protocols in commercial studio environments. Stakeholders must monitor evolving digital health regulations as hybrid delivery models blur distinctions between physical fitness services and telehealth-adjacent wellness platforms.
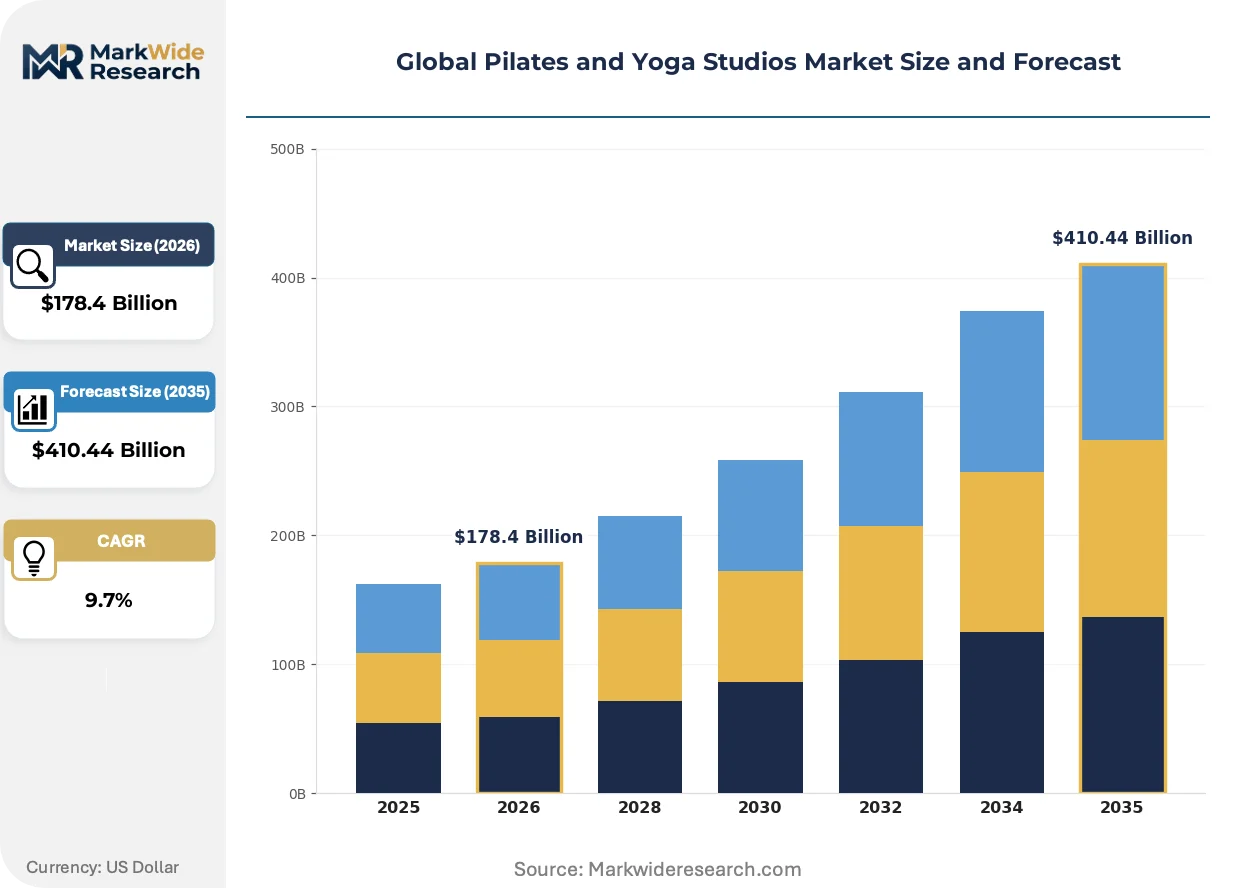
Market Dynamics
Hybrid delivery models are compressing studio catchment economics as asynchronous digital instruction erodes the geographic moats that once protected brick-and-mortar operators from competition outside their immediate radius.
Growth Catalysts
- Employer wellness mandates:United States corporations are expanding subsidized studio memberships as ISO standards for fitness service quality validate structured movement programs in occupational health frameworks.
- CE marking alignment:European Union equipment safety protocols are accelerating apparatus upgrade cycles across Germany, France, and the Netherlands as studios invest in spring-resistance systems meeting MDR-adjacent mechanical safety benchmarks.
- Biometric integration:Wearable sensor technology is enabling real-time form correction in mat-based classes, pulling hardware manufacturers into instructor training partnerships.
Market Restraints
- Certified instructor scarcity:Pipeline constraints for comprehensively trained teachers in the United States and United Kingdom are capping class throughput at established studios.
- Commercial real estate concentration:Prime urban retail space in Tokyo, London, and New York City commands premium rents that consume disproportionate revenue share for independent operators.
- Digital platform substitution:Low-cost asynchronous content libraries are eroding price discipline for introductory membership tiers.
Strategic Opportunities
- Underpenetrated Indian metros:Bangalore, Mumbai, and Delhi present whitespace for standardized franchise formats as disposable income growth meets limited organized competition.
- Medical referral channels:Physical therapy integration creates reimbursement-adjacent revenue streams as United States clinicians prescribe movement interventions for chronic pain management.
- AI-driven personalization:Computer vision form analysis converging with breath-monitoring wearables enables differentiated premium tiers without proportional instructor cost scaling.
Industry Challenges
- Teacher training duration:Comprehensive certification programs require 200-500 contact hours, creating 18-24 month lag between enrollment and revenue-generating capacity.
- Multi-jurisdiction compliance:Studios operating across United States state lines must navigate divergent health facility licensing, OSHA ergonomic mandates, and FDA wellness claim boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pilates and Yoga Studios Market |
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $410.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Studio Type: Independent Studios, Franchise Studios, Wellness Centers, Community Centers Service Offering: Group Classes, Private Sessions, Workshops, Online Classes Membership Model: Monthly Subscriptions, Pay-Per-Class, Annual Passes, Class Packs Target Demographic: Fitness Enthusiasts, New Parents, Seniors, Corporate Groups |
| Companies Covered | Club Pilates, CorePower Yoga, YogaWorks, Pure Barre, Life Time Fitness, YogaSix, Solidcore, Flex Studios, Authentic Pilates Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pilates and Yoga Studios Market Shifts & Advancements
Digital infrastructure investments are reconfiguring competitive advantage away from location density toward content quality and instructor brand equity, compressing the traditional studio model's defensible perimeter.
Immersive projection systems paired with spatial audio are fragmenting the group class experience into personalized micro-environments where participants follow individually paced visual cues within shared physical space. Boutique studios in Seoul and Sydney are deploying these installations to justify 40% membership premiums over conventional formats. The technology is fragmenting class economics by enabling higher student-to-instructor ratios without perceived quality degradation.
Japan's METI has issued voluntary guidelines for digital health platform interoperability that are pressuring domestic studio chains to adopt standardized data exchange protocols for member health metrics. The framework is accelerating API development investments among equipment manufacturers seeking integration with third-party wellness apps. Domestic operators must now budget for compliance engineering that was previously discretionary.
Subscription fatigue among United States urban consumers is driving unbundling of all-access memberships into single-class purchases and specialized modality passes. Digital-native entrants are capturing this behavior with dynamic pricing algorithms that adjust real-time rates based on inventory and demand patterns. The shift is most visible in Los Angeles and Miami, where legacy annual contract models are shedding market position to flexible consumption platforms.
Global Pilates and Yoga Studios Market Segmentation
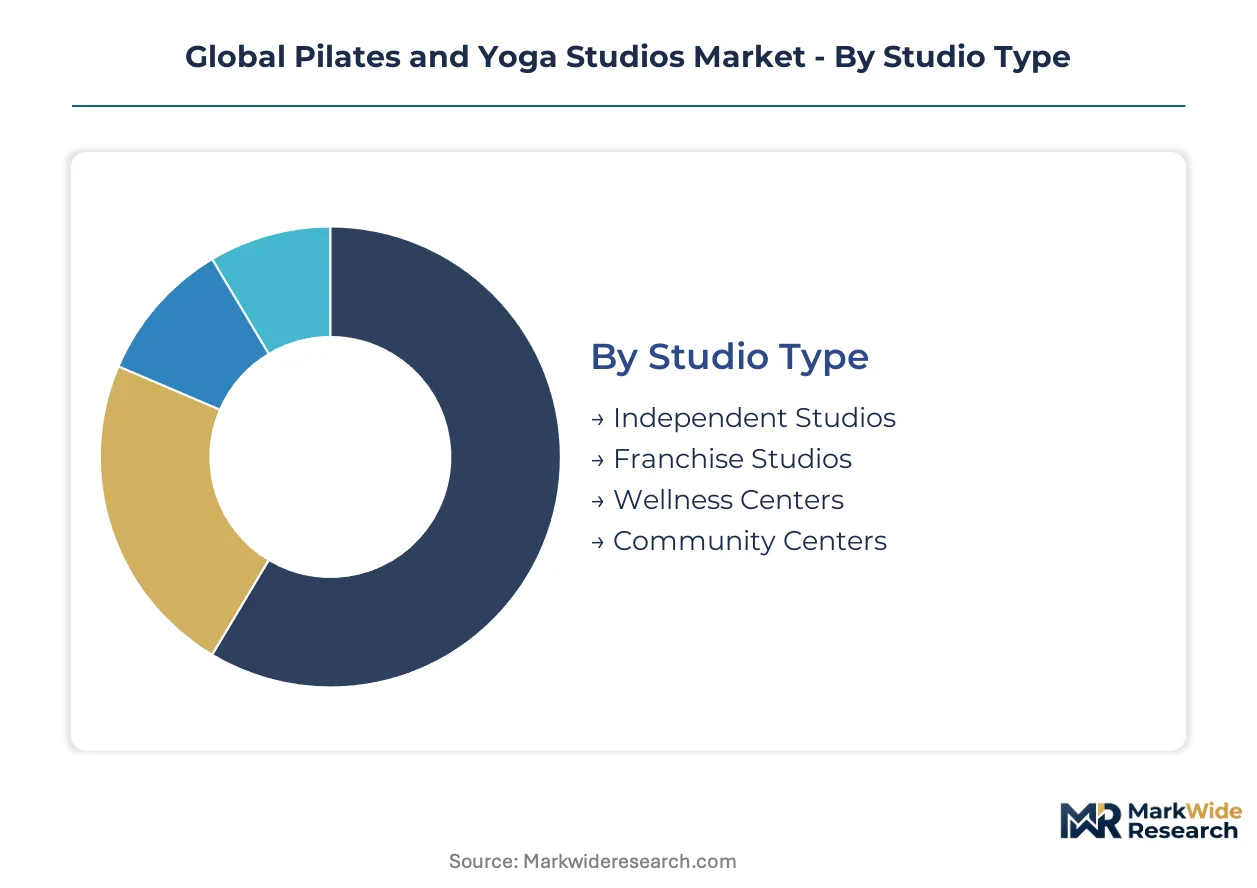
Segmentation in the Pilates and yoga studios market reveals how regulatory frameworks, real estate economics, and delivery modalities partition revenue streams across distinct operational archetypes. Each category captures divergent capital intensity, margin profiles, and compliance burdens that shape competitive positioning.
Studio Type:
FDA wellness claim boundaries and state-level health facility licensing create divergent compliance architectures across studio ownership structures, with franchisors bearing centralized liability while independents navigate localized regulatory patchworks.
- Independent Studios:Owner-operated single locations dominate hyperlocal neighborhood positioning with customized programming and community-anchored instructor relationships. Demand concentrates in dense urban corridors of New York City, London, and Tokyo where premium rents are offset by high-frequency member loyalty and limited direct competition within walking distance. OSHA ergonomic mandates fall directly on proprietors, driving equipment investment decisions without corporate support.
- Franchise Studios:Branded networks leverage centralized procurement, standardized curricula, and national marketing scale to compress unit economics across multiple jurisdictions. Multi-jurisdiction compliance complexity—spanning divergent state health facility licenses, OSHA workplace safety protocols, and FDA marketing boundaries—favors franchisors with dedicated legal infrastructure over independent operators.
- Wellness Centers:Integrated health campuses bundle Pilates and yoga with medical, spa, and nutritional services under single-roof membership models.
- Community Centers:Municipal or nonprofit facilities offer subsidized access with lower price points and reduced amenity tiers.
Established volume favors franchise studios; emerging adoption favors independent studios.
Service Offering:
Cost tier stratification separates premium synchronous instruction from scalable asynchronous delivery, with biometric integration and immersive technology driving divergence in student-to-instructor economics.
- Group Classes:Mat-based and apparatus-based sessions serve as the volume foundation for most studio revenue models. Seoul and Sydney operators deploy immersive projection systems with spatial audio to justify 40% membership premiums while enabling higher student-to-instructor ratios without perceived quality degradation.
- Private Sessions:One-on-one instruction commands premium pricing for personalized form correction and injury rehabilitation protocols. Demand concentrates among corporate wellness beneficiaries and medical referral patients in the United States seeking reimbursement-adjacent movement interventions for chronic pain management.
- Workshops:Intensive multi-hour or multi-day immersions targeting skill acquisition or teacher certification prerequisites.
- Online Classes:Asynchronous digital instruction eliminates real estate dependency and extends geographic reach beyond traditional catchment zones.
Revenue concentration remains with group classes; steepest expansion trajectory belongs to online classes.
Membership Model:
Customer type and consumption pattern segmentation reflects subscription fatigue among urban consumers and the unbundling of legacy annual contracts into flexible, inventory-responsive purchasing.
- Monthly Subscriptions:Recurring revenue models provide predictable cash flow for studio operators while locking in member commitment. Los Angeles and Miami markets show accelerating erosion of this structure as digital-native entrants capture preference shifts with dynamic pricing alternatives.
- Pay-Per-Class:Single-session purchasing aligns with sporadic practitioners and trial users unwilling to commit to recurring obligations. ISO standards for fitness service quality validate structured movement programs in employer-sponsored frameworks, yet individual consumers increasingly favor this flexibility over bundled access.
- Annual Passes:Upfront payment models exchange deep discounts for guaranteed revenue and reduced churn exposure.
- Class Packs:Prepaid bundles of 5-20 sessions balance commitment with flexibility for intermittent practitioners.
Legacy dominance sits with monthly subscriptions; momentum shift favors pay-per-class.
Target Demographic:
Maturity and life-stage segmentation maps distinct programming requirements, instructor specialization needs, and pricing sensitivity across participant cohorts with divergent physical capability profiles and scheduling constraints.
- Fitness Enthusiasts:High-frequency practitioners seek advanced apparatus training, heated power yoga formats, and performance-oriented progression systems. CE marking alignment for European equipment safety protocols accelerates apparatus upgrade cycles in Germany, France, and the Netherlands to serve this demand tier.
- New Parents:Postnatal-focused classes emphasize core rehabilitation, pelvic floor restoration, and child-accommodating scheduling. Demand concentrates in suburban United States markets where employer wellness mandates subsidize return-to-fitness programming.
- Seniors:Gentle movement protocols prioritize fall prevention, joint mobility, and chronic condition management with modified intensity.
- Corporate Groups:Employer-sponsored cohorts access subsidized memberships or on-site programming as occupational health investments.
Current revenue weight favors fitness enthusiasts; demographic tailwinds favor new parents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power in United States urban corridors exceeds equivalent capacity in German secondary cities by substantial margins, reflecting divergent employer subsidy penetration and real estate cost structures. This asymmetry shapes capital allocation toward Anglo-American expansion while compressing returns in Continental European markets.
United States
Employer wellness mandates from Fortune 500 corporations subsidize boutique studio memberships across Manhattan, Los Angeles, and Miami metropolitan zones. OSHA ergonomic guidelines govern equipment specifications and instructor workplace protocols in commercial environments. New York City operators command 40% membership premiums through immersive projection installations that fragment group classes into personalized micro-environments.
Germany
CE marking alignment for spring-resistance apparatus accelerates equipment upgrade cycles in Berlin, Munich, and Hamburg studio networks. The country's national fitness quality regulator enforces mechanical safety benchmarks adjacent to EU MDR standards. Frankfurt's integrated wellness campuses bundle Pilates instruction with medical and spa services under single-roof membership models.
Japan
METI voluntary guidelines for digital health platform interoperability pressure Tokyo and Osaka studio chains to adopt standardized data exchange protocols for member biometrics. JIS standards influence equipment design specifications for domestic manufacturers. Seoul-influenced immersive technology deployments in Roppongi and Shibuya districts justify premium pricing through spatial audio and projection systems.
United Kingdom
Certified instructor scarcity caps class throughput in London, Manchester, and Birmingham established studios. The Health and Safety Executive administers workplace safety protocols parallel to OSHA ergonomic mandates. Shoreditch and Notting Hill independents dominate hyperlocal neighborhood positioning with customized programming and community-anchored instructor relationships.
India
Whitespace opportunity concentrates in Bangalore, Mumbai, and Delhi as disposable income growth meets limited organized franchise competition. The Bureau of Indian Standards issues voluntary equipment quality benchmarks that precede formal certification requirements. Bandra and Indiranagar boutique operators test standardized formats ahead of national chain rollout.
Global Pilates and Yoga Studios Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Pilates and yoga studios market. The vendor base concentrates around three structural tiers: integrated wellness campus operators, boutique franchise networks, and independent owner-operators. National franchise chains capture procurement economies and brand scale while independents defend hyperlocal positioning. Dominant competitive moves include proprietary teacher training pipeline development and immersive technology integration to justify membership premiums.
Within the franchise network tier, CorePower Yoga exemplifies national scale through proprietary instructor development systems, while YogaWorks anchors coastal United States presence with specialized teacher certification programs. Life Time Fitness occupies a position representing integrated wellness campus formats that bundle movement instruction with medical and spa services. These three entities illustrate divergent capital intensity models: pure-play studio franchising, coastal geographic concentration, and multi-service health campus integration.
| Leading Market Players |
|---|
| Club Pilates |
| CorePower Yoga |
| YogaWorks |
| Pure Barre |
| Life Time Fitness |
| YogaSix |
| Solidcore |
| Flex Studios |
| Authentic Pilates Ltd. |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four-month instructor certification pipelines compress inventory flexibility for studio operators, tethering pricing power to human capital availability rather than equipment procurement cycles. This lead-time rigidity concentrates margin leverage with franchisors possessing proprietary teacher training infrastructure while independent studios absorb spot-market wage volatility.
Pricing Analysis
The customization-premium spread between immersive projection-enabled classes and conventional mat instruction reaches forty percent in Manhattan and Los Angeles markets. Three-tier pricing structure across premium immersive, standard group, and economy digital tiers dominates membership architecture. Price differentiation hinges on biometric integration density and instructor certification tier. Pricing pressure stems from asynchronous platform substitution eroding introductory tier discipline. Corporate wellness beneficiaries exhibit lowest price sensitivity; sporadic digital-native consumers drive unbundling toward single-class purchasing.
Supply Chain Analysis
Inbound logistics costs for spring-resistance apparatus from German and Chinese manufacturers fluctuate with container availability on Asia-Europe trade lanes. Equipment manufacturing concentrates in Germany, China, and the United States. Raw material dependencies span surgical-grade steel springs, hardwood reformer frames, and antimicrobial mat polymers. Supply chain risk centers on CE marking alignment delays for MDR-adjacent mechanical safety upgrades. Distribution runs through franchisor-centralized procurement for branded networks and direct manufacturer relationships for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as subscription fatigue unbundles legacy annual contracts into flexible consumption platforms. Demand-side channel fragmentation rewards specialists over generalists.
For Market Incumbents: Consolidate proprietary teacher training pipelines to defend against certified instructor scarcity capping class throughput. Acquire immersive technology deployment capabilities to justify membership premiums eroded by digital platform substitution. Vertical integration into biometric hardware partnerships locks in form-correction differentiation.
For New Entrants and Emerging Players: Medical referral channel underdevelopment in United States physical therapy integration presents whitespace for reimbursement-adjacent movement intervention studios. Target Bangalore, Mumbai, and Delhi metropolitan zones where disposable income growth meets limited organized franchise competition. Pursue employer wellness mandate certification as the primary go-to-market anchor.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because certified instructor scarcity and multi-jurisdiction compliance complexity favor scaled franchisors over fragmented independents. Acquisition targets should demonstrate proprietary training infrastructure or immersive technology deployment capabilities. Watch ISO fitness service quality standard adoption velocity as the inflection signal for employer subsidy expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Teacher Training Pipeline Development | CorePower Yoga's instructor development system sustains national franchise growth despite certified teacher shortages. |
| Immersive Technology Integration | Seoul and Sydney operators deploy spatial audio projection systems to justify forty percent membership premiums. |
| Medical Referral Channel Establishment | Physical therapy integration creates reimbursement-adjacent revenue streams for chronic pain management prescriptions. |
| Biometric Wearable Partnership | Real-time form correction via sensor technology enables differentiated premium tiers without proportional instructor cost scaling. |
| Employer Wellness Mandate Certification | ISO fitness service quality validation unlocks Fortune 500 subsidized membership expansion across metropolitan zones. |
Research Methodology
Operator-level perspectives from studio owners, franchise development executives, certified instructor training directors, and employer wellness program managers anchored the qualitative base. Secondary validation drew from OSHA ergonomic guideline filings, FDA wellness claim adjudications, METI digital health platform interoperability frameworks, and ISO fitness service quality documentation. Bottom-up unit economics modeling triangulated against top-down market sizing from national fitness industry associations and commercial real estate transaction databases.
Sensitivity analysis tested instructor pipeline lag effects, commercial rent escalation scenarios, and digital substitution elasticity across the projection horizon. Segmentation dimensions modeled encompassed studio ownership structure, service delivery modality, membership commitment tier, and target demographic life-stage. CAGRs derived from cohort retention curve analysis and geographic expansion run-rate extrapolation. Forecast inputs incorporated employer wellness mandate penetration curves and immersive technology adoption thresholds.
Forecasts assume regulatory continuity in FDA wellness claim boundaries, OSHA ergonomic mandates, and state-level health facility licensing regimes; material policy shifts would require re-modeling. Instructor certification duration rigidity and commercial real estate concentration risk constitute primary forecast revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gyms and Fitness Centers
Global Climbing Gym Market
Gyms and Fitness Centers
South Korea Health and Fitness Club Market
Gyms and Fitness Centers
Saudi Arabia Health and Fitness Club Market
Gyms and Fitness Centers
Health and Fitness Club Market
Gyms and Fitness Centers
Europe Pilates & Yoga Studios Market
Gyms and Fitness Centers
Fitness and Recreational Sports Centers Market
Gyms and Fitness Centers
South America Health and Fitness Club Market
Gyms and Fitness Centers
Southeast Asia Health and Fitness Club Market
Gyms and Fitness Centers
Boutique Fitness Studio Market
Gyms and Fitness Centers
Europe Climbing Gym Market