
 Health and Fitness Club Market | 2026-2036
Health and Fitness Club Market Size, Share, and Industry Trends Forecast 2026-2036
Health and Fitness Club Market Analysis
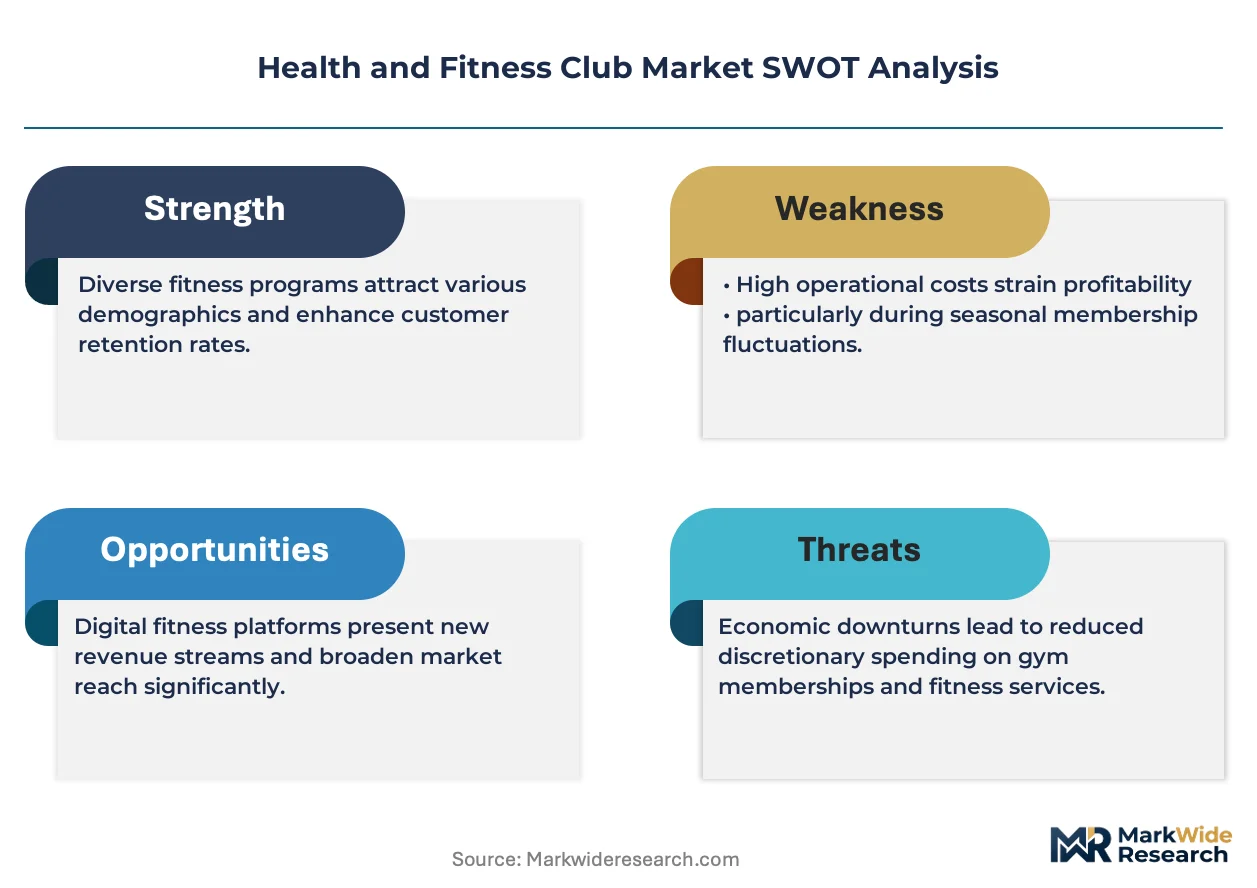
A capital-intensity divergence between premium full-service operators and budget franchise networks is redrawing competitive boundaries in the health and fitness club sector. Equinox Holdings sustains its position through high-amenity real estate in dense metropolitan corridors. Planet Fitness leverages a no-frills, high-volume model that dominates price-sensitive suburban markets. Basic-Fit anchors European expansion through standardized, scalable club formats that control development costs.
A health and fitness club constitutes a commercial facility providing structured physical exercise environments through cardiovascular equipment, resistance training apparatus, and instructor-led programming, typically operating on membership-based revenue models with ancillary service monetization. The facility type dimension stratifies sharply: commercial gyms capture the broadest membership bases through equipment density, while boutique studios command premium pricing through specialized programming in cycling, yoga, and high-intensity interval formats. Service offering differentiation increasingly concentrates around personal training and nutrition counseling, where per-session economics exceed standard membership dues and retention correlates with individualized coaching engagement.
Regulatory oversight spans OSHA workplace safety standards for employee protection, state-level health department sanitation mandates for facility hygiene, and municipal zoning ordinances that restrict club placement and operating hours. The EU Green Deal and national building efficiency codes in Germany and France are pressuring facility operators to retrofit HVAC and lighting systems, elevating capital requirements for market access. Stakeholders must weigh technology deployment against physical footprint economics as hybrid digital-physical membership models test traditional unit-economics assumptions.
Market Dynamics
Wearable fitness technology integration is compressing member acquisition cycles while forcing traditional operators to reconfigure floor space toward experiential programming and away from equipment density.
Growth Catalysts
- Corporate Wellness Mandates:Large employers across the United States are expanding subsidized gym memberships as a retention tool, channeling steady volume into commercial club networks.
- EU Green Deal Building Codes:Energy efficiency retrofit requirements in Germany and France are accelerating HVAC and lighting upgrades that reduce long-term facility operating costs.
- Urban Health Infrastructure Investment:Municipal governments in China are incorporating fitness facilities into mixed-use development approvals, embedding clubs within residential and commercial clusters.
Market Restraints
- Prime Real Estate Scarcity:Metropolitan corridor rents in New York, London, and Shanghai consume disproportionate revenue share for full-service operators.
- Qualified Instructor Shortage:Certified personal trainers and specialized class instructors command wage premiums that compress franchise unit economics.
- Digital-Only Substitutes:App-based home workout platforms capture price-sensitive users who prioritize convenience over facility access.
Strategic Opportunities
- India Tier-II City Penetration:Underdeveloped health infrastructure in Pune, Jaipur, and Lucknow offers first-mover positioning for standardized club formats.
- Medicare Advantage Integration:US insurers are expanding fitness benefit riders that reimburse senior memberships, opening demographic white space.
- Wearable-CRM Convergence:Biometric data streams from Apple Watch and Garmin devices enable predictive retention interventions and personalized programming.
Industry Challenges
- Legacy System Integration:Established operators struggle to mesh decades-old membership databases with modern mobile booking and payment platforms.
- Sanitation Compliance Velocity:Post-pandemic health department inspection protocols in multiple jurisdictions demand rapid operational adjustments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Health and Fitness Club Market |
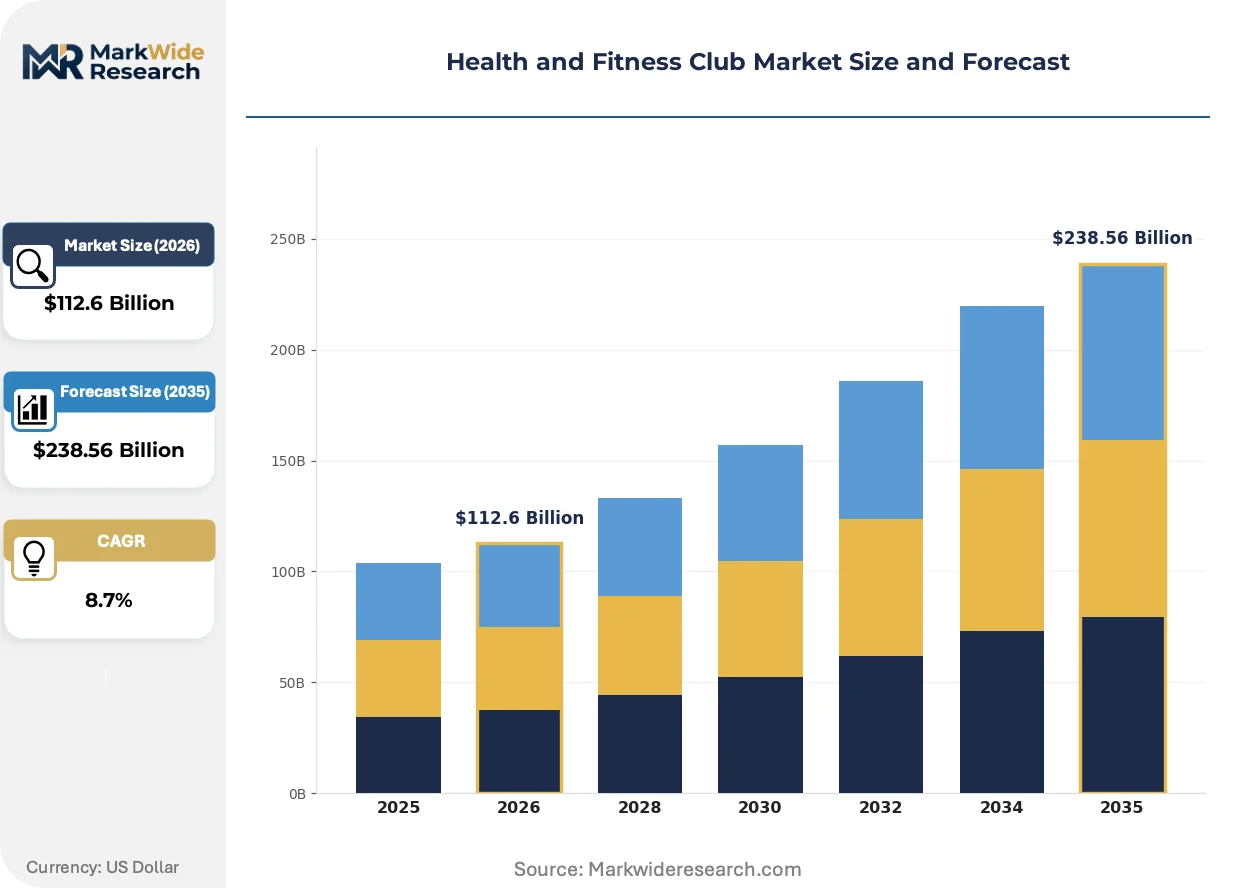
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $238.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Membership Type: Individual, Family, Corporate, Student Facility Type: Commercial Gym, Boutique Studio, Community Center, Hospital Gym Service Offering: Personal Training, Group Classes, Nutrition Counseling, Spa Services Equipment Type: Cardio Machines, Strength Equipment, Free Weights, Functional Training Tools |
| Companies Covered | Planet Fitness, Life Time Group Holdings, Equinox Holdings, 24 Hour Fitness, Basic-Fit, LA Fitness, Anytime Fitness, Crunch Fitness, RSG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Health and Fitness Club Market Emerging Trajectories
Technology deployment is bifurcating member expectations between immersive, data-rich experiences and frictionless, low-touch access. Operators must now serve both simultaneously.
Artificial intelligence-powered coaching platforms are bifurcating the personal training market. High-frequency gym users in the United States and United Kingdom are adopting algorithmic workout prescription at scale. This compression is displacing entry-level trainer roles while elevating demand for elite human specialists who manage complex rehabilitation and performance cases.
REACH chemical safety regulations in the European Union are mandating material disclosures for rubber flooring, foam mats, and resistance equipment polymers. Manufacturers serving Germany, France, and the Netherlands face reformulation costs or supplier switches. Club operators in these markets are accelerating procurement audits to preempt supply disruptions.
Subscription unbundling is fragmenting how consumers purchase fitness services. Boutique studio chains in California and New York are decoupling class packs from membership commitments. This model is spreading to Texas and Florida markets where consumers prefer pay-per-session flexibility over annual contracts.
Health and Fitness Club Market Segmentation
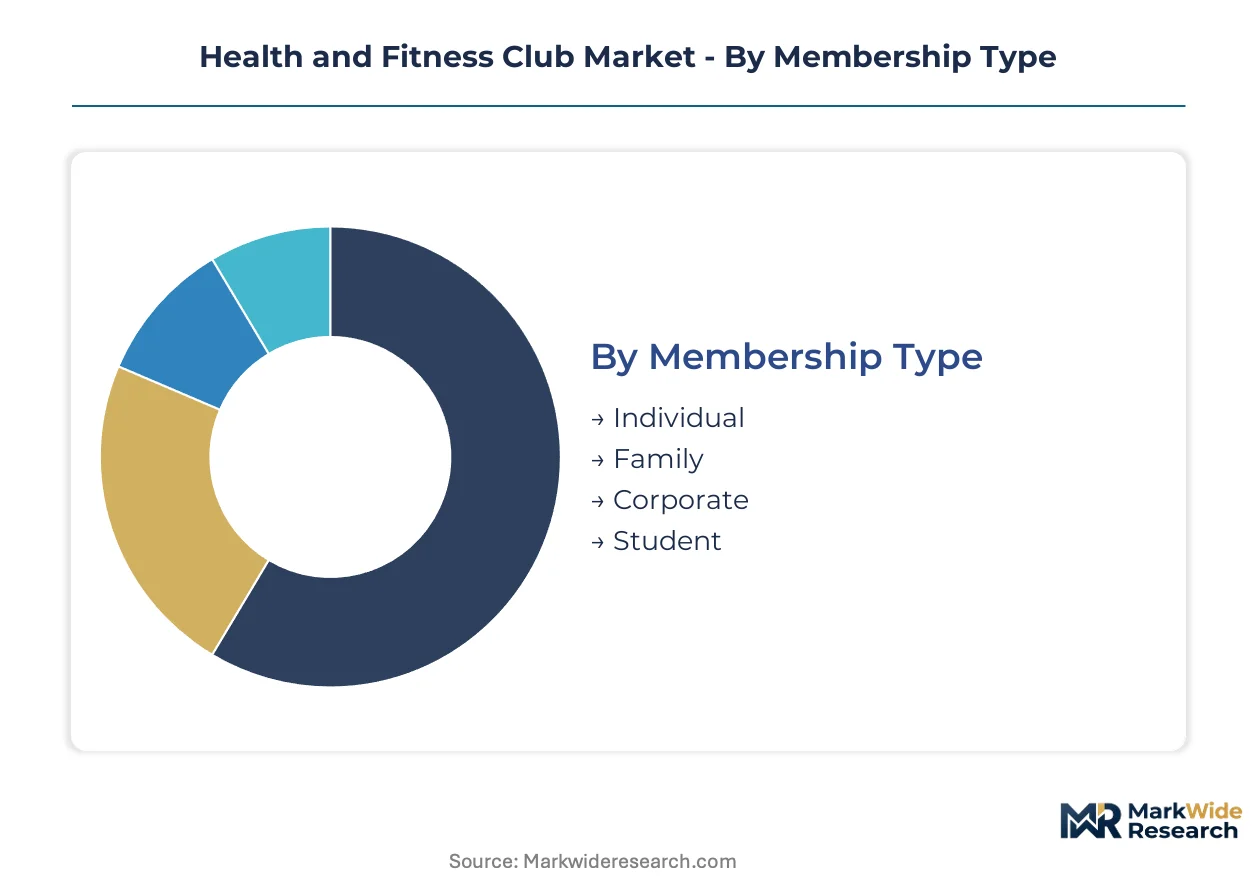
Segmentation in the health and fitness club market determines capital allocation, pricing architecture, and regulatory compliance pathways. Facility operators configure service portfolios around membership density, equipment depreciation schedules, and instructor certification requirements.
Membership Type:
Regulatory differentiation separates corporate-sponsored enrollments from individual contracts under US ERISA benefit rules and EU consumer protection directives. Tax treatment and subsidy eligibility vary sharply across these enrollment structures.
- Individual:Single-adult contracts dominate urban cores where young professionals prioritize schedule flexibility over household coordination. Demand concentrates in Shanghai, New York, and London where solo living rates exceed 35% and disposable income supports premium monthly dues.
- Family:Multi-generational plans bundle child-care amenities and youth programming to capture household budgets. Suburban operators in Texas, Florida, and Germany's Mittelstand towns favor this format for retention stability and higher lifetime value per account.
- Corporate:Employer-subsidized memberships channel volume through B2B procurement with standardized reporting for wellness ROI metrics.
- Student:Discounted academic-term contracts build early brand loyalty with price-sensitive cohorts.
Established volume favors Individual; emerging adoption favors Corporate.
Facility Type:
Cost tier stratification drives site selection, with land and construction costs dictating feasible service intensity per square meter.
- Commercial Gym:Large-format facilities deploy equipment density across 10,000+ square meter footprints to maximize membership throughput. Demand concentrates in China's tier-one cities where municipal zoning embeds fitness into mixed-use developments.
- Boutique Studio:Specialized formats in cycling, yoga, and HIIT command premium pricing through instructor charisma and community formation. Manhattan, Los Angeles, and London's Zone 1 districts support the highest concentration of single-discipline studios.
- Community Center:Public or nonprofit facilities serve price-sensitive populations with subsidized access.
- Hospital Gym:Clinical integration supports rehabilitation and chronic disease management under medical supervision.
Commercial Gym anchors revenue scale; Boutique Studio delivers steepest expansion trajectory in premium corridors.
Service Offering:
Margin concentration separates labor-intensive coaching from capital-intensive amenities, with per-session economics varying tenfold across the portfolio.
- Personal Training:One-on-one coaching generates the highest per-visit revenue through customized programming and accountability relationships. Demand concentrates in the United States and United Arab Emirates where disposable income supports $75-$150 hourly rates.
- Group Classes:Instructor-led sessions amortize labor costs across 20-40 participants, improving unit economics. Germany's fitness chains and California's studio networks have standardized formats that minimize choreography development costs.
- Nutrition Counseling:Registered dietitian services extend member lifetime value through lifestyle integration.
- Spa Services:Recovery amenities monetize downtime between workouts with high-margin ancillary spend.
Personal Training commands premium pricing; Group Classes enable volume scaling.
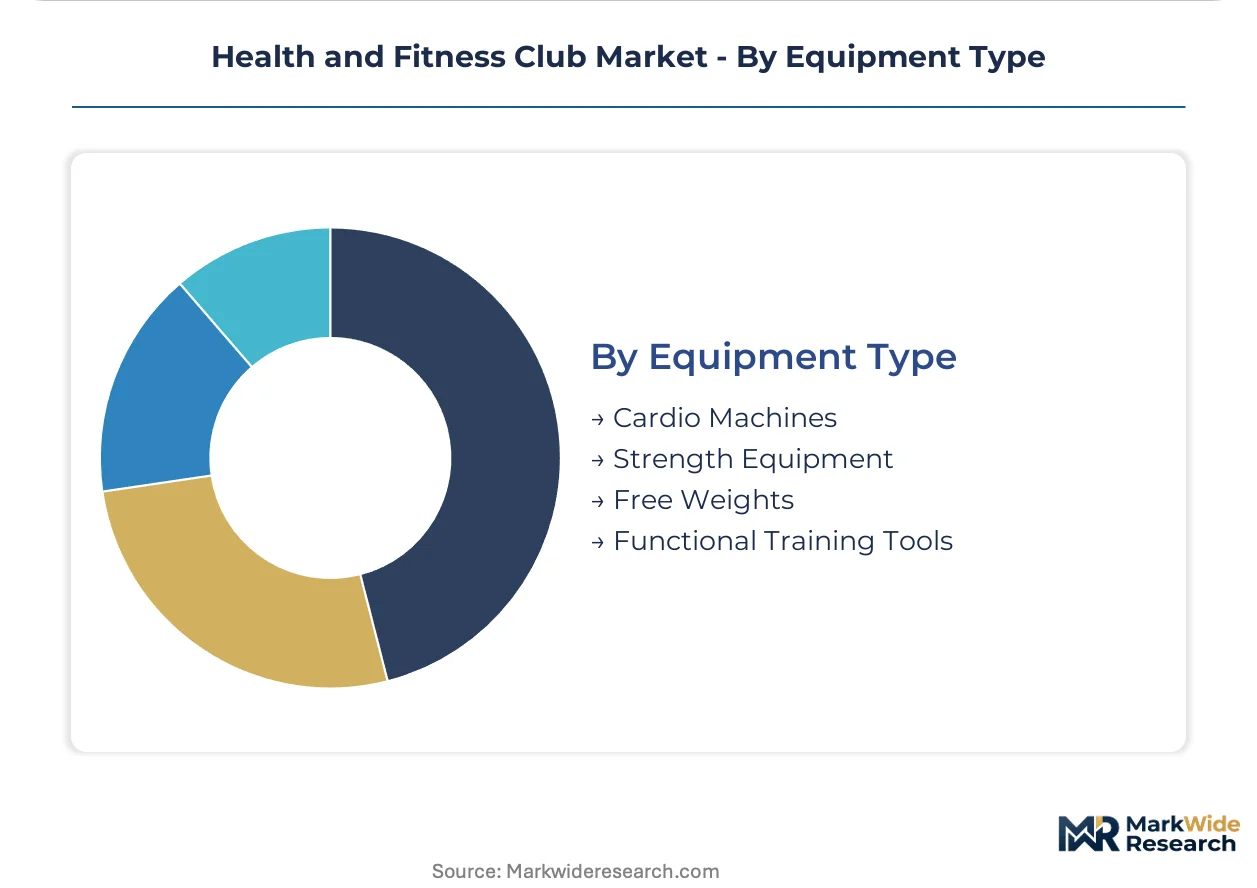
Equipment Type:
Supply concentration among German, Chinese, and US manufacturers shapes procurement costs and maintenance networks.
- Cardio Machines:Treadmills, ellipticals, and rowing stations dominate floor space allocation and energy consumption. Demand concentrates in commercial gyms across the United States and China where member throughput priorities favor reliable, low-maintenance units.
- Strength Equipment:Selectorized machines and plate-loaded stations require higher capital investment but lower replacement frequency. European operators in France and the Netherlands favor this category under REACH chemical safety mandates for polymer components.
- Free Weights:Dumbbell and barbell collections occupy minimal footprint with maximal durability.
- Functional Training Tools:Kettlebells, suspension trainers, and plyometric equipment support movement-based programming.
Cardio Machines anchor membership acquisition; Functional Training Tools gain share fastest in boutique formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States favors corporate-subsidized memberships and premium boutique formats. China concentrates investment in municipal-embedded commercial gyms within mixed-use developments. Germany emphasizes energy-efficient facility retrofits under EU environmental mandates.
United States
Corporate wellness mandates and Medicare Advantage fitness benefits channel volume into commercial networks. OSHA workplace safety standards govern employee protection across facility operations. Manhattan, Los Angeles, and Miami anchor boutique studio density where cycling and HIIT formats command premium pricing.
China
Municipal governments embed fitness facilities into residential-commercial clusters under urban health infrastructure programs. GB standards and dual carbon goals pressure HVAC and lighting efficiency upgrades. Shanghai, Beijing, and Shenzhen concentrate large-format commercial gyms within mixed-use zoning approvals.
Germany
EU Green Deal building codes accelerate energy retrofit investments that reduce long-term operating costs. REACH chemical safety regulations mandate material disclosures for rubber flooring and resistance equipment polymers. Berlin, Munich, and Hamburg anchor standardized club formats that control development costs across metropolitan corridors.
United Kingdom
Young professionals in urban cores prioritize schedule flexibility through individual membership contracts. GDPR compliance requirements shape biometric data handling from wearable fitness integrations. London's Zone 1 districts support the highest concentration of single-discipline boutique studios commanding premium rates.
India
Underdeveloped health infrastructure in secondary cities offers first-mover positioning for standardized club formats. BIS standards govern equipment safety and facility construction specifications. Pune, Jaipur, and Lucknow present expansion opportunities as urban health investment accelerates outside tier-one metros.
Health and Fitness Club Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the health and fitness club sector. Premium full-service operators compete on amenity density and real estate positioning. Budget franchise networks dominate price-sensitive markets through high-volume, low-touch models. European standardization specialists control development costs across scalable formats. Competitive moves concentrate on geographic expansion through franchise licensing and technology integration partnerships.
Within the premium-tier vector, Equinox Holdings occupies a position exemplifying high-amenity metropolitan positioning. Planet Fitness represents the budget-franchise archetype through its no-frills, high-volume operational model. Basic-Fit anchors the European standardization approach through cost-controlled, scalable club formats.
| Leading Market Players |
|---|
| Planet Fitness |
| Life Time Group Holdings |
| Equinox Holdings |
| 24 Hour Fitness |
| Basic-Fit |
| LA Fitness |
| Anytime Fitness |
| Crunch Fitness |
| RSG Group |
| Others |
Supply Flow & Price Mechanics
Rubber flooring and polymer mat substitution for traditional PVC surfaces is redrawing procurement geography toward REACH-compliant German and Dutch suppliers while elevating per-square-meter material costs for facility operators.
Pricing Analysis
Long-term corporate wellness contracts anchor revenue stability for commercial gym networks, with pricing stratifying across premium, standard, and economy tiers based on amenity density and location quality. Price differentiation hinges on urban real estate premiums and instructor certification tiers, with Manhattan and London operators commanding multiples over suburban franchise formats. Cost compression in budget segments is intensifying because Planet Fitness and Basic-Fit scale standardized footprints. Price-sensitive consumers cluster in student and family membership tiers, while corporate buyers prioritize reporting capabilities over rate negotiation.
Supply Chain Analysis
Equipment lead times from German, Chinese, and US manufacturers stretch 12-20 weeks for cardio machines with embedded biometric sensors. Supply draws from steel frame fabricators in China, polymer component specialists in Germany under REACH mandates, and electronics integrators in Taiwan. Single-source vulnerability concentrates in semiconductor chips for connected fitness consoles. Distribution runs through direct OEM relationships for large-format chains and regional distributors serving independent boutique studios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified personal trainer scarcity constrains expansion velocity for operators pursuing premium service tiers, compressing unit economics where human capital cannot scale.
For Market Incumbents: Shield market position by locking multi-year instructor employment contracts in Tier-II Indian cities before wage premiums emerge. Accelerate backward integration into proprietary wearable-CRM platforms to reduce dependence on Apple and Garmin data architectures. Counter digital-only substitutes through experiential programming that algorithmic platforms cannot replicate.
For New Entrants and Emerging Players: ACE and NASM certification fast-tracks unlock immediate staffing capacity in Pune and Jaipur where qualified instructor pools remain shallow. Penetrate Medicare Advantage-integrated senior fitness segments where reimbursement mechanisms reduce member acquisition friction. Pursue white-label corporate wellness partnerships rather than competing for individual subscription volume.
For Investors and Strategic Acquirers: EU Green Deal building code enforcement reshapes the acquisition landscape toward energy-retrofitted facility portfolios with lower operating cost trajectories. Target mid-scale operators with scalable formats and existing municipal zoning approvals. Monitor REACH chemical disclosure compliance velocity as a signal for supply chain disruption risk among European equipment suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Wearable-CRM Platform Integration | Biometric data convergence enables predictive retention interventions at Equinox and Life Time scale. |
| REACH-Compliant Material Sourcing | Polymer reformulation investments preempt supply disruptions for German and French facility operators. |
| Tier-II City Franchise Licensing | Standardized club formats capture first-mover positioning in Lucknow and Jaipur municipal developments. |
| Medicare Advantage Partnership | Insurer reimbursement riders open demographic white space for senior-focused facility networks. |
| Energy Retrofit Capital Deployment | HVAC and lighting upgrades reduce long-term operating costs under EU Green Deal mandates. |
Methodological Framework
The analysis maps commercial gyms, boutique studios, and corporate wellness programs, each validated through facility operations directors, certified personal trainers, municipal zoning officials, and equipment procurement managers. Primary fieldwork combined with secondary validation from OSHA workplace safety filings, EU Green Deal implementation reports, REACH chemical safety databases, and municipal development approval records. Bottom-up membership volume estimates triangulated against top-down health infrastructure investment flows across the analysis window.
Consistency checks validated volume and value outputs against IHRSA industry membership surveys and municipal fitness facility permitting data. Segmentation modeling incorporated facility type, membership structure, service offering intensity, and equipment technology tier across the projection horizon. CAGRs derived from historical facility development rates, urban health infrastructure budget trajectories, and corporate wellness program adoption curves. Wearable technology penetration and AI-powered coaching adoption served as demand-side forecast inputs.
Decision-makers should treat outputs as directional under sustained urban health infrastructure investment and stable corporate wellness subsidy policies; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gyms and Fitness Centers
Global Pilates and Yoga Studios Market
Gyms and Fitness Centers
Saudi Arabia Health and Fitness Club Market
Gyms and Fitness Centers
South Korea Health and Fitness Club Market
Gyms and Fitness Centers
Global Climbing Gym Market
Gyms and Fitness Centers
Southeast Asia Health and Fitness Club Market
Gyms and Fitness Centers
Boutique Fitness Studio Market
Gyms and Fitness Centers
South America Health and Fitness Club Market
Gyms and Fitness Centers
Europe Pilates & Yoga Studios Market
Gyms and Fitness Centers
Europe Climbing Gym Market
Gyms and Fitness Centers
Fitness and Recreational Sports Centers Market