
 Saudi Arabia Health and Fitness Club Market | 2026-2036
Saudi Arabia Health and Fitness Club Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Health and Fitness Club Market Analytics
Market Context with Strategic Players
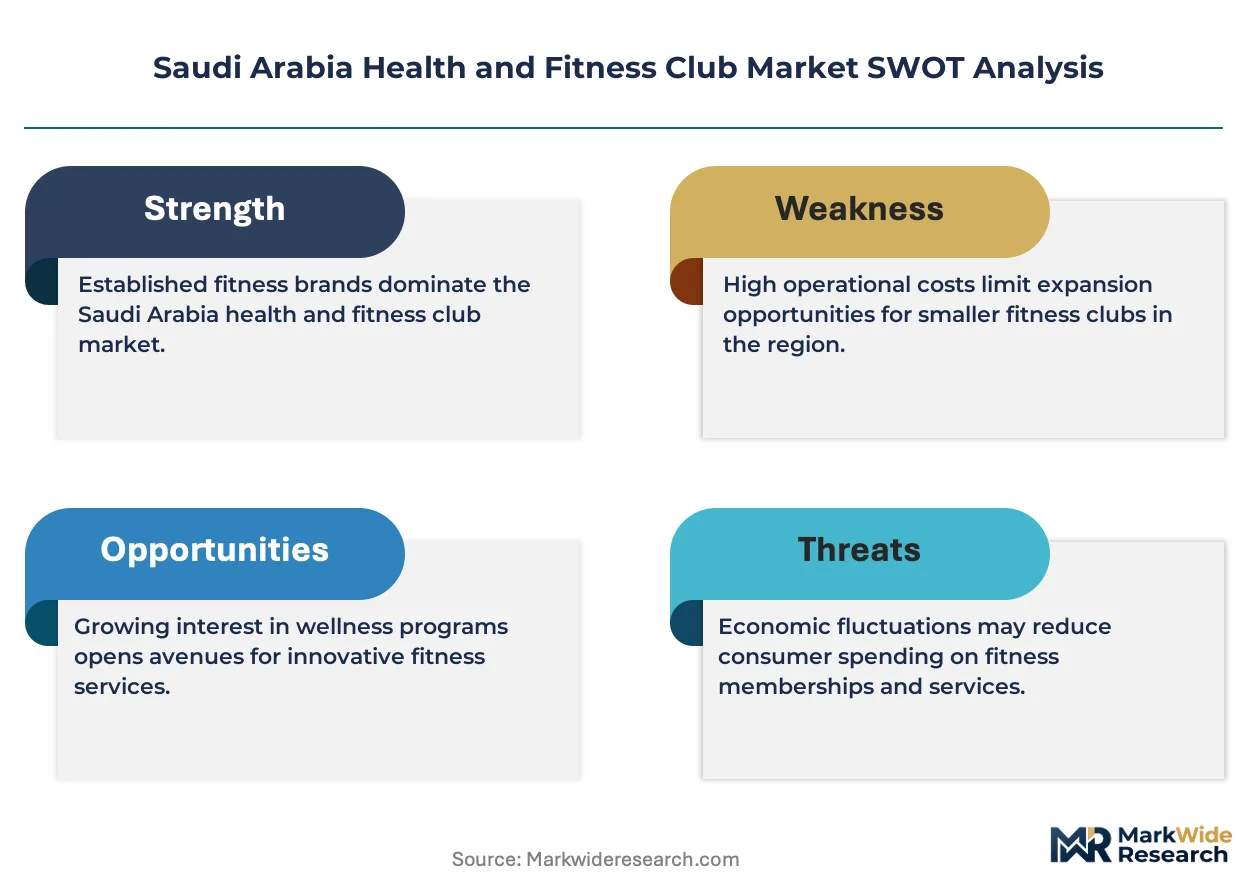
Digital wearable integration is tilting how Saudi fitness clubs design member engagement and retention protocols. Leejam Sports Company leverages its multi-city footprint to sustain dominant coverage across the Kingdom's urban corridors. World Gym International LLC anchors its competitive stance through equipment standardization and trainer certification rigor. Fitness Time differentiates via female-only facilities that comply with cultural preferences while expanding accessible capacity.
Technical Definition and Structural Segments
The Saudi Arabia health and fitness club sector comprises commercial and semi-commercial facilities providing structured physical training, recovery services, and wellness programming across equipment-based, group-format, and individualized delivery modes. These operations typically span 2,000 to 15,000 square meters, incorporate cardiovascular and resistance training zones, and generate recurring revenue through subscription-based access models. Membership type segmentation shows corporate packages capturing sustained bulk commitments from employers investing in workforce wellness. Service offering stratification reveals personal training and nutritional counseling commanding premium pricing relative to standard floor access. Facility type dynamics position specialty fitness centers and CrossFit boxes as fastest-growing formats against the mature gym category.
Regulatory Framework and Forward Outlook
The General Authority for Sports oversees facility licensing and instructor credentialing, while the Saudi Food and Drug Authority monitors nutritional supplement retail within club premises. SFDA registration requirements for on-site protein and supplement sales create compliance thresholds that filter smaller operators. Municipal zoning boards in Riyadh, Jeddah, and Dammam regulate land use classifications for mixed-gender versus gender-segregated facilities. Stakeholders must monitor how evolving sports privatization policies and foreign investment licensing reshape competitive entry rules.
Market Dynamics
Corporate wellness mandates are compressing sales cycles for Saudi fitness operators as employers seek bulk membership contracts to reduce workforce healthcare expenditure. This demand concentration is forcing facility operators to reconfigure pricing models and service tiers around enterprise procurement rather than individual subscription economics.
Growth Catalysts
- SFDA Nutrition Labeling Standards:Mandatory disclosure requirements for on-site supplement retail are professionalizing product merchandising and elevating consumer trust in club-sourced nutrition products.
- Riyadh-Jeddah Urban Concentration:Premium real estate development in these metropolitan corridors is creating purpose-built fitness infrastructure with integrated recovery and wellness amenities.
- Biometric Wearable Integration:Continuous glucose monitors and heart-rate variability trackers are enabling data-driven personalization that extends member engagement beyond facility walls.
Market Restraints
- Land Cost Escalation:Municipal zoning premiums in Riyadh's northern districts and Jeddah's waterfront zones are inflating facility development breakeven thresholds.
- Gender-Segregation Compliance:General Authority for Sports licensing requirements for parallel facility infrastructure effectively double capital requirements for mixed-market operators.
- Trainer Certification Bottleneck:Limited accredited instruction capacity under the National Qualifications Framework is constraining service expansion velocity.
Strategic Opportunities
- Eastern Province Undersupply:Dammam and Al-Khobar currently operate at half the fitness facility density of Riyadh, presenting first-mover expansion potential.
- Recovery Service Integration:Cryotherapy, hydrotherapy, and sleep optimization programming command 40-60% premium pricing over standard membership access.
- Neom Development Zone:The giga-project's wellness-city mandate is creating captive demand for integrated fitness infrastructure with guaranteed occupancy floors.
Industry Challenges
- Specialized Instructor Scarcity:Certified strength-and-conditioning coaches and registered dietitians remain concentrated in Riyadh, forcing secondary-market operators to absorb relocation premiums.
- Legacy System Integration:Enterprise resource planning migration from basic POS systems to unified member-management platforms is disrupting billing continuity and data migration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Health and Fitness Club Market |
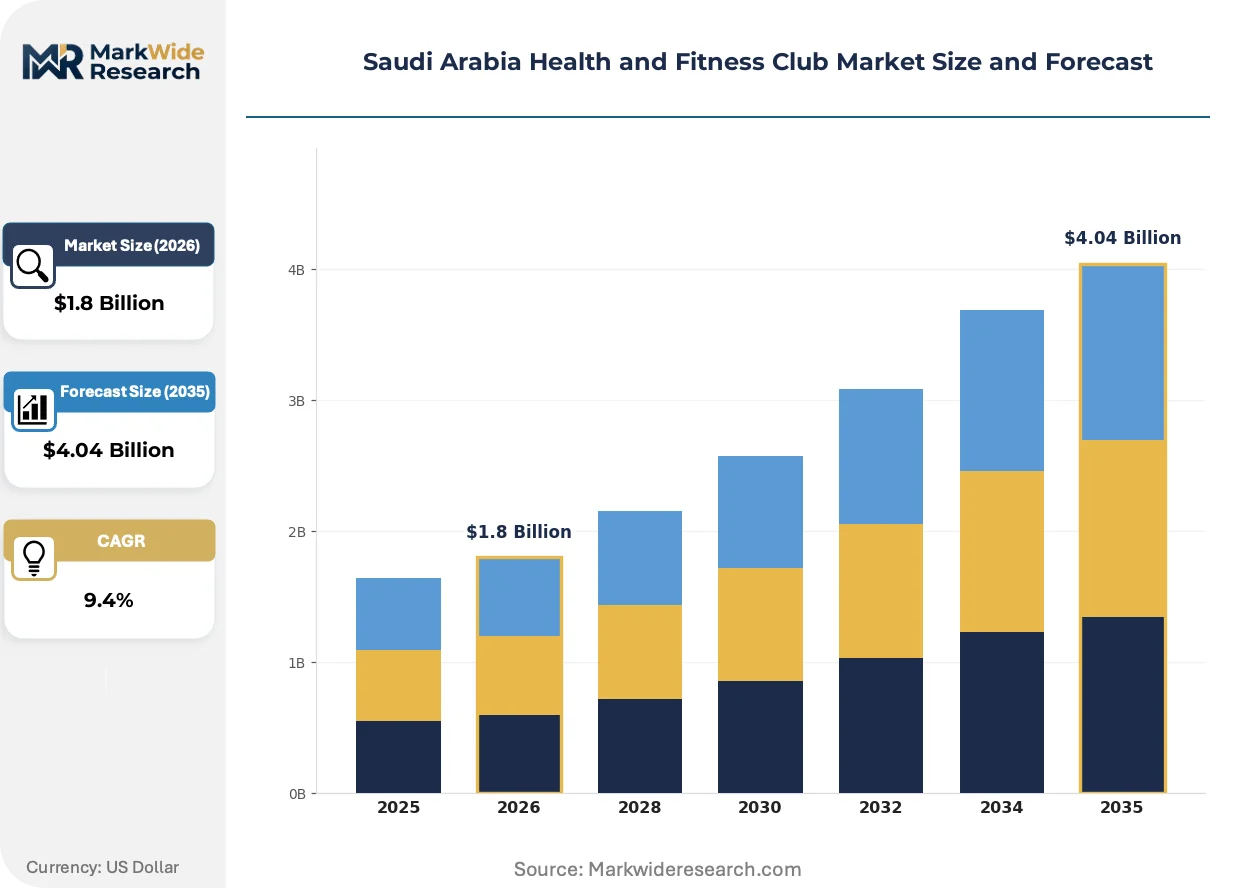
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Membership Type: Individual, Family, Corporate, Student Service Offering: Group Classes, Personal Training, Nutritional Counseling, Massage Therapy Facility Type: Gym, Yoga Studio, Specialty Fitness Center, CrossFit Box Gender Target: Male, Female, Co-ed, Family-Friendly |
| Companies Covered | World Gym International LLC, Leejam Sports Company, Fitness Time, NuYu Fitness, RSG Group GmbH, GymNation LLC, Landmark Group, Arena Fitness Centers KSA, Gold's Gym Saudi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Health and Fitness Club Market Evolving Landscape
Data-driven personalization is displacing standardized programming as the primary member retention mechanism across Saudi fitness operations. This shift is compressing the competitive relevance of equipment-heavy facilities while elevating operators with integrated digital-physical service architectures.
Artificial intelligence-powered movement analysis is migrating from boutique rehabilitation clinics to mainstream commercial gym floors. Leejam Sports and Fitness Time are deploying computer-vision form correction across select Riyadh locations. This technology is compressing the personal training addressable market while expanding scalable coaching capacity.
The General Authority for Sports is tightening instructor credentialing reciprocity standards for qualifications obtained outside the Kingdom. Foreign-certified trainers now face supplementary assessment requirements before licensure. This regulatory friction is most acute for operators recruiting from European and North American talent pools, forcing accelerated investment in domestic certification pipelines.
Employer-sponsored wellness procurement is consolidating individual membership acquisition channels. Human resource departments are negotiating multi-year corporate packages that displace direct-to-consumer marketing spend. This concentration is most visible among petrochemical and financial services employers in the Eastern Province, where workforce wellness metrics tie to insurance premium negotiations.
Saudi Arabia Health and Fitness Club Market Segmentation
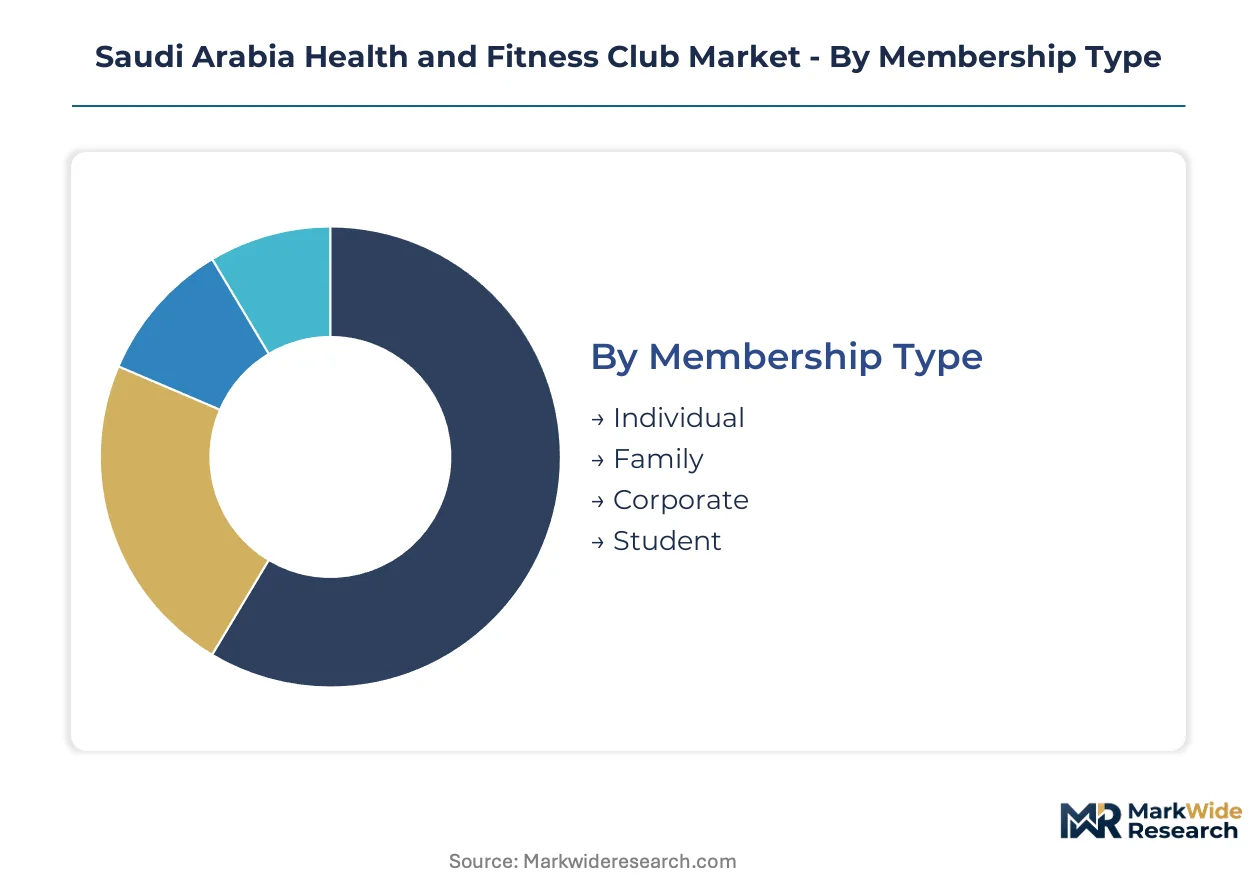
Saudi fitness operators configure service architectures around four intersecting dimensions that determine capital deployment, staffing models, and pricing power. Segmentation discipline separates facilities capturing premium recovery margins from volume-driven competitors competing on access convenience.
Membership Type:
Mature individual subscriptions coexist with emerging corporate procurement channels that reshape operator economics.
- Individual:Single-user subscriptions deliver the highest per-member revenue but carry elevated churn risk. Riyadh's northern districts concentrate demand from young professionals seeking flexible access without household commitment.
- Corporate:Employer-bundled packages generate predictable recurring revenue and compress acquisition costs. Eastern Province petrochemical employers negotiate multi-year contracts tied to workforce wellness metrics.
- Family:Multi-user household plans expand addressable revenue per sales interaction. Jeddah's family-oriented suburban developments drive concentration here.
- Student:Discounted academic-term access builds early loyalty pipelines. University corridor locations in Riyadh and Dammam anchor this segment.
Corporate memberships retain volume leadership; student plans hold the steepest expansion curve.
Service Offering:
Cost tier stratification separates premium human-delivered services from scalable programming.
- Personal Training:One-on-one coaching commands 200-300% pricing premiums over floor access. Certified strength-and-conditioning specialists concentrate in Riyadh, forcing secondary-market operators to absorb relocation premiums.
- Nutritional Counseling:Registered dietitian services integrate with SFDA compliance requirements for on-site supplement retail. Demand concentrates among corporate wellness programs seeking measurable health outcomes.
- Group Classes:Scalable instructor-to-member ratios improve facility utilization during off-peak hours. Les Mills and similar licensed formats dominate scheduling in Leejam and Fitness Time locations.
- Massage Therapy:Recovery services extend dwell time and ancillary spend per visit. Premium clubs in Jeddah's waterfront zones package this with hydrotherapy access.
Group classes retain volume leadership; nutritional counseling holds the steepest expansion curve.
Facility Type:
Application-driven format selection determines equipment mix, square footage requirements, and member acquisition strategy.
- Gym:Full-service facilities spanning 5,000-15,000 square meters with comprehensive equipment floors. Riyadh and Jeddah host the densest concentration of mature branded chains.
- Specialty Fitness Center:Boutique formats targeting specific modalities—cycling, Pilates, boxing—deliver premium pricing through experience differentiation. Al-Khobar's underserved market presents first-mover expansion potential.
- Yoga Studio:Low-capital footprint operations emphasizing instructor quality over equipment density. Female-only configurations align with cultural preferences in conservative districts.
- CrossFit Box:High-intensity functional training facilities with community-driven retention mechanics. Affiliation fees and coach certification requirements filter operator entry.
Gyms retain volume leadership; specialty fitness centers hold the steepest expansion curve.
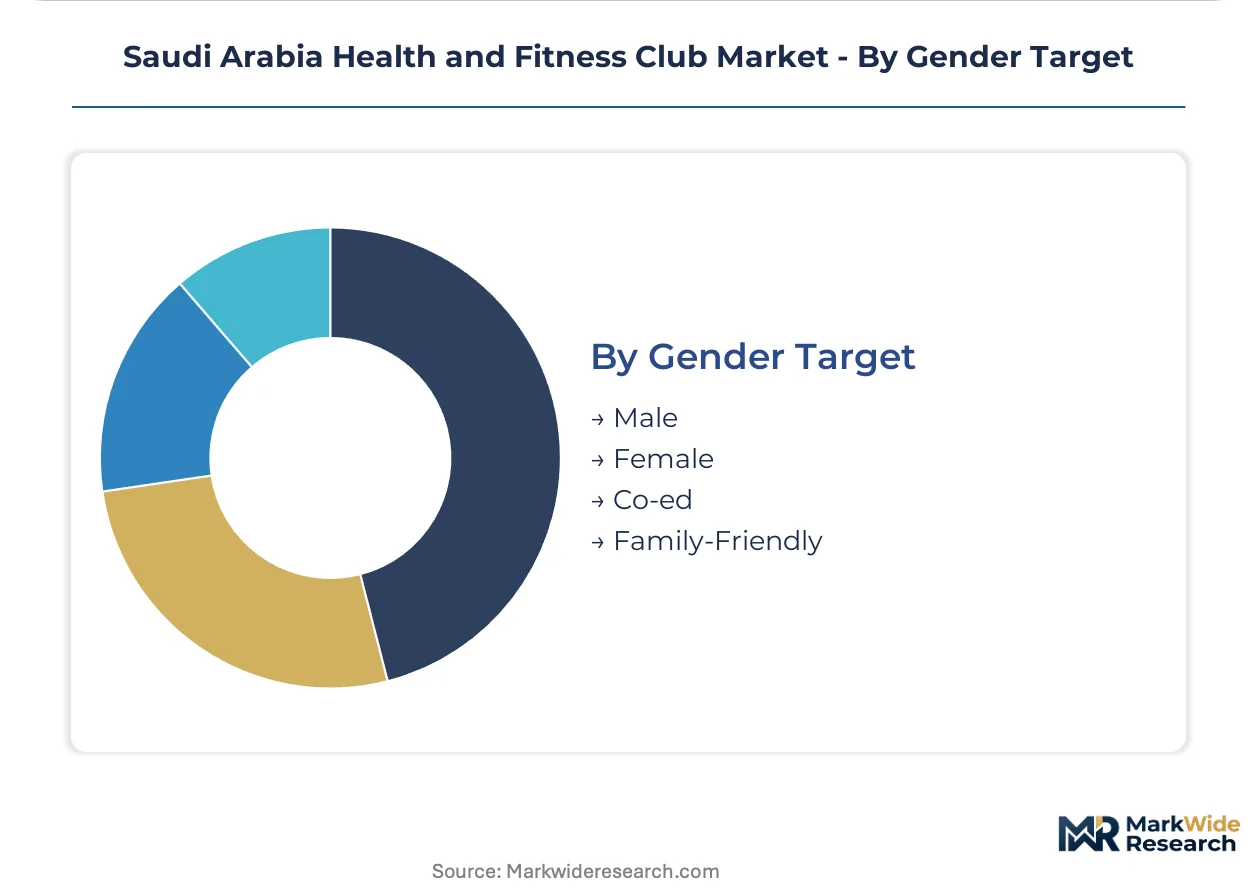
Gender Target:
Customer-type segmentation reflects regulatory compliance architecture and facility design requirements.
- Female:Women-only facilities operate under distinct General Authority for Sports licensing with separate infrastructure mandates. Fitness Time has built dominant coverage through this format.
- Male:Traditional men's facilities face compressed differentiation as co-ed alternatives expand. Legacy operators in Dammam maintain share through established neighborhood positioning.
- Co-ed:Mixed-gender access requires parallel facility zones or staggered operating hours. Municipal zoning boards in Riyadh regulate land use classifications strictly here.
- Family-Friendly:Segmented scheduling accommodates household units with children. Suburban mall-anchored locations in Jeddah capture this demand.
Female-targeted facilities retain volume leadership; family-friendly formats hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's fitness infrastructure exports wellness programming and operational models across the Gulf Cooperation Council corridor, with Riyadh-based operators licensing formats to Dubai and Kuwait City buyers.
Riyadh
Corporate headquarters concentration and Vision 2030 workforce localization programs are driving employer-sponsored wellness procurement. The General Authority for Sports enforces strict facility licensing and instructor credentialing standards. Northern district developments host the densest concentration of premium clubs with integrated recovery amenities.
Eastern Province
Petrochemical sector employers negotiate multi-year corporate wellness contracts tied to insurance premium reductions. Municipal zoning boards in Dammam regulate land use for gender-segregated versus mixed-gender facilities. Al-Khobar operates at half the fitness facility density of Riyadh, presenting first-mover expansion potential.
Western Region
Jeddah's waterfront real estate development is creating purpose-built fitness infrastructure with premium positioning. The Saudi Food and Drug Authority monitors nutritional supplement retail within club premises. Suburban mall-anchored locations capture family-oriented demand through segmented scheduling.
NEOM Northwest
The giga-project's wellness-city mandate is generating captive demand for integrated fitness infrastructure with guaranteed occupancy floors. Foreign investment licensing frameworks are reshaping competitive entry rules for international operators. The development zone prioritizes biometric wearable integration and AI-powered service delivery.
Saudi Arabia Health and Fitness Club Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct facility formats and membership models. The Saudi market exhibits moderate consolidation around multi-city operators with established brand recognition. Three archetypes dominate: scale-driven national chains with standardized equipment floors, culturally-adapted specialists operating female-only facilities, and premium boutique formats targeting recovery services. Competitive intensity centers on geographic expansion into undersupplied secondary markets and integration of digital personalization technologies.
Among Saudi-based operators, Leejam Sports Company and Fitness Time exemplify contrasting strategic positions. Leejam occupies the scale-driven archetype through multi-city footprint coverage. Fitness Time anchors the culturally-adapted specialist tier through female-only facility configurations. World Gym International LLC represents the international brand-licensing model with equipment standardization emphasis.
| Leading Market Players |
|---|
| World Gym International LLC |
| Leejam Sports Company |
| Fitness Time |
| NuYu Fitness |
| RSG Group GmbH |
| GymNation LLC |
| Landmark Group |
| Arena Fitness Centers KSA |
| Gold's Gym Saudi |
| Others |
Value Network & Pricing Analysis
Regulatory chokepoint exposure through SFDA supplement registration requirements determines both pricing tier spreads and supply chain shape. Facilities absorbing compliance costs for on-site protein retail must recapture through premium service bundling, while operators avoiding this threshold compete purely on access convenience.
Pricing Analysis
Equipment-generation pricing gaps separate AI-enabled biometric facilities from legacy equipment floors. Three-tier pricing structure across premium recovery-integrated, standard full-service, and economy access-only levels dominates membership architecture. Price differentiation hinges on trainer certification tier under the National Qualifications Framework and biometric wearable integration depth. Pricing pressure stems from corporate procurement consolidation as Eastern Province petrochemical employers negotiate multi-year workforce wellness contracts. Student segments exhibit highest price sensitivity; corporate bundles demonstrate lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates fitness equipment sourcing risk for Saudi operators. Commercial-grade cardiovascular and resistance equipment concentrates manufacturing in China, the United States, and Germany. Raw material dependencies span steel framing, electronic control systems, and synthetic flooring compounds. Single-source vulnerability concentrates in computer-vision movement analysis software licensed from North American providers. Distribution runs through Riyadh-based equipment distributors with Jeddah satellite warehousing for Western Region fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's health and fitness club sector represents a high-growth disruption anchored by biometric wearable integration and AI-powered service delivery. The General Authority for Sports' evolving credentialing reciprocity standards create regulatory inflection that rewards domestic capability building.
For Market Incumbents: Pre-empt corporate wellness procurement consolidation by securing multi-year employer contracts before competitor saturation in the Eastern Province. Leejam Sports Company and Fitness Time should accelerate certified trainer pipeline investment under the National Qualifications Framework to offset foreign credentialing friction. Defensive positioning requires backward integration into recovery service infrastructure—cryotherapy and hydrotherapy equipment—to capture 40-60% premium pricing over standard membership access. For New Entrants and Emerging Players: Establish a beachhead in Al-Khobar's specialty fitness center gap, where facility density runs at half Riyadh levels. Female-only boutique formats aligned with Fitness Time's proven cultural adaptation model offer penetrable white-space. Recovery service integration—sleep optimization and nutritional counseling—provides differentiated go-to-market positioning against equipment-heavy incumbents. For Investors and Strategic Acquirers: The market sits at an early-consolidation phase that favors scale-driven national chains with integrated digital-physical architectures. Long-term viability over a 5-10 year window hinges on corporate wellness channel control and biometric data platform ownership. Acquisition target archetype: regional operators with established municipal zoning approvals in Riyadh's northern districts. The signal to watch is General Authority for Sports foreign investment licensing liberalization as sports privatization policy evolves.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Movement Analysis Deployment | Leejam Sports' computer-vision form correction compresses personal training addressable market while expanding scalable coaching capacity. |
| Corporate Wellness Contract Securement | Multi-year employer packages with Eastern Province petrochemical firms lock predictable recurring revenue and compress acquisition costs. |
| Recovery Service Infrastructure Buildout | Cryotherapy and hydrotherapy integration at Jeddah waterfront facilities commands premium pricing and extends member dwell time. |
| Domestic Trainer Certification Pipeline | Accelerated investment under National Qualifications Framework offsets foreign credentialing reciprocity friction from European and North American talent pools. |
| Neom Development Zone Entry | Guaranteed occupancy floors within the giga-project's wellness-city mandate de-risk capital deployment for integrated fitness infrastructure. |
Research Methodology
Initial hypotheses were tested against primary input from club operations directors, corporate wellness procurement managers, General Authority for Sports licensing officials, and fitness equipment distributors and refined through secondary validation. Club operations directors provided facility utilization metrics and member retention mechanics. Corporate wellness procurement managers disclosed contract negotiation parameters and workforce wellness metric linkages. General Authority for Sports officials clarified instructor credentialing and facility licensing standards. Fitness equipment distributors detailed import logistics and tariff exposure patterns. Secondary sources included SFDA regulatory filings, municipal zoning board records from Riyadh and Jeddah, and National Qualifications Framework certification data. Bottom-up facility count triangulation against top-down market value estimates anchored size calculations.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled encompass membership type, service offering tier, facility format, and gender-target configuration. Corporate procurement velocity and biometric wearable adoption curves served as industry-specific forecast inputs. CAGRs were derived from time-series regression against macroeconomic proxies and sector-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in oil revenue cycles and expatriate workforce composition would shift the trajectory. Forecasts reflect underlying assumptions about Vision 2030 sports privatization continuity and SFDA regulatory stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gyms and Fitness Centers
Global Pilates and Yoga Studios Market
Gyms and Fitness Centers
Global Climbing Gym Market
Gyms and Fitness Centers
Europe Pilates & Yoga Studios Market
Gyms and Fitness Centers
Southeast Asia Health and Fitness Club Market
Gyms and Fitness Centers
Health and Fitness Club Market
Gyms and Fitness Centers
Boutique Fitness Studio Market
Gyms and Fitness Centers
Fitness and Recreational Sports Centers Market
Gyms and Fitness Centers
South America Health and Fitness Club Market
Gyms and Fitness Centers
Europe Climbing Gym Market
Gyms and Fitness Centers
South Korea Health and Fitness Club Market