
 South Korea Health and Fitness Club Market | 2026-2036
South Korea Health and Fitness Club Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Health and Fitness Club Market Insights
Multi-vendor service procurement is shifting toward integrated wellness platforms across South Korean fitness operators. Samsung Leports Center leverages its corporate parentage to anchor large-format facility networks in Seoul and Busan. Fit Club Seoul competes through specialized group programming that differentiates its boutique positioning from mass-market chains. James Gym Fitness Center sustains member retention through personalized training protocols that dominate the premium segment in capital-region suburbs.
The South Korea health and fitness club industry encompasses facilities delivering structured physical training, recovery services, and wellness programming through equipment-based and instructor-led modalities, typically operating on 2,000–15,000 square meter footprints with ventilation rates mandated at 30 cubic meters per hour per person under indoor air quality codes. Facility type segmentation reveals full-service gyms occupying the largest revenue pool through all-inclusive membership structures, while boutique studios capture disproportionate margins via pay-per-class pricing models that attract young professionals seeking specialized modalities. Service type segmentation shows personal training generating the highest per-member revenue, though group classes drive volume acquisition through lower entry barriers and social retention mechanics.
MFDS guidelines on health functional foods intersect with nutrition counseling services, while the Korea Health Promotion Act shapes facility certification requirements that operators must satisfy for tax incentive eligibility. KOSHA workplace wellness standards create compliance obligations for corporate gym installations serving employee populations. Stakeholders must monitor how municipal zoning in Seoul, Busan, and Daegu affects new club permits as district governments tighten commercial fitness density limits.
Market Dynamics
Corporate wellness buyers are consolidating vendor relationships into single-platform contracts, compressing procurement cycles and elevating integrated service providers over standalone gym operators across South Korea's fitness landscape.
Growth Catalysts
- MFDS wellness guidelines:Facility certification requirements under these standards unlock tax incentive eligibility for compliant operators, accelerating capital investment in premium locations.
- Seoul metropolitan density:Concentration of young professionals in Gangnam and Seongdong districts sustains pay-per-class boutique demand that outpaces national membership growth rates.
- KOSHA workplace standards:Mandatory employee health provisions drive corporate gym installations at manufacturing and technology campuses, creating captive member bases with lower churn.
Market Restraints
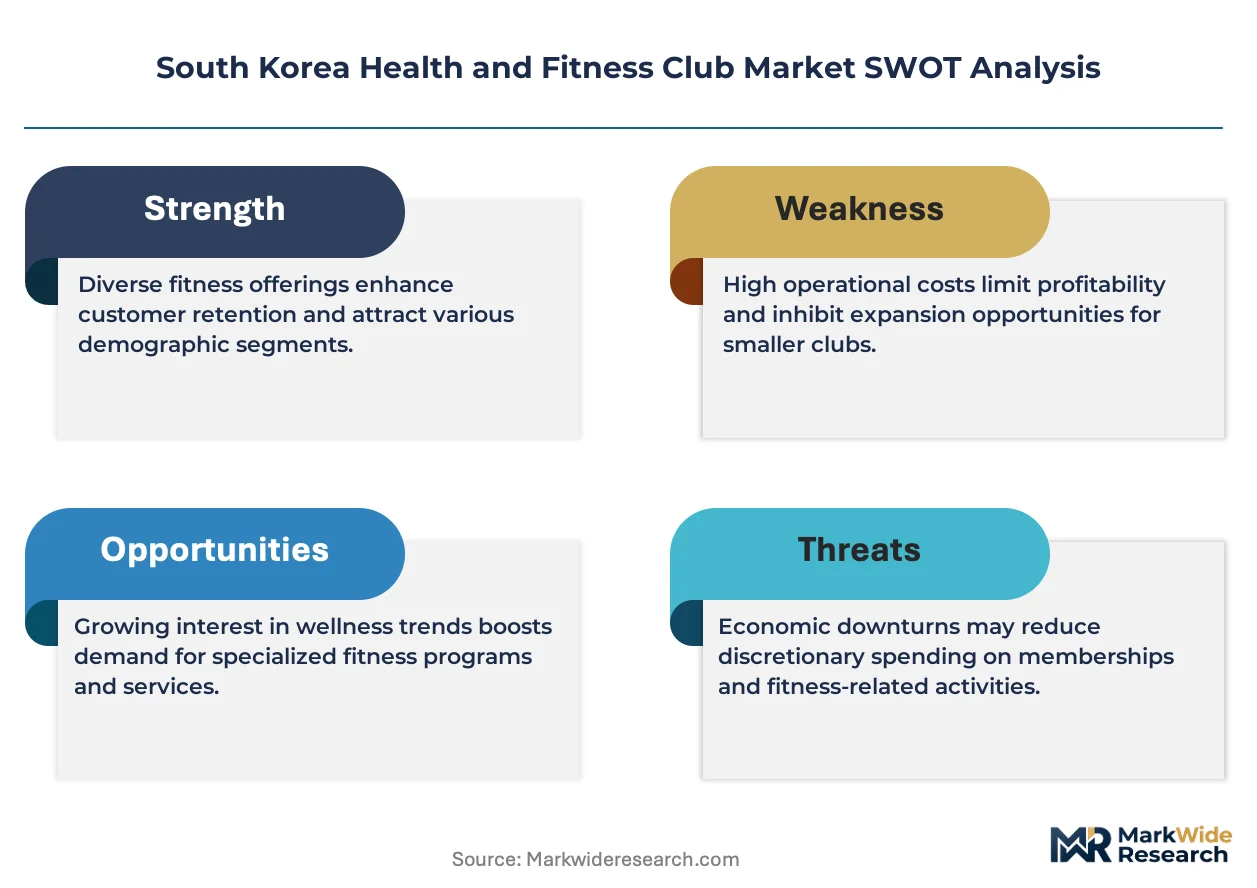
- Commercial real estate costs:Prime Seoul retail space commands premiums that compress operator margins below sustainable thresholds for independent facilities under 500 square meters.
- Ventilation infrastructure:Korea Health Promotion Act mandates of 30 cubic meters per hour per person require HVAC retrofits that add 15-20 percent to facility buildout costs.
- Substitute wellness modalities:Outdoor cycling collectives and home-based digital fitness platforms capture discretionary spending from price-sensitive demographics.
Strategic Opportunities
- Busan secondary market:Underserved premium segments in Korea's second-largest city present first-mover advantages for boutique concepts replicating Seoul's Seongdong cluster model.
- Recovery service integration:Cryotherapy and compression therapy convergence with traditional strength training creates service bundles that command 40-60 percent membership premiums.
- Municipal wellness grants:District government programs in Daegu and Gwangju subsidize facility permits for operators meeting community health access targets.
Industry Challenges
- Specialized instructor certification:MFDS-recognized nutrition counseling credentials require 18-month training pipelines that outpace hiring demand at expanding chains.
- Legacy membership system migration:Established operators face 12-18 month integration timelines when transitioning from on-premise servers to cloud-based access control platforms.
- Air quality compliance documentation:Continuous monitoring equipment and quarterly third-party verification create recurring administrative burdens for multi-location operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Health and Fitness Club Market |
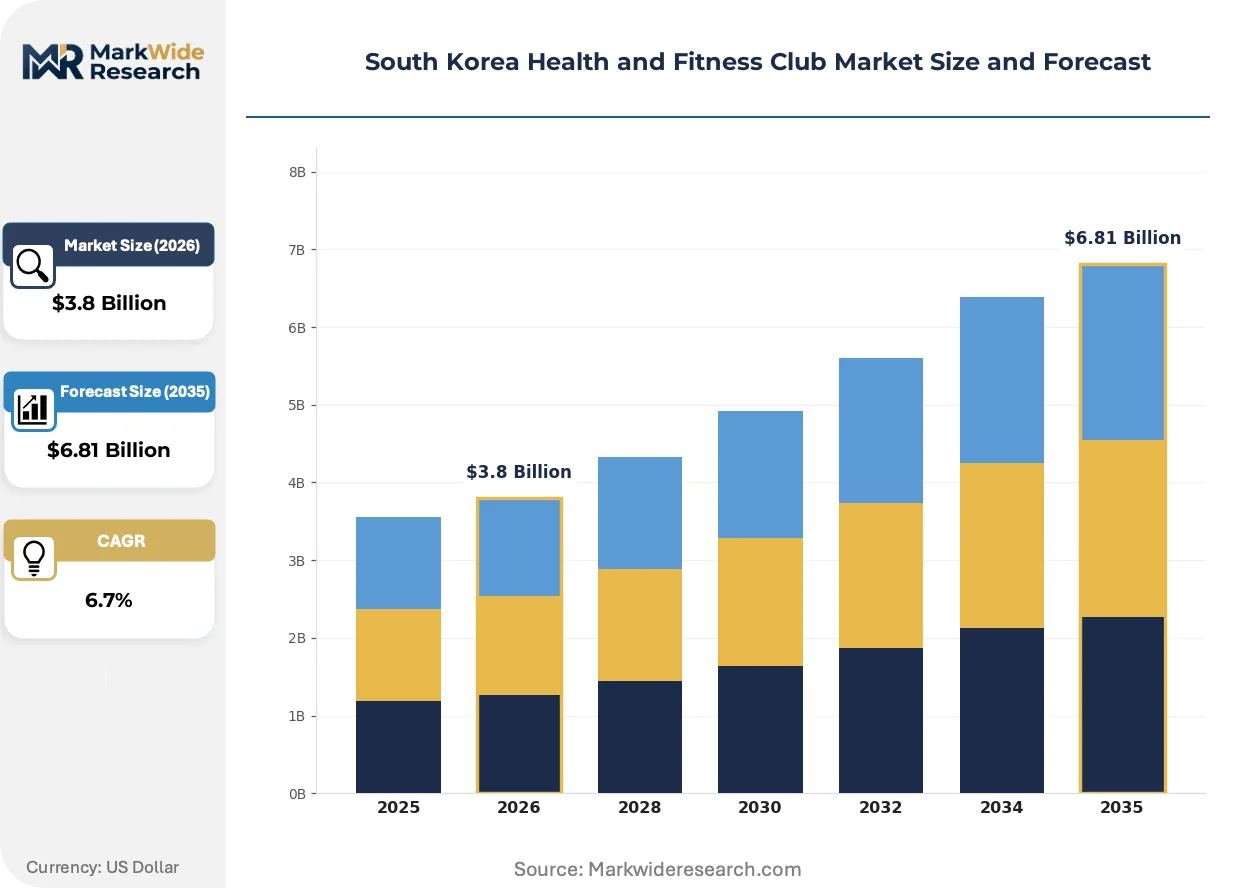
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Personal Training, Group Classes, Nutrition Counseling, Wellness Programs Facility Type: Full-Service Gym, Boutique Studio, Corporate Gym, Community Center Pricing Model: Membership Fee, Pay-Per-Class, Group Discounts, Trial Offers Target Demographic: Young Professionals, Families, Seniors, Students |
| Companies Covered | James Gym Fitness Center, Punho Boxing Club, Fit Club Seoul, Lfl Co. Ltd (4tp Fitness), N&Company Goto, Samsung Leports Center, Star Kali Fitness, 10th Planet Jiu Jitsu Seoul, Hit Fit Boxing Lounge, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Health and Fitness Club Market Trends and Innovations
Biometric feedback systems and AI-assisted coaching platforms are compressing the personalization gap between boutique studios and mass-market chains, reshaping how South Korean operators differentiate member experience.
AI-powered movement analysis is integrating into strength training equipment across premium Seoul facilities. Boutique operators in Gangnam deploy computer-vision form correction that reduces injury liability while enabling higher trainer-to-member ratios. This technology is integrating previously manual coaching functions into hardware, allowing mid-tier clubs to offer personalized protocols without dedicated personal training staff.
MFDS guidelines on health functional foods are expanding facility compliance obligations beyond physical infrastructure into nutrition counseling services. Operators must now document supplement recommendation protocols to maintain wellness certification status. Full-service gyms with integrated cafés face the steepest adaptation requirements as food service and fitness programming converge under single regulatory frameworks.
Corporate procurement teams are consolidating wellness vendor relationships from multi-club arrangements into exclusive platform partnerships. Technology sector employers in Pangyo and Songdo lead this consolidation, replacing reimbursement-based programs with on-site facility access. Busan manufacturing campuses follow this pattern as KOSHA compliance deadlines approach, favoring operators with occupational health expertise over general fitness brands.
South Korea Health and Fitness Club Market Segmentation
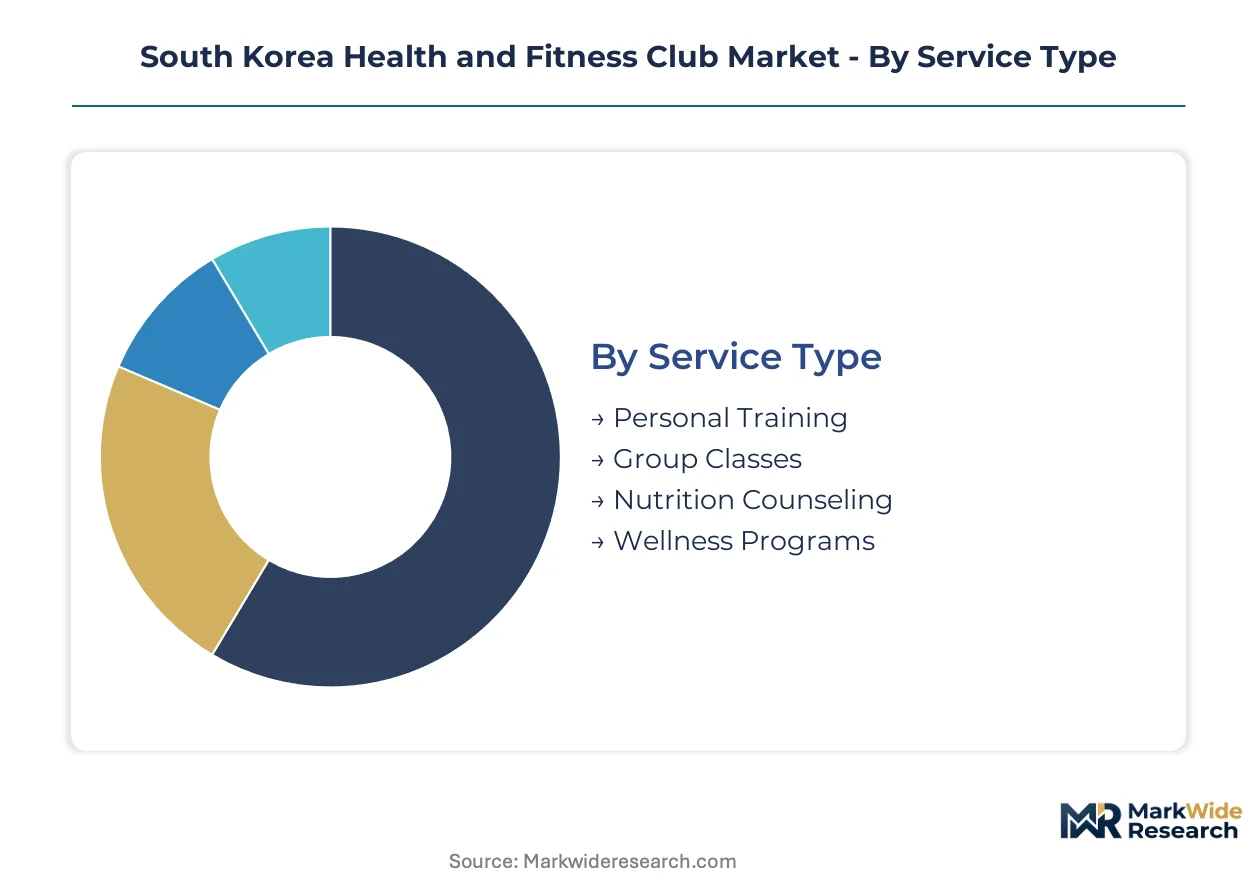
South Korean fitness operators configure service portfolios around distinct member acquisition economics and retention mechanics. Facility investments, pricing architectures, and demographic targeting strategies diverge sharply across Seoul's premium districts versus secondary metropolitan markets.
Service Type:
Buyer differentiation hinges on willingness to pay for individualized attention versus social engagement formats.
- Personal Training:One-on-one coaching protocols generate the highest per-member revenue through customized programming and accountability relationships. Demand concentrates in Gangnam and Seongdong premium facilities where professionals seek time-efficient results. MFDS wellness certification requirements for nutrition-adjacent coaching elevate credential barriers.
- Group Classes:Instructor-led sessions in cycling, yoga, and HIIT formats drive volume acquisition through lower entry costs and peer retention mechanics. Boutique studios in Seoul's young professional corridors rely on pay-per-class models that outpace traditional membership growth rates.
- Nutrition Counseling:Dietary planning services integrated with training protocols require 18-month MFDS-recognized credential pipelines.
- Wellness Programs:Holistic health packages combining fitness, recovery, and lifestyle coaching attract corporate wellness buyers consolidating vendor relationships.
Volume sits with Group Classes; growth tilts toward Personal Training.
Facility Type:
Capital intensity and real estate exposure separate scalable network operators from specialized location-dependent concepts.
- Full-Service Gym:Large-format facilities spanning 2,000–15,000 square meters deliver all-inclusive membership structures with equipment-based and instructor-led modalities. Korea Health Promotion Act ventilation mandates at 30 cubic meters per hour per person inflate buildout costs for independent operators under 500 square meters.
- Boutique Studio:Specialized concepts in cycling, pilates, or barre capture disproportionate margins through pay-per-class pricing and premium location clustering. Seongdong district density sustains highest concentration nationally.
- Corporate Gym:On-site installations at manufacturing and technology campuses serve captive employee populations with lower churn under KOSHA workplace wellness standards.
- Community Center:Municipal-subsidized facilities in Daegu and Gwangju meet community health access targets with grant-supported permit structures.
Revenue concentrates in Full-Service Gym networks; boutique expansion accelerates fastest.
Pricing Model:
Payment structure selection signals member commitment depth and lifetime value expectations.
- Membership Fee:Recurring monthly or annual contracts anchor cash flow predictability for full-service operators. Young professionals in Seoul's dense districts show rising preference for flexibility over lock-in.
- Pay-Per-Class:Single-session purchasing dominates boutique studio economics and attracts trial-prone demographics.
- Group Discounts:Corporate and family rate structures reduce per-capita acquisition costs while expanding base.
- Trial Offers:Introductory pricing converts prospects experiencing recovery-integrated service bundles commanding 40-60 percent membership premiums.
Membership Fee structures retain largest base; Pay-Per-Class gains share fastest.
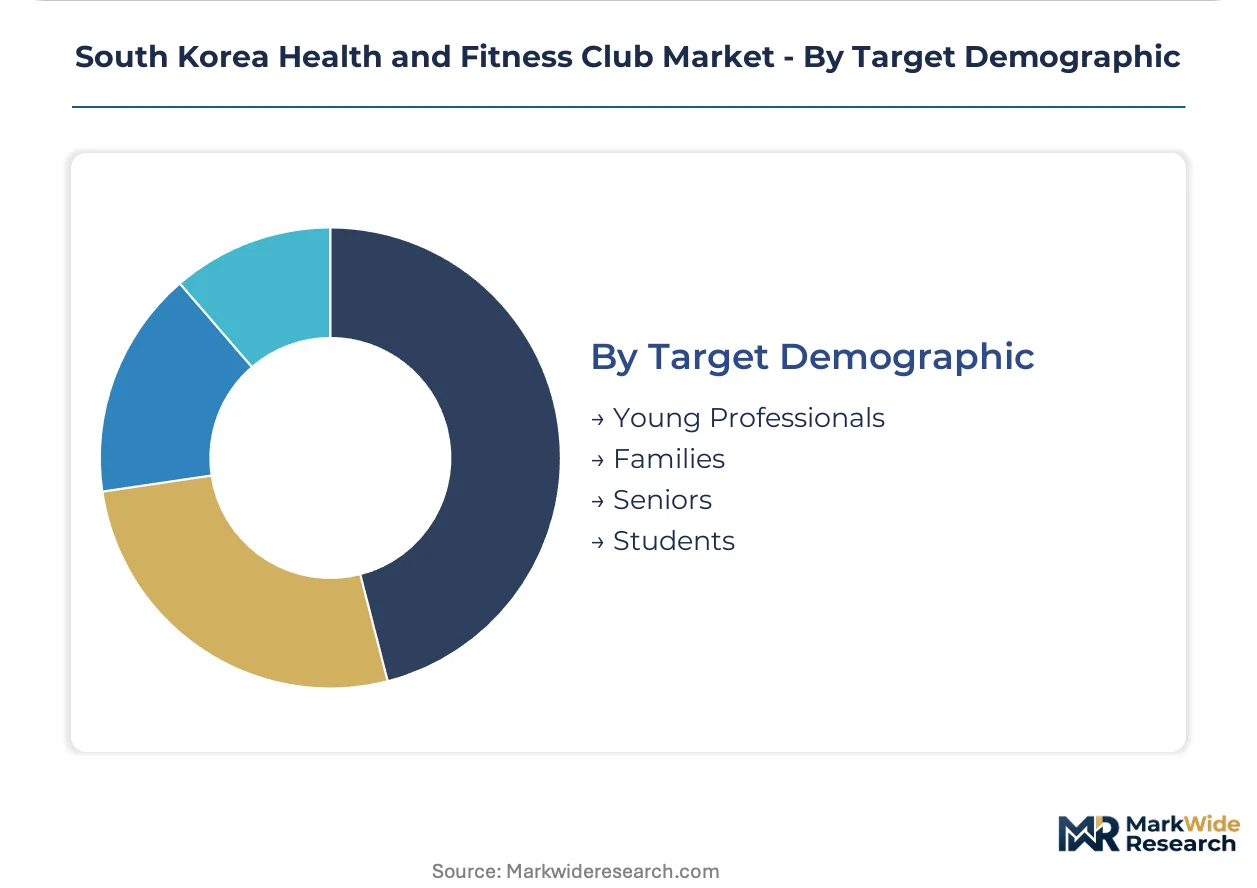
Target Demographic:
Life stage and disposable income availability shape programming design and facility amenity investment.
- Young Professionals:Time-constrained workers aged 25-35 prioritize location convenience and specialized modalities over comprehensive offerings. Gangnam and Pangyo technology corridor density sustains premium boutique demand.
- Families:Multi-generational membership structures require childcare integration and varied programming depth.
- Seniors:Low-impact programming and recovery service integration attract aging population segments with specific joint health priorities.
- Students:Price-sensitive university populations in Seoul, Busan, and Daegu favor trial offers and discount structures.
Young Professionals dominate current spending; Seniors represent steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Gangnam district anchors South Korean fitness demand through concentrated young professional populations and premium real estate clustering.
Seoul Capital Area
Gangnam and Seongdong districts concentrate boutique studio density at levels unmatched nationally, with pay-per-class models capturing time-constrained professionals aged 25-35. MFDS wellness certification requirements shape facility compliance investments across the metropolitan zone. Pangyo technology corridor employers consolidate corporate wellness contracts into exclusive platform partnerships, replacing reimbursement-based programs with on-site access.
Busan-Ulsan
Manufacturing campuses under KOSHA workplace wellness standards drive corporate gym installations with captive employee populations and lower churn characteristics. Secondary market positioning creates first-mover advantages for boutique concepts replicating Seoul's Seongdong cluster model. Haeundae and Centum City districts attract premium positioning attempts from expanding operators.
Daegu-Gyeongbuk
Municipal wellness grant programs subsidize facility permits for operators meeting community health access targets, reducing capital barriers for independent entrants. District government tightening of commercial fitness density limits constrains new club approvals in central zones. Regional price sensitivity favors membership-fee structures over boutique pay-per-class models.
Daejeon-Sejong
Government complex employee populations sustain mid-tier full-service gym demand with predictable recurring revenue profiles. Sejong administrative city planning incorporates fitness facility mandates into commercial zoning codes. Limited boutique penetration leaves specialized modality gaps for targeted entrants.
Gwangju-Honam
Grant-supported permit structures under district wellness programs attract operators expanding beyond saturated Seoul and Busan markets. University populations in the Honam region generate student-segment demand favoring trial offers and discount structures. Recovery service integration remains underdeveloped compared to capital-region facilities.
South Korea Health and Fitness Club Market Competitive Landscape
Capacity expansion dominates the current landscape as established operators retrofit ventilation infrastructure to meet Korea Health Promotion Act mandates. The vendor base separates into three distinct tiers: corporate-affiliated networks with real estate advantages, independent boutique specialists with programming differentiation, and municipal-subsidized community operators with grant-dependent economics. Strategic archetypes include integrated wellness platform providers, specialized modality studios, and occupational health-focused corporate installers. Competitive moves center on M&A consolidation of regional independents and technology licensing for biometric feedback integration.
Within the corporate-affiliated tier, Samsung Leports Center anchors large-format facility networks through parent-company real estate access. Fit Club Seoul exemplifies boutique positioning through specialized group programming that differentiates from mass-market chains. James Gym Fitness Center occupies the premium independent segment, sustaining member retention through personalized training protocols in capital-region suburbs.
| Leading Market Players |
|---|
| James Gym Fitness Center |
| Punho Boxing Club |
| Fit Club Seoul |
| Lfl Co. Ltd (4tp Fitness) |
| N&Company Goto |
| Samsung Leports Center |
| Star Kali Fitness |
| 10th Planet Jiu Jitsu Seoul |
| Hit Fit Boxing Lounge |
| Others |
Pricing and Supply Chain Analysis
Horizontal integration through multi-location operator networks anchors both supply resilience and pricing power across South Korean fitness markets. Samsung Leports Center leverages parent-company real estate access to compress facility buildout costs below independent competitors, while boutique clusters in Gangnam and Seongdong sustain premium positioning through location scarcity rather than scale economies.
Pricing Analysis
Service-bundling architecture separates membership tiers: full-service gyms package equipment access with group classes and basic recovery amenities, while boutique studios unbundle personal training and cryotherapy as premium add-ons. Three-tier pricing structure across premium, standard, and economy levels reflects ventilation compliance costs under Korea Health Promotion Act mandates, with certified facilities commanding 15-20 percent premiums. Cost compression in economy-tier memberships intensifies as outdoor cycling collectives and digital fitness platforms capture price-sensitive university students in Daegu and Gwangju. Corporate wellness buyers show lowest price sensitivity, consolidating vendor relationships into exclusive platform contracts that prioritize KOSHA compliance over per-member cost minimization.
Supply Chain Analysis
Workforce availability constraints in Seoul and Busan metropolitan zones limit specialized instructor pipeline expansion, with MFDS-recognized nutrition counseling credentials requiring 18-month training programs that outpace hiring demand at expanding chains. Equipment manufacturing concentrates in China, South Korea, and Taiwan, with biometric feedback systems and AI-assisted coaching platforms increasingly sourced from domestic technology suppliers. HVAC infrastructure and continuous air quality monitoring equipment draw from Japanese and German component suppliers, creating tariff exposure as trade policy shifts. Distribution runs through direct manufacturer relationships for large-format chains, while independent boutiques rely on regional equipment distributors with longer fulfillment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korean fitness operators face a technology-transition phase as AI-powered movement analysis and computer-vision form correction displace manual coaching functions across mid-tier facilities.
For Market Incumbents: Extend recovery service integration to defend premium positioning against digital fitness substitutes, bundling cryotherapy and compression therapy with traditional strength training to justify 40-60 percent membership premiums. Accelerate cloud-based access control platform migration to reduce 12-18 month legacy system integration timelines that expose operational vulnerability to technology-native entrants. Certification investment in MFDS wellness guidelines unlocks tax incentive eligibility and creates regulatory moats against uncertified competitors. For New Entrants and Emerging Players: Capture underserved premium segments in Busan's Haeundae and Centum City districts, where secondary market positioning creates first-mover advantages for boutique concepts replicating Seoul's Seongdong cluster model. Target municipal wellness grant programs in Daegu and Gwangju to reduce capital barriers for independent facility permits. Deploy occupational health expertise as go-to-market anchor for KOSHA-compliant corporate gym installations at manufacturing campuses. For Investors and Strategic Acquirers: Exit pathways concentrate in regional independent consolidation as capacity expansion mandates under Korea Health Promotion Act ventilation requirements strain undercapitalized operators. Long-term viability favors integrated wellness platform providers with corporate parentage advantages or specialized modality studios with programming differentiation. Monitor MFDS guideline expansion into nutrition counseling services as inflection indicator for regulatory compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Recovery Service Integration | Cryotherapy and compression therapy bundles command premium positioning in Gangnam and Seongdong districts. |
| AI Coaching Platform Deployment | Computer-vision form correction reduces injury liability while enabling higher trainer-to-member ratios. |
| MFDS Certification Investment | Wellness certification unlocks tax incentive eligibility and shapes facility compliance investments nationwide. |
| Corporate Wellness Consolidation | Exclusive platform partnerships replace reimbursement-based programs at Pangyo technology corridor employers. |
| Cloud Infrastructure Migration | Access control platform modernization reduces operational vulnerability to technology-native competitors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this South Korea health and fitness club market assessment. Primary interviews with facility operators, corporate wellness procurement managers, specialized fitness instructors, and municipal health department officials combined with bottom-up and top-down triangulation. Secondary validation drew from Korea Health Promotion Act compliance documentation, MFDS wellness guideline filings, KOSHA workplace standards records, and Seoul metropolitan zoning permit databases.
Granularity-level modeling distinguished facility type segmentation across full-service gyms, boutique studios, corporate installations, and community centers; service type segmentation across personal training, group classes, nutrition counseling, and wellness programs; and pricing model segmentation across membership fees, pay-per-class structures, and corporate discount arrangements. CAGRs derived from facility count expansion rates, membership volume trajectories, and average revenue per member trends across the analysis window. Industry-specific forecast inputs incorporated ventilation infrastructure retrofit timelines and MFDS-recognized credential pipeline constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to municipal zoning density limits in Seoul and Busan, KOSHA compliance deadline acceleration, and substitute wellness modality capture rates. Forecasts reflect documented assumptions regarding corporate wellness buyer consolidation velocity and boutique studio pay-per-class model adoption. Material deviation in MFDS guideline expansion scope or Korea Health Promotion Act enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gyms and Fitness Centers
Fitness and Recreational Sports Centers Market
Gyms and Fitness Centers
Saudi Arabia Health and Fitness Club Market
Gyms and Fitness Centers
Health and Fitness Club Market
Gyms and Fitness Centers
Boutique Fitness Studio Market
Gyms and Fitness Centers
South America Health and Fitness Club Market
Gyms and Fitness Centers
Europe Pilates & Yoga Studios Market
Gyms and Fitness Centers
Global Pilates and Yoga Studios Market
Gyms and Fitness Centers
Europe Climbing Gym Market
Gyms and Fitness Centers
Global Climbing Gym Market
Gyms and Fitness Centers
Southeast Asia Health and Fitness Club Market