
 Swimming Pool Liner Market | 2026-2036
Swimming Pool Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Swimming Pool Liner Market Insights
Market Context
Digital templating and automated cutting is fragmenting how custom pool liners are measured, fabricated, and delivered to installers. Latham Pool Products leverages vertical integration from extrusion to installation to capture margin across the value chain. GLI Pool Products sustains manufacturing scale across multiple North American plants, while Loop-Loc differentiates through premium mesh safety cover and liner combinations that command higher price points.
Technical Definition and Segments
Swimming pool liners are flexible membrane barriers, typically 20–30 mil in thickness, thermoformed or seamed from calendered vinyl sheeting to create watertight surfaces that protect structural shells from chemical corrosion and soil moisture ingress. Vinyl dominates material type selection due to its balance of weldability, UV resistance, and cost structure, though polyethylene is gaining traction in modular above-ground systems where lighter weight simplifies handling. In-ground installation type anchors the value pool given higher material requirements and labor intensity, while hospitality venues within end user segmentation represent the fastest replacement cycle due to operational uptime demands and brand standards.
Regulatory Outlook
EPA regulations on phthalate content in flexible vinyl products shape formulation choices for domestic manufacturers, while ASTM F2208 safety cover standards and state-level pool barrier codes in California, Florida, and Arizona directly influence liner-adjacent product bundling and liability exposure. ISO 9001 quality management certifications increasingly serve as table stakes for commercial facility procurement. Stakeholders must monitor evolving state chemical disclosure requirements and position inventory flexibility to accommodate reformulation timelines without disrupting seasonal installation windows.
Market Dynamics
Digital templating systems are compressing measurement-to-installation cycles from weeks to days, forcing fabricators to reconfigure production workflows around just-in-time fulfillment or lose seasonal volume to nimbler competitors.
Growth Catalysts
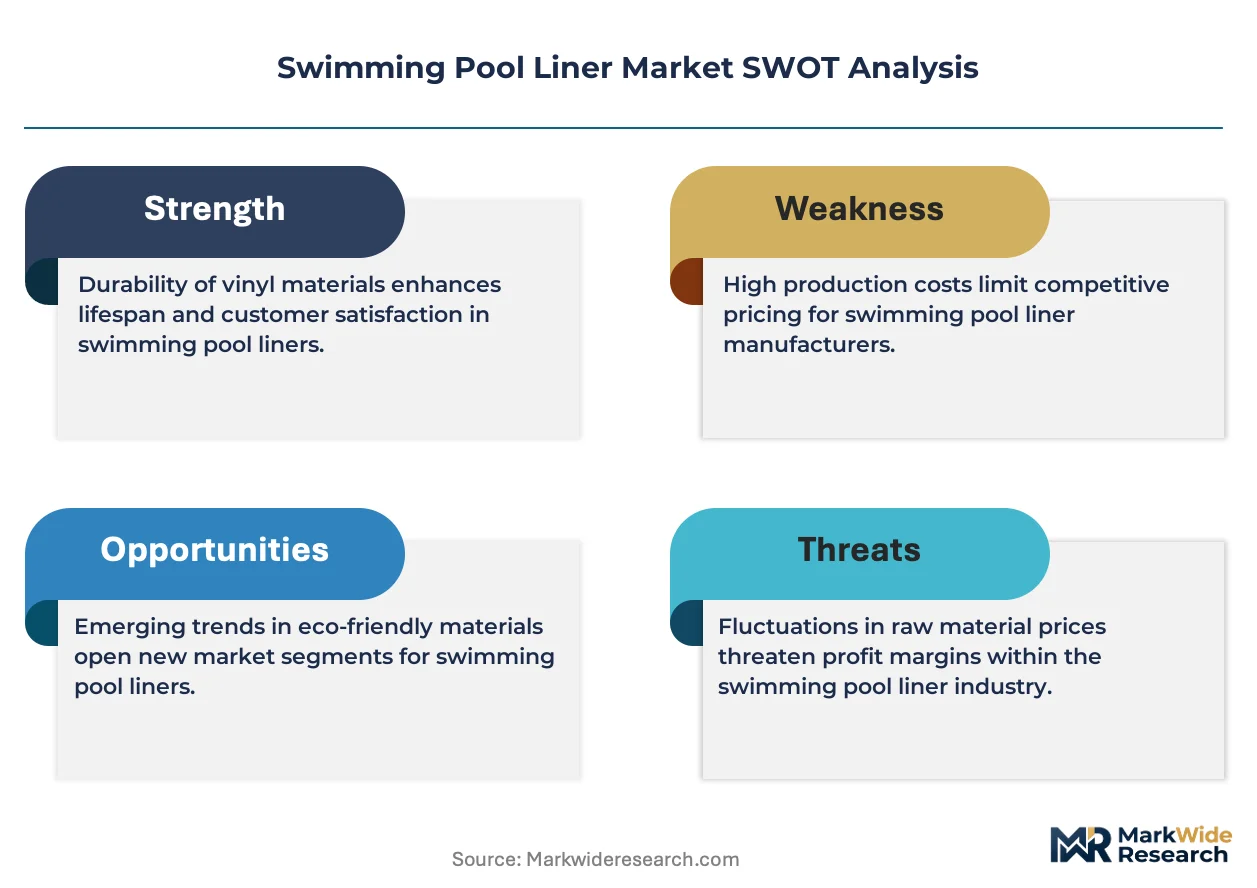
- California Title 24 efficiency mandates:These building codes elevate thermal performance requirements for pool enclosures, accelerating replacement demand among homeowners seeking compliant barrier systems.
- Mesh-vinyl hybrid technology:Advanced composite formulations deliver superior puncture resistance and UV stability, opening premium positioning in commercial hospitality installations.
- Sun Belt suburban clusters:Pool ownership rates in Arizona, Texas, and Florida exceed national benchmarks by substantial margins, concentrating replacement cycles in these geographies.
Market Restraints
- Phthalate input volatility:EPA restrictions on plasticizer chemistries force reformulation cycles that disrupt established supply relationships and inflate raw material qualification costs.
- Calendered vinyl supply concentration:Domestic sheeting production clusters in the Ohio River Valley, creating geographic vulnerability to regional weather events and logistics bottlenecks.
- Welded seam durability ceiling:Thermoformed joint integrity remains the dominant failure mode in high-chemical-load commercial environments, limiting service life guarantees.
Strategic Opportunities
- Modular above-ground polyethylene systems:Lightweight membrane alternatives suit rental property portfolios and seasonal markets where permanent installation is impractical.
- ASTM F2208 safety cover bundling:Liner-installer networks can capture adjacent product margin by integrating certified barrier systems into replacement workflows.
- ISO 9001 procurement table stakes:Commercial facility managers increasingly mandate quality management certification, creating tiered market access for compliant fabricators.
Industry Challenges
- Digital measurement technician scarcity:Pool geometry capture requires specialized photogrammetry skills that outpace vocational training pipeline output.
- Seasonal installation window compression:Climate-dependent ground conditions in northern latitudes compress viable work periods, straining fleet utilization and labor scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swimming Pool Liner Market |
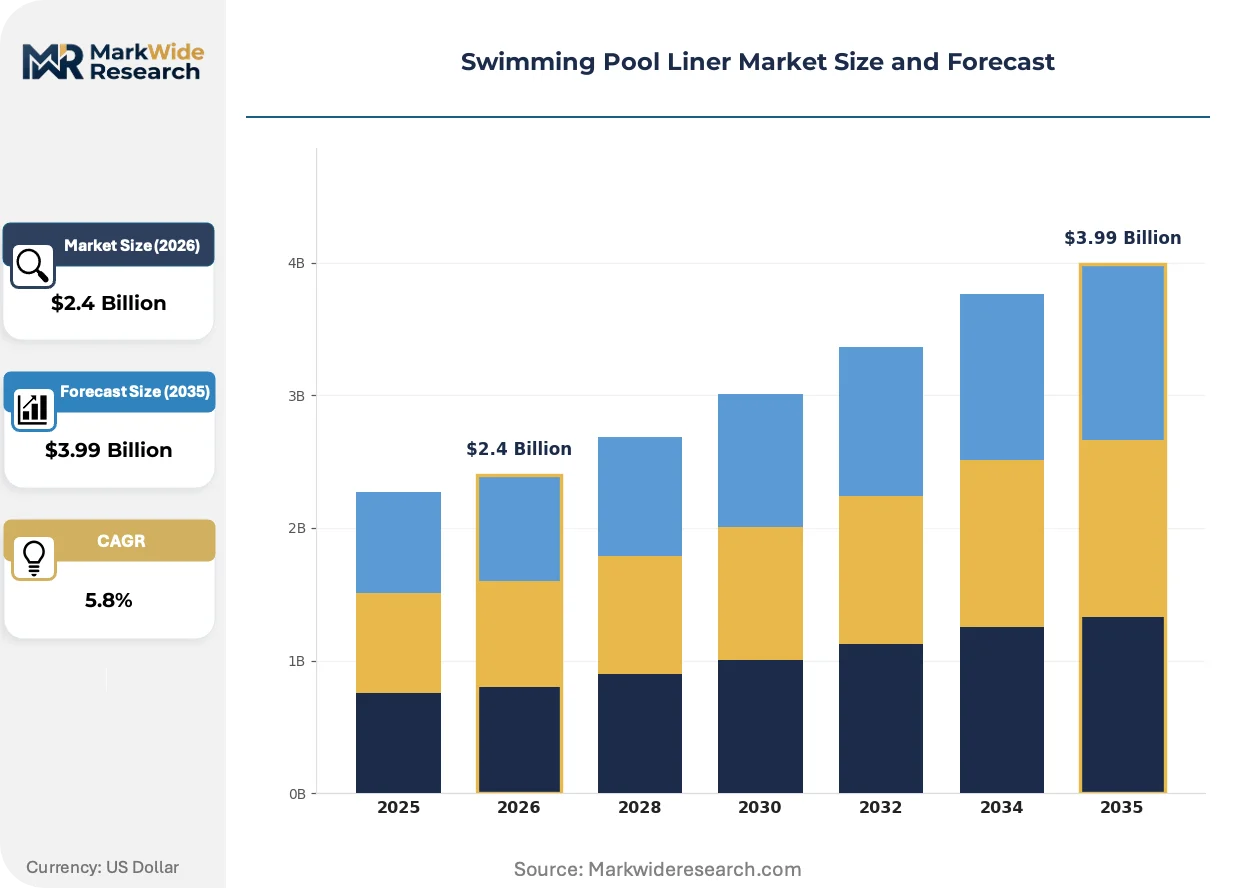
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Vinyl, PVC, Polyethylene, Hypalon, Polypropylene, Neoprene Installation Type: In-ground, Above-ground, Semi-inground, Modular End User: Residential Homeowners, Commercial Facilities, Hospitality Venues, Sports Complexes Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Distributors |
| Companies Covered | GLI Pool Products, McEwen Industries, Latham Pool Products, Pocono Pool Products, Merlin Industries, Swimline Corp., Loop-Loc, Continental, Garrett Liners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swimming Pool Liner Market Trends and Innovations
Automation is penetrating fabrication floors and installer toolkits simultaneously, compressing lead times while elevating precision benchmarks that reshape competitive sorting between integrated and distributed supply models.
Robotic seam welding is migrating from high-volume commercial fabricators to mid-tier regional producers. Hospitality chains with standardized pool footprints are specifying automated weld consistency in procurement tenders. This capability compression is eliminating the quality differentiation that previously justified premium positioning for established manufacturers with proprietary thermal bonding equipment.
EPA phthalate disclosure requirements are forcing formulation transparency throughout the vinyl supply chain. Domestic compounders must document plasticizer chemistry from resin to finished liner, elevating compliance costs for smaller blenders. California and Florida state-level chemical registries are receiving the most intensive supplier documentation submissions, with reformulation timelines now built into seasonal inventory planning.
Direct-to-installer digital platforms are disintermediating traditional distributor relationships. Custom pool builders in Texas and Arizona are increasingly sourcing templated liners through manufacturer portals that bypass regional wholesale networks. This channel compression concentrates pricing power with fabricators possessing captive measurement technology while eroding the inventory-holding role of conventional distributors.
Swimming Pool Liner Market Segmentation
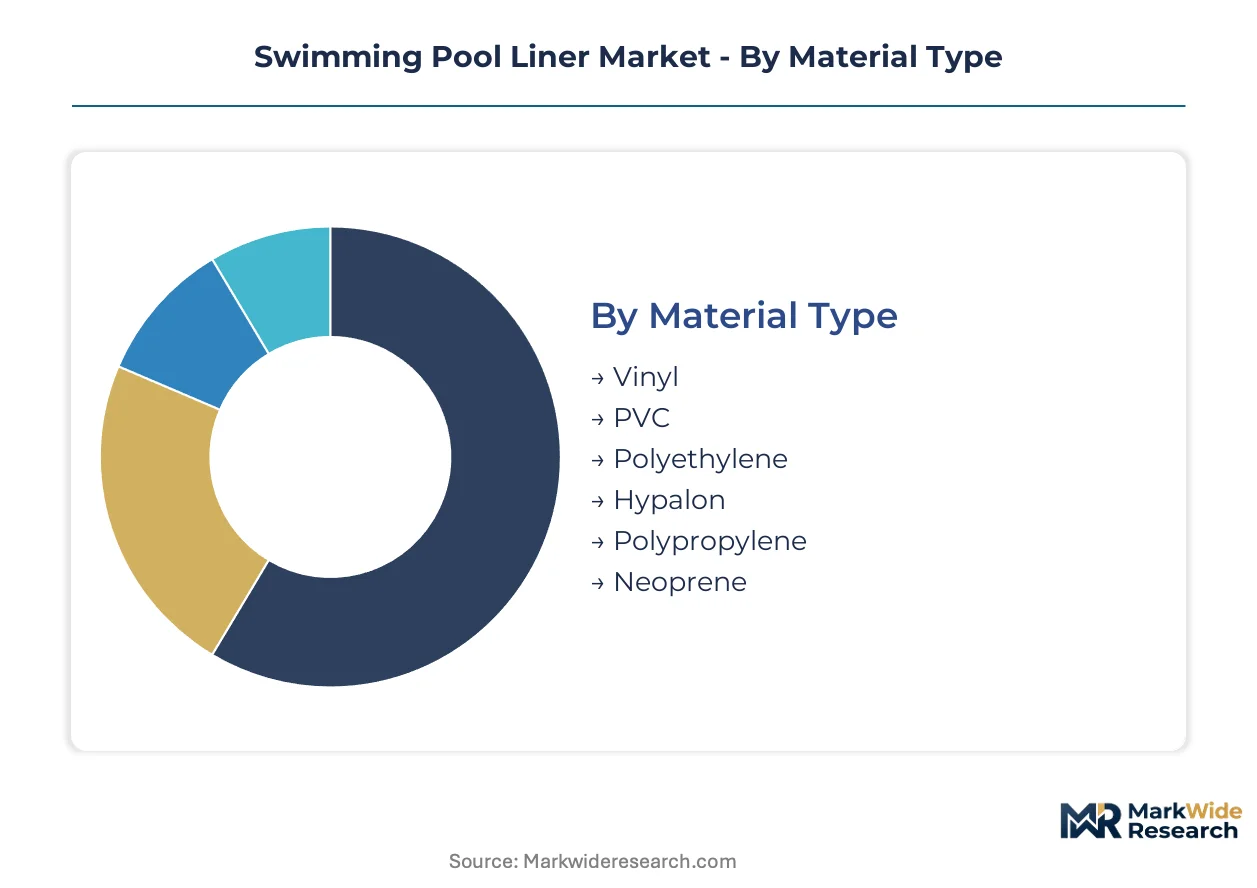
Swimming pool liner procurement varies sharply by structural application, chemical exposure profile, and channel access. Material chemistry and installation geometry together determine warranty terms, replacement cycles, and installer certification requirements across the value chain.
Material Type:
Performance requirements span from backyard residential durability to commercial chemical resistance, with cost tiers separating commodity vinyl from engineered elastomers.
- Vinyl:Calendered PVC sheeting at 20–30 mil thickness dominates fabrication due to thermoformability and weld consistency. Sun Belt residential replacement cycles in Arizona, Texas, and Florida concentrate demand for this material, though EPA phthalate restrictions force periodic reformulation.
- Polyethylene:Extruded linear low-density formulations serve modular above-ground systems where reduced weight simplifies seasonal handling. Rental property portfolios in suburban Florida favor this material for installation speed and removal flexibility.
- PVC:Rigid-to-flexible compound variations suit semi-inground structural hybrids requiring dimensional stability at panel joints.
- Hypalon:Chlorosulfonated polyethylene delivers superior UV and chemical resistance for commercial hospitality installations with aggressive sanitization protocols.
- Polypropylene:Olefin-based alternatives address phthalate-free formulation mandates in California and Florida state chemical registries.
- Neoprene:Synthetic rubber compounds serve niche cold-climate applications where low-temperature flexibility extends installation windows.
Established volume favors vinyl; emerging adoption favors polyethylene.
Installation Type:
Structural integration depth determines labor intensity, material specifications, and replacement logistics for each configuration.
- In-ground:Custom thermoformed membranes anchor structural shells against hydrostatic pressure and soil chemistry. California Title 24 thermal efficiency standards and Florida humidity exposure drive specification upgrades in these permanent installations.
- Above-ground:Prefabricated panel systems with drop-in liners suit suburban homeowners seeking lower capital commitment. Texas and Arizona retail channels move significant volume through seasonal big-box programs.
- Semi-inground:Hybrid structural designs blend aesthetic integration with simplified excavation requirements for sloped terrain properties.
- Modular:Demountable frame systems target rental properties and temporary hospitality installations where asset mobility matters.
In-ground claims the value concentration; modular configurations are climbing the fastest.
End User:
Operational intensity and brand exposure create divergent procurement priorities across customer categories.
- Residential Homeowners:Suburban replacement cycles in Sun Belt states drive volume, with digital templating compressing measurement-to-installation timelines for aging vinyl removals.
- Hospitality Venues:Brand standards and operational uptime demands force aggressive replacement schedules. Automated seam welding specifications appear increasingly in chain procurement tenders.
- Commercial Facilities:Municipal and institutional pools prioritize ASTM F2208 safety cover bundling and ISO 9001 supplier certification in competitive bidding.
- Sports Complexes:Competition-grade dimensional tolerances and chemical load management distinguish this segment from general commercial specifications.
Residential volume dominates unit sales; hospitality replacement frequency yields premium pricing realization.
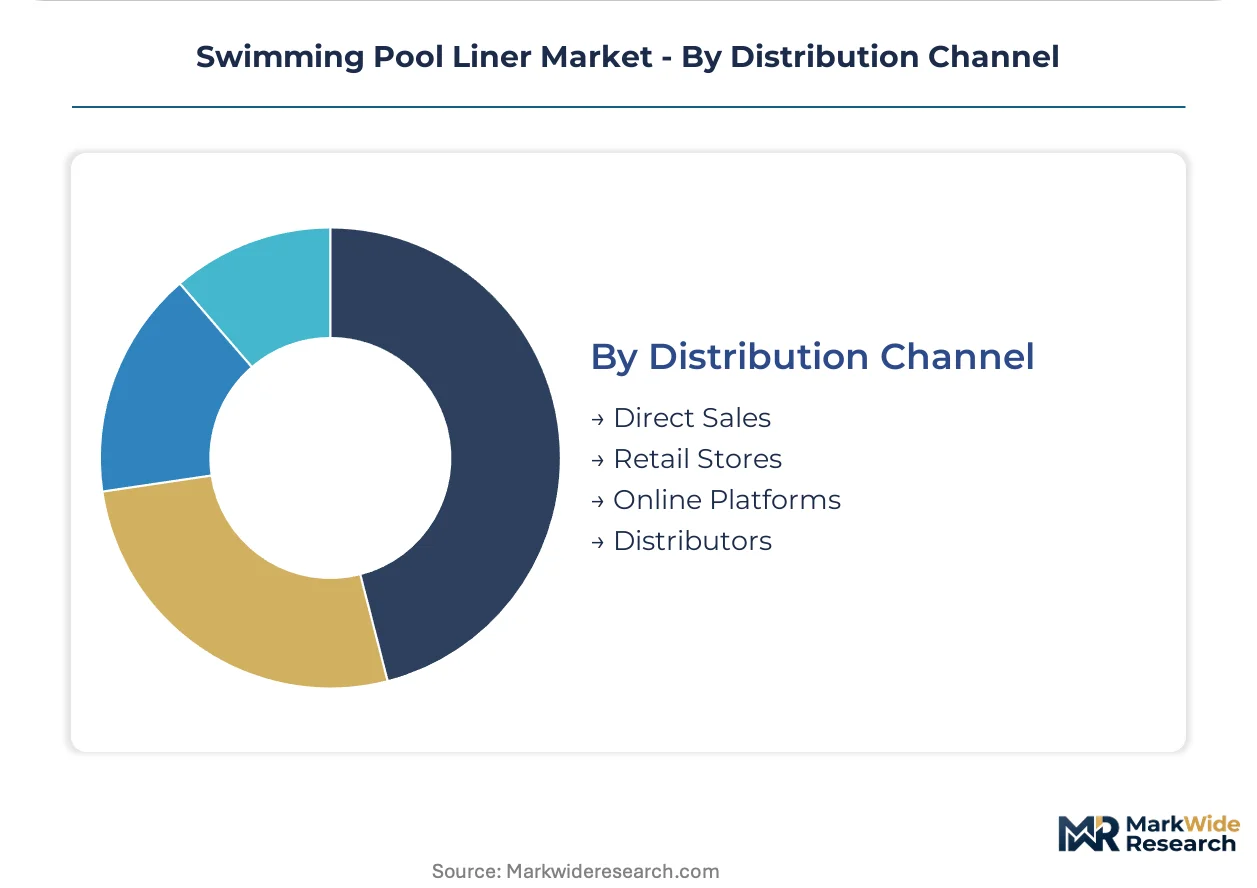
Distribution Channel:
Channel structure is shifting as digital platforms compress traditional wholesale hierarchies.
- Direct Sales:Manufacturer portals with captive templating technology disintermediate regional distributors in Texas and Arizona custom pool builder networks.
- Distributors:Conventional wholesale networks retain inventory-holding value in northern latitudes where seasonal compression rewards local availability.
- Retail Stores:Big-box seasonal programs capture above-ground volume in suburban markets with high pool ownership density.
- Online Platforms:Third-party marketplaces serve replacement part and accessory demand, though full liner procurement remains installer-mediated.
Direct sales gain share fastest; distributor relationships defend position in climate-constrained geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based fabricators export calendered vinyl sheeting to Canadian and Mexican installer networks, while European compounders supply Mediterranean hospitality markets with phthalate-compliant formulations.
United States
California Title 24 building efficiency standards and Florida humidity exposure drive specification upgrades for in-ground thermal barrier systems. EPA phthalate disclosure requirements force domestic compounders to document plasticizer chemistry from resin to finished liner. The Ohio River Valley hosts concentrated calendered vinyl sheeting production, creating geographic vulnerability to regional weather disruptions.
Canada
Seasonal installation window compression in Ontario and Quebec concentrates replacement demand into compressed summer periods. Health Canada PMRA oversees chemical safety standards for flexible vinyl products entering recreational water applications. The Greater Toronto Area anchors distributor inventory-holding networks that buffer northern climate constraints.
Mexico
Rising suburban pool ownership in Nuevo León and Jalisco generates above-ground system demand through retail seasonal programs. Mexican federal environmental regulations align with EPA frameworks for cross-border chemical formulation consistency. Mexico City Metro fabricators serve hospitality renovation cycles for coastal resort properties.
Australia
Queensland and New South Wales pool ownership rates exceed national benchmarks, concentrating vinyl liner replacement cycles. TGA chemical safety guidelines influence formulation choices for imported flexible membrane products. Sydney-based distributors manage inventory for the Sun Belt corridor from Brisbane to Melbourne.
Germany
REACH chemical registration requirements elevate compliance costs for vinyl compounders serving Central European markets. Bavarian fabricators specialize in automated seam welding equipment for hospitality chain procurement. The North Rhine-Westphalia industrial cluster supplies precision calendering machinery to Mediterranean liner producers.
Swimming Pool Liner Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base separates into three strategic archetypes: vertically integrated manufacturers with captive extrusion capacity, regional fabricators dependent on outsourced sheeting supply, and premium-positioned specialists bundling safety cover systems. Dominant competitive moves include backward integration into resin compounding and geographic expansion through installer network acquisition.
Among North American fabricators, GLI Pool Products and Latham Pool Products exemplify scale-driven archetypes with multi-plant manufacturing footprints, while Loop-Loc occupies a premium-tier position through safety cover and liner combination positioning. McEwen Industries represents the regional specialist archetype with focused distribution relationships. These three company structures illustrate the competitive sorting between volume efficiency and premium differentiation that characterizes procurement dynamics.
| Leading Market Players |
|---|
| GLI Pool Products |
| McEwen Industries |
| Latham Pool Products |
| Pocono Pool Products |
| Merlin Industries |
| Swimline Corp. |
| Loop-Loc |
| Continental |
| Garrett Liners |
| Others |
Pricing and Supply Chain Analysis
Ohio River Valley calendered vinyl sheeting production concentrates upstream supply, positioning compounders with captive extrusion capacity to capture margin pools that regional fabricators dependent on outsourced feedstock cannot access.
Pricing Analysis
Prior-generation hand-templated liner pricing faces compression from digital measurement platforms, while next-generation automated seam welding commands premium positioning in hospitality procurement tenders. Three-tier pricing structure across premium, standard, and economy levels separates certified ASTM F2208 safety cover bundling from commodity vinyl replacements. Price differentiation hinges on ISO 9001 certification status and geographic delivery cost to Sun Belt installation clusters. Pricing pressure stems from direct-to-installer portal disintermediation eroding distributor markup capture. Residential homeowners in suburban replacement cycles exhibit highest price sensitivity; hospitality chains with brand standard mandates show lowest.
Supply Chain Analysis
Export-control restrictions on automated seam welding equipment limit technology transfer to Mediterranean and Asia-Pacific fabricators, constraining capability diffusion beyond established North American and German equipment suppliers. Raw material flows draw from Ohio River Valley vinyl calendering, Texas petrochemical resin supply, and Canadian plasticizer compounders. Supply chain risk centers on single-source vulnerability for robotic welding systems specified in hospitality tenders. Distribution runs through manufacturer-direct portals in Arizona and Texas, conventional wholesale networks in northern latitudes, and seasonal retail programs for above-ground systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swimming pool liner demand sits in early-cycle expansion as California Title 24 efficiency mandates and Florida humidity exposure accelerate replacement timelines beyond historical replacement rates.
For Market Incumbents: Insulate margin position by deepening backward integration into resin compounding and acquiring installer networks in Texas and Arizona where direct-to-fabricator portal adoption concentrates. EPA phthalate disclosure requirements threaten smaller blenders with compliance cost burdens that integrated compounders can absorb. Certification investment in ISO 9001 quality management systems defends commercial facility procurement access against emerging regional competitors. For New Entrants and Emerging Players: Establish a beachhead in modular above-ground polyethylene systems serving Florida rental property portfolios where installation speed and removal flexibility outweigh brand loyalty. The most penetrable segment is seasonal big-box retail channels in suburban Sun Belt markets with compressed measurement-to-installation expectations. A go-to-market angle anchored in lightweight material handling and simplified DIY installation protocols bypasses incumbent installer network control. For Investors and Strategic Acquirers: Capital is best deployed toward regional fabricators with established distributor relationships in climate-constrained northern geographies where seasonal compression rewards local inventory-holding capability. Long-term viability over a multi-year horizon favors suppliers with formulation flexibility to accommodate state-level chemical registry mandates without seasonal disruption. The signal to watch is hospitality chain procurement tender specifications for automated seam welding consistency as a threshold qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures margin upstream and insulates against EPA-mandated reformulation disruption. |
| Installer Network Acquisition | Concentrates channel control in Texas and Arizona where portal adoption accelerates. |
| ISO 9001 Certification Investment | Meets commercial facility procurement table stakes and tiered market access requirements. |
| Automated Seam Welding Deployment | Matches hospitality chain tender specifications and eliminates quality differentiation gaps. |
| Direct-to-Installer Portal Development | Disintermediates distributor markup and concentrates pricing power with templating technology owners. |
Research Methodology
Desk research of customs trade data, EPA regulatory filings, and ASTM standard documentation preceded structured interviews with vinyl compounder plant managers, pool liner fabricator procurement leads, custom pool builder operations directors, and hospitality facilities engineering heads. Secondary validation drew from state building code registries, industry association membership directories, and equipment manufacturer technical specifications. Bottom-up unit economics and top-down market sizing were triangulated against seasonal installation volume patterns.
Assumptions held fixed across the analysis window include California Title 24 thermal efficiency standard continuity and EPA phthalate disclosure requirement enforcement timelines; variables tested included hospitality sector capital expenditure cycles and robotic welding equipment adoption rates. Segmentation dimensions modeled encompass material chemistry, installation geometry, end-user operational intensity, and distribution channel structure. CAGRs were derived from replacement cycle frequency analysis and geographic ownership density correlations, with inputs from chemical exposure degradation curves and regional climate condition severity indices.
Stress conditions across resin price volatility, seasonal installation window compression, and state chemical registry expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology adoption S-curves. Material shifts in EPA plasticizer restriction scope or California Title 24 expansion to additional states would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Camping Utensils Market
Outdoor & Sports
Global Paintball Equipment Market
Outdoor & Sports
Global Sailing Dinghy Masts Market
Outdoor & Sports
Global Canoe and Kayak Market
Outdoor & Sports
Mexico Fishing Reels Market
Outdoor & Sports
Swimming Pool Equipment Market
Outdoor & Sports
Hunting Blinds Market
Outdoor & Sports
Camping Beds and Mats Market
Outdoor & Sports
Swimming Pool and Spa Market
Outdoor & Sports
Portable Kayaks Market
Outdoor & Sports
Paintball Field Service Market
Outdoor & Sports
Riding Multi-Purpose Lawn Mower Market
Outdoor & Sports
China Fishing Reels Market
Outdoor & Sports
Sleeper Pads Market
Outdoor & Sports
Global Pool Floats Market
Outdoor & Sports
Kids Scooter Market