

Riding Multi-Purpose Lawn Mower Market Size, Share, and Industry Trends Forecast 2026-2036
Riding Multi-Purpose Lawn Mower Market Insights
Skilled small-engine technician availability is collapsing across rural service territories, forcing OEMs to redesign field-service protocols and pre-delivery inspection regimes. Deere & Company leverages its dealership density to sustain same-day parts fulfillment in fragmented territories. Husqvarna Group anchors its competitive stance through vertical integration into cutting-deck manufacturing, controlling alloy sourcing and weld quality. The Toro Company dominates commercial channel relationships with landscape contractors, securing multi-year fleet agreements that lock in aftermarket revenue streams.
A riding multi-purpose lawn mower is a self-propelled turf-maintenance machine with a seated operator position, typically equipped with a cutting deck spanning 30 to 72 inches and power outputs from 10 to 35 horsepower, designed for sustained grass-cutting across variable terrain in residential, commercial, and agricultural settings. Zero-turn configurations command the premium tier due to maneuverability advantages on irregular lots, while electric motor technology is gaining fastest share as lithium-ion pack costs decline and runtime thresholds cross four-hour commercial shifts. Gasoline engine variants still occupy the volume core in price-sensitive residential segments where upfront capital constraints dominate purchase decisions.
EPA Phase 3 emission standards and NHTSA rollover protective structure requirements shape product engineering timelines and certification costs for manufacturers selling into the United States. OSHA landscaping hazard communication rules further influence fleet purchasing criteria, pushing property managers toward machines with integrated operator-presence systems and documented maintenance histories. Stakeholders must monitor battery recycling infrastructure buildout and state-level rebate program durability as electrification commitments reshape total cost-of-ownership calculations against legacy gasoline platforms.
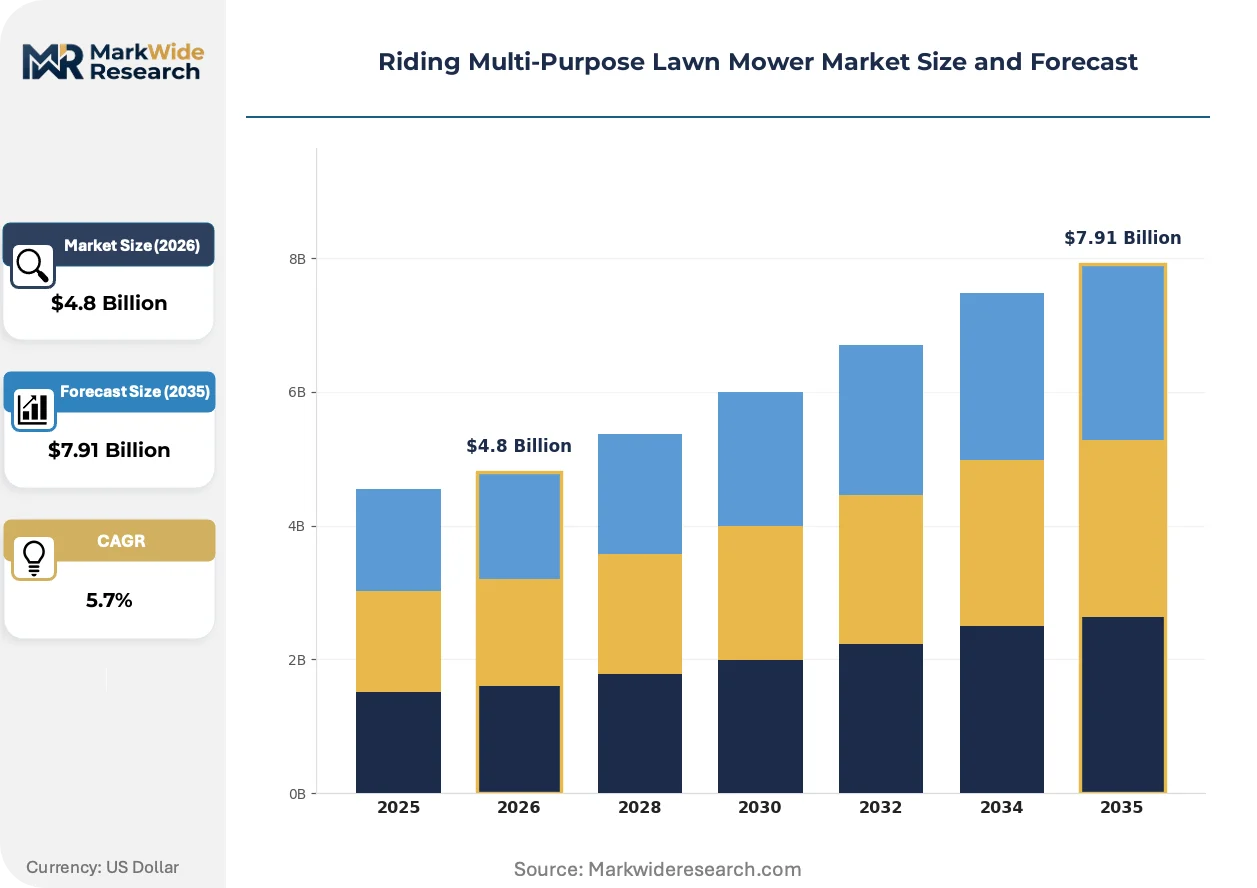
Market Dynamics
Electrification pressure from EPA Phase 3 emission standards is compressing gasoline-engine development cycles while lithium-ion pack economics cross commercial viability thresholds. Manufacturers must simultaneously fund dual-platform R&D and retool assembly lines without disrupting dealer inventory flows.
Growth Catalysts
- Commercial Grounds Maintenance Contracts:Landscape contractors across the southeastern United States are expanding fleet purchases to service multiplying municipal and corporate property management agreements. Multi-year service contracts lock in predictable replacement cycles.
- OSHA Landscaping Hazard Communication Rules:Property managers now require documented maintenance histories and integrated operator-presence systems. Fleet purchasers favor OEMs with telematics-ready platforms that automate compliance documentation.
- Lithium-Ion Cost Decline:Battery pack economics have improved sufficiently to support four-hour commercial runtime thresholds. Electric variants now compete on total cost-of-ownership against legacy gasoline platforms in high-utilization scenarios.
Market Restraints
- Skilled Technician Scarcity:Rural service territories face collapsing availability of small-engine repair specialists. OEMs absorb elevated warranty costs from improper field maintenance.
- Alloy Supply Concentration:Cutting-deck manufacturing depends on captive steel sourcing from limited domestic mill capacity. Weld quality specifications constrain substitution to lower-grade materials.
- Gasoline Platform Stranding Risk:Residential price-sensitive segments remain anchored to internal-combustion engines. Electrification capital requirements threaten margin compression in volume tiers.
Strategic Opportunities
- Battery Recycling Infrastructure Buildout:First-movers securing end-of-life lithium-ion processing partnerships will control circular supply economics. State-level rebate program durability favors vertically integrated service models.
- Telematics-Enabled Fleet Management:Convergence of GPS tracking and predictive maintenance algorithms creates aftermarket revenue streams. Landscape contractors pay premiums for uptime-guarantee contracts.
- Zero-Turn Configuration Expansion:Maneuverability advantages on irregular lots command premium pricing. Residential estate owners increasingly specify commercial-grade cutting decks for reduced mow times.
Industry Challenges
- Dual-Certification Burden:NHTSA rollover protective structure requirements and EPA emission timelines compress product engineering schedules. Simultaneous compliance testing strains validation laboratory capacity.
- Dealer Network Reconfiguration:Electric drivetrains eliminate traditional service revenue from oil changes and engine overhauls. Franchise agreements require renegotiation to incorporate battery-swap and electronics-diagnostic competencies.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Riding Multi-Purpose Lawn Mower Market Trends and Innovations
Power electronics and thermal management systems are displacing mechanical drivetrain components as the primary engineering frontier. This shift reconfigures supplier hierarchies and procurement priorities across the value chain.
Silicon carbide MOSFETs are miniaturizing inverter packaging while sustaining 35-horsepeak equivalent outputs. Commercial fleet operators in Florida and Georgia are specifying these configurations for reduced heat-generation and extended duty cycles. The technology is miniaturizing cooling-system requirements, enabling more compact battery enclosures without sacrificing runtime.
EPA Phase 3 emission standards are forcing gasoline-engine manufacturers to deploy exhaust after-treatment systems previously absent in sub-35-horsepower equipment. Engineering teams face compressed certification timelines as state-level adoption accelerates ahead of federal mandates. The southeastern United States exhibits fastest regulatory alignment, with Texas and North Carolina adopting California Air Resources Board equivalency protocols.
Landscape contractors are unbundling equipment procurement from maintenance service agreements, treating mowers as depreciating assets rather than bundled fleet solutions. Independent financing entities now intermediate capital allocation, displacing traditional OEM captive finance programs. This pattern concentrates in metropolitan Atlanta and Charlotte, where contractor density supports third-party equipment-leasing specialization.
Riding Multi-Purpose Lawn Mower Market Segmentation
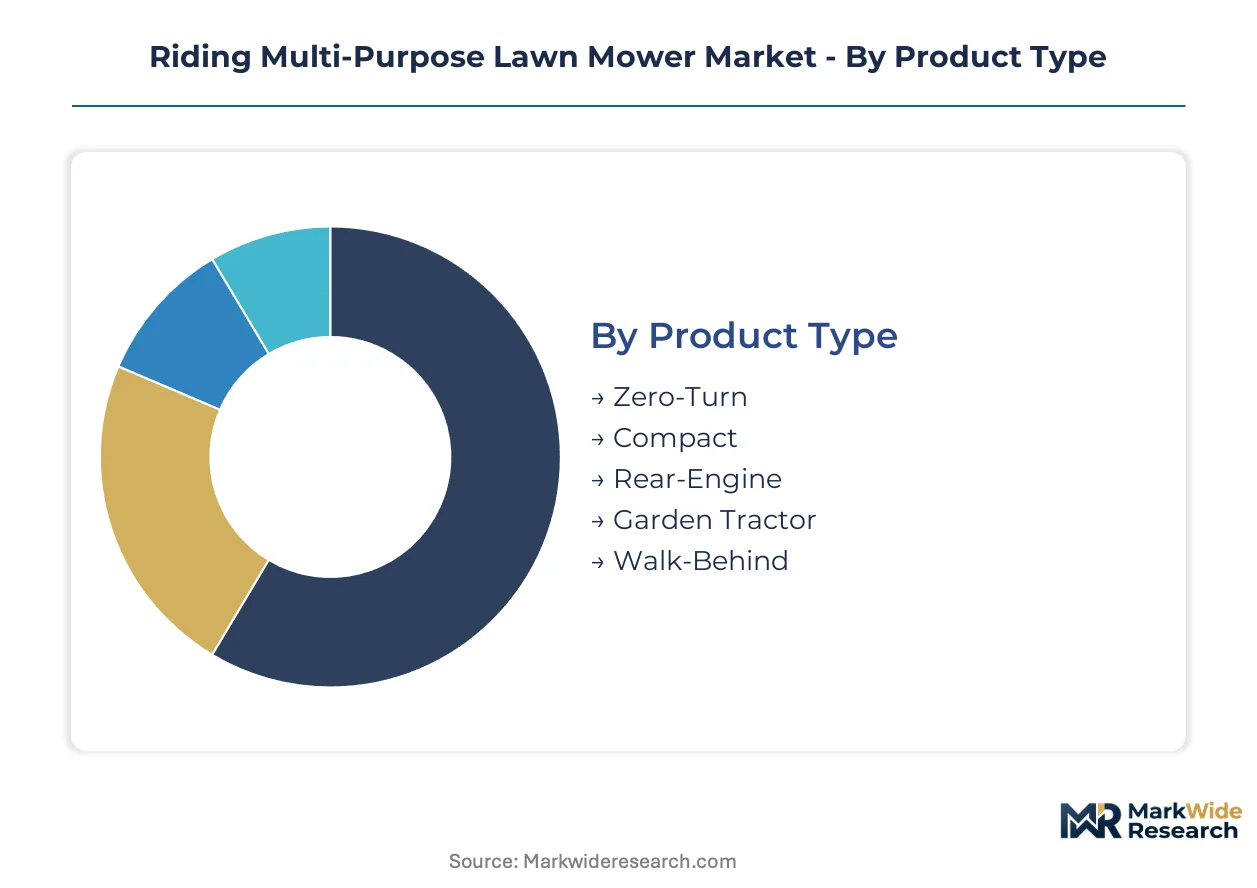
Segmentation in riding multi-purpose lawn mowers reveals how EPA Phase 3 emission standards and NHTSA rollover requirements create divergent engineering investments across product architectures. Each dimension exposes distinct margin profiles and aftermarket revenue potential that reshape competitive positioning.
Product Type:
Regulatory differentiation in rollover protective structures and cutting-deck safety certifications segments this category into compliance-cost tiers that determine viable distribution channels.
- Zero-Turn:Dual-hydrostatic wheel motors enable independent wheel rotation for tight-radius maneuvering on irregular lots. Landscape contractors in Florida and Georgia specify these configurations for reduced mow times on commercial contracts, absorbing premium pricing in exchange for labor-hour savings.
- Compact:Reduced deck footprints and lower center-of-gravity designs suit residential gate-width constraints and sloped terrain. Demand concentrates in southeastern estate markets where homeowners prioritize storage footprint over cutting width.
- Rear-Engine:Engine placement behind the operator seat enables shorter overall machine length for confined spaces. Groundskeepers at municipal facilities favor these for transportability between dispersed maintenance sites.
- Garden Tractor:Reinforced frame structures support attachment compatibility with tillers, snow blowers, and utility carts. Agricultural field applications in rural counties drive replacement cycles tied to seasonal implement demands.
- Walk-Behind:Operator-standing configurations bridge residential and light-commercial duty cycles. Facility supervisors specify these for steep-gradient zones where seated operation risks rollover exposure.
Established volume favors Compact configurations in residential replacement cycles; emerging adoption favors Zero-Turn as landscape contractors professionalize fleet specifications.
Technology:
Cost tier stratification separates capital-intensive electric platforms from maintenance-heavy gasoline systems, with total cost-of-ownership calculations diverging across utilization intensity levels.
- Gasoline Engine:Carbureted and fuel-injected variants dominate price-sensitive residential segments where upfront capital constraints override lifecycle cost analysis. EPA Phase 3 after-treatment systems add certification burden without displacing volume leadership in low-utilization households.
- Electric Motor:Brushless DC architectures with lithium-ion packs now sustain four-hour commercial runtime thresholds. Texas and North Carolina landscape contractors pilot fleet electrification where state-level rebate programs improve payback calculations.
- Hybrid Drive:Range-extender configurations pair small gasoline generators with electric traction motors. Parks and recreation departments evaluate these for remote sites lacking charging infrastructure.
- Hydrostatic Transmission:Variable-displacement hydraulic pumps replace mechanical gearboxes for infinite speed control without clutch wear. Commercial grounds maintenance contracts specify these for operator fatigue reduction during extended shifts.
- Manual Transmission:Synchronized gearboxes with mechanical clutches occupy economy-tier price positioning. Residential estate owners in cost-conscious rural markets accept operational complexity for acquisition savings.
High-utilization commercial applications are climbing the fastest toward electric motor adoption; gasoline engines retain margin concentration in replacement-part aftermarket streams.
Application:
Customer type maturity separates institutional procurement with documented maintenance requirements from discretionary residential purchases driven by aesthetic preferences.
- Residential Lawns:Sub-acre parcel maintenance drives seasonal replacement cycles tied to spring retail promotions. Southeastern homeowners exhibit highest attachment rates for extended warranty and seasonal tune-up programs.
- Commercial Landscaping:Multi-year municipal and corporate contracts enforce fleet standardization and telematics integration. Atlanta and Charlotte contractor density supports specialized equipment-leasing intermediaries.
- Agricultural Fields:Pasture maintenance and rough-cut applications demand reinforced deck structures and higher ground clearance. Rural service territories face technician scarcity that elevates warranty costs for manufacturers.
- Parks & Recreation:Public-sector procurement requires competitive bidding with operator-presence system documentation. OSHA hazard communication rules shape specification templates across state park systems.
- Grounds Maintenance:Institutional facilities management combines mowing with snow removal and debris collection. Attachment compatibility drives platform selection more than cutting performance alone.
Procurement centralization favors Commercial Landscaping for multi-unit fleet agreements; discretionary flexibility favors Residential Lawns for seasonal promotion timing.
End User:
Supply concentration in cutting-deck manufacturing and captive alloy sourcing aligns with end-user scale tiers that determine order-volume predictability.
- Property Managers:Multi-site portfolio oversight demands standardized fleets with interoperable parts and unified maintenance documentation. Telematics-ready platforms command premium positioning for compliance automation.
- Groundskeepers:Municipal and institutional employment structures emphasize operator training certification and documented safety inspection protocols. NHTSA rollover protective structure compliance shapes purchasing criteria.
- Landscape Contractors:Independent business ownership drives financing sensitivity and depreciation-focused asset management. Equipment unbundling from service agreements treats mowers as standalone capital assets.
- Estate Owners:Residential acreage above two hectares motivates commercial-grade specification for time efficiency. Zero-turn configurations gain traction in this segment for maneuverability on irregular lot perimeters.
- Facility Supervisors:Corporate campus and healthcare facility maintenance requires noise ordinance compliance and emission documentation. Electric variants penetrate this user category where indoor-adjacent operation occurs.
Volume concentration favors Landscape Contractors for fleet replacement predictability; specification complexity favors Property Managers for integrated platform standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southeastern United States dominates consumption through year-round turf management contracts, while European demand clusters around emission-compliant fleet renewals and Asia-Pacific growth concentrates in mechanized agricultural conversion.
United States
Landscape contractors in Florida and Georgia expand fleet purchases to service multiplying municipal grounds maintenance agreements. EPA Phase 3 emission standards and NHTSA rollover protective structure requirements compress product engineering timelines for manufacturers. Atlanta and Charlotte contractor density supports specialized equipment-leasing intermediaries that unbundle procurement from service agreements.
Germany
Commercial landscaping firms prioritize emission-compliant fleet standardization for corporate campus maintenance contracts. REACH regulations and EU Green Deal decarbonization targets accelerate electrification roadmaps for outdoor power equipment. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia concentrate precision manufacturing capabilities for cutting-deck components.
China
Mechanized conversion of agricultural turf management drives replacement demand in pasture maintenance applications. MIIT equipment standards and dual carbon goals shape domestic manufacturer R&D priorities toward electric drivetrains. Manufacturing gravity centers on Yangtze River Delta provinces where component supplier ecosystems support assembly scale.
Australia
Estate owners and groundskeepers specify commercial-grade cutting decks for expansive residential acreage and municipal park systems. State-level noise ordinances in New South Wales and Victoria constrain gasoline-engine operation windows in suburban adjacencies. Sydney and Melbourne metropolitan procurement centralizes fleet purchasing for institutional facilities management.
Japan
Compact configuration demand dominates residential estate markets with constrained storage footprints and precise terrain navigation requirements. METI energy efficiency standards and JIS certification protocols govern product safety specifications. Nagoya industrial corridor manufacturers supply precision hydrostatic transmission components to regional assembly operations.
Riding Multi-Purpose Lawn Mower Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidation pressure intensifying as electrification R&D costs escalate. The upper tier commands aftermarket revenue streams through captive parts distribution and multi-year fleet service agreements. Mid-scale specialists compete on attachment compatibility and regional service density. Dominant competitive moves include backward integration into cutting-deck manufacturing and telematics platform development for predictive maintenance monetization.
Among North American equipment manufacturers, Deere & Company and The Toro Company exemplify the integrated-leader archetype through dealership network scale and commercial channel penetration. Husqvarna Group occupies a position within the European specialist tier, representing vertical manufacturing control over alloy sourcing and weld quality specifications. These three anchors illustrate divergent strategic postures: captive distribution infrastructure, fleet relationship lock-in, and upstream component integration.
| Leading Market Players |
|---|
| Deere & Company |
| Husqvarna Group |
| The Toro Company |
| STIGA S.p.A. |
| Kubota Corporation |
| American Honda Motor Co. |
| Briggs & Stratton |
| Ariens Company |
| Robert Bosch |
| Others |
Pricing and Supply Chain Analysis
EPA Phase 3 emission standards gate both supplier qualification and price differentiation simultaneously, forcing OEMs to absorb certification costs in premium tiers while gasoline-engine manufacturers compress margins in residential segments. NHTSA rollover protective structure requirements further stratify pricing across zero-turn, compact, and garden tractor configurations.
Pricing Analysis
Long-term fleet service agreements dominate commercial procurement, locking landscape contractors into multi-year offtake structures with telematics bundling. Three-tier pricing structure across premium, standard, and economy levels separates zero-turn configurations with silicon carbide inverters from carbureted gasoline models. Cost compression in economy tiers intensifies because residential buyers prioritize upfront capital constraints over lifecycle analysis. Landscape contractors exhibit lowest price sensitivity due to labor-hour savings from maneuverability advantages.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for lithium-ion cell imports from South Korea and Japan. Domestic cutting-deck manufacturing draws from captive steel sourcing in Ohio and Pennsylvania mills, with weld quality specifications constraining substitution. Single-source vulnerability concentrates in precision hydrostatic transmission components from Nagoya industrial corridor suppliers. Distribution runs through authorized dealer networks requiring battery-swap competency renegotiation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EPA and NHTSA compliance timelines create certification switching costs that protect incumbent positions against unqualified entrants.
For Market Incumbents: Fortify aftermarket revenue streams through telematics-enabled predictive maintenance platforms that automate OSHA documentation for property managers. Deepen captive parts distribution density in rural service territories where technician scarcity threatens warranty cost escalation. Prioritize backward integration into cutting-deck manufacturing to control alloy sourcing against mill capacity constraints.
For New Entrants and Emerging Players: Anchor in battery recycling infrastructure partnerships with state-level rebate program administrators to secure circular supply economics. Target facility supervisor segments in Texas and North Carolina where indoor-adjacent noise ordinances favor electric variants. Pursue direct-to-contractor leasing models that displace OEM captive finance in Atlanta and Charlotte metropolitan clusters.
For Investors and Strategic Acquirers: EPA Phase 3 state-level adoption ahead of federal mandates reshapes the acquisition landscape toward electrification-ready manufacturing assets. Five-to-ten year viability favors targets with silicon carbide inverter packaging capabilities and existing NHTSA rollover certification pipelines. Monitor battery recycling infrastructure buildout velocity as the primary inflection signal for circular supply chain control.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Development | OSHA compliance automation commands premium positioning among property managers and facility supervisors. |
| Battery Recycling Partnership | State-level rebate durability favors vertically integrated service models with end-of-life lithium-ion processing. |
| Zero-Turn Configuration Expansion | Florida and Georgia landscape contractors absorb premium pricing for reduced mow times on irregular lots. |
| Dealer Network Reconfiguration | Franchise agreement renegotiation incorporates battery-swap and electronics-diagnostic competencies. |
| Silicon Carbide Inverter Adoption | Reduced heat-generation extends duty cycles for commercial fleet operators in southeastern states. |
Research Methodology
Cross-validation between OEM procurement leads and landscape contractor fleet managers anchors the qualitative findings. Primary interviews with dealership operations heads, aftermarket service technicians, municipal groundskeepers, and property management executives combined with secondary validation against EPA certification databases, NHTSA rollover test records, state-level rebate program filings, and equipment-leasing contract registries. Bottom-up unit shipment analysis triangulates against top-down market value reconstruction.
Sensitivity analysis across product type, technology architecture, application intensity, and end-user scale dimensions shapes the projection framework. Modeled segmentation spans zero-turn versus compact configurations, electric motor versus gasoline engine propulsion, commercial landscaping versus residential lawn applications, and landscape contractor versus estate owner purchasing patterns. CAGRs derive from replacement cycle analysis correlated with municipal contract award velocity and lithium-ion cost decline trajectories.
Underlying assumptions cover EPA Phase 3 adoption timelines and NHTSA rollover compliance deadlines, with deviation risk concentrated in state-level regulatory acceleration or battery recycling infrastructure delays. Forecast outputs reflect these documented conditions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.