
 SAP HANA and S4HANA Market | 2026-2036
SAP HANA and S4HANA Market Size, Share, and Industry Trends Forecast 2026-2036
SAP HANA and S4HANA Market Analytics
Manufacturing is expanding its share of S4HANA deployments as factories pursue unified ERP and IoT data streams. SAP anchors the ecosystem through its proprietary database kernel and certification pathways. Accenture leverages its industry-specific implementation templates to dominate complex migration projects. Tata Consultancy Services sustains competitive positioning through scale delivery centers across India and Central Europe.
SAP HANA and S4HANA constitute an in-memory database platform and next-generation enterprise resource planning suite built on SAP's columnar HANA architecture, designed to process transactional and analytical workloads within a single system without separate data warehousing. The platform serves commercial purposes by enabling real-time reporting, predictive analytics, and simplified data models that reduce IT complexity. Cloud-based deployment is capturing the fastest growth as enterprises exit owned data centers, while on-premise installations retain margin concentration among regulated industries with strict data residency requirements. Large enterprises occupy the dominant spending tier, though SME adoption is accelerating through subscription pricing and preconfigured industry editions.
Germany's national data protection authority enforces GDPR compliance that shapes how SAP customers architect cross-border data flows within HANA environments. The EU AI Act imposes documentation and risk-classification requirements on automated decision-making modules integrated into S4HANA workflows. ISO 27001 certification governs information security management for cloud-hosted HANA instances across European deployments. Stakeholders must monitor how regulatory fragmentation between European data localization rules and multi-cloud operational models affects platform architecture decisions.
Market Dynamics
Cloud migration mandates under the EU AI Act and GDPR compliance requirements are accelerating replacement of legacy ECC systems, forcing enterprises to rearchitect data flows around real-time analytics and automated decision-making.
Growth Catalysts
- EU AI Act documentation requirements:Automated risk-classification protocols for S4HANA workflows create upgrade urgency among European manufacturers seeking compliance certainty.
- Manufacturing IoT convergence:Factories demand unified ERP and sensor data streams for predictive maintenance, pulling S4HANA deployments into production environments.
- Germany's data localization gravity:SAP's headquarters proximity and established enterprise relationships concentrate pilot-to-production cycles in German industrial clusters.
Market Restraints
- Specialized HANA migration expertise scarcity:Certified consultants command premium rates, elongating project timelines for complex custom-code remediation.
- Multi-cloud operational friction:Cross-border data residency conflicts between GDPR localization rules and hyperscaler architectures create architectural uncertainty.
- Legacy ABAP technical debt:Decades of custom developments resist automated conversion tools, forcing manual recoding that inflates total cost of ownership.
Strategic Opportunities
- Central European SME segment:Subscription pricing and preconfigured industry editions unlock mid-market manufacturers previously priced out of enterprise ERP.
- Edge-to-cloud analytics convergence:S4HANA integration with factory-floor edge computing enables real-time quality control without separate data warehousing layers.
- CSRD sustainability reporting mandates:Embedded carbon accounting modules position S4HANA as compliance infrastructure for European disclosure requirements.
Industry Challenges
- Dual-stack BASIS administration skills gap:Organizations struggle to staff teams fluent in both legacy ECC and containerized S4HANA operations simultaneously.
- ISO 27001 certification timeline compression:Cloud-hosted HANA instances require accelerated security audits that strain internal compliance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SAP HANA and S4HANA Market |
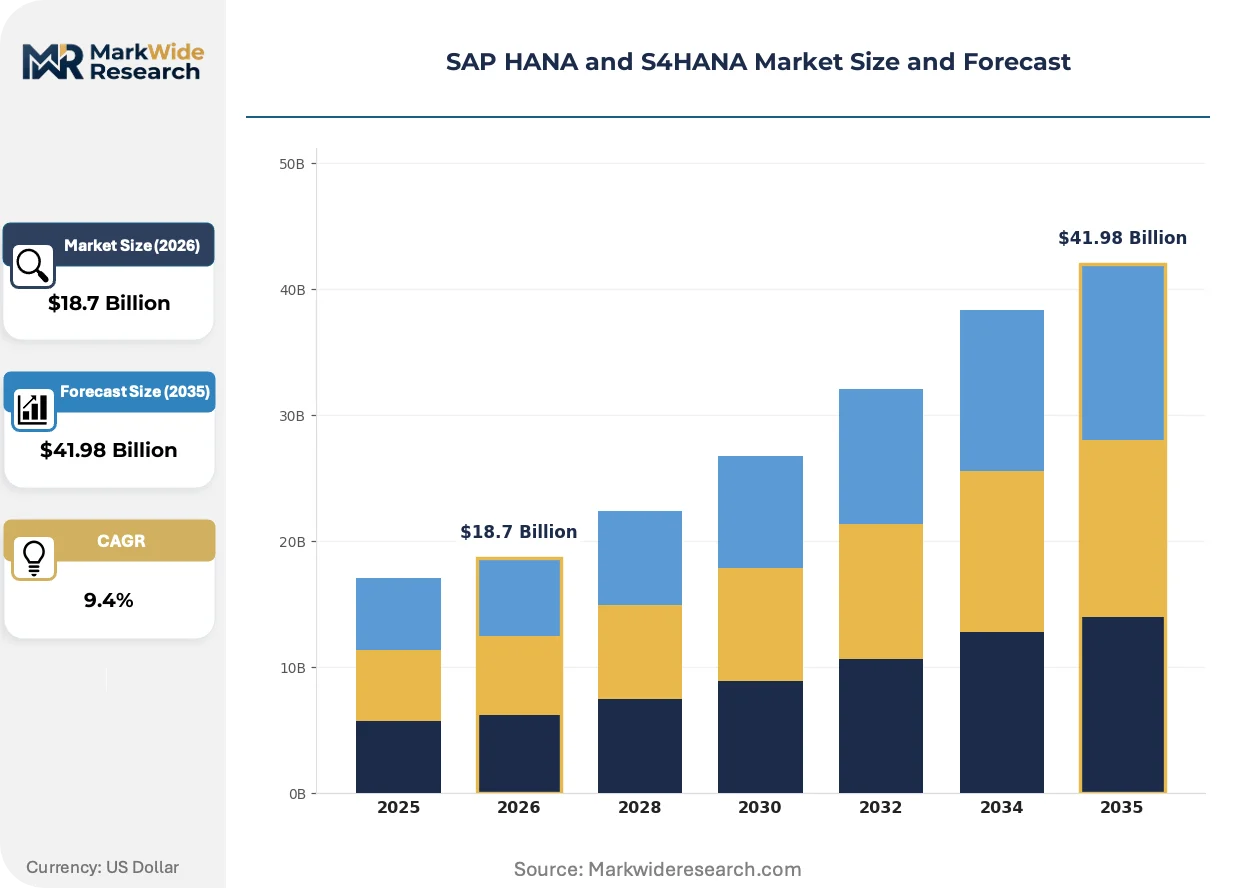
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud-Based, Hybrid, Multi-Cloud Industry Vertical: Manufacturing, Retail, Finance, Healthcare End User: Large Enterprises, SMEs, Government, Educational Institutions Functionality: Data Analytics, Business Intelligence, Reporting, Application Development |
| Companies Covered | IBM, Infosys, SAP, Atos, Accenture, Deloitte, Tata Consultancy Services, Wipro, Capgemini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SAP HANA and S4HANA Market Evolving Landscape
Architectural decoupling is fragmenting monolithic ERP into composable services, allowing enterprises to modernize incrementally rather than through high-risk big-bang migrations.
Embedded AI capabilities within S4HANA is modularizing predictive analytics into discrete business functions. Procurement teams at industrial manufacturers now consume demand-forecasting models as native workflow components rather than separate BI tools. This decomposition is compressing vendor consolidation cycles as point solutions lose standalone justification.
Germany's Federal Office for Information Security (BSI) has issued cloud compliance guidelines that reshape how SAP customers architect cross-border data flows. Industrial enterprises must now document data sovereignty controls for HANA instances spanning multiple jurisdictions. Automotive suppliers with German headquarters are restructuring multi-cloud contracts to satisfy these certification requirements.
Subscription consumption models are displacing perpetual license purchasing among mid-market buyers. Channel partners now deliver S4HANA through managed service wrappers that bundle infrastructure, support, and continuous updates. This preference shift is most pronounced in German-speaking markets where CFOs prioritize operational expenditure predictability over capital ownership.
SAP HANA and S4HANA Market Segmentation
SAP HANA and S4HANA deployments fragment across infrastructure choices, regulatory postures, and operational maturity levels. Understanding these divides clarifies where upgrade urgency concentrates and which customer profiles warrant differentiated implementation approaches.
Deployment Model:
Migration cycles from legacy ECC systems reveal starkly different risk appetites across infrastructure strategies.
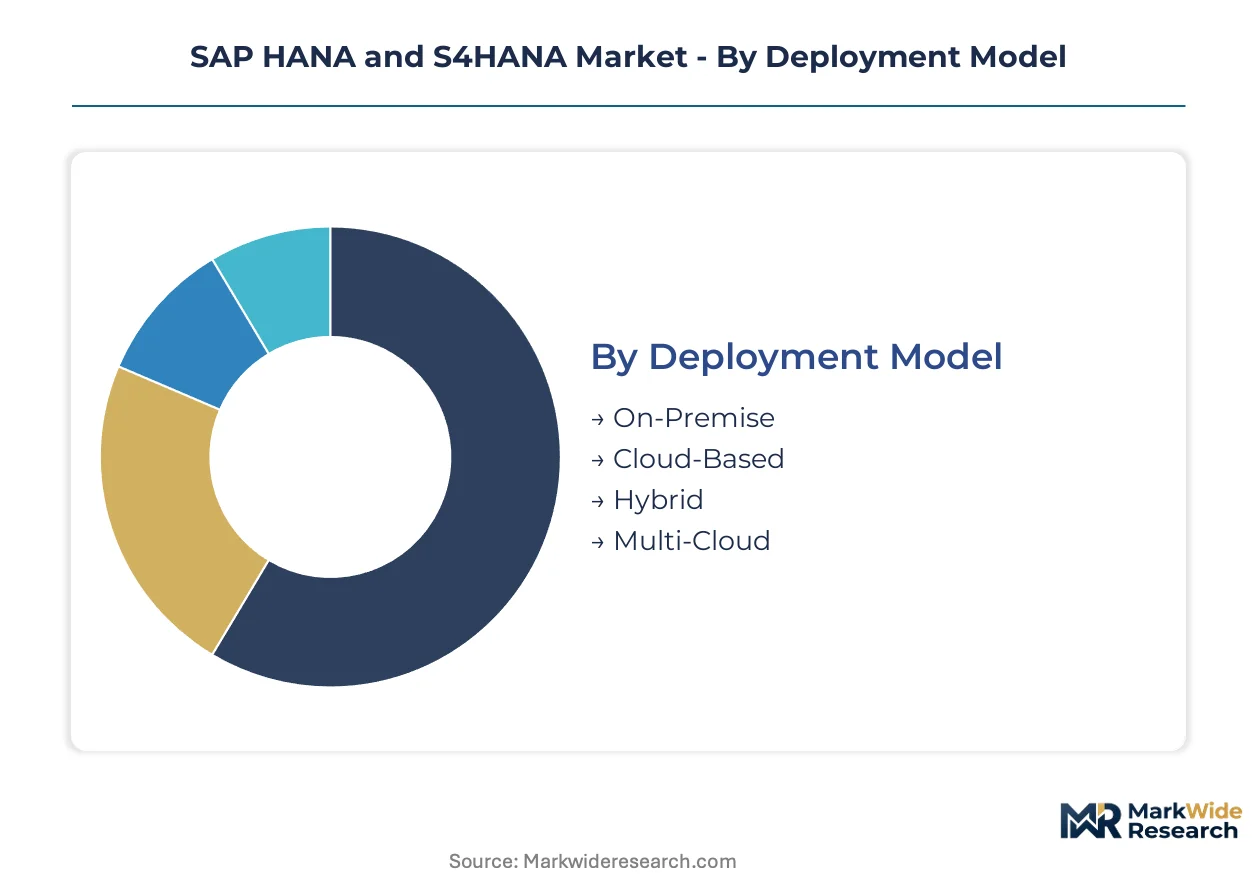
- Cloud-Based:Hyperscaler-hosted HANA instances eliminate data center capital burdens while embedding automated compliance patches for GDPR and EU AI Act requirements. German automotive suppliers and industrial manufacturers dominate early adoption, driven by CFO preferences for operational expenditure predictability and SAP's proximity for escalation support.
- On-Premise:Retained installations serve regulated industries with strict data residency mandates—Swiss banking, French defense supply chains, and German critical infrastructure operators. These deployments retain margin concentration through premium support contracts and specialized BASIS administration.
- Hybrid:Split workloads keep transactional cores on-premises while pushing analytics to cloud tiers.
- Multi-Cloud:Distributed architectures across AWS, Azure, and GCP reduce vendor lock-in but amplify cross-border data flow complexity.
Cloud-Based sits at the top of the volume ranking, with Multi-Cloud climbing the fastest as sovereignty-conscious enterprises seek architectural flexibility.
Industry Vertical:
Functional requirements diverge sharply between asset-heavy production environments and transaction-intensive service sectors.
- Manufacturing:Factory-floor IoT convergence demands real-time sensor ingestion into S4HANA cores for predictive maintenance and quality control. German industrial clusters—automotive in Stuttgart, chemicals in Ludwigshafen, machinery in Munich—anchor deployment density.
- Finance:Banking and insurance workloads stress transactional throughput and audit trail immutability. Swiss private banks and Frankfurt-based insurers maintain on-premise dominance due to FINMA and BaFin supervisory expectations.
- Retail:Omnichannel inventory synchronization and demand forecasting drive cloud preference among fashion and grocery chains.
- Healthcare:Hospital networks and pharmaceutical distributors prioritize patient data isolation, slowing cloud migration despite embedded AI diagnostic modules.
Manufacturing commands the largest installed base, though Finance demonstrates the steepest expansion trajectory as EBA stress-testing and CSRD disclosure mandates force platform refreshes.
End User:
Customer scale determines implementation methodology, staffing models, and vendor engagement intensity.
- Large Enterprises:Complex custom-code estates and multi-entity consolidations demand Accenture-style system integrators with industry-specific templates. These projects stretch 18-36 months and absorb the majority of certified HANA migration specialists.
- SMEs:Mid-market manufacturers previously priced out of enterprise ERP now access preconfigured industry editions through subscription consumption. German-speaking markets—Austria, Switzerland, plus German Länder—show strongest uptake via channel-managed service wrappers.
- Government:Federal and state agencies face procurement rigidity and security clearance requirements that elongate sales cycles.
- Educational Institutions:Universities and research centers leverage academic licensing for supply chain management curricula and HANA-native research computing.
Large Enterprises retain the deepest project values, while SMEs gain share fastest as SAP's RISE with SAP program compresses time-to-value for sub-billion-revenue manufacturers.
Functionality:
Technical use case selection reflects organizational data maturity and analytical ambition.
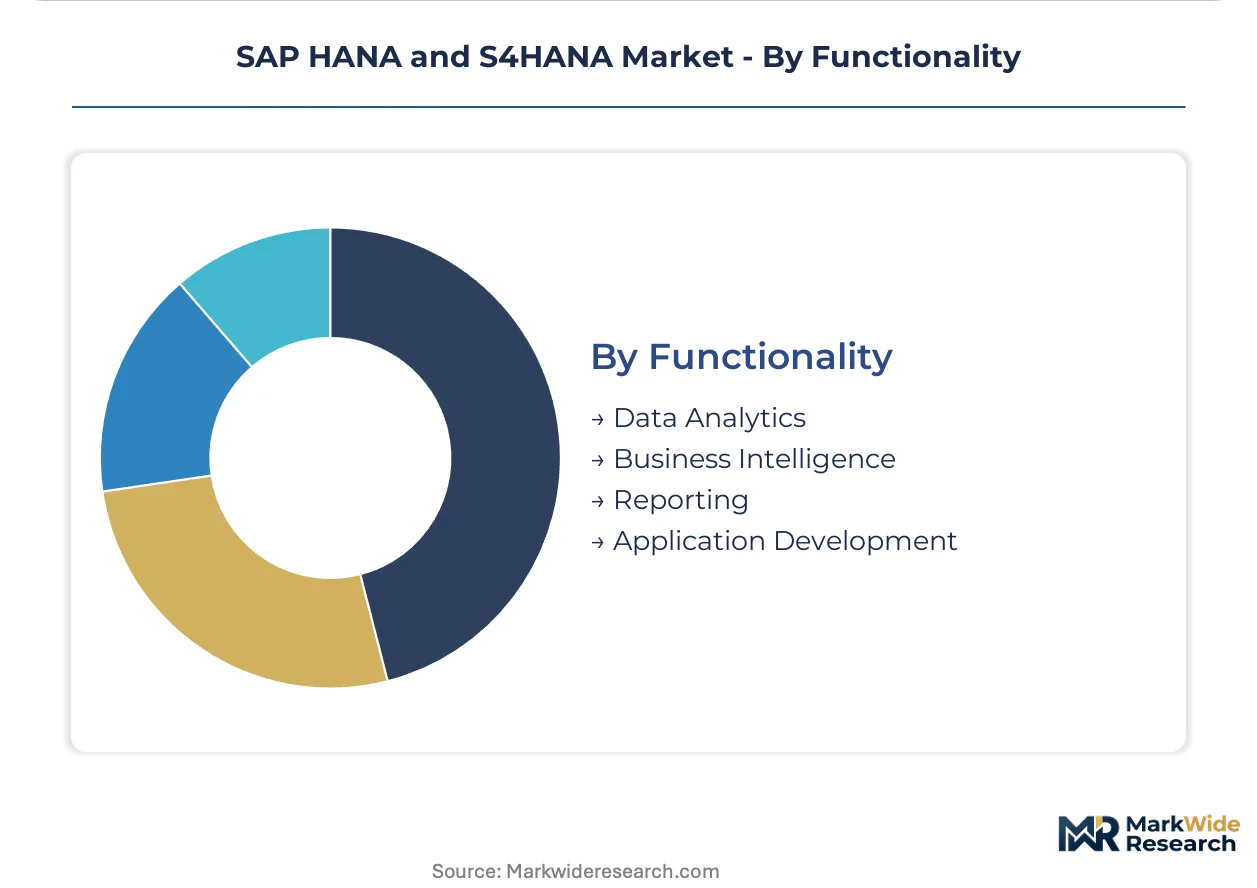
- Data Analytics:In-memory columnar processing eliminates separate data warehousing layers, enabling real-time operational dashboards. Manufacturing quality engineers and finance controllers represent core demand clusters.
- Business Intelligence:Embedded predictive models—demand forecasting, cash flow projection, supplier risk scoring—modularize AI consumption within familiar workflow contexts.
- Reporting:CSRD sustainability disclosures and management board packs drive standardized output requirements.
- Application Development:ABAP and JavaScript-based extensions on SAP BTP allow custom process automation without core system modification.
Data Analytics leads functional deployment, with Business Intelligence expanding most quickly as procurement and supply chain teams adopt native predictive capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between data localization mandates and cloud operational flexibility is redrawing where enterprises choose to host SAP HANA workloads. Compliance cost differentials across jurisdictions are accelerating migration decisions toward markets with clearer certification pathways.
Germany
Automotive suppliers in Stuttgart and chemical producers in Ludwigshafen are driving S4HANA adoption for real-time supply chain visibility. The Federal Office for Information Security enforces BSI cloud compliance guidelines that reshape cross-border data architecture. Munich-based industrial clusters anchor the densest concentration of pilot-to-production deployments.
United States
Fortune 500 manufacturers and defense contractors are modernizing ERP estates under pressure from supply chain resilience directives. The SEC's climate disclosure rules intersect with CSRD-equivalent reporting demands for multinational subsidiaries. Chicago and Houston industrial corridors host the largest concentration of hybrid HANA deployments.
India
IT services exporters and domestic conglomerates are expanding HANA footprints to support real-time analytics for global delivery operations. The Reserve Bank of India's data localization requirements for financial services create captive on-premise demand. Bengaluru and Hyderabad technology parks concentrate certified migration specialist talent pools.
Switzerland
Private banking groups and pharmaceutical headquarters maintain on-premise dominance due to FINMA supervisory expectations around audit trail immutability. The country's data protection framework exceeds baseline GDPR stringency for cross-border transfers. Zurich and Basel financial centers sustain premium support contract concentration.
United Kingdom
Post-Brexit regulatory divergence is complicating data flow architectures for enterprises with EU exposure. The Financial Conduct Authority's operational resilience requirements are forcing platform refreshes among London insurers. Manchester and Birmingham manufacturing hubs are adopting subscription-based S4HANA editions.
SAP HANA and S4HANA Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with system integrators capturing margin concentration in complex migration projects while cloud hyperscalers absorb infrastructure commoditization. The vendor base organizes around three strategic archetypes: global consultancies with industry templates, offshore scale delivery operators, and SAP-certified boutique specialists. Consolidation pressure is intensifying through vertical capability acquisitions and strategic cloud partnership formations.
Among global consultancies, Accenture and Deloitte exemplify the template-driven implementation archetype, anchoring large enterprise transformations through preconfigured industry methodologies. Tata Consultancy Services occupies a position within the offshore scale tier, leveraging delivery center networks across India and Central Europe. SAP itself sits at the platform core, controlling certification pathways and database kernel architecture that constrain competitive positioning for adjacent service providers.
| Leading Market Players |
|---|
| IBM |
| Infosys |
| SAP |
| Atos |
| Accenture |
| Deloitte |
| Tata Consultancy Services |
| Wipro |
| Capgemini |
| Others |
Value Network & Pricing Analysis
In-memory columnar database migration from legacy row-based architectures compresses hardware refresh cycles while concentrating certified migration expertise in German and Indian delivery centers. This technological inflection simultaneously elevates premium pricing for scarce HANA specialists and forces subscription model adoption among mid-market buyers seeking predictable operational expenditure.
Pricing Analysis
Channel partner margins on managed service wrappers absorb 15-25 percentage points above direct SAP list pricing, with Accenture and Tata Consultancy Services commanding widest spreads due to proprietary industry templates. Three-tier pricing structure across premium certified-consulting, standard system-integration, and economy offshore-delivery levels differentiates project economics, with volume scale and customization depth as primary levers. Cost compression in the offshore tier intensifies because Indian delivery center expansion outpaces certified specialist supply. Mid-market manufacturers in German-speaking markets exhibit highest price sensitivity, while Fortune 500 industrial conglomerates prioritize compliance certainty over rate negotiation.
Supply Chain Analysis
Freight costs for hyperscaler hardware into Central European data centers add 8-12% landed cost premiums versus APAC direct provisioning, tilting cloud migration economics toward regional hosting partnerships. Supply concentrates in Germany for SAP kernel development and certification authority, India for scale delivery talent, and Ireland for EU data residency compliance. Raw material dependencies span Intel Xeon processors, Samsung HBM memory modules, and Cisco networking equipment. Single-source vulnerability around SAP's proprietary database kernel creates architectural lock-in risk. Distribution runs through direct SAP sales for enterprise accounts and channel-managed service wrappers for SME segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on automated conversion tool advancement reducing manual ABAP recoding labor, alongside premium-tier cloud migration services capturing compliance-driven upgrade urgency.
For Market Incumbents: Anchor defensive positioning through captive certification program scale-up in Bengaluru and Munich delivery centers, while embedding ISO 27001 compliance automation into managed service offerings. Threat substitution from low-code ERP alternatives demands vertical integration into edge-to-cloud analytics middleware. Capacity addition in Swiss and Austrian data centers addresses FINMA-grade data residency requirements. For New Entrants and Emerging Players: Embedded AI diagnostic modules for predictive maintenance represent the most penetrable wedge, targeting mid-market automotive suppliers in Stuttgart industrial clusters with preconfigured industry editions. White-space concentration in CSRD sustainability reporting compliance tooling for German chemical producers offers second entry vector. Go-to-market through SAP BTP marketplace listings reduces customer acquisition friction versus direct enterprise sales cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among boutique HANA migration specialists with deep ABAP legacy code expertise but limited brand recognition. Long-term viability across the analysis window favors platform-agnostic analytics layer investments over pure-play implementation services. Acquisition target archetype: 50-200 person firms with German automotive vertical concentration and existing SAP partner status. Signal to watch: EU AI Act enforcement timeline acceleration triggering compliance-driven budget releases.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedded AI modules in S4HANA cores enable predictive maintenance without separate BI infrastructure. |
| Geographic Expansion | Swiss and Austrian data center buildouts satisfy FINMA data residency for private banking clients. |
| Acquisition of Specialist Firm | Boutique ABAP remediation shops address legacy technical debt conversion bottleneck. |
| Strategic Partnership | Hyperscaler alliances embed automated GDPR compliance patches into cloud-hosted instances. |
| Product Launch | Preconfigured industry editions compress SME time-to-value through subscription consumption. |
Research Methodology
Multiple input streams — primary interviews with SAP BASIS administrators, cloud migration project managers, and industrial manufacturing CIOs; secondary validation through SAP SE regulatory filings, BSI cloud compliance guidelines, and EU AI Act documentation requirements; plus customs data on hyperscaler hardware imports — were reconciled through bottom-up deployment tracking and top-down market sizing triangulation.
Data-stream reconciliation anchored the forecast framework across deployment model, organization size, vertical concentration, and regional regulatory cluster dimensions. CAGRs were derived from trend extrapolation of migration pipeline visibility and compliance deadline proximity. Industry-specific inputs included certified consultant supply estimates and cloud infrastructure capex disclosure patterns from hyperscaler partners.
The model holds under steady EU AI Act enforcement interpretation and stable hyperscaler pricing; deviation in regulatory fragmentation severity or memory chip supply disruption would shift migration timeline assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global ITSM Software Market
Software & Services
Lease Accounting and Management Software Market
Software & Services
Global Order Management Software Market
Software & Services
Android Emulator Market
Software & Services
Latin America ERP Software Market
Software & Services
Observability Platform Market
Software & Services
Saas-Based Expense Management Market
Software & Services
Global Offshore Software Development Market
Software & Services
Global Kiosk Software Market
Software & Services
Africa Sports Management Software Market
Software & Services
Global Maintenance Management Software Market
Software & Services
Audit Management Software Market
Software & Services
Engineering Software Market
Software & Services
Global Church Management Software Market
Software & Services
Enterprise Resource Planning (ERP) Software Market
Software & Services
India Sports Management Software Market