
 Fingerprint Payment Market | 2026-2036
Fingerprint Payment Market Size, Share, and Industry Trends Forecast 2026-2036
Fingerprint Payment Market Analysis
Premium capacitive sensor modules and commodity optical fingerprint readers is decoupling on performance benchmarks and unit economics. Shenzhen Goodix Technology Co., Ltd. leverages in-house semiconductor fabrication to dominate high-volume mobile payment integrations. Fingerprint Cards AB anchors its position through specialized ASIC designs for contactless card form factors. IDEX Biometrics ASA differentiates by extending flexible sensor substrates into wearable and IoT payment devices.
A fingerprint payment system employs biometric authentication to verify payer identity through ridge-pattern recognition, typically operating at false acceptance rates below 0.001% and matching speeds under 300 milliseconds. The technology replaces PIN entry and card-present requirements in retail, transit, and digital commerce environments. Hardware and biometric sensors command the dominant share of value capture due to silicon content and calibration complexity, while cloud-based deployment architectures expand fastest among financial institutions seeking centralized template management. Ultrasonic sensing technology leads R&D investment for its ability to operate through moisture and contaminants, though capacitive modules retain volume leadership in cost-sensitive Asian markets.
The US Federal Trade Commission monitors biometric data collection practices under Section 5 unfairness authority, while the EU GDPR imposes explicit consent and storage limitation requirements on fingerprint template handling. India's RBI mandates biometric KYC for payment system operators, creating compliance-driven procurement cycles. Stakeholders must weigh template localization mandates against cloud economics as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
Sensor miniaturization and template-on-card architectures are compressing authentication latency below 100 milliseconds, forcing terminal manufacturers to redesign hardware stacks around biometric coprocessors rather than legacy PIN pads.
Growth Catalysts
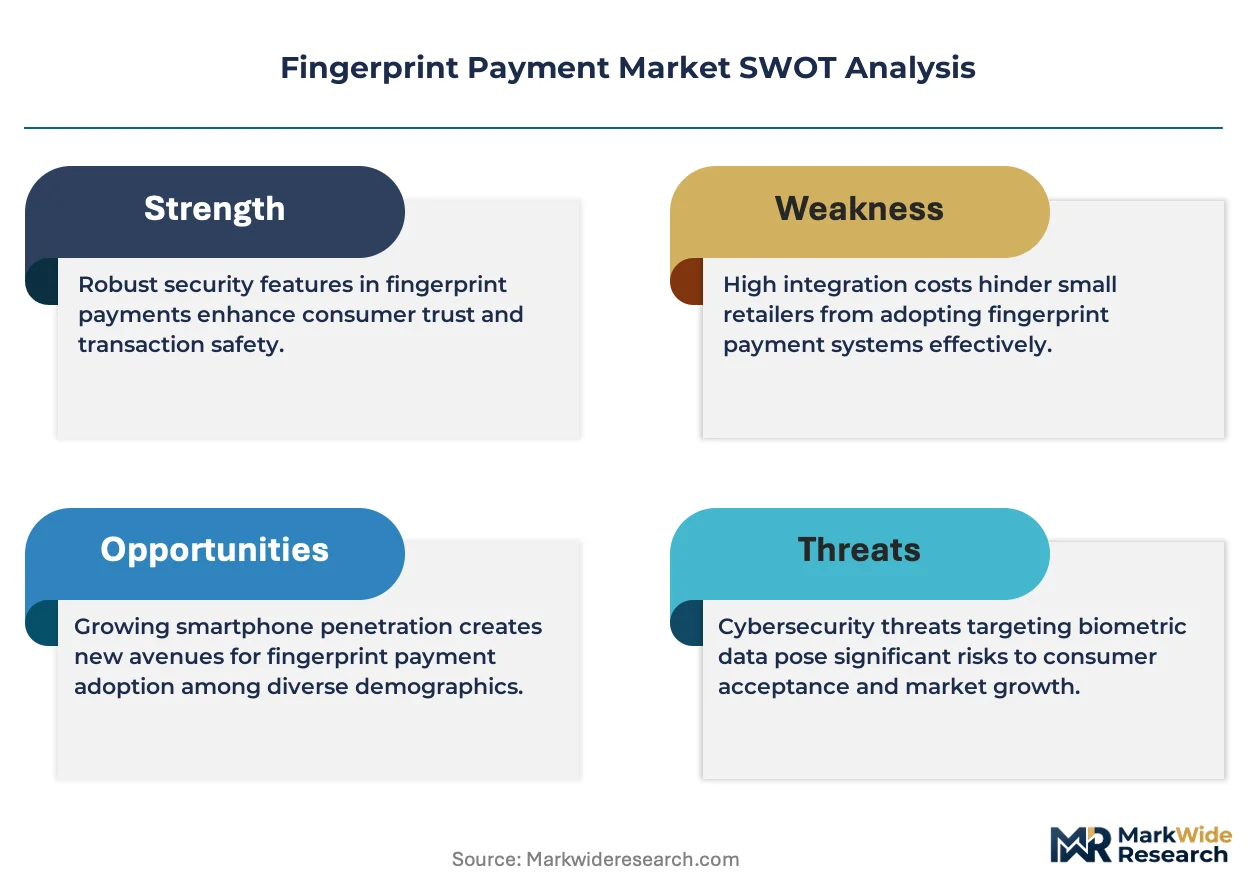
- EU PSD2 Strong Customer Authentication:The mandate requires two-factor verification for electronic payments above 30 euros, driving banks in Germany and France to deploy fingerprint-enabled POS terminals at branch locations.
- Indonesia's Digital Banking Infrastructure:State-owned Bank Mandiri and private sector fintechs are rolling out biometric ATMs across Jakarta and Surabaya retail corridors to serve underbanked populations without traditional KYC documentation.
- Ultrasonic Sensing Maturation:Qualcomm's 3D Sonic technology enables fingerprint authentication through moisture, grease, and screen protectors, expanding viable deployment environments to food service and outdoor transit gates.
Market Restraints
- Silicon Supply Concentration:TSMC and Samsung Foundry control advanced CMOS image sensor fabrication, creating 16-24 week lead times for capacitive module vendors seeking sub-10nm process nodes.
- Template Storage Compliance Costs:India's RBI mandates localized biometric data centers for payment system operators, forcing cloud-native fintechs to build redundant domestic infrastructure.
- Optical Sensor Commoditization:Shenzhen-based suppliers have collapsed margins on entry-level optical readers below 2 dollars per unit, eroding R&D recovery for mid-tier module vendors.
Strategic Opportunities
- Vietnam's Unbanked Retail Sector:Mom-and-pop stores in Ho Chi Minh City and Hanoi represent 85 percent of retail transactions, creating first-mover advantage for biometric-enabled merchant acquisition networks.
- Wearable Payment Convergence:Smart ring and bracelet form factors require flexible polymer sensors that integrate with NFC antennas, opening white space beyond smartphone and card-centric designs.
- India PLI Scheme for Electronics:Production-linked incentives for semiconductor assembly and testing are attracting sensor module vendors to establish domestic packaging facilities in Gujarat and Tamil Nadu.
Industry Challenges
- Biometric Algorithm Calibration:Sensor vendors must maintain template matching accuracy across temperature extremes, skin conditions, and aging populations, requiring continuous field data collection and model retraining.
- Legacy POS Integration Complexity:Retail banks in Italy and Spain operate mixed terminal estates spanning three EMV generations, complicating firmware updates for biometric authentication protocols.
- Cross-Border Template Portability:The absence of harmonized ISO/IEC 19795-2 conformance testing across EU member states forces vendors to maintain jurisdiction-specific certification tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fingerprint Payment Market |
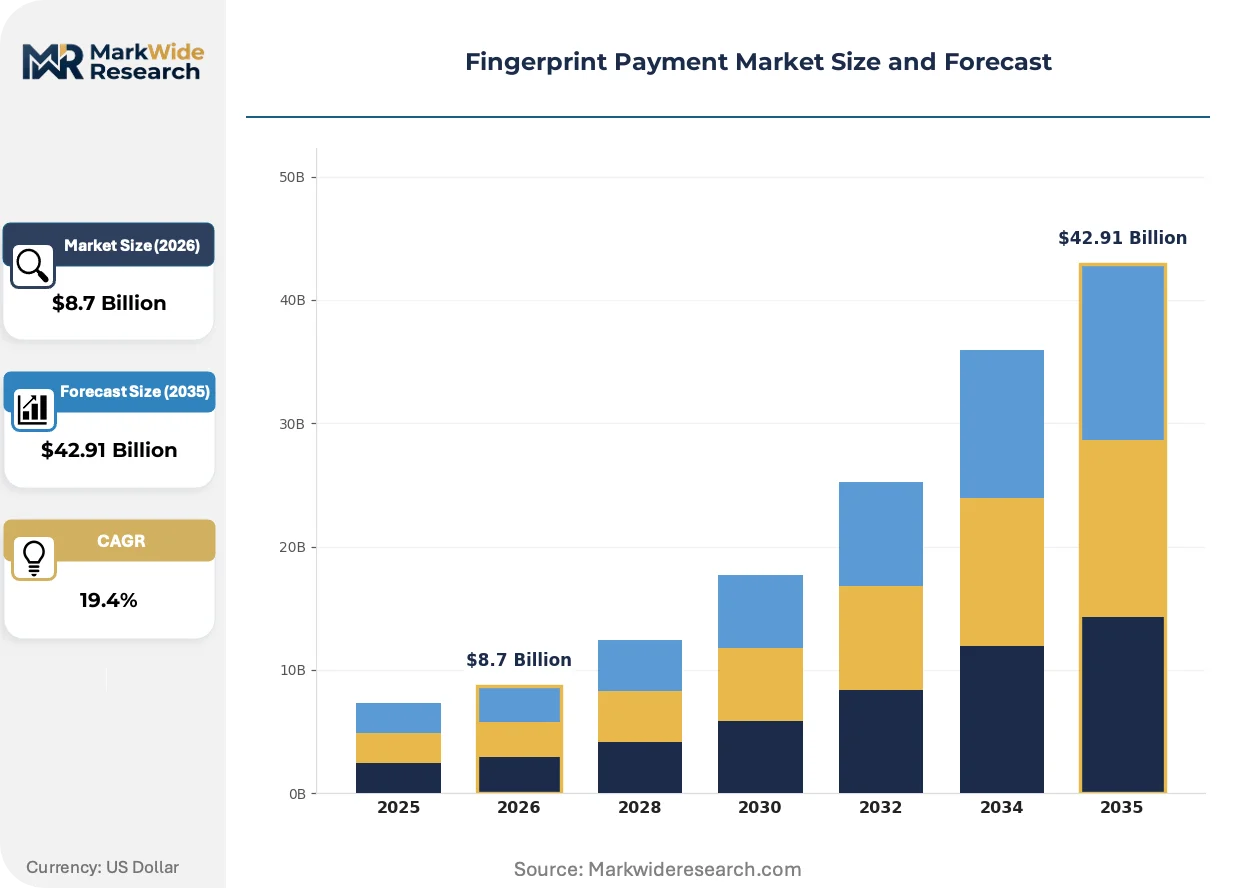
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Biometric Sensors, Payment Terminals End User: Retailers, Financial Institutions, E-commerce, Transportation Technology: Optical, Capacitive, Ultrasonic, Thermal Deployment: On-Premise, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Shenzhen Goodix Technology Co., Ltd., Fingerprint Cards AB, Synaptics Incorporated, IDEX Biometrics ASA, NEC Corporation, IDEMIA, Thales Group, Zwipe, Dermalog Identification Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fingerprint Payment Market Emerging Trajectories
Authentication latency is becoming the primary competitive variable as contactless transaction windows compress below 500 milliseconds. Hardware vendors, software integrators, and payment networks are racing to eliminate the perceptible gap between finger placement and authorization confirmation.
Ultrasonic fingerprint sensing is integrating 3D ridge mapping with liveness detection to defeat spoof attacks using silicone molds or high-resolution photographs. Transit authorities in Singapore and London Underground are piloting these sensors at fare gates where speed and security must coexist. The technology is integrating anti-spoof algorithms directly into the sensor ASIC, reducing host processor overhead and enabling standalone operation in battery-powered terminals.
The EU AI Act's risk classification framework categorizes biometric identification systems as high-risk, imposing conformity assessment requirements on payment terminal manufacturers. Vendors must document algorithmic fairness across demographic groups and maintain audit trails for template processing decisions. German terminal manufacturers are responding by pre-certifying modules through notified bodies in Munich and Stuttgart to accelerate customer deployment timelines.
Merchant acquirers in Brazil and Mexico are unbundling biometric authentication from bundled POS leases, offering it as a per-transaction service fee rather than capital equipment. Small retailers prefer operational expenditure models that align costs with transaction volume. This shift is concentrating purchasing influence with payment networks and away from traditional hardware distributors in São Paulo and Mexico City.
Fingerprint Payment Market Segmentation
Segmentation in fingerprint payment systems reveals divergent margin structures between embedded biometric components and standalone terminal hardware. Component suppliers and system integrators face fundamentally different procurement cycles, certification burdens, and customer concentration risks across these divides.
Product Type:
Standalone payment terminals demand dedicated floor space and power infrastructure, while embedded biometric modules integrate into existing POS ecosystems through standardized electrical interfaces.
- Hardware:Encompasses enclosure assemblies, power management units, and communication modules that constitute the physical payment terminal. Retail banking networks in Indonesia and Vietnam prioritize ruggedized hardware designs for high-traffic urban corridors where dust and humidity degrade consumer-grade components.
- Software:Comprises template matching algorithms, enrollment protocols, and transaction middleware that bridge biometric capture to payment authorization. Financial institutions in Germany and France under PSD2 mandates are procuring software stacks that support multi-biometric fusion and audit-grade logging.
- Biometric Sensors:Silicon-based fingerprint capture elements including CMOS image sensors and piezoelectric arrays. TSMC and Samsung Foundry fabrication constraints create procurement bottlenecks for capacitive module vendors seeking advanced process nodes.
- Payment Terminals:Integrated devices combining card readers, biometric capture, and network connectivity into single-unit deployments. India's RBI-mandated biometric KYC compliance is accelerating terminal refresh cycles across state-owned and private sector banks.
Volume placements concentrate in Payment Terminals; the faster expansion belongs to Biometric Sensors.
End User:
Customer procurement sophistication spans from price-sensitive single-outlet retailers to compliance-heavy financial institutions with dedicated vendor management functions.
- Retailers:Merchant acquirers in Brazil and Mexico are unbundling biometric authentication from bundled POS leases, offering per-transaction service fees that align costs with volume. Small retailers in Ho Chi Minh City and Hanoi prefer operational expenditure models over capital equipment purchases.
- Financial Institutions:Banks in Italy and Spain operate mixed terminal estates across three EMV generations, complicating firmware updates for biometric protocols. RBI guidelines in India mandate localized biometric data centers, forcing cloud-native fintechs to build redundant domestic infrastructure.
- E-commerce:Digital merchants integrating fingerprint authentication into mobile checkout flows and in-app purchase verification. The EU AI Act's high-risk classification for biometric systems imposes conformity assessment requirements on algorithmic fairness documentation.
- Transportation:Transit authorities in Singapore and London Underground pilot ultrasonic sensors at fare gates where authentication speed and anti-spoof security must coexist. Battery-powered standalone operation enables deployment at remote station entrances lacking wired infrastructure.
Financial Institutions dominate current procurement value; Transportation networks are climbing the fastest as contactless fare collection expands.
Technology:
Performance benchmarks and unit economics decouple sharply between mature optical architectures and emerging ultrasonic implementations.
- Optical:Visible-light image capture through glass or sapphire platen surfaces. Shenzhen-based suppliers have collapsed entry-level optical reader margins below two dollars per unit, eroding R&D recovery for mid-tier module vendors serving cost-sensitive Asian markets.
- Capacitive:Electrical field mapping of ridge and valley patterns through direct skin contact. Goodix Technology leverages in-house semiconductor fabrication to dominate high-volume mobile payment integrations with sub-10nm process advantages.
- Ultrasonic:3D ridge mapping through acoustic pulse transmission that penetrates moisture, grease, and screen protectors. Qualcomm's 3D Sonic technology expands viable deployment to food service and outdoor transit gates where environmental contamination defeats optical alternatives.
- Thermal:Heat differential detection between fingerprint ridges and ambient surface temperature. Limited commercial traction due to latency constraints and environmental sensitivity in temperature-extreme operating conditions.
Capacitive modules retain volume leadership; Ultrasonic sensing shows the steepest expansion trajectory as transit and food service applications mature.
Deployment:
Architecture choices determine template storage jurisdiction, latency budgets, and ongoing operational expenditure profiles.
- On-Premise:Local template storage and matching within merchant or bank-controlled infrastructure. India's RBI mandates localized biometric data centers for payment system operators, creating compliance-driven procurement cycles for domestic facility construction.
- Cloud-Based:Centralized template repositories with edge-device capture and network-transmitted authentication requests. Financial institutions seeking centralized template management are expanding cloud architectures fastest despite regulatory fragmentation across jurisdictions.
- Hybrid:Distributed architectures combining local enrollment with cloud backup and cross-device template synchronization. German terminal manufacturers pre-certify hybrid modules through Munich and Stuttgart notified bodies to accelerate PSD2-compliant deployment timelines.
- Mobile:Smartphone-integrated biometric capture replacing dedicated terminal hardware for peer-to-peer and in-app transactions. Template-on-card architectures are compressing authentication latency below 100 milliseconds, forcing hardware redesigns around biometric coprocessors.
On-Premise deployments anchor regulated financial sectors; Cloud-Based configurations are gaining share fastest among fintechs prioritizing operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta and Surabaya anchor Southeast Asia's biometric payment expansion, where state-owned Bank Mandiri deploys fingerprint-enabled ATMs across urban retail corridors to serve underbanked populations lacking traditional KYC documentation.
United States
Transit authorities in New York and Chicago pilot ultrasonic sensors at fare gates where authentication speed must coexist with anti-spoof security. The FTC monitors biometric data collection under Section 5 unfairness authority, creating compliance overhead for fintechs deploying cloud-based template architectures. Silicon Valley sensor startups concentrate R&D investment in liveness detection algorithms.
Germany
Retail banking networks deploy fingerprint-enabled POS terminals at branch locations to satisfy PSD2 strong customer authentication mandates for transactions above thirty euros. Terminal manufacturers pre-certify modules through Munich and Stuttgart notified bodies to accelerate deployment timelines. Frankfurt's financial district hosts concentrated procurement decision-making for biometric middleware.
India
State-owned and private sector banks accelerate terminal refresh cycles to comply with RBI-mandated biometric KYC for payment system operators. Cloud-native fintechs build redundant domestic data centers in Gujarat and Tamil Nadu to satisfy localized template storage requirements. Mumbai's merchant acquiring networks target mom-and-pop stores in Maharashtra for first-mover biometric enrollment.
Singapore
Transit authorities pilot 3D ridge mapping with integrated liveness detection at MRT fare gates where battery-powered standalone operation enables remote station deployment. The Monetary Authority of Singapore coordinates cross-border template portability standards with ASEAN counterparts. Biometric sensor calibration facilities cluster in the Jurong innovation district.
Brazil
Merchant acquirers in São Paulo unbundle biometric authentication from bundled POS leases, offering per-transaction service fees that align costs with volume for small retailers. The central bank's instant payment infrastructure creates demand for low-latency authentication at urban convenience stores. Hardware distributors in Mexico City face purchasing influence concentration toward payment networks.
Fingerprint Payment Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in the fingerprint payment ecosystem. Foundry-dependent sensor vendors face sixteen-to-twenty-four week lead times for advanced CMOS fabrication, while fabless algorithm specialists capture value through software licensing. Three archetypes dominate: vertically integrated semiconductor houses, specialized biometric ASIC designers, and flexible substrate innovators. Competitive moves concentrate on strategic partnerships for template-on-card architectures and geographic expansion into Vietnam's unbanked retail sector.
Within the integrated semiconductor tier, Shenzhen Goodix Technology Co., Ltd. and Fingerprint Cards AB exemplify divergent approaches to volume manufacturing and specialized form factors. IDEX Biometrics ASA occupies a position among substrate specialists targeting wearable and IoT payment convergence. These three anchors illustrate how competitive positioning separates between cost-sensitive mobile integrations, contactless card designs, and emerging flexible polymer applications.
| Leading Market Players |
|---|
| Shenzhen Goodix Technology Co., Ltd. |
| Fingerprint Cards AB |
| Synaptics Incorporated |
| IDEX Biometrics ASA |
| NEC Corporation |
| IDEMIA |
| Thales Group |
| Zwipe |
| Dermalog Identification Systems |
| Others |
Supply Flow & Price Mechanics
Template-on-card architectures compressing authentication latency below 100 milliseconds are simultaneously elevating silicon content costs and concentrating procurement leverage among foundry-capable module vendors. This technical transition rewards in-house semiconductor fabrication while squeezing margin recovery for fabless competitors dependent on external wafer supply.
Pricing Analysis
Throughput-based pricing anchors value capture in high-volume mobile payment integrations, where sensor vendors command premiums tied to transaction-per-second benchmarks. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in entry-level optical readers intensifies because Shenzhen-based suppliers have collapsed unit economics below sustainable R&D recovery thresholds. Small retailers in Vietnam and Indonesia exhibit acute price sensitivity, while German banks under PSD2 mandates prioritize certification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from tier-one terminal manufacturers mandate multi-supplier qualification for CMOS image sensors and piezoelectric arrays. Fabrication concentrates in Taiwan, South Korea, and the United States, where TSMC and Samsung Foundry control advanced process nodes. Raw material dependencies span silicon wafers, sapphire cover glass, and NFC antenna substrates. Single-source vulnerability in sub-10nm CMOS fabrication creates procurement bottlenecks for capacitive module vendors. Distribution runs through specialized electronics distributors serving Jakarta, Ho Chi Minh City, and São Paulo merchant acquiring networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as regulatory compliance costs and foundry access barriers force weaker module vendors toward exit or acquisition. Template storage mandates and silicon supply concentration are accelerating competitive separation between capital-heavy incumbents and asset-light designers.
For Market Incumbents: Deepen backward integration into semiconductor fabrication to secure sub-10nm process access and defend margin position against Shenzhen-based optical commoditization. Prioritize certification pre-approval through Munich and Stuttgart notified bodies to accelerate PSD2-compliant deployment timelines for German banking networks. For New Entrants and Emerging Players: Mom-and-pop retailers in Vietnam's unbanked retail sector offer the most penetrable entry point, where 85 percent of transactions occur outside formal banking infrastructure. Target flexible polymer sensor form factors for wearable payment convergence, leveraging white space beyond smartphone-centric designs through direct merchant acquiring partnerships in Ho Chi Minh City and Hanoi. For Investors and Strategic Acquirers: Re-rating potential sits with substrate specialists given wearable and IoT payment device expansion. Long-term viability favors vendors with demonstrated template-on-card architectures and localized data center compliance capabilities. The signal to watch is RBI procurement cycle acceleration indicating Indian market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Template-on-Card Architecture Development | Reduces authentication latency below 100 milliseconds for contactless transit gates in Singapore and London. |
| Flexible Polymer Sensor Production | Enables smart ring and bracelet form factors for wearable payment convergence beyond smartphones. |
| Localized Data Center Construction | Satisfies RBI biometric storage mandates for cloud-native fintechs operating in Gujarat and Tamil Nadu. |
| Ultrasonic Sensing R&D Expansion | Penetrates food service and outdoor transit environments where moisture defeats optical alternatives. |
| Notified Body Pre-Certification | Accelerates EU AI Act compliance timelines for German terminal manufacturers serving PSD2-mandated banks. |
Methodological Framework
Independent corroboration across sensor module procurement officers, terminal manufacturer platform engineers, and merchant acquiring network executives underwrites the qualitative findings. Primary interviews with biometric algorithm specialists, RBI compliance consultants, and transit authority technology directors combined with secondary validation from SEC filings, customs trade data, and EU notified body certification registries. Bottom-up sensor shipment analysis and top-down payment terminal deployment tracking triangulate volume estimates.
Rate-of-change decomposition across the projection horizon isolates technology transition effects from regulatory compliance cycles and foundry capacity expansion. Segmentation dimensions span sensor technology, deployment architecture, end-user procurement sophistication, and regional regulatory cluster. CAGRs derive from installed base growth modeling and replacement cycle acceleration. Forecast inputs incorporate RBI KYC mandate enforcement timelines and ultrasonic sensing maturation curves for transit and food service applications.
Revisions become necessary when RBI template localization mandates expand beyond current data center requirements or when TSMC and Samsung Foundry capacity allocation shifts disrupt sixteen-to-twenty-four week lead time assumptions. A model refresh is warranted upon material change in EU AI Act high-risk system classification enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Mexico Real Time Payments Market
Payments
Global Virtual Payment (POS) Terminals Market
Payments
Payment Processing Solutions Market
Payments
Germany POS Terminal Market
Payments
Vehicle Toll Collection and Access System Market
Payments
United Arab Emirates Mobile Payments Market
Payments
Slovenia Point of Sale (POS) Terminal Market
Payments
Netherlands Mobile Payments Market
Payments
Sweden Mobile Payments Market
Payments
Cash Management Software Market
Payments
Mobile Payment Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
Payment Analytics Software Market
Payments
Contactless Payment Ring Market
Payments
Money Transfer Agencies Market
Payments
Mobile Payment Data Protection Market