
 Global Virtual Payment (POS) Terminals Market | 2026-2036
Global Virtual Payment (POS) Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual Payment (POS) Terminals Market Intelligence
The historical dominance of large-format retail in hardware procurement is decoupling from the rapid, software-led adoption by independent restaurants and hospitality businesses. Stripe Inc. specializes in providing integrated software platforms for e-commerce and small business ecosystems. Square Inc. leverages its ecosystem of mobile POS hardware and software to serve small to medium-sized enterprises. In contrast, Verifone Systems Inc. sustains its position through established relationships with large retail chains and petroleum clients, anchoring the traditional hardware segment.
Virtual payment (POS) terminals are software-based solutions that enable standard computing devices like smartphones or tablets to function as secure payment acceptance points. These systems typically utilize Near Field Communication (NFC) or QR code scanning to process transactions without dedicated hardware. The market's deployment model is shifting decisively toward cloud-based solutions, displacing legacy on-premise systems. Within product types, mobile POS and smart POS solutions are the fastest-growing categories, driven by their flexibility and lower upfront costs.
Compliance with the Payment Card Industry Data Security Standard (PCI DSS) is a fundamental requirement for all market participants, shaping software development and security protocols. In parallel, regulations like Europe's GDPR and guidance from bodies like the U.S. Federal Trade Commission impose strict rules on consumer data handling. Stakeholders must now navigate the challenge of embedding advanced security features without compromising the speed and convenience demanded by consumers and merchants.
Market Dynamics
The central dynamic shaping the virtual POS terminal market is the fundamental decoupling of payment acceptance software from proprietary hardware. This shift, enabled by cloud infrastructure and ubiquitous consumer-grade devices, allows software to become the primary value driver and competitive battleground.
Growth Catalysts
- Policy-Led Digitization:India's national UPI framework and related digital payment initiatives from the Reserve Bank of India create a vast, standardized infrastructure, accelerating merchant adoption of low-cost, QR-code and mobile-based virtual terminals.
- Hospitality Sector Mobility:Strong demand from restaurants, cafes, and food trucks for flexible, mobile payment solutions drives adoption of tablet and smartphone-based POS systems that improve table turnover and customer experience.
- NFC Technology Proliferation:The widespread integration of Near Field Communication (NFC) chips in consumer smartphones provides the foundational technology for "Tap-to-Pay" functionality, eliminating the need for dedicated hardware dongles for merchants.
Market Restraints
- Connectivity and Power Dependence:Virtual POS solutions are inherently reliant on stable internet access and the battery life of consumer devices, creating a point of failure in locations with unreliable network coverage or during power outages.
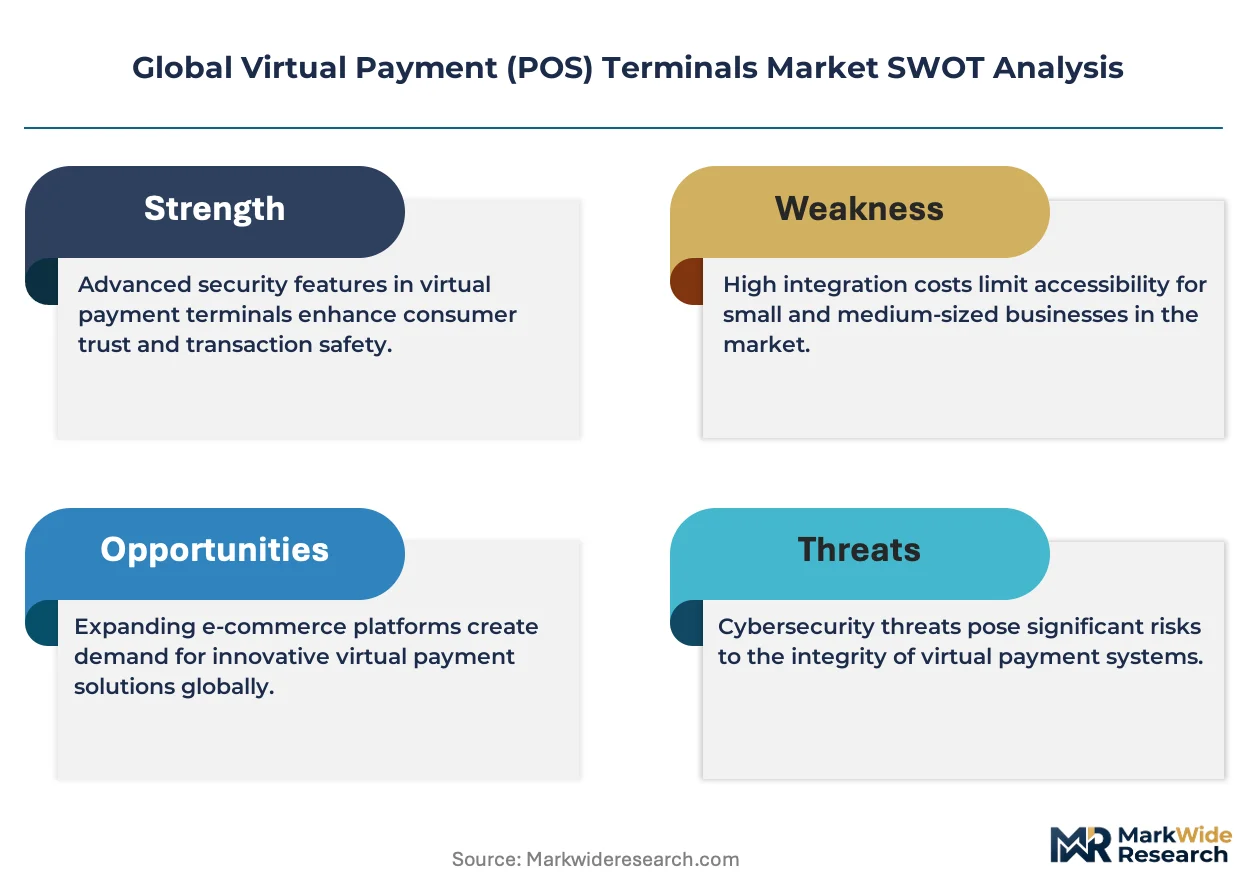
- Security Perception Gap:Despite adherence to PCI DSS, a segment of merchants and consumers remains hesitant to use personal or general-purpose devices for financial transactions, perceiving them as less secure than dedicated hardware terminals.
- P2P Payment Substitution:The rise of direct peer-to-peer payment applications allows micro-merchants and service providers to bypass formal POS systems entirely for simple transactions, representing a form of non-consumption.
Strategic Opportunities
- Southeast Asian SME Penetration:Targeting small and medium-sized enterprises in high-growth economies like Indonesia and Vietnam, where smartphone adoption is high but legacy POS penetration is low, offers significant expansion potential.
- Platform-as-a-Service Expansion:Integrating virtual POS capabilities with adjacent business management tools, such as inventory control, employee scheduling, and customer loyalty programs, creates a stickier, higher-value software platform.
- Gig Economy Solutions:Developing specialized virtual POS applications tailored to the needs of independent contractors and gig economy workers, such as delivery drivers and freelance service providers, opens a new user segment.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is the complexity and cost of integrating modern, cloud-based virtual POS software with merchants' existing, often outdated, backend systems for accounting, CRM, or inventory.
- Navigating Data Privacy Regulations:The requirement to comply with a patchwork of stringent data privacy laws, including Europe's GDPR and various U.S. state-level regulations, adds significant overhead to software development and deployment.
- Evolving Fraud Vectors:The shift to software-centric solutions moves the security battleground from physical tampering to sophisticated cyber threats, demanding continuous investment in advanced fraud detection and prevention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual Payment (POS) Terminals Market |
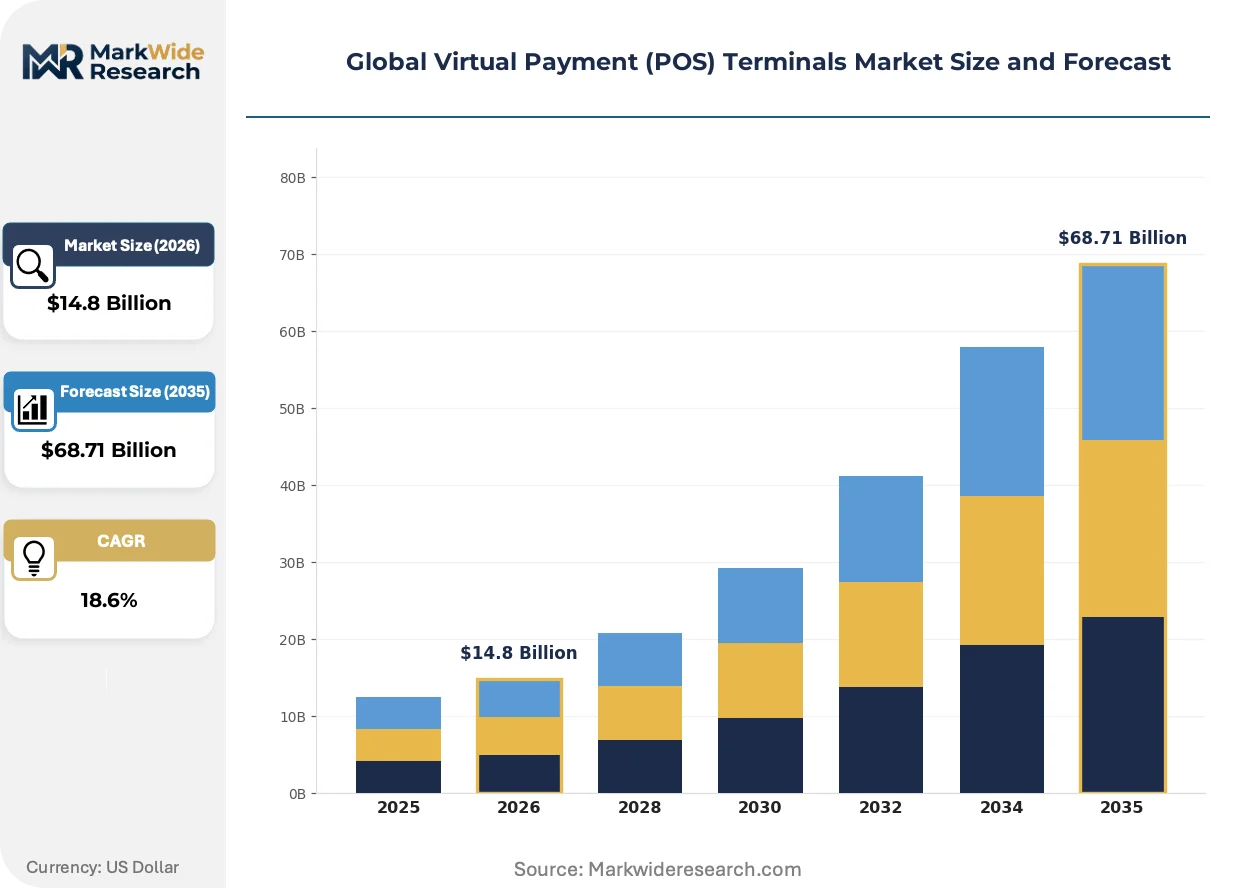
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $68.71 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile POS, Smart POS, Traditional POS, Contactless POS Deployment Model: On-Premise, Cloud-Based, Hybrid, Integrated End User: Retailers, Restaurants, E-Commerce, Hospitality Payment Mode: Credit Card, Debit Card, Digital Wallet, Others |
| Companies Covered | PAX Technology Limited, Global Payments Inc., Stripe Inc., Castles Technology Co. Ltd., Square Inc., Adyen N.V., Ingenico Group SA, NCR Corporation, Verifone Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual Payment (POS) Terminals Market Strategic Shifts & Innovations
Software is becoming the definitive layer for innovation, with value creation shifting from mere transaction processing to integrated business intelligence. The market's evolution is defined by embedding payment functionality within broader operational workflows, making the transaction itself almost invisible to the end-user.
Tap-to-Pay technology enables standard smartphones to function as secure, contactless payment acceptance devices using their built-in NFC capabilities. Small businesses and mobile merchants, from farmers' market vendors to independent consultants, are rapidly adopting this hardware-free solution. This capability is unifying the payment terminal with the primary business management device, collapsing the hardware stack and lowering entry barriers for entrepreneurship.
Europe's Payment Services Directive (PSD2) and its mandate for Strong Customer Authentication (SCA) directly influence virtual POS software design. This rule is forcing developers to integrate seamless, multi-factor authentication methods, such as biometrics or device-specific passkeys, into the payment flow. The mobile payments segment is most affected, with providers now competing on the security and user-friendliness of their SCA implementation.
Merchants are increasingly choosing POS providers based on the ecosystem of integrated software tools rather than on per-transaction processing fees. This behavioral shift disrupts the traditional sales model focused on hardware distribution, favoring subscription-based platforms that bundle payments with analytics, marketing, and inventory management. This trend is most visible among independent retail and hospitality businesses in the United States and Australia.
Global Virtual Payment (POS) Terminals Market Segmentation
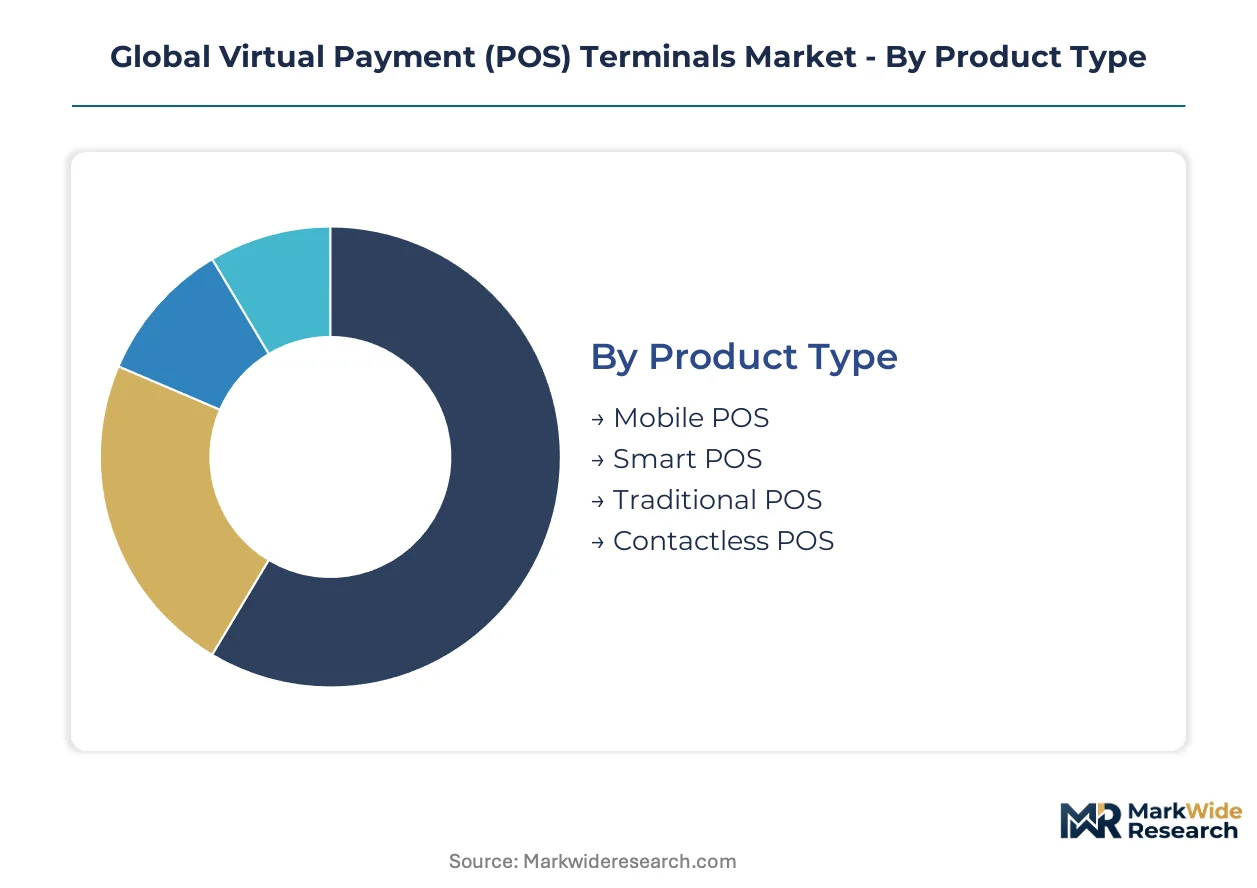
The virtual payment (POS) terminals market is highly differentiated, reflecting the diverse operational needs and technological preferences of merchants. Understanding these distinct segments is crucial for solution providers to tailor offerings that meet specific industry requirements and accelerate adoption across various business environments.
Product Type:
The virtual POS market differentiates its offerings primarily along technological specifications and form factors, enabling a range of solutions for different merchant scales and mobility needs.
- Mobile POS:These are software-based solutions running on consumer smartphones or tablets, transforming them into payment acceptance devices. Small businesses and mobile merchants, such as food trucks and independent consultants, widely adopt Mobile POS for its flexibility and low setup costs.
- Smart POS:Dedicated, often Android-based terminals integrate payment processing with additional business management features like inventory tracking and sales analytics. Independent retail and hospitality businesses favor Smart POS for combining secure payment acceptance with comprehensive operational data.
- Traditional POS:Legacy hardware terminals primarily used by large retail chains continue to support high-volume, fixed-location transactions.
- Contactless POS:Systems enabling Near Field Communication (NFC)-based payments are increasingly integrated into mobile and smart POS devices for rapid, secure transactions.
Smart POS leads on scale; Mobile POS leads on momentum.
Deployment Model:
The market's deployment models are shaped by the fundamental architecture choices merchants make for their payment infrastructure, influencing control, accessibility, and cost implications.
- Cloud-Based:These are Software as a Service (SaaS) solutions hosted on remote servers, accessible via the internet, minimizing local infrastructure. New businesses and small to medium-sized enterprises (SMEs) prefer cloud-based systems for their lower upfront costs and automatic updates, particularly in countries like India.
- Integrated:Payment processing capabilities are embedded directly into broader business management platforms, such as enterprise resource planning (ERP) or customer relationship management (CRM) systems. Larger enterprises seek integrated solutions to streamline operations and unify data across various business functions.
- On-Premise:Software is installed and managed directly on the merchant's local servers, providing full control over data and system customization.
- Hybrid:This model combines local and cloud-based components, balancing the benefits of data control with remote accessibility and scalability.
Cloud-Based solutions are expanding most quickly, driven by their operational flexibility.
End User:
End-user demand for virtual POS terminals varies significantly across different commercial environments, with each sector presenting unique requirements for payment functionality and integration.
- Hospitality:Solutions designed for hotels, cafes, and food service businesses often incorporate features for table management, mobile ordering, and split payments. Strong demand from this sector drives adoption for flexible, mobile payment solutions that improve table turnover and customer experience.
- Retailers:Virtual POS systems for physical stores support inventory management, customer relationship tools, and loyalty programs. Small and independent retailers increasingly adopt these systems to reduce hardware costs and enhance checkout efficiency.
- Restaurants:Specialized virtual POS offerings for dining establishments focus on order management, kitchen display systems, and efficient tip handling.
- E-Commerce:Integrated payment gateways and virtual terminals primarily process online transactions, often incorporating advanced fraud detection features.
The hospitality sector exhibits the steepest expansion trajectory for virtual POS adoption.
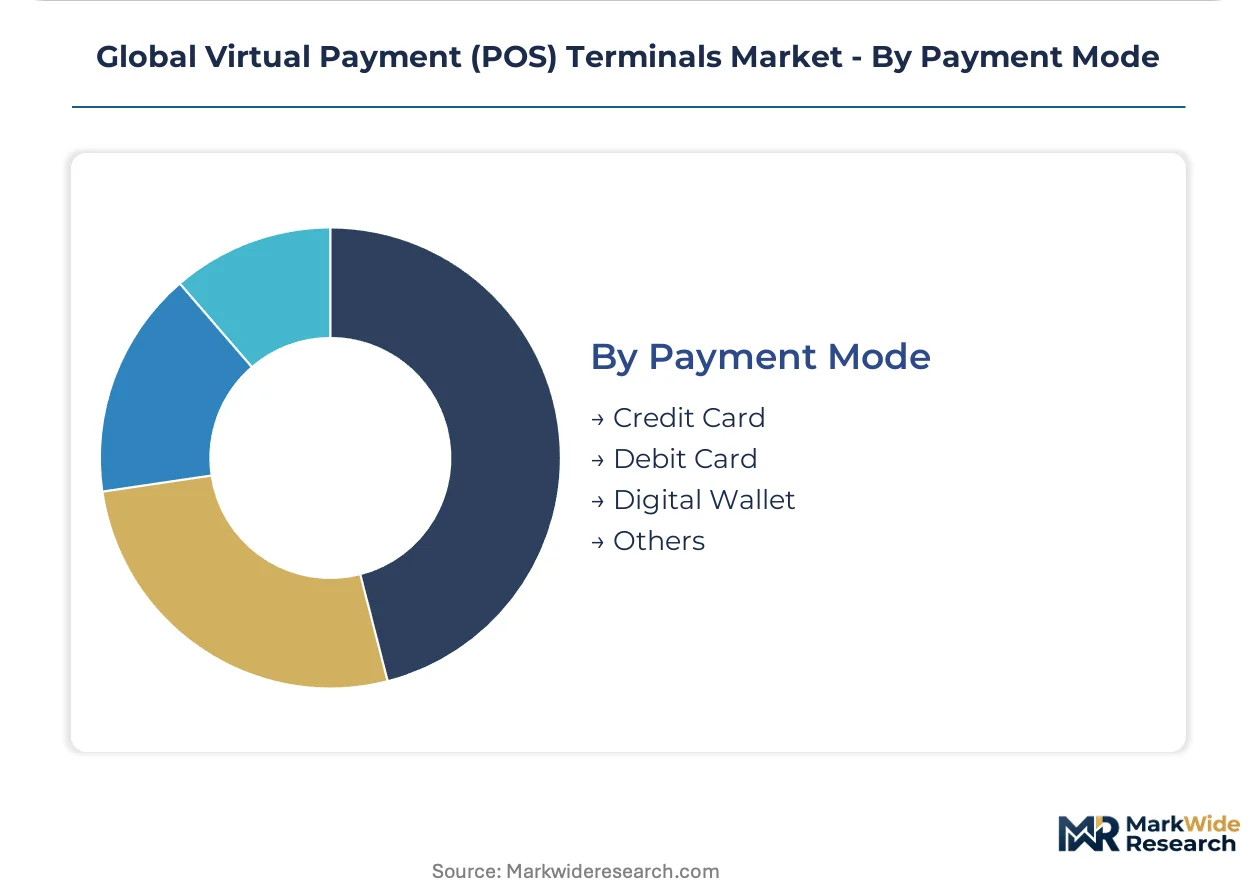
Payment Mode:
The virtual POS market supports diverse payment modes, each leveraging distinct transaction protocols and catering to evolving consumer preferences and security standards.
- Digital Wallet:Transactions are processed via mobile payment applications like Apple Pay, Google Pay, or country-specific solutions such as India's UPI. This mode gains traction from policy-led digitization initiatives and widespread smartphone adoption, particularly in emerging economies.
- Credit Card:Secure processing of credit card payments through tokenization and encryption adheres strictly to Payment Card Industry Data Security Standard (PCI DSS) standards. Credit cards remain a foundational payment method, requiring robust security features within virtual POS software for consumer trust.
- Debit Card:This mode facilitates direct deductions from bank accounts, offering a cost-effective payment option for merchants and widespread consumer acceptance.
- Others:This category includes alternative payment methods such as direct bank transfers, loyalty points redemption, or buy-now-pay-later options.
Digital Wallet payments are gaining share fastest, reflecting evolving consumer preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global virtual POS terminals market exhibits diverse regional growth trajectories, often shaped by national regulatory frameworks and digital payment infrastructure. Jurisdictions with proactive digital payment policies often see faster adoption, driving investment. This creates a landscape where regulatory support accelerates market penetration.
India
India experiences significant virtual POS adoption, fueled by policy-led digitization and extensive smartphone penetration. The Reserve Bank of India's UPI framework standardizes digital payments, creating a vast infrastructure. Mumbai, a major financial hub, drives widespread merchant adoption of QR-code based virtual terminals.
United States
The United States market benefits from strong demand in the hospitality sector for mobile payment solutions. PCI DSS compliance fundamentally shapes virtual POS software development and security protocols nationwide. Silicon Valley, a prominent technology hub, drives innovation in advanced cloud-based POS solutions.
Germany
Germany shows growing interest in virtual POS due to increasing contactless payment preferences and SME modernization efforts. Europe's GDPR regulations significantly influence data privacy and security features in local software development. Berlin, a dynamic tech center, fosters new startups developing integrated virtual POS platforms.
Brazil
Brazil's virtual POS market expands rapidly, driven by the need for financial inclusion and a mobile-first consumer base. The Central Bank of Brazil actively promotes digital payment ecosystems through various initiatives. São Paulo, a vast urban center, experiences rapid deployment of mobile POS systems.
Indonesia
Indonesia presents significant expansion potential, characterized by high smartphone adoption and low legacy POS penetration. Bank Indonesia actively supports the development of robust digital payment systems. Jakarta, the country's capital, serves as a hub for fintech innovation and virtual POS adoption among SMEs.
Global Virtual Payment (POS) Terminals Market Key Industry Players
Portfolio diversification dominates the current landscape, as companies expand beyond core payment processing to offer integrated business solutions. The market exhibits a tiered structure, with established hardware providers coexisting with agile software-centric platforms. Two strategic archetypes emerge: traditional terminal manufacturers and innovative software-as-a-service providers. Competitive moves focus on strategic partnerships for ecosystem integration and geographic expansion into underserved markets. Companies also prioritize technology licensing to embed virtual POS capabilities into broader platforms.
Within the software-centric platform archetype, Stripe Inc. represents a leading provider of integrated software for e-commerce and small business ecosystems. Square Inc., a US-based entity, exemplifies the ecosystem approach, leveraging mobile POS hardware and software for small to medium-sized enterprises. In contrast, Verifone Systems Inc. anchors the traditional hardware segment, sustaining its position through established relationships with large retail chains and petroleum clients. These companies collectively illustrate the market's dual focus on agile, cloud-based solutions and robust, enterprise-grade systems.
| Leading Market Players |
|---|
| PAX Technology Limited |
| Global Payments Inc. |
| Stripe Inc. |
| Castles Technology Co. Ltd. |
| Square Inc. |
| Adyen N.V. |
| Ingenico Group SA |
| NCR Corporation |
| Verifone Systems Inc. |
| Others |
Cost & Logistics Intelligence
Venture-backed software developers, focusing on rapid innovation, drive competitive pricing strategies and flexible supply models for virtual POS solutions. This approach enables market entry for numerous agile firms, shaping the overall cost structure.
Pricing Analysis
Direct-to-merchant pricing models dominate the virtual POS market, often leveraging subscription-based platforms that bundle payment processing with integrated business management tools. Price differentiation stems from the level of software customization for specific industry needs and the volume scale of transactions handled. Pricing pressure intensifies from the proliferation of low-cost, cloud-based solutions, particularly impacting basic transaction processing fees. Small businesses and mobile merchants exhibit high price sensitivity, prioritizing low upfront costs and flexibility over extensive feature sets.
Supply Chain Analysis
Multi-supplier qualification for core software components and cloud infrastructure is becoming a standard practice among virtual POS providers to ensure resilience. The supply chain for virtual POS software concentrates in technology hubs like Silicon Valley, Berlin, and India, leveraging global talent pools. Key dependencies include stable internet infrastructure, robust cloud computing services, and readily available consumer-grade hardware for mobile solutions. Connectivity and power dependence represent a structural risk, particularly for merchants in remote areas. Distribution primarily runs through direct-to-merchant SaaS models and app marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global virtual POS terminals market is evolving into a late-cycle quality story, driven by a demand shift toward integrated business intelligence and seamless user experiences. Merchants now prioritize comprehensive software ecosystems over standalone payment processing.
For Market Incumbents: Acquire specialized software development firms to bolster integrated business intelligence capabilities and advanced fraud detection. Incumbents must expand their platform-as-a-service offerings to counter the threat from agile software-centric platforms and P2P payment substitution. Investing in R&D for seamless strong customer authentication (SCA) integration will maintain a competitive edge. Strengthen established relationships with large retail chains by offering robust, customizable enterprise-grade solutions.
For New Entrants and Emerging Players: Capture underserved segments in high-growth economies like Indonesia and Vietnam, where smartphone adoption is high but legacy POS penetration is low. Target gig economy workers and independent contractors with specialized, low-cost virtual POS applications tailored for mobile-first operations. A go-to-market strategy emphasizing ease of setup, hardware-free solutions, and transparent pricing will resonate with micro-merchants. Focus on embedding payment functionality within broader operational workflows for these specific user segments.
For Investors and Strategic Acquirers: Enterprise software conglomerates are the most active acquirers in this space, seeking to expand their integrated business management ecosystems. Long-term viability favors virtual POS platforms demonstrating strong recurring revenue from subscription models and deep integration with adjacent business tools. Acquisition targets should be cloud-based SaaS providers specializing in vertical-specific solutions for hospitality or independent retail. The proliferation of policy-led digitization initiatives and evolving data privacy regulations serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform-as-a-Service Expansion | Integrating virtual POS with inventory and CRM tools creates stickier merchant relationships and higher-value offerings. |
| Targeted Gig Economy Solutions | Developing specialized applications for freelance service providers taps into a rapidly expanding, mobile-first user segment. |
| Advanced Fraud Detection R&D | Continuous investment in AI-driven fraud prevention addresses evolving cyber threats and maintains merchant trust. |
| Seamless SCA Implementation | Integrating biometrics and device-specific passkeys improves user experience and ensures compliance with European regulations like PSD2. |
| Geographic Expansion into Southeast Asia | Penetrating high-growth economies with high smartphone adoption, such as Indonesia, offers significant market expansion potential. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, informing a robust analytical framework. Primary research involved discussions with payment gateway executives, POS software developers, hospitality business owners, and small retail managers. This was rigorously validated against secondary data from central bank reports, industry association publications, and technology patent databases. A bottom-up market sizing approach was triangulated with top-down validation to ensure accuracy.
The segment-weighting approach informed the market forecast, integrating historical performance with projected growth drivers across the analysis window. Segmentation dimensions modeled included product type, deployment model, end-user, payment mode, and regional adoption patterns. Compound Annual Growth Rates were derived from an assessment of market dynamics and technology diffusion trends. Key forecast inputs included global smartphone penetration rates and national digital payment policy initiatives.
Evolving fraud vectors, new data privacy regulations, and global economic shifts are the dominant revision risks to the market forecasts. These projections reflect current market assumptions and technological trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Online Charging System (OCS) Market
Payments
Mexico Payments Market
Payments
Russia Payments Market
Payments
Electronic Payment System for Transportation Market
Payments
Asia-Pacific Payment Analytics Software Market
Payments
Italy POS Terminals Market
Payments
Saudi Arabia Payments Market
Payments
Singapore Payments Market
Payments
UAE POS Terminal Market
Payments
Slovakia POS Terminal Market
Payments
Epayment System Market
Payments
Payment Processing Solutions Market
Payments
Remote Mobile Payment Market
Payments
South Africa Gift Card and Incentive Card Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
Canada Payment Gateway Market