
 Clinical Communication and Collaboration Software Market | 2026-2036
Clinical Communication and Collaboration Software Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Communication and Collaboration Software Market Outlook
Buyer concentration among hospital networks is pivoting toward enterprise-wide platform standardization, replacing fragmented point solutions. Epic anchors the inpatient electronic health record ecosystem, leveraging deep EHR integration to embed communication tools within clinical workflows. TigerConnect competes through specialized messaging infrastructure that spans acute and ambulatory settings. Stryker sustains its position by extending hardware-software convergence in perioperative and emergency communication.
Clinical communication and collaboration software encompasses secure messaging, video consultation, task orchestration, and workflow automation platforms engineered to HIPAA-compliant encryption standards and real-time clinical alerting protocols. These systems synchronize care teams across distributed settings, reducing response latency and medical error incidence. Cloud-based solutions dominate new procurement cycles as hospitals prioritize scalability and disaster recovery, while on-premises systems retain share in facilities with restrictive data sovereignty requirements. Messaging solutions capture the largest addressable base, though workflow platforms generate superior per-seat margins through deep EHR and nurse-call integrations.
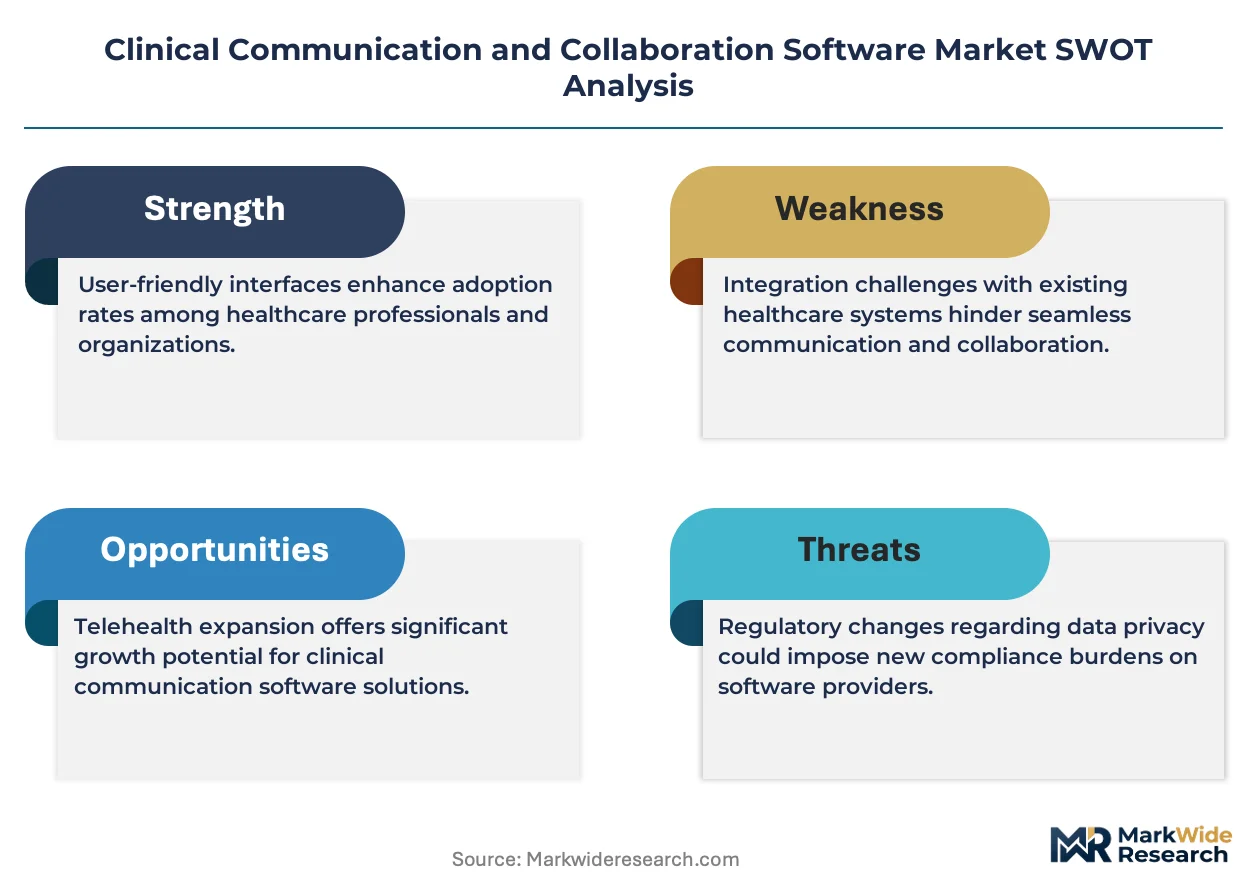
The US FDA oversees software-as-medical-device classifications for clinical decision support modules embedded within communication platforms, while HIPAA mandates encryption and access audit trails that shape vendor architectural requirements. The 21st Century Cures Act interoperability rules from the Office of the National Coordinator force vendors to enable seamless data exchange across competing systems. Stakeholders must monitor whether federal enforcement of information blocking penalties accelerates replacement of legacy paging infrastructure or merely perpetuates hybrid communication environments.
Market Dynamics
Hospital procurement committees are consolidating vendor relationships around platforms that embed communication directly into electronic health record workflows, compressing the addressable market for standalone messaging vendors while elevating integration depth as the primary selection criterion.
Growth Catalysts
- Interoperability mandates:The 21st Century Cures Act information blocking rules compel health systems to replace siloed paging infrastructure with bidirectional data exchange capabilities.
- Perioperative efficiency targets:Surgical services departments are deploying automated escalation protocols to reduce first-response latency during critical events.
- Cloud migration:Health systems are prioritizing SaaS architectures that offload disaster recovery and encryption key management to specialized infrastructure providers.
Market Restraints
- IT budget fragmentation:Hospital capital committees allocate communication software spend across multiple departmental silos, preventing enterprise-wide contract consolidation.
- Legacy hardware lock-in:Nurse call system vendors maintain proprietary integration protocols that restrict third-party messaging platform connectivity.
- Specialized talent scarcity:Health informatics teams with dual expertise in clinical workflow design and FHIR API implementation command premium compensation packages.
Strategic Opportunities
- Post-acute extension:Skilled nursing facilities and home health agencies present untapped demand for HIPAA-compliant mobile coordination tools.
- AI-assisted triage:Natural language processing engines are converging with messaging platforms to automate urgency classification and routing decisions.
- Veterans Health Administration:Federal procurement vehicles offer streamlined pathways for platform vendors to deploy across integrated care networks.
Industry Challenges
- EHR integration complexity:Epic, Cerner, and Meditech each maintain distinct API architectures that require vendor-specific development roadmaps.
- Clinical validation timelines:Software-as-medical-device classifications under FDA 21 CFR Part 820 extend quality assurance cycles for decision-support modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Communication and Collaboration Software Market |
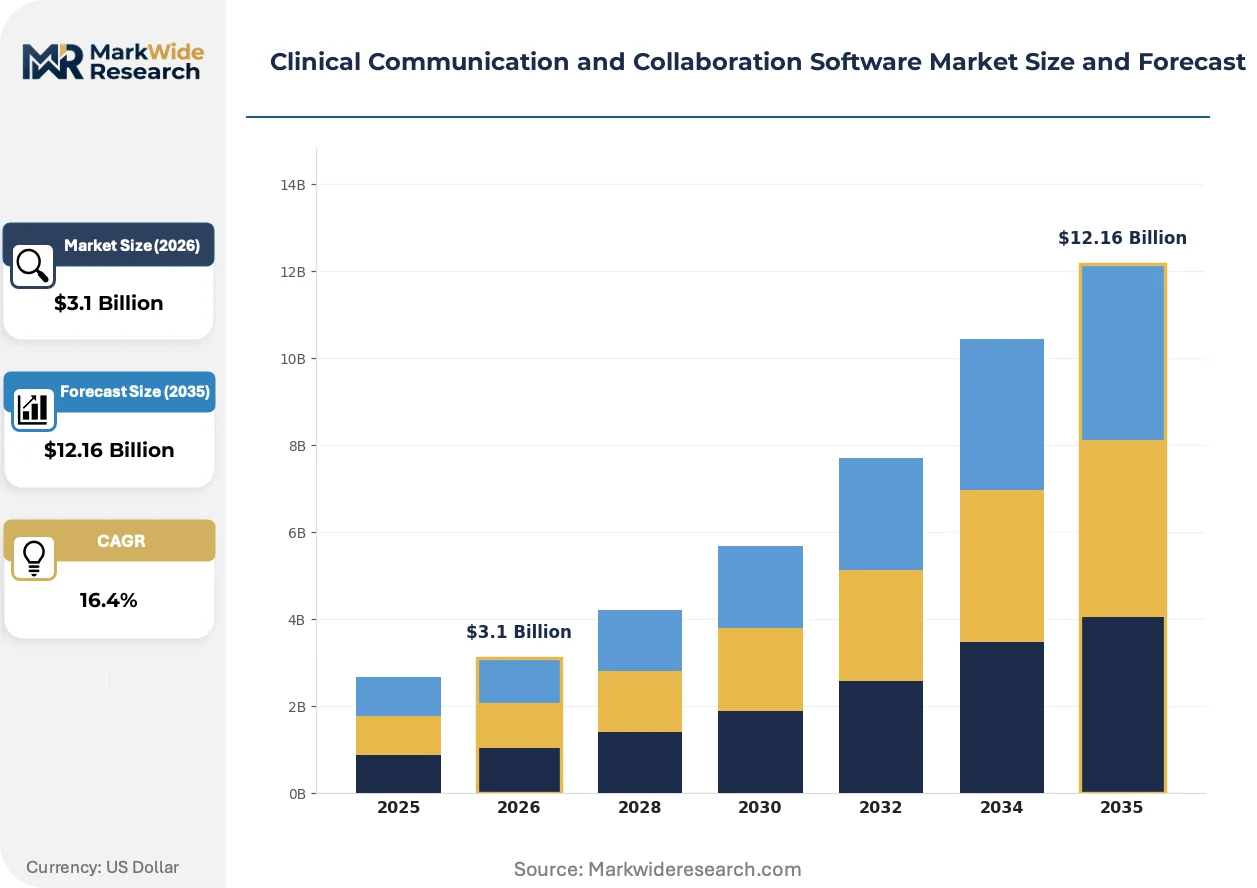
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Messaging Solutions, Video Conferencing Tools, Task Management Systems, Workflow Platforms Technology: Cloud-Based Solutions, On-Premises Systems, Hybrid Models, Mobile Applications End User: Hospitals, Laboratories, Long-Term Care Facilities, Rehabilitation Centers Deployment: Public Cloud, Private Cloud, Hybrid Deployment, Onsite Solutions |
| Companies Covered | OnPage, QliqSOFT, TigerConnect, Oracle Health, Stryker, PerfectServe, symplr, Epic, Spok, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Communication and Collaboration Software Market Strategic Shifts
Artificial intelligence is penetrating clinical communication infrastructure at the workflow layer rather than the interface layer, automating task prioritization and resource allocation decisions that previously required human triage nurses.
Large language models trained on clinical encounter data are rewriting escalation protocols across emergency departments and intensive care units. Health systems in Texas and Florida are piloting autonomous alert routing that bypasses traditional charge-nurse intermediaries. This compression of decision layers is eliminating response latency during sepsis and stroke protocols.
The FDA's evolving enforcement posture on clinical decision support software is creating architectural uncertainty for vendors embedding predictive algorithms within messaging platforms. Developers must now document intended use cases and validation datasets prior to commercial deployment. Early-stage companies are responding by modularizing AI components to isolate regulatory exposure.
Subscription pricing for communication platforms is displacing perpetual license models as hospital finance departments prioritize operational expenditure classification. Large integrated delivery networks in California and New York are negotiating enterprise-wide agreements that bundle messaging, video, and workflow automation under single per-clinician rates. This consolidation of procurement categories is compressing vendor margins while extending contract durations.
Clinical Communication and Collaboration Software Market Segmentation
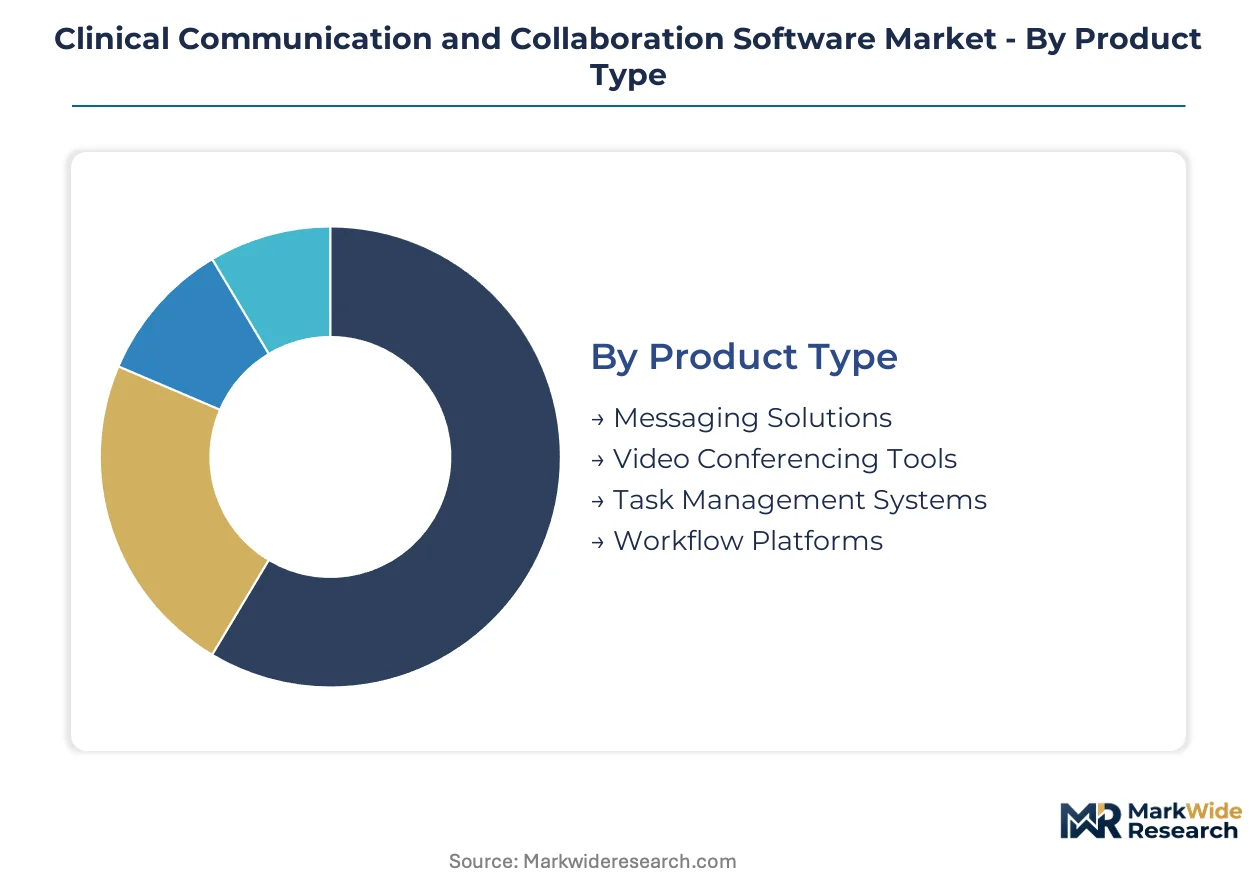
Hospital procurement committees evaluate clinical communication platforms across multiple technical and operational dimensions. Segmentation reveals where integration complexity, compliance requirements, and workflow depth concentrate vendor differentiation and buyer investment priorities.
Product Type:
Technology specification determines integration depth and per-seat margin structure across clinical communication portfolios.
- Messaging Solutions:Secure text, image, and voice exchange platforms engineered to HIPAA encryption standards with read-receipt tracking and escalation timers. Demand concentrates in large US health systems replacing legacy paging infrastructure, driven by the 21st Century Cures Act interoperability mandates that compel bidirectional data exchange.
- Workflow Platforms:Nurse-call integration, task orchestration, and clinical alerting systems embedded directly within EHR interfaces. Perioperative departments in Texas and Florida health networks are deploying these for automated escalation during sepsis and stroke protocols, compressing response latency.
- Video Conferencing Tools:HIPAA-compliant telehealth modules with waiting room management and clinical documentation capture.
- Task Management Systems:Role-based assignment engines with handoff documentation and accountability tracking.
Mature deployment sits with Messaging Solutions. Newer deployment is concentrated in Workflow Platforms.
Technology:
Architecture choice shapes disaster recovery posture, encryption key custody, and total cost of ownership for health system IT departments.
- Cloud-Based Solutions:SaaS architectures with vendor-managed infrastructure, automatic security patching, and elastic scaling for seasonal census fluctuations. California and New York integrated delivery networks are negotiating enterprise-wide agreements bundling cloud communication under operational expenditure budgets.
- Mobile Applications:Native iOS and Android clients with offline message queuing, biometric authentication, and push notification management. Ambulatory clinics and home health agencies are standardizing on these for distributed care team coordination.
- On-Premises Systems:Hardware-controlled deployments retaining data sovereignty for facilities with restrictive governance requirements.
- Hybrid Models:Split architectures with sensitive workflows on-premises and general messaging in cloud environments.
Cloud-Based Solutions dominate new procurement cycles. Hybrid Models are climbing the fastest among facilities with mixed compliance requirements.
End User:
Facility type dictates alert urgency, integration complexity, and regulatory scrutiny intensity for platform vendors.
- Hospitals:Acute care networks with 24/7 code team activation, operating room scheduling, and multi-floor nurse coordination. Enterprise-wide deployments in US health systems are compressing the addressable market for standalone vendors through EHR-embedded procurement decisions.
- Long-Term Care Facilities:Skilled nursing and assisted living operators with medication administration tracking and family communication portals. Post-acute extension strategies are targeting these facilities for HIPAA-compliant mobile coordination tools.
- Laboratories:Pathology and diagnostic centers with specimen chain-of-custody alerts and critical value notification protocols.
- Rehabilitation Centers:Therapy scheduling and interdisciplinary care plan coordination for stroke and orthopedic recovery programs.
Revenue concentration sits with Hospitals. Long-Term Care Facilities represent the steepest expansion trajectory for vendor footprint extension.
Deployment:
Infrastructure location determines latency, redundancy, and audit trail custody for clinical communication traffic.
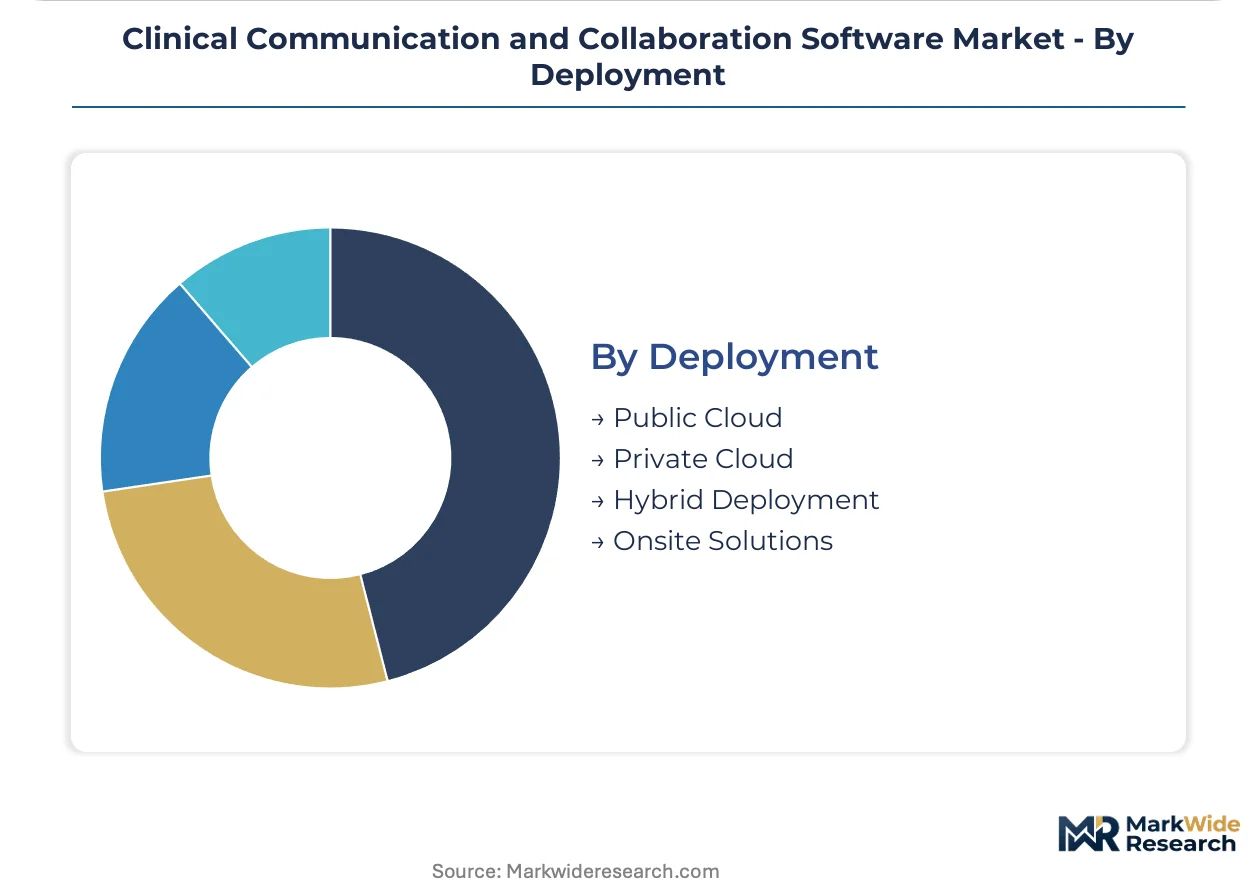
- Private Cloud:Dedicated tenant environments with single-organization data isolation and custom encryption key management. Health systems with FDA-regulated clinical decision support modules are prioritizing these for software-as-medical-device validation cycles.
- Public Cloud:Multi-tenant SaaS with shared infrastructure economics and geographic redundancy. Smaller community hospitals are migrating here to offload disaster recovery responsibilities.
- Hybrid Deployment:Segmented workloads with protected health information in private environments and administrative traffic in public cloud.
- Onsite Solutions:Fully local hardware with air-gapped security for critical access hospitals with limited connectivity.
Private Cloud anchors enterprise health system procurement. Public Cloud is gaining share fastest among independent and rural facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure concentration in Northern Virginia and Dallas anchors North American deployment capacity for clinical communication platforms. Health system procurement committees across multiple countries are consolidating vendor relationships around EHR-embedded architectures.
United States
Large integrated delivery networks in California and New York are negotiating enterprise-wide agreements bundling messaging, video, and workflow automation. The 21st Century Cures Act information blocking rules compel replacement of siloed paging infrastructure. Texas and Florida health networks are piloting autonomous alert routing for sepsis and stroke protocols.
United Kingdom
NHS trusts are migrating toward cloud-native communication platforms with vendor-managed disaster recovery. GDPR and NHS Digital compliance requirements shape encryption and audit trail specifications. London and Southeast England health systems are consolidating procurement around platforms with deep Epic and Cerner integration.
Germany
University hospitals in Bavaria and North Rhine-Westphalia are deploying workflow platforms for perioperative efficiency targets. The BfArM regulates software-as-medical-device classifications for clinical decision support modules. Berlin-Brandenburg health networks are standardizing on hybrid cloud deployments with sensitive workloads remaining on-premises.
Japan
Metropolitan hospital networks in Tokyo and Osaka are adopting mobile-first communication platforms for distributed care team coordination. The PMDA oversees software validation timelines for AI-assisted triage modules embedded within messaging systems. Kansai region health systems are prioritizing FHIR API integration for interoperability with existing EHR infrastructure.
India
Corporate hospital chains in Maharashtra and Karnataka are procuring HIPAA-compliant cloud solutions for telehealth expansion. The CDSCO regulates clinical decision support software classifications for platforms with diagnostic algorithms. Telangana's health technology corridor is attracting vendor development centers for FHIR API implementation expertise.
Clinical Communication and Collaboration Software Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue AI-assisted triage and post-acute extension strategies. The vendor base stratifies across EHR-embedded incumbents, specialized messaging infrastructure providers, and hardware-software convergence specialists. Dominant competitive moves include strategic partnerships with nurse call system vendors and geographic expansion into skilled nursing facility markets.
Within the EHR-embedded tier, Epic and Oracle Health exemplify platforms leveraging deep electronic health record integration to compress the addressable market for standalone messaging vendors. TigerConnect occupies a position among specialized messaging infrastructure providers spanning acute and ambulatory settings. Stryker represents hardware-software convergence specialists extending perioperative and emergency communication capabilities.
| Leading Market Players |
|---|
| OnPage |
| QliqSOFT |
| TigerConnect |
| Oracle Health |
| Stryker |
| PerfectServe |
| symplr |
| Epic |
| Spok |
| Others |
Value Chain & Pricing Dynamics
Deep EHR integration anchors both supply positioning and pricing power for clinical communication vendors, as hospital procurement committees prioritize workflow-embedded platforms over standalone messaging infrastructure. This vertical integration into electronic health record ecosystems compresses margins for point-solution providers while elevating per-seat rates for systems with nurse-call and perioperative module connectivity.
Pricing Analysis
Service-bundling differentiation separates enterprise agreements with full implementation support from stripped-down SaaS tiers with self-service onboarding. Subscription pricing stratifies across premium, standard, and economy tiers based on EHR integration depth and clinical decision support module inclusion. Cost compression in the standalone messaging tier is intensifying because Epic and Oracle Health embed communication tools at no incremental license cost. Community hospitals and independent ambulatory clinics exhibit the highest price sensitivity, while integrated delivery networks in California and New York negotiate volume discounts that obscure per-seat economics.
Supply Chain Analysis
Regional distribution centers in Northern Virginia and Dallas anchor cloud infrastructure delivery for North American health systems, with latency-optimized edge nodes serving metropolitan hospital networks. Software development draws from engineering talent pools in Telangana, Massachusetts, and Bavaria, where FHIR API expertise concentrates. Single-source vulnerability sits with hyperscaler cloud platforms that host the majority of SaaS deployments. Distribution runs through direct enterprise sales teams and value-added resellers with clinical workflow consulting capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native architectures are displacing on-premises paging infrastructure across hospital networks, creating replacement-cycle opportunities for platforms with HIPAA-compliant encryption and real-time alerting protocols.
For Market Incumbents: To counter margin compression from EHR-embedded communication tools, TigerConnect and Spok should deepen nurse-call system partnerships that create switching costs, while investing in AI-assisted triage modules that extend software-as-medical-device classification timelines for competitive insulation. For New Entrants and Emerging Players: Enter via post-acute extension into skilled nursing facilities and home health agencies, where HIPAA-compliant mobile coordination tools face minimal incumbent saturation. Texas and Florida health networks present the most penetrable acute-care entry points due to autonomous alert routing pilot programs seeking specialized workflow vendors. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by EHR platform vendors seeking to fill communication gaps, with financial sponsors targeting workflow automation specialists with FDA-validated decision-support modules. Watch for 21st Century Cures Act enforcement acceleration as the inflection signal that forces legacy paging replacement at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic's embedded communication tools compress standalone vendor addressable market through EHR workflow lock-in. |
| Strategic Partnership | Nurse-call system alliances with Stryker and symplr create proprietary integration barriers for competing messaging platforms. |
| Acquisition of Specialist Firm | AI-assisted triage module vendors attract buyers seeking FDA-validated clinical decision support capabilities. |
| Geographic Expansion | Post-acute penetration into skilled nursing facilities opens revenue streams beyond saturated hospital markets. |
| Product Launch | Cloud-native SaaS architectures with vendor-managed disaster recovery align with hospital operational expenditure priorities. |
Study Parameters
Multi-period observation of hospital procurement cycles, EHR migration timelines, and interoperability mandate compliance anchored the trend analysis, supplemented by interviews with health system CIOs, clinical informatics directors, perioperative services managers, and GPO contracts specialists. Secondary validation drew from CMS Medicare data, hospital procurement databases, FDA 510(k) filings for software-as-medical-device classifications, and ONC information blocking enforcement disclosures. Bottom-up sizing of vendor-reported seat deployments triangulated against top-down health system IT budget allocations.
Segment-weighting across deployment models, facility types, and integration complexity tiers shaped the analytical framework, with CAGRs derived from logistic adoption curves fitted to EHR penetration benchmarks. Cloud migration velocity, 21st Century Cures Act compliance deadlines, and AI module regulatory validation timelines fed into scenario-weighted projections across the modeling period.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA enforcement posture shifts for clinical decision support software and hyperscaler cloud service disruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Integration Brokerage Software Market
Software & Services
North America Automotive Software Market
Software & Services
Web Scraping Software Market
Software & Services
Ecommerce Inventory Management Software Market
Software & Services
Talent Management Software Market
Software & Services
Structured Data Management Software Market
Software & Services
Global Vendor Management Software Market
Software & Services
Invoice Processing Software Market
Software & Services
Global Contract Lifecycle Management Software Market
Software & Services
Network Documentation Software Market
Software & Services
Electronic Design Automation Software Market
Software & Services
Global Absence Management Software Market
Software & Services
Global Auction Software Market
Software & Services
Office Productivity Software Market
Software & Services
Cloud-Based ERP Software Market
Software & Services
Software Testing Tools Market