
 Transit Station Display Board Market | 2026-2036
Transit Station Display Board Market Size, Share, and Industry Trends Forecast 2026-2036
Transit Station Display Board Market Intelligence
Demand from large public transit operators is bifurcating the market, favoring suppliers with scalable, integrated solutions over those serving smaller, private transit firms. SWARCO leverages its deep expertise in traffic management systems to offer comprehensive solutions for urban transit networks. Hitachi competes on its ability to deliver large-scale, technologically advanced displays for major railway infrastructure projects, while GDS Group specializes in ruggedized displays for outdoor transit environments.
A transit station display board is an electronic visual communication device engineered for public information dissemination. These systems often feature high-brightness LEDs and weather-resistant enclosures to ensure readability in various ambient conditions. LED Display technology continues to dominate the market due to its superior visibility and energy efficiency compared to older LCD variants. While railway stations remain a core segment, applications in metro stations are the fastest-growing opportunity, driven by global urban densification projects.
Regulatory frameworks directly influence product design and market access. In the United States, the Americans with Disabilities Act (ADA) mandates specific visual and audible communication standards for passenger information. Concurrently, European suppliers must adhere to CE marking for electronic safety and often comply with the EN 50155 standard for railway applications. System integrators must therefore decide whether to prioritize low initial capital outlay or a lower total cost of ownership through more durable, software-upgradable systems.
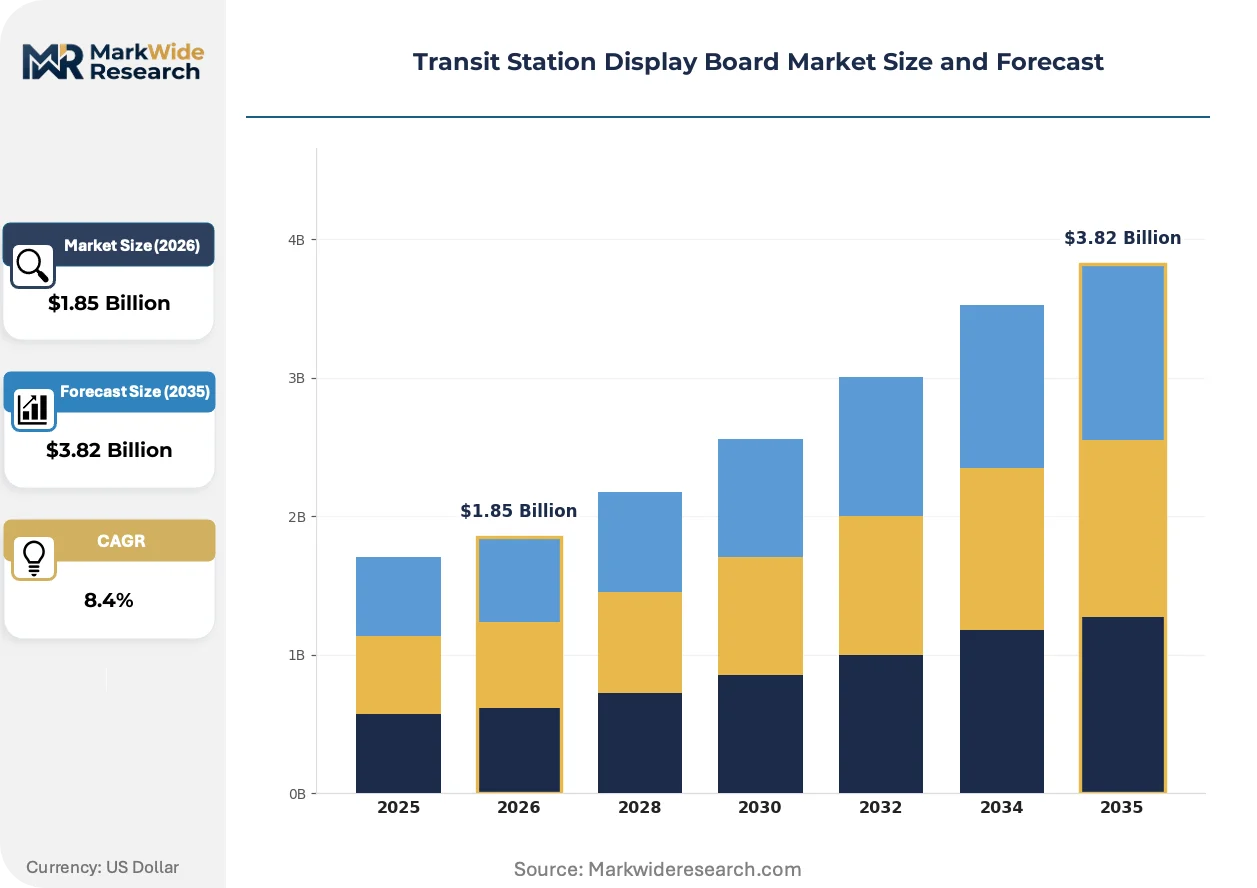
Market Dynamics
The central structural force shaping the market is the bifurcation of demand, where large public transit authorities require highly integrated, scalable information ecosystems, while smaller operators prioritize lower initial capital outlay, creating distinct product and service tiers.
Growth Catalysts
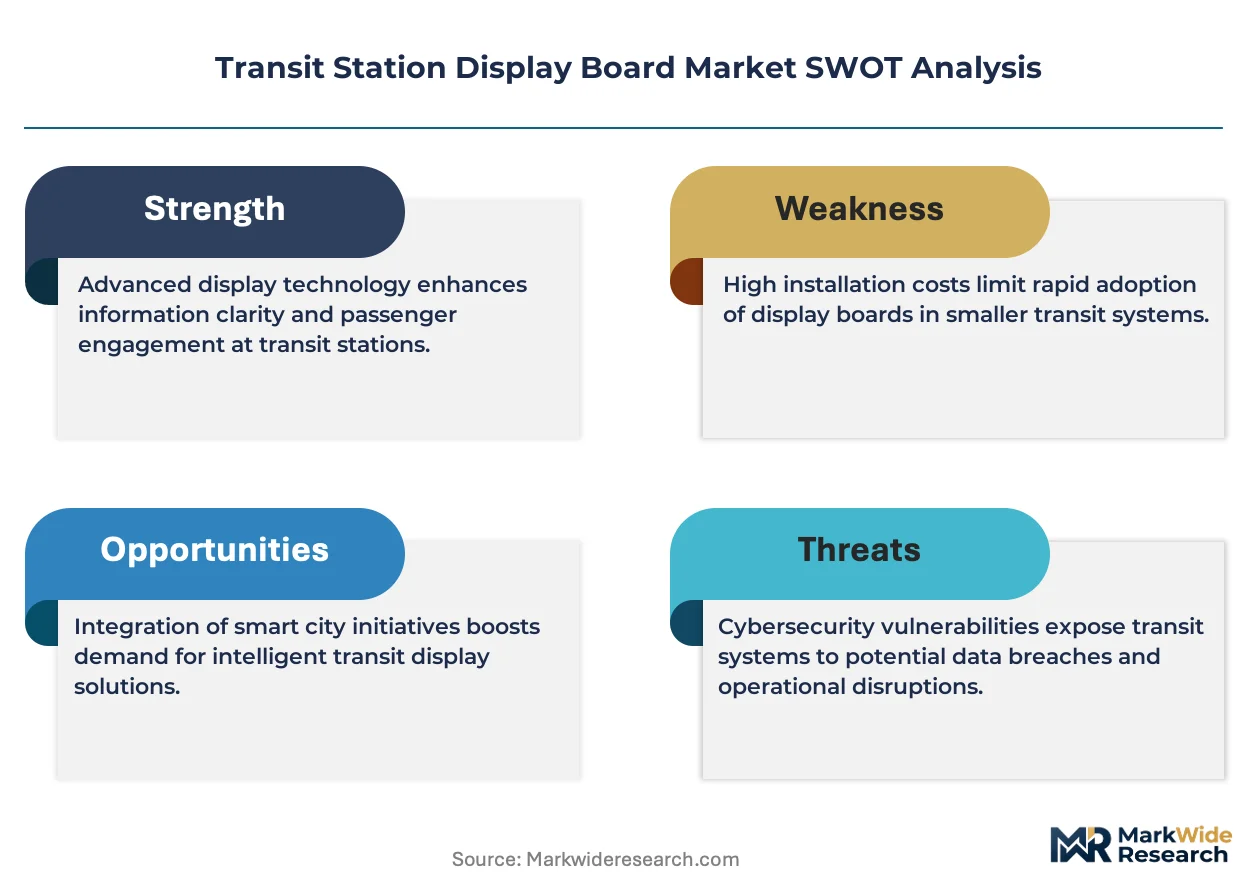
- Smart City Initiatives:Government-led programs, particularly in India, are accelerating the modernization of public transport infrastructure, mandating the installation of real-time passenger information systems in metro and bus stations to improve urban mobility.
- IoT and Cloud Integration:The adoption of Internet of Things (IoT) platforms allows transit operators to remotely manage content, monitor display health, and push dynamic updates, which significantly enhances operational efficiency and passenger communication.
- Passenger Experience Mandates:A focus on improving the passenger journey compels transit agencies to invest in clear, reliable, and real-time information displays, moving beyond static signage to dynamic, multi-modal information hubs.
Market Restraints
- High Initial Investment:The significant capital expenditure required for ruggedized, high-brightness, and weather-resistant display systems presents a substantial barrier for transit authorities with constrained budgets, particularly smaller municipal or private operators.
- Complex Regulatory Compliance:Suppliers face friction navigating disparate and stringent standards, such as the Americans with Disabilities Act (ADA) in the US and the EN 50155 railway standard in Europe, which increases design and certification costs.
- Technical Durability Requirements:Displays must withstand harsh environmental conditions including extreme temperatures, humidity, and vibration, which necessitates specialized enclosures and components, thereby increasing manufacturing complexity and cost compared to indoor commercial displays.
Strategic Opportunities
- Software-as-a-Service (SaaS) Models:A shift from one-time hardware sales to recurring revenue models based on content management software, remote monitoring, and data analytics offers a new value proposition for transit operators.
- Expansion to Ancillary Transit Hubs:Underpenetrated applications at bus shelters, ferry terminals, and light rail platforms represent a significant growth area as cities aim to create a unified information network across all public transport modes.
- Integration with Mobile Applications:Linking on-station displays with passenger mobile apps provides a seamless information experience, enabling features like journey planning, real-time disruption alerts, and personalized messaging, creating new partnership opportunities.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is the difficulty of integrating modern, IP-based display systems with older, proprietary IT and signaling infrastructure prevalent in many established transit networks, causing deployment delays.
- Certification Timelines:Achieving compliance with electronic safety and railway-specific standards like CE marking and EN 50155 is a time-consuming and expensive process that can delay market entry for new products.
- Specialized Skill Scarcity:The market faces a shortage of technicians who possess the hybrid skillset required for installing ruggedized hardware in public environments and configuring the complex software for network management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transit Station Display Board Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: LED Display, LCD Display, OLED Display, E-Paper Display Technology: Wired Connectivity, Wireless Connectivity, IoT Integration, Cloud-Based Control Application: Railway Stations, Bus Terminals, Metro Stations, Ferry Ports End User: Transport Authorities, Public Transit Operators, Private Transit Firms, Infrastructure Managers |
| Companies Covered | SWARCO, Toshiba Infrastructure Systems & Solutions Corporation, Hitachi, Ortana, Roctec Technology Limited, Oat Foundry, Softway Consultancy Private Limited, Nexcom International, GDS Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transit Station Display Board Market Strategic Shifts & Innovations
The evolution from standalone hardware to networked information ecosystems defines the market's trajectory. This shift prioritizes software-defined features, remote management capabilities, and seamless integration with broader transit authority data platforms over the physical display specifications alone.
System-on-Chip (SoC) technology integrates media processing and connectivity functions directly onto the display's mainboard. Transit operators are adopting SoC-based displays to eliminate the need for separate external media players, reducing system complexity, points of failure, and overall installation costs. This trend toward integrated intelligence is fragmenting the traditional component supply chain for media players and displays, favoring suppliers who can deliver a complete, self-contained solution.
European Union regulations like the EN 50155 standard for electronic equipment used on rolling stock are increasingly being applied to stationary trackside equipment, including platform displays. This forces manufacturers to subject their products to rigorous testing for temperature, shock, and vibration, ensuring higher reliability in demanding railway environments. The railway station segment is most affected, with compliance becoming a prerequisite for participation in major infrastructure tenders across the EU.
A notable shift in buying behavior involves transit authorities prioritizing total cost of ownership (TCO) over initial acquisition cost. Procurement decisions are increasingly based on factors like energy efficiency, modular design for easier maintenance, and the longevity of software support, rather than simply the lowest upfront price. This is most evident in public tenders in countries like Germany and France, where lifecycle cost analysis and sustainability are weighted heavily in vendor selection criteria.
Transit Station Display Board Market Segmentation
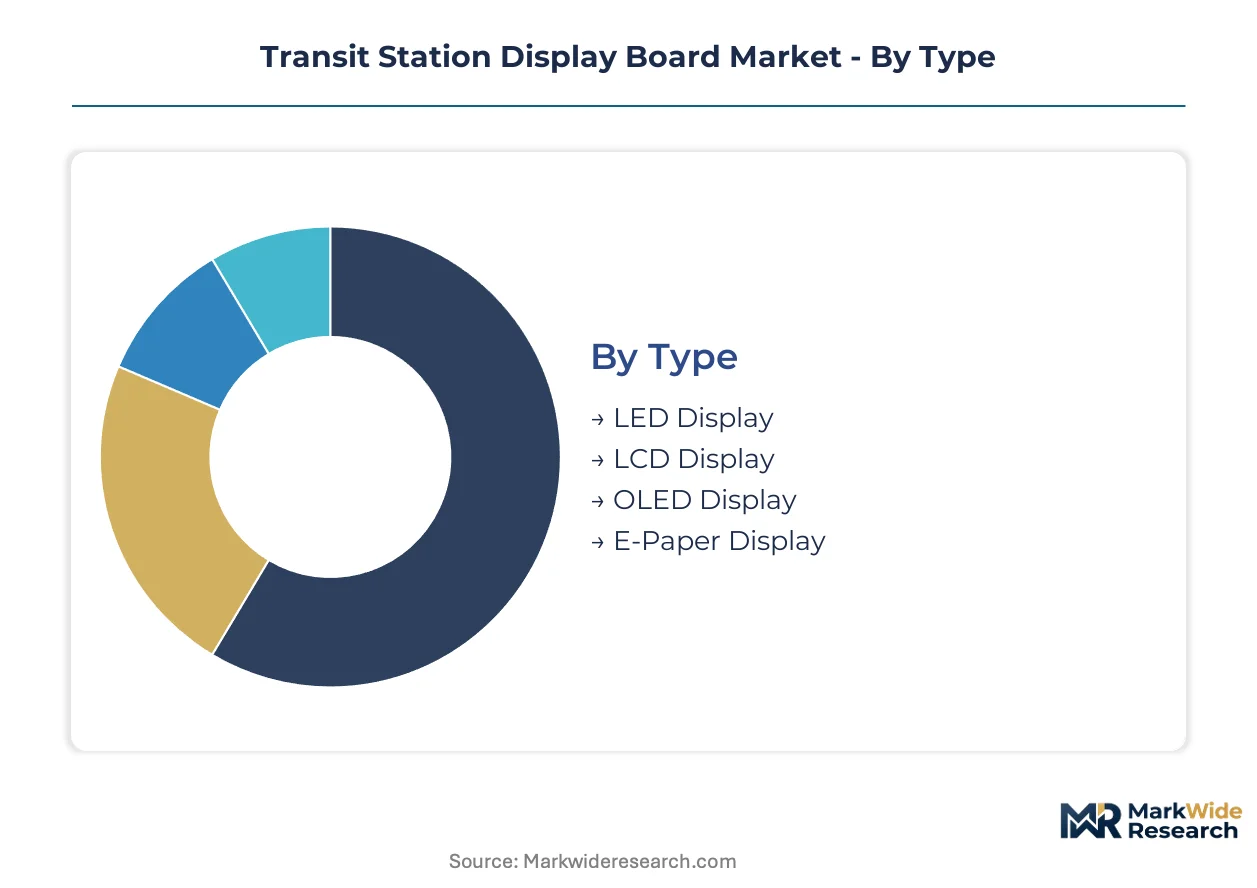
Understanding the varied requirements across the transit sector necessitates a granular segmentation of the display board market. This analysis delineates distinct product types, technological integrations, application areas, and end-user profiles, each presenting unique demand characteristics and operational considerations for suppliers.
Type:
Regulatory frameworks profoundly influence display technology choices, particularly regarding visibility and accessibility standards.
- LED Display:These displays utilize light-emitting diodes to produce bright, high-contrast visuals, offering superior readability in diverse ambient conditions. Demand from global public transit operators for durable, energy-efficient signage drives continued innovation in LED technology.
- OLED Display:Organic light-emitting diode displays provide exceptional contrast ratios and wider viewing angles due to self-emissive pixels, enhancing passenger information clarity in premium installations. This technology is gaining traction in modern metro stations seeking advanced visual aesthetics and dynamic content delivery.
- LCD Display:Liquid crystal display technology offers a cost-effective solution for indoor transit environments where extreme brightness is not a primary concern. Older installations in bus terminals often rely on these established, reliable panels.
- E-Paper Display:These ultra-low power displays offer static information with excellent readability, ideal for bus stops and less frequently updated signage. Their minimal energy consumption makes them attractive for off-grid or solar-powered applications.
LED Display technology handles the majority of throughput; OLED Display is gaining share fastest.
Technology:
The functional requirements of transit operations dictate specific technology integrations for display management.
- IoT Integration:This involves embedding sensors and connectivity into display systems, allowing for real-time monitoring of device health, environmental conditions, and remote content updates. Smart city initiatives across India are prioritizing IoT-enabled displays for enhanced operational intelligence.
- Cloud-Based Control:Centralized cloud platforms enable transit authorities to manage display networks across multiple stations from a single interface, delivering dynamic content and emergency alerts efficiently. This approach reduces on-site maintenance and scales easily for large urban networks.
- Wired Connectivity:Traditional ethernet or fiber optic connections provide highly reliable and secure data transmission for display networks, particularly critical in railway signaling environments. Legacy transit systems frequently depend on robust wired infrastructure.
- Wireless Connectivity:Technologies like Wi-Fi and cellular networks facilitate flexible deployment in locations where cabling is impractical or expensive. Bus shelters and temporary installations often leverage wireless communication for quick setup.
Wireless Connectivity solutions simplify deployment in existing infrastructure, while IoT Integration introduces advanced operational capabilities.
Application:
Passenger volume and operational complexity largely determine the display system requirements across different transit environments.
- Railway Stations:These applications require large-format, highly durable displays capable of real-time train schedules, platform changes, and safety messages. Compliance with standards like EN 50155 is mandatory for displays in European railway environments.
- Metro Stations:Characterized by high passenger density and rapid service intervals, metro stations demand clear, multi-language displays for route information and disruption alerts. Urban densification projects globally are driving significant investment in metro display infrastructure.
- Bus Terminals:Displays here provide bus arrival/departure times, route maps, and service updates, often requiring weather-resistant enclosures for outdoor or semi-outdoor installations. Smaller municipal operators frequently procure these systems.
- Ferry Ports:These locations utilize display boards for ferry schedules, boarding information, and weather warnings, often needing robust displays capable of withstanding marine environments. Coastal cities are gradually upgrading their port information systems.
Railway Stations account for significant installed base, but Metro Stations are demonstrating the steepest expansion trajectory.
End User:
The scale and ownership structure of transit entities shape their procurement preferences and system demands.
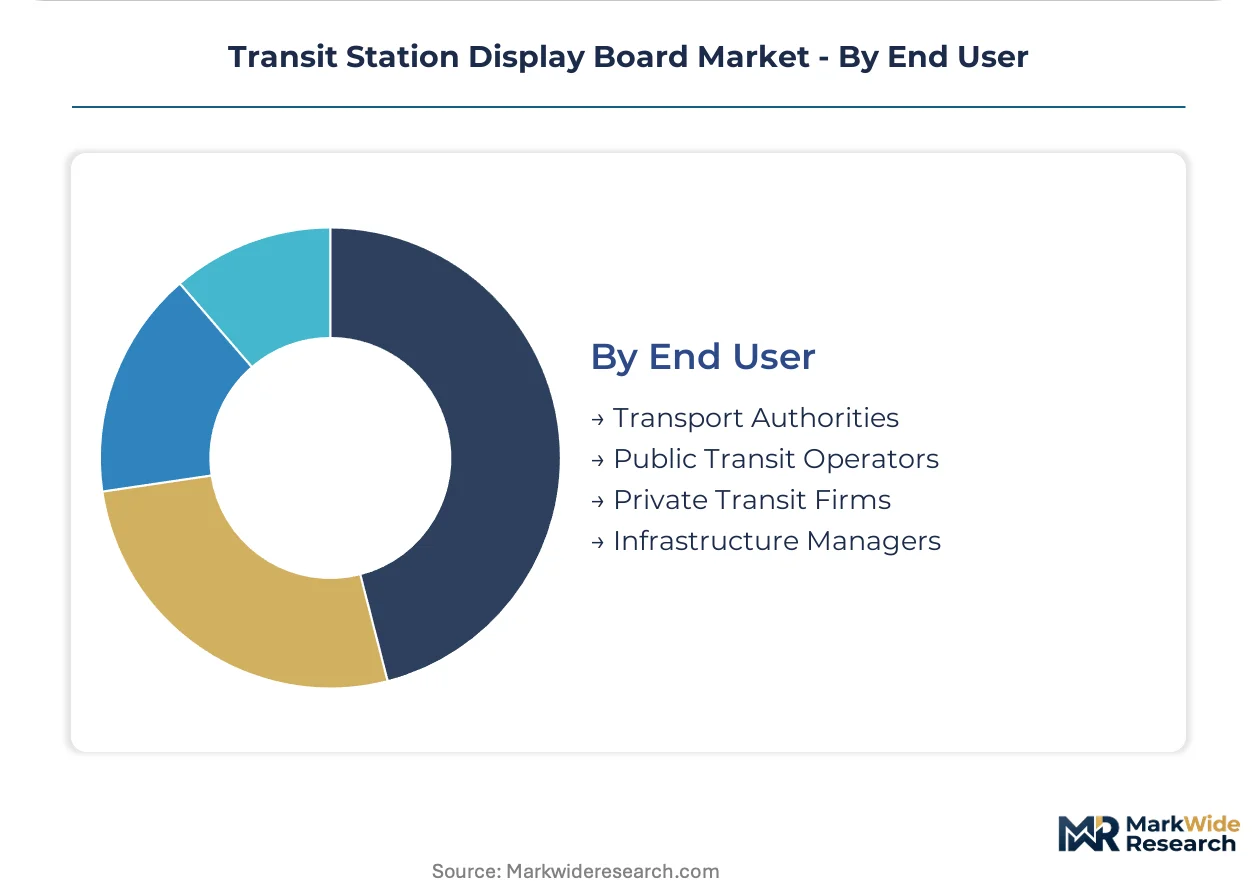
- Transport Authorities:These government bodies oversee entire public transportation networks, requiring integrated, scalable display solutions that can span multiple modes of transit. They prioritize total cost of ownership and long-term software support.
- Public Transit Operators:Companies or organizations responsible for daily operations of public transport systems, such as bus or metro lines, procure displays to enhance passenger experience and operational efficiency. Their focus often aligns with regulatory compliance and system reliability.
- Private Transit Firms:Smaller, privately owned bus companies or shuttle services typically seek cost-effective display solutions with lower initial capital outlay. These firms often prioritize ease of installation and basic functionality.
- Infrastructure Managers:Entities responsible for maintaining railway tracks, stations, and associated infrastructure also purchase displays for operational information, such as track status or maintenance alerts. Their requirements emphasize ruggedization and integration with existing control systems.
Transport Authorities drive large-scale infrastructure investments, while Private Transit Firms focus on cost-effective, adaptable solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for advanced transit display solutions from India is increasingly influencing technology specifications, while European manufacturers export their EN 50155 compliant systems globally. Urban densification projects across major economies are driving the need for sophisticated real-time passenger information systems. This trend necessitates robust, scalable, and compliant display technologies tailored to diverse regional requirements.
India
India's rapid urbanization and Smart City Initiatives are driving significant demand for real-time passenger information systems. The government's PLI scheme encourages domestic manufacturing of display components. Major metropolitan areas like Delhi-NCR and Bengaluru are spearheading large-scale public transport upgrades, integrating IoT-enabled displays.
United States
United States transit authorities prioritize accessible and reliable real-time information to enhance passenger journeys. The Americans with Disabilities Act (ADA) mandates specific visual and audible communication standards for displays. Major metropolitan areas such as New York City and Los Angeles are investing in advanced display systems for subway and bus networks.
Germany
Germany's public transit operators emphasize total cost of ownership and durability in procurement decisions for display boards. Compliance with CE marking and the EN 50155 railway standard is a prerequisite for market entry. Major cities like Berlin and Munich are implementing robust, energy-efficient display solutions for their extensive railway and metro networks.
China
China's vast urban densification projects and ongoing metro expansion create substantial demand for high-capacity display systems. National smart city policies and GB standards guide the deployment of sophisticated passenger information displays. Cities within the Yangtze River Delta and Beijing are rapidly deploying advanced display technologies in new and existing transit hubs.
United Kingdom
The United Kingdom is modernizing its public transport infrastructure, driving demand for integrated display solutions across rail and bus networks. Compliance with CE marking and EN 50155 is essential for railway applications. Transport for London (TfL) and other major urban centers are upgrading their display infrastructure to improve real-time passenger information.
Transit Station Display Board Market Key Industry Players
Player mix skews toward specialized technology providers and system integrators. The market exhibits a tiered structure, with a few large entities offering comprehensive, integrated solutions and numerous smaller firms focusing on niche applications. Strategic archetypes include large-scale infrastructure specialists, traffic management system experts, and ruggedized display manufacturers. Companies are pursuing strategic partnerships and portfolio diversification to address varied operator requirements.
Specialists in comprehensive traffic management solutions include SWARCO, leveraging its deep expertise to offer urban transit network systems. Hitachi occupies a position as a provider of large-scale, technologically advanced displays, particularly for major railway infrastructure projects. GDS Group exemplifies expertise in ruggedized display solutions, specifically engineered for challenging outdoor transit environments. These entities represent distinct segments of the market, catering to different operational scales and environmental demands within the transit sector.
| Leading Market Players |
|---|
| SWARCO |
| Toshiba Infrastructure Systems & Solutions Corporation |
| Hitachi |
| Ortana |
| Roctec Technology Limited |
| Oat Foundry |
| Softway Consultancy Private Limited |
| Nexcom International |
| GDS Group |
| Others |
Cost & Logistics Intelligence
Long lead times for custom ruggedized display components directly influence supply chain planning and exert pressure on project-based pricing for transit authorities. This dynamic necessitates robust inventory management strategies from manufacturers to mitigate potential delivery delays and cost fluctuations.
Pricing Analysis
The technology-generation pricing gap differentiates modern OLED and advanced LED displays from older LCD variants. Project-based pricing dominates for large-scale infrastructure deployments, often incorporating long-term service agreements. Price differentiation stems from rigorous certification levels, such as EN 50155 compliance, and the degree of software integration required. Pricing pressure stems from the high initial investment costs for transit authorities with constrained budgets. Private transit firms exhibit the highest price sensitivity, often prioritizing lower upfront costs, while transport authorities focus on total cost of ownership.
Supply Chain Analysis
Specific semiconductor fabs for display controllers and specialized LED component manufacturing in East Asia represent a chokepoint for the global supply chain. Geographic supply concentration for display panels and electronic components is primarily in China and South Korea. Raw material dependencies include rare earth elements for LED production and specialized plastics for weather-resistant enclosures. Geopolitical tensions affecting key manufacturing regions pose a structural supply chain risk. Distribution typically runs through direct sales channels for large public transit operators and through system integrators for smaller projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story for established players, largely due to the high regulatory entrenchment and significant switching costs associated with integrated transit information systems.
For Market Incumbents: Secure long-term service and maintenance contracts with public transit authorities to ensure recurring revenue streams and customer loyalty. Invest in advanced software platforms for predictive maintenance and AI-driven content management to counter emerging software-as-a-service (SaaS) threats from new entrants. Focus R&D on developing modular, software-upgradable systems that reduce total cost of ownership for operators.
For New Entrants and Emerging Players: Certification fast-track for niche regional standards, such as specific local accessibility requirements, offers a viable market entry point. Target underpenetrated ancillary transit hubs like bus shelters and ferry terminals, which often have lower barriers to entry compared to railway stations. A compelling go-to-market angle involves offering flexible, cloud-based content management systems bundled with wireless-enabled displays.
For Investors and Strategic Acquirers: Carve-out targets emerge from large electronics conglomerates seeking to divest non-core display divisions with specialized transit expertise. Long-term viability for investments hinges on the continued global push for urban densification and smart city initiatives. Acquisition archetypes include specialized software providers offering content management and data analytics for transit networks. A signal to watch is the increasing number of public tenders mandating comprehensive, integrated information ecosystems.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop SaaS-based content management platforms | This initiative allows transit authorities to remotely manage display networks, enhancing operational efficiency and passenger communication across urban systems. |
| Invest in EN 50155 compliant display technology | This ensures market access and competitive advantage in European railway infrastructure projects, meeting stringent safety and durability standards. |
| Form strategic partnerships with system integrators | These collaborations facilitate broader market reach and specialized deployment capabilities for complex transit network installations. |
| Expand into ancillary transit hubs like bus shelters | This move captures new growth opportunities in underpenetrated segments, broadening the application base beyond traditional railway and metro stations. |
| Acquire specialized IoT sensor technology firms | This acquisition deepens capabilities in real-time display monitoring and predictive maintenance, reducing operational downtime for transit operators. |
Research Approach
A spread of perspectives from public transit procurement officers, display manufacturers' R&D heads, system integrators, and urban planning officials converged on the working assumptions for this analysis. Primary interviews with industry stakeholders were triangulated with extensive secondary research. Secondary sources included public tender documents, transit authority annual reports, technology vendor whitepapers, and smart city initiative reports, informing both bottom-up and top-down market sizing. This comprehensive approach ensured a robust and validated data foundation.
The segmentation dimensions modeled included display type, technology integration, application area, end-user profile, and regional regulatory compliance. This analytical framework projects market trajectories across the analysis window by correlating historical growth patterns with anticipated infrastructure investments. Compound annual growth rates were derived from a detailed analysis of market drivers and restraints. Key industry-specific forecast inputs included global urbanization rates and smart city investment budgets.
Underlying assumptions cover current technological adoption rates and regulatory environments, with deviation risk concentrated in unforeseen shifts in public funding for infrastructure projects. Forecasts reflect these assumptions, but practitioners should keep alternative scenarios live as global economic conditions and evolving regulatory standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Ticketing Solution Market
Digital Solutions
Europe Smart Government Market
Digital Solutions
Europe Digital Signage Market
Digital Solutions
Service Mesh Market
Digital Solutions
Global Dock and Yard Management System Market
Digital Solutions
Germany Digital Twin Market
Digital Solutions
IT Asset Management (ITAM) Software Market
Digital Solutions
Contactless Ticketing Ics Market
Digital Solutions
Japan Online Gambling Market
Digital Solutions
UK High Performance Computing Market
Digital Solutions
Farm Management Software Market
Digital Solutions
Microservices Architecture Market
Digital Solutions
Global Interactive Whiteboard (IWB) Market
Digital Solutions
Labor Management System in Retail Market
Digital Solutions
Open-Source Intelligence (OSINT) Market
Digital Solutions
Ad Network Software Market