
 Video Management Software (VMS) Market | 2026-2036
Video Management Software (VMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Video Management Software (VMS) Market Analysis
GDPR's strict data retention and biometric processing rules are broadening compliance requirements for video analytics deployments across European enterprises. Genetec leverages its unified security platform architecture to anchor premium positioning in regulated environments. Hikvision dominates hardware-software bundled offerings in price-sensitive segments. Axis Communications differentiates through open-platform interoperability and edge-to-cloud flexibility.
Video Management Software comprises applications that ingest, process, store, and distribute video feeds from IP cameras, DVRs, and NVRs, typically supporting H.264/H.265 compression, ONVIF protocol compatibility, and real-time event correlation across thousands of camera endpoints. Its primary commercial purpose is enabling centralized situational awareness, forensic search, and automated alerting for physical security operations. Cloud-based deployments are capturing the fastest expansion as organizations trade capital intensity for subscription predictability and elastic storage scaling. On-premises installations retain dominance in government and critical infrastructure verticals where air-gapped networks and sovereign data control override cost considerations. The analytics feature layer sits at the core of margin expansion, with AI-powered object detection and behavioral pattern recognition commanding substantial pricing premiums over baseline recording and playback functionality.
FCC guidelines on communications infrastructure resilience and NHTSA transit security directives shape US procurement standards for transportation sector VMS implementations. EMA privacy assessments and EU AI Act conformity requirements are tightening vendor qualification thresholds for biometric and facial recognition deployments across European member states. OSHA workplace safety incident documentation rules extend VMS utility into industrial liability protection beyond traditional security applications. Stakeholders must monitor evolving algorithmic transparency mandates and cross-border data localization requirements as determinants of product architecture and market access.
Market Dynamics
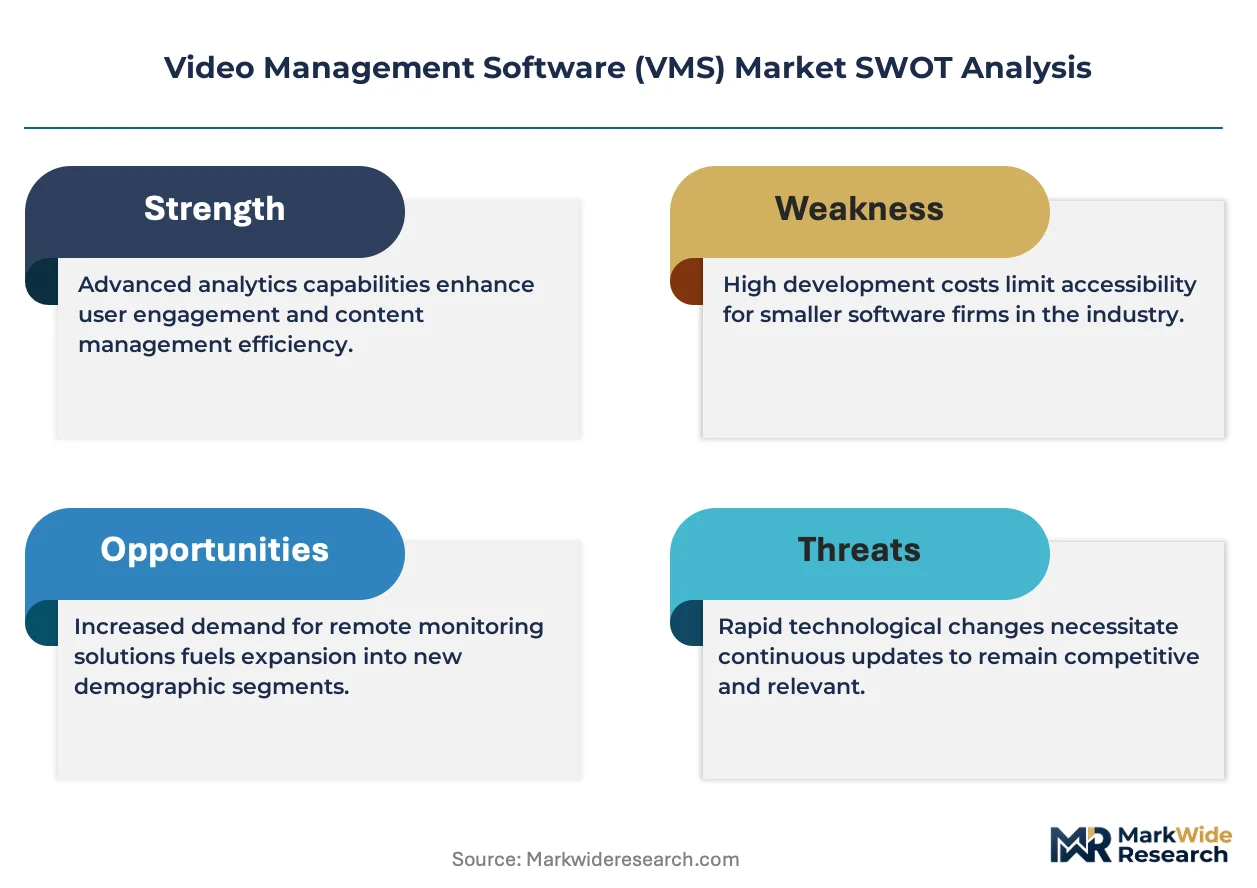
Cloud-native architectures are compressing deployment cycles for enterprise VMS buyers, forcing incumbent vendors to rearchitect legacy codebases while municipal procurement cycles lag behind private sector adoption curves.
Growth Catalysts
- FCC resilience mandates:Transportation authorities in the United States face hardened infrastructure requirements for communications systems, accelerating VMS upgrades at airports and transit hubs.
- Edge AI silicon proliferation:On-camera inference capabilities reduce bandwidth costs and enable real-time alerting without centralized processing bottlenecks.
- Smart city infrastructure budgets:Municipal governments across Germany, Singapore, and the United Arab Emirates are prioritizing integrated surveillance networks for traffic management and public safety coordination.
Market Restraints
- GPU and NPU supply concentration:Taiwan-based foundry capacity constraints limit edge device production scalability for AI-enabled camera deployments.
- GDPR biometric processing friction:European enterprises face extended legal review cycles for facial recognition implementations, delaying project approvals.
- Air-gapped network requirements:Critical infrastructure operators in energy and defense sectors cannot adopt cloud-native VMS, constraining addressable market expansion.
Strategic Opportunities
- EU AI Act conformity services:Vendors can capture recurring revenue streams by certifying high-risk biometric systems for European law enforcement and border control agencies.
- Industrial safety documentation:OSHA incident recording requirements extend VMS utility into manufacturing liability protection beyond traditional security applications.
- Hybrid edge-cloud orchestration:Converged architectures enable tiered storage economics where forensic retention stays local and analytics processing scales elastically.
Industry Challenges
- ONVIF profile interoperability gaps:Proprietary extensions by camera manufacturers fragment integration testing workloads for software vendors.
- Cybersecurity certification timelines:Common Criteria and FIPS 140-2 validation processes extend 12-18 months, delaying government contract eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Management Software (VMS) Market |
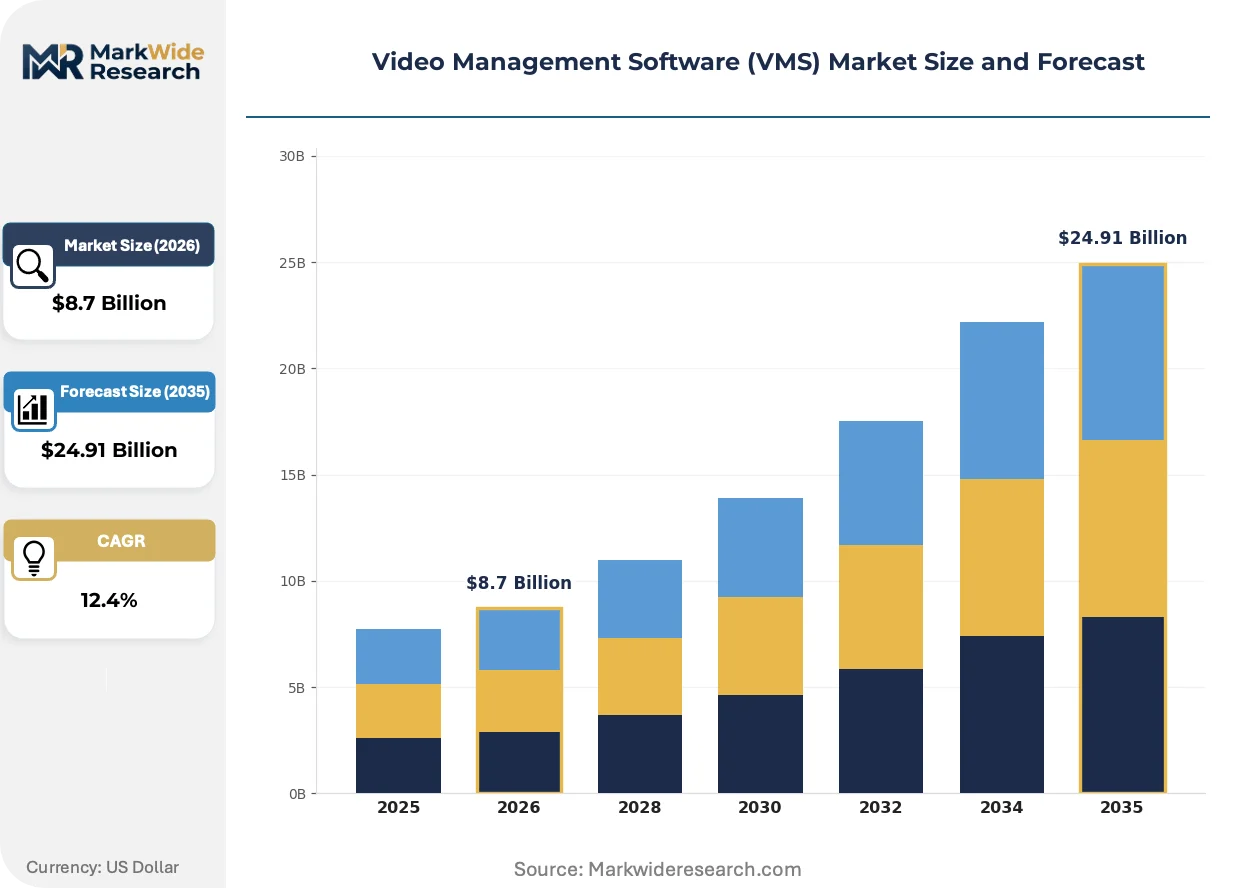
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $24.91 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premises, Hybrid, Embedded End User: Retail, Transportation, Education, Government Deployment: Public Cloud, Private Cloud, Multi-cloud, Edge Computing Feature: Analytics, Mobile Access, Multi-camera Support, Cloud Storage |
| Companies Covered | Bosch, Axis Communications, Genetec, Honeywell International, Milestone Systems, Hanwha Techwin, Hikvision, Johnson Controls, Dahua Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Management Software (VMS) Market Emerging Trajectories
Containerized microservices architectures are displacing monolithic VMS codebases, enabling modular feature deployment and reducing patch-induced downtime windows for mission-critical installations.
Serverless video analytics is overtaking provisioned VM-based processing for intermittent surveillance workloads. Retail and logistics operators with seasonal demand spikes adopt event-triggered inference to eliminate idle compute costs. This consumption model is compressing TCO advantages previously held by on-premises perpetual-license vendors.
The EU AI Act's risk classification framework is mandating algorithmic transparency documentation for biometric surveillance systems deployed in public spaces. European integrators now require vendors to supply conformity assessment packages before contract award. Law enforcement procurement in France, Germany, and Italy has shifted toward pre-certified solution bundles.
Subscription pricing for cloud VMS is displacing perpetual-license maintenance renewals in mid-market commercial segments. Value-added resellers face margin compression as direct vendor-to-end-user SaaS channels bypass traditional distribution. This channel disruption is most pronounced in United States healthcare and education verticals where IT standardization teams prefer consolidated vendor relationships.
Video Management Software (VMS) Market Segmentation
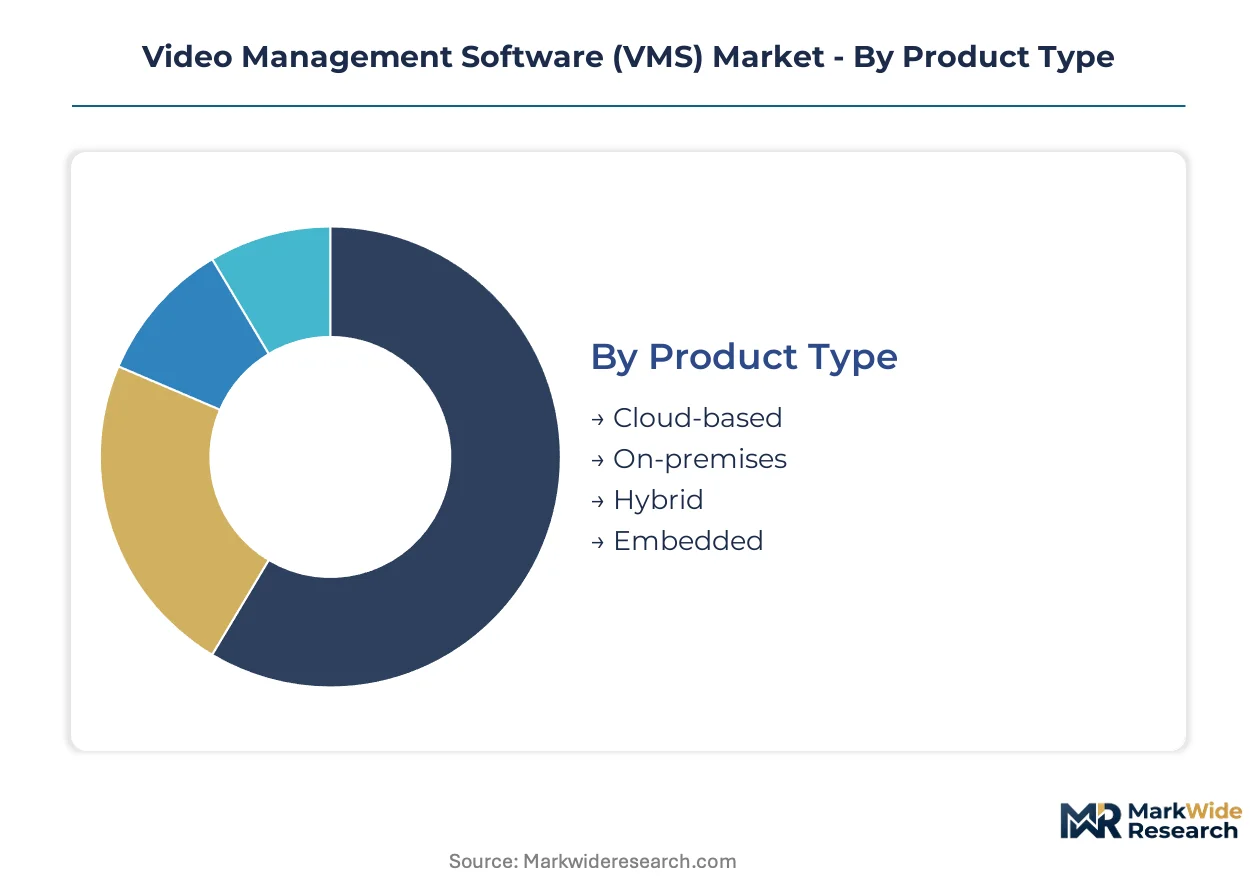
VMS procurement patterns diverge sharply across infrastructure maturity and regulatory exposure. Buyers select architectures based on data sovereignty requirements, camera density, and integration complexity with existing physical security stacks.
Product Type:
Capital intensity varies dramatically across deployment models, with perpetual-license on-premises installations demanding the highest upfront infrastructure commitment.
- Cloud-based:Subscription models eliminate server procurement and facility buildouts. Demand concentrates in United States healthcare and education verticals where IT standardization teams favor consolidated vendor relationships and elastic storage scaling.
- On-premises:Requires dedicated NVR arrays, redundant storage, and climate-controlled server rooms. Government and critical infrastructure operators in Germany and the United States select this architecture where air-gapped networks and sovereign data control override cost considerations.
- Hybrid:Blends local recording with cloud analytics tiering. Retail chains deploy this model to balance forensic retention compliance with AI-powered object detection.
- Embedded:Firmware-integrated VMS running directly on camera SoCs. Manufacturing facilities adopt this for low-latency alerting without centralized processing bottlenecks.
Most installed capacity flows through On-premises. Expansion is steepest in Cloud-based.
End User:
Application environments dictate feature prioritization and compliance burden across buyer categories.
- Transportation:Multi-site coordination across airports, rail hubs, and transit authorities demands real-time event correlation across thousands of endpoints. FCC resilience mandates and NHTSA security directives accelerate VMS upgrades at United States airports.
- Government:Federal facility security upgrades and critical infrastructure protection mandates drive enterprise deployments. FIPS 140-2 and Common Criteria certification requirements extend procurement cycles.
- Retail:Loss prevention and customer flow analytics dominate use cases. Seasonal demand spikes favor serverless video analytics to eliminate idle compute costs.
- Education:Campus safety and emergency response integration shape procurement. K-12 districts prioritize mobile access for security personnel.
Transportation commands the highest camera density per site. Retail is gaining share fastest through AI-powered behavioral pattern recognition.
Deployment:
Network architecture choices determine latency profiles, data residency, and vendor lock-in exposure.
- Public Cloud:Shared infrastructure delivers lowest unit economics for intermittent surveillance workloads. Logistics operators with seasonal spikes adopt event-triggered inference.
- Private Cloud:Dedicated tenant isolation satisfies GDPR data localization and EU AI Act conformity requirements for French and German law enforcement agencies.
- Multi-cloud:Redundancy across hyperscaler regions mitigates availability risk. Financial institutions in Singapore and the United Arab Emirates favor this architecture.
- Edge Computing:On-camera inference reduces bandwidth costs and enables sub-second alerting. Smart city traffic management systems in Germany deploy edge-first architectures.
Public Cloud hosts the broadest camera fleet. Edge Computing is climbing the fastest as AI silicon proliferation accelerates.
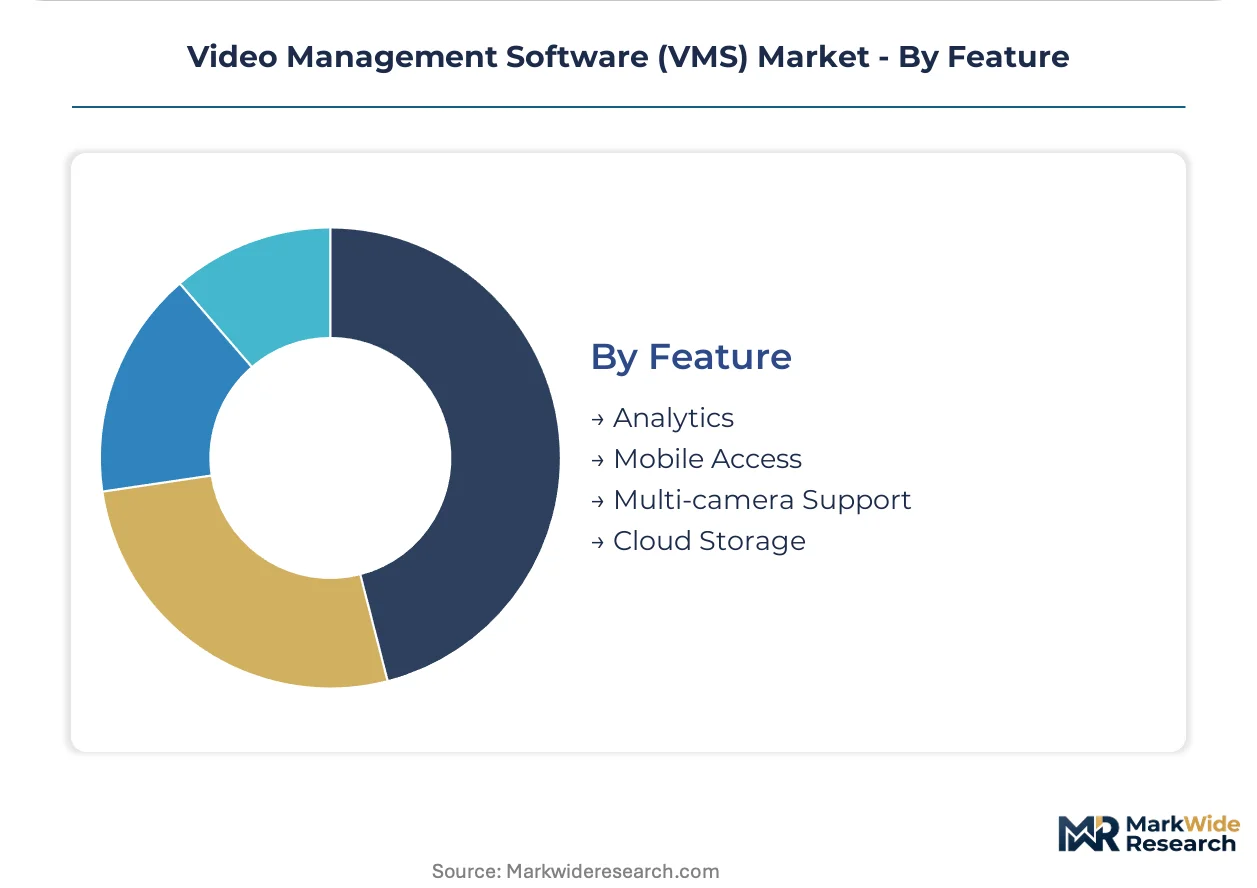
Feature:
Capability tiers separate baseline recording from premium-margin analytics layers.
- Analytics:AI-powered object detection and behavioral pattern recognition command substantial pricing premiums over baseline functionality. EU AI Act risk classification mandates algorithmic transparency documentation for biometric surveillance in public spaces.
- Mobile Access:Native iOS and Android applications enable remote monitoring for distributed security teams. Hospitality and property management sectors prioritize this capability.
- Multi-camera Support:Scalability to tens of thousands of concurrent streams distinguishes enterprise-grade platforms. Casino and stadium operators require this tier.
- Cloud Storage:Automated tiering to object storage reduces on-site retention hardware. Healthcare providers leverage this for HIPAA-compliant long-term archival.
Multi-camera Support underpins the largest installed base. Analytics is expanding most quickly through AI-powered feature premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Video management software originated in North American enterprise security environments during the IP camera transition of the early 2000s. European manufacturers subsequently developed open-platform architectures to challenge proprietary systems. Asian hardware producers now dominate camera-integrated deployments across price-sensitive segments worldwide.
United States
Federal facility security upgrades and critical infrastructure protection mandates drive enterprise VMS procurement. FCC resilience guidelines and NHTSA transit security directives shape transportation sector implementations. Airport authorities in Atlanta and Dallas-Fort Worth deploy multi-thousand-camera systems for real-time threat correlation.
Germany
Smart city infrastructure budgets prioritize integrated surveillance networks for traffic management and public safety coordination. EU AI Act conformity requirements and GDPR biometric processing rules tighten vendor qualification thresholds. Munich and Hamburg municipal authorities mandate algorithmic transparency documentation for facial recognition deployments.
China
Domestic camera manufacturing scale enables bundled hardware-software offerings across price-sensitive commercial segments. National standards for video surveillance interoperability shape procurement specifications. Shenzhen and Hangzhou technology clusters drive edge AI silicon integration into camera system-on-chips.
Singapore
Multi-cloud redundancy architectures attract financial institutions seeking availability risk mitigation. Government smart nation initiatives fund integrated sensor networks for urban management. The island-state's data center density supports low-latency video analytics processing for maritime security applications.
United Arab Emirates
Mega-project developments in Dubai and Abu Dhabi specify enterprise-grade VMS for hospitality and retail complexes. Federal critical infrastructure operators maintain air-gapped network requirements that favor on-premises architectures. NEOM's planned city infrastructure incorporates edge-first video analytics for autonomous mobility systems.
Video Management Software (VMS) Market Vendor Landscape
Capital-heavy hardware manufacturers compete with asset-light software specialists across divergent margin structures. The vendor base separates into three strategic tiers: unified security platform providers commanding premium positioning in regulated environments, hardware-software bundlers capturing price-sensitive volume segments, and open-platform specialists differentiating through interoperability commitments. Dominant competitive moves include vertical integration into edge AI silicon and strategic partnerships with hyperscale cloud providers for hybrid deployment architectures.
Within the unified platform tier, Genetec anchors premium positioning through compliance-centric feature sets for European law enforcement agencies. Axis Communications exemplifies open-platform differentiation, while Hikvision occupies the hardware-integrated volume position. Bosch and Honeywell International represent diversified industrial conglomerates leveraging existing security channel relationships. Milestone Systems and Hanwha Techwin sit within the mid-market specialist category, with Dahua Technology and Johnson Controls rounding out the hardware-software bundler archetype.
| Leading Market Players |
|---|
| Bosch |
| Axis Communications |
| Genetec |
| Honeywell International |
| Milestone Systems |
| Hanwha Techwin |
| Hikvision |
| Johnson Controls |
| Dahua Technology |
| Others |
Supply Flow & Price Mechanics
Backward integration into edge AI silicon anchors supply positioning and pricing power for hardware-software bundlers. Hikvision and Dahua Technology leverage captive camera SoC production to undercut open-platform specialists on unit economics, while Genetec and Axis Communications defend premium positioning through compliance certification investments that buyers cannot replicate internally.
Pricing Analysis
Subscription-SaaS tiering with elastic storage scaling dominates commercial segments, while perpetual licensing persists in government verticals. Price differentiation rests on FIPS 140-2 certification grade and GDPR conformity documentation depth. Cost compression in mid-market cloud tiers intensifies as direct vendor-to-end-user channels bypass traditional reseller markups. Healthcare and education buyers exhibit highest price sensitivity; critical infrastructure operators prioritize sovereign data control over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for cloud-native deployments, while value-added resellers retain government and industrial accounts. Component supply concentrates in Taiwan for GPU and NPU foundry capacity, China for camera assembly and SoC integration, and South Korea for memory modules. Raw material dependencies include silicon wafers, rare earth elements for sensor optics, and cobalt for battery-backed edge devices. Single-source vulnerability in Taiwan-based foundry capacity constrains edge AI camera production scalability. Distribution runs through systems integrators for enterprise deployments and direct procurement for municipal smart city contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification is a regulatory compounder, mandating algorithmic transparency documentation that reshapes procurement criteria and creates recurring conformity revenue streams for prepared vendors.
For Market Incumbents: Deepen certification investment in Common Criteria and FIPS 140-2 validation to defend government contract eligibility against cloud-native challengers. Anchor platform stickiness through hybrid edge-cloud orchestration capabilities that air-gapped critical infrastructure operators cannot source from pure-play SaaS entrants. Prioritize EU AI Act conformity service bundling to capture recurring revenue from European law enforcement agencies facing extended legal review cycles. For New Entrants and Emerging Players: Capture serverless video analytics demand among retail and logistics operators with seasonal surveillance workloads, where event-triggered inference eliminates idle compute costs and compresses TCO advantages of legacy perpetual-license vendors. Target United States healthcare verticals where IT standardization teams prefer consolidated vendor relationships and elastic storage scaling. Lead with direct SaaS channels that bypass traditional distribution margin compression. For Investors and Strategic Acquirers: Roll-up economics work for mid-market VMS specialists because municipal procurement cycles lag private sector cloud adoption curves, creating valuation gaps between growth-stage SaaS vendors and cash-generating on-premises installers. Focus acquisition screening on platforms with existing FIPS 140-2 or EU AI Act pre-certification that larger conglomerates can scale through existing security channel relationships. Watch edge AI silicon integration timelines as inflection indicator for hardware-software margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Unlocks law enforcement procurement in France, Germany, and Italy through pre-certified solution bundles. |
| Hybrid Edge-Cloud Architecture Launch | Enables tiered storage economics where forensic retention stays local and analytics processing scales elastically. |
| Strategic Partnership with Hyperscaler | Accelerates cloud-native deployment cycles for enterprise buyers trading capital intensity for subscription predictability. |
| Acquisition of Edge AI Silicon Specialist | Secures captive supply of on-camera inference chips reducing bandwidth costs for smart city traffic management. |
| Platform Integration with Access Control | Reinforces unified security platform positioning that Genetec leverages in regulated European environments. |
Methodological Framework
Direct dialogue with physical security directors, municipal procurement officers, IT standardization leads, and channel integration specialists grounded qualitative findings. Secondary validation drew from FCC resilience guidelines, EU AI Act conformity documentation, NHTSA transit security directives, and hyperscaler capex disclosures for cloud infrastructure expansion. Bottom-up camera deployment counts across transportation hubs, federal facilities, and smart city projects triangulated with top-down software licensing revenue estimates.
Segment-level outputs across deployment model, organization size, vertical application, and regional regulatory cluster fed into the analytical framework. CAGRs derived from elasticity-adjusted adoption curves incorporating GDPR compliance friction and edge AI silicon proliferation timelines. Model inputs included municipal infrastructure budget allocations, FIPS 140-2 certification pipeline durations, and ONVIF profile interoperability testing workloads.
Taiwan foundry capacity constraints, EU biometric processing legal review delays, and cybersecurity certification timeline extensions are the dominant revision risks. Forecasts reflect documented assumptions regarding cloud migration velocity in government verticals and edge device production scalability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Content Moderation Software Market
Software & Services
Data Compression Software Market
Software & Services
Global Online Expense Management Software Market
Software & Services
Email Checker Tools Market
Software & Services
Global App Design Software Market
Software & Services
Sales Dialer Software Market
Software & Services
Hotel Management Software Market
Software & Services
Middle-East Virtual Data Room Market
Software & Services
Global Rapid Application Development Market
Software & Services
Lead Management Software Market
Software & Services
Global Directory Software Market
Software & Services
UK Point of Sale Software Market
Software & Services
Payroll and HR Software Market
Software & Services
Load Balancing Software Market
Software & Services
Architectural Rendering Software Market
Software & Services
Enterprise Resource Planning (ERP) Software Market