
 Organic Cosmetic Ingredients Market | 2026-2036
Organic Cosmetic Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Cosmetic Ingredients Market Intelligence
Subscription-based formulation advisory services is recalibrating how ingredient portfolios get built and renewed. BASF SE leverages its biotechnology R&D hubs to sustain leadership in fermented active compounds. Croda International Plc anchors its position through backward integration into shea and palm-derived supply chains. Symrise competes by dominating the botanical extraction segment for fragrance and skin care actives.
Organic cosmetic ingredients comprise plant-derived, marine, and mineral substances certified free from synthetic pesticides, petrochemicals, and genetically modified organisms, typically processed through cold-press extraction, supercritical CO2 methods, or gentle aqueous infusion to preserve bioactive integrity for topical delivery systems. Essential oils and botanical extracts command the deepest margin pools due to concentration-dependent efficacy claims and limited geographic sourcing, while natural preservatives represent the fastest-expanding category as formulators replace parabens and phenoxyethanol across skin care and hair care applications. Plant-based sources occupy the volume leadership position, though marine-derived segments are gaining traction in premium anti-aging formulations.
REACH registration requirements and the EU Green Deal's chemical sustainability targets are forcing reformulation investments across European supply chains. ECHA's ongoing restriction proposals on endocrine-disrupting compounds are narrowing the acceptable input set for skin care and makeup applications. India's BIS organic certification standards and China's GB standards for natural cosmetics are creating parallel compliance architectures that multinational suppliers must navigate simultaneously. Stakeholders should monitor regulatory divergence between jurisdictions as a primary determinant of formulation cost structures and market access timelines.
Market Dynamics
Clean-label procurement mandates from European skin care formulators are compressing supplier qualification timelines, forcing ingredient distributors to pre-certify entire portfolios against REACH and EU Green Deal thresholds before contract negotiation begins.
Growth Catalysts
- REACH chemical restrictions:ECHA's tightening permissible substance lists are redirecting R&D budgets toward plant-derived alternatives, accelerating replacement cycles for synthetic emulsifiers and preservatives.
- Marine biotechnology:Cold-press extraction of algae-derived polysaccharides is unlocking functional claims in premium anti-aging segments previously dominated by petrochemical humectants.
- German retail concentration:Natural cosmetics retailers in Germany command disproportionate influence over European supply chain specifications, creating pull-through effects for certified organic inputs across neighboring markets.
Market Restraints
- Shea butter price volatility:West African harvest fluctuations and currency instability transmit directly into formulation cost structures for mid-tier skin care brands.
- Extraction capacity bottlenecks:Supercritical CO2 equipment requires 18-24 month lead times, constraining scale-up for botanical actives with proven efficacy profiles.
- Endocrine disruptor substitution complexity:ECHA's pending restrictions on certain UV filters force reformulation without drop-in replacements, extending product development timelines.
Strategic Opportunities
- India BIS certification:Early alignment with India's organic cosmetics standards creates first-mover positioning as domestic formulators professionalize ingredient sourcing.
- Subscription advisory services:Tiered formulation support contracts are embedding suppliers deeper into customer R&D workflows, reducing churn and improving demand visibility.
- Fermented active convergence:Biotechnology platforms combining precision fermentation with traditional botanical extraction are opening novel intellectual property positions in microbiome-targeted skin care.
Industry Challenges
- Cross-jurisdiction compliance staffing:Simultaneous navigation of REACH, BIS, and China's GB standards requires specialized regulatory talent that commands premium compensation in tight labor markets.
- Legacy ERP integration:Batch-level traceability requirements for organic certification clash with decades-old manufacturing software, forcing costly middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Cosmetic Ingredients Market |
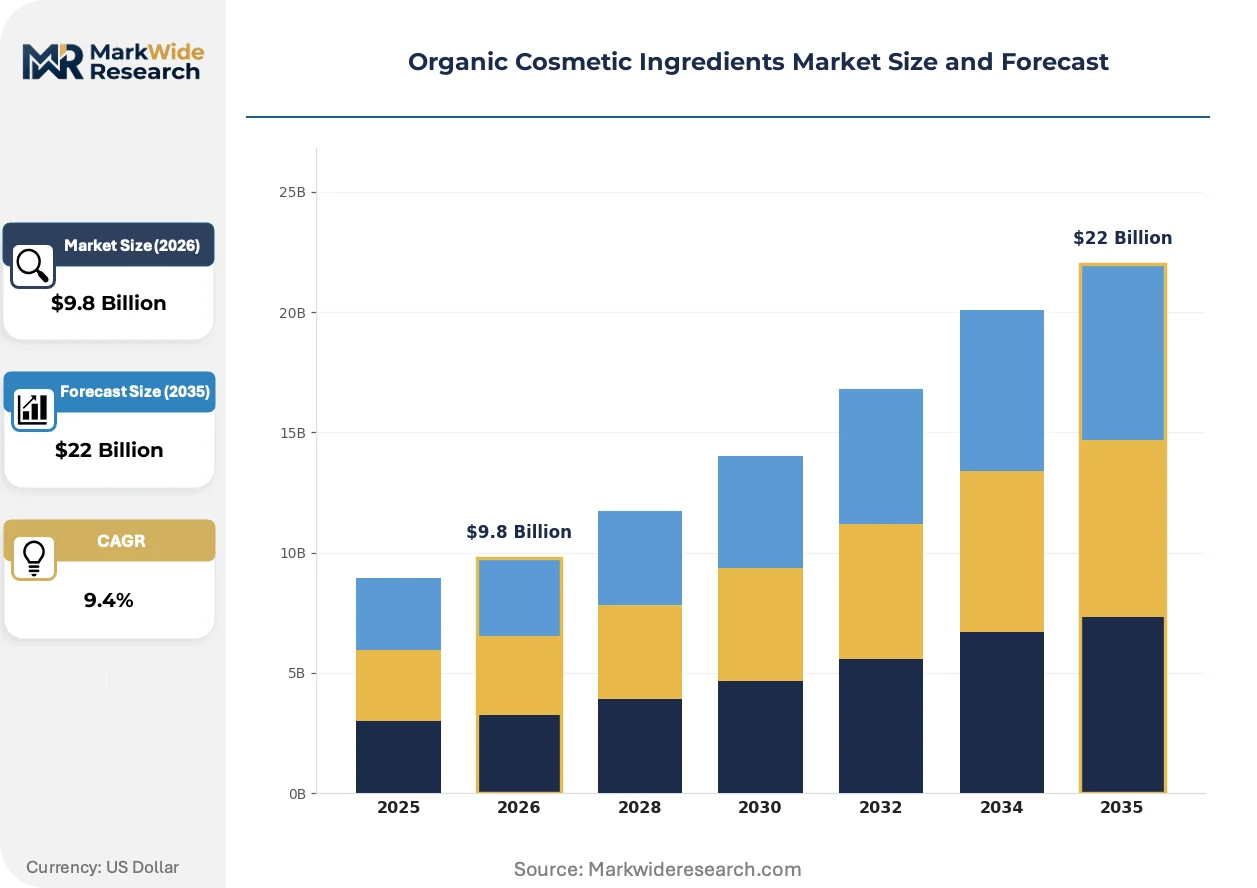
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $22 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Botanical Extracts, Natural Preservatives, Emollients Form: Liquid, Powder, Cream, Gel Application: Skin Care, Hair Care, Makeup, Fragrance Source: Plant-Based, Marine, Mineral, Animal-Derived |
| Companies Covered | Koninklijke DSM NV, Clariant AG, BASF SE, Shaanxi LonierHerb Bio - Technology Co., Ltd., Eastman Chemical Co, Croda International Plc, Solvay SA, Symrise, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Cosmetic Ingredients Market Strategic Shifts & Innovations
Biotechnology-derived actives are displacing conventional extraction methods across premium formulation tiers, while regulatory divergence between jurisdictions is fragmenting compliance architectures and reshaping supplier specialization strategies.
Precision fermentation is consolidating production economics for rare botanical molecules previously constrained by agricultural yields and seasonal harvest windows. Luxury skin care brands in France and Switzerland are accelerating adoption of fermented squalane and ceramide analogs, compressing price premiums between biotechnology and traditional plant-derived equivalents.
REACH authorization requirements are forcing mid-tier suppliers to abandon certain synthetic preservative chemistries entirely, redirecting investment toward natural antimicrobial systems derived from rosemary extract and chitosan. German formulators face the steepest compliance cost escalations, prompting consolidation of supplier relationships around vertically integrated producers with captive extraction capabilities.
Clean-label transparency mandates are shortening ingredient disclosure cycles from annual to quarterly refresh rates. Direct-to-consumer brands in California and New York now demand real-time supply chain visibility down to farm-gate coordinates, displacing traditional certificate-based verification with blockchain-enabled traceability platforms that integrate directly into e-commerce interfaces.
Organic Cosmetic Ingredients Market Segmentation
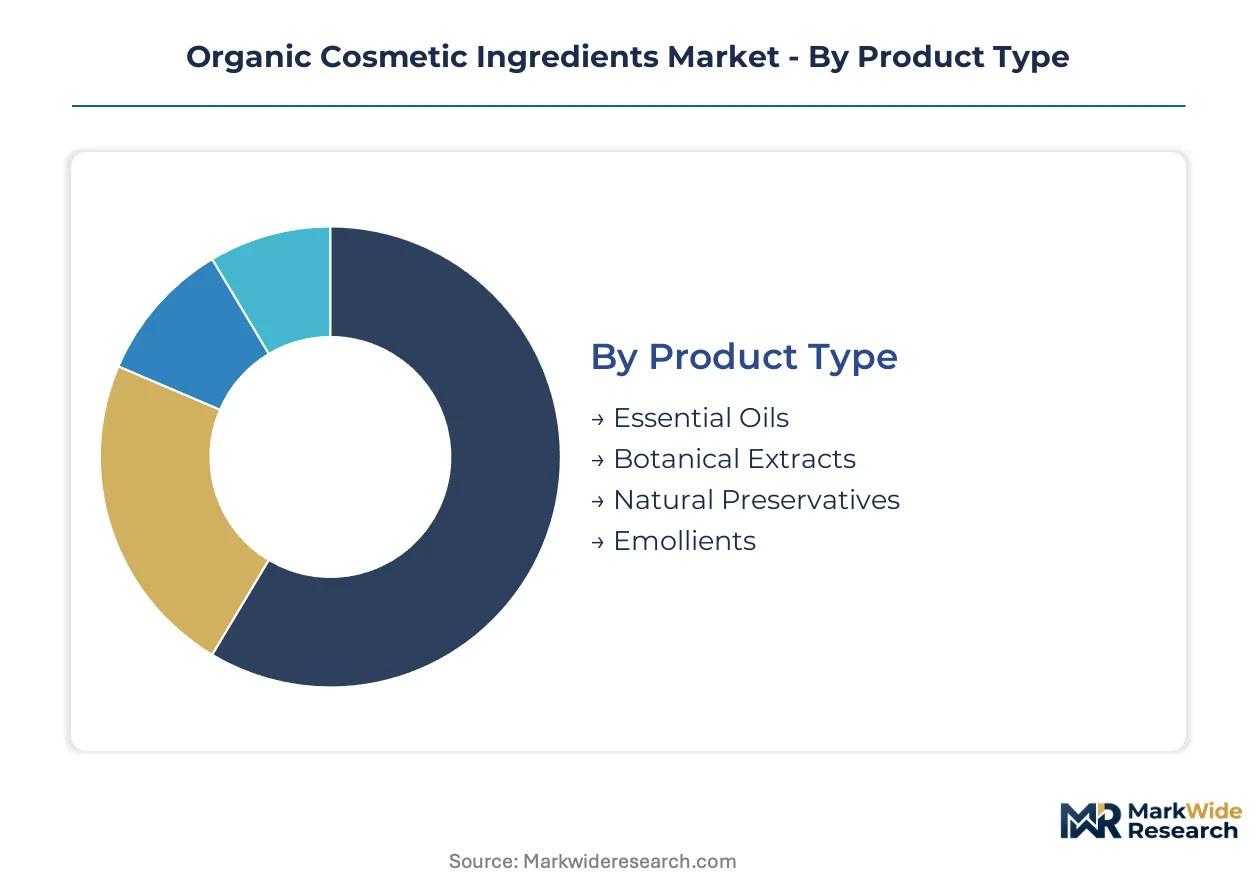
Segmentation in organic cosmetic ingredients reveals how formulation specifications cascade through supply chain procurement decisions. Technical requirements around extraction methods and certification tiers create distinct commercial zones that reshape supplier qualification protocols and margin structures across end-use categories.
Product Type:
Cold-press and supercritical CO2 extraction technologies define efficacy thresholds and geographic sourcing constraints across ingredient categories.
- Essential Oils:Concentrated volatile compounds extracted through steam distillation or cold-press methods from lavender, tea tree, and citrus cultivars. French and Bulgarian producers command premium positioning through terroir-specific certification, though harvest volatility in Mediterranean growing regions compresses margin predictability for distributors.
- Botanical Extracts:Standardized polyphenol and flavonoid concentrates from green tea, chamomile, and centella asiatica processed via aqueous or ethanol-based methods. German natural cosmetics retailers drive specification intensity here, requiring batch-level organic certification that extends supplier qualification timelines.
- Natural Preservatives:Rosemary extract, chitosan, and organic acids replacing synthetic antimicrobials under REACH pressure.
- Emollients:Plant-derived oils and butters including shea, jojoba, and squalane providing skin barrier function.
Mature deployment sits with essential oils. Newer deployment is concentrated in natural preservatives.
Form:
Physical state determines compatibility with formulation equipment and stability requirements across manufacturing scales.
- Liquid:Oil-based and aqueous extracts requiring nitrogen blanketing and UV-protective packaging to prevent oxidation. Cold-press liquid formats dominate premium skin care manufacturing in Switzerland and France, where batch consistency requirements favor suppliers with captive extraction infrastructure.
- Powder:Spray-dried and lyophilized actives offering extended shelf life and precise dosing in powder-to-liquid systems. Spray-dried botanical powders are expanding most quickly in Asian contract manufacturing facilities seeking reduced shipping weights and customs complexity.
- Cream:Pre-emulsified bases incorporating multiple actives for direct compounding.
- Gel:Hydrogel and organogel matrices for targeted delivery of heat-sensitive compounds.
Established scale sits with liquid formats. Accelerating adoption is concentrated in powder.
Application:
End-use performance claims dictate certification depth and documentation requirements through finished product registration.
- Skin Care:Anti-aging serums, moisturizers, and cleansers requiring dermatological testing and stability validation. Clean-label skin care brands in California and New York now mandate blockchain-enabled farm-gate traceability, displacing traditional certificate-based verification systems.
- Hair Care:Scalp treatments and conditioning systems where microbiome-targeted claims are displacing conventional silicone chemistry.
- Makeup:Color cosmetics facing ECHA restrictions on endocrine-disrupting UV filters and synthetic pigments.
- Fragrance:Natural perfume compounds where IFRA compliance intersects with organic certification requirements.
Volume concentration sits with skin care. Steepest expansion trajectory is concentrated in hair care.
Source:
Raw material provenance shapes regulatory pathway complexity and supply security profiles for ingredient portfolios.
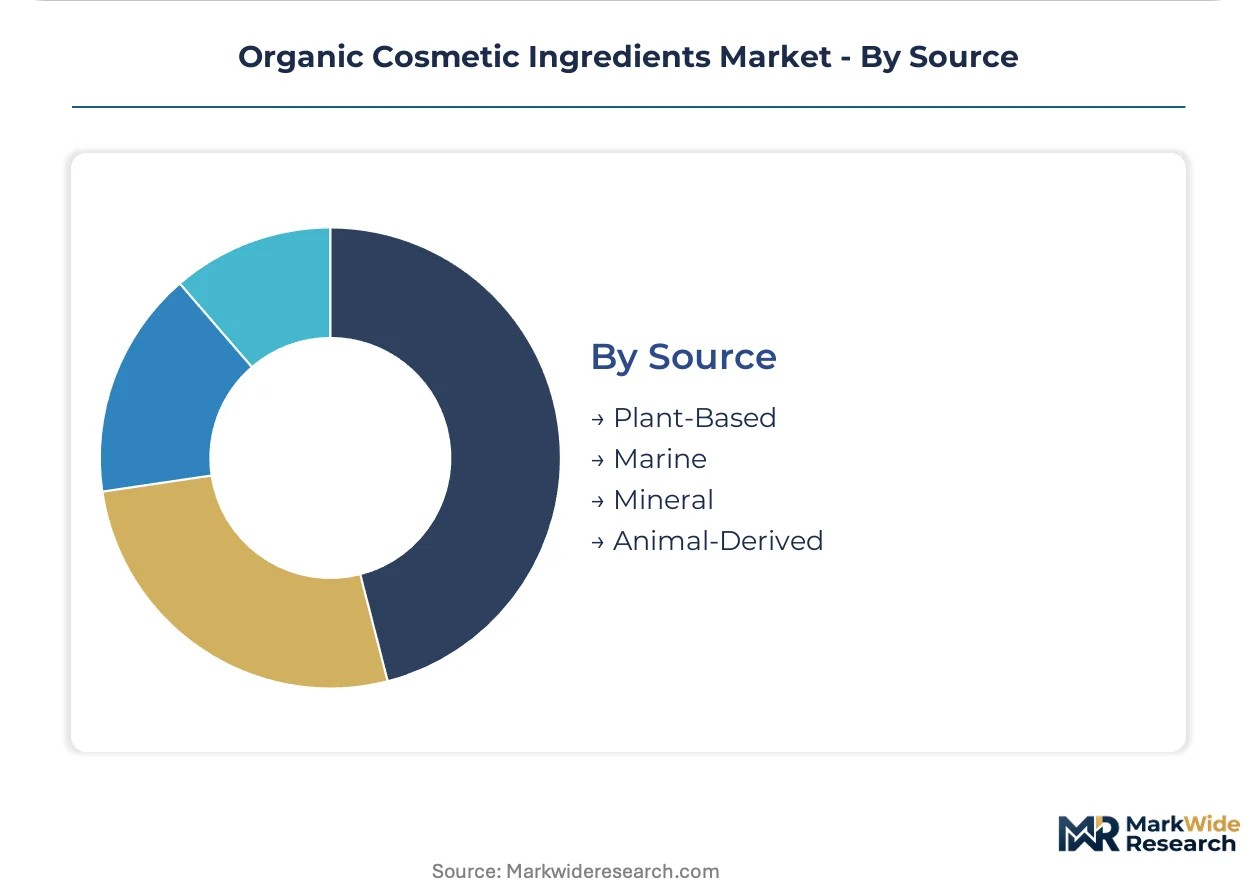
- Plant-Based:Agricultural derivatives from certified organic cultivation occupying volume leadership across all application categories. West African shea and Moroccan argan supply chains face currency instability and climate variability that transmit directly into mid-tier brand cost structures.
- Marine:Algae-derived polysaccharides and cold-press extracted bioactives from controlled aquaculture operations. Marine biotechnology platforms are gaining share fastest in premium anti-aging segments previously dominated by petrochemical humectants.
- Mineral:Clay, mica, and zinc oxide requiring heavy metal testing and conflict mineral documentation.
- Animal-Derived:Beeswax, lanolin, and honey extracts facing vegan formulation substitution pressure in European markets.
Supply maturity sits with plant-based sources. Emerging scale is concentrated in marine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg anchors European ingredient distribution, where specialized traders and certification bodies cluster around the port's logistics infrastructure for organic raw materials.
Germany
Natural cosmetics retailers in Hamburg and Berlin command disproportionate influence over European supply chain specifications, pulling certified organic inputs across neighboring markets. ECHA's REACH authorization requirements force mid-tier suppliers to abandon synthetic preservative chemistries entirely. Bavarian formulators face the steepest compliance cost escalations, consolidating supplier relationships around vertically integrated producers with captive extraction capabilities.
France
Lyon and Grasse host concentrated fragrance and skin care formulation clusters demanding terroir-specific essential oil certification. ANSM intersects with EU Green Deal chemical sustainability targets to narrow permissible input sets for topical applications. Provence lavender and Bulgarian rose supply chains face harvest volatility that compresses margin predictability for distributors serving Paris-based luxury houses.
United States
California and New York direct-to-consumer brands mandate blockchain-enabled farm-gate traceability, displacing traditional certificate-based verification systems. FDA cosmetic ingredient oversight overlaps with state-level clean-label transparency mandates in these jurisdictions. Contract manufacturers in New Jersey and Illinois adapt formulation equipment to accommodate quarterly rather than annual ingredient disclosure refresh rates.
India
Maharashtra and Gujarat house emerging domestic formulators professionalizing ingredient sourcing as BIS organic certification standards create parallel compliance architectures. CDSCO navigates cosmetic safety assessments while central government PLI schemes incentivize biotechnology manufacturing investments. Mumbai-based ingredient distributors build pre-certification capabilities against REACH thresholds to access European export channels.
China
Shanghai and Guangzhou formulators face GB standards for natural cosmetics that multinational suppliers must navigate simultaneously with Western regulatory frameworks. NMPA registration pathways for imported botanical actives extend market access timelines. Yangtze River Delta biotechnology platforms combine precision fermentation with traditional extraction to serve domestic premium skin care brands.
Organic Cosmetic Ingredients Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the organic cosmetic ingredients space, creating a tiered structure where integrated extraction specialists hold supply security advantages over formulation advisory boutiques. The vendor base separates into three strategic archetypes: biotechnology platforms leveraging precision fermentation, vertically integrated agricultural processors with captive shea and palm supply chains, and botanical extraction specialists dominating fragrance and skin care actives. Competitive moves concentrate on backward integration into raw material sourcing and subscription-based advisory contracts that embed suppliers deeper into customer R&D workflows.
Among European chemical conglomerates, BASF SE, Croda International Plc, and Symrise occupy distinct positioning vectors. BASF SE anchors the biotechnology platform archetype through fermentation R&D infrastructure. Croda International Plc exemplifies backward integration strategy with controlled supply chains for plant-derived emollients. Symrise represents the botanical extraction specialist tier with concentrated capabilities in fragrance and active compound isolation. These three structures illustrate how scale, integration depth, and technical specialization segment competitive terrain without requiring identical strategic postures.
| Leading Market Players |
|---|
| Koninklijke DSM NV |
| Clariant AG |
| BASF SE |
| Shaanxi LonierHerb Bio - Technology Co., Ltd. |
| Eastman Chemical Co |
| Croda International Plc |
| Solvay SA |
| Symrise |
| Evonik Industries AG |
| Others |
Cost & Logistics Intelligence
Supercritical CO2 extraction specialists in Bavaria command wage premiums that compress margin structures for mid-tier botanical processors, widening spreads between premium-certified and conventional-grade ingredient tiers across European supply chains.
Pricing Analysis
Outcome-based pricing anchored to bioactive concentration thresholds dominates contract structures for essential oils and fermented actives. Three-tier pricing structure across premium, standard, and economy levels separates cold-pressed terroir-certified inputs from solvent-extracted equivalents. Cost compression in mid-tier emollients is intensifying because shea butter harvest volatility transmits directly into formulation budgets. Indie skin care brands in California exhibit highest price sensitivity, while Paris-based luxury houses absorb premiums for traceability documentation.
Supply Chain Analysis
Regional distribution centers in Hamburg and Rotterdam orchestrate hub-and-spoke patterns for organic raw materials entering European formulation facilities. Supply concentrates in Bulgaria, Morocco, and West Africa for lavender, argan, and shea respectively. Cold-press equipment and supercritical CO2 systems constitute critical production dependencies. Single-source vulnerability runs through Moroccan argan cooperatives facing climate variability. Distribution runs through certified organic traders pre-qualifying portfolios against REACH thresholds before contract negotiation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race as backward integration into shea and palm supply chains emerges as the decisive lever for securing margin and specification control.
For Market Incumbents: Hedge against ECHA's pending endocrine-disruptor restrictions by accelerating natural preservative R&D partnerships and captive extraction capacity in Germany. Consolidate supplier relationships around vertically integrated producers with batch-level traceability infrastructure to defend against blockchain-enabled transparency mandates from direct-to-consumer brands. For New Entrants and Emerging Players: Enter via India's BIS certification advisory services, where domestic formulators lack pre-certification capabilities against REACH thresholds. Target Maharashtra-based contract manufacturers seeking European export qualification. Lead with subscription-based formulation support contracts that embed deeper into customer R&D workflows than transactional ingredient supply. For Investors and Strategic Acquirers: Re-rating potential sits with biotechnology platforms combining precision fermentation with botanical extraction given convergence toward microbiome-targeted skin care claims. Long-term viability favors asset-light designers with proprietary strain libraries over capital-heavy agricultural processors. Monitor CDSCO regulatory harmonization signals as inflection indicators for Indian market professionalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Shea Supply Chains | Croda International Plc's captive West African sourcing secures margin control against harvest volatility. |
| Precision Fermentation Platform Investment | BASF SE's biotechnology R&D hubs consolidate production economics for rare botanical molecules. |
| Blockchain-Enabled Traceability Deployment | California direct-to-consumer brands now mandate farm-gate coordinate disclosure displacing certificate systems. |
| BIS Certification Pre-Qualification Services | Mumbai distributors building REACH-aligned capabilities capture first-mover positioning in professionalizing Indian sourcing. |
| Subscription Advisory Contract Structuring | Tiered formulation support embeds suppliers deeper into customer R&D workflows reducing churn. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with formulation chemists at German natural cosmetics retailers, procurement leads at French luxury skin care houses, extraction equipment specialists in Bavaria, and regulatory affairs directors navigating BIS and REACH convergence were cross-validated against ECHA restriction proposals and CDSCO cosmetic safety assessments. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Data-stream reconciliation across extraction method categories, certification tiers, application end-uses, and geographic production clusters shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate synthesis rather than single-point extrapolation. Fermented active penetration curves and natural preservative substitution elasticities informed scenario boundaries.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence acceleration or marine biotechnology breakthroughs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Liposome in Cosmetics Market
Cosmetic Chemicals
Face Primer Market
Cosmetic Chemicals
Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Ethylhexylglycerin for Cosmetics Market
Cosmetic Chemicals
Lip Powder Market
Cosmetic Chemicals
Cosmetic Grade CI 77491 Market
Cosmetic Chemicals
Premium Tattoo Ink Market
Cosmetic Chemicals
Cosmetic Chemicals Market
Cosmetic Chemicals
Xerosis Market
Cosmetic Chemicals
Global Hyaluronic Acid Based Dermal Fillers Market
Cosmetic Chemicals
Makeup Emulsion Market
Cosmetic Chemicals
Chemicals for Cosmetics and Toiletries Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Anti-Acne Serum Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market
Cosmetic Chemicals
Cosmetic Cetearyl Alcohol Ingredients Market