
 Social Collaboration Software Market | 2026-2036
Social Collaboration Software Market Size, Share, and Industry Trends Forecast 2026-2036
Social Collaboration Software Market Outlook
North America is fragmenting as cloud infrastructure capacity expands across Virginia, Oregon, and Quebec data center clusters. Microsoft leverages its Azure backbone to sustain enterprise lock-in through bundled Teams and SharePoint deployments. Salesforce anchors its position by embedding Slack into CRM workflows for revenue operations teams. Atlassian competes through specialized developer-centric tooling that dominates software engineering workflows.
Social collaboration software encompasses digital platforms that integrate real-time messaging, document co-editing, video conferencing, and workflow orchestration through APIs supporting 99.99% uptime SLAs and end-to-end encryption protocols. These systems serve to eliminate information silos and accelerate decision velocity across distributed workforces. Enterprise social networks and team collaboration tools currently command the deepest margin pools as vendors bundle premium security and analytics modules. Communication platforms represent the fastest-expanding segment as voice-over-IP and asynchronous video replace legacy telephony. Project management software remains mature with slower growth but sticky renewal rates among construction and professional services buyers.
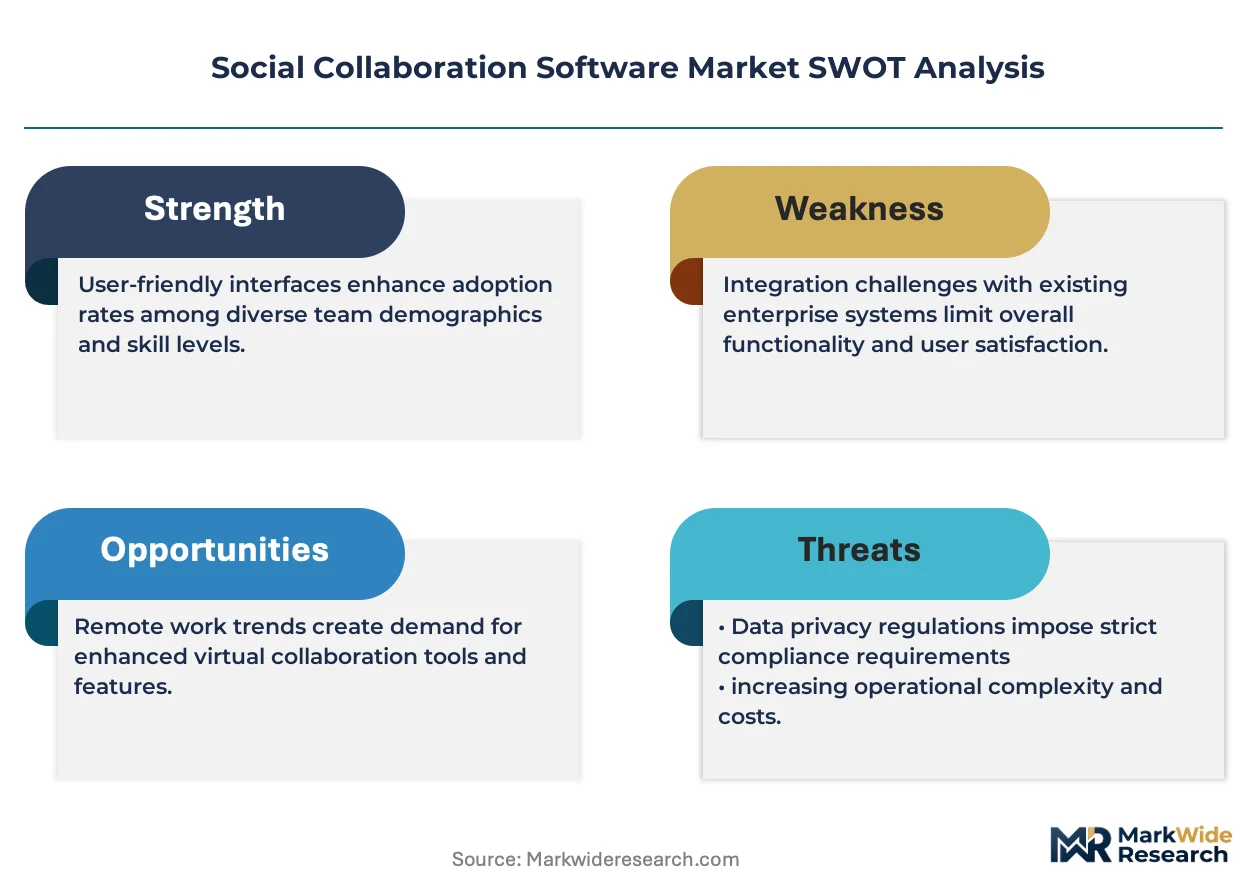
FCC broadband infrastructure rules in the United States, GDPR data residency requirements across European member states, and ISO 27001 certification standards collectively shape vendor qualification criteria and procurement timelines. Healthcare buyers in the United States additionally navigate HIPAA business associate agreements that constrain cloud deployment options. Stakeholders must monitor how generative AI integration triggers new liability frameworks before committing to platform roadmaps.
Market Dynamics
Generative AI integration is compressing feature development cycles while forcing vendors to rearchitect security models around EU AI Act conformity and HIPAA business associate agreements.
Growth Catalysts
- GDPR data residency mandates:European enterprises are consolidating vendor relationships around platforms offering sovereign cloud deployments, accelerating replacement of legacy on-premise systems.
- Healthcare workflow digitization:US hospital systems are deploying secure clinical messaging to replace pagers and fragmented pagers, driven by Joint Commission patient safety requirements.
- API-first architecture:Manufacturing enterprises in Germany's industrial corridor are embedding collaboration tools into MES and ERP systems through standardized integration protocols.
Market Restraints
- Encryption export controls:US EAR regulations restrict deployment of end-to-end encrypted platforms in sanctioned jurisdictions, fragmenting vendor roadmaps.
- Hyperscaler concentration:Cloud infrastructure dependency on three dominant providers creates single-point-of-failure risk for SaaS collaboration stacks.
- Legacy telephony sunk costs:Enterprises with multi-year PBX depreciation schedules face switching friction that delays full-stack replacement.
Strategic Opportunities
- Frontline worker mobilization:Retail and logistics operations in France are adopting lightweight mobile-first tools for deskless workforce coordination.
- CSRD reporting integration:Sustainability disclosure mandates are creating demand for collaboration platforms with embedded carbon accounting and supply chain transparency modules.
- Voice-to-text automation:Convergence of real-time transcription and task extraction is opening clinical documentation and legal discovery applications.
Industry Challenges
- AI liability frameworks:Unclear fault attribution for generative model outputs is delaying procurement sign-offs among risk-averse financial services buyers.
- ISO 27001 certification backlog:Audit capacity constraints are extending vendor qualification timelines from months to over a year.
- Interoperability tax:Custom integration work for legacy ECM systems consumes 30-40% of implementation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Social Collaboration Software Market |
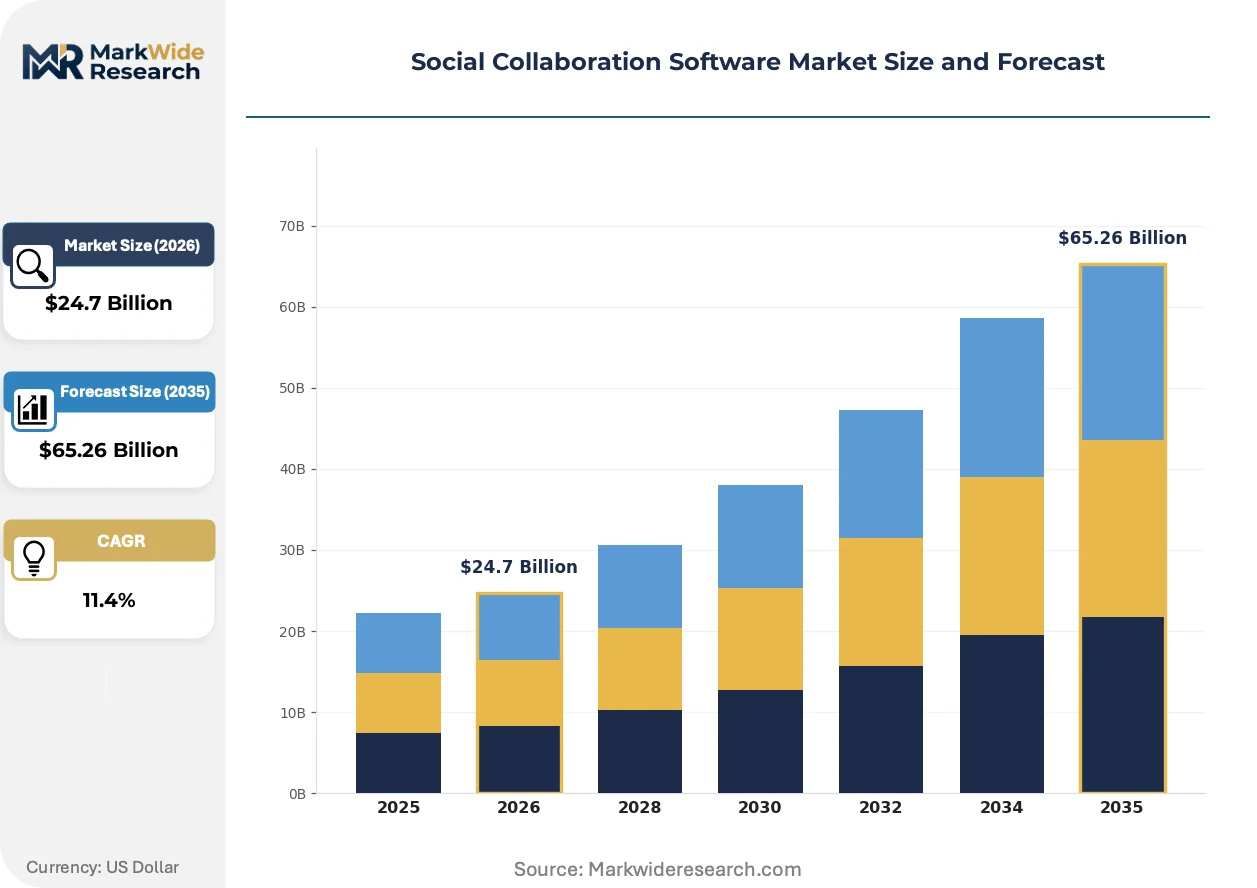
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $65.26 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enterprise Social Networks, Team Collaboration Tools, Project Management Software, Communication Platforms End User: SMBs, Large Enterprises, Educational Institutions, Non-profit Organizations Deployment: Cloud-based, On-premises, Hybrid, Open Source Service Type: Consulting, Support & Maintenance, Training, Customization |
| Companies Covered | Microsoft, Salesforce, Slack Technologies, Cisco Systems, Google, Atlassian, Zoom Video Communications, IBM, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Social Collaboration Software Market Strategic Shifts
Foundation model capabilities are collapsing the boundary between communication platforms and intelligent workflow agents, forcing architectural bets before liability standards crystallize.
Large language model copilots are collapsing the distinction between chat interfaces and task execution layers. Healthcare revenue cycle teams are piloting ambient documentation that extracts billing codes from synchronous video encounters. This compression is eliminating standalone scribe vendors and forcing platform consolidation.
The EU AI Act's risk classification system is mandating conformity assessments for high-risk workplace applications. Vendors must now document training data provenance and human oversight protocols before deploying summarization features. Healthcare and financial services procurement teams are prioritizing platforms with existing notified body certifications.
Subscription fatigue among mid-market buyers is driving unbundling of collaboration stacks. IT departments in US professional services firms are selecting best-of-breed tools for specific functions rather than accepting bundled suites. This fragmentation rewards vendors with superior API documentation and forces hyperscalers to defend position through data gravity rather than feature breadth.
Social Collaboration Software Market Segmentation
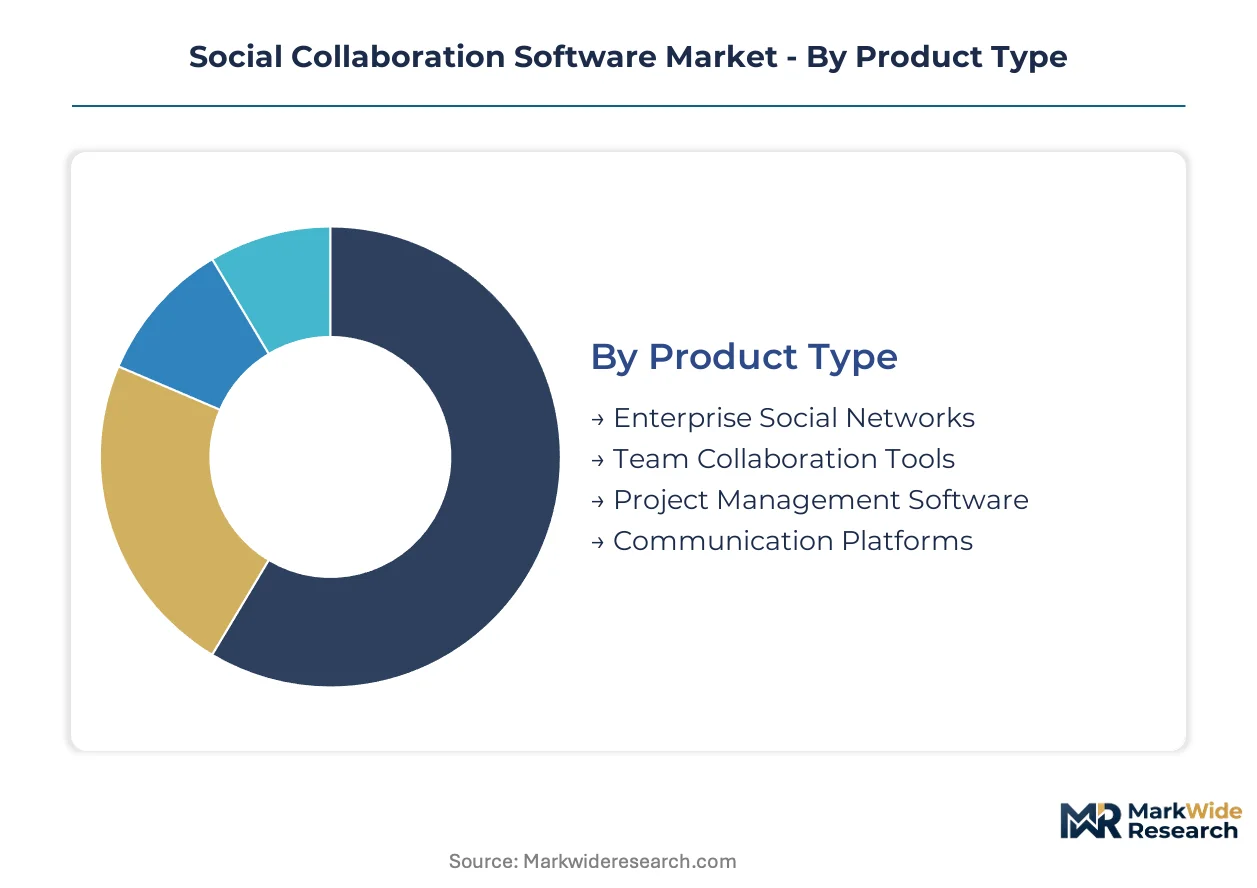
Segmentation in social collaboration software reveals how procurement priorities diverge across security postures, workforce configurations, and integration complexity. Buyers sort into distinct camps based on regulatory exposure, legacy infrastructure depreciation schedules, and generative AI readiness.
Product Type:
Application focus determines margin structure and renewal elasticity across buyer cohorts.
- Enterprise Social Networks:Organization-wide platforms with activity feeds, expertise directories, and executive broadcasting capabilities. Healthcare systems in Germany deploy these for clinical knowledge management under EU AI Act documentation requirements. Deep margin pools concentrate here through bundled security and analytics modules.
- Communication Platforms:Voice-over-IP and asynchronous video systems replacing legacy telephony infrastructure. US hospital chains accelerate pager replacement driven by Joint Commission patient safety mandates. These platforms are expanding most quickly as synchronous video converges with ambient documentation.
- Team Collaboration Tools:Channel-based messaging with threaded conversations and file sharing.
- Project Management Software:Task sequencing and resource allocation systems with Gantt visualization.
Enterprise Social Networks hold installed capacity. Communication Platforms is rotating up the share rankings.
End User:
Customer scale dictates deployment architecture and compliance module selection.
- Large Enterprises:Multi-divisional organizations with 10,000+ seats requiring federated identity management and data residency controls. France-based retail conglomerates adopt these for frontline workforce mobilization across hypermarket networks. Procurement cycles extend 12-18 months due to ISO 27001 certification requirements.
- SMBs:Sub-500 employee organizations prioritizing rapid deployment and per-seat pricing predictability. Professional services firms in the United States unbundle suites to select best-of-breed tools for specific functions. Subscription fatigue here drives fragmentation over bundled acceptance.
- Educational Institutions:Universities and K-12 districts with semester-based procurement rhythms.
- Non-profit Organizations:Grant-funded entities with constrained IT budgets and volunteer coordination needs.
Large Enterprises anchor vendor R&D roadmaps. SMBs is climbing the fastest in absolute seat additions.
Deployment:
Infrastructure location shapes liability exposure and integration tax magnitude.
- Cloud-based:Multi-tenant SaaS with 99.99% uptime SLAs and automatic feature updates. GDPR data residency mandates across European member states accelerate sovereign cloud deployments. Hyperscaler concentration creates single-point-of-failure risk that procurement teams increasingly weigh.
- Hybrid:Split architectures with sensitive data on-premises and collaboration layers in cloud. US healthcare providers navigate HIPAA business associate agreements through this model. Custom integration work for legacy ECM systems consumes 30-40% of implementation budgets here.
- On-premises:Self-managed installations with full data sovereignty and manual patch cycles.
- Open Source:Community-developed codebases with commercial support subscriptions.
Cloud-based holds installed capacity. Hybrid is rotating up the share rankings.
Service Type:
Margin capture shifts from license revenue toward ongoing relationship economics.
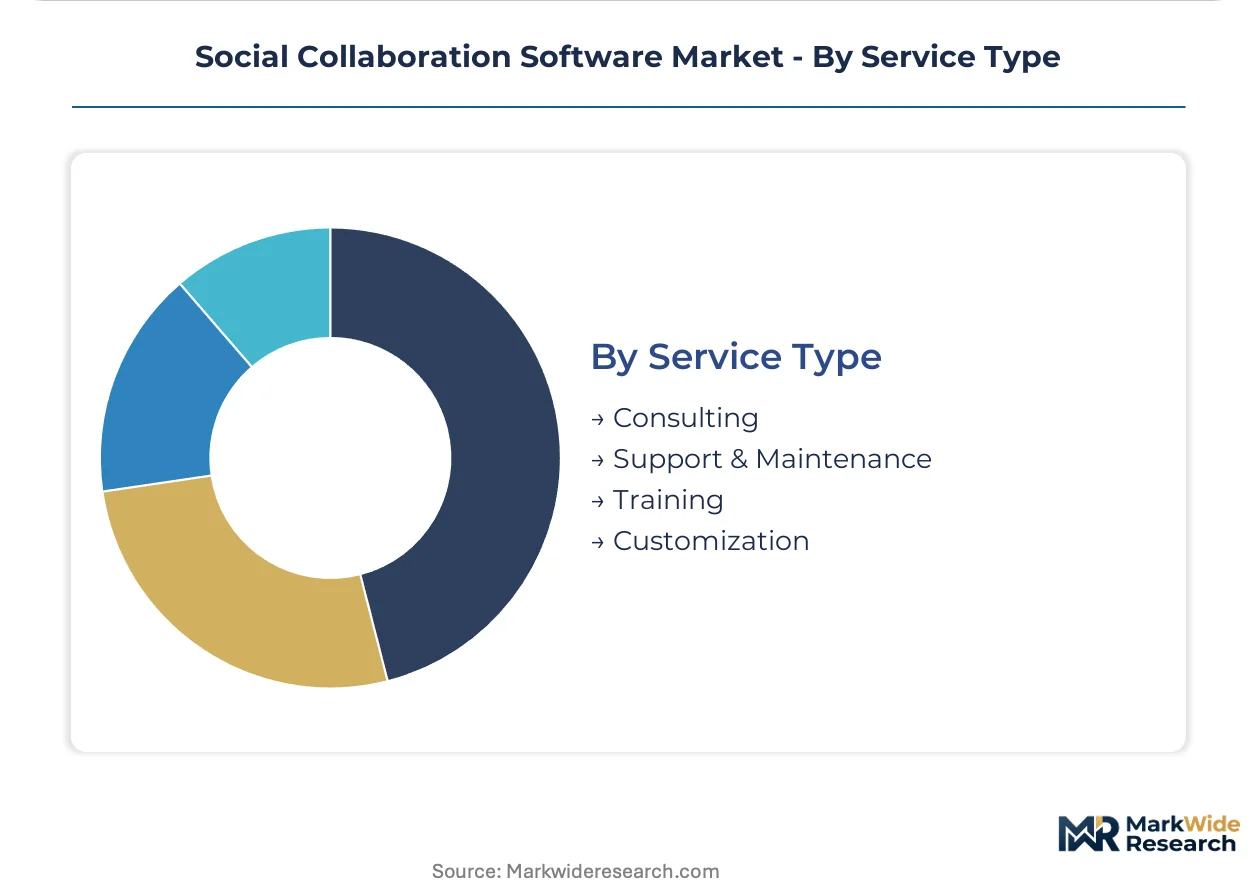
- Support & Maintenance:Tiered response-time guarantees with dedicated technical account managers. Manufacturing enterprises in Germany's industrial corridor demand 24/7 coverage for MES-embedded collaboration tools. Renewal rates here exceed 90% when tied to workflow-critical deployments.
- Consulting:Change management and adoption acceleration services for platform migrations. US financial services buyers delay procurement sign-offs pending clarity on AI liability frameworks, extending consulting engagement durations. Audit capacity constraints for ISO 27001 certifications stretch vendor qualification timelines.
- Training:Certification programs and end-user enablement curricula.
- Customization:API development and bespoke workflow automation builds.
Support & Maintenance holds installed capacity. Consulting is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC broadband infrastructure rules in the United States anchor the dominant geography, while GDPR data residency mandates across European member states and ISO 27001 certification standards collectively reshape vendor qualification criteria and procurement timelines worldwide.
United States
US hospital systems deploy secure clinical messaging to replace pagers, driven by Joint Commission patient safety requirements and HIPAA business associate agreements that constrain cloud deployment options. FCC broadband infrastructure rules expand cloud capacity across Virginia, Oregon, and Quebec data center clusters. Healthcare revenue cycle teams in Boston and San Francisco pilot ambient documentation extracting billing codes from synchronous video encounters.
Germany
Manufacturing enterprises in Germany's industrial corridor embed collaboration tools into MES and ERP systems through standardized integration protocols. EU AI Act conformity assessments mandate documented training data provenance and human oversight protocols for high-risk workplace applications. Siemens and Bosch anchor demand in Bavaria and Baden-Württemberg as automotive suppliers digitize shop-floor coordination.
United Kingdom
Professional services firms in London unbundle suites to select best-of-breed tools for specific functions, driving fragmentation over bundled acceptance. GDPR data residency requirements accelerate sovereign cloud deployments as enterprises consolidate vendor relationships. Financial services procurement teams in the City of London delay sign-offs pending clarity on AI liability frameworks for generative model outputs.
France
Retail and logistics operations adopt lightweight mobile-first tools for deskless workforce coordination across hypermarket networks. CSRD reporting integration creates demand for platforms with embedded carbon accounting and supply chain transparency modules. Carrefour and LVMH anchor procurement in Île-de-France as frontline worker mobilization accelerates.
Japan
Enterprise buyers prioritize platforms with existing notified body certifications under EU AI Act risk classification systems for cross-border deployment compatibility. METI industrial digitization programs accelerate API-first architecture adoption. Toyota and Sony drive demand in the Nagoya and Tokyo corridors as manufacturing workflows converge with intelligent automation layers.
Social Collaboration Software Market Competitive Environment
Capability concentration sits with specialized developer-centric vendors; scale advantage sits with hyperscaler-backed platforms bundling infrastructure and productivity suites. The market structure reflects a tiered hierarchy where enterprise lock-in through data gravity competes against best-of-breed unbundling. Three archetypes dominate: hyperscaler-integrated stacks, workflow-specialized independents, and security-hardened vertical solutions. Competitive moves center on API ecosystem expansion and generative AI feature integration ahead of liability standard crystallization.
Within the hyperscaler-integrated tier, Microsoft and Google exemplify platforms leveraging cloud infrastructure to sustain enterprise relationships through bundled deployments. Atlassian occupies a position representing the workflow-specialized archetype, anchoring developer-centric tooling that dominates software engineering collaboration. Salesforce sits within the CRM-embedded communication tier, exemplifying how revenue operations teams drive platform consolidation through workflow integration.
| Leading Market Players |
|---|
| Microsoft |
| Salesforce |
| Slack Technologies |
| Cisco Systems |
| Atlassian |
| Zoom Video Communications |
| IBM |
| Oracle |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in hyperscaler data center clusters across Virginia, Oregon, and Quebec is compressing infrastructure costs and enabling aggressive SaaS bundling strategies that reshape buyer procurement calculus across enterprise segments.
Pricing Analysis
Per-seat pricing spreads 40-60% between North American enterprise deployments and European sovereign cloud configurations driven by GDPR data residency premiums. The dominant structure is three-tier subscription licensing across premium security, standard collaboration, and economy communication tiers. Price differentiation rests on ISO 27001 certification grade and integration complexity with legacy ECM systems. Cost compression in the mid-market tier is intensifying because SMB buyers unbundle suites to select best-of-breed point solutions. Healthcare providers show least price sensitivity due to HIPAA compliance requirements, while professional services firms exhibit highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration sits with Foxconn, Wistron, and Quanta Computer for endpoint hardware supporting collaboration deployments. Geographic supply concentration centers on Taiwan for semiconductor components, China for consumer-grade hardware assembly, and Mexico for North American logistics optimization. Raw material dependencies draw from rare earth elements for server magnets, high-purity silicon for chip fabrication, and lithium-ion cells for mobile device batteries. Single-source vulnerability in advanced GPU supply for AI inference workloads threatens platform roadmaps. Distribution runs through hyperscaler marketplaces, direct enterprise sales teams, and regional systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in unbundled procurement patterns as mid-market buyers reject bundled suites for best-of-breed specialization, creating niche openings for API-native specialists.
For Market Incumbents: Entrench data gravity advantages through deeper SharePoint and Teams integration while accelerating EU AI Act conformity assessments ahead of liability framework crystallization. Defensive consolidation should prioritize acquiring ambient documentation startups threatening clinical messaging margins. Capacity addition in German sovereign cloud regions addresses GDPR-driven vendor consolidation. For New Entrants and Emerging Players: Frontline workforce mobilization tools for deskless retail and logistics operations in France represent the most penetrable entry point given Carrefour and LVMH procurement momentum. API-first architectures for MES-ERP embedding in Germany's industrial corridor offer second white-space target. Go-to-market should route through manufacturing systems integrators with existing shop-floor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native communication platforms as hyperscaler infrastructure commoditizes compute layers. Long-term viability favors vertical specialists with HIPAA business associate agreements and notified body certifications under EU AI Act risk classifications. Acquisition target archetype: clinical workflow platforms with ambient documentation capabilities. The signal to watch is Joint Commission patient safety mandate acceleration driving pager replacement procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Notified body assessments unlock healthcare and financial services procurement pipelines in Germany and France. |
| Ambient Documentation Integration | Revenue cycle automation threatens standalone scribe vendors and forces platform consolidation in US hospital systems. |
| Sovereign Cloud Deployment | GDPR data residency mandates accelerate replacement of legacy on-premise systems across European member states. |
| API Ecosystem Expansion | Standardized integration protocols enable MES-ERP embedding for manufacturing enterprises in Baden-Württemberg. |
| Frontline Worker Mobilization | Lightweight mobile-first tools capture deskless coordination demand from Carrefour and LVMH hypermarket networks. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with CTOs, IT procurement officers, platform engineers, and healthcare informatics directors; and secondary validation against SEC filings, hyperscaler capex disclosures, App Annie mobile adoption metrics, and EU regulatory conformity databases. Bottom-up sizing triangulated seat-count deployments by organization tier against top-down revenue aggregation across vendor segments.
Forecast inputs considered deployment model transitions, organization size migration patterns, vertical regulatory exposure tiers, and regional adoption velocity differentials across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro technology spending indicators. Industry-specific inputs included Joint Commission patient safety mandate timelines and EU AI Act implementation phase schedules.
Macroeconomic conditions sit as an overlay; deviation in enterprise software budget cycles, cloud infrastructure pricing, or cross-border data transfer restrictions would shift the trajectory. Forecasts reflect documented assumptions about regulatory compliance timelines and substitution elasticity between bundled suites and point solutions. Quarterly review of ISO 27001 certification backlog durations and AI liability framework clarity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Online Form Builder Software Market
Software & Services
Business Productivity Software Market
Software & Services
Compositing Software Market
Software & Services
Visitor Identification Software Market
Software & Services
Optical Coatings Design Software Market
Software & Services
Global Web Scraper Software Market
Software & Services
Global Help Desk Software Market
Software & Services
Global Offshore Software Development Market
Software & Services
Latin America ERP Software Market
Software & Services
Global Time and Attendance Management Software Market
Software & Services
Cloud Backup and Recovery Software Market
Software & Services
Global Digital Experience Management Software Market
Software & Services
Global Embedded Database Management Systems Market
Software & Services
Global Meeting Room Booking System Software Market
Software & Services
Global Version Control Systems Market
Software & Services
Android Emulator Market