
 Europe Wall Coverings Market | 2026-2036
Europe Wall Coverings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wall Coverings Market Foresight
European wallcovering production is decoupling from legacy PVC-dependent supply chains as Belgian and Dutch coating specialists retool for water-based polymer lines. Grandeco Wallfashion Group leverages its Benelux manufacturing footprint to sustain pan-European distribution density for non-woven substrates. Akzo Nobel N.V. anchors decorative coatings supply through its controlled pigment and resin formulation network. Sanderson Design Group differentiates via heritage archive licensing that commands premium positioning in British residential specification.
Wall coverings encompass surface-finishing materials applied to interior vertical substrates for protection, acoustical modulation, or aesthetic enhancement, typically manufactured through calendering, coating, or textile lamination processes yielding specified widths and fire-resistance ratings. Residential spaces remain the volume foundation across Papers and Vinyl segments, though Hospitality applications represent the fastest-growing specification channel as hotel operators cycle assets toward experiential design. Natural Fiber materials command margin concentration among designer-led projects, while PVC-based solutions dominate contractor-driven commercial installations where cost efficiency and washability outweigh sustainability premiums.
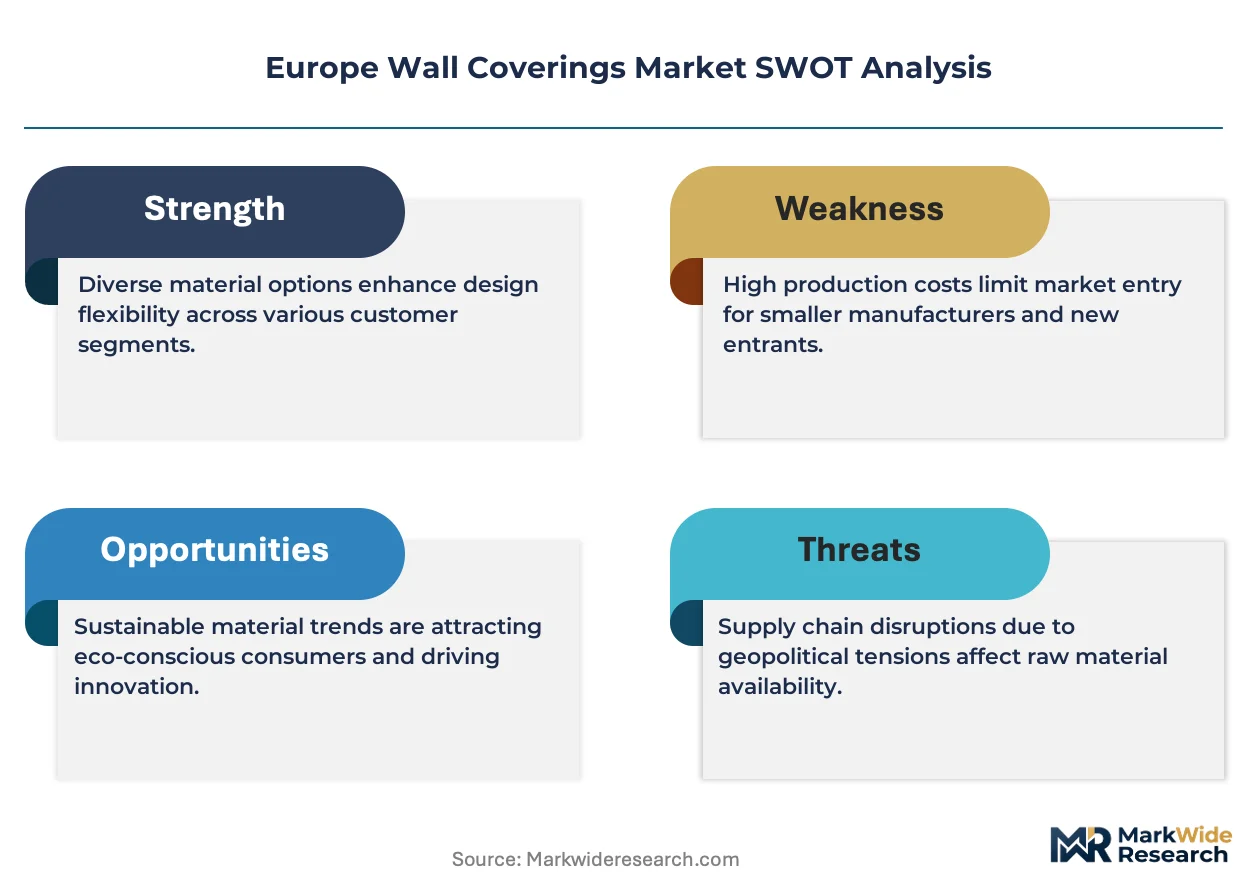
REACH compliance and the EU Green Deal's building performance standards are reshaping material permissible chemistry across the European Economic Area, with ECHA substance restrictions directly limiting certain plasticizer categories in vinyl wallcovering formulations. CE marking under the Construction Products Regulation mandates declared fire performance for commercial applications, creating divergent certification burdens between member states with stricter national annexes. Stakeholders must monitor the trajectory of CSRD-aligned supply chain disclosure requirements, which will force substrate provenance transparency before the decade closes.
Market Dynamics
EU Green Deal building renovation targets are compressing specification timelines across commercial interiors, forcing contractors to pre-validate substrate compliance before tender submission rather than during project execution.
Growth Catalysts
- Hospitality asset cycling:German, French, and Italian hotel operators are compressing renovation intervals to 5-7 years, creating recurring demand for premium textile and vinyl installations.
- REACH substance restrictions:ECHA limitations on phthalate plasticizers are accelerating R&D investment in bio-based polymer alternatives across coating specialists.
- Non-woven substrate adoption:Large-format installation efficiency gains are pulling commercial contractors away from traditional paper-backed products toward certified non-woven lines.
Market Restraints
- PVC feedstock volatility:Chlor-alkali energy intensity exposes vinyl wallcovering margins to natural gas price swings at Antwerp-Rotterdam chemical clusters.
- Coating specialist concentration:Benelux water-based polymer retooling creates single-source risk for pan-European non-woven supply during transition periods.
- CE marking divergence:Stricter national annexes in France and Italy impose redundant fire-performance testing beyond baseline CPR requirements.
Strategic Opportunities
- CSRD-aligned provenance disclosure:Upcoming supply chain transparency mandates create first-mover advantage for substrate traceability systems.
- Polish commercial corridor development:Warsaw and Kraków office refurbishment rates lag western capitals, offering volume expansion for certified product lines.
- Digital print-on-demand integration:Short-run customization capability converges with heritage archive licensing to unlock residential premium positioning.
Industry Challenges
- Installer certification gaps:Large-format non-woven application requires specialized seam-matching skills that outpace vocational training program updates.
- Dual chemistry inventory management:Contractors must stock both legacy PVC and emerging water-based lines during multi-year transition windows, straining working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wall Coverings Market |
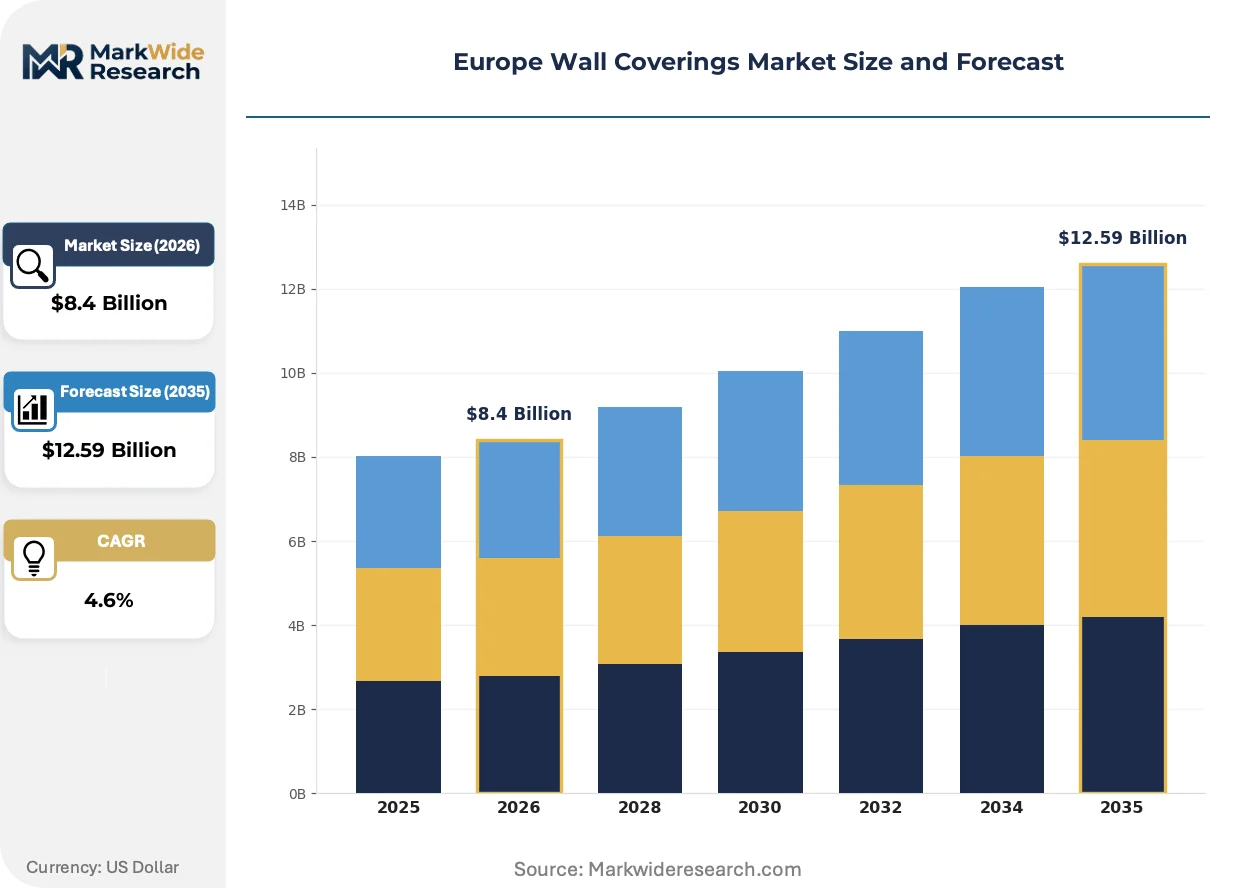
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Papers, Vinyl, Textiles, Wood Application: Residential Spaces, Commercial Spaces, Hospitality, Institutional Settings Material: Non-Woven, PVC, Natural Fiber, Synthetic Fiber End User: Homeowners, Designers, Contractors, Retailers |
| Companies Covered | Benjamin Moore & Co., Grandeco Wallfashion Group, Akzo Nobel N.V., Sanderson Design Group, Osborne & Little Ltd., A.S. Création Tapeten AG, Ahlstrom-Munksjö Oyj, Walker Greenbank PLC, Arte International N.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wall Coverings Market Shifts & Advancements
Material chemistry transformation is the dominant theme, with coating technology, regulatory disclosure architecture, and procurement behavior all pivoting simultaneously toward verifiable sustainability credentials.
Water-based acrylic-polyurethane hybrid coatings are absorbing specification share from solvent-borne systems in commercial vinyl production. Hospitality operators in Milan and Barcelona specify these formulations for LEED-equivalent project scoring. The shift is absorbing margin compression from higher raw material costs through reduced ventilation and drying infrastructure at installation sites.
EU Green Deal building performance standards are tightening VOC emission thresholds for interior finish materials. ECHA substance restrictions now directly limit specific plasticizer categories, forcing reformulation cycles across Belgian and Dutch coating lines. German commercial contractors respond by demanding pre-certified substrate documentation to avoid project delay penalties.
Specification decisions now consolidate at the general contractor level rather than dispersing to interior designers. Large-format non-woven products enable faster installation cycles that align with compressed hospitality renovation windows. This concentration is most visible in Frankfurt and Munich corridor projects where single-source procurement reduces coordination friction.
Europe Wall Coverings Market Segmentation
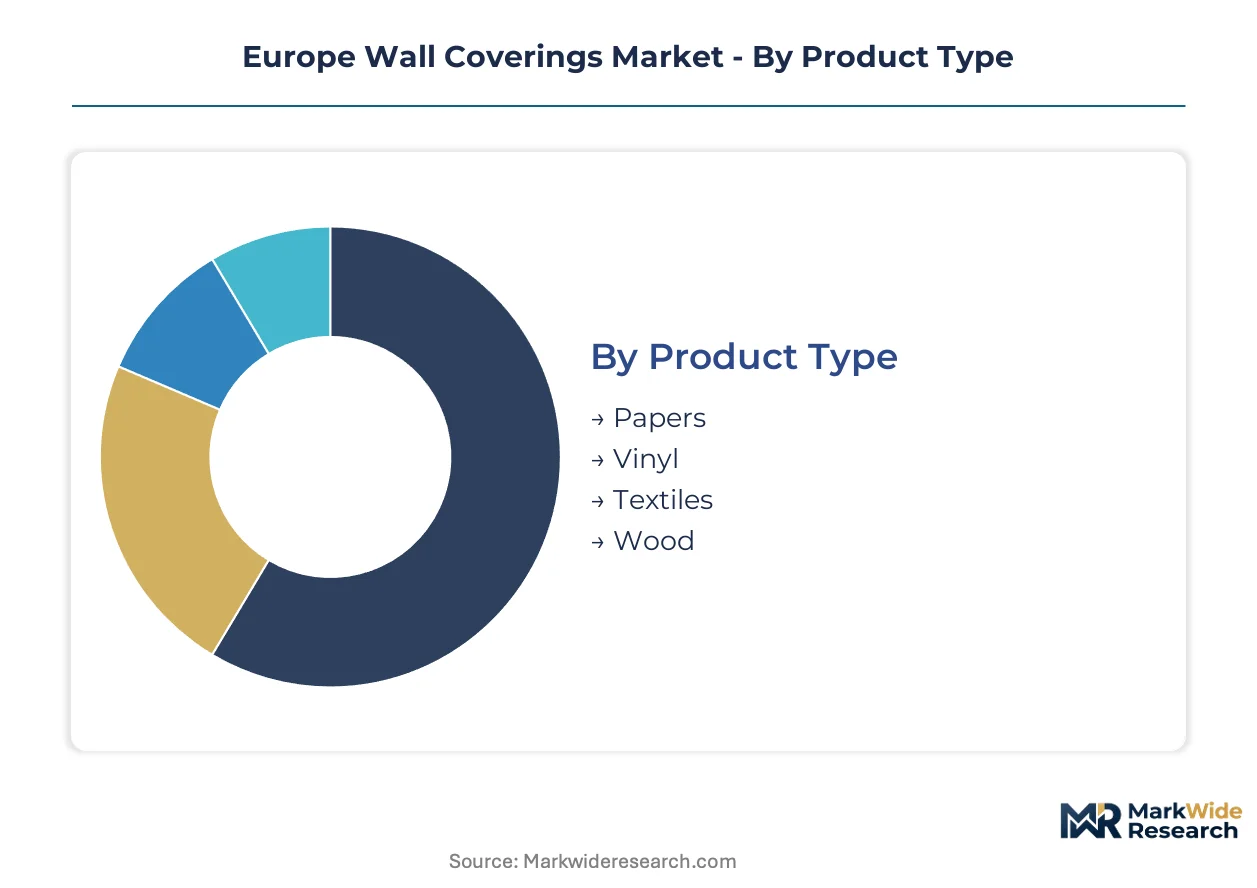
Wall covering specification in Europe fragments across multiple decision axes, from substrate chemistry to procurement authority. Understanding these segment boundaries clarifies where margin concentrates and which channels absorb regulatory compliance costs first.
Product Type:
Customization intensity varies sharply across this spectrum, from mass-produced vinyl rolls to bespoke textile commissions.
- Vinyl:Calendered or coated polymer substrates dominate commercial installation volumes across Germany and France. Washability and fire certification align with hospitality operator procurement standards. Belgian coating specialists are retooling production lines toward water-based acrylic formulations to meet tightening ECHA substance restrictions.
- Papers:Traditional cellulose-based wallcoverings retain residential volume leadership in British and Italian markets. Heritage archive licensing from Sanderson Design Group commands premium positioning among designer-led specification channels.
- Textiles:Woven or laminated fabric substrates serve experiential design requirements in luxury hospitality. Milan and Barcelona hotel operators specify these for acoustic modulation and tactile differentiation.
- Wood:Engineered veneer panels occupy niche commercial applications requiring natural material disclosure under upcoming CSRD-aligned mandates.
Most installed capacity flows through Vinyl. Expansion is steepest in Textiles.
Application:
Project scale and compliance burden separate residential from commercial channels, with hospitality occupying the high-velocity middle ground.
- Hospitality:German, French, and Italian hotel operators compress renovation cycles to five-to-seven-year intervals. Large-format non-woven installation efficiency aligns with compressed project windows in Frankfurt and Munich corridor developments.
- Residential Spaces:British and Italian homeowners drive volume across Papers and Vinyl segments. Digital print-on-demand integration is unlocking short-run customization for heritage archive licensing.
- Commercial Spaces:Warsaw and Kraków office refurbishment rates lag western capitals, offering volume expansion for certified product lines. CE marking under CPR mandates declared fire performance.
- Institutional Settings:Healthcare and education procurement prioritizes washability and VOC emission compliance under EU Green Deal building performance standards.
Hospitality absorbs the highest specification velocity. Institutional Settings impose the strictest certification requirements.
Material:
Supply chain provenance transparency is becoming the primary sorting mechanism as REACH compliance tightens.
- Non-Woven:Synthetic fiber mat bonded with latex or acrylic enables large-format installation efficiency. German commercial contractors prioritize certified lines to avoid project delay penalties from compliance documentation gaps.
- PVC:Chlor-alkali-derived polymer dominates cost-sensitive commercial installations. Antwerp-Rotterdam chemical cluster energy intensity exposes margins to natural gas price volatility.
- Natural Fiber:Cellulose, jute, or sisal substrates command margin concentration in designer-led projects. ECHA substance restrictions on phthalate plasticizers accelerate R&D investment in bio-based alternatives.
- Synthetic Fiber:Polyester or nylon-based substrates serve durability requirements in high-traffic hospitality corridors.
Non-Woven is gaining share fastest among commercial contractors. Natural Fiber carries the highest sustainability premium.
End User:
Procurement authority is consolidating at the general contractor level, compressing designer influence and retailer margins.
- Contractors:German commercial refurbishment specialists now control substrate specification for large-format non-woven installations. Single-source procurement reduces coordination friction in compressed hospitality renovation timelines.
- Designers:Heritage archive licensing and textile specification retain influence in British residential and luxury hospitality channels. Vocational training program updates lag specialized seam-matching skill requirements for non-woven application.
- Homeowners:Digital print-on-demand platforms are disintermediating traditional retail for residential Papers and Vinyl segments.
- Retailers:Inventory management strain from dual chemistry requirements during multi-year transition windows is compressing working capital availability.
Contractors control the steepest volume growth. Designers retain the highest margin access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian and Dutch coating specialists are capturing production share as ECHA substance restrictions widen the compliance-cost gap with legacy PVC-dependent supply chains. Benelux water-based polymer retooling draws specification volume from German and French commercial refurbishment corridors seeking pre-certified substrate documentation.
Germany
Frankfurt and Munich hospitality corridors drive specification velocity for large-format non-woven installations. EU Green Deal building performance standards mandate declared fire performance under CE marking for commercial applications. North Rhine-Westphalia coating clusters anchor water-based acrylic-polyurethane hybrid production serving pan-European distribution.
France
Paris hotel operators compress renovation cycles to five-year intervals, accelerating demand for premium textile and vinyl products. Stricter national annexes under the Construction Products Regulation impose redundant fire-performance testing beyond baseline requirements. Île-de-France specification channels consolidate procurement authority at the general contractor level.
Italy
Milan and Barcelona luxury hospitality operators specify woven fabric substrates for acoustic modulation and tactile differentiation. REACH compliance documentation gaps trigger project delay penalties, forcing contractors toward pre-validated supply relationships. Lombardy textile lamination specialists serve experiential design requirements across Mediterranean markets.
United Kingdom
British residential channels retain volume leadership across Papers segments, with heritage archive licensing commanding premium positioning. Sanderson Design Group anchors designer-led specification through controlled archive access. Greater London commercial refurbishment rates lag German corridors, offering expansion headroom for certified non-woven lines.
Poland
Warsaw and Kraków office refurbishment rates trail western capitals, creating volume expansion opportunity for certified product lines. CSRD-aligned supply chain disclosure requirements will force substrate provenance transparency before the decade closes. Polish commercial contractors prioritize certified non-woven substrates to avoid compliance documentation friction.
Europe Wall Coverings Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue water-based polymer alternatives and digital print-on-demand integration. The vendor base stratifies across coating specialists, textile laminators, and heritage archive licensors. Three archetypes dominate: Benelux-based manufacturing footprint holders, decorative coatings formulators with controlled resin networks, and heritage design houses leveraging archive licensing. Capacity expansion and portfolio diversification toward sustainable substrates represent the dominant competitive moves.
Among Benelux-based manufacturing footprint holders, Grandeco Wallfashion Group and Arte International N.V. exemplify the coating-retooling archetype, while Akzo Nobel N.V. anchors the decorative coatings supply tier through its controlled pigment and resin formulation network. Sanderson Design Group occupies a position within the heritage archive licensing segment, representing the designer-led premium channel. These three entities collectively illustrate the geographic and capability clustering that defines current competitive positioning.
| Leading Market Players |
|---|
| Benjamin Moore & Co. |
| Grandeco Wallfashion Group |
| Akzo Nobel N.V. |
| Sanderson Design Group |
| Osborne & Little Ltd. |
| A.S. Création Tapeten AG |
| Ahlstrom-Munksjö Oyj |
| Walker Greenbank PLC |
| Arte International N.V. |
| Others |
Supply & Pricing Matrix
Water-based polymer retooling across Belgian and Dutch coating lines is compressing production economics while concentrating supply authority in Benelux manufacturing clusters. This dual transformation elevates input costs for reformulated substrates even as it narrows viable supplier pools for German and French commercial contractors demanding pre-certified documentation.
Pricing Analysis
Retailer markup layers separate heritage archive licensing premiums from mass-market vinyl rolls across British residential channels. Three-tier pricing structure across premium, standard, and economy levels sorts by certification grade and installation complexity. Pricing pressure stems from chlor-alkali energy intensity at Antwerp-Rotterdam chemical clusters. Hospitality operators exhibit lowest price sensitivity; Polish office contractors face highest budget constraints.
Supply Chain Analysis
Skilled coating technician shortages in North Rhine-Westphalia and Flanders constrain water-based acrylic-polyurethane hybrid output expansion. Supply concentrates in Belgium, the Netherlands, and Germany. Raw material flows draw from chlor-alkali complexes, synthetic fiber mat producers, and decorative pigment formulators. Single-source vulnerability runs through Benelux retooling transitions. Distribution runs through pan-European logistics hubs serving general contractor procurement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through bio-based polymer substitution premiums offsetting legacy PVC feedstock volatility. Water-based formulation certification investments capture compliance-driven specification shifts.
For Market Incumbents: Cement control over water-based polymer coating capacity in Benelux clusters before ECHA substance restrictions harden. Secure backward integration into synthetic fiber mat supply to defend against single-source vulnerability during regional retooling transitions. Prioritize CSRD-aligned provenance documentation systems as a channel-lock mechanism against emerging coating specialists.
For New Entrants and Emerging Players: EU Green Deal building performance standards in Germany open a window for certified non-woven substrate penetration in Warsaw and Kraków commercial corridors. Target Polish office refurbishment lag with direct-to-contractor distribution bypassing legacy retail layers. Lead with pre-validated REACH compliance documentation to accelerate tender acceptance.
For Investors and Strategic Acquirers: Valuations sit cheapest among heritage archive licensors with undermonetized digital print-on-demand integration. Five-to-ten-year viability favors coating specialists with completed water-based retooling and pan-European distribution density. Monitor ECHA substance restriction enforcement velocity as inflection indicator for bio-based polymer adoption curves.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Polymer Retooling | Belgian coating specialists capture specification share from legacy PVC-dependent supply chains under REACH compliance. |
| Heritage Archive Licensing Expansion | Sanderson Design Group monetizes controlled design access through digital print-on-demand residential platforms. |
| CSRD-Aligned Provenance Systems | Substrate traceability investments create first-mover advantage in upcoming supply chain disclosure mandates. |
| Polish Commercial Corridor Development | Warsaw and Kraków office refurbishment lag offers volume expansion for certified non-woven product lines. |
| Large-Format Non-Woven Capacity Addition | Installation efficiency gains align with compressed hospitality renovation timelines in Frankfurt and Munich. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with coating plant managers, commercial contractor procurement leads, hospitality operator facility directors, and heritage design house licensing executives with secondary validation against ECHA substance restriction databases, EU Green Deal building performance standard filings, customs trade data for vinyl substrate flows, and Benelux chemical cluster production disclosures. Bottom-up volume triangulation against top-down macroeconomic anchors ensured forecast robustness.
Historical reference periods anchored growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include substrate chemistry, application channel, material composition, and procurement authority concentration. CAGRs derived from trend extrapolation calibrated against regulatory compliance cost absorption rates and hospitality asset cycling velocity. Forecast inputs incorporated chlor-alkali energy price sensitivity and water-based polymer adoption curves.
Revisions become necessary when ECHA substance restriction enforcement accelerates, EU Green Deal building renovation targets shift, or CSRD disclosure mandates advance beyond current timelines. Forecasts reflect assumptions about coating line retooling completion rates and contractor certification documentation adoption. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
New Zealand Window Covering Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
Global Decorative Panels Market
Homecare and Decor
United Arab Emirates Interior Design Market
Homecare and Decor
Smart Bed Mattress Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
Frame for Painting Market
Homecare and Decor
Wall Covering and Wall Decor Market
Homecare and Decor
Terracotta Pots Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
Pillow Market
Homecare and Decor
United Kingdom Resilient Floor Covering Market
Homecare and Decor
Bulletin Board Market
Homecare and Decor
Global Wallpaper Market
Homecare and Decor
Asia-Pacific Decorative Laminates Market
Homecare and Decor
Gas Fire Table Market