
 United Kingdom Tumble Dryers Market | 2026-2036
United Kingdom Tumble Dryers Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Tumble Dryers Market Insights
Subscription-based maintenance bundling is pivoting how manufacturers monetize installed bases in the United Kingdom. Beko leverages its Turkish manufacturing scale to occupy the mid-market price band through supermarket and big-box retail partnerships. Miele sustains premium positioning with extended warranty programs and certified technician networks. Hotpoint competes on replacement-cycle speed, anchoring landlord and property management procurement through bulk channel arrangements.
A tumble dryer is a forced-air laundry appliance that removes moisture from textiles via heated air circulation, with drum capacities typically spanning 7-10 kg for domestic units and functional parameters governed by specific energy consumption metrics per kilogram of cotton load. Heat pump variants now dominate structural margin pools, capturing value through refrigerant-based closed-loop drying that cuts energy draw versus vented or condenser architectures. Sensor-based technology leads replacement demand, while smart connectivity remains nascent but growing fastest among new-build residential specifications. The commercial end-user segment shows maturity, with on-premises laundry operations standardizing replacement cycles around seven-year equipment lifespans.
The UK's Ecodesign and Energy Labelling regulations, enforced by the Department for Environment, Food and Rural Affairs alongside BEIS framework compliance, mandate minimum efficiency tiers that progressively disqualify vented dryers from new sales. The Office for Product Safety and Standards further shapes market access through electrical equipment safety certifications and recall protocols. Stakeholders must monitor refrigerant transition timelines under F-Gas Regulation amendments and decide on heat pump compressor supply chain positioning before compliance thresholds tighten.
Market Dynamics
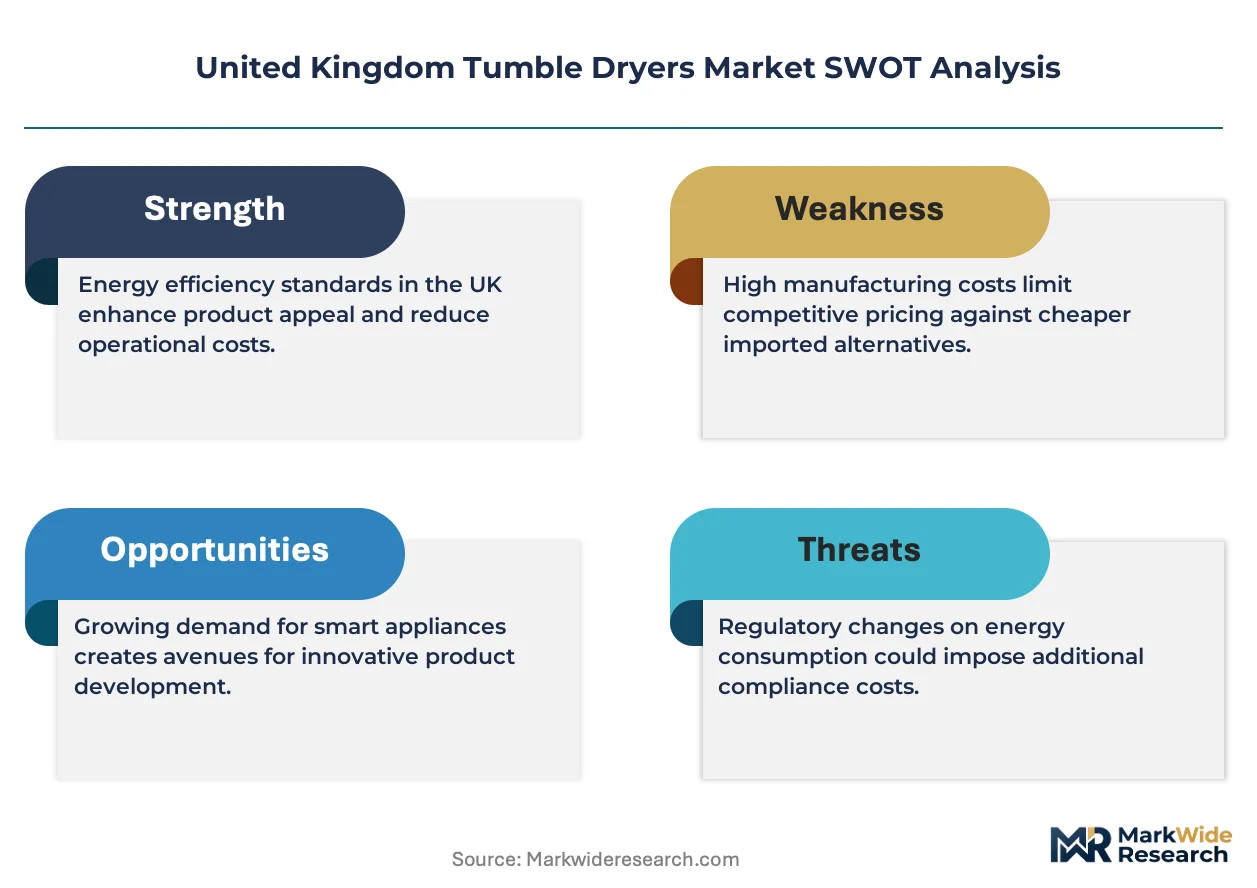
Heat pump technology is restructuring the United Kingdom tumble dryers market as Ecodesign and Energy Labelling regulations progressively disqualify vented models from new sales, forcing manufacturers to reconfigure supply chains around refrigerant-based closed-loop architectures.
Growth Catalysts
- Ecodesign and Energy Labelling regulations:These UK mandates enforce minimum efficiency tiers that accelerate replacement of vented dryers with heat pump variants, expanding addressable market for compliant manufacturers.
- Sensor-based drying technology:Moisture detection systems reduce energy consumption per cycle and command price premiums in residential retrofit applications across England's southeast commuter belt.
- Rental property portfolio expansion:London and Manchester landlords are compressing appliance refresh cycles to meet tenant expectations, creating recurring demand for mid-capacity units.
Market Restraints
- Refrigerant cost volatility:F-Gas Regulation amendments are tightening supply of conventional refrigerants, squeezing margins on heat pump compressor production.
- Supply concentration in compressor manufacturing:Heat pump dryer production depends on a narrow base of European and East Asian compressor suppliers, creating vulnerability to regional disruptions.
- Technical limitation in low-temperature performance:Heat pump variants exhibit extended cycle times for heavy cotton loads, limiting appeal in commercial on-premises laundry operations.
Strategic Opportunities
- Smart connectivity integration:WiFi-enabled diagnostics and remote cycle management are converging with home automation systems, opening premium positioning in new-build residential specifications.
- Subscription-based maintenance bundling:Extended warranty and certified technician networks represent underexploited recurring revenue streams beyond initial equipment sales.
- Scotland and Northern England retrofit penetration:These sub-regions lag southeast England in heat pump adoption, offering whitespace for efficiency-focused replacement campaigns.
Industry Challenges
- Certified technician scarcity:Heat pump refrigerant handling requires F-Gas certification, constraining service network expansion and extending repair lead times.
- Legacy vented dryer inventory liquidation:Retailers and distributors face working capital pressure clearing non-compliant stock before regulatory deadlines.
- Integration complexity with existing ventilation infrastructure:Heat pump installation demands different spatial and electrical specifications than vented replacements, complicating retrofit sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Tumble Dryers Market |
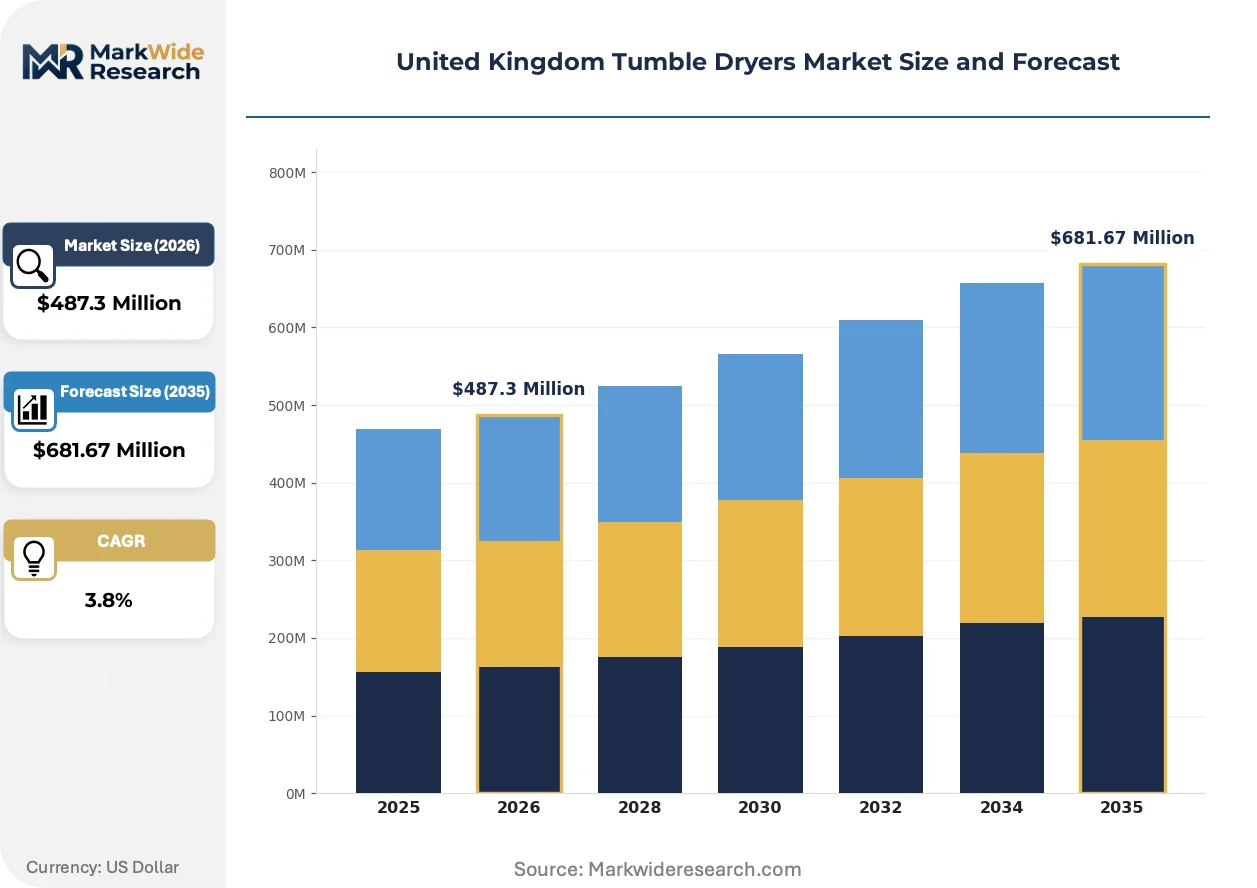
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $681.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vented, Condenser, Heat Pump, Washer Dryer Technology: Smart, Sensor-Based, Traditional, Energy Efficient End User: Residential, Commercial, Institutional, On-Premises Distribution Channel: Online, Retail, Direct Sales, Specialty Stores |
| Companies Covered | Bosch, Whirlpool, Electrolux, Samsung, LG, Beko, Miele, Hotpoint, AEG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Tumble Dryers Market Trends and Innovations
Refrigerant-based closed-loop drying architectures are displacing conventional heating elements across the United Kingdom market, while connectivity features and service model unbundling reshape how value is captured from installed bases.
Heat pump compressors are converging with variable-speed inverter drives to optimize energy draw across load sizes. Buy-to-let landlords in Greater London are adopting these configurations fastest, driven by tenant utility cost concerns and portfolio ESG targets. The technology is converging with smart metering infrastructure, enabling time-of-use optimization that reduces peak grid strain.
The UK's Ecodesign and Energy Labelling regulations, enforced by the Department for Environment, Food and Rural Affairs, are tightening minimum efficiency thresholds on a phased schedule. This policy architecture is compressing the viable product mix toward heat pump variants exclusively. Vented dryer SKUs are disappearing from big-box retail assortments first, with independent electrical channels following.
Tenant-facing procurement is fragmenting traditional retail concentration. Property management platforms and bulk procurement consortia are disintermediating individual consumer purchases in multi-unit residential buildings. This channel shift is most visible in Manchester's purpose-built rental sector, where standardized appliance specifications enable volume pricing and centralized maintenance contracts.
United Kingdom Tumble Dryers Market Segmentation
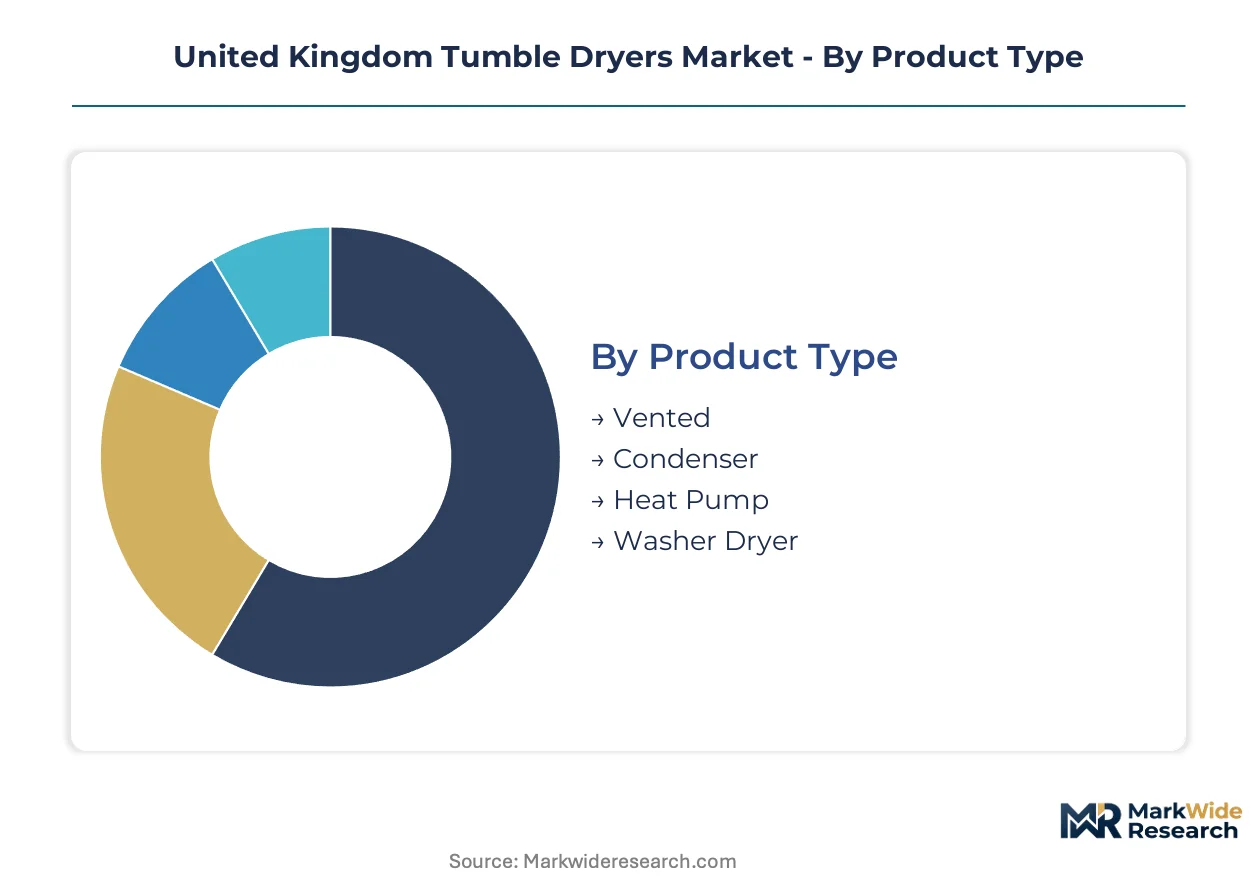
Segmentation in the United Kingdom tumble dryers market reveals how regulatory pressure and procurement channel shifts are fragmenting demand across incompatible technical specifications. Buyers now sort by installation constraints, energy compliance tiers, and service integration requirements rather than simple capacity or price.
Product Type:
Buyers in this category diverge sharply by housing infrastructure and retrofit feasibility, with installation requirements dictating viable options more than brand preference or price sensitivity.
- Heat Pump:Refrigerant-based closed-loop systems recover thermal energy through compressor-driven heat exchange, cutting electricity draw versus resistive heating. Demand concentrates in England's southeast commuter belt where new-build residential specifications and landlord ESG targets align with Part L building regulations. The Department for Environment, Food and Rural Affairs mandates progressively tighten efficiency floors that advantage this architecture.
- Vented:External-duct configurations expel moist hot air through wall or window penetration, requiring dedicated ventilation paths incompatible with many apartment layouts. Inventory liquidation pressure mounts as Ecodesign deadlines approach, with independent electrical channels still clearing residual stock ahead of compliance thresholds.
- Condenser:Self-contained moisture collection via internal reservoir or plumbed drainage suits rental properties lacking external venting options. Manchester's purpose-built rental sector standardizes around these units for installation flexibility.
- Washer Dryer:Combined drum systems sacrifice drying capacity and energy efficiency for spatial economy in compact urban dwellings. London's micro-apartment developments drive specification despite extended cycle times.
Volume sits with Heat Pump; growth tilts toward Washer Dryer in space-constrained urban retrofits.
Technology:
Margin capture in this dimension separates equipment with embedded service revenue potential from commodity replacements lacking connectivity or diagnostic capability.
- Sensor-Based:Moisture detection electrodes or capacitive arrays terminate cycles automatically when residual dampness hits programmed thresholds, preventing over-drying energy waste. Buy-to-let landlords in Greater London prioritize these configurations to reduce tenant utility disputes and protect textile assets.
- Smart:WiFi-enabled units integrate with home automation platforms and utility time-of-use pricing, permitting remote cycle management and predictive maintenance alerts. New-build residential specifications in England's southeast increasingly require this connectivity tier.
- Traditional:Timer-controlled fixed-duration operation without load sensing remains price-accessible but faces regulatory displacement. Scotland and Northern England retrofit markets still absorb these units where upfront cost dominates purchase decisions.
- Energy Efficient:Broad certification tier encompassing multiple technical approaches to reduced consumption per kilogram of cotton load, often bundling inverter-driven compressors with improved drum airflow geometry.
Revenue concentrates with Sensor-Based; Smart connectivity climbs fastest among premium new-build specifications.
End User:
Procurement scale and replacement cycle predictability distinguish buyers here, with institutional contracts offering volume stability against fragmented residential demand.
- Residential:Individual households and family units purchase through retail or online channels with replacement intervals averaging 7-10 years, though London and Manchester rental portfolio expansion compresses refresh cycles.
- Commercial:On-premises laundry operations in hospitality and healthcare standardize equipment around seven-year lifespans with centralized maintenance contracts. Technical limitation in low-temperature performance constrains heat pump penetration here.
- Institutional:University residences, military barracks, and correctional facilities procure through bulk tender processes with standardized specifications and extended warranty requirements.
- On-Premises:Dedicated facility laundry rooms in multi-unit residential buildings, serviced apartment complexes, and corporate housing operate under centralized management with remote monitoring integration.
Unit shipments favor Residential; contract value tilts toward Institutional procurement consolidation.
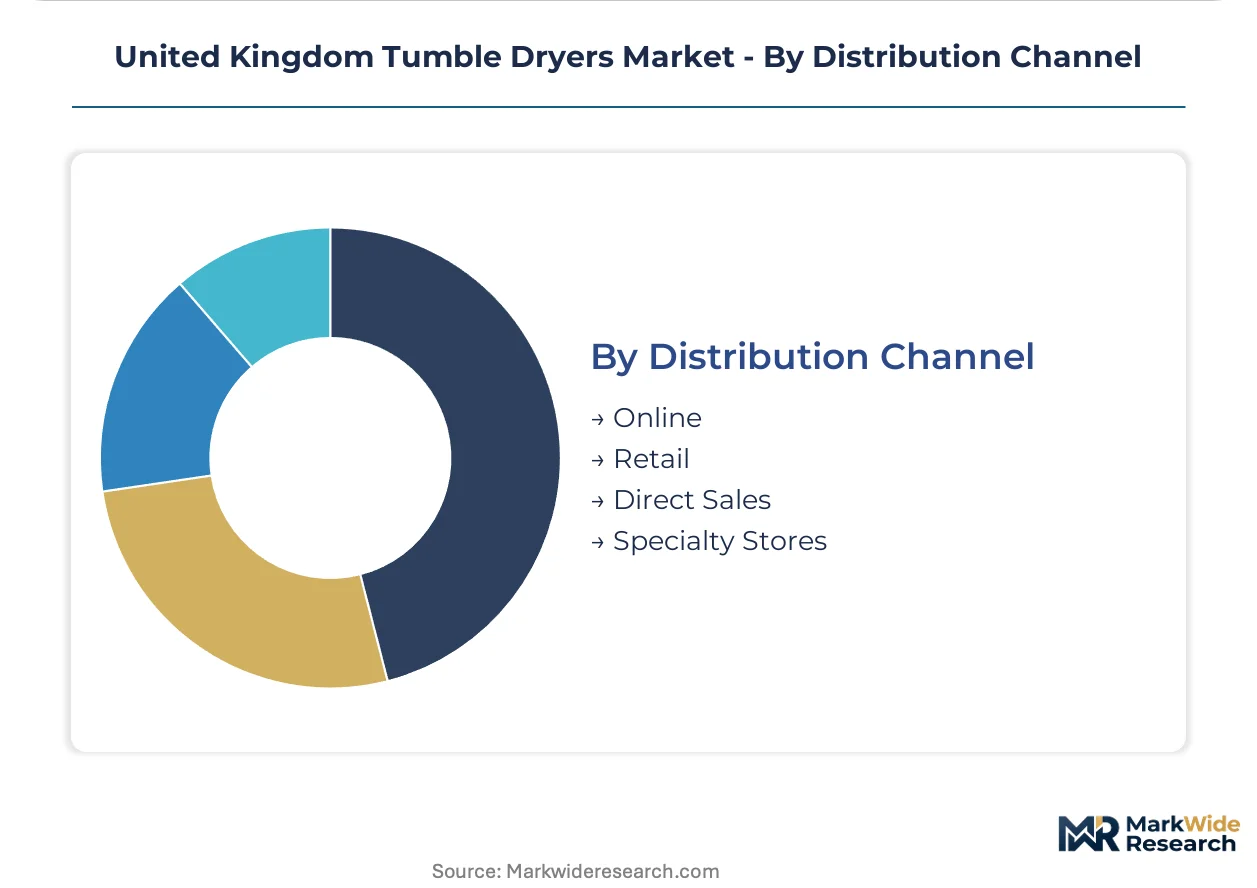
Distribution Channel:
Channel selection reflects buyer urgency, technical support requirements, and integration complexity with existing procurement systems.
- Online:E-commerce platforms capture replacement demand from informed buyers with straightforward installation requirements, though heat pump complexity drives some purchasers toward assisted channels.
- Retail:Big-box and supermarket partnerships anchor mid-market volume, with Beko leveraging Turkish manufacturing scale through these relationships. Vented dryer SKUs are disappearing from retail assortments first.
- Direct Sales:Manufacturer-controlled channels enable extended warranty bundling and certified technician network attachment, supporting Miele's premium positioning with F-Gas-certified service coverage.
- Specialty Stores:Independent electrical retailers retain relevance for retrofit consultations where heat pump installation demands different spatial and electrical specifications than vented replacements.
Transaction volume flows through Retail; margin expansion tilts toward Direct Sales with service attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production capacity in the United Kingdom concentrates on final assembly and component integration rather than compressor manufacturing, creating import dependency for heat pump core technologies. Consumption patterns diverge sharply between England's southeast commuter belt and northern sub-regions, with regulatory deadlines compressing replacement cycles unevenly across geographies.
London and Southeast England
Purpose-built rental developments in Tower Hamlets and Croydon standardize heat pump specifications to meet Part L building regulations and landlord ESG reporting requirements. The Department for Environment, Food and Rural Affairs enforces phased Ecodesign efficiency thresholds that eliminate vented dryer sales from 2026. Buy-to-let portfolio managers in Greater London compress appliance refresh cycles to seven-year intervals, creating recurring procurement demand through property management platforms.
Midlands
Manufacturing heritage in Birmingham and Coventry sustains a base of component suppliers serving domestic assembly operations, though compressor production remains concentrated in Germany and East Asia. BEIS framework compliance mandates shape industrial procurement for on-premises laundry facilities in hospitality clusters. Leicester's textile processing sector maintains residual demand for high-capacity condenser units where heat pump cycle times prove operationally prohibitive.
North England
Manchester's purpose-built rental sector drives standardized appliance specifications through bulk procurement consortia, with centralized maintenance contracts displacing individual retail purchases. Scotland and Northern England retrofit markets lag southeast adoption rates by 18-24 months, preserving demand for traditional timer-controlled units where upfront cost dominates tenant-facing landlord decisions. Yorkshire's independent electrical retail channels retain relevance for heat pump retrofit consultations requiring spatial and electrical specification assessments.
Scotland
Edinburgh and Glasgow residential retrofits exhibit slower heat pump penetration due to housing stock age and installation complexity in tenement buildings with restricted external venting options. The Scottish Government's energy efficiency programs subsidize sensor-based technology upgrades in social housing portfolios. Aberdeen's corporate housing market for energy sector workers standardizes around washer-dryer combinations in compact urban dwellings.
Wales and Northern Ireland
Cardiff and Belfast markets show pronounced price sensitivity in residential replacement cycles, with retail channel concentration in supermarket and big-box partnerships anchoring mid-market volume. Rural housing dispersion in North Wales and County Antrim sustains residual vented dryer inventory liquidation through independent channels ahead of regulatory deadlines. Cross-border supply chain logistics from England-based distribution centers extend delivery lead times for heat pump variants requiring F-Gas-certified installation support.
United Kingdom Tumble Dryers Market Competitive Landscape
Top-tier vendors anchor premium positioning through extended warranty networks and certified technician coverage, while mid-market players compete on manufacturing scale and retail channel penetration. The vendor base spans three strategic tiers: premium specialists with service integration, mass-market manufacturers leveraging offshore production scale, and value-oriented brands targeting replacement-cycle speed. Consolidation pressure operates through portfolio diversification into adjacent laundry categories and geographic expansion via distribution partnerships rather than horizontal merger activity.
Within the premium-service archetype, Miele occupies a position emphasizing technician certification and maintenance bundling. Beko exemplifies scale-driven mid-market positioning through Turkish manufacturing and supermarket retail partnerships. Hotpoint sits within the landlord-focused tier, anchoring property management procurement through bulk channel arrangements and replacement-cycle responsiveness. These three patterns represent the dominant competitive configurations reshaping how value is captured from installed bases across England's rental property corridors.
| Leading Market Players |
|---|
| Bosch |
| Whirlpool |
| Electrolux |
| Samsung |
| LG |
| Beko |
| Miele |
| Hotpoint |
| AEG |
| Others |
Pricing and Supply Chain Analysis
F-Gas-certified technician concentration in Germany and Turkey widens pricing-tier spreads between premium service-bundled and bare-equipment offerings. Labor-cost differentials between these compressor manufacturing hubs and UK installation networks compress margins on mid-market heat pump variants while sustaining premium positioning for certified maintenance coverage.
Pricing Analysis
Margin tightening in the mid-market tier traces to Turkish manufacturing scale flooding supermarket and big-box channels with cost-optimized heat pump units. Three-tier pricing structure across premium, standard, and economy levels separates Miele's technician-network bundling from Beko's retail partnerships and Hotpoint's landlord bulk arrangements. Price differentiation rests on F-Gas certification coverage and sensor-based moisture detection tiers. First-time buyers in Scotland and Northern England exhibit highest price sensitivity; portfolio landlords in Greater London prioritize total cost of ownership over upfront equipment cost.
Supply Chain Analysis
Freight cost volatility from East Asian compressor hubs through Rotterdam and Felixstowe feeds margin pressure across heat pump production networks. Manufacturing concentrates in Turkey, Germany, and China, with refrigerant handling equipment sourcing from Italy and Poland. Raw material dependencies span copper tubing, rare-earth compressor magnets, and synthetic refrigerants subject to F-Gas Regulation phase-down schedules. Single-source vulnerability concentrates in inverter-drive controller semiconductors. Distribution runs through England-based consolidation centers serving retail, direct sales, and property management platform channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat pump compressor supply constraints prop pricing power for manufacturers with captive refrigerant handling capabilities. F-Gas certification bottlenecks limit service network expansion, sustaining premium attachment rates for extended warranty bundling.
For Market Incumbents: Cement technician certification pipelines through partnerships with German and Turkish training institutes before 2026 regulatory thresholds tighten. Defend margin position by backward integration into refrigerant reclamation services, countering emerging entrants with pure equipment plays. Lock bulk procurement relationships with Manchester and London property management platforms to secure replacement-cycle visibility.
For New Entrants and Emerging Players: Smart connectivity integration offers a technology-first wedge into new-build residential specifications where incumbent service networks lack presence. Target Scotland and Northern England retrofit whitespace with simplified installation kits addressing tenement building constraints. Pursue direct-to-landlord digital channels disintermediating traditional retail concentration.
For Investors and Strategic Acquirers: Re-rating potential sits with F-Gas-certified service networks given regulatory compliance thresholds eliminating uncertified competitors. Long-term viability favors platforms combining equipment financing with maintenance subscriptions over pure manufacturing plays. Monitor BEIS framework amendment timelines as inflection signal for compliance-driven replacement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Network Expansion | F-Gas compliance requirements constrain service capacity, advantaging early certifiers. |
| Refrigerant Reclamation Infrastructure | F-Gas Regulation phase-down elevates reclaimed refrigerant cost advantage over virgin supply. |
| Property Management Platform Integration | London and Manchester portfolio standardization enables volume pricing and recurring revenue capture. |
| Sensor-Based Technology Bundling | Moisture detection systems reduce tenant utility disputes and protect textile assets in rental portfolios. |
| Scotland Retrofit Channel Development | Eighteen-month adoption lag versus southeast England offers whitespace for efficiency-focused campaigns. |
Research Methodology
Multi-period observation of Ecodesign compliance transitions, refrigerant price indices, and rental portfolio appliance refresh cycles anchored the trend analysis, supplemented by interviews with heat pump compressor procurement leads, F-Gas certification training providers, London property management platform operators, and independent electrical retail channel owners. Secondary validation drew from BEIS framework compliance filings, Department for Environment, Food and Rural Affairs enforcement bulletins, UK customs trade data, and big-box retail SKU assortment tracking. Bottom-up shipment modeling triangulated against top-down energy efficiency regulation impact assessments.
Segment-weighting across product type, technology tier, end-user procurement scale, and distribution channel structure informed volume and value allocation throughout the forecast period. CAGRs derived from regression analysis of historical replacement cycles against regulatory deadline proximity, with heat pump adoption curves and rental portfolio growth rates as industry-specific demand drivers. Cross-validation against compressor manufacturing capacity announcements and refrigerant supply contract disclosures tested supply-side constraints.
Several conditions sit outside the modeled scope, including unannounced F-Gas Regulation amendment timelines, abrupt refrigerant supply disruptions, and macroeconomic shocks to UK housing transaction volumes. Forecasts reflect documented assumptions about regulatory enforcement consistency and landlord ESG target persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Water Heater Market
Appliances
Smart Washing Machine Market
Appliances
Qatar Dishwashers Market
Appliances
Europe Tumble Dryers Market
Appliances
Electric Kettle Market
Appliances
United States Electric Kettle Market
Appliances
Asia Pacific Water Heater Market
Appliances
Asia-Pacific Washing Machine Market
Appliances
Asia-Pacific Tumble Dryers Market
Appliances
Colombia Laundry Appliances Market
Appliances
Saudi Arabia Electric Water Heater Market
Appliances
US Washing Machine Parts Market
Appliances
GCC Dishwashers Market
Appliances
Asia-Pacific Microwave Oven Market
Appliances
Washing Appliances Market
Appliances
Middle East and Africa Commercial Dishwashers Market