
 Electric Fan Market | 2026-2036
Electric Fan Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Fan Market Insights
Residential construction across tropical climate zones is shifting toward integrated air-circulation systems, pulling demand away from standalone cooling units. Midea Group leverages its Guangdong manufacturing base to dominate mass-market ceiling fan exports. Havells India anchors its position through backward integration into copper winding and motor lamination operations. Panasonic Holdings differentiates through sensor-enabled smart fan platforms targeting Japanese and South Korean apartment retrofits.
An electric fan is a rotary bladed device driven by an electric motor that displaces air for thermal comfort, ventilation, or industrial process cooling, with blade diameters ranging from 12 inches for personal units to 60 inches for commercial ceiling installations and power consumption spanning 15W for DC motor models to 75W for conventional AC induction designs. Ceiling fans occupy the largest volume share due to their ubiquity in residential and light commercial spaces across warm-climate economies. Smart fans represent the fastest-expanding technology segment as Wi-Fi connectivity and voice-control integration command retail price premiums. Energy-efficient fans concentrate margin pools where brushless DC motors and aerodynamic blade geometries meet tightening minimum energy performance standards.
India's Bureau of Indian Standards enforces mandatory star-labeling for ceiling fans under its appliance efficiency program, compelling domestic manufacturers to redesign motor architectures. The EU Ecodesign Directive and F-Gas Regulation indirectly steer demand toward high-efficiency air-circulation equipment as buildings reduce mechanical cooling loads. China's GB standards for household electrical appliances set minimum motor efficiency tiers that shape export manufacturing specifications. Stakeholders must monitor how fragmented national efficiency regimes fragment product platform strategies and whether modular motor designs can bridge compliance gaps across regulatory jurisdictions.
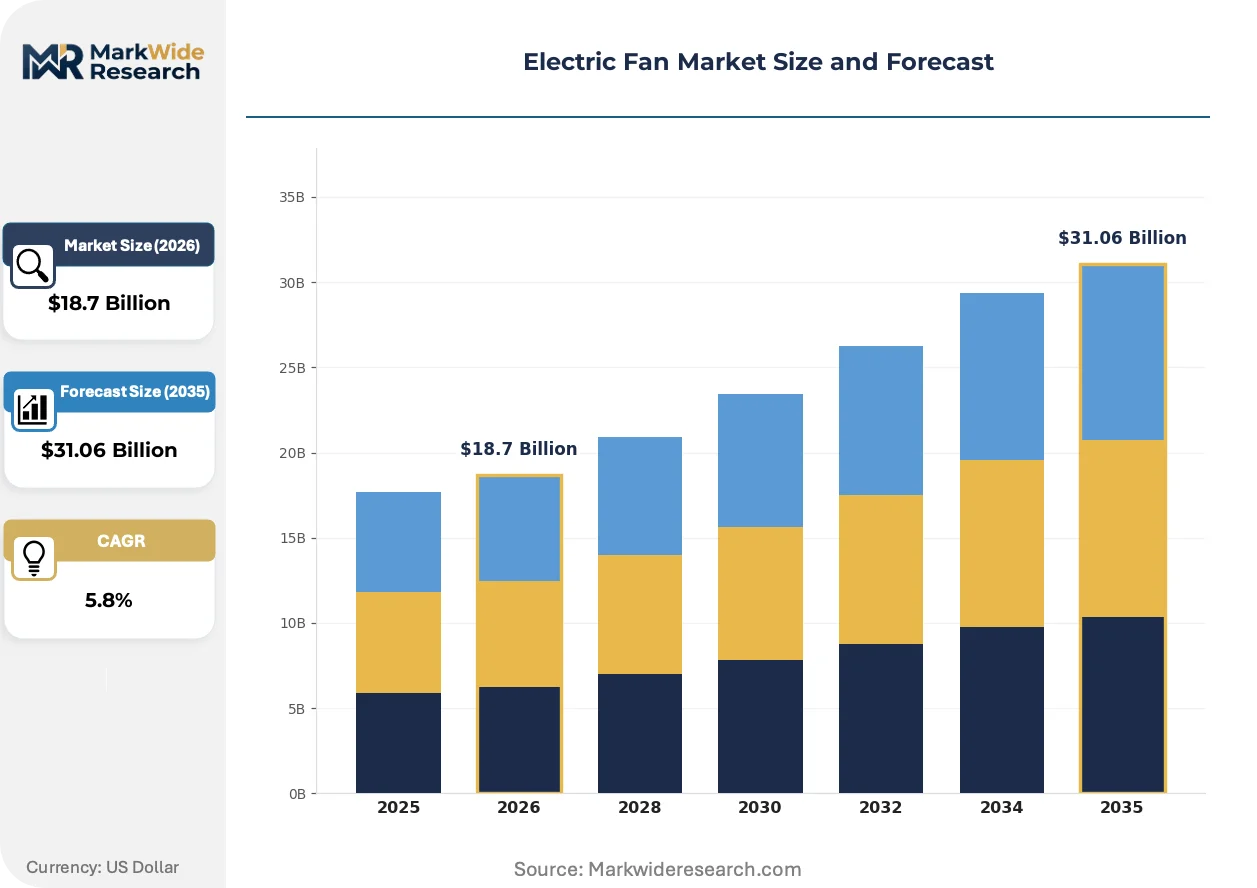
Market Dynamics
The electric fan market is undergoing a fundamental restructuring as brushless DC motor architectures replace AC induction designs under pressure from national efficiency mandates. This technology transition is compressing legacy supply chains while opening margin pools for manufacturers that can deliver modular motor platforms compliant across fragmented regulatory jurisdictions.
Growth Catalysts
- India's BIS star-labeling mandates:The Bureau of Indian Standards enforces mandatory energy-efficiency grades for ceiling fans, compelling domestic manufacturers to redesign motor architectures and accelerating replacement cycles in the world's largest ceiling fan market.
- Southeast Asian apartment construction:Residential cooling adoption is accelerating across Vietnam, Indonesia, and the Philippines as urbanization drives integrated air-circulation system specifications in new high-rise developments.
- Wi-Fi connectivity integration:Smart fan platforms with voice-control compatibility command retail price premiums in Japanese and South Korean apartment retrofits, expanding the addressable market for sensor-enabled products.
Market Restraints
- Copper and rare-earth magnet cost volatility:Brushless DC motors depend on neodymium magnet supply concentrated in Chinese processing facilities, exposing manufacturers to input price swings that compress gross margins.
- Legacy AC motor inventory overhang:Distributors and retailers in South Asian markets hold substantial stocks of conventional induction-motor fans that resist discounting, slowing the transition to higher-efficiency platforms.
- Mechanical cooling substitution:Mini-split air conditioning units are penetrating middle-income households in Vietnam and Thailand, displacing ceiling fans as primary thermal comfort solutions in new construction.
Strategic Opportunities
- Rural electrification corridors in sub-Saharan Africa:Off-grid solar home system deployments create first-time demand for low-wattage DC fans, opening white space for manufacturers with 12V-24V product lines.
- EU F-Gas Regulation tailwinds:Building codes across Germany, France, and Italy are reducing mechanical cooling loads, steering demand toward high-efficiency air-circulation equipment as primary thermal management.
- Direct-to-installer channel development:Electrical contractors in North American renovation markets are bypassing traditional retail, creating margin capture opportunities for brands with trade-exclusive product lines and training programs.
Industry Challenges
- Embedded software engineering scarcity:Smart fan development requires firmware talent for sensor integration and cloud connectivity, a capability gap constraining product roadmap execution at mid-tier manufacturers.
- Multi-jurisdictional certification timelines:UL, CE, and BIS testing sequences for new motor platforms extend 14-18 months, delaying revenue recognition and freezing engineering resources across product generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Fan Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceiling Fans, Table Fans, Floor Fans, Exhaust Fans Technology: Smart Fans, Energy-Efficient Fans, Conventional Fans, Solar-Powered Fans End User: Residential, Commercial, Industrial, Institutional Distribution Channel: Online Retailers, Specialty Stores, Wholesale Distribution, Direct Sales |
| Companies Covered | Midea Group, Haier Smart Home, Panasonic Holdings, Crompton Greaves Consumer Electricals, Havells India, Orient Electric, Hunter Fan Company, LG Electronics, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Fan Market Trends and Innovations
Product architecture is converging around intelligent motor control and aerodynamic blade geometries. Three forces are reshaping competitive positioning: electrification of motor platforms, tightening efficiency regulations, and channel fragmentation between retail and professional installation markets.
Brushless DC motor technology is electrifying the residential fan segment by enabling precise speed control and 60-70% energy reduction versus AC induction designs. Japanese and South Korean apartment developers are specifying these platforms as standard in premium retrofits. The technology is compressing the addressable market for conventional motor suppliers while expanding margin pools for semiconductor and magnet suppliers.
The EU Ecodesign Directive and F-Gas Regulation are restructuring product specifications across European markets by limiting mechanical cooling capacity in new buildings. Manufacturers serving Germany, France, and Italy are re-engineering blade geometries and motor efficiencies to qualify for green building certification schemes. The commercial ceiling fan segment is responding fastest, with specification-grade products now required to demonstrate lifecycle energy performance.
Professional electrical contractors in North American renovation markets are consolidating purchase authority previously held by retail consumers. Big-box distributors are losing specification influence to trade-focused suppliers with dedicated contractor programs and same-day fulfillment capabilities. This channel rotation is most visible in California and Texas metro markets where renovation permit volumes exceed new construction.
Electric Fan Market Segmentation
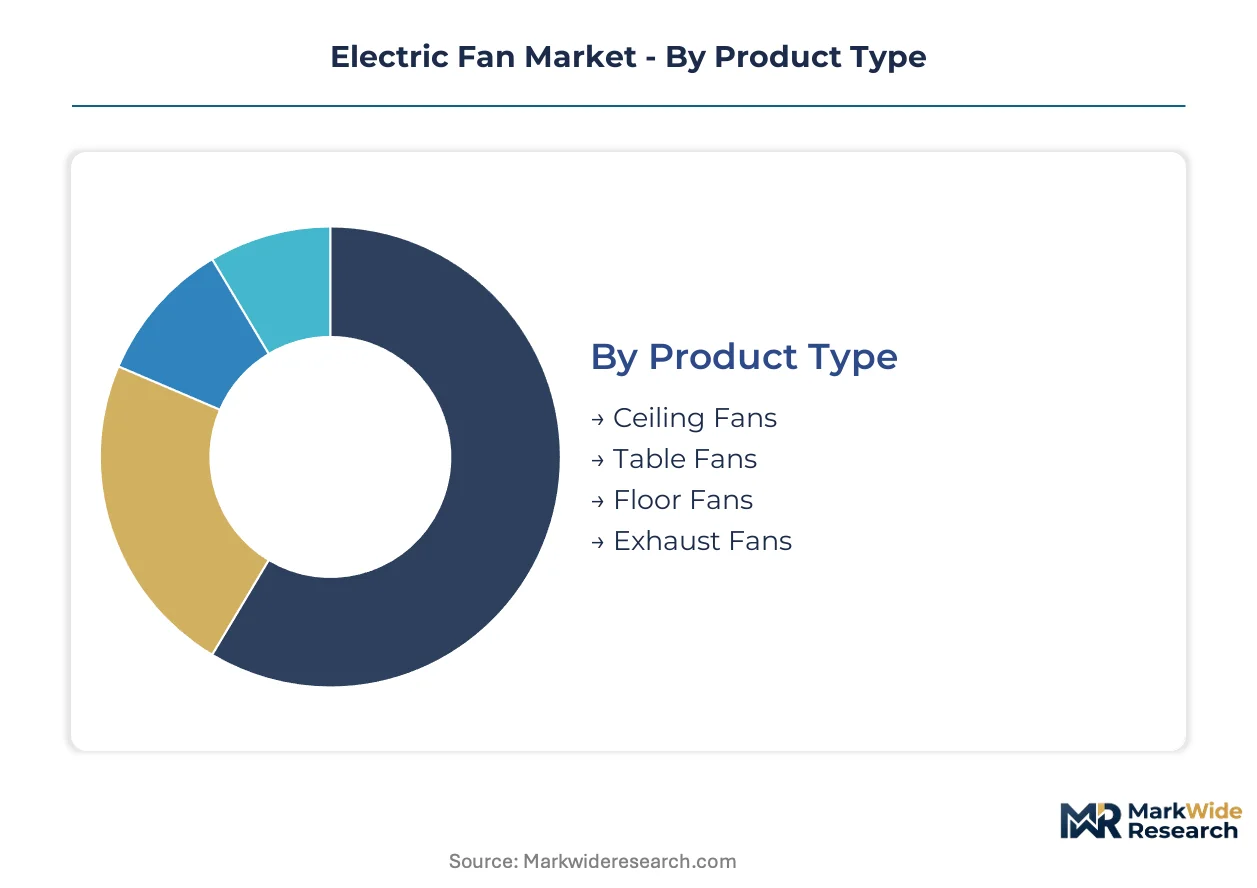
Product segmentation in the electric fan market reveals distinct upgrade cycles across motor technologies and distribution channels. Replacement demand concentrates where efficiency mandates accelerate obsolescence of legacy AC induction platforms.
Product Type:
Upgrade cycles vary dramatically by mounting configuration and installation complexity, with hardwired products commanding longer replacement horizons than portable units.
- Ceiling Fans:Hardwired installations with 12-inch to 60-inch blade spans dominate residential thermal comfort across tropical and subtropical climates. India's BIS star-labeling mandates are compressing replacement cycles for conventional induction-motor units in the world's largest ceiling fan market.
- Table Fans:Portable 12-inch to 16-inch units with oscillating heads serve localized cooling needs in offices and small residential spaces. Demand concentrates in Southeast Asian urban rental markets where tenants prioritize mobility over permanent installation.
- Floor Fans:Pedestal and tower configurations with adjustable height mechanisms target flexible air circulation in commercial lobbies and residential common areas. These units face substitution pressure from mini-split air conditioning in Vietnam and Thailand middle-income households.
- Exhaust Fans:Wall-mounted and window-insertion units engineered for moisture and fume extraction in kitchens and bathrooms. Specifications tighten where building codes mandate mechanical ventilation in high-rise construction across the Philippines and Indonesia.
Ceiling fans sit at the top of the volume ranking, with smart-enabled platforms climbing the fastest as Wi-Fi integration commands retail price premiums.
Technology:
Cost-tier stratification separates premium brushless DC platforms from mass-market AC induction designs, with regulatory compliance costs widening the gap.
- Smart Fans:Wi-Fi-enabled platforms with voice-control compatibility and sensor-driven automation target Japanese and South Korean apartment retrofits. Firmware development requirements constrain mid-tier manufacturers lacking embedded software engineering capabilities.
- Energy-Efficient Fans:Brushless DC motor architectures delivering 60-70% consumption reduction versus conventional designs. EU Ecodesign Directive compliance and India's BIS mandates are accelerating specification-grade procurement in Germany, France, and Italy.
- Conventional Fans:AC induction motor platforms with fixed-speed operation and copper-wound stators. Distributor inventory overhang in South Asian markets resists discounting, slowing transition to higher-efficiency alternatives.
- Solar-Powered Fans:12V-24V DC units designed for off-grid solar home system integration in sub-Saharan Africa rural electrification corridors. Low-wattage requirements align with small-scale photovoltaic deployment capacities.
Energy-efficient fans capture the steepest expansion trajectory as multi-jurisdictional efficiency mandates force motor architecture redesigns.
End User:
Application-specific performance requirements create divergent procurement patterns across installation permanence and duty-cycle intensity.
- Residential:Single-family and multi-unit dwellings specifying thermal comfort and air circulation for living spaces. New apartment construction across Vietnam, Indonesia, and the Philippines is integrating ceiling fans as standard equipment.
- Commercial:Retail, hospitality, and office environments requiring continuous operation and aesthetic integration. Specification-grade products in this segment must demonstrate lifecycle energy performance under EU green building certification schemes.
- Industrial:High-velocity air circulation for process cooling, ventilation, and personnel comfort in manufacturing facilities. Duty-cycle intensity demands robust motor construction and extended warranty terms.
- Institutional:Schools, healthcare facilities, and government buildings with procurement governed by public tender processes. Energy efficiency ratings carry weighted scoring in competitive bidding across Indian state-level purchases.
Residential commands the dominant volume position, with commercial applications gaining share fastest as renovation markets professionalize procurement through electrical contractors.
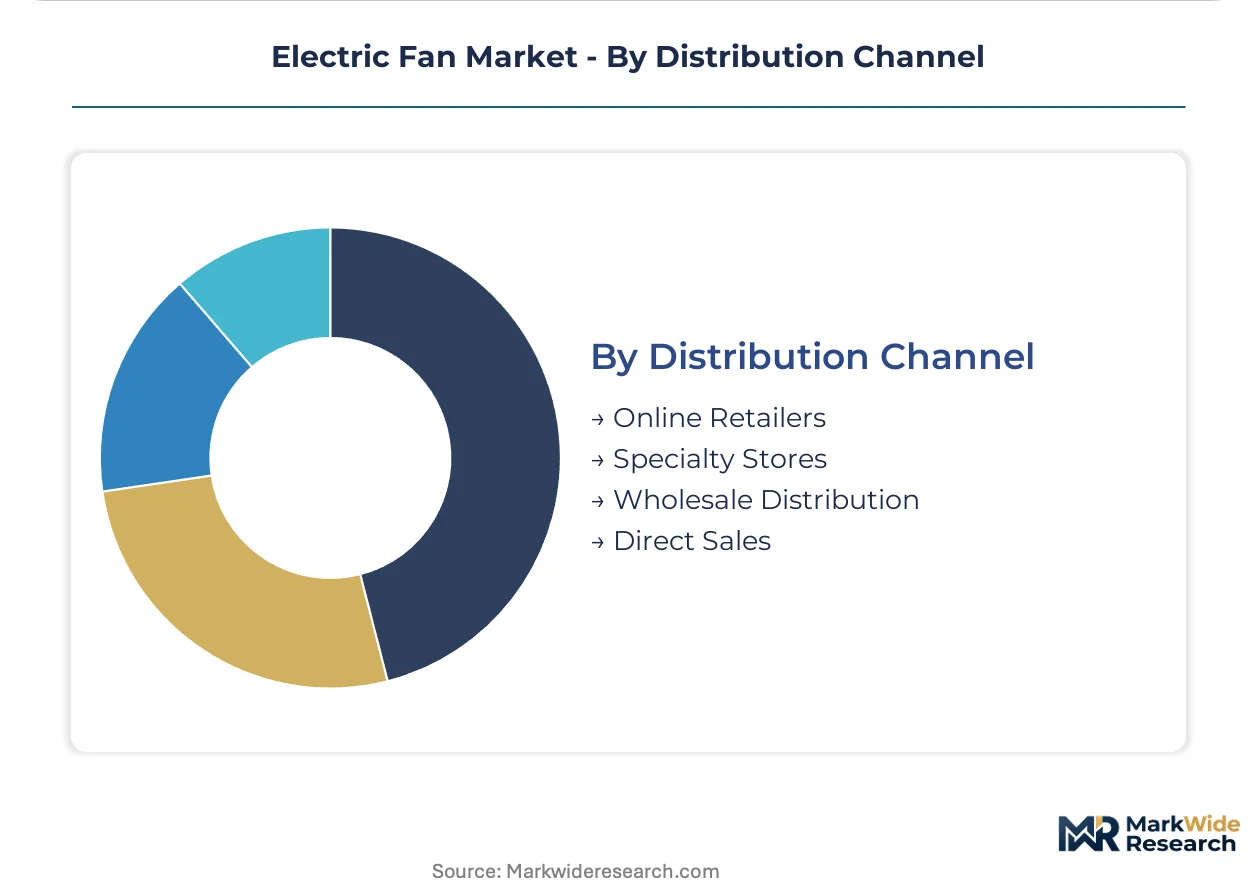
Distribution Channel:
Channel fragmentation between retail and professional installation markets is reshaping margin capture and brand access strategies.
- Online Retailers:E-commerce platforms with direct-to-consumer fulfillment and comparison-shopping interfaces. These channels expand access to smart fan platforms with voice-control compatibility in Japanese and South Korean urban markets.
- Specialty Stores:Dedicated appliance and home improvement retailers with in-store demonstration capabilities. Staff expertise influences upgrade decisions toward brushless DC platforms where efficiency premiums require explanation.
- Wholesale Distribution:Bulk procurement channels serving electrical contractors and project developers with trade pricing structures. Same-day fulfillment capabilities are consolidating purchase authority in California and Texas renovation markets.
- Direct Sales:Manufacturer-to-installer relationships bypassing traditional retail markup for large-scale commercial and institutional projects. Training programs and specification support differentiate competing motor platform offerings.
Wholesale distribution anchors the highest transaction volumes, with direct sales channels expanding most quickly as contractor consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing migration toward lower-compliance-cost jurisdictions is redrawing production maps as efficiency mandates widen cost-of-compliance gaps between regulatory regimes. Vietnam's export corridor absorbs capacity seeking BIS-equivalent standards without India's domestic-market obligations.
India
Ceiling fan replacement cycles compress under BIS star-labeling mandates that force motor architecture redesigns across the world's largest installed base. The Bureau of Indian Standards enforcement accelerates obsolescence of conventional induction-motor inventory held by distributors in Gujarat and Maharashtra manufacturing clusters.
Vietnam
Export-oriented production scales for North American and European retail channels from manufacturing corridors around Ho Chi Minh City and Hanoi. The country's cost-positioned assembly base captures orders from brands seeking CE and UL certification without EU or US domestic-market regulatory overhead.
China
Guangdong province anchors mass-market ceiling fan exports through integrated motor and blade manufacturing ecosystems. GB standards for household electrical appliances set minimum motor efficiency tiers that shape specifications for production bound for Southeast Asian and African markets.
Japan
Sensor-enabled smart fan platforms target apartment retrofits in Tokyo and Osaka metro areas where METI efficiency guidelines and aging building stock converge. Voice-control integration commands retail price premiums as electrical contractors specify connected systems in renovation projects.
Germany
EU Ecodesign Directive compliance and F-Gas Regulation implementation steer commercial building specifications toward high-efficiency air-circulation equipment in Frankfurt and Munich development corridors. Green building certification schemes now require demonstrated lifecycle energy performance for ceiling fan procurement.
Electric Fan Market Competitive Landscape
Backward integration into motor core components dominates the current landscape as manufacturers seek margin defense against copper and magnet cost volatility. The vendor base stratifies across three tiers: diversified appliance conglomerates with captive component production, electrical specialists with winding and lamination capabilities, and contract assemblers dependent on outsourced motor platforms. Two strategic archetypes command attention: integrated manufacturers controlling upstream magnet and copper supply, and specification-grade brands capturing renovation-market premiums through contractor-direct channels. Competitive intensity concentrates around capacity expansion in Vietnam's export corridor and technology licensing for brushless DC motor platforms.
Within the diversified conglomerate tier, Midea Group and Haier Smart Home exemplify scale-driven manufacturing anchored in Guangdong province production ecosystems. Panasonic Holdings occupies a position representing premium-tier sensor-enabled platforms targeting developed-market retrofits. Among India-based electrical specialists, Havells India and Orient Electric exemplify backward integration strategies into copper winding and motor lamination operations that defend margin positions under BIS efficiency mandates. Crompton Greaves Consumer Electricals sits within the same archetype, representing domestic-market-focused manufacturers compelled by regulatory pressure toward motor architecture redesign.
| Leading Market Players |
|---|
| Midea Group |
| Haier Smart Home |
| Panasonic Holdings |
| Crompton Greaves Consumer Electricals |
| Havells India |
| Orient Electric |
| Hunter Fan Company |
| LG Electronics |
| Emerson Electric |
| Others |
Pricing and Supply Chain Analysis
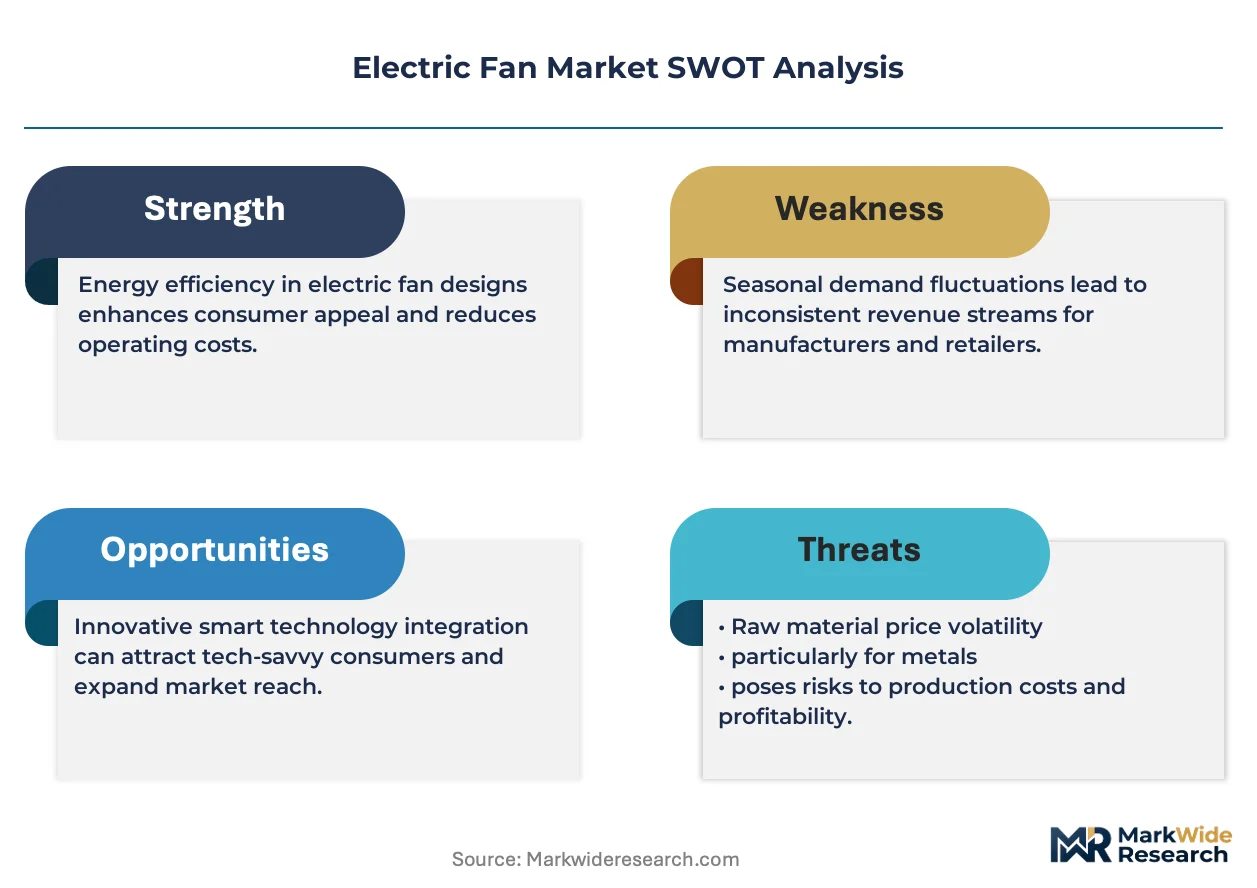
India's BIS star-labeling mandates for ceiling fans are forcing manufacturers to absorb redesign costs for brushless DC motor platforms, compressing margins on mass-market units while creating premium capture opportunities for compliant producers. This specification shift concentrates pricing power with integrated manufacturers controlling upstream magnet and copper supply.
Pricing Analysis
Distributor margins in South Asian markets absorb the steepest compression as legacy AC induction inventory resists discounting against higher-efficiency alternatives. Pricing stratifies across premium smart-enabled platforms, standard BIS-compliant brushless DC units, and economy-tier conventional designs, with certification grade and volume scale driving differentiation. Cost compression in mass-market segments intensifies because neodymium magnet supply concentrates in Chinese processing facilities. Institutional buyers in Indian state-level tenders exhibit lowest price sensitivity due to weighted energy-efficiency scoring, while Southeast Asian rental markets demonstrate highest sensitivity to unit cost.
Supply Chain Analysis
Certification timelines for UL, CE, and BIS testing extend 14-18 months, gating market access and freezing engineering resources across product generations. Manufacturing concentrates in China, Vietnam, and India, with Guangdong province anchoring integrated motor-blade ecosystems and Vietnam's export corridor scaling for North American and European retail channels. Raw material dependencies center on copper windings, neodymium rare-earth magnets, and silicon steel laminations. Single-source vulnerability in Chinese magnet processing exposes margin volatility. Distribution runs through wholesale channels serving electrical contractors, with direct-to-installer models gaining share in North American renovation markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Vietnam's export corridor captures orders seeking CE and UL certification without India's domestic BIS compliance overhead, exploiting a regulatory cost differential that widens margin capture for export-oriented assemblers.
For Market Incumbents: Lock in backward integration into copper winding and motor lamination operations to defend margin positions against neodymium price volatility. Prioritize capacity addition in Vietnam's manufacturing corridor to serve North American and European retail channels while maintaining BIS-compliant production lines for India's replacement cycle acceleration. Certification investment in multi-jurisdictional motor platforms bridges fragmented efficiency regimes. For New Entrants and Emerging Players: Rural electrical contractors in sub-Saharan Africa's solar home system corridors represent an underserved buyer archetype with first-time demand for 12V-24V DC fans. Off-grid deployment partnerships with photovoltaic integrators offer the most penetrable entry path. Specification-grade commercial retrofits in EU markets present secondary white space where green building certification creates procurement preference for lifecycle-documented products. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier manufacturers possessing brushless DC motor platforms but lacking embedded software engineering capabilities for smart fan development. Long-term viability favors targets with demonstrated multi-jurisdictional certification execution and captive magnet supply relationships. Watch for inflection when Indian distributor inventory overhang clears and BIS-compliant replacement demand accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Cores | Captive copper winding and lamination operations defend margins against BIS compliance cost absorption. |
| Vietnam Export Corridor Expansion | CE and UL-certified production scales for North American and European retail without India's domestic regulatory overhead. |
| Smart Fan Platform Development | Wi-Fi connectivity and voice-control integration command retail price premiums in Japanese and South Korean apartment retrofits. |
| Direct-to-Installer Channel Development | Electrical contractors in California and Texas renovation markets consolidate purchase authority previously held by retail consumers. |
| Multi-Jurisdictional Certification Investment | Modular motor designs bridge compliance gaps across India's BIS, EU Ecodesign, and North American UL regimes. |
Research Methodology
Multiple input streams — primary interviews with motor manufacturing executives, electrical contractor procurement leads, and regulatory affairs specialists at certification bodies, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured perspectives from product development directors at integrated appliance conglomerates, category buyers at North American big-box distributors, and state-level tender officials in Indian institutional procurement. Secondary sources included BIS notification records, EU Ecodesign Directive implementation documents, UL certification databases, and customs trade data for fan motor and component flows.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation modeled by motor technology platform, mounting configuration, distribution channel, and end-use application intensity. CAGRs were derived from installed base replacement cycle analysis and new construction penetration assumptions. Industry-specific forecast inputs incorporated BIS star-labeling compliance timelines, EU F-Gas Regulation building code adoption curves, and solar home system deployment trajectories in sub-Saharan Africa.
Underlying measurement precision varies by segment; smart-enabled platforms and BIS-compliant brushless DC categories carry tighter precision than conventional AC induction inventory overhangs in South Asian distributor channels. Forecasts reflect assumptions regarding regulatory enforcement consistency and magnet supply chain stability. A model refresh is warranted upon material change in Indian distributor inventory clearance rates or Chinese rare-earth export policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Saudi Arabia Water Heater Market
Appliances
GCC Dishwashers Market
Appliances
Domestic Food Preparation Appliances Market
Appliances
Wall Oven Market
Appliances
Middle East and Africa Commercial Dishwashers Market
Appliances
Clothing Iron Market
Appliances
Middle East Water Heater Market
Appliances
Saudi Arabia Gas Hobs Market
Appliances
Bahrain Microwave Ovens Market
Appliances
Garments Steamer Market
Appliances
Induction Cooktops Market
Appliances
Minibar Refrigerators Market
Appliances
Household Vacuum Cleaners Market
Appliances
Europe Tumble Dryers Market
Appliances
Mexico Laundry Appliances Market
Appliances
Refrigerator Door Seal Market