
 Europe Swimming Pools and Spas Market | 2026-2036
Europe Swimming Pools and Spas Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Swimming Pools and Spas Market Analysis
Composite fiberglass is restructuring shell economics across the European pool industry, trimming installation timelines and reducing long-term maintenance burdens for property owners. Fluidra S.A. leverages its pan-European distribution network to dominate commercial project channels. Pentair Plc sustains technology leadership in variable-speed pump systems. Jacuzzi Brands LLC specializes in hydrotherapy configurations for the premium residential segment.
Europe swimming pools and spas encompass engineered water-retention structures built from concrete, vinyl, fiberglass, or steel, designed for recreational immersion, hydrotherapy, or athletic training with integrated filtration, heating, and water-treatment subsystems. The primary purpose spans private leisure, hospitality amenity provision, and public health infrastructure across municipal and institutional settings. In-ground pools anchor the value pool given higher per-unit spend and permanence, while above-ground variants compete on accessibility for cost-sensitive residential buyers. Spas and hot tubs occupy a distinct margin tier driven by wellness-oriented consumers seeking compact hydrotherapy solutions.
The EU F-Gas Regulation and Ecodesign Directive constrain refrigerant choices and minimum efficiency thresholds for pool heating equipment, compelling manufacturers to redesign thermal systems. REACH compliance governs chemical treatment formulations and liner material composition, shaping supplier qualification criteria across member states. CE marking requirements for electrical and mechanical components filter market access for non-compliant imports. Stakeholders must monitor upcoming revisions to EU energy-labeling frameworks and assess how circular-economy mandates for material recovery will alter shell replacement cycles and aftermarket service models.
Market Dynamics
EU energy-efficiency mandates for pool heating equipment are compressing installation timelines and forcing rapid technology substitution across member states. Residential and commercial buyers now face mandatory heat pump adoption where gas-fired systems once dominated.
Growth Catalysts
- F-Gas Regulation phase-down:Restrictions on high-GWP refrigerants accelerate heat pump R&D investment and create compliant product differentiation for pool heating manufacturers.
- Mediterranean municipal upgrades:Coastal municipalities in Spain, France, and Italy are replacing aging aquatic infrastructure with energy-efficient filtration and circulation systems.
- Composite fiberglass shells:Reduced installation labor and 30-year service life expectations shift homeowner preferences away from concrete and vinyl alternatives.
Market Restraints
- Copper and polymer input volatility:Heat exchanger materials and pool liner polymers face commodity price swings that compress OEM margins on fixed-price municipal contracts.
- CE marking compliance costs:Electrical and mechanical component certification creates market access barriers for non-EU suppliers without established conformity assessment partnerships.
- Above-ground pool substitution:Cost-sensitive residential buyers in Eastern Europe opt for temporary structures rather than permanent in-ground installations.
Strategic Opportunities
- Poland and Czech Republic residential penetration:Pool ownership rates below 5% in these markets create first-mover advantages for fiberglass shell distributors establishing local installation networks.
- Heat pump-solar thermal hybrid systems:Convergence of air-source heat pumps with rooftop solar thermal collectors addresses peak-load heating demand in Nordic climates.
- EU Green Deal renovation subsidies:National recovery funds for building efficiency retrofits now cover pool equipment upgrades in France and Germany.
Industry Challenges
- Heat pump technician certification gaps:Refrigeration handling qualifications required under F-Gas Regulation outpace vocational training program expansion in Southern Europe.
- Legacy gas-fired infrastructure replacement:Existing pool heating systems require electrical panel upgrades and heat loss calculations that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Swimming Pools and Spas Market |
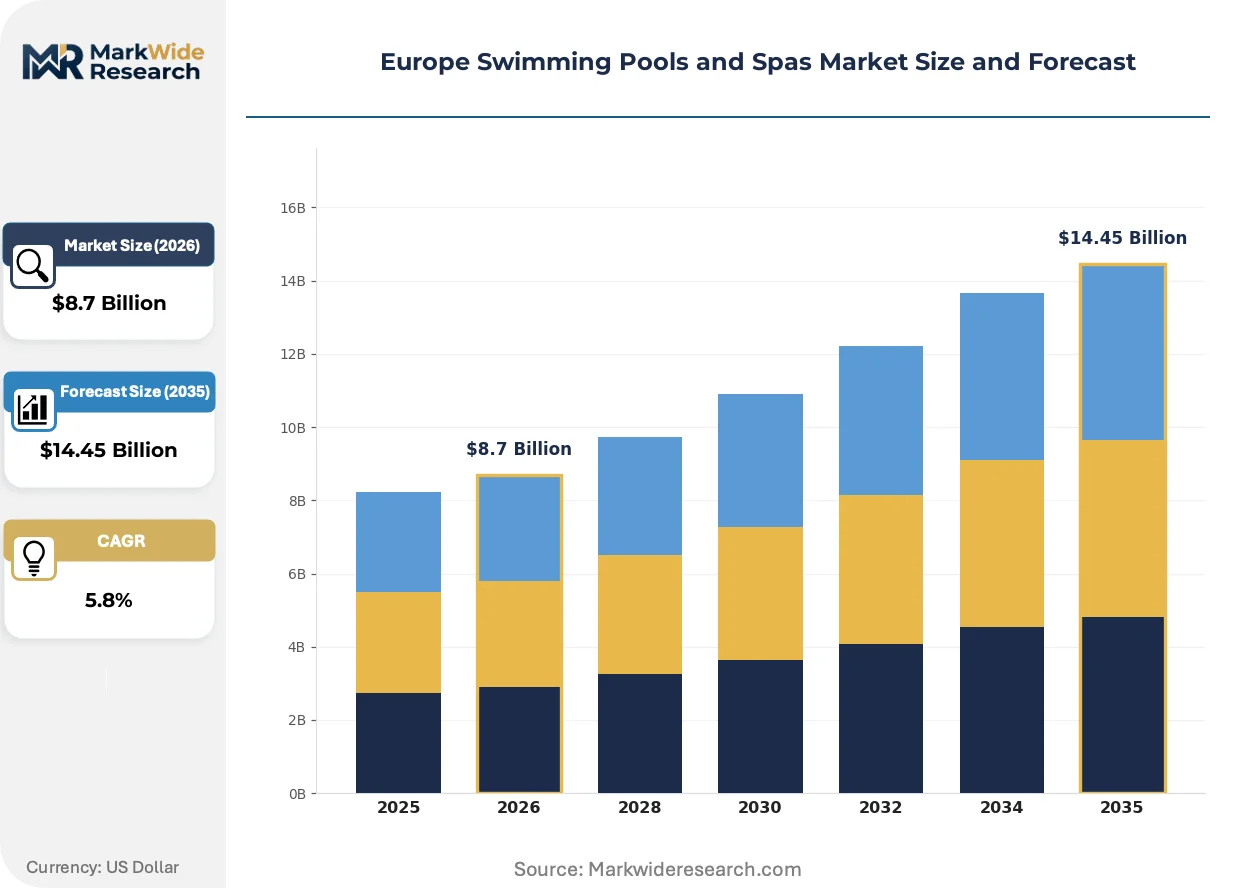
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-ground Pools, Above-ground Pools, Spas, Hot Tubs Material: Concrete, Vinyl, Fiberglass, Steel End User: Residential, Commercial, Hotels, Municipalities Design Type: Modern, Traditional, Custom, Eco-friendly |
| Companies Covered | Bullfrog International LC, Villeroy & Boch AG, Fluidra S.A., Myrtha Pools, Kohler Co., Pentair Plc, Hayward Holdings, Inc., AKVO Spiralift Inc, Jacuzzi Brands LLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Swimming Pools and Spas Market Emerging Trajectories
Digital control systems and predictive maintenance platforms are redefining how pool operators manage energy consumption and water chemistry. Equipment manufacturers now compete on software integration rather than hardware specifications alone.
Variable-speed pump technology is consolidating market share across both residential and commercial installations. Aquatic facility managers in Germany and France specify these units for municipal projects to meet Ecodesign Directive minimum efficiency thresholds. The technology is consolidating supplier margins by reducing aftermarket parts demand and extending replacement cycles.
REACH compliance protocols now govern chemical treatment formulations and liner material composition across all EU member states. Manufacturers reformulate sanitizers and algaecides to eliminate restricted substances, forcing reformulation investments that smaller chemical suppliers cannot absorb. Pool service companies in Italy and Spain face extended supplier qualification timelines as they verify substance registration status.
Direct-to-consumer configuration tools are displacing traditional dealer-led sales processes for residential pool projects. Online platforms allow French and German homeowners to specify shell dimensions, heating systems, and filtration packages before contractor engagement. This shift concentrates demand among manufacturers with robust digital product configurators and compresses margins for distributors without value-added installation services.
Europe Swimming Pools and Spas Market Segmentation
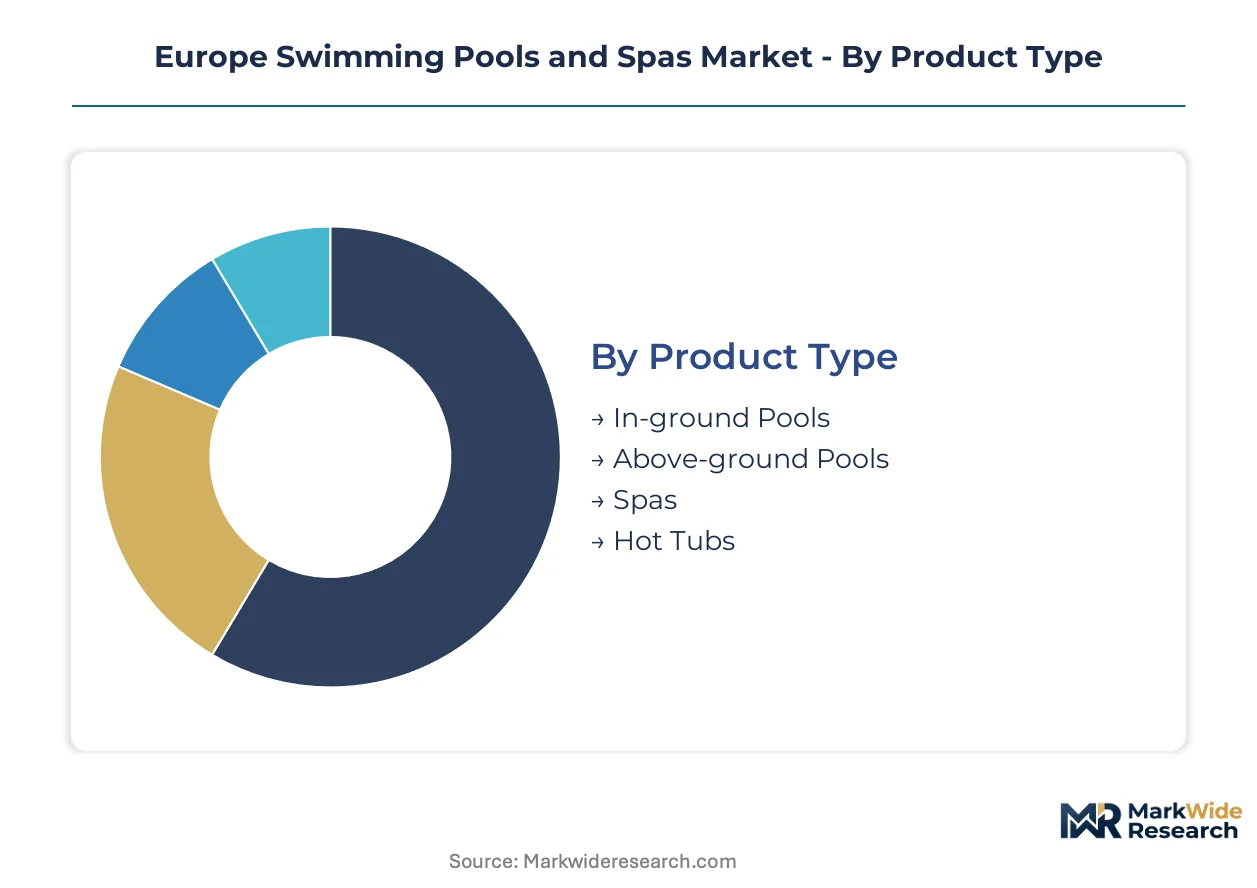
Segmentation in the European pools and spas market reveals divergent buyer priorities across installation permanence, material durability, and end-use application. Each category carries distinct margin profiles and regulatory exposure that shape supplier positioning.
Product Type:
Buyers in this category separate by capital commitment and installation permanence, with permanent structures commanding premium pricing and temporary solutions competing on accessibility.
- In-ground Pools:Permanent excavated structures with reinforced concrete, fiberglass, or vinyl composite shells. Residential installations in France and Germany concentrate here, driven by property value appreciation and EU Green Deal renovation subsidies covering heat pump upgrades.
- Above-ground Pools:Modular steel or resin-frame systems with liner membranes. Cost-sensitive households in Poland and the Czech Republic favor these for seasonal use, constrained by electrical panel limitations in older housing stock.
- Spas:Compact hydrotherapy units with jetted seating configurations. Wellness-oriented consumers in Italy and Spain drive demand for premium residential installations.
- Hot Tubs:Wood-fired or electrically heated soaking vessels. Nordic markets in Sweden and Finland show concentration for outdoor thermal bathing traditions.
Volume sits with In-ground Pools; growth tilts toward Spas.
Material:
Material selection tracks buyer time horizons and maintenance tolerance, with long-life composites gaining share against traditional options requiring periodic resurfacing.
- Concrete:Poured or shotcrete shells with plaster or tile finishes. Municipal aquatic facilities in Spain and Italy specify these for structural longevity under heavy public use, though construction timelines extend due to curing requirements.
- Vinyl:Flexible polymer liners suspended over steel or polymer wall panels. Budget residential buyers in Eastern Europe select these for lower upfront costs, facing replacement cycles every 7-10 years.
- Fiberglass:Factory-molded composite shells with gelcoat surfaces. German and French homeowners increasingly specify these for 30-year service life and reduced chemical maintenance under REACH compliance protocols.
- Steel:Corrosion-resistant metal panels for above-ground frame systems. Temporary installation demand in Poland leverages galvanized or powder-coated variants.
Concrete anchors municipal volume; fiberglass expands most quickly in residential replacement cycles.
End User:
End-user categories diverge by procurement sophistication, with institutional buyers subject to EU public procurement rules and residential buyers influenced by energy-efficiency incentives.
- Residential:Private homeowners installing pools or spas for leisure and property enhancement. Mediterranean coastal municipalities in France show high penetration rates, while Eastern European markets remain under 5% ownership.
- Commercial:Fitness centers, wellness clubs, and hospitality properties. German commercial operators prioritize variable-speed pump systems to meet Ecodesign Directive thresholds.
- Hotels:Hospitality amenities competing on guest experience differentiation. Spanish resort properties in the Balearic and Canary Islands drive seasonal upgrade cycles.
- Municipalities:Public aquatic facilities operated by local governments. Italian municipalities replace aging infrastructure with F-Gas-compliant heat pump systems under national recovery funding.
Residential commands absolute volume; Municipalities offer steepest expansion trajectory amid EU infrastructure subsidies.
Design Type:
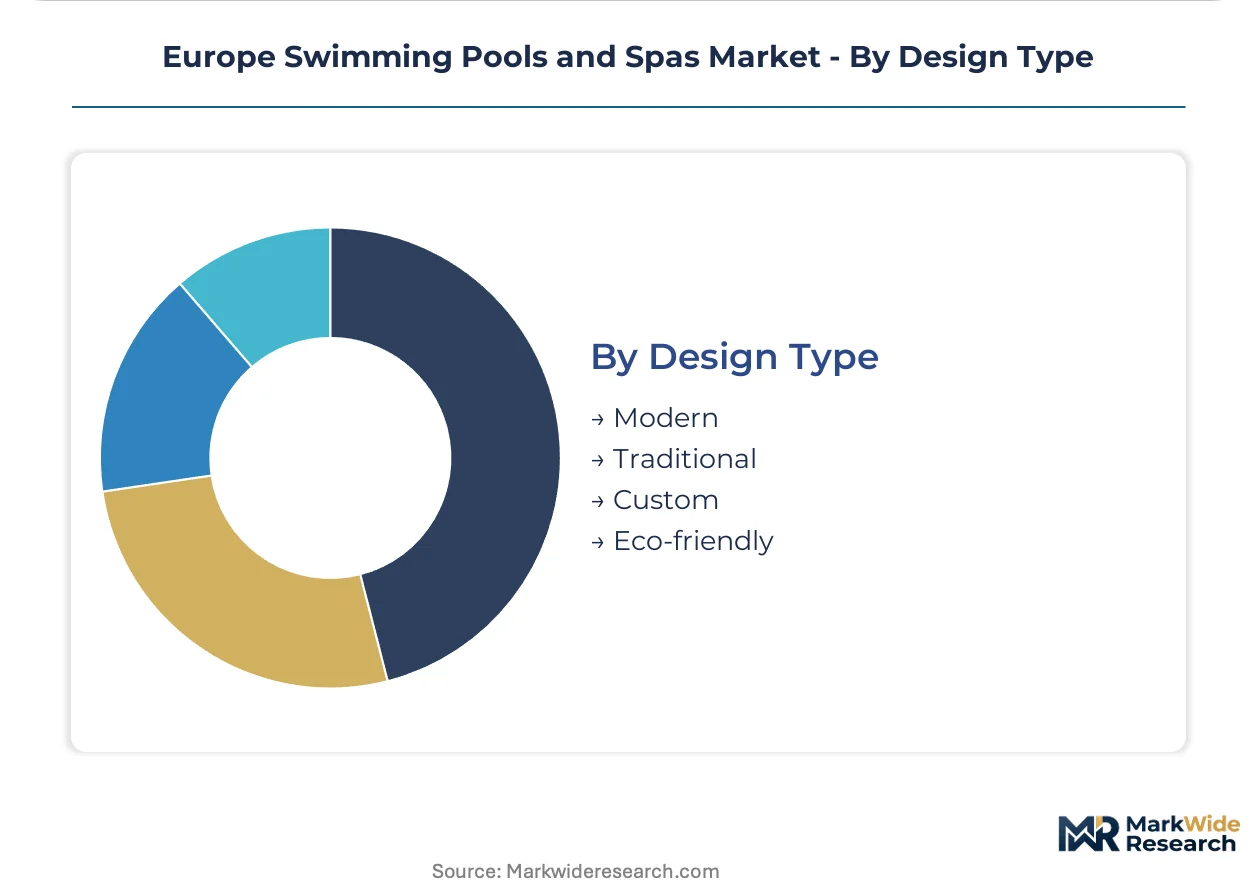
Design preferences reflect buyer aesthetic positioning and sustainability commitments, with eco-conscious specifications increasingly influencing specification decisions.
- Modern:Clean geometric lines with integrated infinity edges and minimal hardscaping. Urban residential projects in Paris and Berlin favor these for contemporary property integration.
- Traditional:Rectangular or Roman-end configurations with classical coping and tile patterns. Rural French properties and historic hotel renovations maintain demand for these forms.
- Custom:Bespoke shapes and features including grottos, swim-up bars, and integrated spas. High-net-worth buyers in Monaco and the Swiss Alps commission these for estate differentiation.
- Eco-friendly:Natural swimming pools with biological filtration and native planting zones. German and Austrian markets lead adoption, aligned with circular-economy mandates for chemical-free operation.
Traditional designs retain volume leadership; Eco-friendly configurations gain share fastest amid circular-economy regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential pool ownership concentrates along Mediterranean coastlines where climate and tourism infrastructure sustain year-round demand, while Northern European markets pivot toward energy-efficient retrofits driven by subsidy programs.
France
French homeowners in Provence-Alpes-Côte d'Azur and Nouvelle-Aquitaine dominate residential installations, with pool ownership exceeding 15% in coastal departments. The EU Green Deal renovation subsidies now cover heat pump upgrades for existing pools, accelerating equipment replacement cycles. The Côte d'Azur cluster around Nice and Cannes drives premium custom installations for luxury properties.
Germany
German consumers prioritize eco-friendly natural swimming pools with biological filtration, particularly in Bavaria and Baden-Württemberg where chemical-free operation aligns with circular-economy mandates. Ecodesign Directive compliance forces municipal aquatic facilities to specify variable-speed pump systems. The Stuttgart industrial corridor hosts engineering specialists developing heat pump-solar thermal hybrid configurations.
Italy
Italian demand splits between residential spas in Lombardy and Veneto wellness markets and municipal facility upgrades in Emilia-Romagna and Lazio. National recovery funding under the EU Next Generation program finances F-Gas-compliant heat pump installations at public pools. The Bologna-Modena industrial district supplies composite fiberglass shell components across Southern Europe.
Spain
Spanish resort properties in the Balearic and Canary Islands drive seasonal commercial upgrade cycles, while mainland Mediterranean municipalities replace aging concrete infrastructure. REACH compliance protocols govern chemical treatment formulations for hotel operators. The Valencia manufacturing hub produces vinyl liner systems for cost-sensitive Eastern European export markets.
Poland
Polish residential penetration remains below 5%, creating first-mover opportunities for fiberglass distributors establishing local installation networks in Warsaw and Kraków metropolitan areas. Cost-sensitive buyers favor above-ground steel-frame systems constrained by electrical panel limitations in socialist-era housing stock. The Łódź region hosts emerging pool equipment assembly operations serving Central European markets.
Europe Swimming Pools and Spas Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium hydrotherapy brands commanding margin premiums while volume-driven equipment suppliers scale through distributor networks. The structure tilts toward consolidation at the equipment tier and fragmentation in shell fabrication. Three archetypes dominate: pan-European distribution platforms, technology-focused pump and filtration specialists, and premium wellness configuration houses. Competitive moves center on geographic expansion into underpenetrated Eastern European markets and portfolio diversification into heat pump-solar hybrid systems.
Among distribution-anchored players, Fluidra S.A. occupies a position exemplifying pan-European commercial project reach, while Pentair Plc represents the technology-specialist archetype in variable-speed pump systems. Jacuzzi Brands LLC anchors the premium hydrotherapy tier. These three companies illustrate how divergent strategic positioning—scale logistics, equipment innovation, and brand premiumization—coexist within the same market structure without direct segment overlap.
| Leading Market Players |
|---|
| Bullfrog International LC |
| Villeroy & Boch AG |
| Fluidra S.A. |
| Myrtha Pools |
| Kohler Co. |
| Pentair Plc |
| Hayward Holdings, Inc. |
| AKVO Spiralift Inc |
| Jacuzzi Brands LLC |
| Others |
Supply Flow & Price Mechanics
Heat pump manufacturing scale-up across Northern Europe simultaneously compresses unit economics and concentrates procurement leverage among integrated equipment suppliers. The shift from gas-fired to electric thermal systems redraws cost structures for pool heating while tightening supplier relationships around refrigerant handling certifications and heat exchanger sourcing.
Pricing Analysis
Volume concentrates in standard fiberglass shell configurations while margins accrue to custom concrete installations and premium hydrotherapy spas. Three-tier pricing structure across premium, standard, and economy levels separates bespoke architectural pools from catalog fiberglass units and seasonal above-ground systems. Cost compression in entry-level vinyl liner segments is intensifying because Eastern European buyers prioritize accessibility over durability. Municipal procurement teams in Italy and Spain exhibit lowest price sensitivity given EU recovery funding coverage, while Polish residential buyers face acute budget constraints.
Supply Chain Analysis
Copper tubing supply rests on German and Italian metal processors serving heat exchanger fabricators, while composite resin feedstock draws from Netherlands and Belgian chemical producers. Fiberglass shell molding concentrates in Spain, Italy, and Poland, with gelcoat formulations sourced from specialty chemical suppliers in Germany. Single-source vulnerability sits with variable-speed pump motor controllers from East Asian semiconductor foundries. Distribution runs through Fluidra's pan-European logistics network for commercial projects, alongside regional dealer-installer channels for residential access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe swimming pools and spas market sits in a technology-transition phase as heat pump systems displace legacy gas-fired heating infrastructure. This substitution wave creates divergent imperatives across incumbent equipment suppliers, new market entrants, and capital allocators.
For Market Incumbents: Anticipate margin compression in standardized pump and filtration equipment as Chinese manufacturers achieve CE marking compliance and enter through Polish distribution channels. Defensive positioning requires deepening captive supply of heat pump compressors through backward integration into refrigeration component sourcing, alongside locking municipal maintenance contracts in France and Germany to secure replacement part revenue streams. For New Entrants and Emerging Players: EU Green Deal renovation subsidies in France and Germany open a window for heat pump-solar thermal hybrid system specialists to establish beachheads before incumbent HVAC players extend into pool applications. White-space targets include Czech Republic residential installations below 5% penetration and eco-friendly natural pool configurations in Austrian and German markets. A direct-to-consumer digital configurator with contractor matching serves as the most penetrable go-to-market angle against established dealer networks. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to building technology conglomerates seeking European pool exposure. Long-term viability favors vertically integrated players controlling shell manufacturing, equipment supply, and installation service capacity. Acquisition target archetypes include fiberglass molders with established REACH compliance protocols and municipal service contractors with F-Gas-certified technician benches. The signal to watch is consolidation velocity among Polish and Czech installation networks as Western European players seek Eastern European growth.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump-Solar Thermal Hybrid Development | Addresses Nordic climate heating loads while qualifying for EU Green Deal subsidies in Germany and France. |
| Fiberglass Shell Capacity Expansion | Captures residential replacement cycles shifting from concrete and vinyl under REACH compliance timelines. |
| F-Gas Technician Certification Programs | Closes service capacity gaps in Southern Europe that constrain heat pump installation velocity. |
| Direct-to-Consumer Digital Platform Launch | Displaces traditional dealer-led sales processes for French and German residential pool specifications. |
| Municipal Maintenance Contract Aggregation | Locks recurring revenue streams from Italian and Spanish public aquatic facility upgrade cycles. |
Methodological Framework
Independent corroboration across pool equipment manufacturer filings, municipal procurement databases, and EU regulatory notices underwrites the qualitative findings in this study. Primary interviews with pool installation contractors, municipal facility managers, HVAC equipment procurement leads, and chemical treatment distributors combined with secondary validation from ECHA substance registrations, F-Gas Regulation compliance databases, and national recovery fund disbursement records. Bottom-up demand modeling across residential, commercial, and municipal end-use segments triangulated against top-down market sizing from trade association membership data.
Comparable-period anchoring to pre-pandemic installation baselines established the forecast trajectory across the projection horizon. The analytical framework models volume and value outputs by product type, material composition, end-user category, and design preference, with cross-segment interaction effects calibrated through installer capacity constraints and regulatory phase-in schedules. CAGRs derive from equipment replacement cycle analysis, subsidy program duration assumptions, and penetration rate convergence modeling against Mediterranean market benchmarks. Industry-specific forecast inputs include heat pump adoption curves under Ecodesign Directive thresholds and fiberglass shell production capacity expansion timelines.
The model assumes a particular technology adoption path; alternative pathways for air-source heat pump deployment would alter the outlook if gas infrastructure retrofit costs decline or electrical grid constraints emerge in Southern Europe. Forecasts reflect assumptions regarding subsidy program continuity, refrigerant phase-down schedules, and vocational training program expansion rates. A small set of named triggers—F-Gas Regulation revision timing, REACH substance restriction updates, and EU Green Deal fund reauthorization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Golf Trolley Market
Outdoor & Sports
Autonomous Golf Caddy Market
Outdoor & Sports
Fire Pits Market
Outdoor & Sports
Freshwater Fishing Rod Market
Outdoor & Sports
Cold Plunge Pools Market
Outdoor & Sports
Swimming Pool Equipment Market
Outdoor & Sports
Aquatic Fins Market
Outdoor & Sports
Australia Kids Scooter Market
Outdoor & Sports
Global Canoe and Kayak Market
Outdoor & Sports
Hunting Blinds Market
Outdoor & Sports
Fishing Reels Market
Outdoor & Sports
Paintball Field Service Market
Outdoor & Sports
Riding Multi-Purpose Lawn Mower Market
Outdoor & Sports
Camping Beds and Mats Market
Outdoor & Sports
Camping Lights and Lanterns Market
Outdoor & Sports
Skateboard Ramp Market