
 Autonomous Golf Caddy Market | 2026-2036
Autonomous Golf Caddy Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Golf Caddy Market Insights
Market Context
Direct-to-course distribution is reshaping how autonomous golf caddies reach end buyers, with manufacturers bypassing traditional retail to secure fleet contracts. TG Caddies leverages its early partnerships with upscale clubs in Arizona and Florida to anchor recurring revenue streams. Club Car competes through its established dealer network and backward integration into electric vehicle chassis production. Hello Caddy differentiates via AI-powered follow-me algorithms that reduce cart-path dependency.
Technical Definition and Segments
An autonomous golf caddy is a self-propelled, battery-powered carriage that transports golf bags across courses using sensor fusion, GPS waypoint tracking, and motor control systems rated for 18-hole range cycles. Its primary commercial purpose is to eliminate manual bag carrying while preserving pace of play across varied terrain. Smart caddies with integrated GPS navigation and automated charging docks command the highest margin pools as clubs prioritize fleet uptime over unit cost. Electric caddies dominate unit volume among individual golfers, while remote-controlled variants face pressure from fully autonomous alternatives in the tournament organizer segment.
Regulatory Frame
The FCC governs wireless transmission protocols under Part 15 rules, while NHTSA guidelines for low-speed vehicles inform frame and braking standards on U.S. courses. ISO 12100 safety standards for machinery design shape export eligibility for manufacturers targeting European clubs. Stakeholders must monitor how emerging state-level autonomous vehicle classifications affect liability frameworks for unmanned caddies operating near public roadways.
Market Dynamics
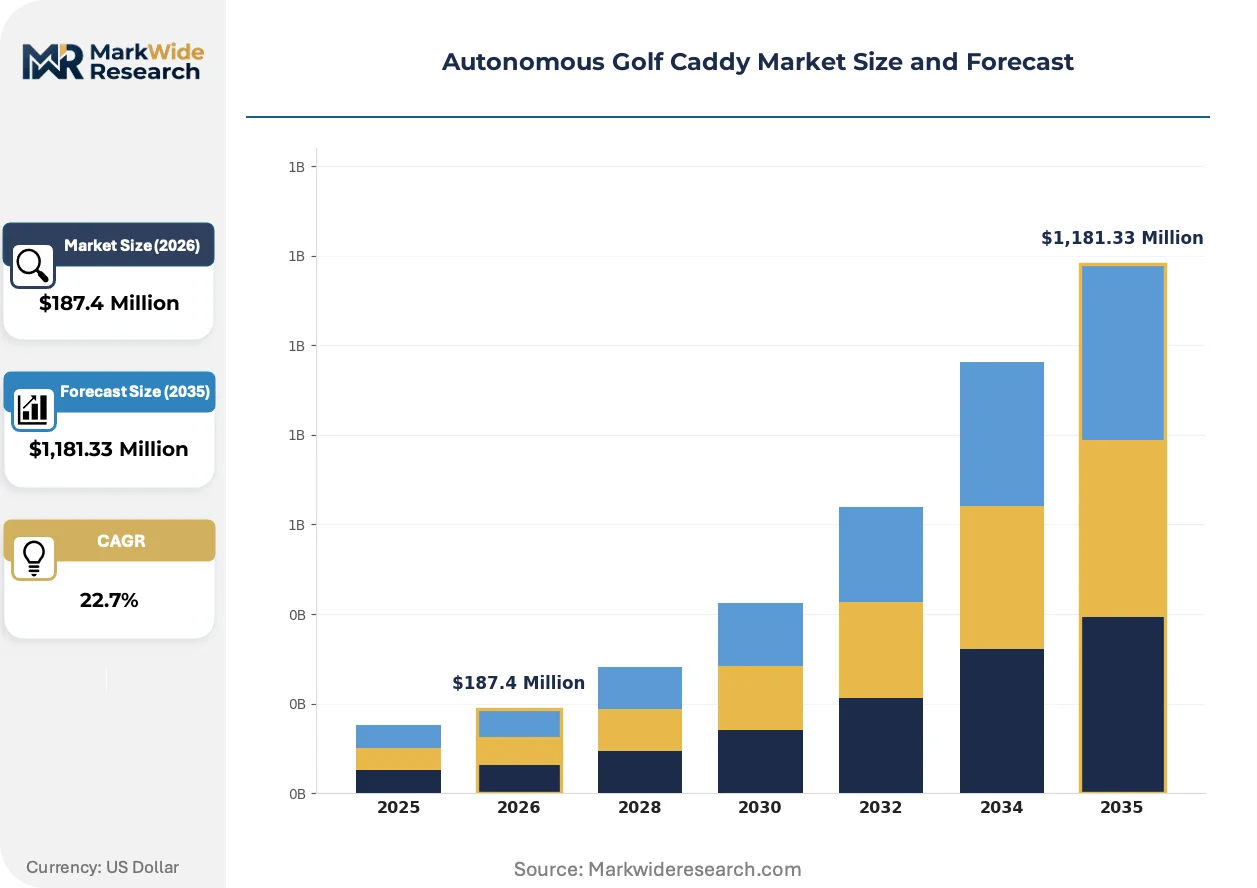
Golf clubs across the United States are replacing traditional caddies with autonomous units to cut labor costs, creating fleet-scale demand that reshapes manufacturer distribution strategies and accelerates direct-to-course contracting models.
Growth Catalysts
- FCC Part 15 compliance:Unlicensed radio rules for Bluetooth and GPS connectivity reduce certification barriers for U.S. manufacturers entering the smart caddy segment.
- Resort fleet modernization:Premium golf installations in Arizona and Florida are deploying autonomous caddies as amenities that differentiate member experiences and justify elevated dues.
- Lithium-ion battery density improvements:Extended 18-hole range cycles eliminate mid-round charging infrastructure, making electric autonomy viable on longer championship layouts.
Market Restraints
- Sensor module cost concentration:Lidar and ultrasonic component supply concentrates among Asian contract manufacturers, exposing U.S. assemblers to input volatility and extended lead times.
- Terrain handling limitations:Steep bunker faces and wet fairway conditions exceed current motor torque ratings, restricting deployment on links-style courses with dramatic elevation changes.
- State autonomous vehicle classification friction:Emerging low-speed vehicle definitions in California and Texas create liability uncertainty for caddies operating near public cart paths.
Strategic Opportunities
- Tournament organizer segment:Professional event staging companies are piloting autonomous caddies for player bag transport, reducing volunteer staffing requirements at PGA Tour and LPGA venues.
- AI-powered follow-me convergence:Computer vision algorithms paired with UWB positioning chips enable cart-path-independent navigation, opening rough-terrain courses previously unsuited for automation.
- Individual golfer channel expansion:Direct-to-consumer e-commerce platforms are bypassing traditional pro shop distribution, capturing margin from high-net-worth recreational buyers in Texas and South Carolina.
Industry Challenges
- Robotics engineering talent scarcity:Sensor fusion and motor control expertise concentrates among automotive and drone industry veterans, forcing golf caddy manufacturers to compete for specialized firmware developers.
- ISO 12100 certification timelines:European machinery safety documentation requirements extend export approval cycles by eight to fourteen months, delaying revenue recognition from German and Swedish club markets.
- Legacy fleet integration complexity:Autonomous caddies must interoperate with existing Club Car and EZ-GO charging infrastructure, requiring proprietary adapter hardware that fragments maintenance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Golf Caddy Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Caddies, Remote-Controlled Caddies, Smart Caddies, Manual Caddies End User: Golf Clubs, Individual Golfers, Tournament Organizers, Golf Resorts Technology: GPS Navigation, Bluetooth Connectivity, Sensor Technology, Automated Charging Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Golf Equipment Distributors |
| Companies Covered | TG Caddies, Axlow, Robera, Tempo Walk, Caddie Wheel, Club Car, Ixie, Carteav, Hello Caddy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Golf Caddy Market Trends and Innovations
Autonomous golf caddy technology is advancing through sensor fusion convergence, regulatory clarity on low-speed vehicle classifications, and procurement model shifts that favor fleet leasing over unit purchase. These forces are compressing product lifecycles and redrawing competitive boundaries.
Ultrasonic and camera-based obstacle detection is hybridizing with GPS waypoint tracking to create redundant navigation systems. Upscale resort operators in Florida are adopting these dual-mode caddies to reduce collision incidents on crowded morning tee sheets. This hybridization is compressing the performance gap between premium smart caddies and basic electric alternatives, forcing mid-tier manufacturers to accelerate R&D spending or exit the category.
NHTSA guidelines for low-speed vehicles are clarifying braking and lighting requirements for caddies operating near public roadways. Manufacturers targeting California and Arizona courses must now certify frame integrity and emergency stop systems to these standards. Tournament organizer segments are responding fastest, embedding compliance documentation into bid packages for municipal and resort venue contracts.
Course-level procurement is consolidating around multi-year fleet service agreements that bundle hardware, maintenance, and software updates. Traditional pro shop retail channels are losing share to manufacturer-direct contracting teams who embed technicians on-site. This shift is most visible across Texas and South Carolina, where private equity-backed club operators are standardizing autonomous caddy fleets across multiple properties to capture volume pricing and unified training protocols.
Autonomous Golf Caddy Market Segmentation
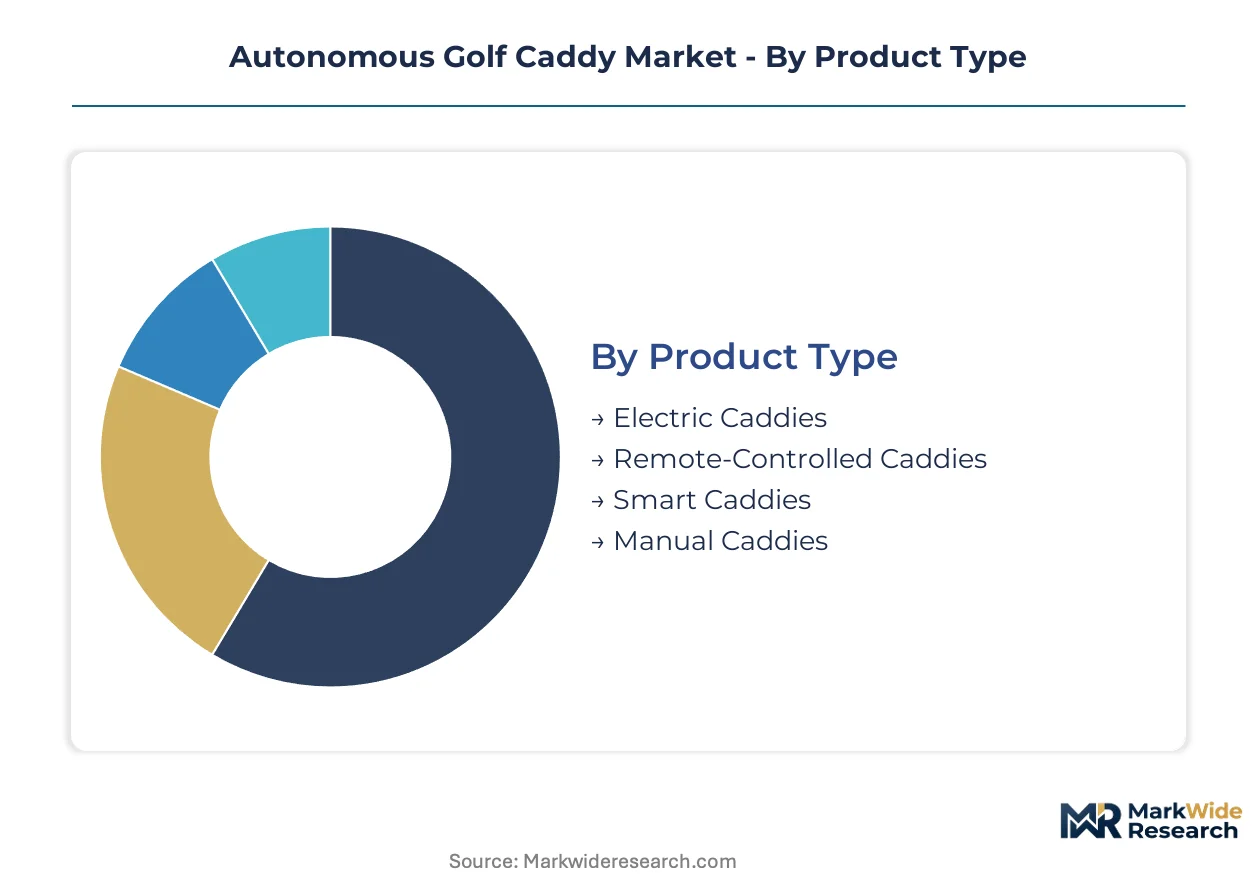
Segmentation in the autonomous golf caddy market reveals how technology tiers, customer economics, and procurement channels create distinct competitive arenas. Manufacturers must align R&D investment and distribution strategy to the specific performance thresholds and buying behaviors of each slice.
Product Type:
Cost tier stratification separates basic electric mobility from premium autonomous systems, with each tier commanding different margin pools and replacement cycles.
- Electric Caddies:Battery-powered units with manual steering and basic motor control dominate unit volume among individual recreational buyers. Demand concentrates in Texas and South Carolina, where direct-to-consumer e-commerce platforms capture margin from high-net-worth golfers seeking cart-path alternatives without autonomy premiums.
- Smart Caddies:Sensor fusion platforms integrating GPS waypoint tracking, ultrasonic obstacle detection, and automated charging docks command the highest margin pools. Arizona and Florida resort installations drive fleet-scale procurement, prioritizing uptime guarantees and embedded technician support over unit acquisition cost.
- Remote-Controlled Caddies:Handheld transmitter units face displacement pressure from fully autonomous alternatives, particularly in tournament organizer segments seeking volunteer staffing reductions.
- Manual Caddies:Unpowered push carts retain residual share among purist golfers and budget-conscious municipal course segments.
Smart Caddies commands the established base. The steepest expansion runs through Electric Caddies.
End User:
Customer type determines procurement scale, with fleet buyers negotiating multi-year service agreements and individual purchasers prioritizing point-of-sale availability.
- Golf Clubs:Private and semi-private facilities across the United States are replacing traditional caddies with autonomous units to cut labor costs, creating fleet-scale demand that reshapes manufacturer distribution strategies. Direct-to-course contracting teams embed technicians on-site, displacing traditional pro shop retail channels.
- Golf Resorts:Premium installations in Arizona and Florida deploy autonomous caddies as amenities that differentiate member experiences and justify elevated dues. These properties standardize fleets across multiple properties to capture volume pricing and unified training protocols.
- Individual Golfers:High-net-worth recreational buyers purchase through manufacturer-direct e-commerce platforms, bypassing traditional distribution.
- Tournament Organizers:Professional event staging companies pilot autonomous caddies for player bag transport, reducing volunteer staffing requirements at PGA Tour and LPGA venues.
Golf Clubs anchors procurement volume. Golf Resorts gains share fastest.
Technology:
Application focus distinguishes navigation infrastructure from connectivity and power management subsystems, with integration complexity rising at the premium tier.
- GPS Navigation:Satellite-based waypoint tracking enables autonomous path following across varied terrain. FCC Part 15 unlicensed radio rules reduce certification barriers for U.S. manufacturers embedding GPS receivers.
- Sensor Technology:Lidar and ultrasonic component supply concentrates among Asian contract manufacturers, exposing U.S. assemblers to input volatility and extended lead times.
- Bluetooth Connectivity:Short-range wireless protocols support smartphone app integration for manual override and status monitoring.
- Automated Charging:Docking systems eliminate manual plug-in requirements, critical for fleet uptime in resort deployments.
GPS Navigation commands the installed base. Sensor Technology climbs the fastest.
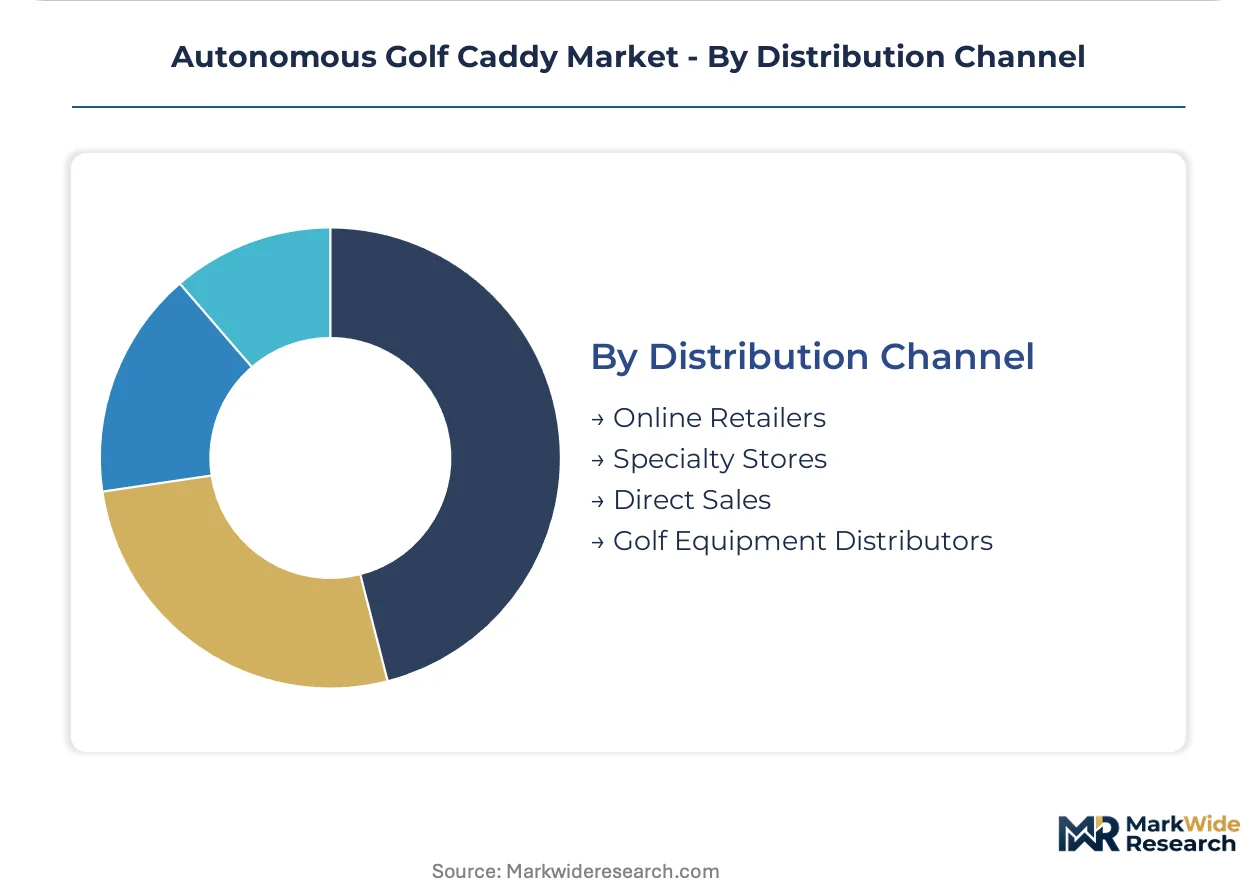
Distribution Channel:
Volume concentration shifts from retail intermediaries toward manufacturer-direct relationships as fleet procurement consolidates.
- Direct Sales:Manufacturer contracting teams secure multi-year fleet service agreements bundling hardware, maintenance, and software updates. This channel captures premium margin from Texas and South Carolina private equity-backed club operators standardizing autonomous caddies across property portfolios.
- Online Retailers:E-commerce platforms serve individual golfer segments with direct-to-consumer fulfillment, bypassing traditional pro shop distribution.
- Specialty Stores:Pro shop and golf retail intermediaries lose share to direct channels but retain residual importance for trial and demonstration.
- Golf Equipment Distributors:Traditional wholesale networks face compression as manufacturers prioritize direct-to-course relationships.
Direct Sales commands the established base. Online Retailers shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium resort installations in Arizona and Florida command pricing premiums that individual purchasers in Texas cannot replicate. Fleet-scale procurement concentrates purchasing power among U.S. golf clubs while European and Asian markets remain nascent.
United States
Arizona and Florida resort clusters drive fleet-scale demand as private equity-backed operators standardize autonomous caddies across property portfolios. The FCC's Part 15 rules for unlicensed radio devices govern Bluetooth and GPS connectivity, reducing certification barriers for domestic manufacturers. Scottsdale and Naples anchor the premium installation base, where clubs deploy smart caddies as member amenities justifying elevated dues.
Germany
Munich-based golf resorts pilot autonomous caddies for tournament staging, reducing volunteer staffing requirements at European Tour venues. ISO 12100 machinery safety standards extend export approval timelines by eight to fourteen months, delaying revenue recognition from club markets. Bavaria's precision engineering clusters supply sensor fusion expertise to caddy assemblers targeting European compliance.
Japan
Tokyo metropolitan area clubs adopt electric caddies for aging golfer demographics seeking cart-path alternatives without autonomy premiums. METI guidelines for low-speed mobility inform braking and lighting standards on courses near public roadways. Chubu region manufacturers leverage automotive supply chain relationships to source motor control systems for domestic assembly.
United Kingdom
London and Southeast England private clubs replace traditional caddies with autonomous units to cut labor costs amid rising minimum wage pressures. CE marking requirements under EU machinery directives shape export eligibility despite post-Brexit regulatory divergence. Scotland's links courses resist deployment due to terrain handling limitations on steep bunker faces and wet fairway conditions.
Australia
New South Wales and Victoria golf resorts test autonomous caddies for pace-of-play management on championship layouts. The country's national communications regulator governs wireless transmission protocols for GPS and Bluetooth integration. Melbourne's technology incubators host startups developing AI-powered follow-me algorithms for cart-path-independent navigation.
Autonomous Golf Caddy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin from sensor modules and motor control systems. The vendor base stratifies between fleet-scale contractors securing multi-year service agreements and direct-to-consumer brands bypassing traditional retail. Three archetypes dominate: established golf equipment manufacturers with dealer networks, autonomous mobility startups with AI navigation IP, and electric vehicle chassis suppliers backward integrated into caddy assembly. Competitive moves concentrate on direct-to-course contracting teams embedding technicians on-site and proprietary adapter hardware for legacy charging infrastructure interoperability.
Among U.S.-based platform integrators, Club Car exemplifies the established equipment manufacturer archetype, leveraging captive chassis production and dealer networks to anchor fleet relationships. TG Caddies and Hello Caddy occupy positions within the autonomous specialist tier, with the former representing early-mover resort partnerships and the latter exemplifying AI-powered navigation differentiation. These three companies illustrate how competitive positioning fragments across manufacturing depth, software capability, and distribution control.
| Leading Market Players |
|---|
| TG Caddies |
| Axlow |
| Robera |
| Tempo Walk |
| Caddie Wheel |
| Club Car |
| Ixie |
| Carteav |
| Hello Caddy |
| Others |
Pricing and Supply Chain Analysis
Chubu region manufacturing clusters in Japan anchor motor control system capacity, with their output fluctuations transmitting directly to North American assembler pricing power during contract renegotiation cycles. Arizona and Florida resort buyers leverage fleet scale to compress configured-to-order premiums, while individual golfers in Texas absorb higher per-unit costs through direct-to-consumer channels.
Pricing Analysis
Configured-to-order pricing for smart caddies with embedded technician support commands spreads over standard electric units due to ISO 12100 certification documentation and uptime guarantee bundling. Three-tier pricing structure across premium, standard, and economy levels separates resort fleet deployments from individual recreational purchases. Cost compression in the electric tier is intensifying because lithium-ion cell suppliers compete for automotive contract overflow. Tournament organizers exhibit the lowest price sensitivity, prioritizing volunteer reduction metrics over per-unit acquisition cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for lidar and ultrasonic sensor modules. Component sourcing concentrates in China, South Korea, and Japan, with Chubu region suppliers feeding motor control systems to domestic assemblers. Raw material dependencies span lithium carbonate, rare-earth magnets, and semiconductor-grade silicon. Single-source vulnerability in Asian contract manufacturing exposes U.S. platform integrators to extended qualification timelines. Distribution runs through direct-to-course contracting teams embedding technicians on-site, displacing traditional pro shop intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among private equity-backed club operators standardizing fleets across multi-property portfolios, fragmenting manufacturer negotiation leverage and compressing margin capture for undifferentiated hardware.
For Market Incumbents: Entrench fleet relationships through captive supply of proprietary charging dock adapters that lock in legacy infrastructure interoperability. Deepen backward integration into sensor fusion firmware development to offset robotics engineering talent scarcity. Defend against autonomous mobility startups by accelerating NHTSA low-speed vehicle compliance certification ahead of state classification clarifications. For New Entrants and Emerging Players: Establish a beachhead in the tournament organizer segment, where volunteer staffing reduction mandates create procurement urgency without entrenched incumbent relationships. Target Scotland's links courses with terrain-handling R&D partnerships, exploiting incumbent avoidance of steep bunker face navigation. Pursue direct-to-consumer e-commerce positioning in South Carolina's high-net-worth recreational buyer pool. For Investors and Strategic Acquirers: Long-term, this sits as a fleet-service-transition play because recurring revenue from multi-year maintenance and software update agreements will displace unit-sales-dependent valuations. Acquisition targets should display embedded technician deployment capabilities and resort property relationship density. The signal to watch is state-level autonomous vehicle classification harmonization, which would trigger liability framework clarity and accelerate municipal course procurement.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Navigation Development | Cart-path-independent algorithms open rough-terrain courses previously unsuited for automation deployment. |
| Multi-Year Fleet Service Agreements | Bundled hardware-maintenance-software contracts capture recurring revenue from Arizona and Florida resort clusters. |
| NHTSA Compliance Certification | Low-speed vehicle braking and lighting standards enable operation near public roadways in California and Texas. |
| Proprietary Charging Infrastructure | Legacy fleet adapter hardware locks in Club Car and EZ-GO interoperability, fragmenting maintenance protocols. |
| European ISO 12100 Certification | Machinery safety documentation extends export approval timelines but unlocks German and Swedish club market access. |
Research Methodology
Cross-validation between primary interviews with golf club operations directors, fleet procurement managers, and resort amenities executives and secondary validation through SEC filings of electric vehicle chassis suppliers, FCC Part 15 equipment authorization databases, and NHTSA low-speed vehicle guidance documents anchors the qualitative findings. Bottom-up triangulation against top-down market sizing incorporates sensor module bill-of-materials analysis and course-level deployment surveys.
Calibration against installed base estimates and replacement cycle assumptions shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-user procurement scale, technology integration complexity, and distribution channel control. CAGRs derive from fleet penetration scenario analysis and individual golfer e-commerce adoption curves. Industry-specific inputs span lithium-ion battery density improvement trajectories and state autonomous vehicle classification timelines.
Macroeconomic conditions sit as an overlay; deviation in private equity club acquisition velocity and resort capital expenditure cycles would shift the trajectory. Forecasts reflect assumptions regarding FCC regulatory stability and sensor module supply normalization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Global Pool Floats Market
Outdoor & Sports
Swimming Pool Accessories Market
Outdoor & Sports
Fire Pits Market
Outdoor & Sports
Camping Beds and Mats Market
Outdoor & Sports
Global Sailing Dinghy Masts Market
Outdoor & Sports
Hunting Blinds Market
Outdoor & Sports
Mexico Fishing Reels Market
Outdoor & Sports
Portable Kayaks Market
Outdoor & Sports
Compound Bow and Crossbows Market
Outdoor & Sports
China Fishing Reels Market
Outdoor & Sports
Camping Tent Market
Outdoor & Sports
Swimming Pool Liner Market
Outdoor & Sports
Swimming Pool Equipment Market
Outdoor & Sports
Freshwater Fishing Rod Market
Outdoor & Sports
Paintball Field Service Market
Outdoor & Sports
Artificial Turf Market