
 Europe Bicycle Market | 2026-2036
Europe Bicycle Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bicycle Market Analysis
Subscription-based fleet leasing and municipal bike-sharing concessions are reconfiguring capital requirements for market entry. Accell Group NV leverages its multi-brand portfolio to dominate fleet procurement contracts across Benelux cities. Bosch anchors the e-bike drive system segment through captive supply of mid-drive motors to European assemblers. Trek Bicycle Corporation sustains premium positioning by controlling specialty retail channels in Germany and France.
A bicycle is a human-powered or electrically assisted vehicle with two wheels in tandem, typically featuring a diamond frame of aluminum alloy or carbon fiber composite, chain or belt drivetrain, and braking systems meeting ISO 4210 safety standards, designed for individual transportation, recreation, or sport. Electric bikes now lead product type growth as lithium-ion battery energy density improves and EU motor-assisted speed regulations standardize at 25 km/h. Urban commuters represent the fastest-expanding end user segment as city congestion charges and low-emission zones expand across Milan, Paris, and Brussels. Specialty stores retain margin concentration in the premium and luxury price tiers, where fitting services and after-sales support justify price differentiation.
The European Union's F-Gas Regulation and CE marking requirements under the Machinery Directive shape e-bike motor and battery compliance costs, while national regulators like Germany's KBA enforce type-approval for speed pedelecs. The EU Green Deal's cycling infrastructure funding criteria and GDPR-compliant mobility data sharing mandates are creating new compliance layers for connected bicycle systems. Stakeholders must monitor how the EU AI Act's risk classification applies to predictive maintenance algorithms and automated fleet dispatch platforms.
Market Dynamics
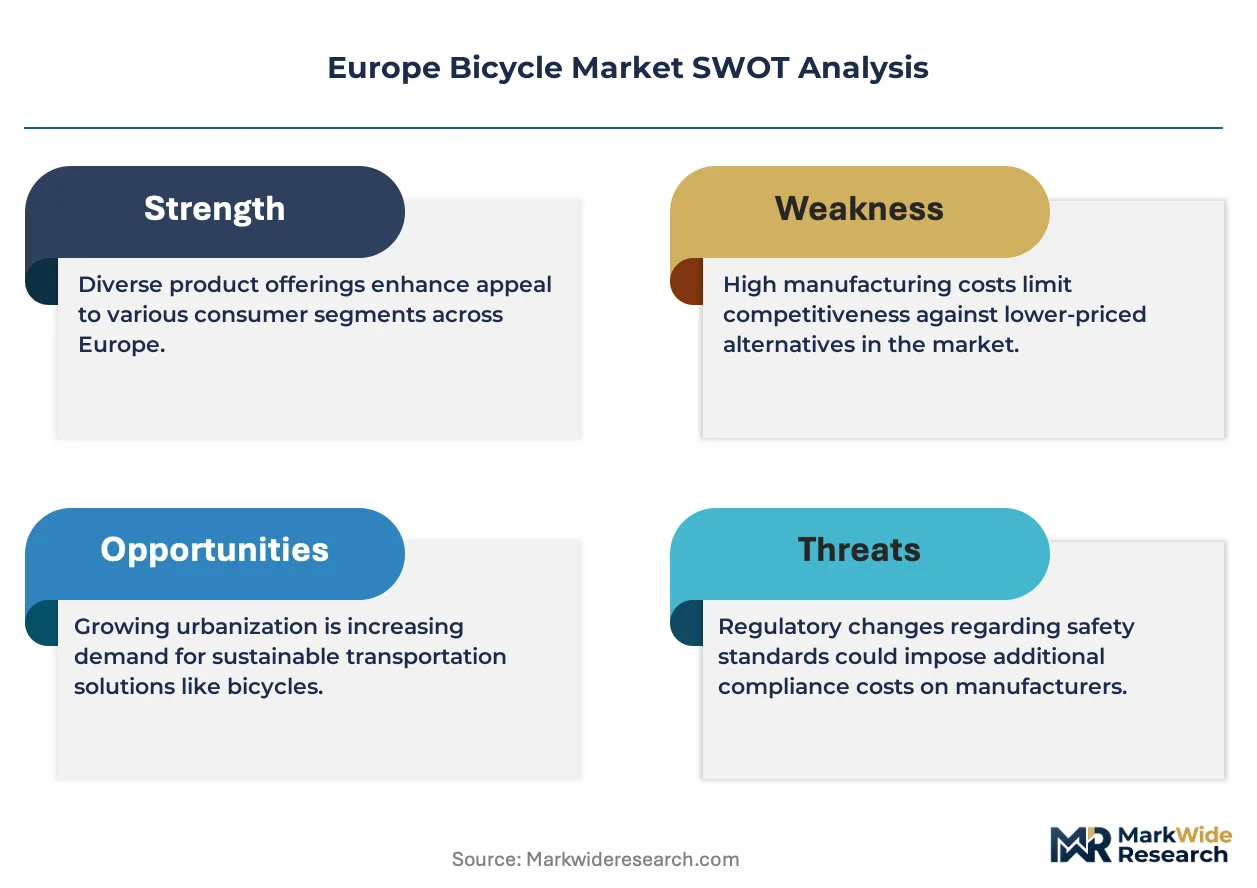
EU Green Deal infrastructure subsidies are compressing payback periods for municipal fleet electrification, while F-Gas Regulation compliance costs are restructuring motor supplier economics across the Rhine-Ruhr corridor.
Growth Catalysts
- CE marking under Machinery Directive:Standardized safety protocols reduce cross-border certification friction for e-bike assemblers exporting from Germany to Benelux markets.
- Lithium-ion energy density gains:Battery pack weight reductions enable 25 km/h pedelec designs that satisfy urban commuter range anxiety without frame geometry compromises.
- Dutch municipal procurement:Rotterdam and Amsterdam fleet concessions are mandating connected bicycle telematics, pulling demand for integrated IoT hardware through the supply chain.
Market Restraints
- Rare earth magnet concentration:Neodymium supply from Chinese processing facilities creates motor cost volatility for European drive system manufacturers.
- GDPR mobility data mandates:Connected bicycle platforms face compliance friction when sharing rider telemetry across Danish-German municipal boundaries.
- Speed pedelec type-approval:Germany's KBA certification timeline extends 14-18 months, delaying product launches for 45 km/h commuter variants.
Strategic Opportunities
- Polish manufacturing corridor:Lower labor costs and EU structural fund access attract frame welding and assembly capacity eastward from traditional Benelux production bases.
- Predictive maintenance algorithms:EU AI Act risk classification for fleet management software creates first-mover advantage for compliant platform vendors serving Paris and Brussels bike-share operators.
- Specialty retail channel consolidation:Independent fitting studios in France are capturing premium urban commuter segments through subscription-based service bundling.
Industry Challenges
- Battery recycling infrastructure:EU Battery Regulation extended producer responsibility requires reverse logistics networks that most mid-tier assemblers lack capital to build.
- ISO 4210 testing capacity:Certification bottlenecks at accredited laboratories delay product launches for carbon fiber frame manufacturers targeting German performance segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bicycle Market |
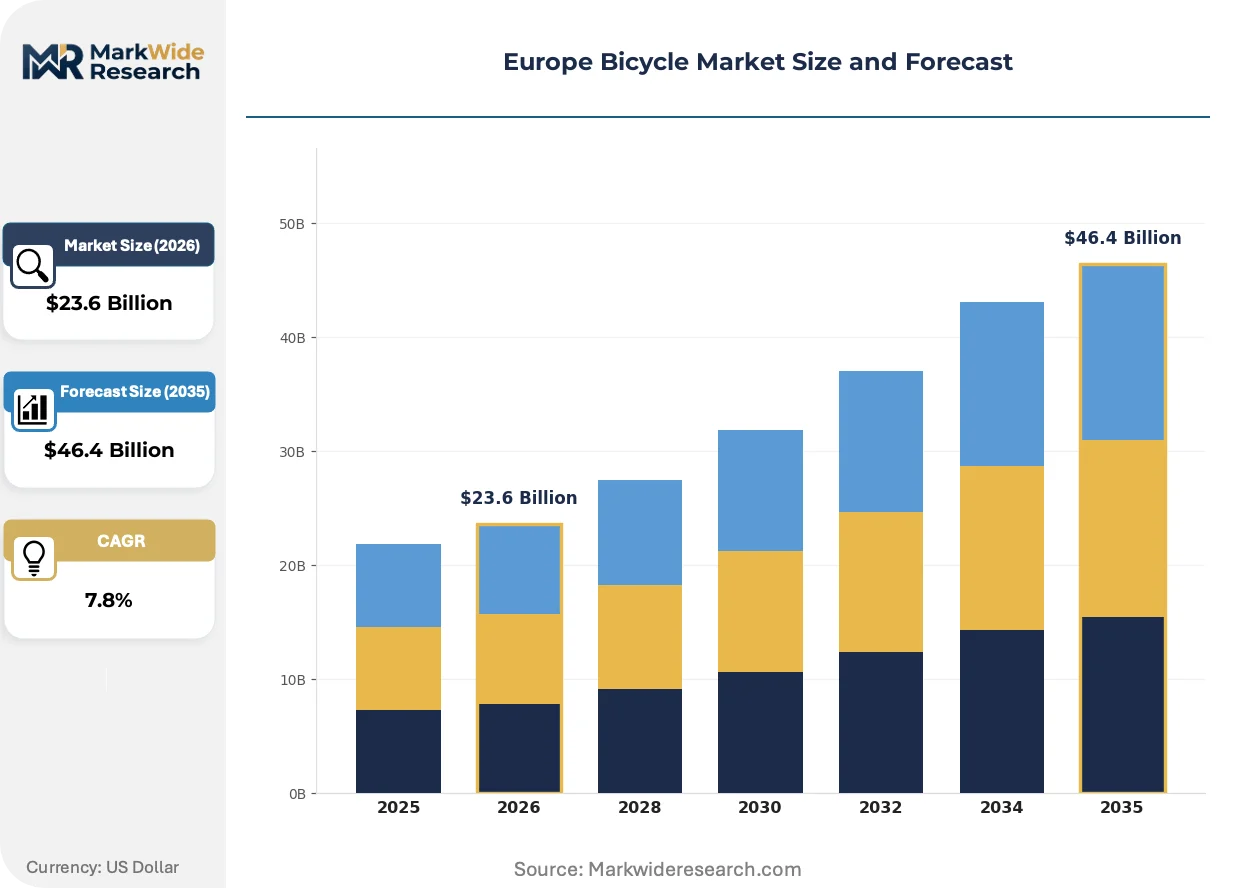
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $46.4 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain Bikes, Road Bikes, Hybrid Bikes, Electric Bikes End User: Urban Commuters, Enthusiasts, Casual Riders, Professional Cyclists Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Third-Party Distributors Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Trek Bicycle Corporation, Kross, Accell Group NV, Bosch, Specialized, Giant Manufacturing Co. Ltd, Scott Sports SA, Shimano, Pon Holdings BV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bicycle Market Emerging Trajectories
Telematics integration and motor-battery system unification are compressing traditional component supplier tiers, while procurement centralization among municipal fleet operators is reconfiguring distribution economics.
Mid-drive motor architectures are collapsing the historical separation between mechanical drivetrain and electronic control suppliers. Urban fleet operators in Copenhagen and Utrecht are specifying integrated motor-battery systems from single vendors to reduce warranty fragmentation. This technical consolidation is collapsing profit pools for standalone controller manufacturers and forcing component suppliers into captive supply relationships with assemblers.
The EU AI Act's risk classification framework for predictive maintenance algorithms is reshaping software procurement criteria for connected bicycle platforms. Fleet management vendors must document algorithmic transparency to serve municipal contracts in Paris and Brussels. Speed pedelec operators face the strictest compliance burdens, with automated dispatch systems requiring human-in-the-loop overrides for 45 km/h vehicle allocation.
Municipal procurement centralization is fragmenting specialty retail influence in the urban commuter segment. Rotterdam and Amsterdam now issue five-year fleet concessions with integrated maintenance clauses, displacing traditional distributor relationships. Danish municipalities are following with consolidated RFPs that bundle hardware, software, and service into outcome-based contracts, compressing margins for standalone equipment vendors.
Europe Bicycle Market Segmentation
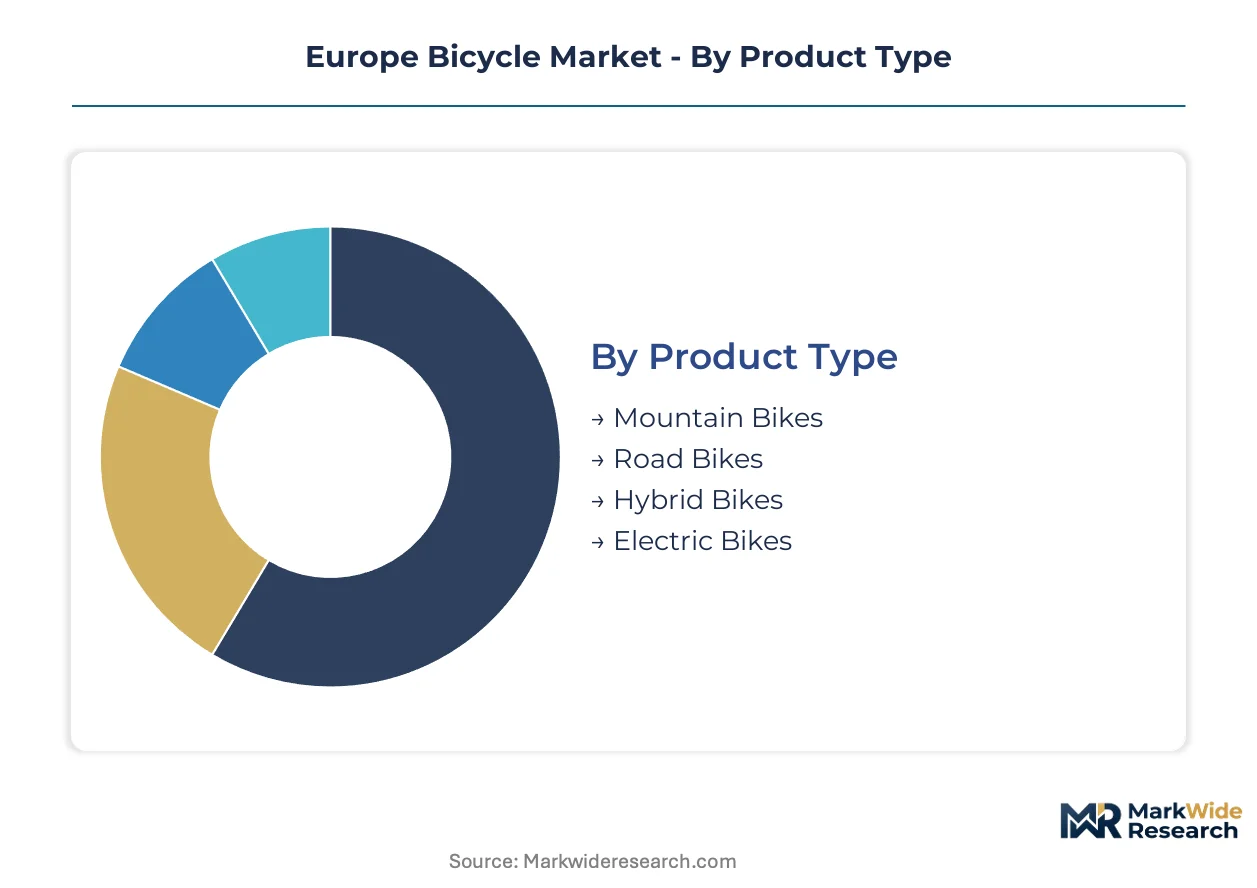
Segmentation in the Europe Bicycle Market reveals how distinct customer requirements reshape supply chain priorities. After-sales service intensity varies dramatically across product tiers, with electric drivetrains demanding specialized maintenance networks that conventional mechanical bicycles do not require.
Product Type:
After-sales service intensity climbs steeply from mechanical to electrified categories, with motor diagnostics and battery health monitoring becoming standard service obligations for dealers.
- Electric Bikes:Pedelec designs integrate lithium-ion battery packs with mid-drive or hub-mounted motors governed by EU motor-assisted speed regulations. Demand concentrates in Germany's Rhine-Ruhr corridor, where cycling modal share expansion and congestion charging schemes pull fleet procurement toward 25 km/h commuter variants. Service complexity and warranty fragmentation favor integrated motor-battery suppliers over standalone component vendors.
- Hybrid Bikes:These combine road bike geometry with wider tire clearances and relaxed frame angles, typically constructed from aluminum alloy with carbon fiber forks. Urban commuters in Dutch and Danish municipalities favor hybrids for mixed-terrain utility, pulled by expanding municipal bike-sharing concessions that specify durable, low-maintenance fleet specifications.
- Mountain Bikes:Suspension-equipped designs with reinforced aluminum or carbon fiber frames meeting ISO 4210 impact testing protocols.
- Road Bikes:Lightweight carbon fiber or aluminum frames optimized for paved surfaces with drop handlebar configurations.
By volume, Hybrid Bikes leads. By growth pace, Electric Bikes is ahead.
End User:
Cost tier alignment separates occasional purchasers from committed enthusiasts, with equipment expenditure correlating directly to replacement frequency and accessory attachment rates.
- Urban Commuters:These riders prioritize reliability, integrated lighting, and weather protection for daily transportation across variable distances. Rotterdam and Amsterdam municipal fleet concessions now mandate connected bicycle telematics, pulling hardware specifications toward IoT-integrated designs that serve centralized dispatch platforms.
- Enthusiasts:Performance-oriented cyclists invest in component upgrades, fitting services, and event participation, sustaining specialty retail margins through high-touch consultation and custom build services. German and French specialty stores capture this segment through subscription-based maintenance bundling.
- Casual Riders:Weekend recreational users with intermittent usage patterns and price-sensitive replacement cycles.
- Professional Cyclists:Elite competitors requiring UCI-compliant equipment with team sponsorship distribution channels.
By volume, Urban Commuters leads. By margin contribution, Enthusiasts is expanding most quickly.
Distribution Channel:
Volume concentration favors centralized procurement, while margin retention depends on service attachment and technical consultation depth.
- Specialty Stores:Independent retailers provide fitting services, maintenance programs, and warranty handling that justify price premiums in premium and luxury tiers. Paris and Brussels bike-share operators are consolidating procurement through outcome-based municipal contracts, compressing standalone equipment margins and displacing traditional distributor relationships.
- Online Retailers:Direct-to-consumer platforms capture price-sensitive segments through standardized specifications and return policies, though they struggle with electric bike service obligations. Danish-German municipal boundaries create GDPR compliance friction for connected bicycle platforms sharing rider telemetry across jurisdictions.
- Supermarkets:Mass-market outlets serving budget-tier mechanical bicycles with minimal service attachment.
- Third-Party Distributors:Wholesale intermediaries facing margin compression from procurement centralization among fleet operators.
By transaction count, Online Retailers leads. By value concentration, Specialty Stores maintains the steepest expansion trajectory.
Price Tier:
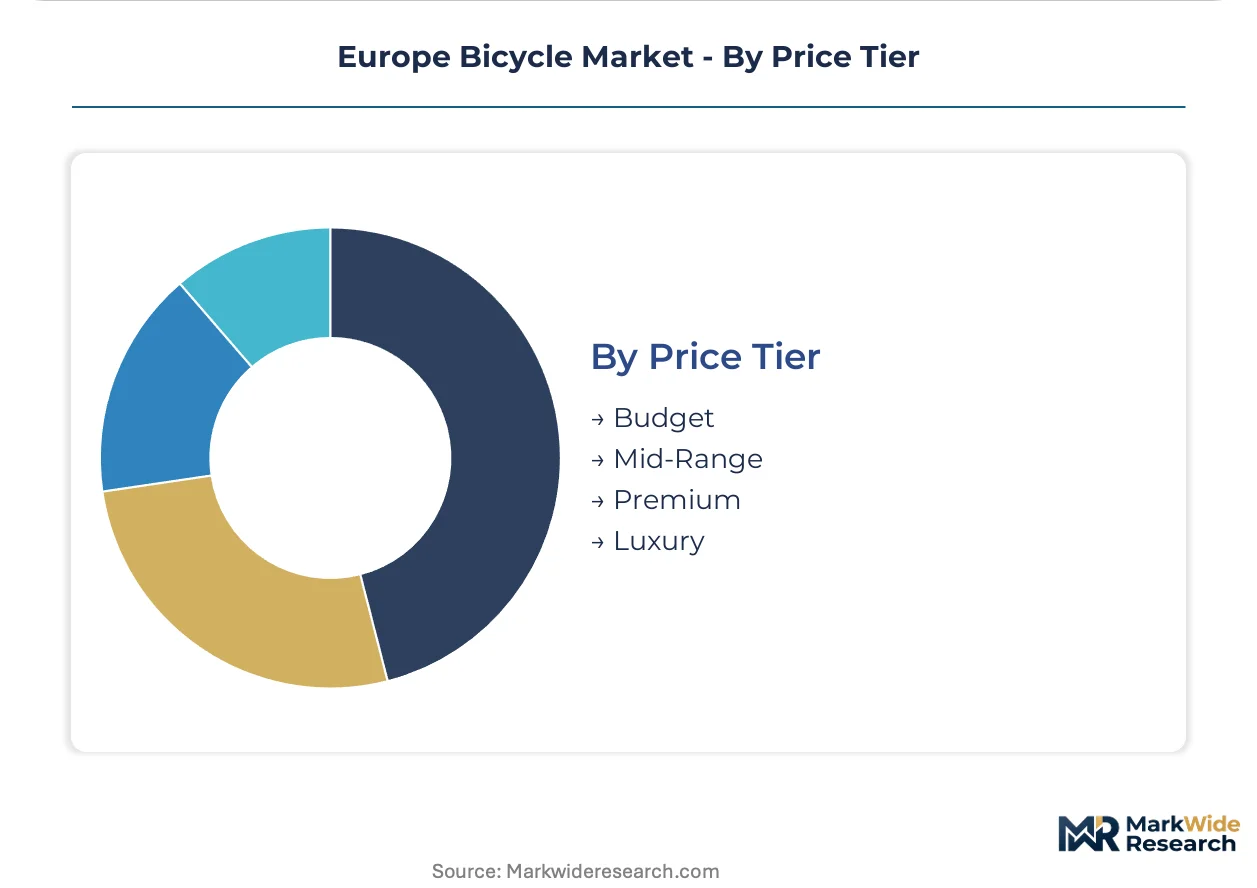
Margin structure stratifies sharply across certification grade and performance tier, with regulatory compliance costs concentrated in upper segments.
- Premium:Carbon fiber frames, electronic shifting, and integrated power meters target enthusiasts and competitive amateurs. Germany's KBA type-approval timeline for speed pedelecs extends product development cycles, delaying launches for 45 km/h variants and concentrating R&D investment among capitalized manufacturers.
- Mid-Range:Aluminum alloy construction with mechanical or entry-level electronic drivetrains balances durability with accessibility. Polish manufacturing corridors attract frame welding and assembly capacity eastward from Benelux production bases, pulled by lower labor costs and EU structural fund access.
- Budget:Entry-level specifications with standardized components and limited service networks.
- Luxury:Custom geometry, hand-built construction, and concierge service programs for discriminating purchasers.
By unit volume, Mid-Range leads. By profitability improvement, Premium is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pricing power in premium e-bike segments while Polish manufacturing corridors capture mid-range assembly economics. This asymmetry concentrates R&D investment westward and production capacity eastward across the European bicycle supply chain.
Germany
Rhine-Ruhr corridor municipalities are expanding cycling modal share through congestion charging schemes and low-emission zones. Germany's KBA enforces 14-18 month type-approval timelines for speed pedelecs, delaying 45 km/h commuter variant launches. Stuttgart and Munich anchor premium e-bike development clusters where integrated motor-battery system suppliers co-locate with assemblers.
Netherlands
Rotterdam and Amsterdam fleet concessions mandate connected bicycle telematics, pulling IoT hardware demand through supply chains. Dutch municipal procurement centralizes five-year concessions with integrated maintenance clauses, displacing traditional distributor relationships. Eindhoven Region hosts assembly operations serving Benelux urban commuter procurement at scale.
Denmark
Copenhagen and Utrecht fleet operators specify unified motor-battery systems to reduce warranty fragmentation. GDPR-compliant mobility data sharing mandates create compliance friction when rider telemetry crosses Danish-German municipal boundaries. Odense maintains specialty retail density serving enthusiast segments through subscription-based maintenance bundling.
France
Paris bike-share operators consolidate procurement through outcome-based municipal contracts, compressing standalone equipment margins. ANSM and CNIL layer data governance requirements onto connected bicycle platforms serving fleet management vendors. Île-de-France specialty stores capture premium urban commuter segments through fitting services and after-sales support.
Poland
Lower labor costs and EU structural fund access attract frame welding and assembly capacity eastward from Benelux production bases. CE marking under the Machinery Directive enables standardized safety protocols for exports to German and Benelux markets. Warsaw and Kraków manufacturing corridors supply mid-range aluminum frame production for European assemblers.
Europe Bicycle Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in captive supply relationships. The market structure consolidates around integrated motor-battery suppliers and multi-brand portfolio holders, with mid-tier assemblers facing margin compression from procurement centralization. Three archetypes dominate: integrated system vendors, multi-brand fleet contractors, and specialty retail channel controllers. Competitive moves concentrate on strategic partnerships for telematics integration and geographic expansion into Polish manufacturing corridors.
Among integrated system suppliers, Bosch anchors the e-bike drive system segment through captive supply of mid-drive motors to European assemblers. Accell Group NV represents the multi-brand fleet contractor archetype, leveraging portfolio breadth to dominate municipal procurement contracts across Benelux cities. Trek Bicycle Corporation occupies a position within specialty retail channel control, sustaining premium positioning through dedicated distribution in Germany and France.
| Leading Market Players |
|---|
| Trek Bicycle Corporation |
| Kross |
| Accell Group NV |
| Bosch |
| Specialized |
| Giant Manufacturing Co. Ltd |
| Scott Sports SA |
| Shimano |
| Pon Holdings BV |
| Others |
Supply Flow & Price Mechanics
Warsaw and Kraków manufacturing corridors attract mid-range aluminum frame assembly from Benelux production bases, compressing cost structures for European assemblers while concentrating pricing power with integrated motor-battery system vendors in Germany and the Netherlands.
Pricing Analysis
The customization-premium spread separates configured-to-order speed pedelecs from standard 25 km/h commuter variants, with Germany's KBA type-approval timeline extending development cycles for 45 km/h designs and supporting price premiums. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling intensity. Pricing pressure stems from procurement centralization among Dutch and Danish municipal fleet operators, which compresses standalone equipment margins. Urban commuters exhibit highest price sensitivity, while enthusiasts accept premium positioning for fitting services and warranty depth.
Supply Chain Analysis
Export-control regimes on rare earth processing constrain neodymium magnet flows from Chinese facilities to European motor manufacturers, creating input cost volatility. Supply concentrates in Poland for frame welding, Germany for motor-battery integration, and China for lithium-ion cell production. Raw material dependencies center on aluminum alloy billet, rare earth magnets, and battery-grade lithium carbonate. Single-source vulnerability in rare earth processing generates margin instability for drive system suppliers. Distribution runs through municipal procurement centralization and specialty retail channel control in premium tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
First-mover advantage in EU AI Act-compliant predictive maintenance algorithms represents the critical capability gap, as fleet management vendors lacking algorithmic transparency documentation face exclusion from Paris and Brussels municipal contracts.
For Market Incumbents: Harden captive supply relationships with Polish frame assemblers to defend cost position against emerging multi-brand contractors. Secure CE marking pre-certification capacity at accredited laboratories to accelerate carbon fiber product launches before ISO 4210 testing bottlenecks worsen. Vertical integration into battery recycling infrastructure addresses EU Battery Regulation extended producer responsibility requirements that mid-tier competitors cannot finance. For New Entrants and Emerging Players: Pursue Polish manufacturing corridor establishment for mid-range aluminum frame production, exploiting EU structural fund access and lower labor costs relative to Benelux bases. Target speed pedelec aftermarket service networks in Germany, where KBA certification delays create maintenance backlogs for existing 45 km/h fleets. Deploy subscription-based maintenance bundling through independent fitting studios in France to bypass entrenched specialty retail distribution. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because municipal procurement centralization favors integrated hardware-software-service vendors over standalone equipment suppliers. Acquisition targets include EU AI Act-compliant fleet management software developers and connected bicycle telematics platforms serving Rotterdam and Amsterdam concessions. Monitor algorithmic transparency documentation rates among predictive maintenance vendors as the inflection signal for contract win probability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Recycling | EU Battery Regulation compliance creates defensible positioning against mid-tier assemblers lacking capital for reverse logistics networks. |
| EU AI Act Algorithmic Compliance Investment | Documented transparency frameworks unlock Paris and Brussels municipal fleet management contracts ahead of enforcement deadlines. |
| Polish Manufacturing Corridor Expansion | Structural fund access and labor cost arbitrage reposition cost structures for mid-range frame production serving German and Benelux markets. |
| Integrated Motor-Battery System Unification | Single-vendor warranty structures reduce fragmentation for Copenhagen and Utrecht fleet operators specifying unified specifications. |
| Specialty Retail Channel Consolidation | Subscription-based maintenance bundling through French fitting studios captures premium urban commuter segments from traditional distributors. |
Methodological Framework
Desk research of EU regulatory filings, trade customs data, and municipal procurement records preceded structured interviews with fleet procurement officers, e-bike drive system engineers, specialty retail operators, and connected bicycle platform developers. Primary fieldwork across the Rhine-Ruhr corridor, Rotterdam-Amsterdam axis, and Polish manufacturing regions validated secondary estimates. Bottom-up assembly cost modeling and top-down market sizing triangulated volume and value outputs.
Assumptions held EU Green Deal infrastructure subsidy continuity and F-Gas Regulation compliance cost trajectories fixed, while varying lithium-ion cell pricing and rare earth magnet availability scenarios. Segmentation modeling spanned product type electrification level, end-user commitment tier, distribution channel service intensity, and regional regulatory cluster. CAGRs derived from fitted growth curves against historical procurement data and infrastructure investment pipelines. Forecast inputs incorporated battery energy density improvement curves and municipal fleet electrification timelines.
Sensitivities concentrate around rare earth supply disruption, GDPR mobility data sharing mandate enforcement intensity, and speed pedelec type-approval timeline extensions. Forecasts reflect documented assumptions on subsidy durability and technology cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
United Arab Emirates E-Bike Market
Bikes and Motorcycles
Motorcycle Instrument Cluster Market
Bikes and Motorcycles
Motorcycle Rider Assistance System Market
Bikes and Motorcycles
Bicycle Saddles Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
Global Motorcycle Supercharger Market
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
Folding Bicycle Market
Bikes and Motorcycles
China Two Wheeler Market
Bikes and Motorcycles
Bicycle Gear Shifter Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
South Africa Two-Wheeler Market
Bikes and Motorcycles
Smart Bicycle Accessories Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Motorsports Motorcycle Market