
 Europe Machine Learning in Banking Market | 2026-2036
Europe Machine Learning in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Machine Learning in Banking Market Analytics
Buyer concentration across European retail and commercial banking is consolidating as tier-one institutions centralize technology procurement decisions into dedicated AI governance offices. BNP Paribas leverages its quantitative research division to deploy supervised learning models across credit portfolios. Deutsche Bank anchors its Berlin-based innovation lab around reinforcement learning for dynamic risk calibration. HSBC competes through its London-Edinburgh dual-center structure for natural language processing in customer service automation.
Europe Machine Learning in Banking encompasses algorithmic systems that ingest structured and unstructured financial data to generate predictive outputs without explicit programming, operating through neural network architectures that require continuous retraining on transaction flows exceeding ten million records daily. Deep learning architectures now dominate fraud detection applications where pattern complexity exceeds classical statistical method capacity. Credit scoring solutions built on predictive analytics command premium pricing due to regulatory auditability requirements under EU frameworks. Robotic process automation segments mature fastest in back-office reconciliation where rule-based logic already prevails.
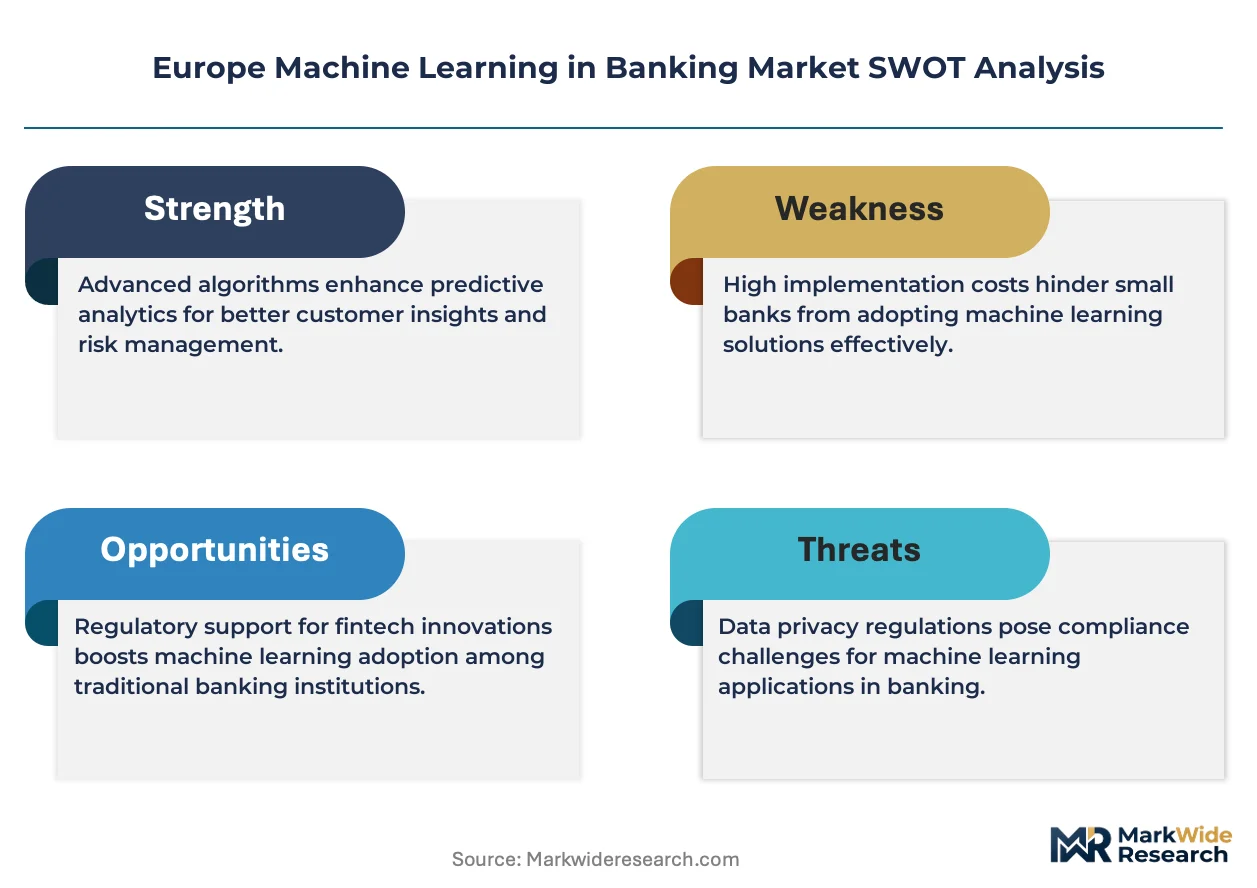
The EU AI Act imposes conformity assessments on high-risk credit scoring algorithms, while GDPR mandates explainability standards that constrain black-box model deployment across member states. EBA guidelines on ICT risk management further shape vendor qualification criteria for cloud-hosted machine learning infrastructure. EMA and ECB coordination on systemic risk monitoring introduces additional data reporting obligations for cross-border banking groups. Stakeholders must track evolving supervisory expectations around model risk management as national regulators transpose EU-level mandates into binding technical standards.
Market Dynamics
The EU AI Act's risk-classification framework is compressing deployment timelines for high-risk credit algorithms, forcing institutions to front-load explainability investments before models enter production. This regulatory velocity is restructuring vendor qualification hierarchies and procurement budgets across the continent.
Growth Catalysts
- GDPR Article 22 mandates:Automated decision-making restrictions are creating audit-ready demand for interpretable machine learning architectures in retail credit workflows.
- Real-time payment rails:Instant settlement systems across Germany and France are expanding transaction velocity beyond classical fraud detection capacity.
- EBA ICT guidelines:Cloud-hosted model risk management standards are accelerating infrastructure modernization budgets at tier-one institutions.
Market Restraints
- GPU supply concentration:Training infrastructure dependency on Taiwan-based semiconductor fabrication is creating procurement bottlenecks for neural network deployment.
- Conformity assessment costs:EU AI Act third-party audit requirements are adding six-figure certification overhead per high-risk algorithm deployment.
- Classical statistical substitutes:Logistic regression and random forest methods retain preference in low-complexity portfolios where interpretability outweighs predictive gain.
Strategic Opportunities
- Eastern European banking modernization:Polish and Romanian retail institutions remain underpenetrated for automated credit decisioning relative to Western European adoption baselines.
- Federated learning architectures:Privacy-preserving model training across siloed datasets is opening cross-institutional collaboration without raw data sharing.
- CSRD disclosure alignment:Sustainability reporting mandates are creating demand for climate risk scoring models that integrate with existing credit infrastructure.
Industry Challenges
- Quantitative risk talent scarcity:MLOps engineering and model validation expertise commands premium compensation in London and Frankfurt labor markets.
- Legacy core integration friction:Mainframe-based transaction systems require expensive API middleware to feed real-time data into cloud-native inference pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Machine Learning in Banking Market |
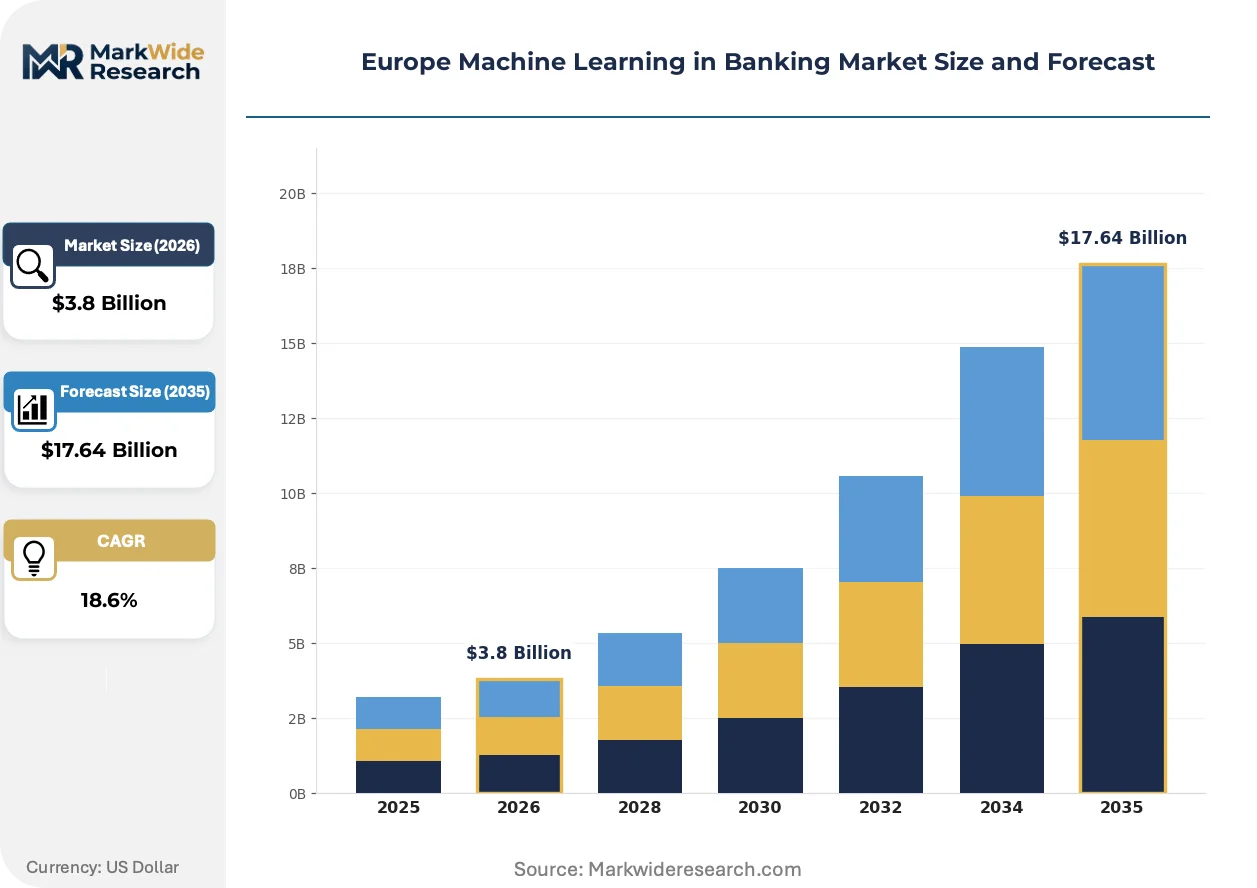
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Supervised Learning, Unsupervised Learning, Reinforcement Learning, Deep Learning Application: Fraud Detection, Risk Management, Customer Service Automation, Credit Scoring End User: Commercial Banks, Investment Banks, Retail Banks, Credit Unions Solution: Predictive Analytics, Robotic Process Automation, Natural Language Processing, Data Management |
| Companies Covered | BNP Paribas, HSBC, Barclays, Deutsche Bank, Santander Group, ING Group, Lloyds Banking Group, NatWest Group, Feedzai, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Machine Learning in Banking Market Evolving Landscape
Transformer-based architectures are migrating from natural language processing into structured financial data prediction, compressing model development cycles while expanding explainability tool requirements. This shift is redrawing competitive boundaries between specialized fintech vendors and incumbent technology providers.
Deep learning ensembles for synthetic identity fraud detection is electrifying transaction monitoring accuracy at UK neobanks, compressing false-positive rates below threshold levels that trigger regulatory scrutiny. Monzo and Starling are deploying these architectures across payment flows exceeding five million daily events. The structural consequence is displacing rules-based detection entirely from high-velocity retail channels.
The EU AI Act's high-risk system classification is mandating conformity assessments for credit scoring algorithms before production deployment, forcing institutions to maintain parallel documentation trails for model logic and training data provenance. German and French regulators are transposing these requirements into binding technical standards ahead of the 2026 enforcement window. Tier-one banks are responding by centralizing AI governance functions that previously sat distributed across business lines.
Centralized procurement of machine learning infrastructure is consolidating vendor relationships at European banking groups, displacing point-solution purchasing that characterized early adoption phases. Technology procurement teams now mandate cloud-agnostic deployment and interoperability with existing risk data warehouses. This concentration is most visible in the United Kingdom, where HSBC and Barclays have established dedicated AI vendor panels with pre-negotiated framework terms.
Europe Machine Learning in Banking Market Segmentation
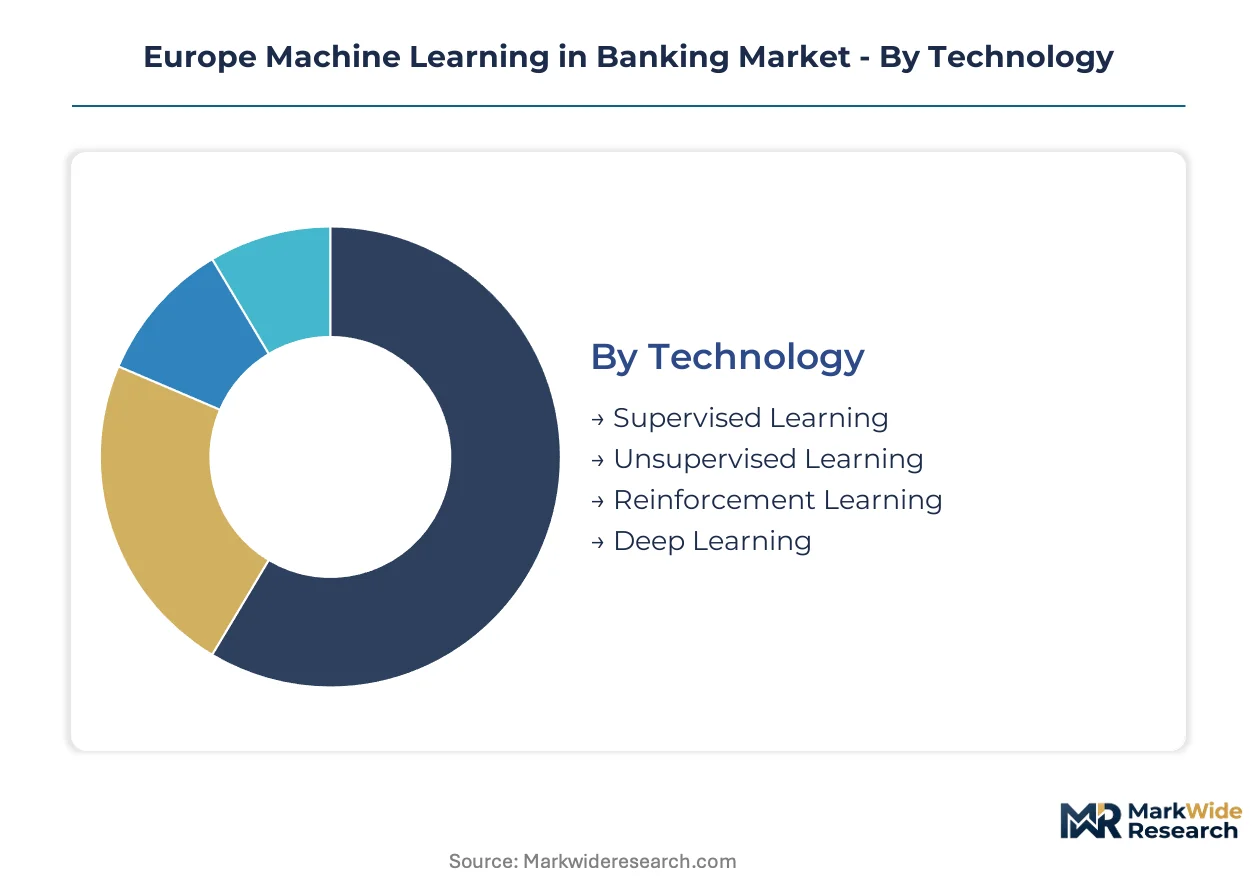
Segmentation reveals where capital allocation concentrates across algorithmic architectures and banking workflows. Procurement patterns diverge sharply between infrastructure-heavy deep learning deployments and lighter supervised learning implementations.
Technology:
Capital intensity varies enormously across algorithmic approaches, with neural network architectures demanding GPU clusters and specialized MLOps talent that simpler statistical methods avoid.
- Deep Learning:Multi-layer neural networks process unstructured transaction data and natural language at scale. German and UK retail banks deploy these architectures for real-time fraud detection where pattern complexity exceeds classical method capacity. The hardware burden and continuous retraining requirements make this the most capital-intensive technology segment.
- Supervised Learning:Labeled training data drives predictive models for credit scoring and customer segmentation. French commercial banks concentrate procurement here due to EU AI Act explainability mandates that favor interpretable architectures with documented feature importance.
- Unsupervised Learning:Clustering algorithms identify anomalous transaction patterns without labeled outcomes.
- Reinforcement Learning:Dynamic optimization of trading and risk calibration through reward-based model iteration.
Deep Learning absorbs the bulk of installed capacity; Reinforcement Learning is expanding most quickly.
Application:
Workflow integration determines deployment velocity, with back-office automation proceeding faster than customer-facing systems subject to stricter regulatory scrutiny.
- Fraud Detection:Real-time transaction monitoring systems ingest millions of daily events to flag synthetic identity and account takeover attempts. UK neobanks lead adoption here, compressing false-positive rates below regulatory threshold levels through ensemble architectures.
- Credit Scoring:Algorithmic underwriting models assess default probability from alternative data streams. German retail banks dominate procurement volume, driven by instant lending demand and EU AI Act conformity requirements for high-risk automated decisioning.
- Risk Management:Portfolio-level stress testing and dynamic capital allocation.
- Customer Service Automation:Conversational interfaces and query routing systems.
Credit Scoring commands the largest share of compliance-adjusted spending; Fraud Detection is gaining share fastest.
End User:
Institutional scale shapes procurement sophistication, with tier-one banks operating dedicated AI governance offices that smaller institutions cannot replicate.
- Retail Banks:High-volume consumer lending and payment processing drives algorithmic investment. The United Kingdom's fintech corridor spanning London and Edinburgh concentrates demand here, with HSBC and Barclays maintaining dual-center machine learning operations.
- Commercial Banks:Corporate credit workflows and treasury services automation. French institutions lead adoption within this segment, leveraging quantitative research divisions for supervised learning deployment across middle-market portfolios.
- Investment Banks:Trading algorithms and risk calibration for complex derivatives.
- Credit Unions:Member-focused lending automation with limited in-house technical capacity.
Retail Banks anchor procurement volume; Commercial Banks are climbing the fastest as EBA ICT guidelines accelerate infrastructure modernization.
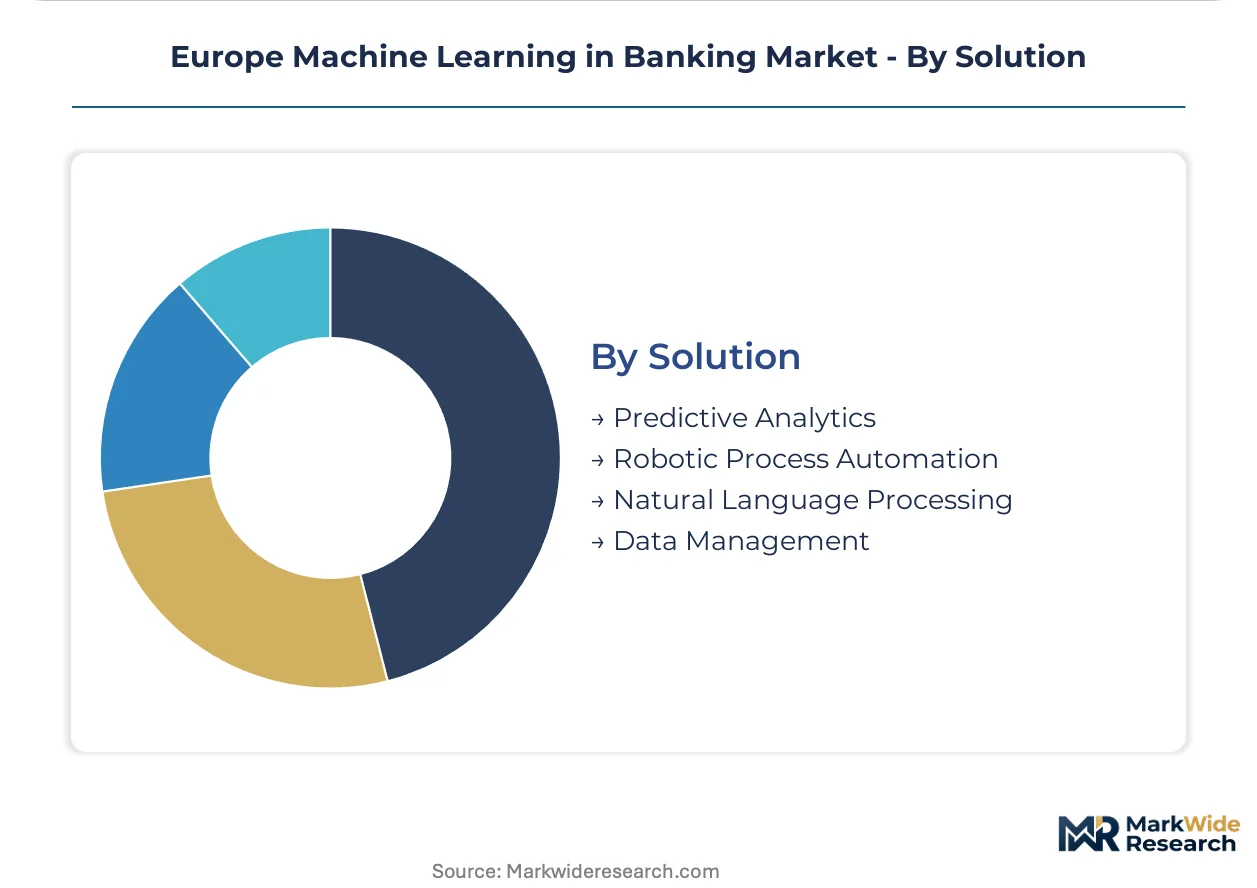
Solution:
Vendor positioning stratifies between infrastructure platforms and point applications, with procurement teams increasingly mandating cloud-agnostic deployment and risk data warehouse interoperability.
- Predictive Analytics:Statistical modeling platforms for forecasting credit performance and customer behavior. Premium pricing persists here due to EU regulatory auditability requirements that constrain black-box deployment.
- Robotic Process Automation:Rule-based workflow automation for reconciliation and compliance reporting. This segment matures fastest in German back-office operations where legacy mainframe integration demands expensive API middleware.
- Natural Language Processing:Document analysis and conversational interfaces for customer interaction.
- Data Management:Governance and provenance tracking for training data pipelines.
Predictive Analytics retains the steepest expansion trajectory; Robotic Process Automation holds the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center infrastructure and MLOps talent pools concentrate in financial capitals across Western Europe, anchoring algorithmic banking deployment to established metropolitan clusters with dense cloud connectivity and regulatory expertise.
United Kingdom
London's fintech corridor generates the densest concentration of machine learning procurement in European banking, with HSBC and Barclays operating dual-center architectures spanning the capital and Edinburgh. The UK Financial Conduct Authority's AI guidance predates EU frameworks, creating earlier compliance baselines for explainable credit algorithms. Edinburgh's quantitative finance cluster feeds specialist talent into fraud detection model development for retail payment networks.
Germany
Deutsche Bank anchors Berlin's innovation lab around reinforcement learning for dynamic risk calibration, while Frankfurt's regulatory proximity shapes vendor qualification standards. The German Federal Financial Supervisory Authority (BaFin) transposes EU AI Act requirements into binding technical standards ahead of the 2026 enforcement window. Munich's insurtech corridor increasingly supplies cross-sector talent into banking MLOps teams.
France
BNP Paribas leverages its quantitative research division to deploy supervised learning across corporate credit portfolios, with Paris hosting the European Banking Authority's ICT risk guidelines development. The French Prudential Supervision and Resolution Authority (ACPR) mandates documentation trails for high-risk algorithmic decisioning. Île-de-France's data science labor market concentrates expertise in interpretable model architectures favored by EU explainability mandates.
Netherlands
ING Group's Amsterdam headquarters drives cloud-native machine learning infrastructure procurement, with the Dutch Central Bank (DNB) advancing model risk management supervision for cross-border banking groups. Rotterdam's port finance ecosystem generates specialized demand for trade finance algorithms. The Randstad's dense cloud provider presence reduces latency for real-time fraud detection inference pipelines.
Spain
Santander Group's Madrid and Barcelona operations anchor Iberian adoption of customer service automation through natural language processing. The Bank of Spain coordinates with ECB systemic risk monitoring frameworks, introducing data reporting obligations for algorithmic trading oversight. Barcelona's growing fintech cluster supplies mid-tier institutions with vendor-agnostic deployment expertise.
Europe Machine Learning in Banking Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue federated learning architectures and climate risk scoring specializations. Tier-one European banking groups concentrate procurement decisions into dedicated AI governance offices, displacing distributed business-line purchasing. Three archetypes dominate: vertically integrated universal banks with captive quantitative research divisions; cloud-native neobanks deploying ensemble fraud detection; and specialized fintech vendors offering point solutions for regulatory compliance. Competitive dynamics center on vendor panel consolidation and framework agreement pre-negotiation rather than technology differentiation alone.
Among UK-based banking groups, HSBC, Barclays, and NatWest exemplify the governance-centralization archetype, each maintaining dedicated AI vendor panels with pre-negotiated cloud-agnostic deployment terms. BNP Paribas and Deutsche Bank represent the continental universal bank model, anchoring innovation capacity in captive quantitative research divisions with regulatory proximity to Paris and Frankfurt respectively. These institutions occupy positions where compliance-adjusted procurement budgets reshape vendor hierarchies.
| Leading Market Players |
|---|
| BNP Paribas |
| HSBC |
| Barclays |
| Deutsche Bank |
| Santander Group |
| ING Group |
| Lloyds Banking Group |
| NatWest Group |
| Feedzai |
| Others |
Value Network & Pricing Analysis
A sharp divergence between EU AI Act-compliant explainable architectures and black-box deep learning deployments manifests in both procurement premiums and vendor qualification hierarchies across European banking. Tier-one institutions in London and Frankfurt pay substantial conformance premiums for documented model provenance while GPU-dependent neural network training strains infrastructure budgets.
Pricing Analysis
Model warranty and continuous retraining service bundles separate premium vendor tiers from unbundled point-solution providers in this market. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth under EU AI Act conformity assessments and GDPR audit trail completeness. Price differentiation hinges on explainability tooling integration and MLOps support intensity. Pricing pressure stems from GPU supply bottlenecks and six-figure third-party audit overhead per high-risk algorithm deployment. Mid-tier Polish and Romanian retail banks exhibit highest price sensitivity; UK neobanks with venture backing show lowest.
Supply Chain Analysis
Training infrastructure rests on Taiwan-based semiconductor fabrication for GPU clusters, Netherlands-located cloud hyperscaler regions for low-latency inference, and Ireland-hosted data centers for GDPR-compliant model storage. Specialized AI accelerators, high-bandwidth memory modules, and liquid cooling systems constitute critical component dependencies. Supply chain risk centers on single-source vulnerability for advanced node chip fabrication amid geopolitical friction. Distribution runs through centralized vendor panels at tier-one banking groups with pre-negotiated framework terms displacing point-solution purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European banking machine learning sits in a technology-transition phase where transformer-based architectures displace classical statistical methods across credit scoring and fraud detection workflows.
For Market Incumbents: Deploy captive quantitative research divisions to internalize model development and reduce third-party conformance audit dependency. BNP Paribas and Deutsche Bank demonstrate this lever through Berlin and Paris-based innovation labs. Cloud-native neobanks deploying ensemble fraud detection represent the emerging competitive threat. Incumbents should consolidate vendor relationships through pre-negotiated AI governance frameworks to defend procurement margin position. For New Entrants and Emerging Players: Cloud marketplace distribution routes offer lowest-friction entry into compliance-constrained procurement environments. Eastern European banking modernization presents the most penetrable white-space, with Polish and Romanian retail institutions operating below Western European automation baselines. Federated learning architectures enable cross-institutional collaboration without raw data sharing, addressing GDPR restrictions directly. A specialist positioning in climate risk scoring models for CSRD disclosure alignment captures sustainability-linked procurement budgets. For Investors and Strategic Acquirers: Re-rating potential sits with MLOps engineering specialists given EU AI Act enforcement compressing deployment timelines and expanding explainability tool demand. Long-term viability over the next decade favors vendors with pre-established tier-one banking group vendor panel status and cloud-agnostic deployment capabilities. The signal to watch is BaFin and ACPR transposition velocity into binding technical standards ahead of the enforcement window.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Third-party audit completion unlocks tier-one bank procurement pipelines under BaFin supervision. |
| Federated Learning Platform Launch | Privacy-preserving training architectures address GDPR cross-border data restrictions for multi-national banking groups. |
| Climate Risk Model Integration | CSRD-aligned scoring modules attach to existing credit infrastructure at ING Group and BNP Paribas. |
| GPU Cluster Backward Integration | In-house training infrastructure reduces dependency on Taiwan-based semiconductor supply concentration. |
| Edinburgh Quantitative Talent Acquisition | Scotland's fintech corridor supplies specialized fraud detection expertise to London-anchored banking operations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with chief data officers, AI governance leads, model validation specialists, and cloud procurement officers at tier-one European banking groups combined with EBA guideline documents, EU AI Act implementation texts, and hyperscaler infrastructure disclosure filings. Bottom-up deployment estimates triangulated against top-down technology spending benchmarks across the United Kingdom, Germany, France, Netherlands, and Spain.
Granularity-level modeling operated at technology-architecture, application-workflow, and end-user-institution dimensions across the projection horizon. Segmentation captured deep learning versus supervised learning deployment splits, fraud detection versus credit scoring application shares, and retail versus commercial bank procurement patterns. CAGRs derived from algorithmic adoption curve analysis and infrastructure investment disclosure tracking. Forecast inputs incorporated GPU supply constraint scenarios and regulatory transposition timeline assumptions.
The model holds under stable EU AI Act implementation schedules and continued cloud infrastructure availability; deviation in semiconductor supply chain disruption or accelerated national regulatory transposition would shift deployment velocity assumptions. Forecasts reflect documented assumptions around tier-one bank governance centralization and vendor panel consolidation trends. A small set of named triggers—GPU supply rationing, BaFin technical standard acceleration, and federated learning standardization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Data Analytics in Banking Market
Banking
Biometrics for Banking and Financial Services Market
Banking
South Korea Data Analytics in Banking Market
Banking
GCC Mobile Banking Market
Banking
Disaster Recovery in Banking Market
Banking
Global AI in Banking Market
Banking
Banking-As-A-Service (Baas) Platform Market
Banking
Canada Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
Investment Banking and Trading Services Market
Banking
Australia Neobanking Market
Banking
Global Certificate of Deposit Market
Banking
Germany Banking As a Service Market
Banking
Global Retail Core Banking Systems Market
Banking
Banking Smart Cards Market
Banking
Europe Neobanking Market
Banking
Armenia Banking Market